
 Reclosable Rigid Containers Market | 2026-2036
Reclosable Rigid Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Reclosable Rigid Containers Market Analytics
China is narrowing its reliance on imported reclosable rigid container tooling by expanding domestic blow-molding and injection-stretch capacity in Zhejiang and Guangdong provinces. Amcor Plc leverages its integrated film-to-container platform across Asia-Pacific to sustain margin capture from resin through retail shelf. Berry Global anchors North American supply for dairy tubs through captive thermoforming operations and regional resin hedging. Silgan Holdings specializes in metal closure systems for glass jars, dominating the premium sauce and condiment segment where hermetic seal integrity commands price premiums.
Reclosable rigid containers are structural packaging units with integrated secondary-use closure mechanisms, typically manufactured through injection molding, thermoforming, or blow-molding processes using polymers with specified melt flow indices between 2 and 20 g/10 min for dimensional stability under repeated flexing. These containers serve primary industrial purposes in product protection, portion control, and consumer convenience across retail and foodservice channels. Plastic jars with screw cap closures occupy the largest volume position due to their compatibility with hot-fill and aseptic processes, while snap lid trays represent the fastest-expanding format as fresh produce retailers eliminate shrink-wrap secondary packaging. Glass jars with metal closures retain concentrated margin pools in premium personal care and pharmaceutical applications where barrier impermeability and chemical inertness justify higher unit economics.
The FDA regulates food-contact substances under 21 CFR 177 for all polymeric closures and container bodies, while EPA guidelines on recycled content thresholds shape resin sourcing decisions for domestic manufacturers. EU REACH restrictions on phthalate plasticizers and the Packaging and Packaging Waste Directive mandate design-for-recycling criteria that reclosable container producers must navigate for European market access. Stakeholders should monitor evolving extended producer responsibility frameworks and closure-to-container compatibility standards as the decisive variables for capital allocation in next-generation format development.
Market Dynamics
EU Packaging and Packaging Waste Regulation targets are forcing food processors across Germany and France to eliminate single-use secondary packaging, redirecting capital toward tamper-evident reclosable formats with design-for-recycling compliance built into tooling investments.
Growth Catalysts
- Fresh Produce Retail Mandates:North American grocery chains now require rigid clamshell trays with snap-fit closures to replace shrink-wrap, extending shelf visibility while reducing film waste disposal costs.
- REACH Plasticizer Restrictions:EU phthalate limitations under ECHA guidance are accelerating migration to bio-based polypropylene closures that maintain melt flow indices between 2 and 20 g/10 min for repeated flexing durability.
- Domestic Tooling Expansion:China's Zhejiang and Guangdong provinces are commissioning blow-molding and injection-stretch capacity to reduce reliance on imported reclosable rigid container molds.
Market Restraints
- Resin Price Volatility:Polypropylene and PET feedstock costs fluctuate with naphtha cracking margins, compressing thermoforming operations that lack regional resin hedging mechanisms.
- Hermetic Seal Technical Ceiling:Metal closure systems for glass jars face fundamental barrier limits against oxygen ingress below 0.1 cc/day, constraining shelf-life extension for premium sauces.
- Extended Producer Responsibility Friction:Emerging EPR frameworks in multiple jurisdictions impose uncertain fee structures on closure-to-container compatibility testing.
Strategic Opportunities
- ASEAN Dairy Processing:Vietnam and Indonesia food processors show underpenetrated demand for hot-fill compatible screw-cap jars with aseptic processing compatibility.
- Pharmaceutical Barrier Convergence:Combination of cyclic olefin copolymer bodies with induction-sealed closures is opening unit-dose packaging for moisture-sensitive APIs.
- EU Green Deal Incentives:Circular economy action plan subsidies favor reclosable formats with mono-material construction and embedded digital watermarks for automated sorting.
Industry Challenges
- Mold Flow Simulation Expertise Gap:Tooling engineers with specialized training in injection molding warpage prediction for thin-wall reclosable designs command scarcity premiums.
- Recycled Content Certification Timelines:FDA 21 CFR 177 compliance documentation for post-consumer resin integration extends qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reclosable Rigid Containers Market |
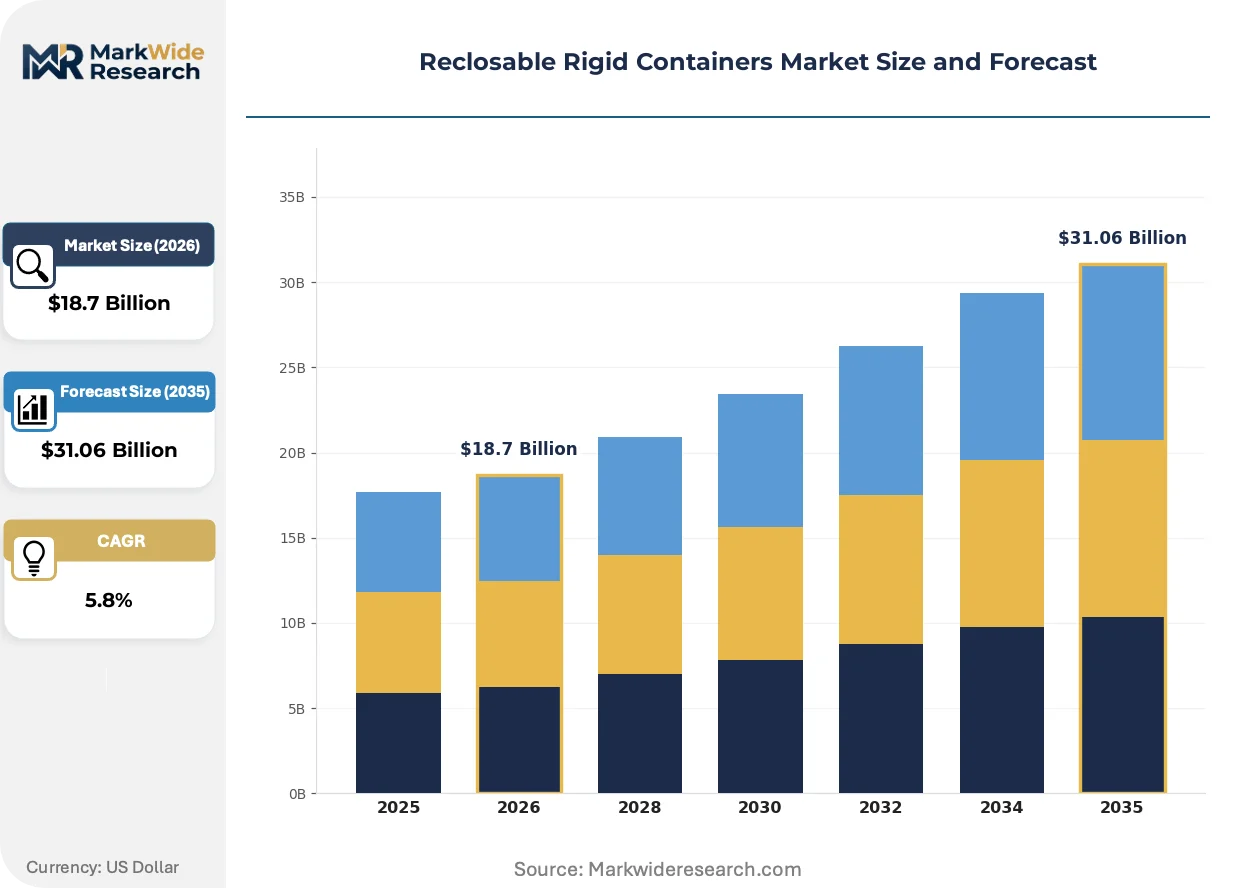
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Jars, Tubs, Trays Material: Plastic, Glass, Metal, Cardboard Closure Type: Screw Caps, Snap Lids, Flip Tops, Zippers End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Goods |
| Companies Covered | Amcor Plc, Berry Global, Silgan Holdings, Plastipak Holdings, Sonoco Products Company, DS Smith Plc, Sealed Air Corporation, ALPLA, Schoeller Allibert Services B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reclosable Rigid Containers Market Evolving Landscape
Digital manufacturing workflows and regulatory compliance automation are compressing development cycles for reclosable rigid containers, while material science advances unlock mono-material constructions that satisfy sorting infrastructure limitations.
Digital twin platforms for injection mold flow analysis are virtualizing traditional prototyping stages. European dairy tub manufacturers deploy these simulations to optimize snap-fit hinge geometries before steel cutting. The technology is virtualizing physical tooling iterations, reducing capital at risk for format variants by enabling predictive validation of dimensional stability under repeated flexing cycles.
EU REACH restrictions on phthalate plasticizers are mandating reformulation of polypropylene closure compounds. Compounders must certify alternative plasticizers through ECHA substance evaluation protocols. The premium sauce segment, where hermetic seal integrity commands price premiums, faces accelerated migration timelines to bio-based alternatives with equivalent melt flow characteristics.
Fresh produce retailers are consolidating purchasing through direct specification of rigid clamshell formats with integrated closures. Traditional packaging distributors lose intermediary value as Walmart and Kroger issue technical standards that bypass converter recommendations. California and Florida growing regions exhibit the most concentrated buyer power, with volume commitments tied to elimination of shrink-wrap secondary packaging.
Reclosable Rigid Containers Market Segmentation
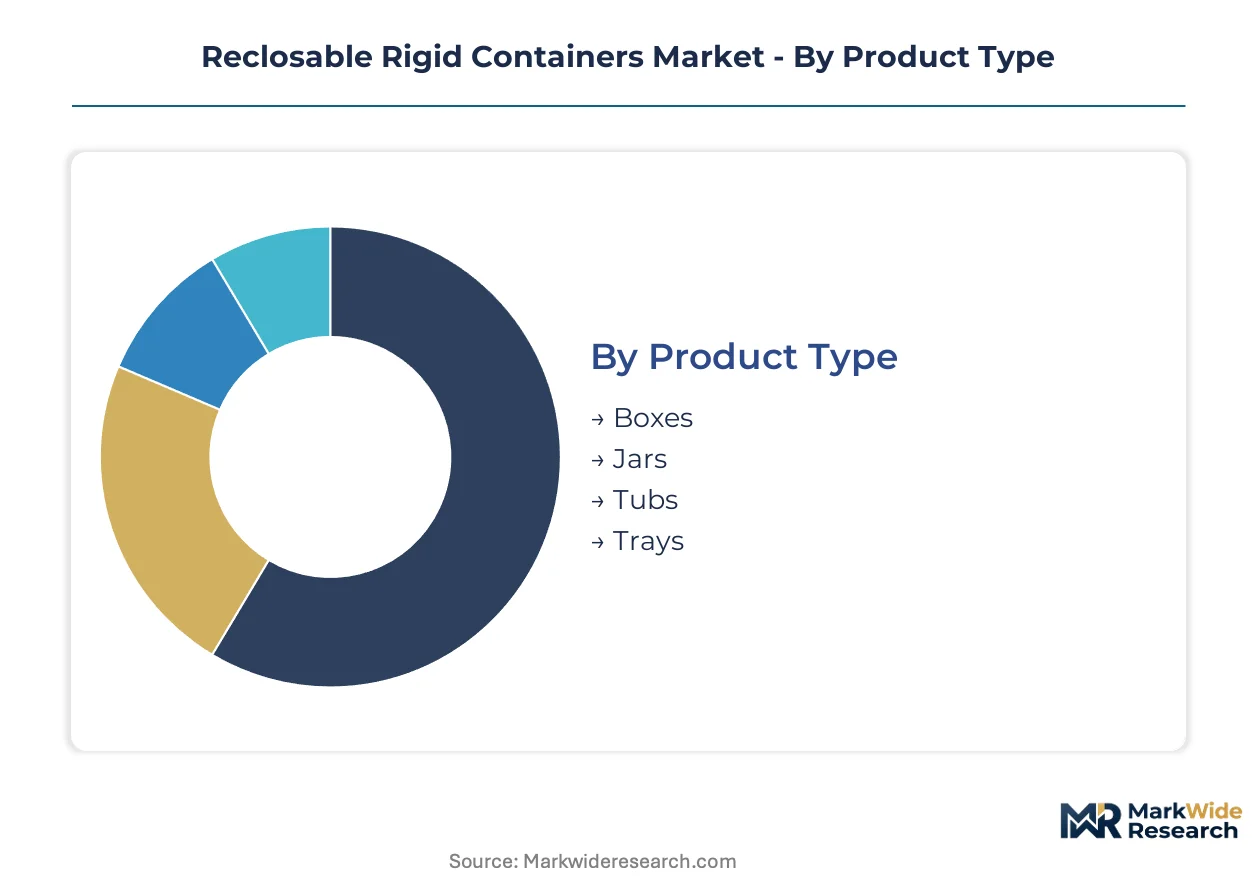
Segmentation in reclosable rigid containers reveals how tooling investments and regulatory compliance cluster around specific format-material combinations. Procurement cycles vary dramatically: fresh produce trays turn over in weeks, while pharmaceutical jars qualify over years.
Product Type:
Jars and trays operate on fundamentally different replacement cycles, with food retail driving rapid tray turnover and premium condiments extending jar amortization periods.
- Jars:Injection-molded or blow-molded cylindrical bodies with threaded neck finishes specified for hot-fill and aseptic processing compatibility. Dairy processors in Germany and France specify tamper-evident reclosable jars for spreads under EU Packaging and Packaging Waste Regulation mandates for design-for-recycling compliance.
- Trays:Thermoformed rigid clamshells with integrated snap-fit hinges, typically produced from PET or PP sheet with specified melt flow indices. North American grocery chains including Walmart and Kroger now mandate these formats to eliminate shrink-wrap secondary packaging and extend shelf visibility.
- Tubs:Wide-mouth cylindrical containers with snap-on or screw-thread closures, common in dairy and deli applications. Berry Global anchors North American supply through captive thermoforming operations with regional resin hedging.
- Boxes:Rectangular formats with hinged or separate lids, prevalent in foodservice and institutional channels. Cardboard-plastic hybrid constructions face sorting infrastructure limitations in automated recycling streams.
Jars dominate installed base across sauce and condiment segments. Trays represent where expansion concentrates as produce retailers eliminate film waste.
Material:
Material selection stratifies by barrier requirements and regulatory jurisdiction, with polymer formulations facing REACH plasticizer scrutiny while glass commands premium positioning.
- Plastic:Polypropylene and PET dominate through compatibility with injection molding, thermoforming, and blow-molding processes. China's Zhejiang and Guangdong provinces are expanding domestic blow-molding capacity to reduce reliance on imported tooling.
- Glass:Soda-lime and borosilicate bodies with metal or plastic closures, specified where chemical inertness and oxygen barrier impermeability justify higher unit economics. Silgan Holdings specializes in metal closure systems for this segment.
- Metal:Tinplate and aluminum formats with crimped or threaded closures, concentrated in aerosol and industrial applications. Hermetic seal technical ceilings constrain shelf-life extension below 0.1 cc/day oxygen ingress thresholds.
- Cardboard:Fiber-based formats with polymer or wax barrier coatings, common in dry goods and foodservice. FDA 21 CFR 177 compliance documentation extends qualification cycles by 18-24 months for food-contact applications.
Plastic commands volume leadership across fresh produce and dairy applications. Glass captures margin concentration in pharmaceutical and premium personal care segments.
Closure Type:
Closure mechanism determines reseal performance cycles and compatibility with automated filling lines, with screw caps offering maximum repeatability and zippers enabling flexible format adaptation.
- Screw Caps:Threaded polymer or metal closures with specified torque removal values and induction seal compatibility. Hot-fill and aseptic processing compatibility makes these dominant in dairy and beverage applications.
- Snap Lids:Hinged or separate lids with interference-fit engagement geometry, produced through thermoforming or injection molding. Fresh produce retailers specify these to replace shrink-wrap and reduce film waste disposal costs.
- Flip Tops:Living-hinge integrated closures common in personal care and condiment dispensing. ECHA substance evaluation protocols mandate reformulation away from phthalate plasticizers for EU market access.
- Zippers:Interlocking profile closures primarily specified for flexible formats, with limited rigid container penetration. Mono-material construction requirements under EU Green Deal circular economy subsidies favor alternative closure architectures.
Screw caps dominate installed base in processed food and beverage applications. Snap lids are climbing fastest as produce packaging eliminates secondary film.
End User:
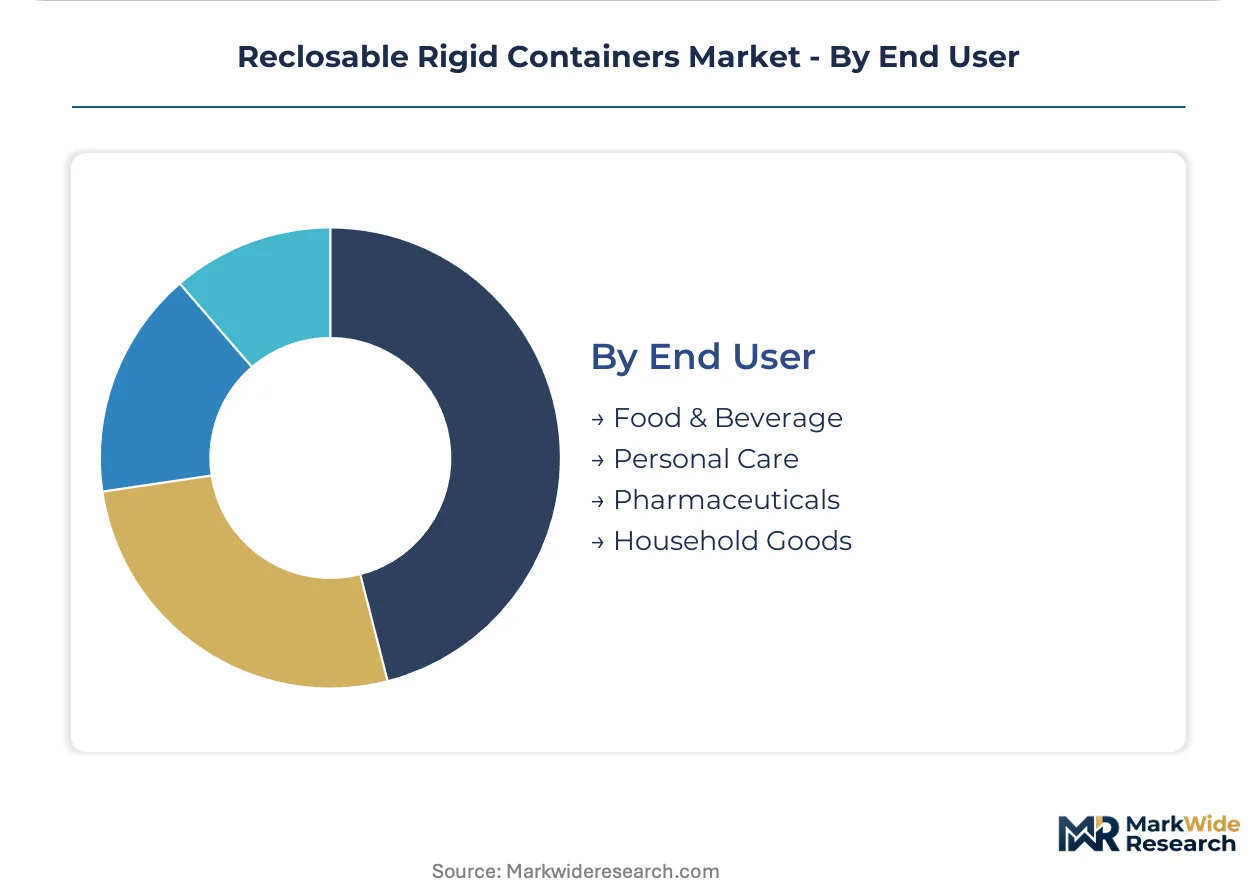
End-use verticals impose distinct qualification protocols and barrier specifications, with pharmaceutical and food applications diverging most sharply on regulatory compliance timelines.
- Food & Beverage:Largest volume vertical encompassing dairy, spreads, sauces, fresh produce, and ready-to-eat meals. EU Packaging and Packaging Waste Regulation targets are redirecting German and French processor capital toward tamper-evident reclosable formats.
- Pharmaceuticals:Unit-dose and multi-dose packaging for moisture-sensitive APIs requiring hermetic barrier integrity. Cyclic olefin copolymer bodies with induction-sealed closures are opening new format development.
- Personal Care:Premium positioning demands glass with metal closures for chemical inertness, though mass-market applications shift to polypropylene with bio-based plasticizer alternatives.
- Household Goods:Industrial and consumer chemical packaging with child-resistant and senior-friendly closure mandates. Extended producer responsibility frameworks impose uncertain fee structures on closure-to-container compatibility testing.
Food & Beverage dominates installed base across all material and closure combinations. Pharmaceuticals represent the steepest expansion trajectory as barrier convergence enables unit-dose rigid formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact regulations under 21 CFR 177 anchor United States demand, while EU REACH plasticizer restrictions and China's domestic tooling expansion reshape supply geography across three continents.
United States
Fresh produce retailers including Walmart and Kroger mandate rigid clamshell trays with snap-fit closures to eliminate shrink-wrap secondary packaging. EPA guidelines on recycled content thresholds shape resin sourcing decisions for domestic thermoforming operations. California and Florida growing regions concentrate buyer power through volume commitments tied to film waste reduction targets.
Germany
Food and beverage processors expand tamper-evident reclosable jar specifications for dairy and spreads. EU Packaging and Packaging Waste Regulation targets redirect capital toward design-for-recycling compliance in tooling investments. Industrial clusters in Bavaria and North Rhine-Westphalia host dairy packaging innovation centers focused on mono-material construction.
China
Blow-molding and injection-stretch capacity expansion in Zhejiang and Guangdong provinces narrows reliance on imported reclosable rigid container tooling. SAMR quality standards and dual carbon goals accelerate domestic mold flow simulation expertise development. Yangtze River Delta and Pearl River Delta manufacturing bases capture regional fresh produce and dairy processing demand.
France
Premium sauce and condiment producers specify glass jars with metal closures where hermetic seal integrity commands price premiums. ECHA substance evaluation protocols mandate phthalate plasticizer reformulation for EU market access. Auvergne-Rhône-Alpes and Île-de-France concentrate food processing headquarters driving format specification decisions.
Vietnam
ASEAN dairy processing shows underpenetrated demand for hot-fill compatible screw-cap jars with aseptic processing compatibility. National food safety regulations align with regional harmonization frameworks for food-contact materials. Ho Chi Minh City and Hanoi industrial zones attract blow-molding capacity serving regional beverage and dairy markets.
Reclosable Rigid Containers Market Competitive Landscape
Integrated resin-to-shelf platforms and specialized closure system suppliers split the market into distinct capability tiers. Consolidation concentrates around manufacturers with captive thermoforming operations and regional resin hedging mechanisms. Three archetypes dominate: integrated multinational packaging platforms, regional captive converters, and specialized closure technology suppliers. Competitive moves center on backward integration into resin compounding and geographic licensing of mold flow simulation platforms.
Within the integrated platform tier, Amcor Plc exemplifies the film-to-container convergence model across Asia-Pacific markets. Berry Global anchors North American dairy tub supply through captive operations. Silgan Holdings occupies the specialized closure position for glass jar formats. These three represent the strategic positioning spectrum from resin integration through regional manufacturing density to component specialization.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global |
| Silgan Holdings |
| Plastipak Holdings |
| Sonoco Products Company |
| DS Smith Plc |
| Sealed Air Corporation |
| ALPLA |
| Schoeller Allibert Services B.V. |
| Others |
Value Network & Pricing Analysis
Asia-Pacific container freight corridors from Shanghai to Los Angeles anchor cost dynamics for reclosable rigid container resin imports, compressing margins for thermoforming operations lacking regional hedging while amplifying price differentiation between captive-integrated manufacturers and spot-market converters.
Pricing Analysis
Geographic price spreads between North American and Asian supply bases exceed freight-adjusted parity, favoring domestic producers with captive resin compounding. Three-tier pricing structure across premium, standard, and economy levels stratifies by melt-flow index precision and FDA 21 CFR 177 compliance documentation. Pricing pressure stems from polypropylene feedstock volatility tied to naphtha cracking margins, with fresh produce retailers exhibiting highest price sensitivity and pharmaceutical buyers accepting premium positioning for barrier-grade specifications.
Supply Chain Analysis
Contract manufacturing concentration rests with Berry Global's captive thermoforming network and Amcor's integrated film-to-container platforms across Asia-Pacific. Supply concentrates in China, Germany, and the United States, with blow-molding capacity expanding in Zhejiang and Guangdong provinces. Raw material dependencies center on polypropylene resin, PET sheet stock, and metal closure substrates. Single-source vulnerability in imported mold tooling creates chokepoint exposure. Distribution runs through direct retailer specifications that bypass traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reclosable rigid containers are approaching a platform-economics inflection as digital twin workflows for mold flow simulation create interoperability standards between tooling engineers and brand specification teams, consolidating value capture around predictive manufacturing platforms.
For Market Incumbents: Entrench backward integration into resin compounding and regional resin hedging mechanisms to defend against naphtha margin volatility. Prioritize captive thermoforming capacity in California and Florida growing regions where Walmart and Kroger buyer power concentrates. Lock in mold flow simulation expertise through exclusive licensing agreements with Zhejiang and Guangdong engineering clusters before scarcity premiums escalate. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Indonesia dairy processing markets where hot-fill compatible screw-cap jar demand remains underpenetrated. Target ASEAN food safety harmonization frameworks as regulatory entry pathway. Lead with aseptic processing compatibility certifications to differentiate from commodity converters serving fresh produce segments. For Investors and Strategic Acquirers: Specialized closure technology suppliers with metal hermetic seal expertise command scarcity positioning as EU REACH plasticizer restrictions accelerate format migration. Long-term viability hinges on mono-material construction capabilities aligned with EU Green Deal circular economy subsidies. Watch EPR framework finalization across multiple jurisdictions as fee-structure clarity will trigger consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates Berry Global from naphtha margin volatility. |
| Digital Twin Platform Licensing | Virtual mold flow analysis reduces capital at risk for Amcor's Asia-Pacific format variants. |
| Mono-Material Construction Certification | EU Green Deal subsidies favor Silgan's metal closure systems with automated sorting compatibility. |
| Regional Resin Hedging Mechanisms | Thermoforming operations in California and Florida secure margin stability against feedstock swings. |
| Aseptic Processing Compatibility Investment | Vietnam dairy processors specify hot-fill screw-cap jars opening premium positioning for qualified entrants. |
Research Methodology
Desk research of FDA 21 CFR 177 compliance databases, EU ECHA substance evaluation protocols, and SEC manufacturing capex disclosures preceded structured interviews with thermoforming plant managers, retail category buyers at Walmart and Kroger, dairy packaging procurement leads, and mold flow simulation engineers. Primary fieldwork across Bavaria, Zhejiang, and California industrial clusters combined with trade data from customs records and ACC resin consumption reports. Bottom-up capacity assessments and top-down demand modeling were triangulated against manufacturer shipment disclosures.
Assumptions around EU Packaging and Packaging Waste Regulation enforcement timelines and China SAMR quality standard harmonization were held fixed, while resin price volatility bands and EPR fee structures were varied across sensitivity scenarios. Segmentation dimensions modeled include product type, material formulation, closure mechanism, and end-use vertical with regional regulatory cluster overlays. CAGRs were derived from installed base turnover rates and format substitution elasticities, incorporating melt-flow index specification premiums and pharmaceutical barrier-grade certification timelines as industry-specific demand drivers.
Stress conditions across polypropylene feedstock spreads, EPR fee implementation schedules, and mold tooling import lead times were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory compliance timelines and buyer concentration trajectories. Quarterly review of EU EPR framework finalization, China dual carbon goal enforcement, and North American retailer specification shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Rigid Industrial Packaging Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
Germany Rigid Plastic Packaging Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
Rigid Sleeve Boxes Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market