
 Brazil Pouch Packaging Market | 2026-2036
Brazil Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Pouch Packaging Market Insights
Consolidation among Brazil's mid-sized food processors is repositioning procurement power toward fewer buyers with larger volume contracts. Amcor Group GmbH leverages its integrated film supply to capture these consolidated accounts. Gualapack SpA anchors its position through specialized spouted pouch formats for dairy and juice segments. Plaszom Industria De Plasticos Ltda competes on regional manufacturing proximity to Minas Gerais and Paraná processing clusters.
Brazil pouch packaging denotes flexible primary containers constructed from single or multi-layer substrates—typically polyethylene, polypropylene, or aluminum laminates—sealed through heat or mechanical closure systems to preserve product integrity against moisture, oxygen, and light. These structures serve commercial distribution by reducing material weight versus rigid alternatives while enabling shelf-stable logistics across Brazil's extended inland supply routes. Plastic-based laminates dominate current volume given cost efficiency and converter infrastructure density, though aluminum composites command premium positioning in pharmaceutical and high-barrier food applications. Stand-up pouches represent the fastest-expanding form factor as retail channel reset priorities favor shelf visibility and consumer convenience in urban supermarkets.
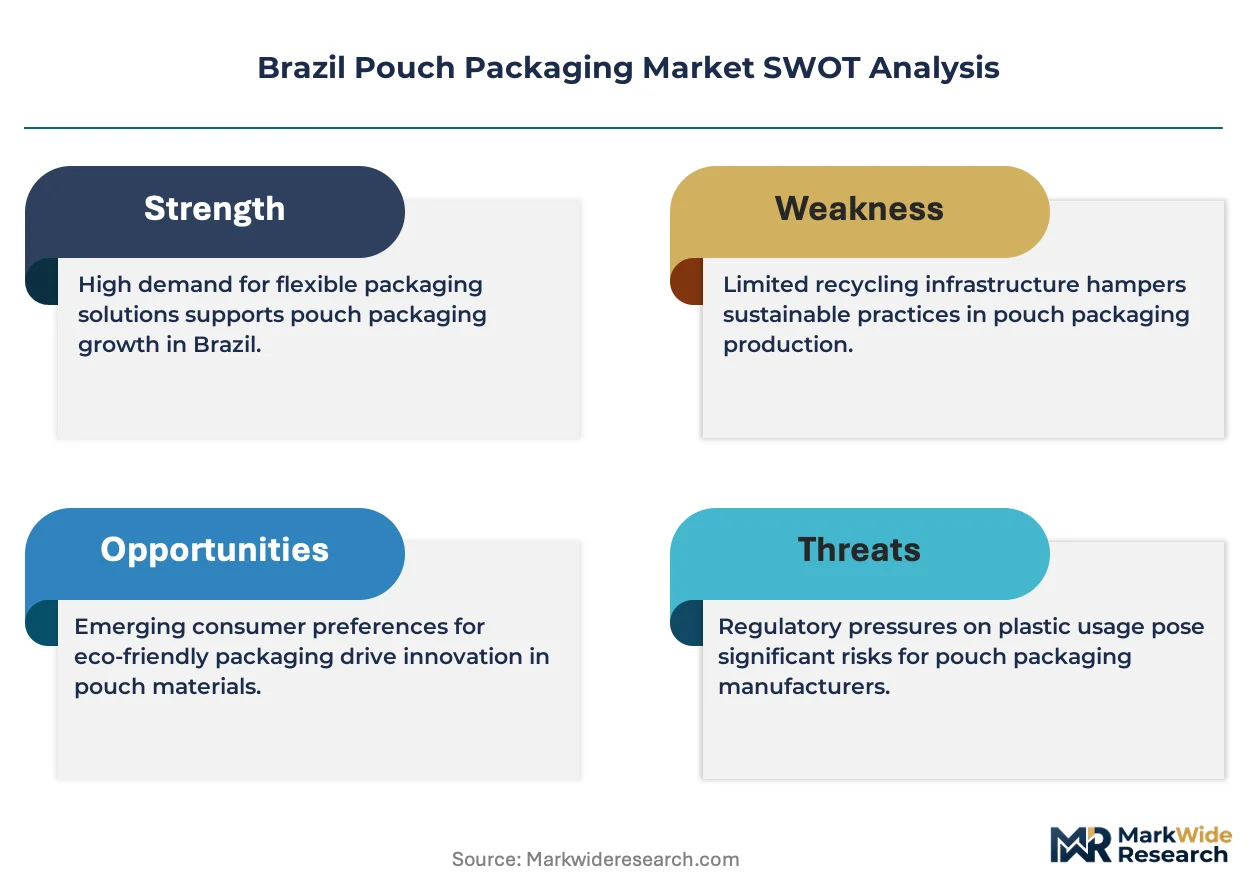
ANVISA governs pharmaceutical pouch sterility and traceability standards, while INMETRO administers conformity assessment for food-contact materials under Mercosur harmonized rules. Brazil's National Solid Waste Policy (PNRS) mandates extended producer responsibility frameworks that reshape material selection toward recyclable or mono-polymer structures. Stakeholders must monitor pending federal decrees on post-consumer recycled content minimums that will determine converter capex allocation and substrate technology roadmaps.
Market Dynamics
ANVISA's updated pharmaceutical packaging standards are compressing compliance timelines for Brazilian converters, forcing simultaneous investment in barrier technology and traceability systems while food processors in São Paulo consolidate procurement volumes.
Growth Catalysts
- Extended Producer Responsibility:Brazil's National Solid Waste Policy mandates recyclable mono-polymer structures, redirecting converter R&D toward compatible substrates and heat-seal technologies.
- Southeastern industrial corridor concentration:Stand-up pouch adoption clusters around São Paulo state's food manufacturing density, creating localized demand pull for high-speed form-fill-seal equipment.
- Mercosur harmonization:INMETRO's unified food-contact material assessments reduce cross-border certification burden for Brazilian exporters targeting Argentina and Uruguay.
Market Restraints
- Resin import dependency:Polyethylene and polypropylene feedstock volatility ties converter margins to international petrochemical pricing and currency fluctuation.
- Aluminum laminate concentration:High-barrier pharmaceutical pouch production relies on limited domestic metallized film supply, creating single-source vulnerability.
- Recycling infrastructure gap:Post-consumer collection and sorting capacity lags behind PNRS mandates, limiting actual circularity rates for flexible packaging.
Strategic Opportunities
- Minas Gerais dairy cluster:Spouted pouch penetration remains below southeastern averages for yogurt and fermented beverages, offering format expansion runway.
- Post-consumer recycled content mandates:Pending federal decrees on minimum recycled thresholds will advantage early movers with qualified mono-material structures.
- E-commerce fulfillment:Lightweight pouch formats reduce last-mile shipping costs for dry grocery and personal care shipments through São Paulo's logistics hubs.
Industry Challenges
- Multi-layer separation technology:Delamination equipment for aluminum-polymer composites requires specialized technical talent scarce in Brazilian converter labor pools.
- Validation timeline compression:ANVISA sterility documentation for pharmaceutical pouch conversions now averages fourteen months, extending new product introduction cycles.
- Legacy gravure cylinder inventory:Mid-sized converters face stranded asset risk as digital printing transitions accelerate short-run flexibility demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Pouch Packaging Market |
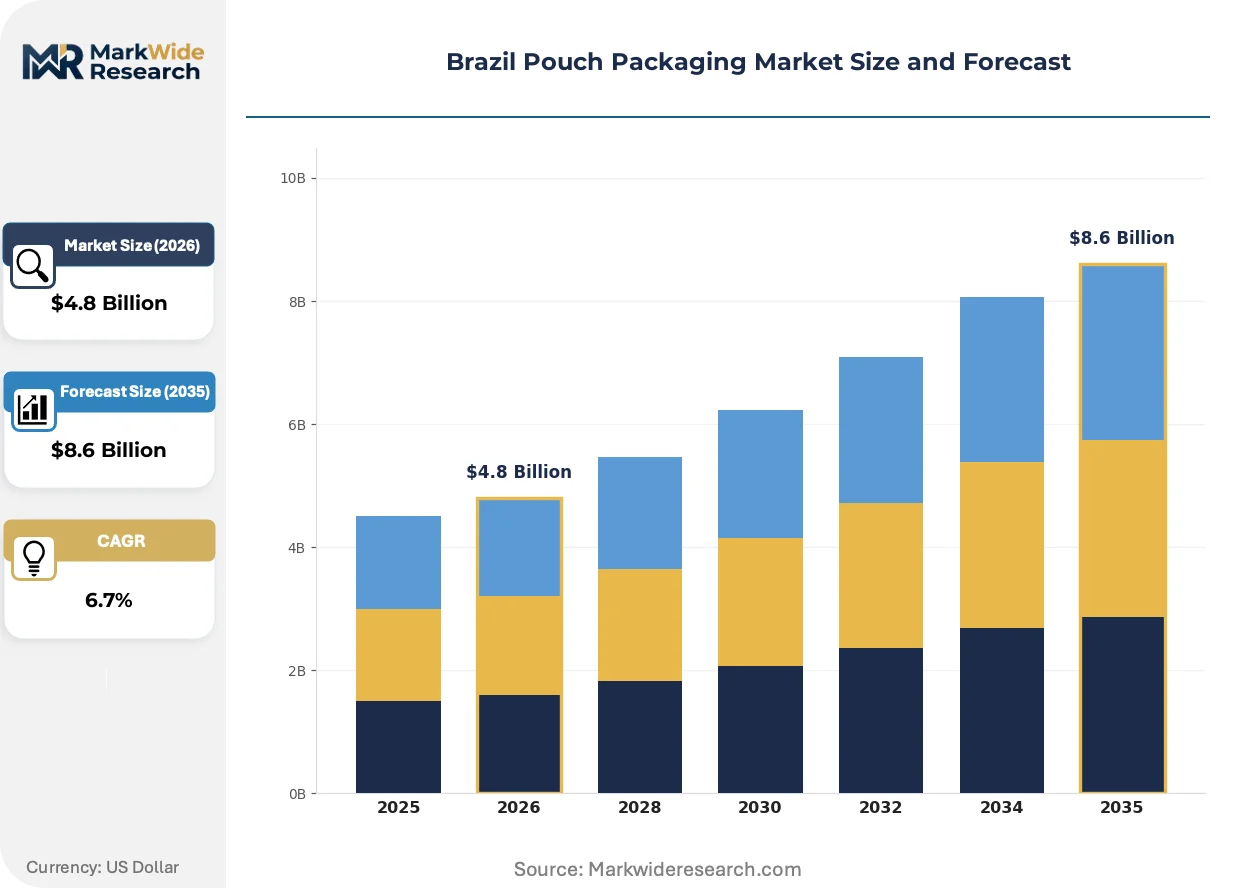
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Aluminum, Paper, Composites Closure Type: Zipper, Heat Seal, Spout, Easy Tear End Use: Food, Beverages, Personal Care, Pharmaceuticals Form Factor: Stand-up Pouches, Flat Pouches, Vacuum Pouches, Gusseted Pouches |
| Companies Covered | Amcor Group GmbH, Sonoco Products Company, Gualapack SpA, Plaszom Industria De Plasticos Ltda, Parnaplast Industria de Plasticos Ltda, Huhtamaki Oyj, Sealed Air Corporation, Suprema Flexo, Embaquim Industria E Comercio Ltda, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Pouch Packaging Market Trends and Innovations
Digital printing and mono-material substrate development are collapsing traditional trade-offs between shelf differentiation and recyclability compliance, while regulatory pressure on traceability accelerates smart packaging integration.
Mono-polymer polyethylene laminates are modularizing converter product portfolios by enabling full compatibility with existing Brazilian mechanical recycling streams. Mid-sized food processors in Paraná are specifying these structures for private-label launches to preempt PNRS enforcement. The technology is modularizing equipment purchasing decisions, as heat-seal parameter standardization reduces changeover complexity.
ANVISA's traceability serialization requirements for pharmaceutical pouches mandate unique identifier integration at the primary package level. Converter investments in vision systems and database infrastructure are diverting capital from capacity expansion. Sterile liquid dose formats for hospital and retail pharmacy chains face the steepest compliance cost escalation.
Direct-to-retailer procurement contracts are displacing traditional distributor networks for high-volume beverage and dairy accounts. São Paulo-based supermarket chains are consolidating flexible packaging specification authority at headquarters level, compressing supplier negotiation cycles. This concentration is most visible in the extended shelf-life juice segment, where annual tender volumes now exceed individual converter single-site capacity.
Brazil Pouch Packaging Market Segmentation
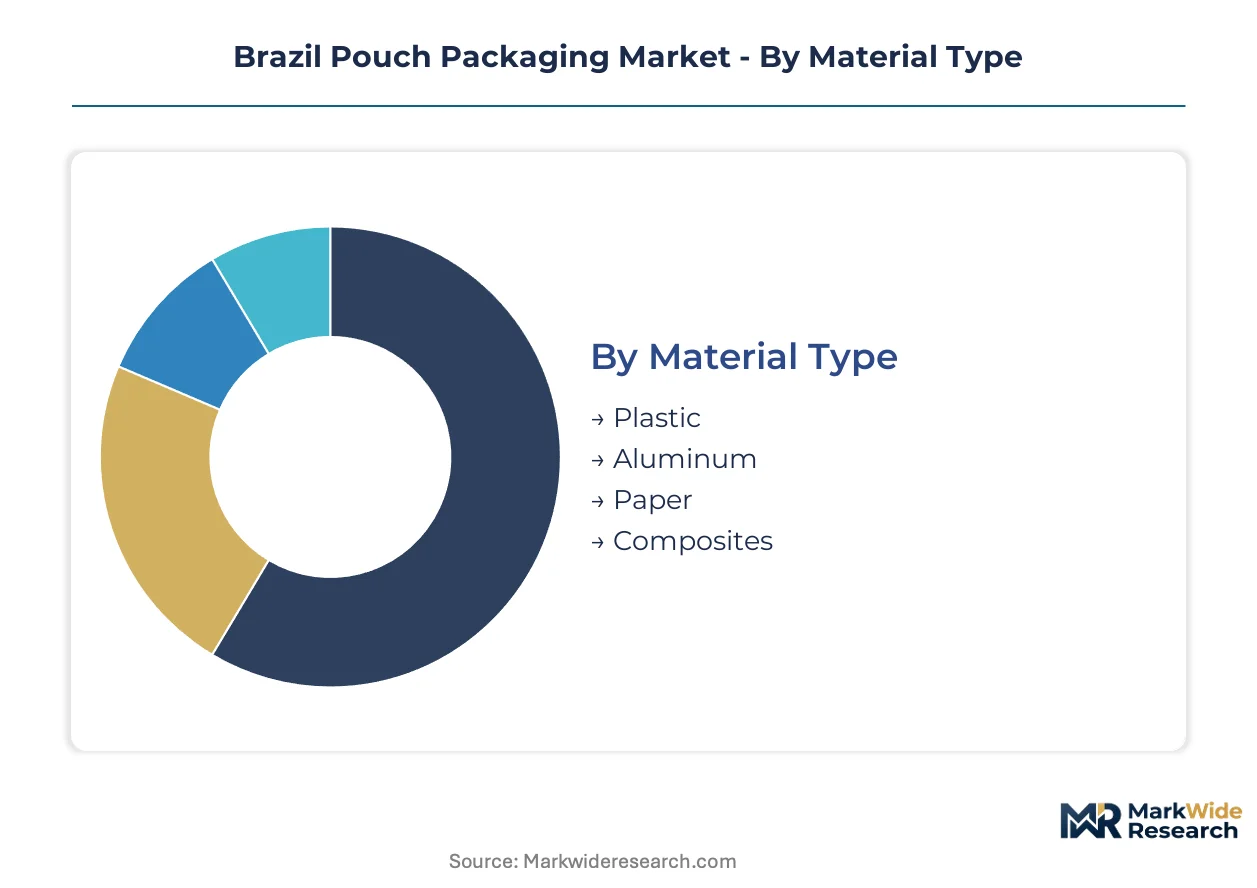
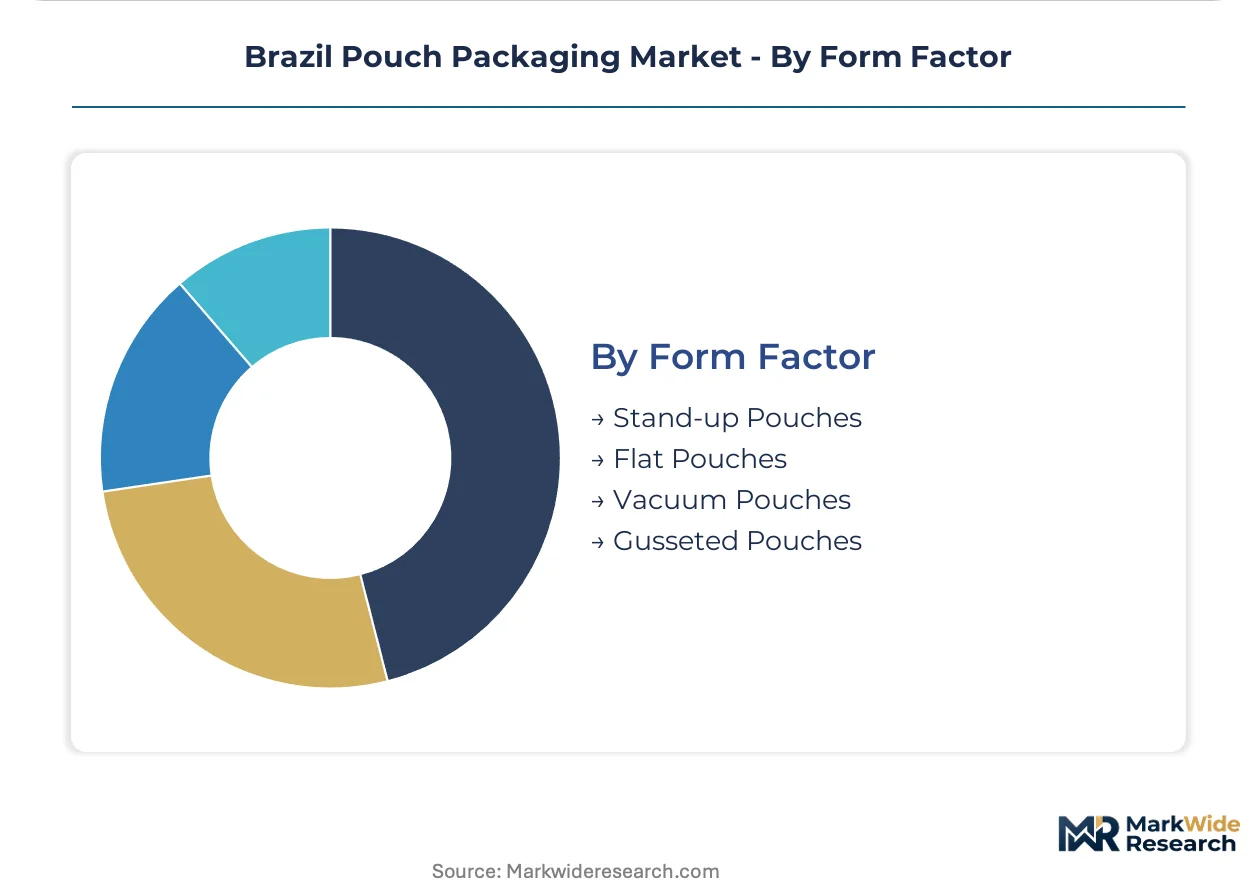
Brazil's pouch packaging segmentation reflects divergent capital requirements across material systems and closure technologies. Converter investment priorities hinge on which segments demand barrier metallization, sterilization infrastructure, or high-speed form-fill-seal integration.
Material Type:
Capital intensity peaks with aluminum lamination lines and pharmaceutical-grade cleanroom extrusion, while plastic substrate conversion requires less specialized equipment.
- Plastic:Polyethylene and polypropylene laminates dominate converter output through existing blown film infrastructure. São Paulo's food processors specify these structures for private-label dairy and snack launches to satisfy PNRS recyclability mandates.
- Aluminum:Metallized film composites command premium positioning in pharmaceutical barrier applications. ANVISA sterility requirements force dedicated cleanroom investment that smaller converters cannot amortize across low volumes.
- Paper:Kraft-based pouches serve dry grocery segments with limited moisture sensitivity. Brazilian paperboard supply constraints restrict format expansion beyond premium organic food niches.
- Composites:Multi-layer aluminum-polymer hybrids balance barrier performance with partial recyclability. Delamination equipment scarcity limits domestic production scale for these structures.
Plastic absorbs the bulk of installed capacity; aluminum is expanding most quickly on pharmaceutical compliance spending.
Closure Type:
Closure selection tracks end-use convenience requirements and filling line compatibility rather than capital intensity alone.
- Zipper:Press-to-close interlocking strips enable resealability for multi-serve food formats. Minas Gerais dairy processors specify zipper pouches for yogurt to differentiate against standard heat-seal competitors.
- Heat Seal:Thermal bonding remains the default for cost-sensitive commodity volumes. São Paulo beverage bottlers favor heat-seal flat pouches for extended shelf-life juice where resealability adds no consumer value.
- Spout:Integrated dispensing fitments command specialized injection molding and in-line welding equipment. Gualapack's dominance in this segment reflects dedicated spout assembly infrastructure that generic converters lack.
- Easy Tear:Laser-scored or notch-perforated openings serve single-serve pharmaceutical sachets. ANVISA child-resistance guidelines complicate easy-tear design for over-the-counter analgesic formats.
Heat Seal retains the greatest volume share; spout formats are gaining share fastest on dairy and juice premiumization.
End Use:
End-use segmentation determines regulatory burden and barrier specification intensity more than equipment scale.
- Food:Dry snacks, frozen vegetables, and ready-meal formats drive flexible packaging consumption across Brazil's supermarket chains. INMETRO food-contact compliance costs are lowest for this segment, permitting mid-sized converter participation.
- Beverages:Extended shelf-life juice and dairy alternatives concentrate demand in São Paulo's industrial corridor. Stand-up pouch adoption here outpaces national averages due to retailer shelf-reset priorities.
- Personal Care:Shampoo, conditioner, and liquid soap pouches serve price-sensitive consumers in Northeast retail channels. Format penetration remains below food and beverage levels due to brand preference for rigid bottle differentiation.
- Pharmaceuticals:Sterile liquid doses and unit-dose solid formats face ANVISA's steepest documentation and validation requirements. Fourteen-month approval timelines restrict converter entry to established pharmaceutical packaging specialists.
Food commands the greatest installed base; pharmaceuticals shows the steepest expansion trajectory on regulatory-driven barrier investment.
Form Factor:
Form factor selection balances shelf visibility, shipping cube efficiency, and filling line retrofit costs.
- Stand-up Pouches:Bottom-gusseted structures with vertical display capability dominate new equipment investment. São Paulo supermarket chains mandate this format for premium juice and dairy sets.
- Flat Pouches:Two- or three-side-seal configurations minimize material use for dry grocery commodities. Legacy form-fill-seal lines across Paraná and Minas Gerais favor this format for capital avoidance.
- Vacuum Pouches:Gas-flushed barrier structures extend protein shelf life for Brazil's meat processing clusters. High-barrier film costs limit adoption beyond export-oriented processors.
- Gusseted Pouches:Side-folded expansion panels accommodate bulk dry goods and institutional foodservice volumes. E-commerce fulfillment applications for this format are climbing fastest in São Paulo logistics hubs.
Flat Pouches retain the largest equipment base; Stand-up Pouches are climbing the fastest on retail channel reset priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for pouch packaging concentrates in Brazil's southeastern industrial corridor, where São Paulo state's food manufacturing density generates procurement volumes unmatched elsewhere in the country. State-level regulatory enforcement and industrial clustering patterns create divergent growth trajectories across Brazil's five macro-regions.
São Paulo
São Paulo state anchors national pouch consumption through its concentration of extended shelf-life juice processors and dairy alternatives manufacturers. ANVISA's pharmaceutical packaging standards drive compliance investment among converters in the São Paulo metropolitan area. The state's ABC industrial corridor hosts the densest cluster of form-fill-seal equipment installations serving retail channel reset programs.
Minas Gerais
Minas Gerais generates specialized demand for spouted pouch formats across yogurt and fermented beverage segments. INMETRO's food-contact material assessments apply uniformly here, though enforcement lags São Paulo's inspection frequency. The Belo Horizonte industrial ring concentrates dairy processing capacity that converters target for format premiumization.
Paraná
Paraná's mid-sized food processors are consolidating procurement volumes toward fewer buyers with larger annual contracts. Brazil's National Solid Waste Policy mandates are reshaping material specifications for private-label launches originating in Curitiba-based manufacturing. The state's western agricultural frontier supplies raw material inputs that reduce resin transport costs for regional converters.
Rio Grande do Sul
Rio Grande do Sul exhibits below-national-average stand-up pouch penetration due to legacy rigid packaging preferences among meat processors. ANVISA's traceability requirements for pharmaceutical exports through Porto Alegre's logistics hub are accelerating barrier technology investment. The Sinos Valley manufacturing cluster retains gravure printing capacity that digital transitions are beginning to displace.
Rio de Janeiro
Rio de Janeiro's pouch demand concentrates in personal care and household chemical segments rather than food and beverage applications. INMETRO conformity assessment procedures for imported flexible packaging materials create compliance friction for converters serving the state's retail chains. The Duque de Caxias petrochemical complex provides polyethylene feedstock that supports regional substrate production.
Brazil Pouch Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue mono-material specialization and digital printing capabilities to bypass legacy equipment barriers. The market structure reflects moderate consolidation among international groups alongside persistent fragmentation among regional Brazilian converters. Three archetypes dominate: integrated film suppliers with captive resin access, specialized spout-assembly operators, and proximity-focused regional fabricators. Competitive dynamics center on M&A activity capturing consolidated food processor accounts and capacity expansion targeting pharmaceutical compliance timelines.
Within the integrated multinational tier, Amcor Group GmbH and Huhtamaki Oyj exemplify scale-driven positioning through film supply integration and geographic coverage breadth. Among specialized regional operators, Gualapack SpA occupies a position representing dedicated spouted pouch infrastructure, while Plaszom Industria De Plasticos Ltda anchors proximity-based competition focused on Minas Gerais and Paraná processing clusters. These three entities represent distinct strategic archetypes: backward-integrated global supply, format-specific technical specialization, and sub-regional manufacturing adjacency.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Sonoco Products Company |
| Gualapack SpA |
| Plaszom Industria De Plasticos Ltda |
| Parnaplast Industria de Plasticos Ltda |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Suprema Flexo |
| Embaquim Industria E Comercio Ltda |
| Others |
Pricing and Supply Chain Analysis
Polyethylene resin costs cascade through Brazilian converter operations into three distinct pricing tiers for food-contact laminates, with São Paulo-based processors commanding premium positioning against Paraná and Minas Gerais competitors facing higher logistics expenditure to southeastern retail channels.
Pricing Analysis
Volume contracts anchor the commodity tier where heat-seal flat pouches for extended shelf-life juice compete on per-unit minimization, while spouted pouch formats for dairy premiumization capture margin expansion through format differentiation. Price differentiation separates pharmaceutical-grade barrier laminates—subject to ANVISA validation timelines—from standard food-contact grades. Cost compression in the plastic substrate tier is intensifying as mono-polymer R&D investment amortizes across thinner converter portfolios. Mid-sized food processors in Paraná exhibit highest price sensitivity due to private-label volume concentration, whereas ANVISA-compliant pharmaceutical specialists face least sensitivity given fourteen-month validation barriers.
Supply Chain Analysis
Regional distribution centers in São Paulo's ABC industrial corridor coordinate hub-and-spoke replenishment to supermarket chain consolidation points, with satellite facilities in Curitiba and Belo Horizonte reducing last-mile exposure to Minas Gerais dairy clusters. Domestic supply draws from the Duque de Caxias petrochemical complex for polyethylene feedstock, though polypropylene and specialized barrier films rely on import channels from the United States and Germany. Single-source vulnerability concentrates in metallized aluminum laminates for pharmaceutical applications. Distribution runs through direct-to-retailer procurement contracts displacing traditional distributor networks for high-volume beverage accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's pouch packaging market operates as a cost-of-compliance story where ANVISA's fourteen-month pharmaceutical validation timelines erect barrier-to-entry moats favoring established converters with amortized sterile infrastructure.
For Market Incumbents: To counter resin import volatility, secure backward integration into captive polyethylene supply from the Duque de Caxias complex or negotiate long-term offtake agreements with regional petrochemical distributors. Capacity addition in Minas Gerais addresses spouted pouch demand growth while preempting Gualapack's geographic expansion. Certification investment in mono-polymer structures positions for pending federal recycled content mandates. For New Entrants and Emerging Players: The price-point gap between premium pharmaceutical barrier laminates and economy heat-seal commodity pouches creates entry space for mid-tier converters specializing in digital-printed short runs for private-label launches. Minas Gerais dairy cluster spouted pouch penetration—currently below southeastern averages—offers the most penetrable geography for format expansion. A go-to-market angle targeting regional supermarket chain tender consolidation with mono-material compliance pre-empts PNRS enforcement timing. For Investors and Strategic Acquirers: Federal decree publication on post-consumer recycled content minimums is the leading indicator that mono-polymer capability will separate viable acquisition targets from stranded-asset converters. Long-term viability over the next decade rests on substrate technology roadmaps aligned with circularity mandates rather than legacy multi-layer infrastructure. Acquisition target archetype: mid-sized converters in Paraná with installed form-fill-seal capacity and unexploited geographic proximity to western agricultural supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Polymer Substrate Transition | Aligns converter portfolios with PNRS recyclability mandates and pending federal recycled content thresholds. |
| Digital Printing Capability Investment | Enables short-run flexibility for private-label launches while avoiding stranded gravure cylinder assets. |
| Spouted Pouch Assembly Infrastructure | Captures premiumization demand from Minas Gerais yogurt and fermented beverage processors. |
| ANVISA Validation Documentation Systems | Compresses fourteen-month approval timelines for pharmaceutical pouch conversions. |
| Direct-to-Retailer Contract Negotiation | Secures volume allocation as São Paulo supermarket chains consolidate specification authority. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with converter operations managers, food processor procurement leads, pharmaceutical packaging specialists, and INMETRO conformity assessment officers with validation against ANVISA documentation requirements, SEC filings from listed packaging groups, and Brazilian resin import statistics. Bottom-up equipment installation counts across São Paulo, Minas Gerais, and Paraná states were triangulated with top-down demand estimates from supermarket chain packaging procurement disclosures.
Segmentation-level modeling tracked material type, closure technology, end-use application, and form factor dimensions across the projection horizon, with CAGRs derived from equipment capacity expansion announcements and food manufacturing investment pipelines. Forecast inputs incorporated ANVISA regulatory timeline compression effects, PNRS enforcement probability weighting, and stand-up pouch adoption curves from retail channel reset programs.
Inputs from converter operations managers and regulatory affairs specialists were available through the study window; gaps in real-time resin pricing transparency and pending federal decree timing introduce uncertainty bands around substrate transition assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Pillow Pouch Packaging Market
Pouch
Foam Pouch Market
Pouch
Benelux Pouch Packaging Market
Pouch
Ziplock Products Market
Pouch
Clipless Vertical Pouches Market
Pouch
Twin Pouch Packaging Market
Pouch
Compostable Pouches Market
Pouch
Peel Pouches Market
Pouch
Argentina Pouch Packaging Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market
Pouch
Europe Retort Pouches Market
Pouch
Retort Pouch Market
Pouch
Open Mouth Sacks Market
Pouch
Doy Pouch Packaging Market