
 Docks Market | 2026-2036
Docks Market Size, Share, and Industry Trends Forecast 2026-2036
Docks Market Intelligence
Composite decking is repositioning traditional wood in marina construction, cutting lifecycle maintenance by half. Bellingham Marine leverages Pacific Northwest manufacturing scale to dominate commercial harbor projects. EZ Dock sustains brand strength through modular polyethylene systems that simplify owner installation. Meeco Sullivan anchors its position via integrated pile-driving services that compress project timelines.
A dock is a platform structure extending from shore into water, providing vessel mooring, cargo transfer, or recreational access; modern variants employ galvanized steel frames, concrete floatation chambers, or rotationally molded polyethylene pontoons rated for specific load capacities and wave action thresholds. The residential application segment leads volume as waterfront property owners prioritize private boat slips and entertainment platforms. Plastic materials represent the fastest-expanding category, displacing pressure-treated lumber amid tightening chemical leaching restrictions. Custom sizing commands the deepest margin pool, since bespoke engineering for irregular shorelines carries limited price transparency.
The U.S. Army Corps of Engineers governs navigable waterway permits, while EPA stormwater regulations shape runoff containment for industrial dock installations. ISO 9001 quality certification and CE marking govern export-oriented manufacturers serving European marina developers. Stakeholders must monitor evolving coastal zone management policies and material substitution economics to preserve margin structures.
Market Dynamics
Composite materials are absorbing waterfront construction volume as pressure-treated lumber faces chemical leaching restrictions across North American lake communities. The U.S. Army Corps of Engineers permit requirements for navigable waterways compress installation timelines and reshape contractor specialization.
Growth Catalysts
- EPA stormwater regulations:Runoff containment mandates for industrial dock installations drive engineered drainage systems and premium material specification in commercial harbor projects.
- Florida intracoastal demand:Salt-resistant composite decking commands premium positioning as waterfront residential development accelerates across the state's canal networks.
- Modular polyethylene systems:Simplified owner installation reduces contractor dependency and expands addressable market to DIY-capable waterfront property owners.
Market Restraints
- Galvanized steel input costs:Frame material volatility compresses margin for fixed-price commercial contracts and forces escalation clauses.
- Pile-driving equipment concentration:Specialized marine construction fleets cluster in Pacific Northwest and Gulf Coast hubs, creating regional capacity bottlenecks.
- Concrete floatation chamber weight:Transportation logistics limit sourcing radius and inflate landed costs for inland lake projects.
Strategic Opportunities
- ISO 9001 certification:Quality system investment opens European marina developer procurement channels for export-oriented manufacturers.
- Rotationally molded polyethylene:Convergence with solar panel integration creates off-grid power platforms for remote lake properties.
- CE marking compliance:Regulatory alignment with EU machinery directives enables cross-border harbor equipment sales.
Industry Challenges
- Marine construction labor pipelines:Certified pile-driving operators and underwater welders face generational replacement gaps.
- Legacy wood dock retrofit integration:Irregular shoreline geometries complicate modular system adaptation and inflate engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Docks Market |
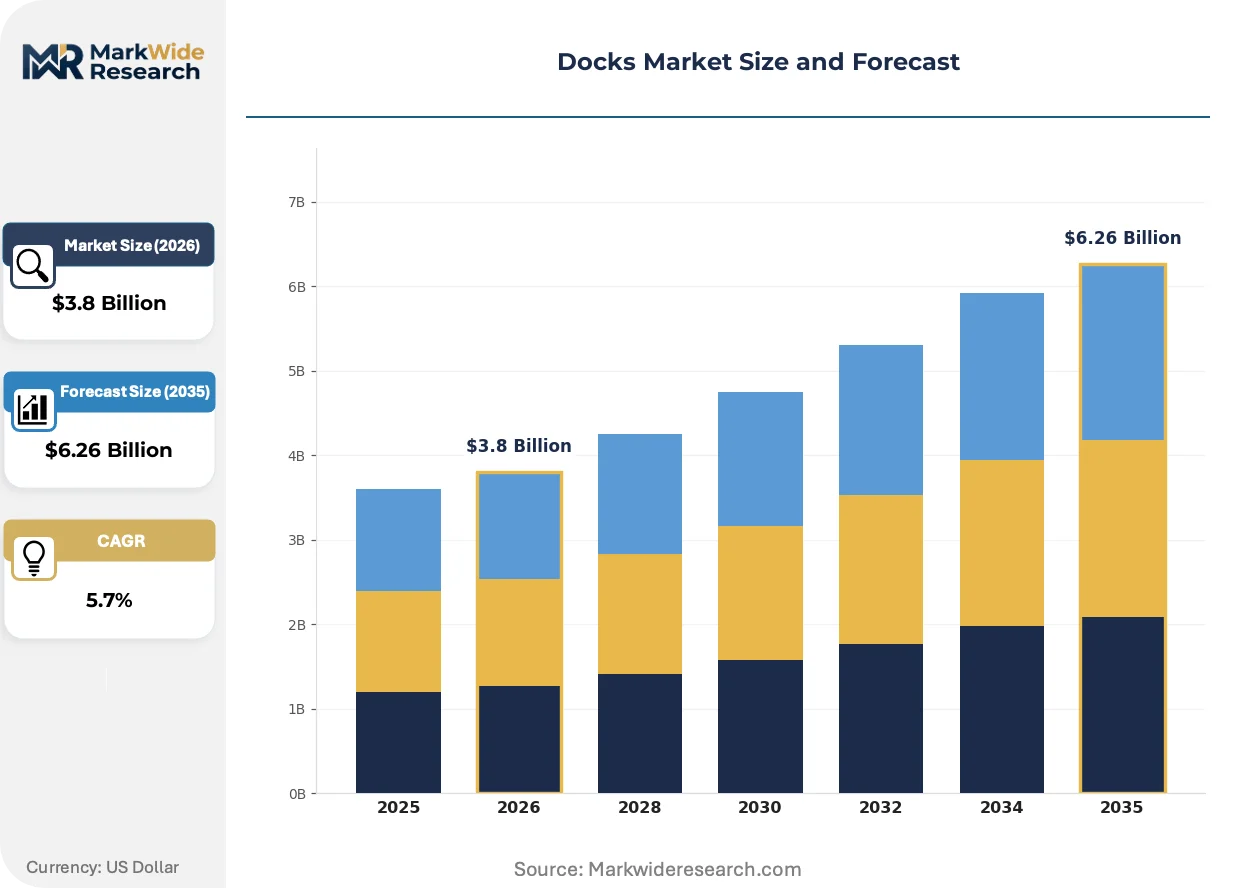
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Floating Docks, Fixed Docks, Cantilever Docks, Portable Docks Material: Wood, Steel, Concrete, Plastic Application: Commercial, Residential, Industrial, Recreational Size: Small, Medium, Large, Custom |
| Companies Covered | AccuDock, Bellingham Marine, EZ Dock, Jet Dock Systems, Marinetek, Meeco Sullivan, MariCorp U.S., PMS Dockmarine, Ingemar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Docks Market Strategic Shifts & Innovations
Material substitution and permitting digitization are compressing project timelines while reshaping competitive differentiation. Three developments warrant particular attention.
Rotationally molded polyethylene is absorbing recreational dock volume through UV-stabilized formulations rated for wave action thresholds. Lake community homeowners are specifying these systems for private boat slips at accelerating rates. The technology is absorbing maintenance burden from traditional wood and enabling owner-managed seasonal removal.
REACH chemical restrictions in Europe are accelerating material disclosure requirements for pressure-treated lumber exports. Manufacturers serving cross-border marina developers must document preservative composition through extended supply chains. CE-marked composite alternatives are capturing specification share in Mediterranean harbor renovations.
Permit pre-consultation services are bundling engineering and regulatory navigation for waterfront property owners. Full-service dock contractors are displacing fragmented designer-installer relationships in Florida's intracoastal markets. This consolidation is most visible in Tampa Bay and Fort Lauderdale yacht basin clusters.
Docks Market Segmentation
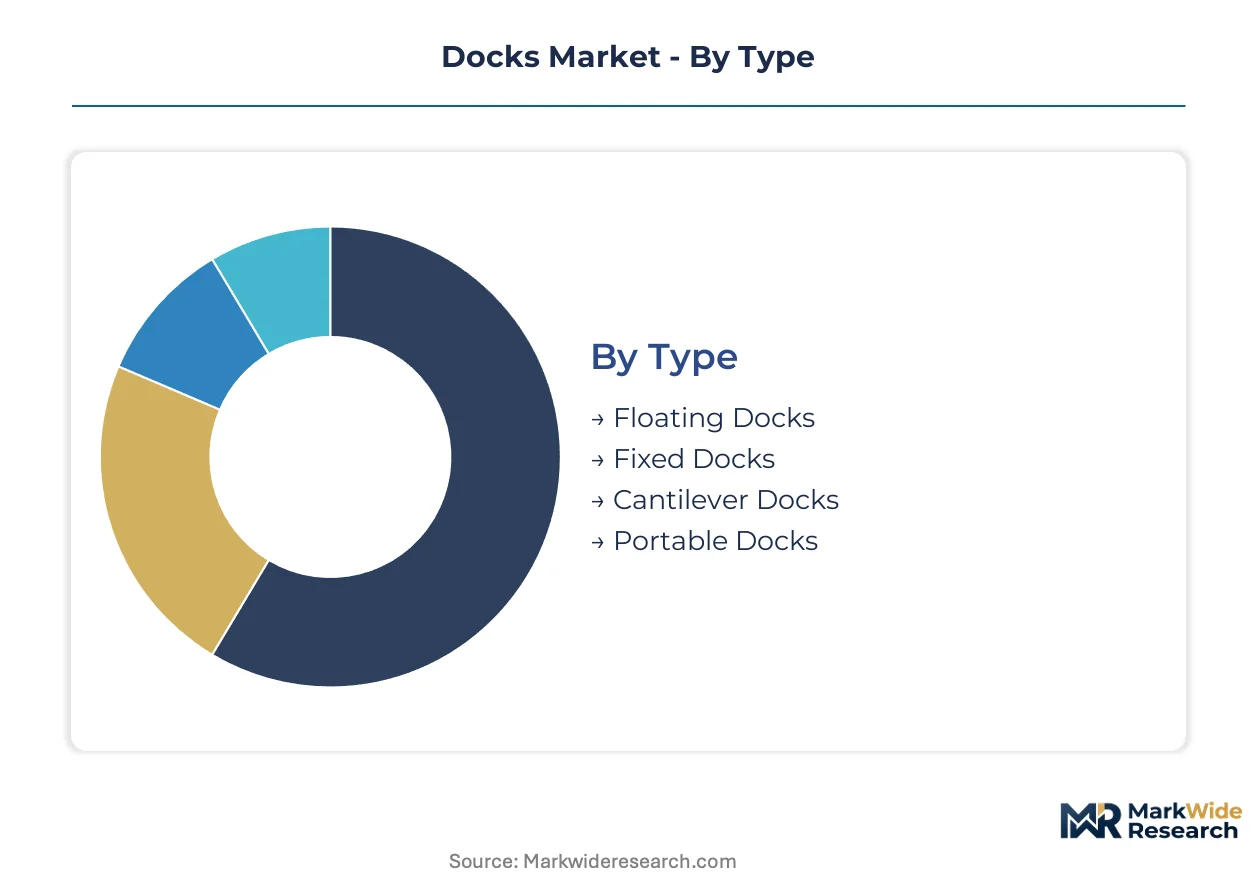
Dock specification varies sharply by water depth, wave exposure, and shoreline geometry. Material selection and sizing decisions cascade through permit complexity, installation cost, and lifecycle maintenance burden. Understanding segment boundaries clarifies where margin pools concentrate and where commoditization threatens.
Type:
Floating dock systems dominate manufacturing scale in the Great Lakes basin where water level fluctuations exceed six feet seasonally.
- Floating Docks:Polyethylene pontoons or concrete chambers provide buoyant platforms that rise and fall with tide or reservoir level. Demand clusters in Florida's intracoastal waterways and Lake Michigan shoreline communities where fixed structures face permit restrictions.
- Fixed Docks:Pile-driven or crib-supported platforms anchored to lakebed or seabed deliver stability in high-wave environments. Specified for Atlantic coastal marinas and Pacific Northwest harbor installations where storm surge exposure demands rigid mooring.
- Cantilever Docks:Shore-mounted frames extend over water without bottom contact, simplifying permit navigation in environmentally sensitive wetlands. Deployed across Minnesota's Boundary Waters and Adirondack lake regions.
- Portable Docks:Modular sectional systems enable seasonal removal and reconfiguration. Popular among Wisconsin and Michigan cabin owners seeking ice-damage avoidance.
Today's leader: Floating Docks. Tomorrow's challenger: Cantilever Docks.
Material:
Raw material volatility and chemical regulation are fragmenting supply sources across North American manufacturing.
- Plastic:Rotationally molded polyethylene and advanced composites displace legacy materials through UV stabilization and salt corrosion resistance. Florida waterfront developers specify these systems for canal-front properties facing EPA stormwater scrutiny.
- Wood:Pressure-treated lumber retains cost advantage in inland lake markets despite tightening leaching restrictions. Wisconsin and Minnesota residential installations still specify cedar and tropical hardwoods for aesthetic matching.
- Steel:Galvanized frames anchor commercial harbor infrastructure. Gulf Coast and Pacific Northwest fabricators concentrate production capacity for marina developers.
- Concrete:Precast floatation chambers deliver mass stability for yacht basins and industrial loading facilities. Transportation radius limits restrict deployment beyond coastal manufacturing hubs.
Plastic materials are expanding most quickly as regulatory pressure and maintenance economics converge.
Application:
End-use differentiation determines engineering standards, insurance requirements, and permit jurisdiction.
- Residential:Private boat slips and entertainment platforms drive volume across lake community property markets. DIY installation capability shapes product specification toward modular polyethylene systems.
- Commercial:Marina operations and yacht basin infrastructure demand engineered load ratings and Coast Guard compliance. Concentrated in Florida, California, and Washington coastal clusters.
- Industrial:Cargo transfer facilities and energy sector marine terminals require heavy-duty pile structures. Subject to U.S. Army Corps of Engineers navigable waterway permits.
- Recreational:Swim platforms and temporary event structures prioritize rapid deployment. Seasonal demand peaks in Great Lakes and Northeast lake regions.
Residential commands current volume leadership. Commercial carries the steepest margin trajectory.
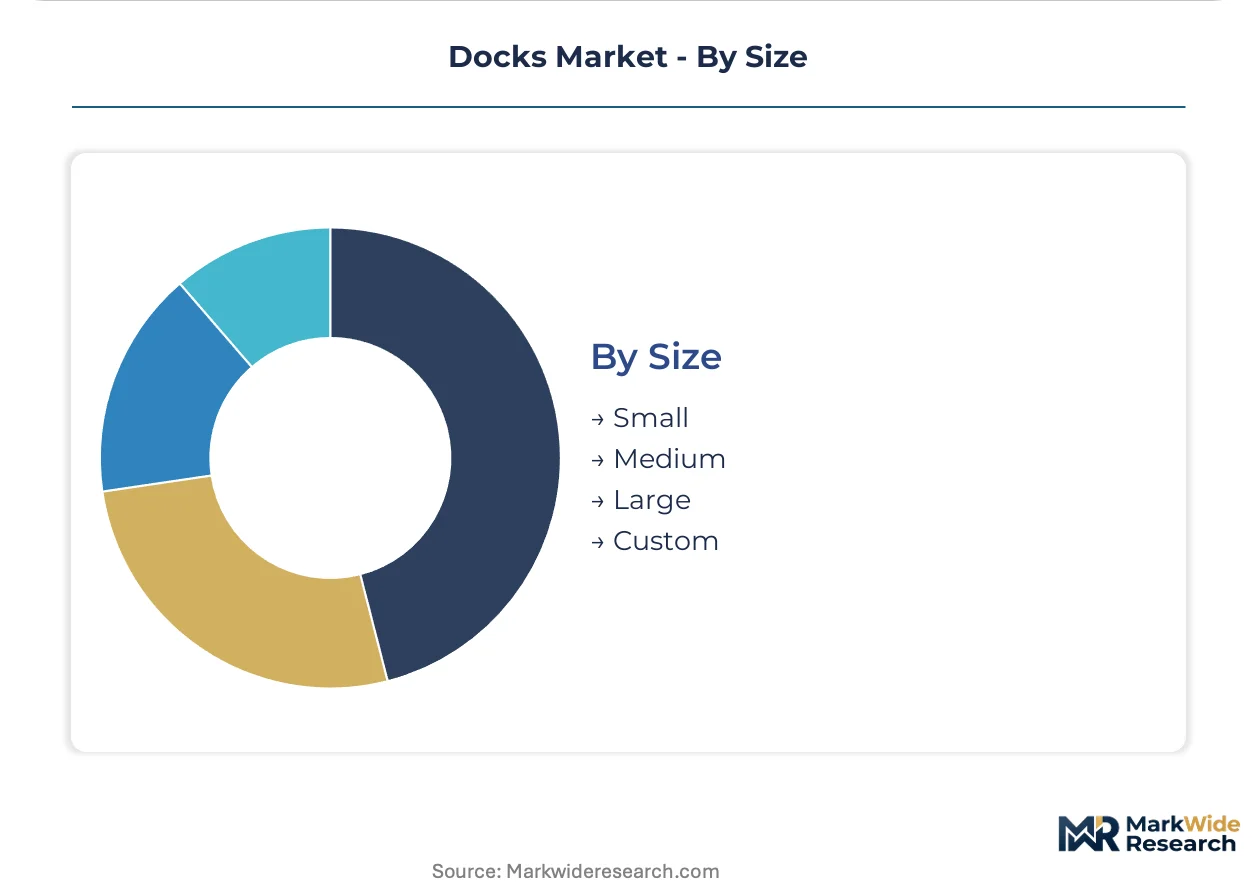
Size:
Project scale dictates contractor specialization and pricing transparency.
- Custom:Bespoke engineering for irregular shorelines carries limited price benchmarking and deepest margin capture. Specified for high-value waterfront estates in the Hamptons, Lake Tahoe, and coastal Maine.
- Large:Multi-slip marina configurations require integrated utility routing and fire suppression systems. Deployed for commercial harbor expansions.
- Medium:Standard residential configurations balance cost and functionality across typical lakefront lots.
- Small:Single-vessel platforms and kayak launches minimize permit complexity. Popular for urban waterfront access programs.
Custom sizing defends margin pools. Medium formats face the sharpest commoditization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's intracoastal waterfront developments concentrate residential dock demand, while U.S. Army Corps of Engineers permit requirements reshape installation compliance across navigable waterways. Lake Michigan communities and Pacific Northwest harbor clusters complete the dominant demand triangle.
United States
Florida canal-front properties and Great Lakes seasonal installations drive polyethylene system adoption. EPA stormwater regulations mandate runoff containment for commercial harbor projects. Tampa Bay and Fort Lauderdale yacht basin clusters consolidate full-service contractor relationships.
Canada
Ontario lake communities and British Columbia coastal marinas prioritize ice-damage-resistant portable systems. Transport Canada marine safety standards govern commercial installation compliance. Vancouver Island fabricators concentrate rotationally molded polyethylene production capacity.
Germany
REACH chemical restrictions accelerate composite decking substitution in Baltic Sea marina renovations. CE marking compliance opens procurement channels for export-oriented manufacturers. Hamburg harbor industrial zones specify galvanized steel frame infrastructure.
Australia
New South Wales coastal residential developments and Queensland tourist marina expansions absorb floating dock volume. ISO 9001 certification requirements shape European export qualification efforts. Perth manufacturing hubs serve Indian Ocean yacht basin projects.
United Arab Emirates
Dubai waterfront luxury estates and Abu Dhabi commercial harbor expansions command custom-engineered pile structures. Local coastal zone management policies restrict fixed installations in environmentally sensitive zones. Jebel Ali industrial clusters concentrate concrete floatation chamber fabrication.
Docks Market Key Industry Players
Modular system standardization dominates the current landscape as manufacturers compress installation timelines and expand DIY-capable addressable markets. The vendor base stratifies across three tiers: integrated pile-driving service providers, rotationally molded polyethylene specialists, and regional wood-frame fabricators. Geographic expansion and strategic partnerships represent the dominant competitive vectors as players seek permit navigation expertise and coastal manufacturing scale.
Within the integrated-service archetype, Meeco Sullivan and Bellingham Marine exemplify vertically structured operators combining engineering, installation, and regulatory compliance capabilities. EZ Dock anchors the modular polyethylene tier through simplified owner-installation systems. These three entities collectively represent the strategic spectrum from full-service project execution to standardized product platforms.
| Leading Market Players |
|---|
| AccuDock |
| Bellingham Marine |
| EZ Dock |
| Jet Dock Systems |
| Marinetek |
| Meeco Sullivan |
| MariCorp U.S. |
| PMS Dockmarine |
| Ingemar |
| Others |
Cost & Logistics Intelligence
EPA stormwater regulations for commercial harbor installations gate qualified supply access and premium-tier pricing power, restricting specification to engineered drainage systems and certified composite materials that command margin premiums over standard polyethylene platforms.
Pricing Analysis
Galvanized steel and polyethylene resin input-cost pass-through dominates dock pricing dynamics, with frame material volatility forcing escalation clauses in fixed-price commercial contracts. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked composite systems from modular polyethylene platforms and pressure-treated lumber alternatives. Pricing pressure stems from concrete floatation chamber transportation logistics that inflate landed costs for inland lake projects. DIY-capable residential buyers in Wisconsin and Michigan exhibit highest price sensitivity, while custom-engineered Hamptons and Lake Tahoe estates show minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements from Florida marina developers and Pacific Northwest harbor contractors mandate multi-supplier qualification for pile-driving services and rotationally molded polyethylene components. Manufacturing concentrates in the United States, Canada, and Germany, with Vancouver Island and Hamburg serving coastal production hubs. Raw material dependencies center on high-density polyethylene resin, marine-grade aluminum, and pressure-treated lumber feedstocks. Supply chain risk manifests in single-source vulnerability for certified pile-driving equipment fleets clustered in Gulf Coast hubs. Distribution runs through full-service dock contractors displacing fragmented designer-installer relationships in Tampa Bay and Fort Lauderdale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as waterfront residential development shifts toward salt-resistant composite specifications and integrated permit-navigation services that command sustained margin premiums.
For Market Incumbents: Deepen backward integration into rotationally molded polyethylene production to capture manufacturing margin and insulate against resin price volatility. Anchor capacity expansion in Vancouver Island and Hamburg to serve Baltic Sea and Pacific Northwest harbor clusters. Defend against modular system commoditization by bundling engineering and regulatory compliance capabilities that compress project timelines. For New Entrants and Emerging Players: Minnesota Boundary Waters cabin owners represent an underserved buyer archetype seeking cantilever dock solutions for environmentally sensitive wetlands with simplified permit navigation. Target Wisconsin and Michigan seasonal removal markets with portable sectional systems that enable ice-damage avoidance. Pursue direct-to-consumer digital channels that reduce contractor dependency and expand DIY-capable addressable markets. For Investors and Strategic Acquirers: Roll-up economics work for regional pile-driving specialists because marine construction labor pipelines face generational replacement gaps that concentrate capability in legacy operators. Five-to-ten year viability hinges on permit navigation expertise and coastal manufacturing scale. Target ISO 9001-certified fabricators serving European marina developer procurement channels. Watch Florida intracoastal permit pre-consultation service bundling as the inflection indicator for contractor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyethylene Production | Captures resin margin and insulates against Gulf Coast petrochemical feedstock volatility. |
| ISO 9001 Certification Investment | Opens Hamburg and Mediterranean marina developer procurement channels for export-oriented manufacturers. |
| Permit Pre-Consultation Service Bundling | Consolidates fragmented designer-installer relationships in Tampa Bay and Fort Lauderdale yacht basins. |
| Modular System Standardization | Expands DIY-capable addressable markets across Wisconsin and Michigan lake communities. |
| CE Marking Compliance Pathway | Enables cross-border harbor equipment sales to Baltic Sea marina renovation projects. |
Research Approach
Direct dialogue with dock installation contractors, marina operations managers, U.S. Army Corps of Engineers permit specialists, polyethylene manufacturing plant managers, and waterfront property developers grounded qualitative insights. Secondary validation drew from EPA stormwater regulation filings, U.S. Coast Guard commercial marina compliance databases, customs trade data for dock material imports, and SEC filings from marine construction equipment manufacturers. Bottom-up segment sizing triangulated against top-down waterfront development permit issuance trends.
Market projections across the analysis window integrated material substitution elasticity models, regulatory compliance cost curves, and regional construction labor availability indices. Segmentation dimensions encompassed dock type, material category, application end-use, and project size tier alongside water depth and wave exposure thresholds. CAGRs derived from historical permit issuance velocity and waterfront residential development pipeline tracking. Forecast inputs included Florida intracoastal canal-front property absorption rates and Great Lakes seasonal installation patterns.
Underlying measurement precision varies by segment; residential polyethylene system volumes carry tighter precision than custom-engineered commercial harbor projects where bespoke engineering obscures benchmarking. Forecasts reflect assumptions around EPA regulatory stability and galvanized steel input cost trajectories. Deviation in U.S. Army Corps of Engineers navigable waterway permit processing timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
Steel Utility Poles Market
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
Heavy Movable Bridges Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Gas Pipeline Infrastructure Market
Infrastructure Construction
Global Transportation Infrastructure Market
Infrastructure Construction
New Zealand Data Center Construction Market