
 Pipe Alignment Clamps Market | 2026-2036
Pipe Alignment Clamps Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Alignment Clamps Market Insights
ASME Section IX qualification is collapsing the supplier base as fabricators demand certified welding alignment equipment. Sumner Manufacturing Co. leverages its domestic production footprint to serve North American pipeline contractors. Mathey Dearman anchors its position through deep specialization in pipe beveling and alignment systems for heavy fabrication. TAG Pipe Equipment Specialists differentiates via hydraulic clamp technology for offshore and subsea applications.
Pipe alignment clamps are mechanical devices that grip, position, and hold cylindrical workpieces during welding or fabrication, typically rated for pipe diameters from 2 inches to over 60 inches and load capacities exceeding 10,000 pounds to maintain root gap and angular alignment. Their primary purpose is to eliminate fit-up variation and reduce rework in pressure-boundary welding across pipeline, structural, and process piping construction. Steel alloy construction dominates material selection due to strength-to-cost ratios in high-load pipeline construction, while aluminum variants gain traction in shipbuilding and marine fabrication where weight reduction matters. Hydraulic clamp types command premium positioning in oilfield services and power generation, where remote actuation and precise force control justify higher capital outlay.
OSHA welding safety standards and API 1104 pipeline welding codes govern equipment specification in the United States, while China's GB standards and NMPA-equivalent pressure equipment regulations shape domestic procurement. The EU Machinery Directive and CE marking requirements enforce design safety validation for clamps sold into European fabrication markets. Stakeholders must monitor how carbon border adjustments and domestic content rules redirect sourcing decisions across energy infrastructure supply chains.
Market Dynamics
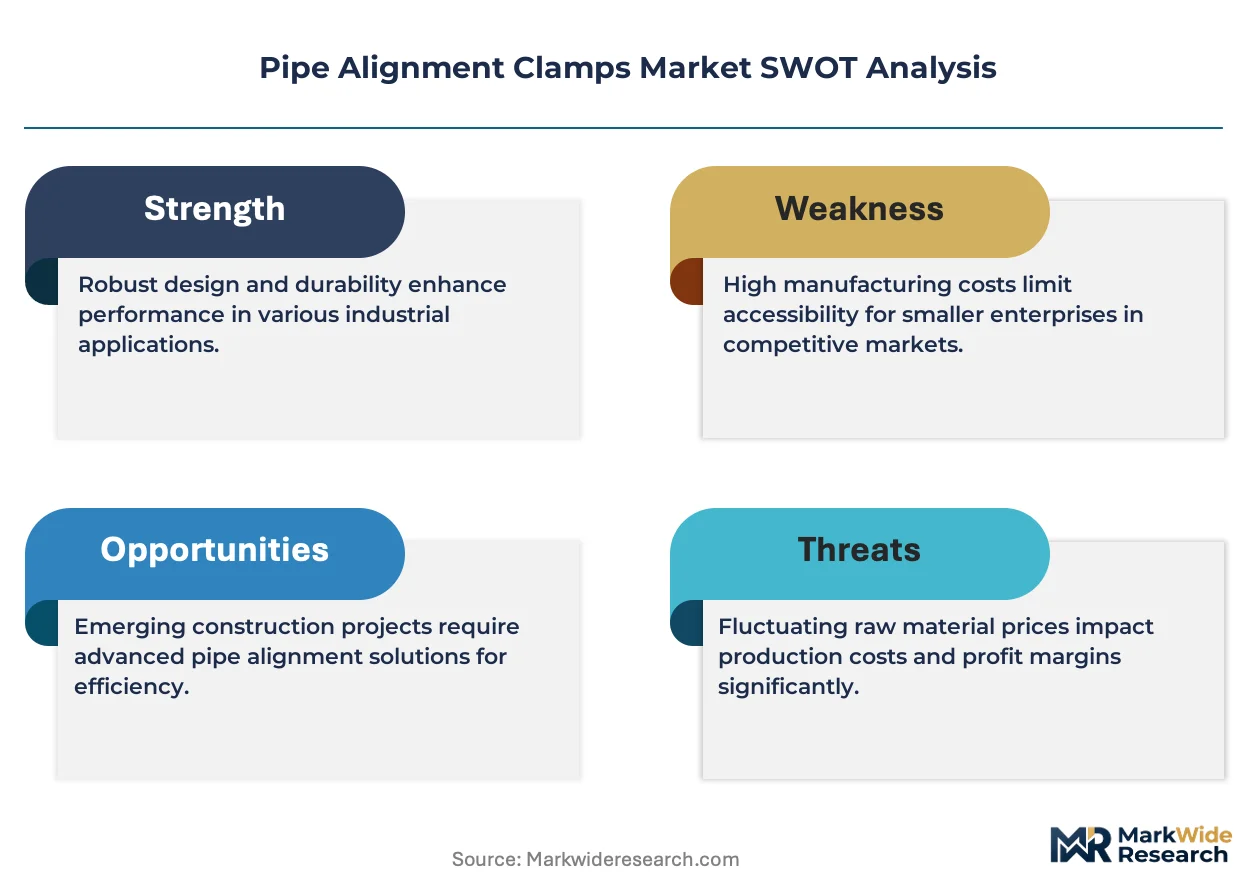
ASME Section IX certification requirements are compressing the supplier base while hydraulic actuation technology reconfigures performance expectations across pipeline construction procurement.
Growth Catalysts
- API 1104 Pipeline Codes:North American contractors now mandate certified alignment equipment for pressure-boundary welding, eliminating uncertified suppliers from bid lists.
- Offshore Subsea Expansion:Deepwater oilfield development in the Gulf of Mexico and North Sea drives specification of remote-actuated hydraulic clamps rated for subsea pressure environments.
- China Energy Infrastructure:GB standards enforcement and state-owned pipeline investment accelerate domestic procurement of heavy-duty steel alloy clamps for cross-country transmission projects.
Market Restraints
- Steel Alloy Input Volatility:Chrome-molybdenum and high-carbon steel price swings compress fabrication margins for clamp manufacturers serving price-sensitive structural markets.
- Specialized Supplier Concentration:ASME-qualified hydraulic clamp production concentrates among a handful of domestic fabricators, creating bottleneck risk for large-diameter pipeline projects.
- Manual Clamp Substitution:Low-complexity fabrication in developing markets retains preference for mechanical screw-type clamps, limiting hydraulic penetration in cost-driven segments.
Strategic Opportunities
- India Pipeline Buildout:Petroleum and Natural Gas Regulatory Board pipeline authorization expansions create first-mover positioning for certified equipment suppliers in a historically underpenetrated market.
- Carbon Capture Infrastructure:CO2 transport pipeline construction requires corrosion-resistant clamp specifications, opening premium positioning for specialized coating and material providers.
- EU Green Deal Alignment:Machinery Directive updates emphasizing repairability and modular design create competitive openings for European manufacturers with circular-economy-ready product architectures.
Industry Challenges
- Welding Inspector Certification Backlogs:ASME Section IX-qualified welder availability constraints delay field deployment of alignment equipment on fast-track pipeline schedules.
- Hydraulic System Integration Complexity:Remote-actuated clamp retrofitting with legacy pipeline construction equipment requires custom engineering, extending project commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Alignment Clamps Market |
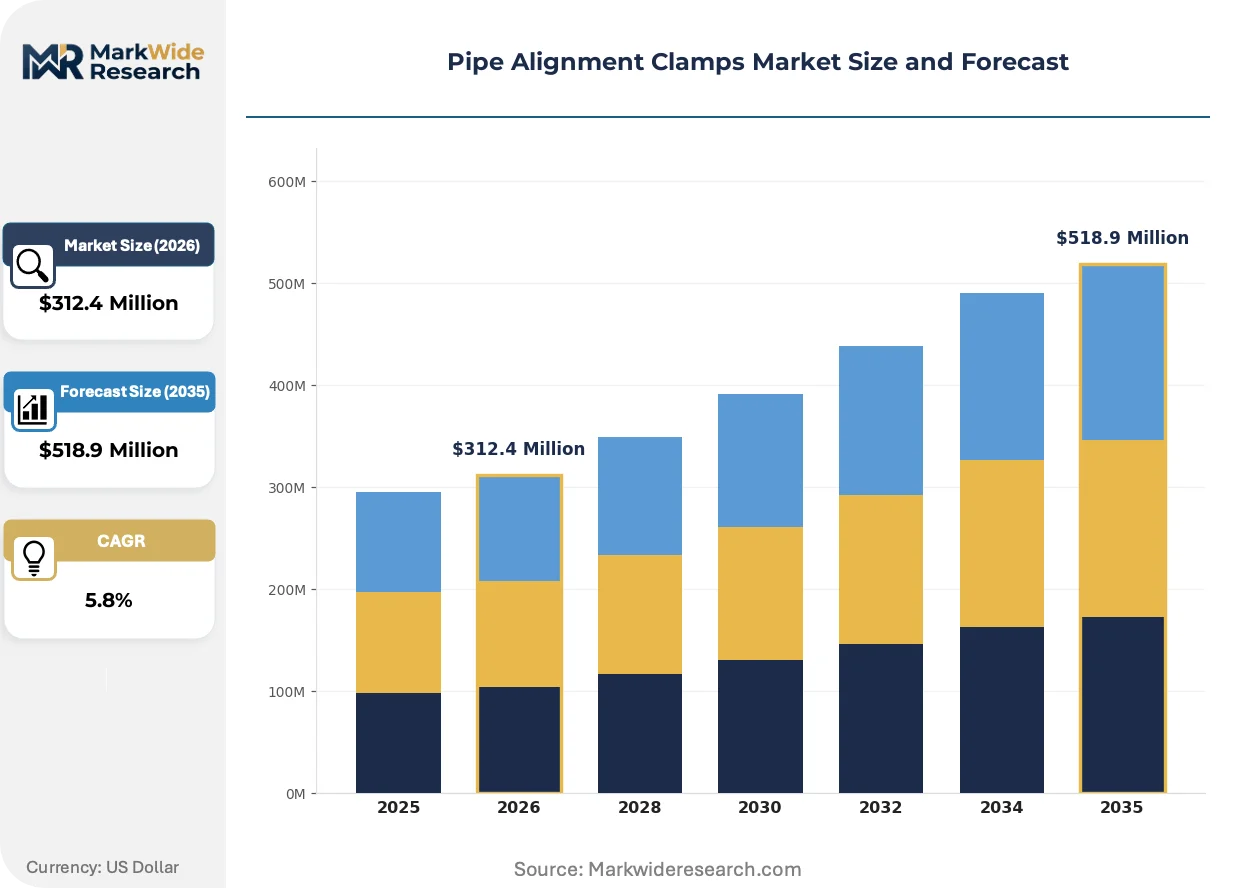
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Clamp Type: Single Screw, Double Screw, Chain Style, Hydraulic, Pneumatic Material: Steel Alloy, Aluminum, Cast Iron, Stainless Steel, Copper Application: Pipeline Construction, Heavy Fabrication, Shipbuilding, Oilfield Services, Power Generation End User: Fabricators, Contractors, Metal Workshops, Marine Engineers, Energy Providers |
| Companies Covered | Sumner Manufacturing Co., Mathey Dearman, TAG Pipe Equipment Specialists, Sawyer Manufacturing Company, H&M Pipe Beveling Machine Company, Gullco International, Esco Tool, Rothenberger, REMS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Alignment Clamps Market Trends and Innovations
Digital force-feedback systems and modular clamp architectures are reconfiguring how contractors specify alignment equipment, while regulatory pressure on welding quality accelerates technology refresh cycles.
Laser-guided root gap measurement systems integrated into hydraulic clamp bodies are fragmenting traditional fit-up workflows. Offshore contractors in the North Sea and Gulf of Mexico specify these systems for subsea pipeline tie-ins where diver access is limited. The technology is fragmenting procurement patterns by decoupling alignment precision from operator skill levels, compressing training requirements while elevating equipment capital intensity.
EU Machinery Directive 2006/42/EC amendments enforcing functional safety validation for powered clamping equipment reshape European procurement specifications. Fabricators in Germany and the Netherlands now require third-party CE marking with documented force-limiting controls. Hydraulic clamp suppliers serving North Sea offshore markets accelerate safety-certified product line development to maintain European market access.
Rental and lease-to-own equipment models displace outright purchase in North American pipeline contracting. Mid-size construction firms in Texas and Alberta shift toward fleet flexibility over capital ownership, consolidating demand with specialized oilfield services distributors. This reconfiguration concentrates procurement influence among rental fleet operators who standardize on multi-diameter compatible clamp platforms.
Pipe Alignment Clamps Market Segmentation
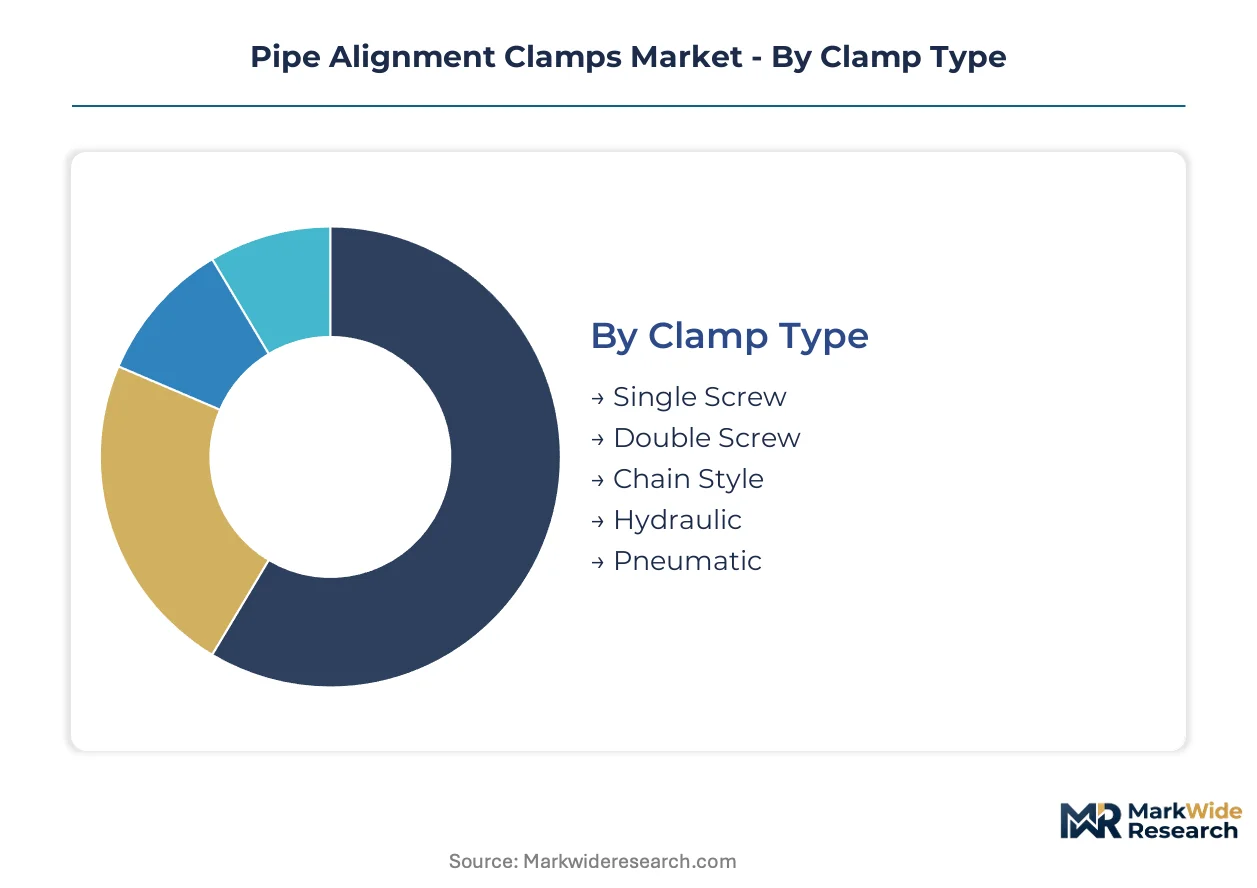
Procurement patterns for pipe alignment clamps diverge sharply across clamp mechanisms, material grades, and end-use applications. Contractors specify equipment based on load requirements, corrosion exposure, and welding code compliance rather than interchangeable commodity selection.
Clamp Type:
Domestic production concentrates on mechanical screw variants, while hydraulic systems flow through specialized import channels serving offshore contractors.
- Hydraulic:Remote-actuated systems rated for 10,000+ pound clamping force dominate Gulf of Mexico and North Sea subsea tie-ins. API 1104-qualified contractors in Texas and Louisiana specify these for deepwater pipeline construction where diver access is restricted.
- Double Screw:Dual-point mechanical actuation delivers balanced load distribution for heavy-wall transmission pipe. German fabricators serving Ruhr industrial clusters favor this configuration for ASME Section IX pressure-boundary welding.
- Single Screw:Compact mechanical design suits field repair and maintenance applications with limited access.
- Chain Style:Wraparound gripping mechanism accommodates variable diameters without size-specific inventory.
- Pneumatic:Compressed-air actuation finds niche use in shipyard environments with existing shop air infrastructure.
Hydraulic holds the largest share; momentum sits with double screw configurations in European heavy fabrication.
Material:
Cost tiers separate commodity structural grades from premium corrosion-resistant alloys specified for process piping and marine exposure.
- Steel Alloy:Chrome-molybdenum and high-carbon formulations deliver strength-to-cost ratios for cross-country transmission pipeline construction. Chinese state-owned pipeline operators specify GB-standard steel alloy clamps for West-East Gas Pipeline expansion segments.
- Stainless Steel:Austenitic and duplex grades resist chloride attack in offshore salt spray and CO2 transport service. North Sea contractors facing EU Machinery Directive corrosion requirements specify 316L and super-duplex variants for subsea installations.
- Aluminum:Lightweight properties serve shipbuilding and marine fabrication where weight reduction improves handling ergonomics.
- Cast Iron:Lower-cost option for stationary shop applications with minimal transport requirements.
- Copper:Specialized grounding and electrical continuity applications in explosive atmosphere environments.
Steel alloy dominates volume; stainless steel is climbing the fastest on corrosion-resistant infrastructure specifications.
Application:
Customer type dictates performance requirements, with energy infrastructure commanding certified equipment and structural markets tolerating standard mechanical grades.
- Pipeline Construction:Pressure-boundary welding for transmission and distribution networks drives specification of ASME-qualified hydraulic and double-screw systems. FERC-regulated interstate projects in the United States mandate certified alignment equipment for girth weld qualification.
- Oilfield Services:Downstream maintenance and midstream gathering systems require portable, rapid-deployment clamps for flowline repair. Alberta oil sands operators specify cold-weather-rated hydraulic systems for sub-zero commissioning.
- Heavy Fabrication:Pressure vessel and structural steel shops utilize mechanical screw clamps for repetitive fit-up operations.
- Shipbuilding:Marine classification society rules govern material selection and safety factor requirements for hull and piping fabrication.
- Power Generation:Combined-cycle and nuclear piping specifications impose additional material traceability and documentation burdens.
Pipeline construction holds the largest share; oilfield services is expanding most quickly on North American shale infrastructure replacement cycles.
End User:
Procurement concentration varies with project scale, from capital-intensive pipeline contractors to fragmented metal workshop segments.
- Contractors:Turnkey construction firms with ASME certification maintain owned fleets of multi-diameter hydraulic systems. Texas and Alberta pipeline contractors increasingly shift toward rental models for fleet flexibility.
- Fabricators:ASME-accredited pressure vessel shops specify certified alignment equipment for shop and field code welding. German fabricators in Duisburg and Dortmund industrial corridors standardize on CE-marked hydraulic platforms.
- Metal Workshops:General fabrication and repair facilities utilize mechanical screw clamps for non-code structural work.
- Marine Engineers:Shipyard and offshore platform construction teams specify corrosion-resistant and lightweight configurations.
- Energy Providers:Utility and pipeline operator maintenance divisions procure specialized clamps for in-service repair and hot tapping operations.
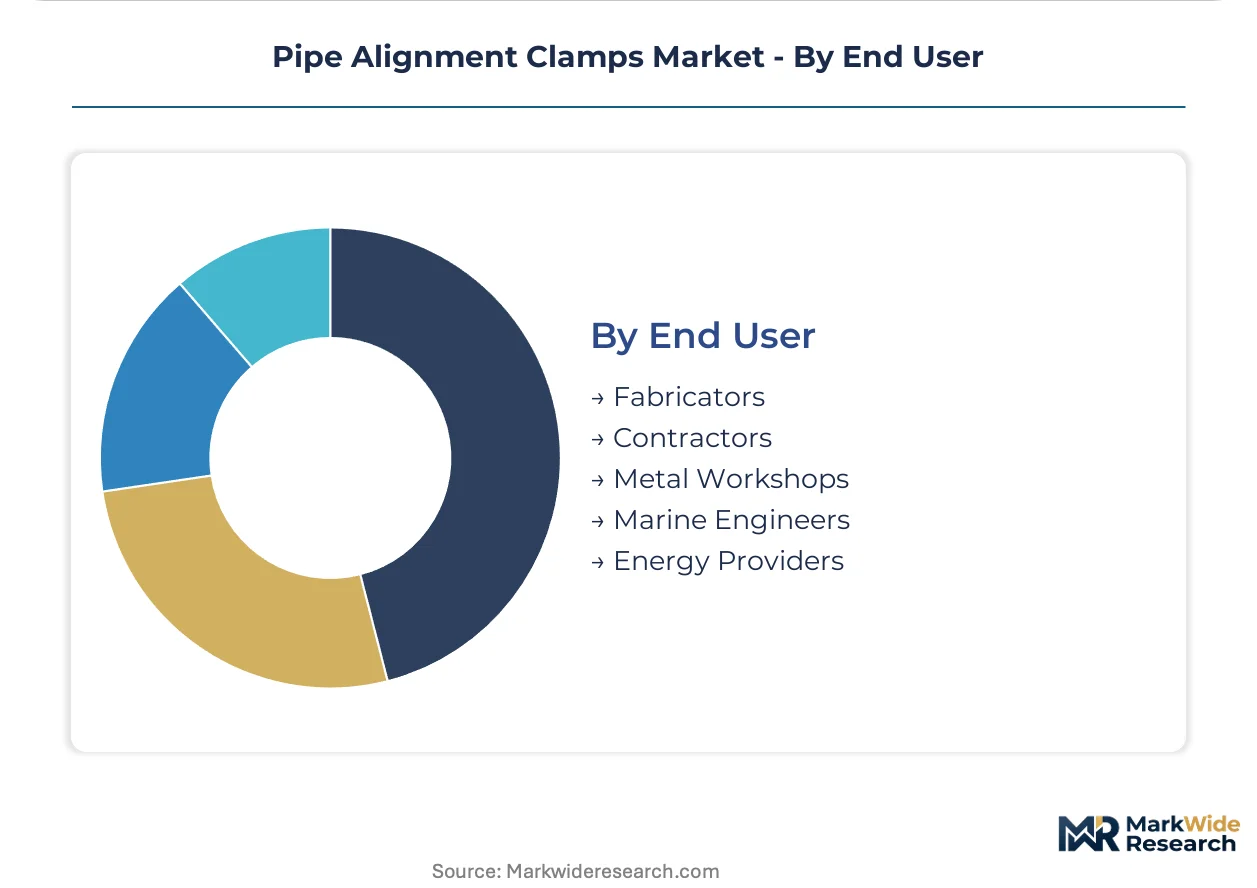
Contractors hold the largest share; fabricators are gaining share fastest on reshoring of pressure equipment manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network expansion underwrites United States demand concentration for certified alignment equipment. Cross-border transmission corridors and subsea tie-in projects across multiple geographies drive specification divergence between mechanical and hydraulic clamp platforms.
United States
FERC-regulated interstate pipeline construction mandates ASME-qualified alignment equipment for girth weld certification. OSHA welding safety standards and API 1104 codes govern procurement specifications for pressure-boundary work. Texas and Louisiana Gulf Coast contractors drive hydraulic clamp demand for deepwater pipeline construction where diver access faces restrictions.
China
West-East Gas Pipeline expansion segments and state-owned transmission infrastructure accelerate domestic procurement of heavy-duty steel alloy clamps. GB standards enforcement and NMPA-equivalent pressure equipment regulations shape certification requirements for fabrication equipment. Sichuan-Chongqing industrial corridors concentrate demand for large-diameter pipeline construction serving shale gas development zones.
Germany
Ruhr industrial cluster pressure vessel fabricators standardize on CE-marked hydraulic platforms for ASME Section IX welding operations. EU Machinery Directive amendments enforcing functional safety validation reshape equipment specifications across European fabrication markets. Duisburg and Dortmund industrial corridors anchor demand for double-screw configurations in heavy fabrication applications.
India
Petroleum and Natural Gas Regulatory Board pipeline authorization expansions create first-mover positioning for certified equipment suppliers in historically underpenetrated transmission markets. BIS standards and CEA regulations govern pressure equipment procurement for cross-country energy infrastructure. Gujarat and Maharashtra industrial zones concentrate fabrication activity serving refinery and petrochemical expansion projects.
United Arab Emirates
ADNOC offshore field development and subsea pipeline construction drive specification of corrosion-resistant clamp systems for salt spray environments. MOHAP-equivalent equipment safety regulations and marine classification requirements shape procurement criteria for marine fabrication. Dubai and Abu Dhabi fabrication yards anchor demand for hydraulic platforms serving Gulf of Arabia deepwater projects.
Pipe Alignment Clamps Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and geographic reach, producing a tiered structure where ASME qualification separates premium suppliers from commodity mechanical clamp fabricators. The supplier base compresses around hydraulic actuation capability and domestic production footprint advantages. Three archetypes dominate: domestic-certified hydraulic specialists, European precision-mechanical fabricators, and diversified oilfield services distributors. Consolidation concentrates among rental fleet operators standardizing multi-diameter platforms, while capacity expansion targets subsea-rated hydraulic production.
Within the domestic-certified tier, Sumner Manufacturing Co. and Mathey Dearman occupy positions anchored in North American pipeline contractor relationships. TAG Pipe Equipment Specialists exemplifies the offshore-specialist archetype, with company naming indicating equipment focus rather than diversified industrial supply. These three represent distinct competitive vectors: domestic production scale, beveling-alignment system integration, and hydraulic technology specialization for restricted-access environments.
| Leading Market Players |
|---|
| Sumner Manufacturing Co. |
| Mathey Dearman |
| TAG Pipe Equipment Specialists |
| Sawyer Manufacturing Company |
| H&M Pipe Beveling Machine Company |
| Gullco International |
| Esco Tool |
| Rothenberger |
| REMS |
| Others |
Pricing and Supply Chain Analysis
Project-based contracting for large-diameter pipeline construction locks in multi-year equipment procurement schedules, binding contractors to certified suppliers while freezing price visibility against steel alloy input volatility. Texas and Alberta pipeline operators negotiate fleet rental agreements that transfer capital risk to distributors, compressing margin buffers for manufacturers serving price-sensitive structural fabrication segments.
Pricing Analysis
Volume-discount tiering separates ASME-certified hydraulic systems from commodity mechanical screw clamps, with premium positioning justified by API 1104 welding code compliance and subsea pressure ratings. Chrome-molybdenum steel alloy grade and ASME Section IX certification level drive price differentiation between transmission pipeline and general fabrication equipment. Cost compression in mechanical clamp tiers is intensifying because Chinese state-owned pipeline operators source domestically produced GB-standard equipment at scale. Structural metal workshops exhibit highest price sensitivity, while Gulf of Mexico offshore contractors accept premium pricing for remote-actuated systems with diverless deployment capability.
Supply Chain Analysis
China and the United States anchor steel alloy clamp fabrication, with Germany specializing in CE-marked hydraulic platforms for European heavy fabrication. Raw material feeds draw from chrome-molybdenum steel mills, high-carbon alloy foundries, and hydraulic actuator component suppliers concentrated in industrial corridors. Single-source vulnerability concentrates in ASME-qualified hydraulic cylinder production, where domestic fabrication capacity limits expansion. Distribution runs through specialized oilfield services distributors and rental fleet operators standardizing on multi-diameter compatible platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers creates niche positioning opportunities as ASME Section IX requirements compress the supplier base and displace uncertified fabricators from bid lists. Rental model proliferation and carbon capture infrastructure specifications open entry paths for specialized coating and modular design providers.
For Market Incumbents: Fortify certification depth by expanding ASME Section IX welding procedure qualification coverage to capture FERC-regulated interstate pipeline contracts. Backward integration into chrome-molybdenum steel alloy sourcing hedges against input cost volatility threatening fabrication margins. Capacity addition in Texas and Louisiana industrial corridors secures proximity to Gulf of Mexico deepwater construction demand. For New Entrants and Emerging Players: ASME Section IX certification fast-track through accredited third-party welding procedure qualification offers entry into North American pressure-boundary welding equipment procurement. India pipeline buildout under Petroleum and Natural Gas Regulatory Board authorization expansions represents the most penetrable geography for first-mover positioning. Go-to-market leverage rests on partnering with established oilfield services distributors operating rental fleet networks. For Investors and Strategic Acquirers: Capital is best deployed toward hydraulic clamp specialists with subsea pressure ratings and European CE marking compliance, positioned for carbon capture transport pipeline construction cycles. Long-term viability hinges on circular-economy-ready product architectures aligned with EU Machinery Directive repairability amendments. Watch for inflection in domestic content rule enforcement across energy infrastructure supply chains as signal for sourcing reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Certification Expansion | API 1104 compliance unlocks FERC-regulated interstate pipeline contractor procurement lists. |
| Subsea Hydraulic Platform Development | Gulf of Mexico and North Sea diverless tie-in specifications command premium positioning. |
| Rental Fleet Network Partnership | Texas and Alberta contractor shifts toward flexibility consolidate demand with distributor channels. |
| Corrosion-Resistant Alloy Integration | CO2 transport pipeline specifications open premium tier for 316L and super-duplex variants. |
| Modular Clamp Architecture Investment | EU Machinery Directive repairability requirements favor circular-economy-ready product designs. |
Research Methodology
A spread of perspectives from pipeline construction project managers, ASME-accredited fabrication shop engineers, oilfield services procurement leads, and hydraulic equipment aftermarket specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against API 1104 welding code documentation, FERC interstate pipeline filings, GB standards enforcement records, and EU Machinery Directive amendment texts. Bottom-up equipment shipment tracking and top-down energy infrastructure investment flow analysis provided triangulation anchors.
Segmentation dimensions modeled span clamp mechanism type, material grade tier, end-use application, and regional regulatory framework cluster across the projection horizon. CAGRs derive from equipment replacement cycle analysis, pipeline construction authorization trajectories, and welding inspector certification capacity constraints. Industry-specific forecast inputs incorporate West-East Gas Pipeline expansion segments, Permian Basin gathering system buildouts, and North Sea subsea tie-in project pipelines.
Decision-makers should treat outputs as directional under sustained energy infrastructure investment and stable steel alloy input cost assumptions; material deviation would warrant model refresh. Specific risks that could revise trajectories include ASME-qualified welder availability bottlenecks delaying field deployment, carbon border adjustment implementation redirecting sourcing decisions, and hydraulic system integration complexity extending project commissioning timelines. Recalibration cycles align with material shifts in pipeline construction authorization rates and welding code amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Asia Pacific Power Tools & Hand Tools Market
Tools
Clamps Market
Tools
Cutting Tool Inserts Market
Tools
Paint Spray Guns Market
Tools
Metal Cutting Tools Market
Tools
Boring-Milling Machines Market
Tools
Drilling Tools Market
Tools
US Hitter Based Hand Tools Market
Tools
Hand and Power Tools Market
Tools
Tapping Machine Market
Tools
Ripper Market
Tools
Machine Bench Vices Market
Tools
2D Laser Cutting Machine Market
Tools
Tool Setting Gauges Market
Tools
Adoption of Benelux Power Tools Market
Tools
Caulking Gun Market