
 Global Port Infrastructure Market | 2026-2036
Global Port Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Global Port Infrastructure Market Outlook
Project finance tied to long-term concession agreements is narrowing the field of viable bidders for greenfield port developments. DP World leverages its global terminal network to secure multi-decade leases across emerging trade corridors. A.P. Moller-Maersk anchors its competitiveness through integrated shipping-terminal logistics control. Adani Ports and SEZ dominates Indian subcontinent capacity expansion with captive hinterland rail linkages.
Global port infrastructure encompasses the fixed and mobile assets enabling vessel berthing, cargo transfer, and intermodal connectivity, including quay walls with 15-20 meter depth specifications, gantry cranes rated above 50 TEU hourly, and automated guided vehicle systems. Container ports command the largest capital deployment pools due to super-post-Panamax vessel accommodation requirements. Bulk ports sustain steadier throughput volumes tied to commodity contract structures, while passenger terminals represent a specialized niche with distinct security and customs infrastructure demands.
The International Maritime Organization's carbon intensity regulations, the EU Green Deal's shore power mandates, and China's MEE emissions standards are collectively forcing terminal operators to retrofit electrified cargo handling equipment and onshore power supply systems. ISO container security standards and the WTO Trade Facilitation Agreement shape customs infrastructure investment priorities. Stakeholders must weigh concession tenure lengths against decarbonization capital cycles when committing to new terminal developments.
Market Dynamics
Container shipping lines are consolidating terminal concessions into multi-decade agreements, compressing bidding competition and forcing operators to front-load electrification capex against uncertain carbon accounting frameworks. This concession concentration is restructuring how greenfield port developments secure project finance.
Growth Catalysts
- EU Green Deal Shore Power Mandates:Terminal operators in Rotterdam and Hamburg are retrofitting onshore power supply systems to accommodate vessel electrification requirements, triggering synchronized cargo handling equipment upgrades.
- Super-Post-Panamax Vessel Proliferation:Shipping lines are deploying 24,000 TEU vessels through the Suez Canal route, forcing quay wall dredging to 20-meter depths at Ningbo-Zhoushan and Singapore.
- India's Sagarmala Program:Captive rail linkages from Mundra and Hazira ports to inland container depots are reducing dwell times and attracting transshipment cargo from Bangladesh and Sri Lanka.
Market Restraints
- Steel and Concrete Input Volatility:Quay wall construction faces cost pressure from fluctuating reinforcing steel prices and specialized marine-grade concrete supply concentrated in China and Turkey.
- MEE Emissions Compliance Burden:China's Ministry of Ecology and Environment standards are forcing simultaneous retrofit of diesel gantry cranes and harbor craft, straining operator balance sheets.
- Sub-Regional Hinterland Congestion:Road and rail bottlenecks around Jakarta's Tanjung Priok and Manila's Port of Manila limit throughput expansion regardless of berth capacity additions.
Strategic Opportunities
- Vietnam's Lach Huyen Deep-Water Development:Hai Phong's second-phase container terminal offers first-mover positioning for 18,000 TEU vessel calls before Cai Mep-Thi Vai saturation.
- Green Hydrogen Bunkering Infrastructure:Convergence of electrolyzer technology and ammonia cracking systems is enabling pilot fueling stations at Rotterdam and Singapore ahead of IMO 2050 targets.
- Automated Guided Vehicle Integration:Vertical transport systems combining AGVs with twin-lift ship-to-shore cranes are compressing vessel turnaround times at Dubai's Jebel Ali Terminal 4.
Industry Challenges
- Electrical Grid Synchronization:Shore power installation at older terminals requires utility-scale transformer upgrades and frequency converters incompatible with existing substation layouts.
- Cyber-Physical System Certification:Terminal operating systems integrating crane automation, vessel traffic management, and customs platforms face extended security accreditation timelines under ISO 27001 maritime extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Port Infrastructure Market |
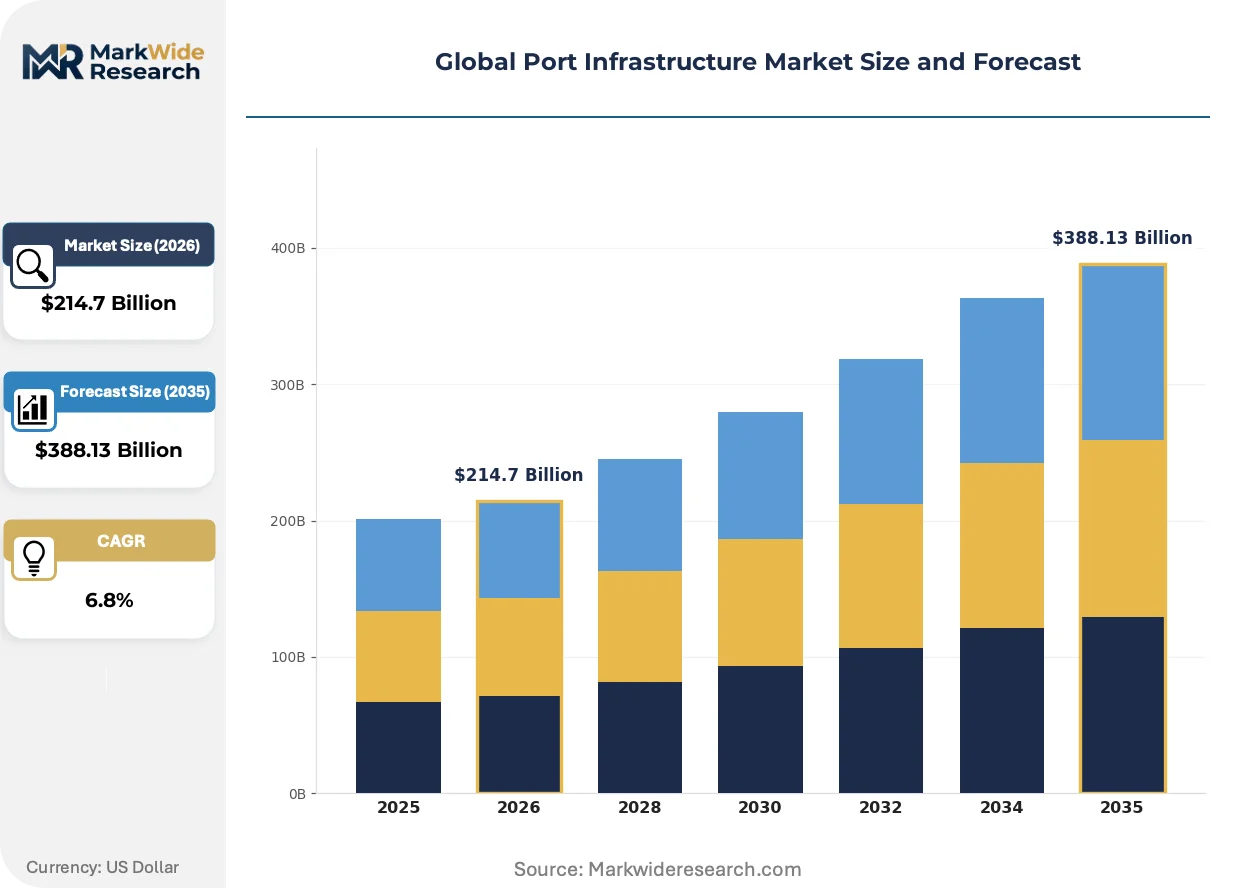
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $388.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Port Type: Container Ports, Bulk Ports, General Cargo Ports, Passenger Terminals Operation Mode: Public Ports, Private Ports, Joint Venture Ports, Multi-User Ports Infrastructure Component: Docking Facilities, Cargo Handling Equipment, Storage Facilities, Access Roads Service Offerings: Loading Services, Unloading Services, Maintenance Services, Inspection Services |
| Companies Covered | DP World, APM Terminals, Hutchison Ports, PSA International, Adani Ports and SEZ, COSCO Shipping Ports, A.P. Moller-Maersk, Ports America, Shanghai International Port Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Port Infrastructure Market Strategic Shifts
Diesel-electric hybrid systems are losing ground to full battery-electric and grid-connected alternatives as regulatory pressure intensifies. Equipment manufacturers and terminal operators are recalibrating procurement specifications around lifecycle carbon intensity rather than fuel efficiency alone.
Battery-electric rubber-tired gantry cranes are migrating from pilot installations at European hub terminals to mainstream deployment across Asia-Pacific transshipment hubs. PSA Singapore and Qingdao Port Group are placing fleet-scale orders for 100% electric RTGs with fast-charging infrastructure, compressing the payback period assumptions that previously favored diesel-hybrid configurations. This technology migration is enabling terminal operators to eliminate onboard fuel storage and reduce insurance premiums tied to hazardous material handling.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigerated container plug-in systems, forcing reefer infrastructure investment toward ammonia and CO2-based cooling. Terminal operators in Antwerp and Barcelona are installing shore-based reefer racks with centralized refrigeration plants, displacing individual genset units per container. Cold chain segments serving pharmaceutical and high-value agricultural exports face the steepest compliance costs and are consolidating throughput at terminals with certified green reefer capacity.
Shipping lines are unbundling terminal handling charges from freight rates, creating direct procurement relationships between beneficial cargo owners and terminal operators. Large retail importers in Germany and the United States are negotiating volume commitments with specific terminals to secure berth priority during congestion, bypassing traditional carrier intermediation. This disintermediation is most visible in the trans-Pacific trade, where Walmart and Amazon are contracting directly with Los Angeles and Long Beach terminal operators for dedicated yard space and expedited gate processing.
Global Port Infrastructure Market Segmentation
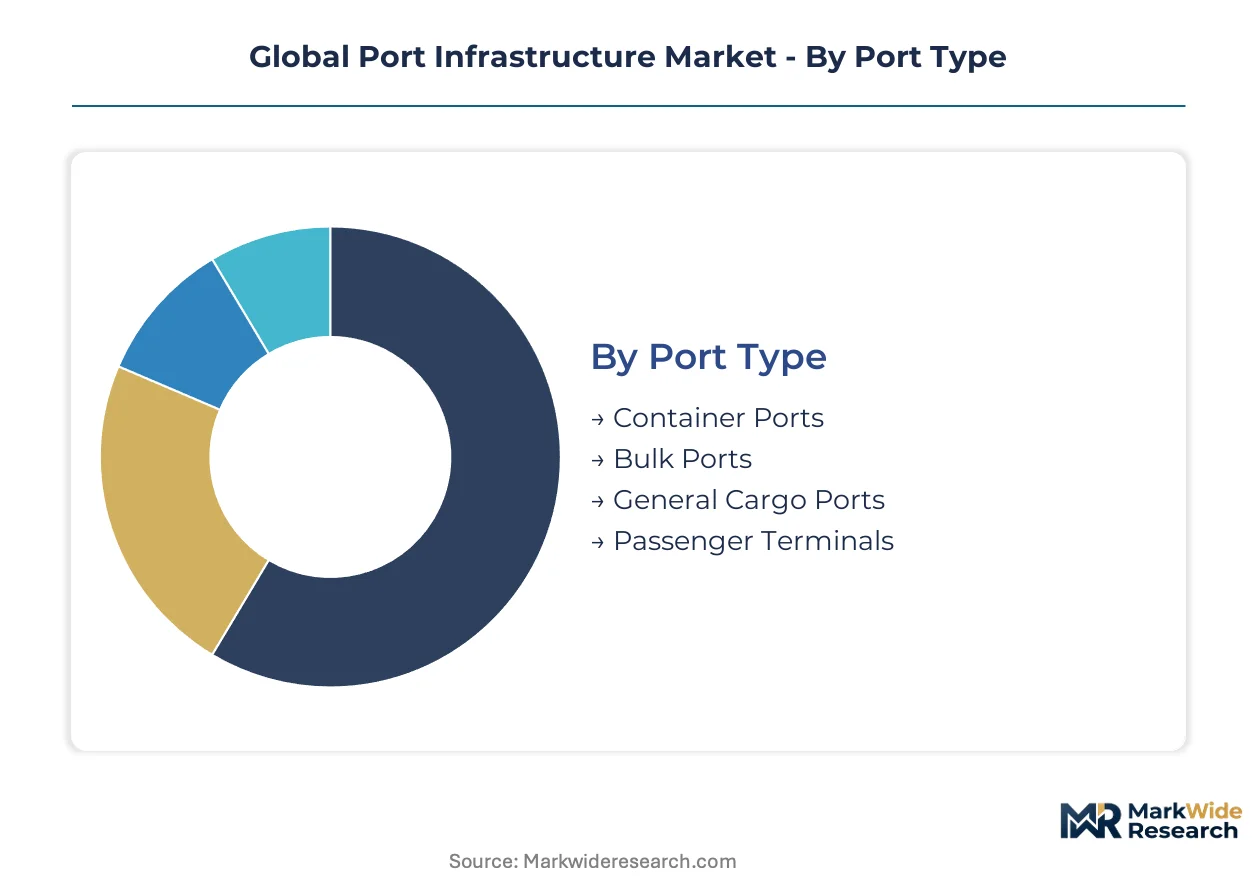
Port infrastructure segmentation reveals how capital deployment priorities diverge across cargo types, governance models, and operational layers. Terminal operators structure procurement and concession strategies around these divisions, while equipment suppliers calibrate product portfolios to match specific berth configurations and throughput intensities.
Port Type:
Mature container terminals anchor the largest capital pools, while emerging passenger infrastructure segments respond to cruise line network expansion and coastal tourism development.
- Container Ports:Deep-water quay walls accommodating 24,000 TEU vessels require 20-meter depth specifications and super-post-Panamax gantry cranes rated above 50 TEU hourly. Demand concentrates at Ningbo-Zhoushan and Singapore as shipping lines consolidate transshipment hubs along the Suez Canal route.
- Bulk Ports:Steadier throughput volumes tied to iron ore, coal, and grain contract structures sustain longer concession tenures with integrated mining and agricultural traders. Capex cycles align with commodity supercycle timing rather than vessel deployment waves.
- General Cargo Ports:Multi-purpose berths handling breakbulk, project cargo, and ro-ro vessels serve industrial hinterlands with diversified trade exposure.
- Passenger Terminals:Specialized security and customs infrastructure demands distinguish cruise and ferry operations from cargo-handling assets.
Container ports retain volume leadership; passenger terminals hold the steepest expansion curve.
Operation Mode:
Cost tier differentiation separates fully public operations from concession-based private models, with joint ventures occupying the middle ground where sovereign risk and commercial returns must balance.
- Public Ports:Municipal or national port authorities retain direct control over strategic trade gateways, prioritizing employment and regional development over yield maximization.
- Private Ports:Global terminal operators like DP World and PSA International leverage multi-decade concessions to amortize electrification capex and secure captive cargo flows.
- Joint Venture Ports:Blended public-private structures distribute construction risk while preserving government oversight of tariff regulation and land use planning.
- Multi-User Ports:Common-user facilities accommodate competing shipping lines through neutral terminal operating companies, preventing single-carrier dominance.
Private ports command the highest throughput per hectare; joint venture structures are gaining share fastest in emerging trade corridors.
Infrastructure Component:
Application specificity drives how quay wall engineering, equipment automation, and intermodal connectivity receive sequential investment priority during terminal expansion phases.
- Docking Facilities:Quay walls, fenders, and bollards form the fixed asset base with 50-year depreciation horizons and highest exposure to dredging cost volatility.
- Cargo Handling Equipment:Ship-to-shore cranes, rubber-tired gantries, and straddle carriers dominate opex profiles and face simultaneous EU Green Deal and China MEE electrification mandates.
- Storage Facilities:Container yards, bulk silos, and refrigerated warehouses balance stacking density against dwell time minimization.
- Access Roads:Rail spurs and truck gates constitute the critical hinterland interface where congestion external to the terminal gate constrains effective capacity.
Cargo handling equipment absorbs the steepest regulatory pressure; access roads represent the most frequent throughput bottleneck.
Service Offerings:
Customer type stratification separates commodity cargo owners seeking lowest unit costs from time-sensitive shippers purchasing priority berth access and expedited gate processing.
- Loading Services:Vessel stowage planning and lashing operations integrate with shipping line fleet deployment schedules to minimize port stay duration.
- Unloading Services:Discharge productivity metrics directly determine demurrage exposure and supply chain inventory positioning for beneficial cargo owners.
- Maintenance Services:Predictive crane servicing and pavement rehabilitation preserve asset availability ratios under continuous operational stress.
- Inspection Services:Customs scanning, phytosanitary checks, and dangerous goods certification add dwell time but reduce downstream supply chain disruption.
Unloading services retain volume leadership; inspection services are climbing the fastest as security and biosecurity protocols tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal shore power mandates and China's MEE emissions standards are redirecting capital toward electrified cargo handling equipment across major maritime gateways. Terminal operators in Rotterdam, Hamburg, and Singapore are retrofitting onshore power supply systems ahead of regulatory deadlines. This policy-driven investment wave is compressing concession timelines and reshaping greenfield development finance.
China
Ningbo-Zhoushan and Shanghai anchor the world's largest container throughput volumes as 24,000 TEU vessels consolidate along the Suez Canal route. China's Ministry of Ecology and Environment standards are forcing simultaneous retrofit of diesel gantry cranes and harbor craft at Qingdao and Tianjin. The Yangtze River Delta mega-port cluster is absorbing the steepest electrification capex as operators balance MEE compliance against concession amortization schedules.
United States
The Ports of Los Angeles and Long Beach are expanding automated guided vehicle systems to compress vessel turnaround times amid trans-Pacific cargo surges. EPA emissions standards for harbor craft and cargo handling equipment are accelerating battery-electric RTG procurement at Oakland and Seattle-Tacoma. The Southeast Atlantic gateway of Savannah is dredging to 47 feet to accommodate super-post-Panamax vessels ahead of Charleston and Norfolk capacity additions.
India
Adani Ports and SEZ is expanding Mundra and Hazira capacity with captive hinterland rail linkages under the Sagarmala Program. The Dedicated Freight Corridor Corporation is synchronizing last-mile rail investments with Jawaharlal Nehru Port Trust automation upgrades. Gujarat's Gulf of Kutch terminals are capturing transshipment cargo from Bangladesh and Sri Lanka through reduced dwell times and direct rail connectivity to Delhi-NCR inland container depots.
Singapore
PSA International is deploying fleet-scale orders for 100% electric rubber-tired gantry cranes with fast-charging infrastructure at Tuas Port. The Maritime and Port Authority's green port program is mandating shore power readiness for all new berth construction. The Tuas mega-terminal consolidation is eliminating fragmented Tanjong Pagar and Keppel operations while setting 65 million TEU annual capacity targets by the mid-2030s.
Netherlands
Rotterdam is piloting green hydrogen bunkering infrastructure through electrolyzer-ammonia cracking convergence ahead of IMO 2050 targets. The EU F-Gas Regulation is phasing down hydrofluorocarbon use in Maasvlakte refrigerated container plug-in systems. The port authority is coordinating with German hinterland operators to synchronize shore power standards across the Rotterdam-Duisburg corridor.
Global Port Infrastructure Market Competitive Environment
On the supply side, the industry is consolidating around multi-decade concession agreements that compress bidding competition and front-load electrification investments. Global terminal operators leverage integrated shipping-logistics control to secure captive cargo flows along emerging trade corridors. Three archetypes dominate: shipping-line-affiliated terminals, independent port developers with sovereign wealth backing, and national champions with captive hinterland rail assets. Competitive positioning hinges on concession tenure length against decarbonization capital cycles, plus vertical integration into intermodal connectivity.
Within the shipping-line-affiliated tier, A.P. Moller-Maersk and COSCO Shipping Ports exemplify integrated control strategies that synchronize vessel deployment with terminal productivity metrics. Among independent developers, DP World and PSA International occupy positions defined by multi-decade lease portfolios across transshipment hubs. Adani Ports and SEZ anchors the national champion archetype through captive rail linkages and subcontinent scale concentration.
| Leading Market Players |
|---|
| DP World |
| APM Terminals |
| Hutchison Ports |
| PSA International |
| Adani Ports and SEZ |
| COSCO Shipping Ports |
| A.P. Moller-Maersk |
| Ports America |
| Shanghai International Port Group |
| Others |
Value Chain & Pricing Dynamics
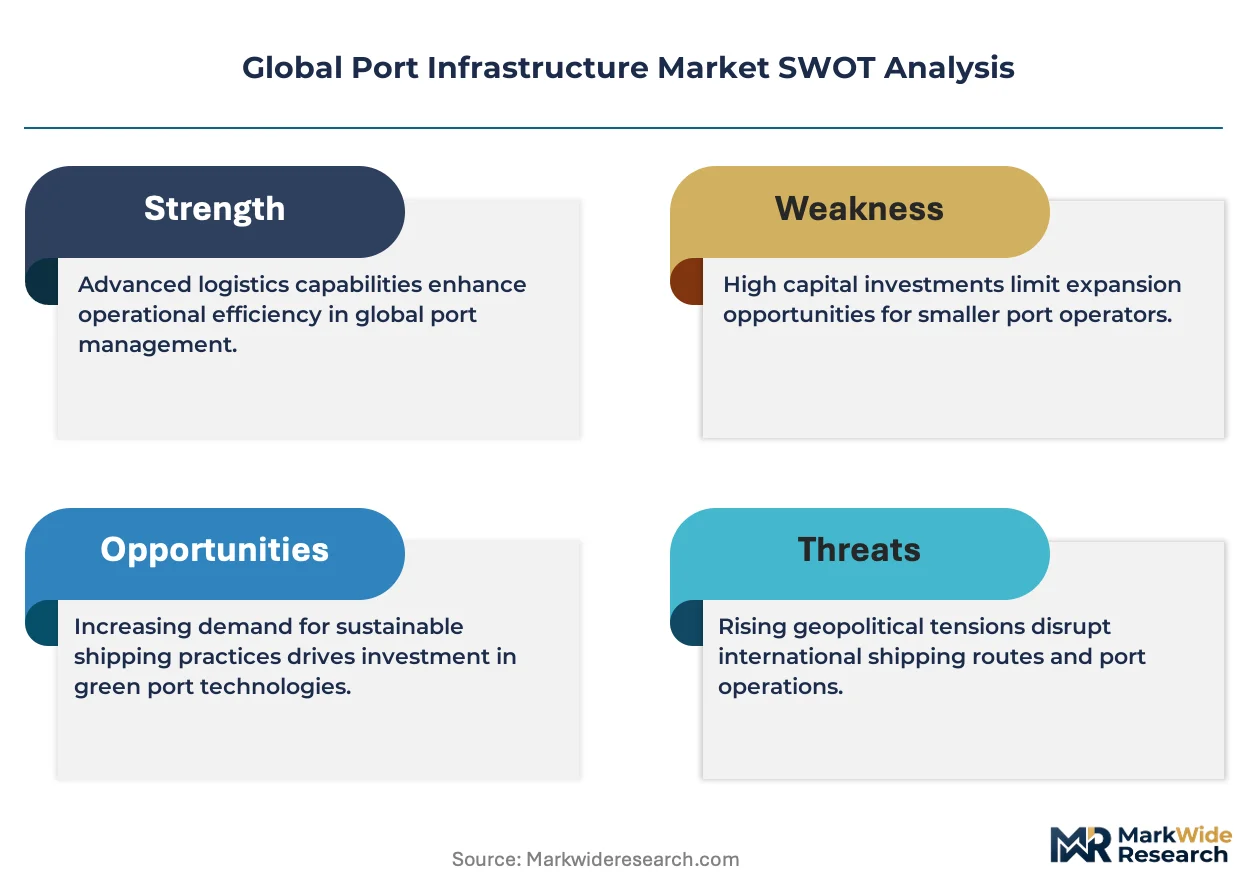
Overcapacity at Ningbo-Zhoushan and Shanghai is compressing terminal handling charges while simultaneously elevating electrification equipment premiums as operators front-load MEE compliance costs against concession amortization schedules.
Pricing Analysis
Certification level under EU Green Deal and MEE emissions standards creates the primary spread between premium electrified terminals and legacy diesel configurations. Contract-based long-term concession agreements dominate, with berth priority fees and expedited gate processing commanding material premiums. Price differentiation hinges on shore power readiness and automated cargo handling certification, with carbon intensity scores displacing fuel efficiency as the core metric. Cost compression in standard-tier terminals is intensifying because steel and concrete input volatility strains quay wall construction budgets. Commodity bulk cargo owners exhibit the highest price sensitivity, while time-sensitive retail importers purchasing direct terminal access show the least.
Supply Chain Analysis
Export controls on crane automation systems and vessel traffic management software are fragmenting equipment procurement channels for non-aligned operators. Manufacturing concentrates in China, Germany, and South Korea for gantry cranes and automated guided vehicle systems. The supply chain draws from specialized marine-grade concrete, high-tensile reinforcing steel, and frequency converter electronics. Single-source vulnerability in Chinese steel supply creates exposure to input cost spikes. Distribution runs through EPC contractors with sovereign wealth backing who bundle civil works, equipment procurement, and long-term maintenance under concession wraps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminal automation and shore power integration represent the fastest-expanding recurring-revenue layer, outpacing berth construction hardware as concession operators monetize equipment-as-a-service contracts and carbon compliance consulting.
For Market Incumbents: Harden concession tenure positions by securing multi-decade lease extensions ahead of EU Green Deal enforcement deadlines, while simultaneously building captive rail linkages to lock in hinterland access. Electrification capex front-loading threatens balance sheet flexibility for operators without sovereign wealth backing. Backward integration into crane maintenance and predictive servicing preserves margin capture against independent equipment vendors. For New Entrants and Emerging Players: Vietnam's Lach Huyen deep-water development and secondary Indian ports under Sagarmala represent the most penetrable entry points before saturation at Cai Mep-Thi Vai and Mundra. Green hydrogen bunkering infrastructure pilot programs at Rotterdam and Singapore offer technology partnership angles with established operators seeking IMO 2050 positioning. A go-to-market strategy anchored in electrolyzer-ammonia cracking system integration bypasses direct concession competition. For Investors and Strategic Acquirers: Capital is best deployed toward national champion archetypes with captive hinterland rail assets and multi-user port structures in emerging trade corridors. Long-term viability across the projection horizon rests on concession tenure length exceeding decarbonization capital cycles. The signal to watch is shore power mandate acceleration at major transshipment hubs, which would force stranded asset risk onto non-compliant terminal portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Tenure Extension | DP World and PSA International secure 30-50 year leases to amortize electrification capex across Rotterdam and Singapore terminals. |
| Captive Hinterland Rail Integration | Adani Ports and SEZ reduces dwell times through Dedicated Freight Corridor synchronization at Mundra and Hazira. |
| Shore Power Infrastructure Deployment | EU Green Deal mandates trigger synchronized cargo handling equipment upgrades at Hamburg and Antwerp. |
| Green Hydrogen Bunkering Pilot | Rotterdam and Singapore test electrolyzer-ammonia cracking convergence ahead of IMO marine fuel standards. |
| Automated Guided Vehicle Fleet Scale-Up | PSA Singapore compresses vessel turnaround times through 100% electric RTG deployment with fast-charging infrastructure. |
Study Parameters
The analysis maps container terminals, bulk ports, passenger terminals, and intermodal connectivity nodes, each validated through terminal operations directors, port authority planning officers, EPC contractor project leads, and shipping line fleet deployment managers. Primary fieldwork combined structured interviews with secondary validation against IMO regulatory filings, EU Green Deal implementation schedules, China MEE emissions standards, and concession agreement databases. Customs throughput data, dredging cost indices, and equipment procurement records provided volume anchors. Bottom-up terminal capacity builds and top-down trade flow models were triangulated against each other.
Assumptions around regulatory enforcement timelines, steel price volatility bands, and vessel deployment schedules were held fixed while concession tenure lengths and electrification capex curves were varied across sensitivity scenarios. The analytical framework spans port type, operation mode, infrastructure component, and service offering dimensions. CAGRs were derived from capacity utilization trajectories and throughput intensity projections. Forecast inputs incorporated super-post-Panamax vessel proliferation rates and shore power mandate adoption curves.
Practitioners should monitor EU F-Gas Regulation phase-down schedules and China MEE enforcement intensity for early signals of equipment retrofit acceleration. Forecasts reflect documented assumptions around commodity trade volumes and carbon accounting framework stability. Material shifts in IMO marine fuel standards or transshipment hub consolidation patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Gas Pipeline Infrastructure Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Concrete Canvas Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
France Transportation Infrastructure Construction Market
Infrastructure Construction
Belgium Data Center Construction Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market