
 Brazil Infrastructure Sector Market | 2026-2036
Brazil Infrastructure Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Infrastructure Sector Market Insights
A chronic shortage of licensed civil engineers is unwinding project timelines across Brazil's southeast corridor. CCR S.A. leverages its dominance in toll-road concessions to sustain long-term revenue visibility. Ecorodovias Infraestrutura e Logística anchors its portfolio in strategic highway corridors connecting Atlantic ports to interior agricultural zones. Odebrecht Engenharia & Construção navigates reputational headwinds while competing for federal infrastructure tenders.
The Brazil Infrastructure Sector encompasses physical systems engineered for mass service delivery, including reinforced concrete superstructures, asphalt polymer blends, and steel-reinforced transmission towers designed for tropical load conditions. Transportation infrastructure leads capital allocation due to Brazil's continental geography and export-dependent commodity flows, while energy infrastructure represents the fastest-growing segment as grid interconnection expands hydroelectric and wind assets. Water supply networks remain structurally mature with concentrated margin pools in leakage-reduction technologies and smart metering retrofits.
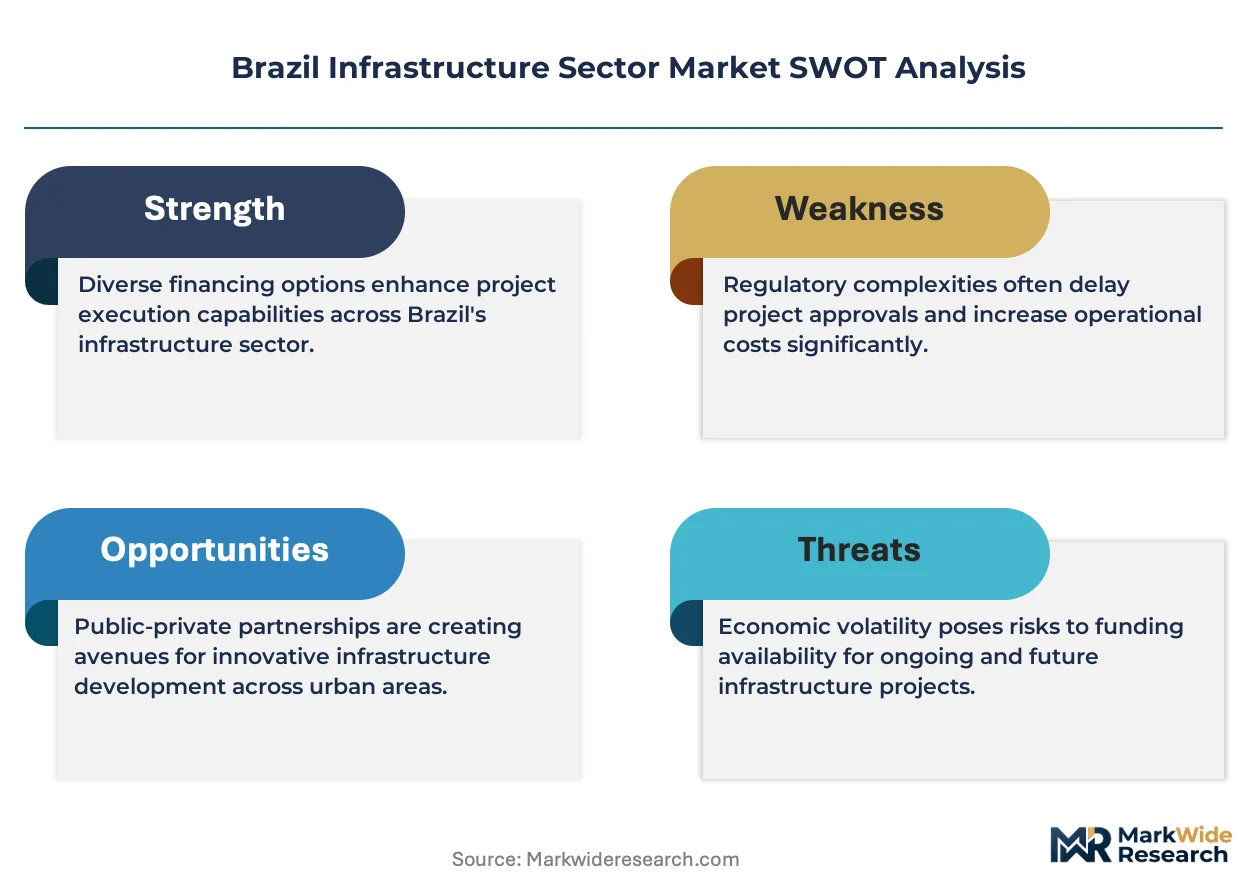
ANVISA regulates materials safety in water supply infrastructure, while the national infrastructure ministry oversees concession bidding frameworks that shape private sector market access. BIS-aligned technical standards govern steel and cement specifications for federally funded projects, creating compliance barriers for imported construction inputs. Stakeholders must monitor how Brazil's fiscal rules and environmental licensing delays reshape project bankability before committing capital to multi-decade concession structures.
Market Dynamics
Federal concession frameworks are redirecting capital toward private toll-road operators while environmental licensing bottlenecks stall hydroelectric transmission corridors. The tension between accelerated procurement timelines and regulatory compliance is compressing project bankability windows.
Growth Catalysts
- New Growth Acceleration Program (PAC):Federal directives channel public investment into energy transmission corridors linking isolated hydroelectric assets to southeastern demand centers.
- Toll-road concession frameworks:Highway privatization protocols enable long-term revenue visibility for operators managing Atlantic-to-interior agricultural logistics corridors.
- São Paulo urban transit modernization:Metropolitan rail and bus rapid transit upgrades concentrate equipment procurement in Brazil's densest economic corridor.
Market Restraints
- Cement input cost volatility:Domestic clinker production shortfalls expose contractors to import price swings from regional suppliers.
- Licensed civil engineer scarcity:Professional credential bottlenecks in Brazil's southeast corridor unwind project timelines and inflate labor premiums.
- Environmental licensing friction:IBAMA approval delays for Amazon basin transmission lines extend development cycles beyond concession financing horizons.
Strategic Opportunities
- Northeast wind corridor grid integration:Ceará and Rio Grande do Norte offshore wind zones lack adequate transmission infrastructure, creating first-mover positioning for transmission tower fabricators.
- Smart metering retrofits:ANA water efficiency mandates drive demand for leakage-detection sensors and automated billing systems in São Paulo and Minas Gerais distribution networks.
- Polymer-modified asphalt adoption:Federal durability standards for tropical load conditions accelerate substitution of conventional binders in federal highway resurfacing contracts.
Industry Challenges
- Geotechnical survey capacity constraints:Specialized foundation engineering for Amazon basin transmission towers exceeds available domestic contractor bandwidth.
- BIS-aligned steel certification timelines:Imported structural steel verification for federally funded projects extends material procurement lead times by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Infrastructure Sector Market |
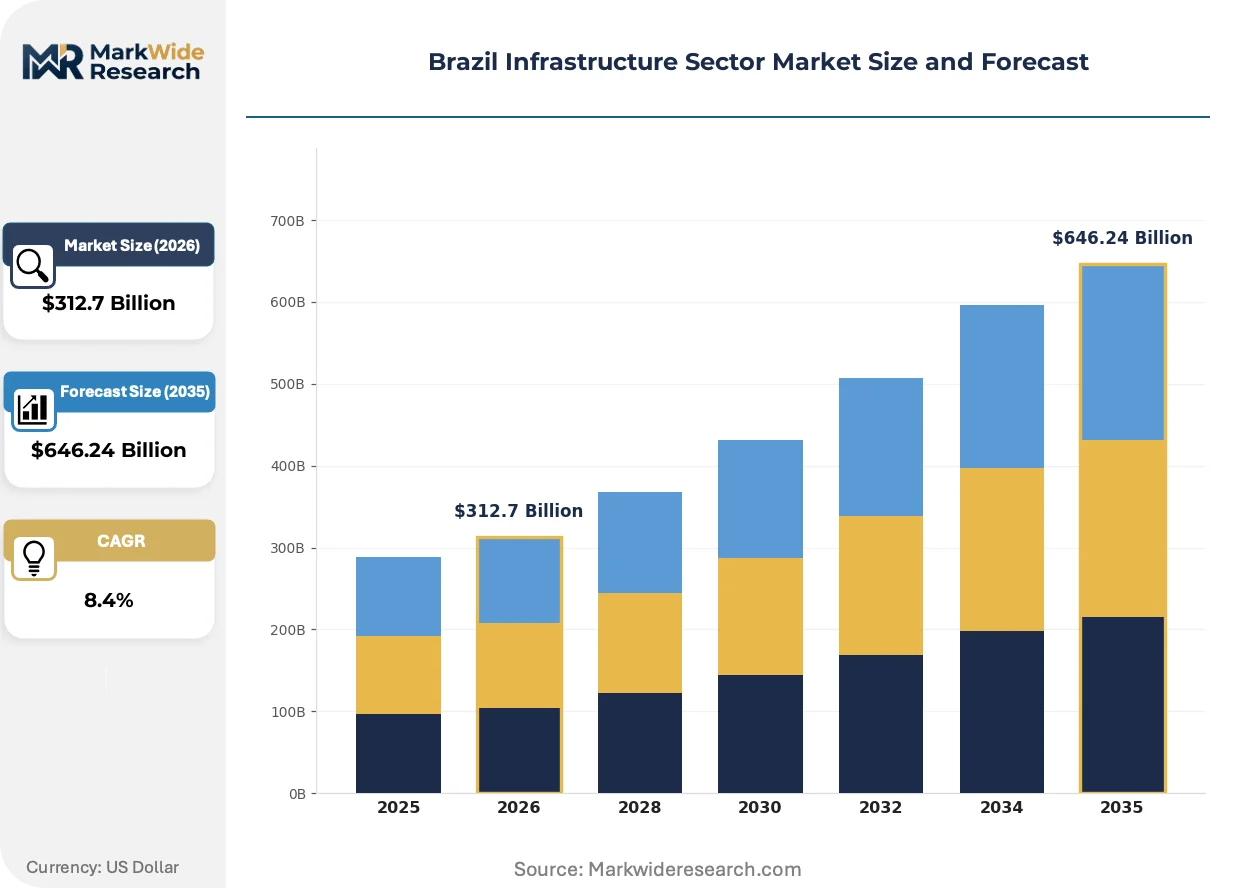
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $646.24 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Type: Public-Private Partnership, Direct Investment, Government Grants, Foreign Investment Infrastructure Category: Transportation, Energy, Water Supply, Telecommunications Development Stage: Planning, Construction, Operation, Maintenance Funding Source: Domestic Banks, International Organizations, Equity Investors, Bonds |
| Companies Covered | CCR S.A., Ecorodovias Infraestrutura e Logística, Odebrecht Engenharia & Construção, Andrade Gutierrez, Construtora Queiroz Galvão, COBRA Group, Camargo Correa Infra Construções, Construcap, Tabocas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Infrastructure Sector Market Trends and Innovations
Digital twin platforms are rewiring how concession operators monitor asset degradation across dispersed highway and energy networks. Three material and process shifts are altering competitive positioning.
Building information modeling (BIM) platforms now integrate real-time sensor feeds from toll-road pavement and transmission tower structural health monitors. State-level concession operators in São Paulo and Paraná deploy these systems to optimize maintenance scheduling. The technology is fragmenting traditional engineering-consulting relationships by enabling direct operator control over predictive analytics.
ANVISA material safety protocols for potable water infrastructure now mandate traceability documentation for polymer additives in pipe manufacturing. Domestic extrusion plants must retrofit quality systems to capture batch-level chemical composition data. Water supply contractors in Minas Gerais and Rio de Janeiro face compliance cost pressures that favor vertically integrated pipe producers with captive laboratory capacity.
Buyers of heavy civil construction services now unbundle long-term maintenance obligations from initial engineering-procurement-construction contracts. State transportation departments in Brazil's southeast issue separate ten-to-fifteen-year pavement performance agreements distinct from construction awards. This restructuring concentrates vendor selection criteria on operational track records rather than lowest-bid construction pricing.
Brazil Infrastructure Sector Market Segmentation
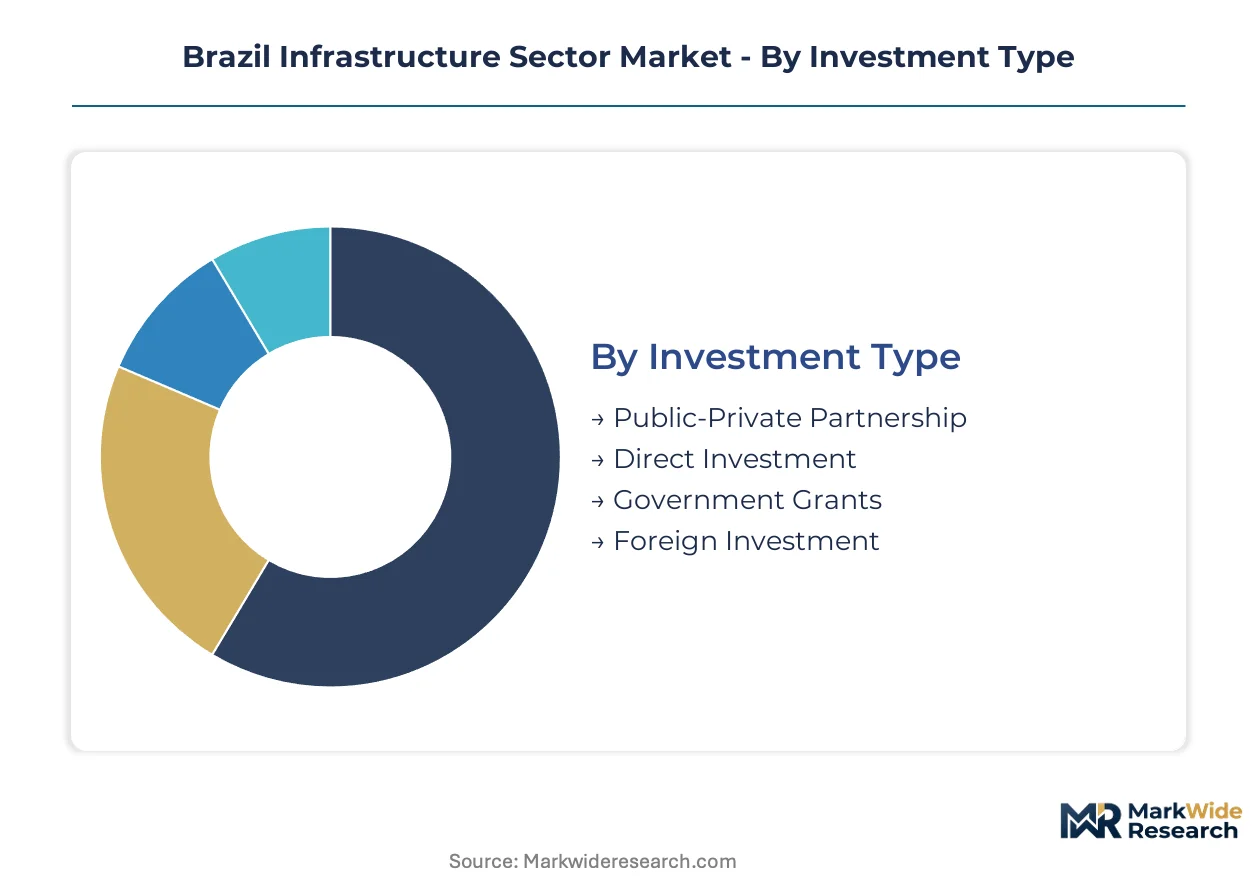
Segmentation reveals how capital flows differentially across Brazil's infrastructure landscape. Investment type determines risk allocation between federal guarantees and private returns. Infrastructure category shapes regulatory exposure and concession duration. Development stage and funding source together dictate project bankability timelines.
Investment Type:
Substitute financing mechanisms exert uneven pressure across investment structures, with government grants facing displacement from blended finance instruments.
- Public-Private Partnership:Risk-sharing frameworks allocate construction liability to private concessionaires while federal entities underwrite revenue guarantees through minimum traffic or demand clauses. São Paulo state highway concessions concentrate procurement volume here, driven by federal toll-road privatization protocols.
- Direct Investment:Balance-sheet deployment by institutional investors seeking unencumbered asset ownership with full operational control. Energy transmission corridors in Minas Gerais attract this structure where long-term offtake contracts provide revenue visibility without concession complexity.
- Government Grants:Non-repayable federal allocations for strategic corridors where private returns fall below hurdle rates. Amazon basin road paving projects rely on this mechanism.
- Foreign Investment:Cross-border capital from development banks and sovereign wealth funds targeting hard-currency revenue streams. Northeast wind transmission projects draw this source.
Public-Private Partnership retains volume leadership; Foreign Investment holds the steepest expansion curve.
Infrastructure Category:
Cost tier differentiation separates high-capex energy and transportation assets from lower-threshold water and telecommunications deployment.
- Transportation:Reinforced concrete superstructures and asphalt polymer blends engineered for tropical load conditions across federal highway networks. São Paulo's urban transit modernization concentrates equipment procurement in bus rapid transit and metropolitan rail corridors.
- Energy:Steel-reinforced transmission towers and grid interconnection assets expanding hydroelectric and wind capacity. This category climbs the fastest as isolated generation assets in the North and Northeast require corridor investment to reach southeastern demand centers.
- Water Supply:Leakage-reduction technologies and smart metering retrofits in structurally mature distribution networks. ANA efficiency mandates in São Paulo and Minas Gerais drive sensor deployment.
- Telecommunications:Fiber backbone and 5G infrastructure deployment lagging other categories due to regulatory spectrum allocation delays.
Transportation dominates capital allocation; Energy gains share fastest on grid expansion imperatives.
Development Stage:
Application maturity varies sharply, with planning-stage projects accumulating regulatory risk and operation-stage assets commanding premium valuations.
- Planning:Feasibility studies, environmental licensing, and geotechnical surveys preceding construction commitment. IBAMA approval bottlenecks for Amazon basin transmission lines extend this phase beyond financing horizons.
- Construction:Physical execution of civil works where licensed engineer scarcity in Brazil's southeast corridor inflates labor premiums and unwinds timelines.
- Operation:Revenue-generating asset management with long-term concession cash flows. Toll-road operators in Paraná deploy digital twin platforms to optimize maintenance scheduling.
- Maintenance:Performance-based pavement and structural integrity contracts unbundled from initial construction awards. State transportation departments now issue separate ten-to-fifteen-year agreements.
Construction absorbs the largest workforce; Operation commands the highest margin premiums.
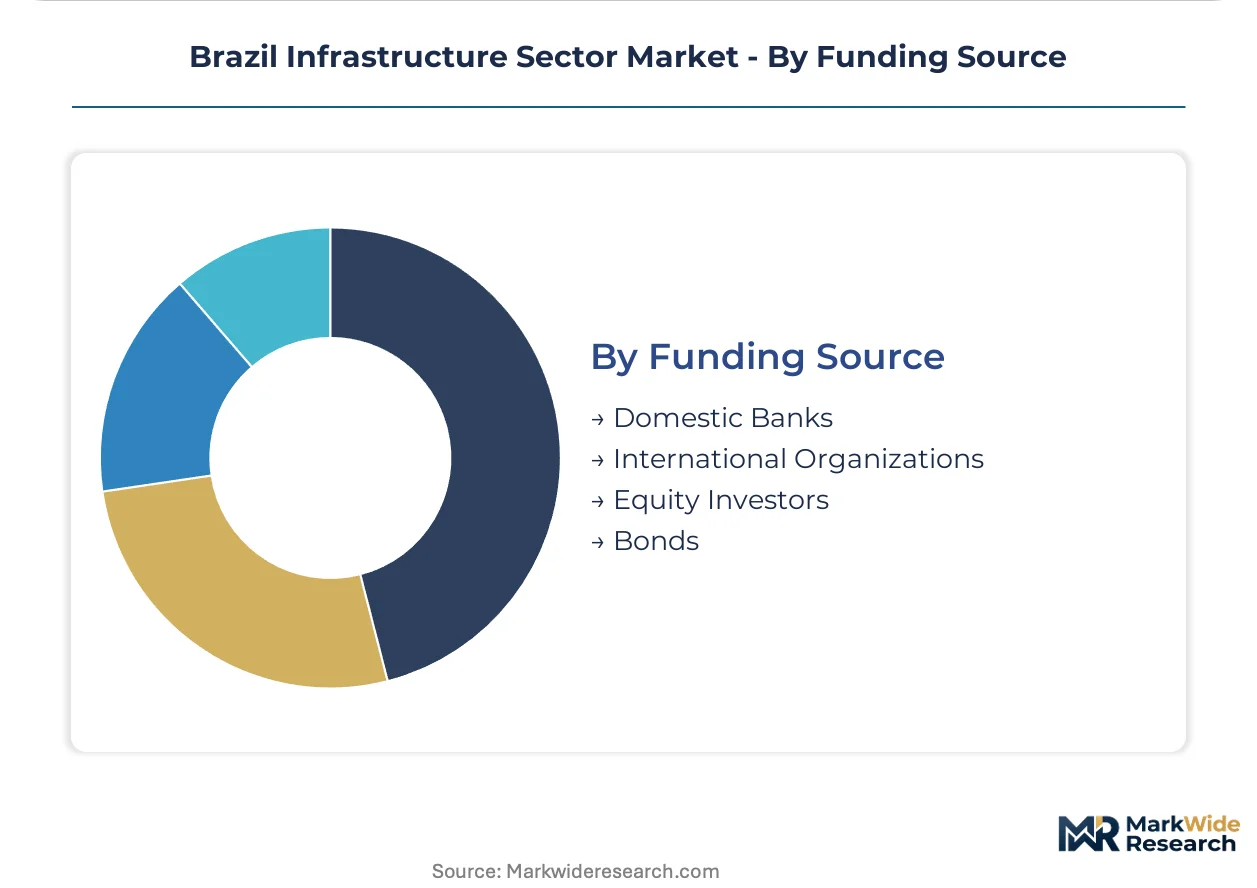
Funding Source:
Customer type fragmentation separates institutional lenders from capital market instruments, each carrying distinct covenant and tenor characteristics.
- Domestic Banks:BNDES and private sector lenders providing long-term real-denominated credit for federally backed concessions. PAC-directed energy transmission corridors flow through this channel.
- International Organizations:Multilateral development banks offering concessional terms for climate-aligned infrastructure. Northeast wind grid integration attracts this source.
- Equity Investors:Infrastructure funds and pension managers seeking inflation-linked returns through concession participation. Highway operators in agricultural logistics corridors target this base.
- Bonds:Project finance issuance in international markets for large-scale transportation and energy assets with investment-grade risk profiles.
Domestic Banks provide the deepest liquidity pool; Bonds expand most quickly as international investor appetite for Brazilian infrastructure hardens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's infrastructure deployment varies sharply across its five macro-regions. The Southeast prioritizes urban transit densification and energy grid reinforcement. The Northeast concentrates wind corridor integration. The North faces Amazon basin environmental licensing friction. The Central-West anchors agricultural logistics corridors. The South maintains mature highway networks requiring performance-based maintenance contracts.
São Paulo
São Paulo state's metropolitan rail and bus rapid transit upgrades concentrate equipment procurement in Brazil's densest economic corridor. The state's concession frameworks for urban transit modernization channel federal PAC resources into integrated mobility networks. São Paulo city anchors demand for smart signaling systems and station modernization across its expanded metro lines.
Minas Gerais
Minas Gerais hosts energy transmission corridors linking isolated hydroelectric assets to southeastern demand centers under federal PAC directives. ANA water efficiency mandates drive leakage-detection sensor deployment across Belo Horizonte's distribution networks. The state's steel-reinforced transmission tower fabricators face BIS-aligned certification timelines that extend material procurement cycles.
Rio de Janeiro
Rio de Janeiro's port modernization and coastal highway resilience projects absorb polymer-modified asphalt for tropical load conditions. ANVISA material safety protocols mandate traceability documentation for potable water infrastructure retrofits across the metropolitan region. The state's civil engineering labor pool faces scarcity pressures that inflate project premiums.
Ceará
Ceará's offshore wind zones lack adequate transmission infrastructure, creating first-mover positioning for transmission tower fabricators. International Organization financing flows toward climate-aligned grid integration projects in this corridor. Fortaleza anchors procurement for subsea cable landing stations and coastal substation equipment.
Paraná
Paraná's toll-road operators deploy digital twin platforms to optimize maintenance scheduling across Atlantic-to-interior agricultural logistics corridors. State transportation departments issue separate ten-to-fifteen-year pavement performance agreements unbundled from construction awards. Curitiba concentrates demand for intelligent transportation systems and weigh-in-motion enforcement infrastructure.
Brazil Infrastructure Sector Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Brazil's infrastructure sector. The upper tier commands concession portfolios with multi-decade revenue visibility through federal highway and energy transmission frameworks. Specialist contractors compete on geotechnical survey capacity and BIS-aligned material certification speed. Dominant competitive moves include portfolio diversification across transportation and energy verticals, and strategic partnerships with international development banks for foreign-currency project finance.
Among toll-road concessionaires, CCR S.A. and Ecorodovias Infraestrutura e Logística occupy positions exemplifying the integrated leader archetype with corridor dominance spanning Atlantic ports to interior agricultural zones. Odebrecht Engenharia & Construção represents the engineering-procurement-construction tier navigating federal tender processes while managing reputational positioning. These three entities anchor competitive dynamics across Brazil's concession-driven infrastructure deployment.
| Leading Market Players |
|---|
| CCR S.A. |
| Ecorodovias Infraestrutura e Logística |
| Odebrecht Engenharia & Construção |
| Andrade Gutierrez |
| Construtora Queiroz Galvão |
| COBRA Group |
| Camargo Correa Infra Construções |
| Construcap |
| Tabocas |
| Others |
Pricing and Supply Chain Analysis
Polymer-modified asphalt substitution for conventional binders in federal highway resurfacing contracts simultaneously shifts procurement geography toward domestic petrochemical clusters and compresses unit economics through volume-scale standardization. This input transition concentrates pricing power among vertically integrated producers with captive laboratory capacity while exposing contractors to regional clinker import volatility.
Pricing Analysis
Long-term offtake agreements dominate energy transmission corridors where BNDES-backed concessions provide revenue visibility, while spot procurement persists for cement and steel in fragmented construction tiers. Price differentiation rests on BIS-aligned certification tiers and tropical durability performance standards. Cost compression in standard-grade construction inputs intensifies as domestic clinker shortfalls force reliance on regional import swings. State transportation departments exhibit highest price sensitivity in maintenance contract bidding, whereas energy concessionaires prioritize performance guarantees over unit cost.
Supply Chain Analysis
China and India anchor structural steel fabrication for transmission tower components, while domestic petrochemical clusters in São Paulo and Rio de Janeiro supply polymer-modified asphalt binders. The supply chain draws from imported clinker, specialized geotechnical survey capacity, and ANVISA-traceable polymer additives. Single-source vulnerability concentrates in BIS-aligned steel certification timelines that extend material procurement cycles. Distribution runs through BNDES-mediated concession frameworks and state-level transportation department procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's infrastructure sector is approaching a platform-economics inflection as digital twin systems and BIM platforms rewire asset management interoperability across concession networks.
For Market Incumbents: Fortify concession portfolio durability by deepening operational control through predictive maintenance platforms that fragment traditional engineering-consulting relationships. Anchor backward integration into polymer-modified asphalt production to capture margin pools from federal durability standards. CCR S.A. and Ecorodovias demonstrate how corridor dominance sustains pricing power against emerging digital-native operators.
For New Entrants and Emerging Players: Lead with geotechnical survey specialization targeting Amazon basin transmission tower foundations where domestic contractor bandwidth falls short. The Northeast wind corridor grid integration presents the most penetrable white space, with Ceará and Rio Grande do Norte lacking adequate transmission infrastructure. Position through strategic partnerships with International Organization financing for climate-aligned project development.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed toll-road operators holding mature concession portfolios in Paraná and São Paulo agricultural logistics corridors. Long-term viability hinges on operational track records in performance-based maintenance contracts rather than construction pricing competitiveness. Monitor IBAMA licensing velocity for Amazon basin transmission lines as the critical inflection signal for energy infrastructure bankability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer-Modified Asphalt | Captures margin pools from ANTT federal durability standards mandating tropical load condition binders. |
| Digital Twin Platform Deployment | Fragments traditional engineering-consulting relationships by enabling direct operator predictive control. |
| BIS-Aligned Steel Certification Investment | Compresses four-to-six month material procurement lead times for federally funded transmission projects. |
| Performance-Based Maintenance Contract Unbundling | Concentrates vendor selection on operational track records rather than lowest-bid construction pricing. |
| Northeast Wind Corridor Grid Integration Partnership | Positions first-mover advantage in Ceará and Rio Grande do Norte offshore transmission infrastructure. |
Research Methodology
A standing panel of concession operators, federal infrastructure ministry procurement officers, BNDES project finance leads, and ANVISA compliance specialists provided ongoing calibration throughout the analysis window. Primary interviews with toll-road operators in São Paulo and Paraná, transmission tower fabricators in Minas Gerais, and water supply contractors across Rio de Janeiro and Belo Horizonte were triangulated against secondary sources including PAC program directives, IBAMA environmental licensing databases, ANA water efficiency mandates, and BIS technical standards documentation. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling were reconciled to ensure consistency.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling incorporated investment type, infrastructure category, development stage, and funding source dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from project-level cash flow analysis and concession revenue visibility assessments. Key forecast inputs included federal highway concession award timelines, energy transmission corridor PAC allocation trajectories, and environmental licensing velocity assumptions.
Forecasts assume regulatory continuity in ANVISA material safety protocols, ANA water efficiency mandates, and IBAMA environmental licensing frameworks; material policy shifts would require re-modeling. Specific risks include fiscal rule modifications affecting concession bankability, cement import price volatility from regional suppliers, and licensed civil engineer scarcity extending construction timelines. Recalibration cycles align with material shifts in federal concession award velocity and environmental licensing throughput.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
France Transportation Infrastructure Construction Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
Global Rail Infrastructure Market