
 Gas Pipeline Infrastructure Market | 2026-2036
Gas Pipeline Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Pipeline Infrastructure Market Analysis
North American midstream operators is pivoting toward large-diameter transmission projects to bridge supply basins with coastal export terminals. Bechtel leverages its lump-sum EPC track record on cross-border pipelines to sustain competitive positioning in megaproject bidding. Energy Transfer anchors its growth through backward integration into pipeline construction and long-term shipper contracts. Samsung Engineering competes on cost-engineered execution for Middle Eastern sour-gas trunklines.
Gas pipeline infrastructure comprises buried or aboveground conduit systems, typically constructed from API 5L-grade steel with diameters ranging from 4 to 48 inches, designed to transport natural gas under pressures up to 1,440 psi from production fields to processing facilities, industrial consumers, and urban distribution networks. Transmission pipelines command the largest capital allocation due to their scale and compressor station requirements, while gathering lines represent the fastest-expanding segment as shale producers drill deeper into peripheral acreage. Steel dominates material selection for high-pressure trunklines, though polyethylene is displacing cast iron in urban distribution renewals where trenchless installation methods reduce surface disruption.
The US Department of Transportation's PHMSA enforces Class location requirements and hydrostatic testing standards that dictate wall thickness and weld inspection protocols, while the Federal Energy Regulatory Commission governs interstate route approvals and environmental compliance. In Europe, the EU Methane Regulation imposes leak detection and repair mandates that force operators to upgrade valve and compressor sealing technologies. Stakeholders must monitor how blending hydrogen into existing steel pipelines reshapes material compatibility standards and compressor station retrofit economics.
Market Dynamics
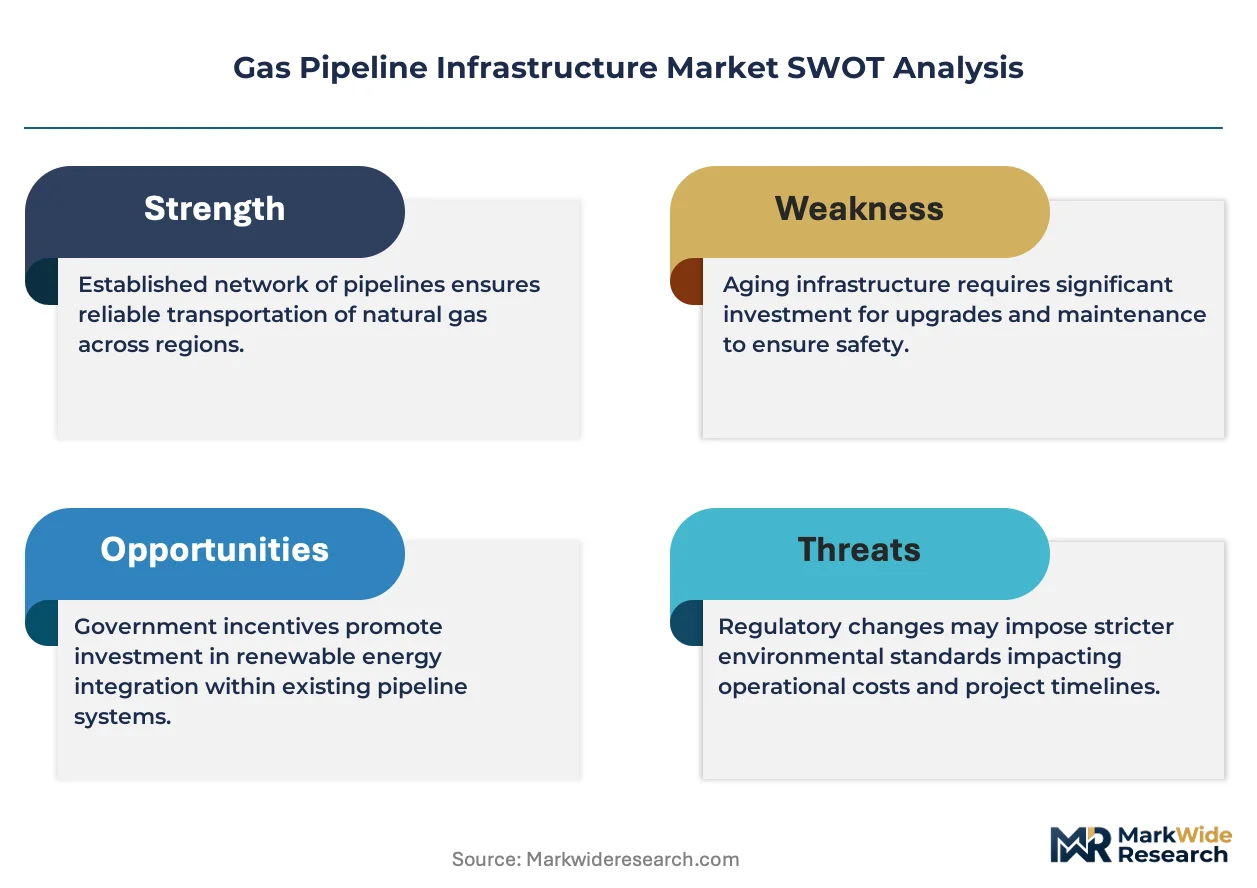
The US Pipeline and Hazardous Materials Safety Administration's integrity management protocols are forcing wholesale replacement of aging cast-iron distribution networks, while Permian Basin takeaway constraints simultaneously pull investment toward newbuild transmission capacity. This dual pressure—regulatory compliance on one flank and supply basin bottlenecks on the other—defines current capital allocation patterns across the sector.
Growth Catalysts
- Power generation utilities:Pipeline-linked gas-fired capacity expansion accelerates as grid operators deploy fast-ramp turbines to balance wind and solar intermittency. Baseload retirement creates permanent demand for flexible gas dispatch.
- FERC interstate route approvals:Streamlined environmental review timelines compress project development cycles for cross-border transmission corridors. Certificate holders secure long-term shipper commitments earlier in the development phase.
- API 5L-grade steel:Domestic mill capacity expansion reduces lead times for high-pressure trunkline materials. Standardized metallurgy lowers fabrication costs for 36-inch and 48-inch diameter projects.
Market Restraints
- Specialized welding labor:Certified pipeline welder shortages in the US Gulf Coast and Alberta extend construction timelines. Training pipeline capacity lags project award velocity by 18-24 months.
- Polyethylene displacement limits:Material temperature and pressure thresholds prevent substitution in high-pressure transmission applications. Steel retains monopoly on compressor station-linked trunklines.
- EU Methane Regulation compliance:Leak detection and repair mandates force valve and compressor sealing upgrades. Retrofit capital requirements compete with greenfield project returns.
Strategic Opportunities
- Hydrogen blending infrastructure:Steel pipeline compatibility testing opens retrofit markets for existing transmission corridors. Compressor station metallurgical assessments create new service revenue streams.
- Trenchless installation methods:Horizontal directional drilling reduces urban surface disruption for distribution renewals. Municipal permitting timelines compress versus open-cut alternatives.
- India's city gas distribution:Underpenetrated geographic coverage in Tier-2 and Tier-3 urban clusters drives polyethylene network deployment. PNGRB bidding rounds accelerate authorization velocity.
Industry Challenges
- Class location hydrostatic testing:Population density reclassification triggers unplanned pressure-test intervals. PHMSA enforcement variance across state jurisdictions complicates compliance scheduling.
- Compressor station integration:Legacy turbine-driven units require sequential retrofit coordination with pipeline outage windows. Hydrogen-ready turbine procurement extends equipment lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Pipeline Infrastructure Market |
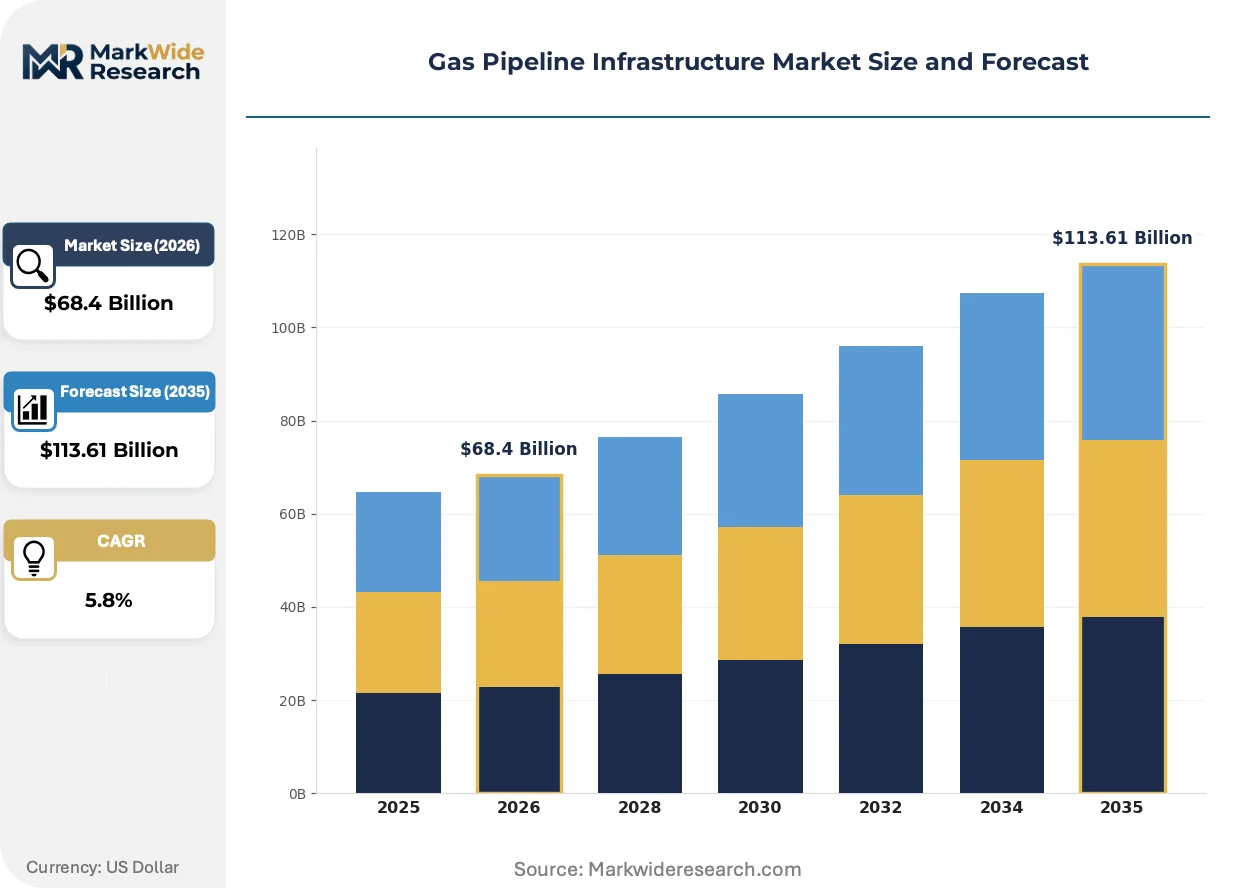
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pipeline Type: Gathering, Transmission, Distribution, Main Component: Pipes, Valves, Compressors, Fittings Material: Steel, Polyethylene, Cast Iron, Composite Installation Method: Trenching, Directional Drilling, HDD, Boring |
| Companies Covered | Michels Corporation, Samsung Engineering, Bechtel, QatarEnergy, Woodside Energy Group, Energy Transfer, Kiewit Corporation, Santos, Mastec, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Pipeline Infrastructure Market Emerging Trajectories
Digital monitoring systems are embedding fiber-optic sensing along pipeline rights-of-way, creating real-time integrity visibility that reshapes maintenance economics and risk transfer mechanisms. This instrumentation wave converges with evolving regulatory disclosure requirements.
Smart pigging technology is converging with machine-learning defect classification to automate anomaly prioritization. Midstream operators in the Permian-to-Gulf corridor deploy autonomous in-line inspection platforms that reduce manual data review cycles. The structural compression of assessment-to-repair timelines is converging with predictive maintenance contracts that shift cost risk to service providers.
The EU Methane Regulation imposes quantified emission reduction targets that force compressor station seal technology upgrades. European operators must deploy optical gas imaging at valve assemblies and above-ground facilities. The regulation's 2027 enforcement horizon is compressing procurement cycles for low-emission packing systems.
Shipper contracting behavior is shortening commitment tenors as renewable penetration obscures long-term gas demand trajectories. Merchant developers face difficulty securing 15-20 year take-or-pay structures that underwrite project finance. This duration compression is most visible in US Northeast expansion projects where state decarbonization mandates create demand uncertainty.
Gas Pipeline Infrastructure Market Segmentation
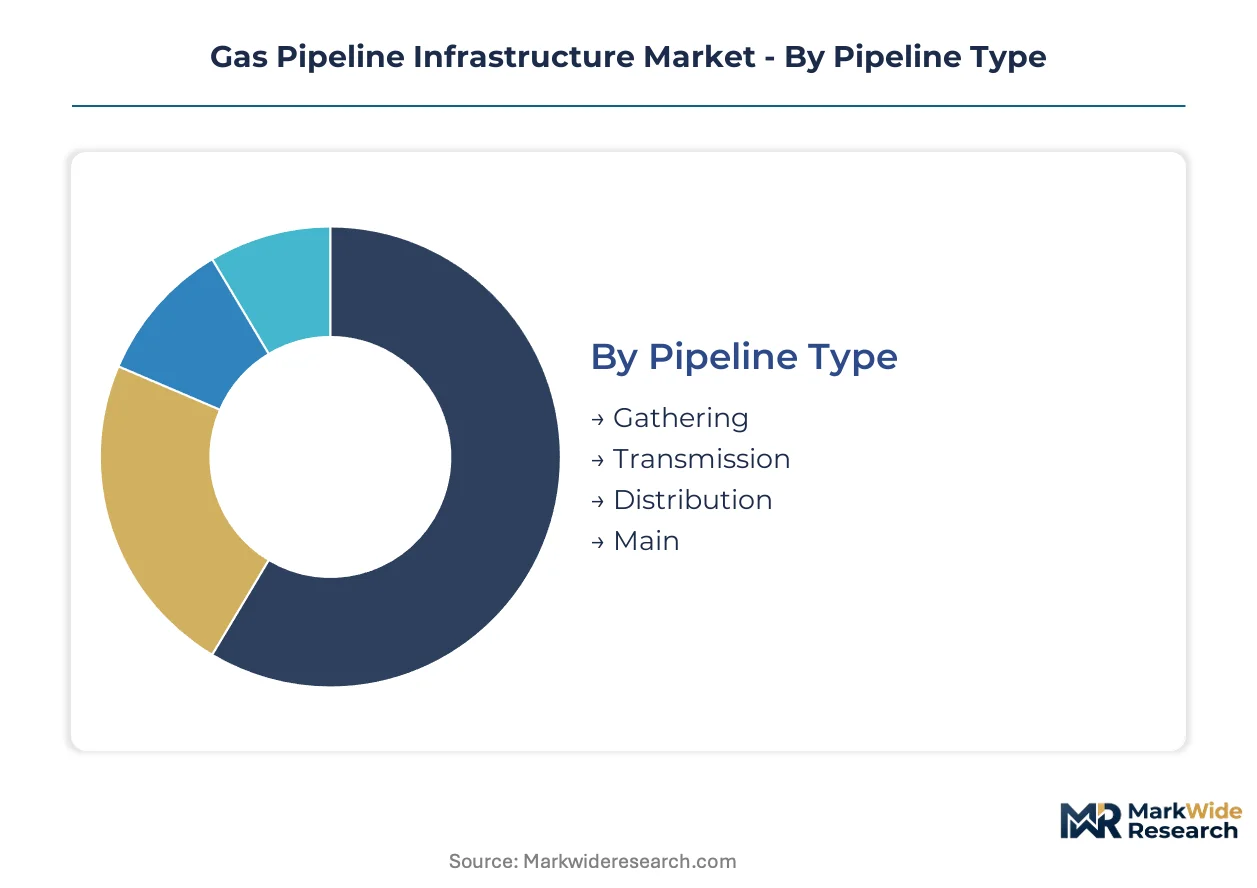
Segmentation reveals how capital allocation splits across pressure regimes, material specifications, and construction methodologies. Each dimension carries distinct regulatory burdens and margin profiles that shape vendor positioning and project economics.
Pipeline Type:
PHMSA Class location requirements and FERC interstate certificates impose tiered compliance burdens that escalate with pipeline scale and population proximity.
- Transmission:High-pressure trunklines operating above 600 psi require API 5L X70/X80 steel, compressor stations at 50-100 mile intervals, and FERC environmental review. Capital concentrates in Permian-to-Gulf corridors where takeaway bottlenecks persist.
- Gathering:Field-level collection networks at 200-800 psi serve shale pad drilling in peripheral acreage. Fastest-expanding segment as producers push into Tier-2 and Tier-3 basins with lower initial flow rates.
- Distribution:Low-pressure urban networks at 60 psi or below connect city gate stations to residential and commercial meters. PHMSA cast-iron replacement mandates dominate capital planning.
- Main:Intermediate pressure feeders bridge transmission interconnections with distribution systems. Municipal franchise agreements dictate route selection and renewal timelines.
Leading the category by volume: Transmission. Growing fastest: Gathering.
Component:
Component selection follows pressure-cycle intensity and maintenance accessibility, with offshore and subterranean installations demanding higher-grade specifications.
- Pipes:Longitudinal seam or spiral-weld steel dominates high-pressure applications; polyethylene displaces cast iron in urban renewal projects where trenchless methods reduce surface disruption.
- Compressors:Centrifugal and reciprocating units powered by gas turbines or electric motors maintain flow momentum across transmission corridors. EU Methane Regulation leak detection mandates accelerate sealing technology upgrades.
- Valves:Block, check, and control configurations enable sectional isolation for maintenance and emergency response. Smart valve actuators with remote telemetry gain share in digitally instrumented networks.
- Fittings:Elbows, tees, reducers, and flanges complete pressure-boundary continuity. Standardized ASME B16.9 specifications reduce fabrication lead times for large-diameter projects.
Revenue concentrates in Pipes. Steepest expansion trajectory: Compressors.
Material:
Material economics hinge on pressure-temperature envelopes, hydrogen compatibility testing, and domestic mill capacity availability.
- Steel:API 5L grades X52 through X80 provide tensile strength for high-pressure transmission. US domestic mill capacity expansion reduces import dependency for 36-inch and 48-inch diameter orders.
- Polyethylene:PE2406 and PE3408 grades serve low-pressure distribution with corrosion immunity and fusion-welded joint integrity. Temperature limits of 140°F prevent transmission application.
- Cast Iron:Legacy urban networks face wholesale replacement under PHMSA integrity management protocols. Remaining installations concentrate in pre-1950s East Coast and Midwest cities.
- Composite:Fiber-reinforced polymer liners enable trenchless rehabilitation of degraded steel mains. Niche adoption in corrosion-prone environments with high soil acidity.
Steel commands absolute volume share. Polyethylene gains share fastest.
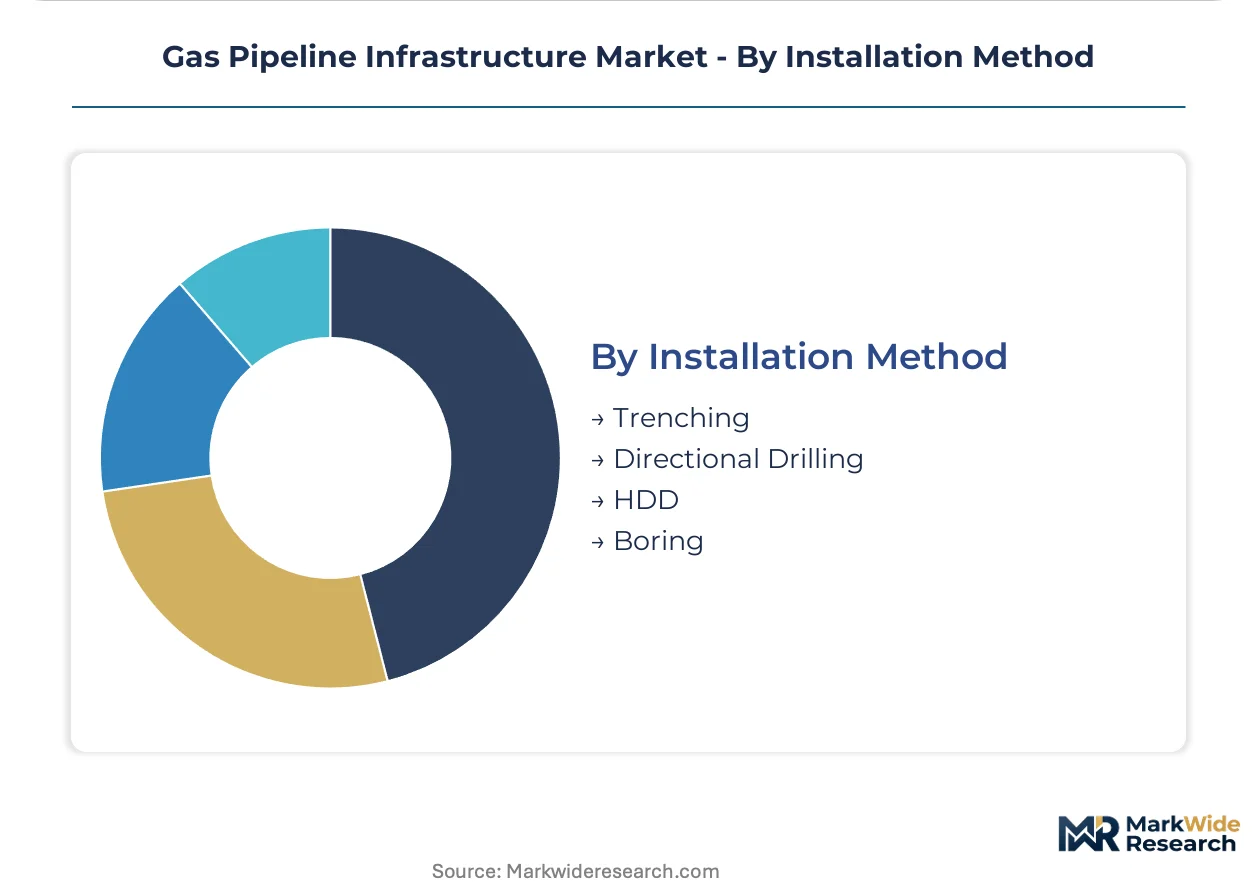
Installation Method:
Surface disruption tolerance and subsurface obstacle density determine method selection, with urban permitting timelines favoring low-impact alternatives.
- Trenching:Open-cut excavation remains standard for greenfield transmission corridors with minimal surface congestion. ROW acquisition and restoration costs dominate economics in agricultural and undeveloped terrain.
- Directional Drilling:Steerable boring under rivers, highways, and wetlands eliminates surface penetration at crossing points. Radius-of-curvature limits constrain application in large-diameter trunklines.
- HDD:Horizontal directional drilling enables urban distribution renewal with minimal traffic disruption. Municipal permitting timelines compress 40-60% versus open-cut alternatives.
- Boring:Micro-tunneling and auger methods complete short crossings under rail lines and existing utilities. Limited to smaller diameters in consolidated soils.
Trenching leads by mileage installed. HDD expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin shale formations anchor North American investment gravity, while Middle Eastern sour-gas reserves and Asia-Pacific city gas distribution programs shape capital flows across three distinct demand poles.
United States
Power utilities deploy pipeline-linked gas turbines to balance renewable intermittency across Texas and California grids. FERC interstate certificate timelines compress development cycles for cross-border corridors. Midstream operators concentrate newbuild investment in the Permian-to-Gulf Coast corridor where takeaway bottlenecks persist.
Germany
Industrial hydrogen blending trials reshape steel pipeline compatibility requirements for existing transmission networks. The EU Methane Regulation mandates optical gas imaging at compressor stations and valve assemblies. Pipeline retrofit clusters concentrate in the Ruhr industrial region where municipal utilities test polyethylene distribution renewals.
China
National oil companies expand West-East trunkline capacity to connect Tarim Basin reserves with coastal demand centers. MIIT pipeline safety standards enforce hydrostatic testing protocols for high-pressure steel installations. Construction activity clusters in the Sichuan-Chongqing shale gas region where gathering network density accelerates.
India
City gas distribution bidding rounds under PNGRB accelerate polyethylene network deployment in Tier-2 and Tier-3 urban clusters. Domestic steel mill capacity expansion reduces import dependency for API 5L-grade transmission materials. Project awards concentrate in Gujarat and Maharashtra where industrial anchor loads justify pipeline economics.
Saudi Arabia
Sour-gas trunkline construction supports Master Gas System expansion into unconventional reserves. National hydrocarbon regulators enforce ASME-compliant welding inspection protocols for high-pressure desert installations. Engineering procurement concentrates in the Eastern Province where offshore-to-onshore gathering systems integrate with processing complexes.
Gas Pipeline Infrastructure Market Vendor Landscape
Global majors compete with regional champions across engineering procurement and construction capability, creating a tiered structure where lump-sum EPC track records separate premium bidders from cost-engineered specialists. Three archetypes dominate: integrated midstream operators with captive construction arms, pure-play engineering contractors with cross-border project experience, and national oil company affiliates with host-government preference. Competitive positioning hardens through backward integration into pipeline construction and long-term shipper contract capture.
Among North American integrated operators, Energy Transfer exemplifies the captive-construction model, while Bechtel represents the lump-sum EPC archetype with cross-border megaproject credentials. Samsung Engineering occupies a position among Asia-Pacific cost-engineered specialists competing for Middle Eastern sour-gas trunkline awards. Mastec anchors the regional utility-services tier focused on distribution network maintenance and urban renewal programs.
| Leading Market Players |
|---|
| Michels Corporation |
| Samsung Engineering |
| Bechtel |
| QatarEnergy |
| Woodside Energy Group |
| Energy Transfer |
| Kiewit Corporation |
| Santos |
| Mastec, Inc. |
| Others |
Supply Flow & Price Mechanics
Integrated midstream operators with captive construction arms command pricing leverage through bundled EPC and long-term tariff structures, while pure-play engineering contractors compete on unbundled lump-sum bids with warranty carve-outs.
Pricing Analysis
Extended warranty and predictive maintenance bundling separates premium EPC bids from baseline construction-only quotes. Three-tier pricing structure across integrated operator, lump-sum contractor, and cost-engineered specialist levels reflects certification depth and track record differentiation. Cost compression in standard-grade transmission projects is intensifying because domestic mill capacity expansion has shortened steel lead times. Merchant developers exhibit highest price sensitivity due to difficulty securing long-term shipper commitments, while national oil company affiliates show lowest sensitivity given host-government preference and captive demand.
Supply Chain Analysis
API 5L-grade steel plate supply rests on domestic US mill capacity, South Korean specialized producers, and German high-strength metallurgy specialists. Longitudinal seam pipe, compressor station turbines, and smart pigging instrumentation constitute critical input categories. Single-source vulnerability concentrates in large-diameter X80 steel orders where qualified mill capacity remains limited. Distribution runs through midstream operator direct procurement for integrated players and tiered contractor-subcontractor networks for project-based awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward integration into pipeline construction and captive steel supply determines competitive durability.
For Market Incumbents: Anchor market position through long-term shipper contract capture in Permian-to-Gulf corridors and backward integration into specialized welding labor training pipelines. Hydrogen-ready turbine procurement delays and certified welder shortages represent immediate threats requiring preemptive capacity locks. For New Entrants and Emerging Players: Begin with trenchless installation method specialization for urban distribution renewals where PHMSA cast-iron replacement mandates create demand visibility. India's PNGRB city gas distribution bidding rounds offer the most penetrable geographic entry point with polyethylene network deployment expertise as the differentiated go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors mid-cap EPC contractors with cross-border megaproject credentials and established FERC certificate navigation capabilities. Long-term viability hinges on hydrogen blending infrastructure retrofit positioning. Watch FERC interstate approval velocity as the primary inflection signal for transmission project finance availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Welding Labor Training | Addresses 18-24 month certified welder shortage lagging project awards across US Gulf Coast and Alberta. |
| Hydrogen-Ready Compressor Station Retrofit | EU Methane Regulation compliance creates service revenue streams for existing transmission corridor operators. |
| Long-Term Shipper Contract Capture | FERC certificate holders secure financing earlier as renewable penetration shortens merchant developer commitment tenors. |
| Trenchless Installation Method Specialization | HDD reduces municipal permitting timelines 40-60% versus open-cut for urban cast-iron replacement mandates. |
| Cross-Border Megaproject EPC Credentialing | Lump-sum track record on FERC-regulated corridors separates premium bidders from cost-engineered specialists. |
Methodological Framework
Independent corroboration across midstream operator planning executives, EPC contractor project directors, and FERC regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork with utility gas procurement managers, pipeline integrity engineers, and steel mill sales directors combined with secondary validation through PHMSA incident databases, FERC certificate filings, and EIA pipeline flow data. Bottom-up project inventory analysis and top-down infrastructure investment tracking triangulate volume estimates.
Historical reference periods spanning pre-shale expansion, mid-decade buildout, and recent bottleneck-constrained investment anchor the projection framework. Segmentation modeling covers pipeline type, pressure regime, material specification, and installation methodology across the analysis window. CAGRs derive from project award velocity tracking and capital commitment pipeline analysis. Hydrogen blending compatibility testing adoption and smart pigging technology penetration serve as industry-specific forecast inputs.
Underlying measurement precision varies by segment; transmission pipeline capital allocation carries tighter precision than gathering network estimates due to FERC disclosure requirements. Forecasts reflect assumptions regarding regulatory enforcement consistency and steel mill capacity expansion timelines. Permian Basin production growth trajectories, EU Methane Regulation implementation pacing, and hydrogen blending standard finalization warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Heavy Movable Bridges Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
Concrete Canvas Market
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
France Transportation Infrastructure Construction Market