
 Oil and Gas Pipeline Fabrication and Construction Market | 2026-2036
Oil and Gas Pipeline Fabrication and Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Pipeline Fabrication and Construction Market Analytics
The oil and gas pipeline fabrication and construction sector is pivoting between premium offshore projects demanding subsea-grade welding and coating capabilities and commoditized onshore spreads competing on throughput velocity. Mastec, Inc. leverages its electric transmission heritage to cross-sell pipeline infrastructure bundling. Michels Corporation anchors its position through self-perform heavy bending capacity across North American shale corridors. Bechtel Corporation dominates megaproject engineering with proprietary modular fabrication yard configurations.
Oil and gas pipeline fabrication and construction encompasses the engineered manufacture, assembly, and field installation of tubular systems for hydrocarbon transport, typically employing API 5L-grade steel with longitudinal or spiral seam welding, fusion-bonded epoxy coating, and radiographic inspection protocols to ensure pressure integrity across transmission and distribution networks. Steel material segments command the deepest margin pools due to alloy grade differentiation and coating complexity, while polyethylene lines represent the fastest-expanding category in gathering and distribution applications where corrosion resistance and trenchless installation reduce lifecycle costs. Welding technology segments lead value capture through automated pipeline welding systems that accelerate tie-in schedules and reduce repair rates on high-strength grades.
PHMSA in the United States enforces pipeline safety regulations through integrity management mandates that drive inspection and maintenance service demand, while API standards govern material specifications and welding procedure qualifications that fabricators must certify before market access. The EU F-Gas Regulation and national methane reduction frameworks in Germany and France are tightening leak detection and repair protocols for existing pipeline networks. Stakeholders must monitor how carbon border adjustments and Scope 3 accounting requirements reshape contractor selection criteria for cross-border pipeline projects.
Market Dynamics
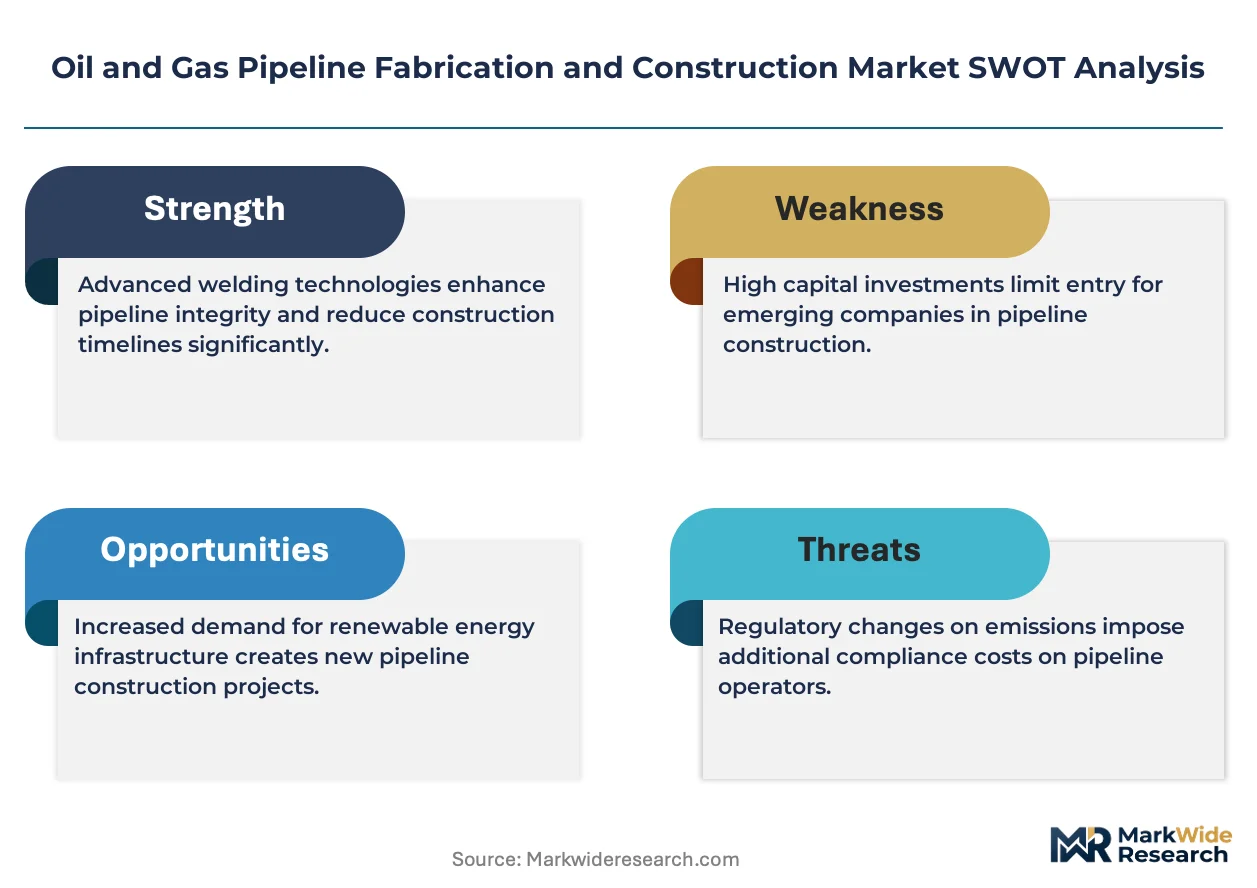
Offshore transmission operators are pushing pipeline networks into deeper waters, forcing fabricators to certify subsea-grade welding procedures and fusion-bonded epoxy coating systems that exceed conventional onshore specifications. This depth-driven capability gap is bifurcating the contractor base between premium subsea specialists and commoditized land spreads.
Growth Catalysts
- Permian Basin infrastructure buildout:Gathering system operators in Texas and New Mexico are commissioning high-strength steel trunklines to handle rising Permian crude output. API 5L X70 and X80 grades dominate new-build specifications.
- EU methane reduction mandates:Germany's national methane framework and France's leak detection protocols are accelerating replacement schedules for aging distribution networks across Continental Europe.
- Automated pipeline welding systems:Mechanized GMAW processes are compressing tie-in schedules on double-jointing lines while reducing radiographic repair rates below two percent on X80 grades.
Market Restraints
- Alloy steel supply concentration:API 5L-grade plate and coil sourcing concentrates among a limited set of integrated mills, exposing fabricators to nickel and molybdenum price volatility.
- PHMSA integrity management mandates:US operators face escalating compliance costs for hydrostatic testing and inline inspection of legacy transmission lines, diverting capital from greenfield construction.
- Polyethylene substitution in gathering:High-density PE pipe is displacing steel in low-pressure shale gathering applications where trenchless installation and corrosion immunity outweigh pressure rating requirements.
Strategic Opportunities
- Hydrogen-ready pipeline retrofits:German transmission operators are piloting X52 steel compatibility assessments for blended hydrogen service, creating inspection and recoating service demand.
- Modular fabrication yard configurations:Bechtel's proprietary yard designs enable parallel spooling and double-jointing workflows that compress project schedules for Middle Eastern megaprojects.
- India's city gas distribution expansion:PNGRB authorization rounds are driving polyethylene and steel distribution network buildouts across tier-two urban clusters.
Industry Challenges
- Certified welding inspector scarcity:API 1104-qualified inspectors command premium rates as project backlogs stretch across North American shale corridors and Gulf Coast export terminals.
- ASME Section IX procedure qualification timelines:New welding procedure specifications require extensive destructive testing and third-party witness, delaying project mobilization by eight to twelve weeks.
- Legacy pipeline material traceability gaps:Pre-1970 transmission lines lack mill test records required for pressure derating assessments under modern integrity management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Pipeline Fabrication and Construction Market |
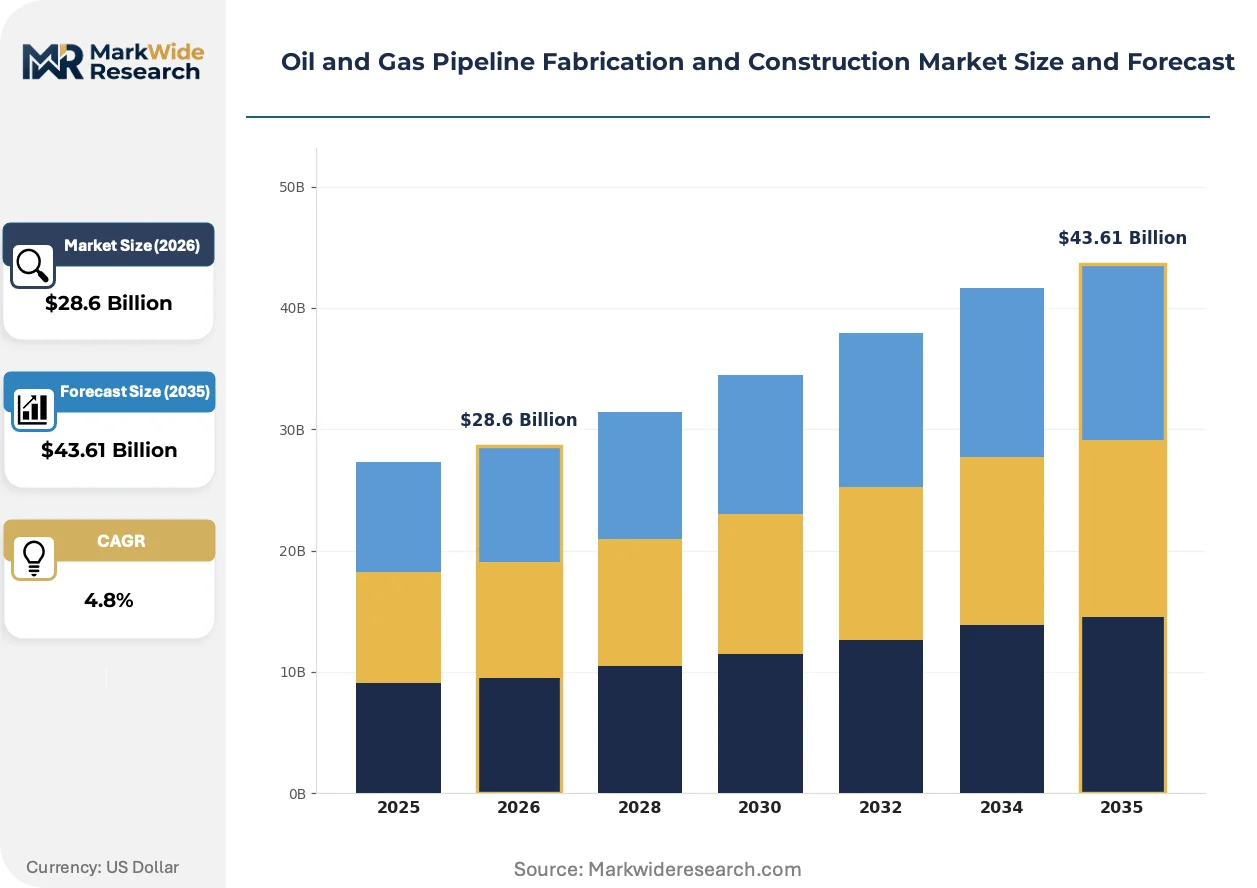
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fabrication, Installation, Inspection, Maintenance Technology: Welding, Coating, Bending, Jointing End User: Exploration Companies, Transmission Operators, Distribution Firms, Contractors Material: Steel, Polyethylene, Composite, Others |
| Companies Covered | Mastec, Inc., Michels Corporation, Bechtel Corporation, Barnard Construction Company, Inc., Snelson Companies Inc., McDermott International, Inc., Kiewit Corporation, Larsen & Toubro Limited, Primoris Services Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Pipeline Fabrication and Construction Market Evolving Landscape
Digital inspection technologies and mechanized welding platforms are compressing fabrication cycles while tightening quality tolerances. The sector is pivoting from manual radiographic interpretation toward automated defect recognition systems that accelerate weld acceptance decisions.
Automated ultrasonic testing is converging with cloud-based data management platforms to enable real-time weld quality verification during offshore pipeline lay operations. Subsea contractors in the Gulf of Mexico and North Sea are deploying phased-array systems that eliminate film-based radiography delays. This convergence is compressing tie-in schedules from fourteen days to four days on deepwater trunkline projects.
The EU F-Gas Regulation is mandating leak detection and repair protocols that exceed conventional pipeline maintenance schedules. German operators must deploy optical gas imaging across transmission corridors with quarterly reporting obligations. This regulatory pressure is accelerating demand for drone-mounted methane sensors and predictive analytics platforms that prioritize dig locations.
Buyer concentration among supermajor operators is forcing fabrication contractors to absorb extended payment terms and performance guarantees. Lump-sum turnkey contracts now dominate offshore project awards, transferring completion risk from Chevron and Shell to construction consortia. This procurement compression is most visible in US Gulf Coast LNG export terminal tie-in projects where contractors self-perform engineering, procurement, and construction scopes.
Oil and Gas Pipeline Fabrication and Construction Market Segmentation
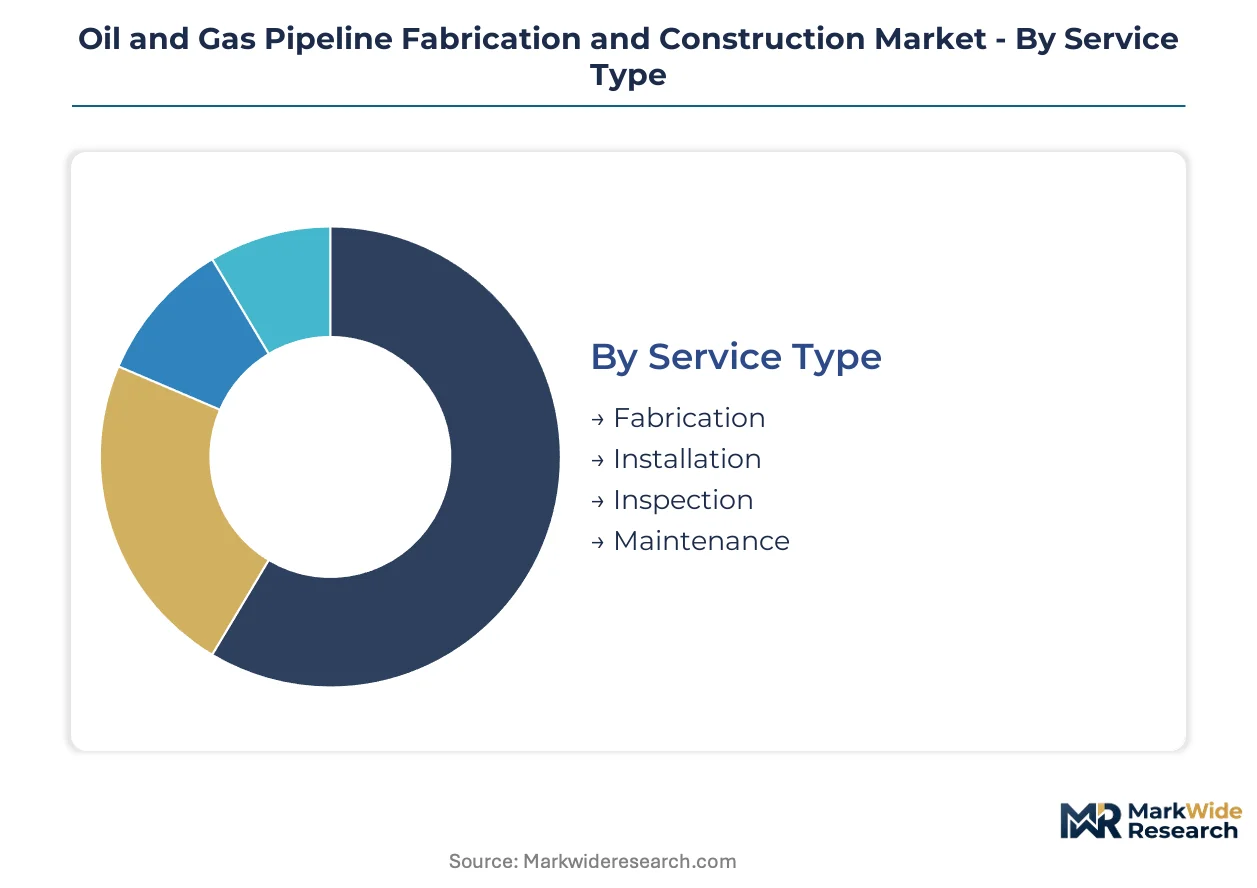
Pipeline fabrication and construction markets fragment across service capabilities, material specifications, and end-user procurement patterns. Each segmentation layer reveals distinct margin pools and capability barriers that determine contractor positioning.
Service Type:
Replacement cycles for aging North American transmission infrastructure are accelerating inspection and maintenance demand while greenfield projects concentrate fabrication and installation spend.
- Fabrication:Shop-based spooling and double-jointing of API 5L-grade pipe dominates capital allocation for new trunkline projects. Permian Basin operators commission high-strength X70 and X80 segments requiring automated welding and fusion-bonded epoxy coating in controlled yard environments.
- Installation:Field construction encompasses trenching, stringing, bending, and tie-in operations across varied terrain. Gulf Coast LNG export terminal tie-ins demand specialized crews for congested corridor work with compressed schedules.
- Inspection:Radiographic and ultrasonic testing protocols verify weld integrity per API 1104 and ASME Section IX requirements. PHMSA integrity management mandates drive recurring revenue from inline inspection tool runs and direct assessment programs.
- Maintenance:Leak repair, recoating, and pressure derating assessments address legacy pipeline conditions. Germany's national methane framework accelerates replacement schedules for pre-1990 distribution networks.
Volume placements concentrate in Fabrication; the faster expansion belongs to Inspection.
Technology:
Cost tiers separate automated systems commanding premium day rates from manual methods competing on labor arbitrage.
- Welding:Mechanized GMAW processes compress tie-in schedules while holding radiographic repair rates below two percent on X80 grades. Certified welding inspector scarcity pushes contractors toward self-performing automated systems rather than subcontracted manual crews.
- Coating:Fusion-bonded epoxy application in shop conditions ensures corrosion protection for subsea and high-temperature service. Offshore projects in deeper Gulf of Mexico waters demand coating systems exceeding conventional onshore specifications.
- Bending:Induction bending of high-strength grades requires precise temperature control to preserve mechanical properties. Self-perform bending capacity anchors contractor positioning in North American shale corridors.
- Jointing:Flash-butt and electrofusion methods serve polyethylene distribution networks. India's city gas distribution expansion drives demand for trenchless jointing technologies in dense urban corridors.
Margin capture clusters in Welding; technology adoption is climbing the fastest in Coating.
End User:
Customer type determines contract structure, with supermajors extracting lump-sum turnkey terms and smaller operators accepting cost-plus arrangements.
- Exploration Companies:Upstream operators commission gathering systems linking wellheads to processing facilities. Permian crude output growth sustains demand for high-pressure steel trunklines from independent producers.
- Transmission Operators:Interstate pipeline companies manage FERC-regulated long-haul corridors with decades-long asset lives. Integrity management spending diverts capital from greenfield construction toward assessment and repair.
- Distribution Firms:Local gas utilities operate low-pressure networks subject to state public utility commission oversight. France's leak detection protocols mandate quarterly optical gas imaging surveys.
- Contractors:Engineering-procurement-construction firms bundle pipeline scopes within broader infrastructure programs. Bechtel's proprietary modular yard configurations compress megaproject schedules.
Procurement volume aggregates with Transmission Operators; the steepest expansion trajectory is emerging among Contractors.
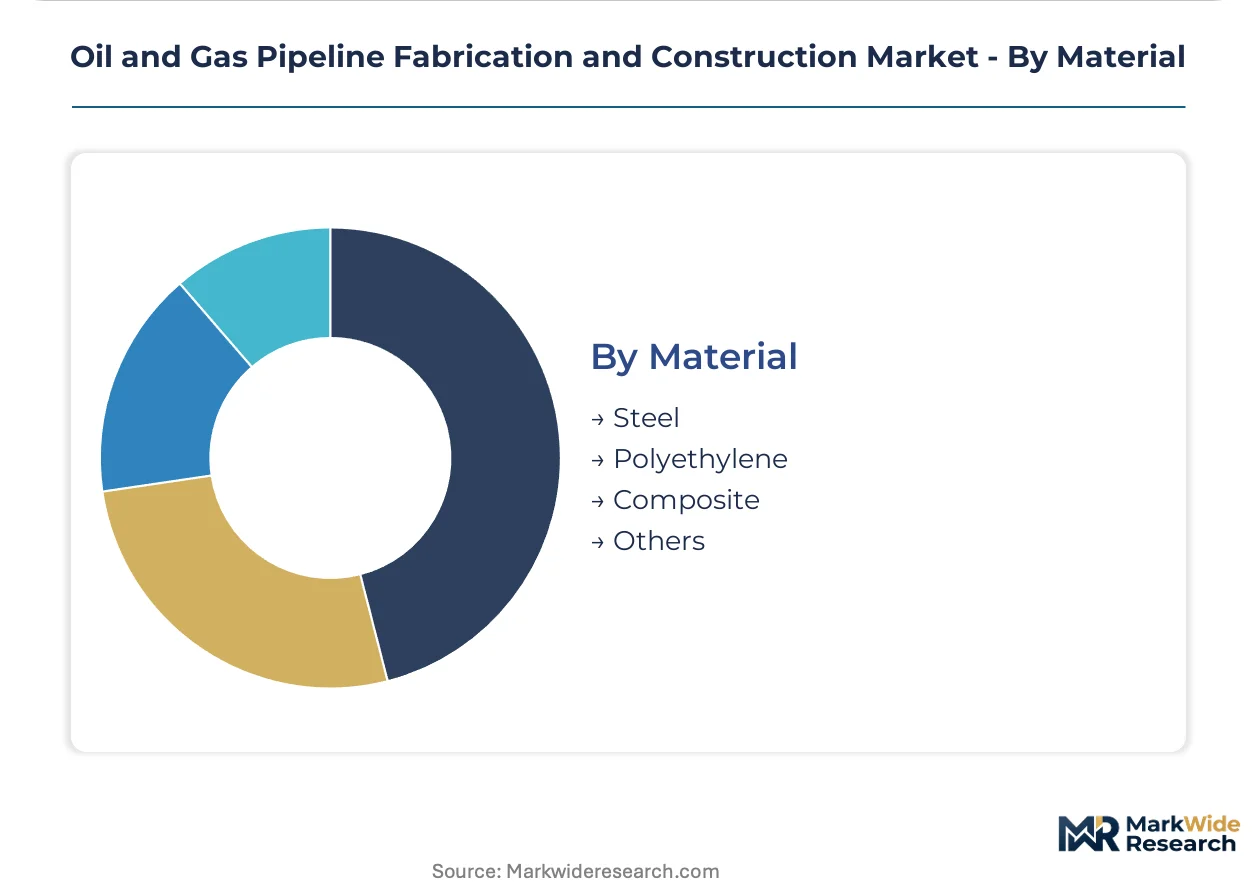
Material:
Application requirements dictate material selection, with pressure ratings and corrosion exposure determining steel versus polyethylene deployment.
- Steel:API 5L-grade carbon and alloy pipe commands the deepest margin pools through grade differentiation and coating complexity. Nickel and molybdenum price volatility exposes fabricators to input cost swings from concentrated mill supply.
- Polyethylene:High-density PE pipe displaces steel in low-pressure shale gathering where trenchless installation and corrosion immunity reduce lifecycle costs. India's PNGRB authorization rounds accelerate polyethylene distribution network buildouts.
- Composite:Reinforced thermoplastic pipe serves corrosive sour gas and subsea jumpers with reduced weight versus steel. Qualification testing under DNV standards limits near-term deployment scale.
- Others:Ductile iron and concrete pressure pipe retain niche positions in water crossover and cooling water applications. These materials face displacement from flexible composite alternatives.
Revenue concentration remains with Steel; Polyethylene is gaining share fastest in gathering applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast corridor from Houston to New Orleans anchors pipeline fabrication capacity, with yard complexes concentrated along the Sabine-Neches waterway serving Permian Basin trunkline demand and LNG export terminal tie-ins.
United States
Permian Basin operators in Texas and New Mexico commission high-strength X70 and X80 trunklines to handle rising crude output. PHMSA enforces integrity management mandates that divert capital toward hydrostatic testing and inline inspection of legacy transmission lines. Fabrication yards in Houston and Beaumont specialize in automated double-jointing and fusion-bonded epoxy coating for export-bound projects.
Germany
Transmission operators pilot X52 steel compatibility assessments for blended hydrogen service, creating inspection and recoating demand across existing networks. The national methane framework mandates quarterly optical gas imaging surveys with leak detection protocols exceeding conventional maintenance schedules. Industrial clusters in North Rhine-Westphalia concentrate pipeline maintenance contractors serving Ruhr corridor distribution networks.
India
PNGRB authorization rounds accelerate polyethylene and steel distribution network buildouts across tier-two urban clusters. City gas distribution mandates drive trenchless installation technologies in dense metropolitan corridors. Fabrication activity concentrates in Gujarat and Maharashtra, where contractors serve expanding networks in Surat, Ahmedabad, and Pune.
Saudi Arabia
Megaproject engineering demand from Aramco sustains specialized fabrication for high-temperature, high-pressure trunklines. Domestic content requirements under Vision 2030 localize yard operations for strategic pipeline corridors. The Eastern Province hosts modular fabrication complexes serving Shaybah and Khurais field extensions.
Brazil
Pre-salt development offshore Santos Basin drives subsea pipeline demand requiring subsea-grade welding certification. ANP local content rules mandate domestic fabrication participation in trunkline projects. Yard capacity concentrates in Rio de Janeiro state, serving Petrobras-led deepwater tie-ins.
Oil and Gas Pipeline Fabrication and Construction Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated contractor base. Premium subsea specialists command day rates for deepwater certification capabilities while commoditized land spreads compete on throughput velocity across shale corridors. Three archetypes dominate: integrated EPC firms bundling engineering and construction, self-perform heavy contractors controlling bending and welding capacity, and specialized inspection service providers. Consolidation pressure concentrates among fabrication yards seeking scale for plate sourcing leverage, while technology licensing agreements spread automated welding platforms across mid-tier operators.
Among North American contractors, Mastec, Inc. and Michels Corporation exemplify the self-perform heavy capacity archetype, with Michels anchoring positioning through controlled bending operations across shale corridors. Bechtel Corporation represents the integrated EPC tier, with proprietary modular yard configurations compressing megaproject schedules in Middle Eastern markets. These three firms illustrate how capability depth in welding automation or modular fabrication design separates premium-tier positioning from rate-competitive land spreads.
| Leading Market Players |
|---|
| Mastec, Inc. |
| Michels Corporation |
| Bechtel Corporation |
| Barnard Construction Company, Inc. |
| Snelson Companies Inc. |
| McDermott International, Inc. |
| Kiewit Corporation |
| Larsen & Toubro Limited |
| Primoris Services Corporation |
| Others |
Value Network & Pricing Analysis
Subsea-grade certification tiers bifurcate contractor positioning between premium offshore specialists commanding day-rate premiums and commoditized land spreads competing on throughput velocity, with this divergence manifesting in divergent procurement strategies and plate sourcing leverage across API 5L-grade steel supply chains.
Pricing Analysis
Throughput-based pricing anchors offshore project awards, where lump-sum turnkey contracts transfer completion risk from supermajor operators to construction consortia. Price differentiation separates API 1104-certified welding crews from manual subcontractor labor, with certified inspector scarcity pushing rates upward. Cost compression in onshore gathering segments intensifies because polyethylene substitution displaces steel in low-pressure applications. Independent Permian Basin producers exhibit highest price sensitivity, while Aramco megaprojects absorb extended payment terms with least negotiation.
Supply Chain Analysis
API 5L procedure qualification requirements gate market access for fabricators, with ASME Section IX destructive testing and third-party witness protocols filtering capable suppliers. Steel plate and coil sourcing concentrates in the United States, Germany, and Japan, with nickel and molybdenum alloying elements drawing from concentrated integrated mill supply. Single-source vulnerability runs through legacy mill test record gaps for pre-1970 transmission lines. Distribution feeds from modular fabrication yard complexes along the Sabine-Neches waterway to field construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated pipeline welding systems are displacing manual radiographic methods, compressing tie-in schedules from fourteen days to four days on deepwater trunkline projects and forcing contractor technology transitions.
For Market Incumbents: Acquire certified welding inspector capacity through targeted recruitment programs and training academy investments. Mastec and Michels should expand self-perform automated GMAW fleets to offset subcontractor labor inflation, while securing long-term API 5L-grade plate offtake agreements with integrated mills to hedge nickel price volatility. For New Entrants and Emerging Players: Mid-tier Indian city gas distribution contractors represent an underserved buyer archetype seeking trenchless polyethylene jointing capabilities. New entrants should anchor positioning through PNGRB-authorized project participation in Surat and Pune, leveraging flash-butt and electrofusion technology licensing from established European suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in EPC consolidation plays, with Bechtel-style modular yard configurations commanding strategic premiums. Long-term viability hinges on hydrogen-ready retrofit service demand across German X52 networks. Watch Aramco domestic content localization timelines under Vision 2030 as inflection indicator for Middle Eastern fabrication capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Welding Platform Deployment | Mechanized GMAW systems compress tie-in schedules below four days on X80-grade deepwater projects. |
| Modular Fabrication Yard Expansion | Parallel spooling configurations enable Bechtel-style schedule compression for Middle Eastern megaprojects. |
| Hydrogen Compatibility Assessment Service | X52 steel recoating demand from German transmission operators pilots blended hydrogen service transitions. |
| API 5L Plate Supply Agreement | Long-term offtake contracts with integrated mills hedge nickel and molybdenum price volatility exposure. |
| Certified Inspector Training Academy | API 1104 qualification pipelines address scarcity premiums stretching across North American shale corridors. |
Research Methodology
Multi-period observation of PHMSA enforcement actions, API welding procedure qualification timelines, and Aramco megaproject award patterns anchored the trend analysis, supplemented by interviews with pipeline integrity management directors, EPC project controllers, API-certified welding inspectors, and steel procurement leads at integrated mills. Secondary validation drew from FERC interstate pipeline filings, EIA crude production data, DNV subsea qualification records, and SEC 10-K disclosures from publicly traded contractors. Bottom-up project pipeline tracking and top-down regional demand modeling enabled triangulation across data sources.
Segment-weighting across service type, material specification, and end-user procurement patterns shaped the analytical framework over the projection horizon. Modeled dimensions encompassed fabrication versus installation versus inspection revenue splits, API 5L X70/X80 grade penetration, and supermajor versus independent operator contract structures. CAGRs were derived from regression analysis against Permian Basin well completion counts and LNG export terminal construction schedules, with hydrogen-ready retrofit demand curves informing European trajectory assumptions.
Revisions become necessary when PHMSA integrity management mandates accelerate, EU methane reduction protocols tighten, or polyethylene substitution rates in shale gathering exceed modeled thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Ship Port Infrastructure Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Concrete Canvas Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
Heavy Movable Bridges Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
South Korea Infrastructure Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market