
 Norway Transportation Infrastructure Construction Market | 2026-2036
Norway Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Transportation Infrastructure Construction Market Analytics
Market Context
The National Transport Plan is restructuring capital allocation across Norwegian construction procurement. Veidekke leverages its domestic civil engineering footprint to anchor large-scale road and rail contracts. Skanska competes through sustainable construction methodologies aligned with public-sector environmental criteria. AF Gruppen specializes in complex tunnelling projects that dominate Norway's mountainous terrain.
Technical Definition and Segment Structure
Norway transportation infrastructure construction encompasses the engineering, materials deployment, and assembly of surface and subsurface transit systems including highways, bridges, railways, and airports, typically requiring reinforced concrete segments rated for freeze-thaw cycles and high axial loads from heavy freight corridors. Railways command the deepest project backlogs as the Bane NOR network electrification program absorbs multibillion-crown commitments. Concrete dominates material procurement due to Norway's abundant domestic aggregate reserves and established ready-mix supply chains. Sustainable construction methods are displacing traditional pour-in-place techniques as public clients embed lifecycle carbon thresholds into tender evaluation.
Regulatory Frame and Outlook
The Norwegian Public Roads Administration and Bane NOR enforce design standards that exceed baseline EU structural codes, particularly for avalanche-resistant bridge geometry and subsea tunnel ventilation. The Planning and Building Act, administered by the Ministry of Local Government and Regional Development, mandates climate risk assessments for all trunk infrastructure exceeding defined cost thresholds. Stakeholders must monitor whether parliamentary revisions to the National Transport Plan accelerate coastal highway completion timelines or redirect funds toward urban transit densification.
Market Dynamics
The National Transport Plan's climate-adapted infrastructure mandate is compressing project timelines while elevating technical specifications for avalanche-resistant geometry and subsea tunnel ventilation systems across Norwegian procurement.
Growth Catalysts
- Railway Electrification Mandate:Bane NOR's multibillion-crown network modernization program sustains deep project backlogs for electrified corridors, particularly along the Oslo-Akershus density corridor.
- Domestic Aggregate Reserves:Norway's abundant hard rock formations enable cost-competitive concrete procurement that anchors ready-mix supply chains for freeze-thaw rated segments.
- Subsea Tunnel Pipeline:Coastal highway completion timelines prioritize complex undersea crossings where specialized tunnelling demand concentrates in western fjord regions.
Market Restraints
- Specialized Labor Scarcity:Norway's tight construction labor market constrains project velocity for subsea tunnel and avalanche-resistant bridge specialists.
- Geographic Supply Concentration:Ready-mix concrete production clusters near coastal population centers, inflating logistics costs for interior mountain corridor projects.
- Design Standard Stringency:The Norwegian Public Roads Administration's codes exceed baseline EU structural requirements, extending engineering cycles and compliance documentation.
Strategic Opportunities
- Troms and Finnmark Connectivity:Northern Norway's sparse road density presents white-space potential for climate-adapted coastal highway extensions serving Arctic freight corridors.
- Lifecycle Carbon Thresholds:Public-sector tender evaluation now embeds embodied carbon metrics, rewarding contractors with low-emission concrete formulations and electrified equipment fleets.
- Digital Twin Convergence:Integration of BIM models with real-time geological sensors enables predictive maintenance contracts for tunnel ventilation and avalanche monitoring systems.
Industry Challenges
- Permitting Timeline Compression:The Planning and Building Act's climate risk assessment mandates add procedural layers that conflict with parliamentary funding cycle pressures.
- Legacy System Interoperability:New electrified rail corridors must integrate with Bane NOR's existing signaling infrastructure, comrolling voltage standardization across network segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Transportation Infrastructure Construction Market |
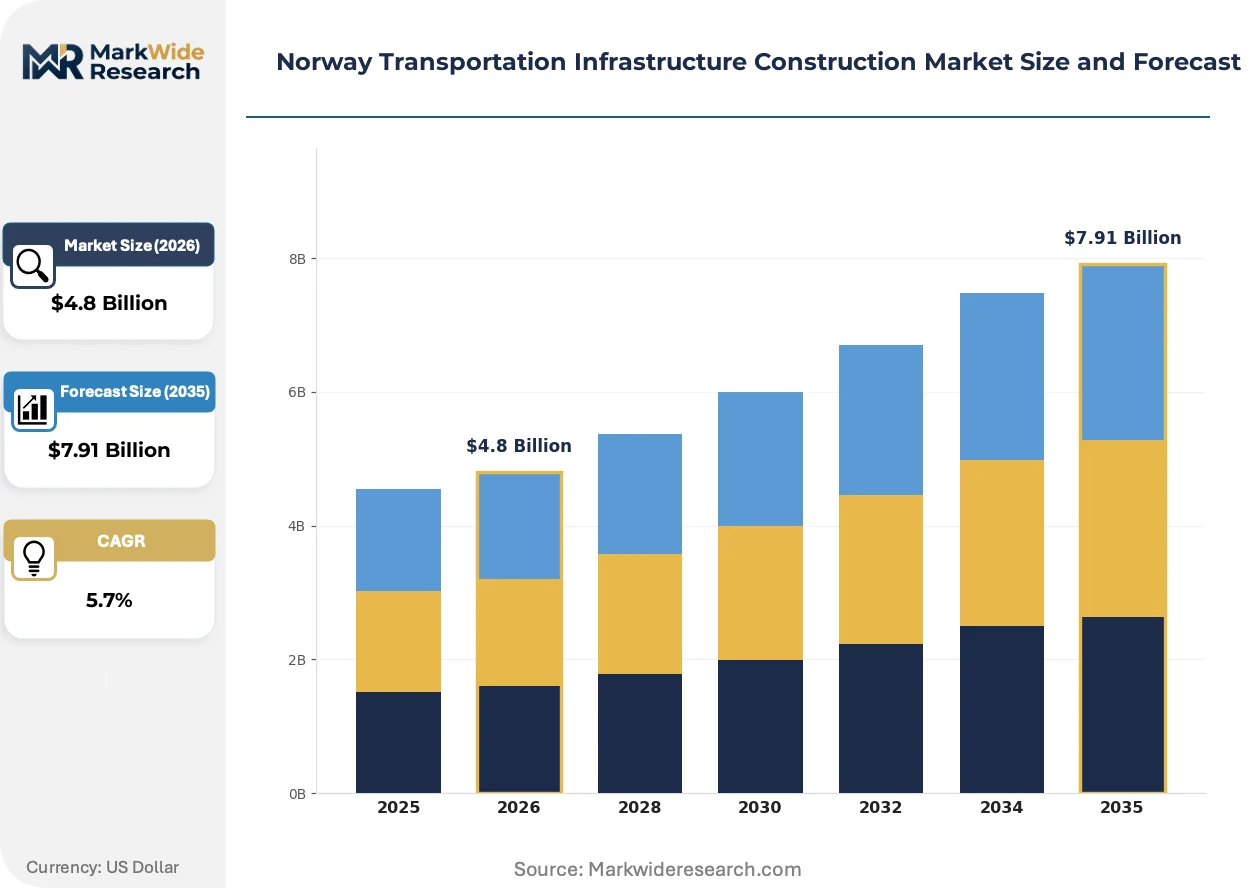
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Highways, Bridges, Railways, Airports Material Type: Concrete, Asphalt, Steel, Composites Construction Method: Traditional, Prefabricated, Modular, Sustainable End User: Government Agencies, Private Developers, Contractors, Consultants |
| Companies Covered | WSP, FCC Construccion, Webuild, NCC, Implenia AG, Skanska, Veidekke, AF Gruppen, ACCIONA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Transportation Infrastructure Construction Market Evolving Landscape
Digital fabrication methods and embodied carbon accounting are restructuring how Norwegian transportation infrastructure moves from design to commissioning, with public procurement criteria now prioritizing measurable lifecycle performance over upfront capital cost.
Prefabricated reinforced concrete segments rated for freeze-thaw cycling are overtaking traditional pour-in-place techniques for bridge and tunnel lining applications. Bane NOR and county road authorities specify factory-cured elements to compress weather-dependent construction windows. This standardization is overtaking site-cast methods that expose crews to Norway's extended winter shutdown periods.
The Planning and Building Act's climate risk assessment mandate, administered by the Ministry of Local Government and Regional Development, now applies to all trunk infrastructure above defined cost thresholds. Project sponsors must document avalanche, flood, and permafrost exposure scenarios before securing development consent. Mountain corridor road and rail projects face the steepest compliance burden, with engineering consultancies expanding geohazard modeling capabilities to meet tender requirements.
Public clients now unbundle long-term maintenance obligations from initial construction contracts, creating separate procurement streams for operational-phase asset management. County road authorities and Bane NOR issue performance-based service agreements spanning 15-25 year horizons. This restructuring is most advanced in the Oslo-Akershus corridor, where density justifies dedicated maintenance vehicle fleets and predictive inspection regimes.
Norway Transportation Infrastructure Construction Market Segmentation
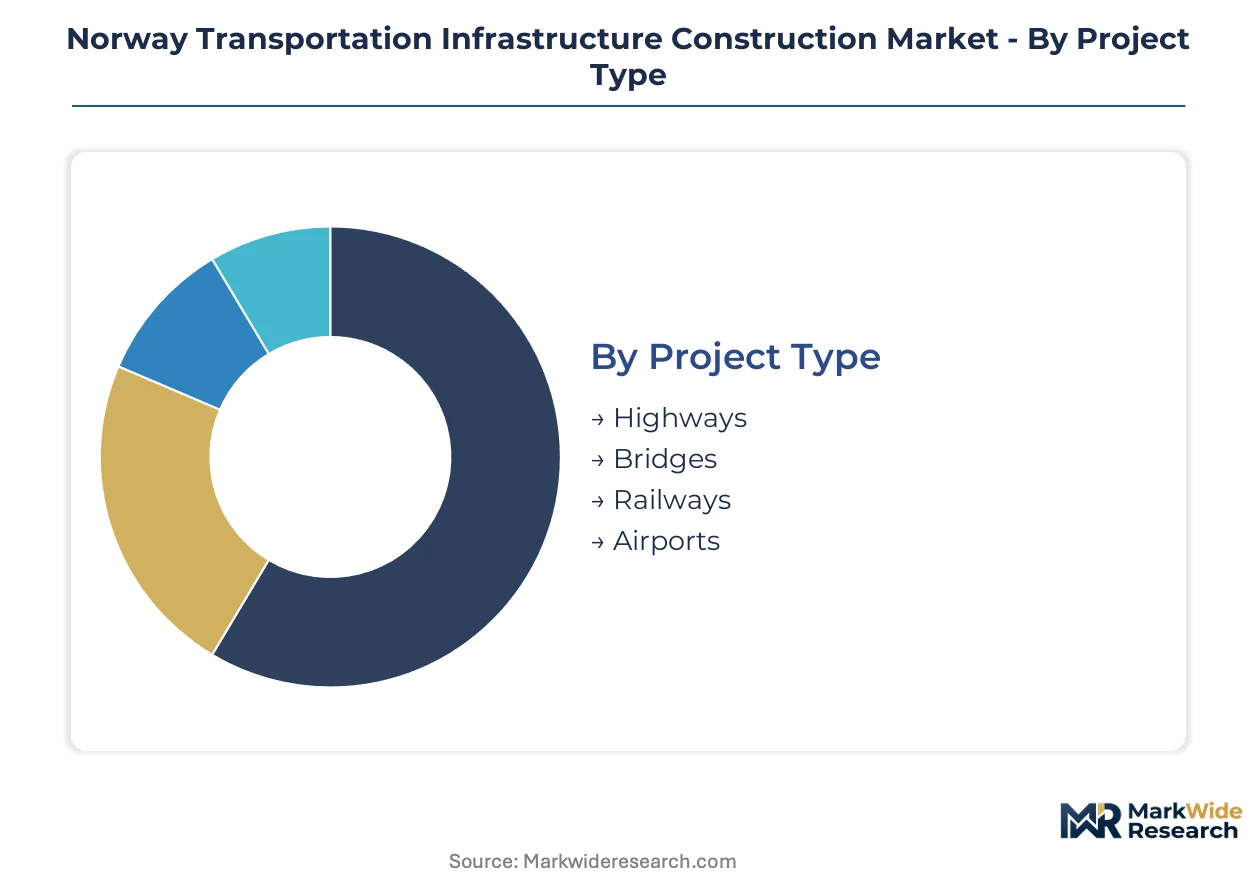
Norway's transportation infrastructure construction segments reflect the country's distinctive geography and climate mandates. Project sponsors select materials and methods based on avalanche exposure, subsea crossing complexity, and Bane NOR electrification timelines rather than cost alone.
Project Type:
Standalone mega-projects dominate procurement volumes, while embedded network extensions absorb sustained maintenance capital across Bane NOR and county road authority portfolios.
- Railways:Electrified corridor construction absorbs the deepest project backlogs under Bane NOR's modernization mandate. Oslo-Akershus density corridor prioritizes double-tracking and platform extensions to accommodate freight growth from Swedish ore lines.
- Highways:Coastal highway completion drives multibillion-crown commitments through western fjord regions where terrain forces subsea tunnel solutions. The Norwegian Public Roads Administration parcels contracts around avalanche-resistant geometry requirements.
- Bridges:Mountain corridor crossings require specialized foundations rated for permafrost degradation and debris flow loading.
- Airports:Avinor's regional network upgrades concentrate on runway resurfacing and terminal expansions serving Arctic freight routes.
Railways lead volumes today; highways are gaining share fastest through coastal corridor completion timelines.
Material Type:
Cost tiers separate domestically sourced bulk materials from imported specialty formulations required for extreme durability specifications.
- Concrete:Factory-cured reinforced segments rated for freeze-thaw cycling now dominate bridge decks and tunnel linings. Norway's abundant hard rock aggregate reserves anchor cost-competitive ready-mix supply chains near coastal population centers.
- Steel:Weathering-grade structural sections command premium procurement for avalanche-resistant bridge superstructures in Troms and Finnmark corridors.
- Asphalt:Polymer-modified surface courses specified for high-altitude roads face extended seasonal placement windows.
- Composites:Fiber-reinforced polymer decking trials advance for lightweight pedestrian bridge applications in heritage-sensitive districts.
Concrete leads volumes today; steel is expanding most quickly through Arctic corridor durability mandates.
Construction Method:
Maturity curves separate decades-established techniques from emerging methodologies still proving lifecycle performance under Norwegian climatic stressors.
- Prefabricated:Off-site concrete segment production compresses weather-dependent construction windows and reduces crew exposure to winter shutdown periods. County road authorities now specify factory-cured elements for standardized bridge components.
- Sustainable:Low-emission concrete formulations and electrified equipment fleets embed lifecycle carbon thresholds into tender evaluation criteria. Bane NOR's green procurement guidelines reward contractors with documented embodied carbon reductions.
- Traditional:Pour-in-place techniques persist for complex foundation work where site-specific geotechnical conditions defy standardization.
- Modular:Pre-assembled tunnel ventilation and drainage systems accelerate subsea crossing schedules where compressed air working limits crew rotations.
Traditional methods lead volumes today; prefabricated approaches are climbing the fastest through weather-window compression incentives.
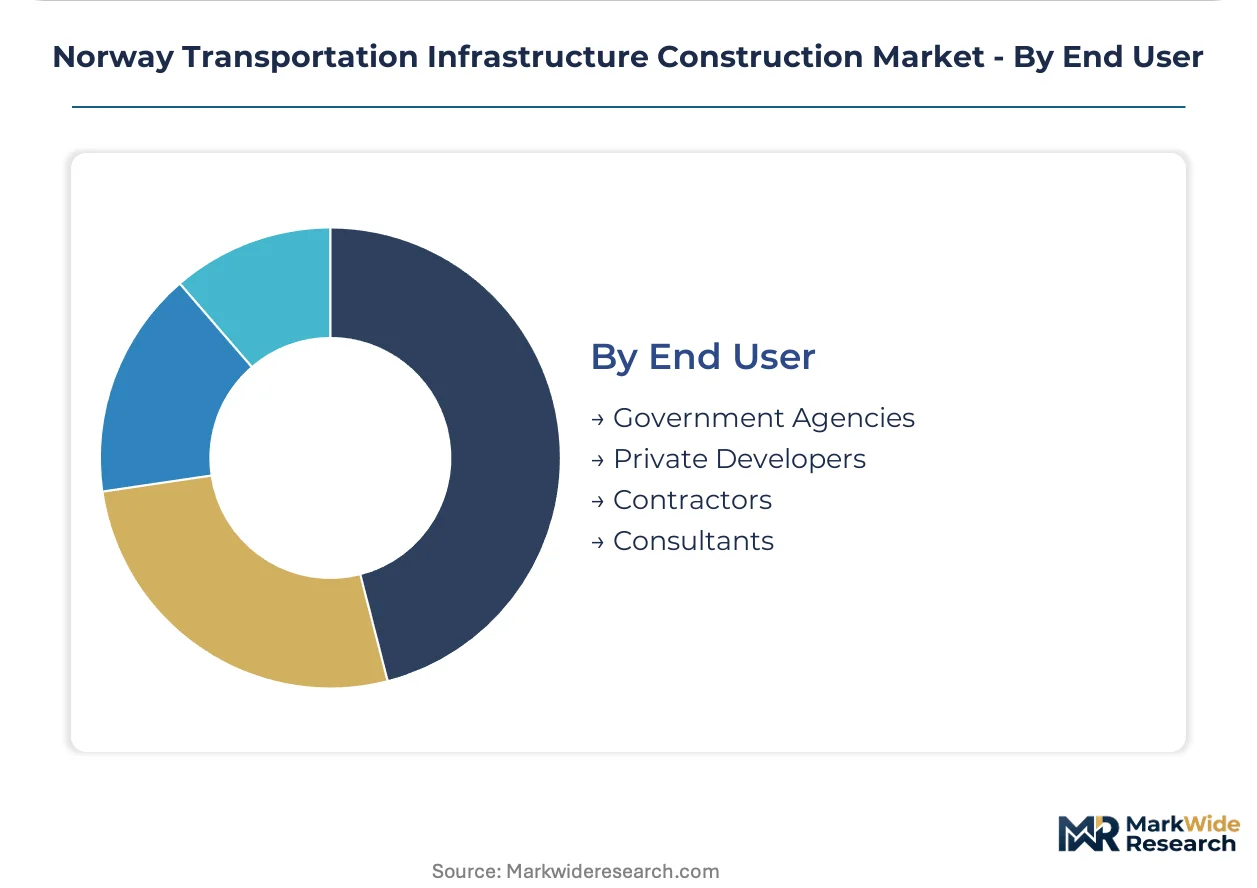
End User:
Customer type determines contract scale, risk allocation, and maintenance obligation bundling across Norwegian procurement streams.
- Government Agencies:The Norwegian Public Roads Administration and Bane NOR issue multiyear framework agreements with performance-based maintenance unbundling. Climate risk assessment mandates under the Planning and Building Act add procedural compliance layers to trunk infrastructure tenders.
- Contractors:Veidekke, Skanska, and AF Gruppen compete for design-build-operate contracts spanning 15-25 year service horizons. Specialized tunnelling capabilities differentiate bidders for western fjord subsea crossings.
- Private Developers:Industrial logistics park sponsors fund last-mile road and rail connections serving Arctic freight corridors.
- Consultants:Geohazard modeling specialists expand capabilities to meet avalanche, flood, and permafrost exposure documentation requirements.
Government agencies lead volumes today; contractors are gaining share fastest through long-term service agreement restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's transportation infrastructure construction sector traces its modern engineering lineage to the post-war expansion of coastal highways and railway electrification programs initiated in the 1950s. These foundational projects established the technical standards and procurement frameworks that persist today. The sector now concentrates investment in corridors where population density intersects with climate adaptation mandates.
Oslo-Akershus Corridor
Bane NOR's double-tracking program and platform extensions drive sustained rail construction volumes along this density spine. The Norwegian Public Roads Administration parcels highway maintenance contracts through performance-based frameworks. Urban transit densification concentrates contractor resources around Drammen and Lillestrøm satellite nodes.
Western Fjord Regions
Subsea tunnel completions dominate capital allocation where terrain blocks surface road continuity. The Planning and Building Act's climate risk assessments apply with particular stringency to avalanche-exposed mountain approaches. Specialized tunnelling consortia cluster around Bergen and Ålesund procurement offices.
Troms and Finnmark
Arctic freight corridor extensions absorb infrastructure investment serving mining and seafood export logistics. Permafrost degradation concerns elevate foundation engineering specifications beyond baseline national codes. Contractor mobilization centers on Tromsø as the northern procurement hub.
Trøndelag Central Zone
Trondheim's regional rail junction status sustains electrification and signaling upgrade cycles. County road authorities prioritize coastal highway resilience against storm surge exposure. Industrial logistics parks near Orkanger generate last-mile connection demand.
Southern Norway
Stavanger's energy sector logistics sustain road and bridge maintenance backlogs. The Norwegian Public Roads Administration enforces stringent subsea tunnel ventilation standards for Rogaland crossings. Prefabricated concrete segment demand concentrates around Kristiansand supply depots.
Norway Transportation Infrastructure Construction Market Competitive Landscape
The competitive structure tilts toward domestic civil engineering specialists with established Bane NOR and county authority relationships. Market concentration remains moderate, with tier-one contractors capturing framework agreements while regional players contest discrete project lots. Two strategic archetypes dominate: integrated design-build-operate consortia and specialized tunnelling subcontractors. Competitive moves center on long-term service agreement restructuring and sustainable construction credential accumulation.
Among Scandinavian-anchored contractors, Skanska and Veidekke occupy positions within the integrated service tier, while AF Gruppen exemplifies the specialized tunnelling archetype. These entities represent distinct competitive vectors—Skanska and Veidekke through multiyear framework coverage across project types, AF Gruppen through concentrated expertise in subsea and mountain corridor execution. Their positioning reflects the market's bifurcation between scale-driven operators and technical specialists.
| Leading Market Players |
|---|
| WSP |
| FCC Construccion |
| Webuild |
| NCC |
| Implenia AG |
| Skanska |
| Veidekke |
| AF Gruppen |
| ACCIONA |
| Others |
Value Network & Pricing Analysis
Factory-cured concrete segment certification separates premium-tier contractors from commodity players across Norwegian procurement, with Bane NOR's green procurement guidelines embedding lifecycle carbon thresholds that simultaneously reshape tender evaluation criteria and aggregate sourcing patterns from coastal population centers to interior mountain corridors.
Pricing Analysis
Bundled long-term service agreements now command premium positioning against unbundled construction-only contracts. Price differentiation rests on embodied carbon documentation and electrified equipment fleet credentials. Cost compression in standard pour-in-place techniques is intensifying because prefabricated methods compress weather-dependent construction windows. Municipal road authorities exhibit highest price sensitivity; Bane NOR electrification programs demonstrate lowest sensitivity due to multiyear framework commitments.
Supply Chain Analysis
Freight cost inflation from coastal ready-mix depots to interior mountain corridors anchors supply chain configuration decisions. Production concentrates in Norway, Sweden, and Denmark. Raw material flows draw from domestic hard rock aggregate reserves, imported weathering-grade steel sections, and polymer-modified asphalt formulations. Single-source vulnerability persists for specialized subsea tunnel ventilation equipment. Distribution runs through county road authority procurement offices and Bane NOR regional frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's transportation infrastructure sector functions as a regulatory compounder, with the Planning and Building Act's climate risk assessment mandate generating sustained engineering demand across avalanche-exposed corridors and subsea tunnel approaches.
For Market Incumbents: Lock in framework agreement renewals with Bane NOR and county road authorities before specialized tunnelling consortia consolidate western fjord market share. Deepen in-house production of factory-cured concrete segments to defend margin position against ready-mix supply chain disruptions. Prioritize electrified equipment fleet investments to meet green procurement thresholds. For New Entrants and Emerging Players: Capture white-space in Troms and Finnmark Arctic freight corridor extensions where permafrost engineering capabilities remain undersupplied. Target digital twin integration services for predictive tunnel maintenance contracts. Lead with BIM-geological sensor convergence as entry wedge against established design-build-operate incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized tunnelling subcontractors holding western fjord project execution track records. Five-to-ten year viability hinges on coastal highway completion timeline acceleration versus urban transit densification fund shifts. Monitor parliamentary National Transport Plan revisions as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Concrete Segment Certification | Bane NOR's green procurement guidelines reward factory-cured elements with documented embodied carbon reductions. |
| Electrified Equipment Fleet Investment | County road authorities now embed lifecycle carbon thresholds into tender evaluation criteria. |
| Digital Twin Platform Integration | Real-time geological sensor convergence enables predictive maintenance contracts for avalanche monitoring systems. |
| Arctic Corridor Capability Expansion | Troms and Finnmark permafrost engineering demand outpaces specialized contractor supply. |
| Long-Term Service Agreement Restructuring | Performance-based 15-25 year frameworks unbundle maintenance obligations from initial construction contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged Bane NOR procurement officers, county road authority planning directors, civil engineering contractors, geohazard modeling consultants, and ready-mix supply chain managers. Secondary validation drew from Norwegian Public Roads Administration tender databases, Bane NOR capital investment disclosures, Ministry of Local Government and Regional Development planning documents, and Nordic construction trade association reports. Bottom-up project pipeline aggregation and top-down national transport budget allocation analysis were cross-referenced for triangulation.
Comparable historical investment cycles across the 2018-2023 reference period anchored projection modeling. Segmentation dimensions included project type, material specification grade, construction method maturity, and end-user procurement archetype. CAGRs were derived from multivariate regression against transport budget appropriations, population density corridor prioritization, and climate adaptation mandate implementation velocity. Industry-specific inputs incorporated electrification timeline commitments and subsea tunnel completion schedules.
Underlying measurement precision varies by segment; Oslo-Akershus corridor rail backlogs carry tighter precision than Troms and Finnmark white-space projections. Forecasts reflect assumptions about parliamentary funding continuity and aggregate supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
South Korea Infrastructure Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Bahrain Construction Market
Infrastructure Construction
Taiwan Data Center Construction Market
Infrastructure Construction
Ship Port Infrastructure Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Rebar Tier Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Belgium Data Center Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market