
 Latin America Data Center Construction Market | 2026-2036
Latin America Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Data Center Construction Market Foresight
Modular deployment is expanding buyer choice across Latin America as prefabricated power and cooling modules cut commissioning cycles. AECOM leverages its integrated design-build platform to capture hyperscale contracts across Brazil and Mexico. Jacobs Engineering sustains engineering leadership through thermal efficiency specialization in tropical climates. Turner Construction competes on speed-to-market delivery for cloud provider campuses in Querétaro and Campinas.
Data center construction encompasses the architectural, mechanical, electrical, and structural build-out of facilities engineered to maintain 99.999% uptime with power densities exceeding 30 kW per rack and N+1 redundancy across cooling systems. Hyperscale technology dominates capital allocation as cloud providers commission multi-hundred-megawatt campuses. Modular construction records the fastest uptake among technology segments due to supply chain predictability and phased capital deployment. New build construction type anchors volume as greenfield sites in Brazil and Mexico absorb the majority of regional investment.
ANATEL in Brazil, CRE in Mexico, and the Chilean Ministry of Energy shape market access through spectrum allocation, energy interconnection rules, and renewable power purchase requirements for critical infrastructure. These frameworks elevate compliance costs for entrants while favoring contractors with established local permitting expertise. Stakeholders must monitor regulatory divergence across Mercosur and Pacific Alliance jurisdictions when scaling cross-border delivery capabilities.
Market Dynamics
Hyperscale cloud providers are compressing commissioning timelines across Latin America, forcing contractors to adopt prefabricated power and cooling modules that slash traditional build cycles from 24 months to under 12 months.
Growth Catalysts
- ANATEL spectrum allocation:Brazil's national broadband plan accelerates fiber backbone deployment into São Paulo's metropolitan corridor, reducing latency for edge computing nodes.
- Querétaro satellite cluster expansion:Mexico's CRE streamlined energy interconnection rules enable 100MW+ campus developments without redundant environmental impact studies.
- Liquid cooling adoption:Tropical climate operators deploy immersion and direct-to-chip systems to sustain 40kW+ rack densities without mechanical refrigeration overload.
Market Restraints
- Copper and aluminum price volatility:Busbar and cabling materials constitute 18-22% of electrical infrastructure costs, exposing contractors to commodity hedge complexity.
- Chilean transmission bottlenecks:The Ministry of Energy's renewable PPA mandates outpace grid interconnection capacity in the Valparaíso and Biobío regions.
- Concrete supply concentration:Three producers control 70% of specialized low-alkali cement required for data center slab foundations across Mercosur jurisdictions.
Strategic Opportunities
- Colombia's underpenetrated Andean corridor:Bogotá and Medellín lack hyperscale presence despite submarine cable landings at Barranquilla.
- CRE renewable energy certificates:Mexico's clean energy credit trading creates arbitrage for contractors bundling solar PPAs with facility leases.
- Modular-mechanical convergence:Prefabricated electrical rooms integrate with factory-built chiller plants, enabling 30% faster phased capital deployment.
Industry Challenges
- Commissioning engineer scarcity:Brazil and Mexico each face deficits of 400+ certified Uptime Institute ATD professionals for Tier III+ facility validation.
- Legacy grid synchronization:Campinas and Querétaro developments require harmonic filtering investment to stabilize voltage for 99.999% SLA commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Data Center Construction Market |
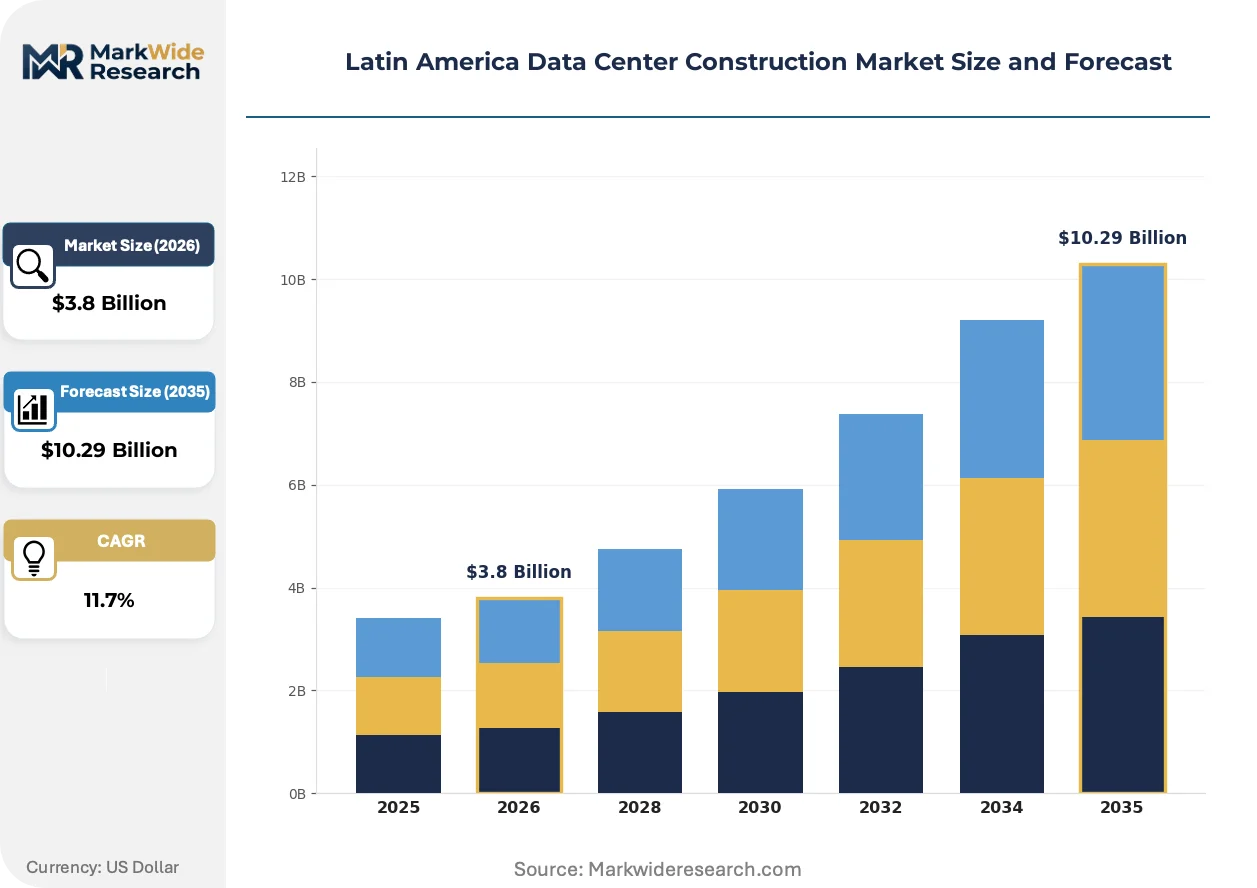
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Construction, Commissioning, Maintenance Technology: Hyperscale, Modular, Containerized, Micro Data Centers End User: Telecommunications, Cloud Service Providers, Enterprises, Government Construction Type: New Build, Expansion, Renovation, Retrofit |
| Companies Covered | AECOM, Aceco TI, Jacobs Engineering, Fluor Corporation, Zeittec, Turner Construction, Sener, DLR Group, Gensler, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Data Center Construction Market Shifts & Advancements
Prefabrication is rewiring competitive advantage across Latin American data center construction, compressing supplier selection criteria toward manufacturing precision and away from traditional field-craft reputation.
Prefabricated power modules integrate medium-voltage switchgear, UPS, and busbar distribution into weatherproof enclosures factory-tested before site delivery. Hyperscale operators in São Paulo and Querétaro specify these systems for 40% of new megawatt capacity. This technology is modularizing contractor capabilities, splitting the market between manufacturing-integrated firms and pure construction labor providers.
ANATEL's revised infrastructure sharing framework mandates open access to fiber ducts and tower structures for data center interconnection. The regulation forces incumbent carriers to publish standardized co-location pricing, reducing negotiation overhead for cloud providers expanding beyond São Paulo. Brazilian state-level environmental agencies are responding with accelerated licensing templates for facilities deploying liquid cooling to eliminate water consumption.
Cloud providers are consolidating procurement under master service agreements spanning design, construction, and 10-year operations. Traditional general contractors lose direct relationships as hyperscalers pre-qualify integrated design-build entities. This concentration is most visible in Mexico, where three operators account for 85% of Querétaro's 2024-2026 pipeline, forcing mid-tier contractors into subcontractor roles or regional secondary markets.
Latin America Data Center Construction Market Segmentation
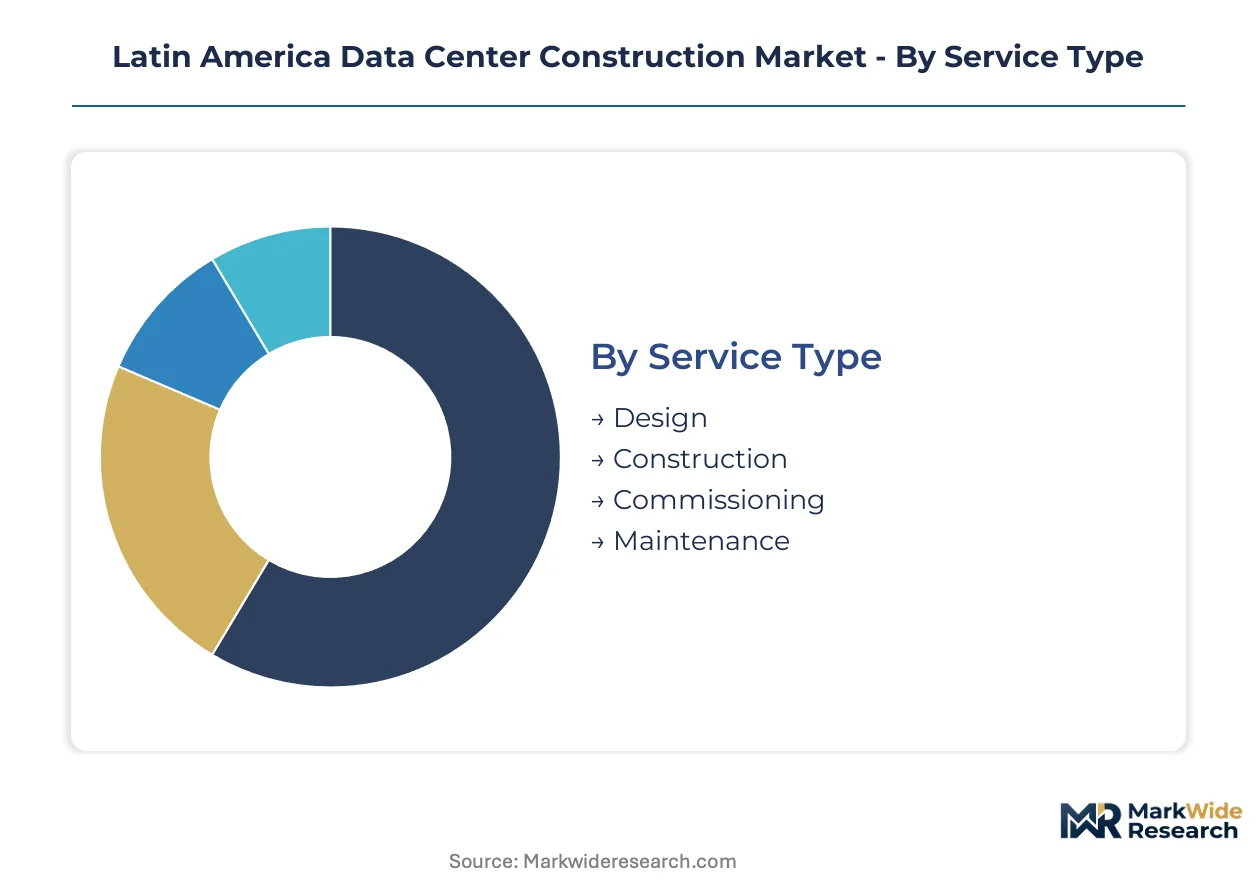
Construction segmentation in Latin America reveals divergent capital deployment patterns across project phases and facility scales. Service type and technology choices determine whether contractors capture multi-year hyperscale campus contracts or smaller enterprise retrofit engagements.
Service Type:
Capital intensity peaks in full-cycle engagements spanning design through commissioning, where contractors assume performance risk across 24-to-36-month timelines.
- Design:Architectural and engineering schematics establish power density specifications, cooling topology, and structural load calculations for tropical seismic zones. Brazilian ANATEL infrastructure sharing mandates force design-phase fiber interconnection planning into every São Paulo metro facility.
- Construction:Physical build-out of electrical, mechanical, and structural systems consumes 60-70% of total project capital in greenfield developments. Mexican CRE streamlined interconnection rules compress construction mobilization timelines for Querétaro satellite cluster projects.
- Commissioning:Integrated systems testing validates Tier III+ uptime guarantees through load bank testing and failover simulation protocols.
- Maintenance:Post-handover service contracts cover predictive thermal monitoring and UPS battery replacement cycles.
Most installed capacity flows through Construction. Expansion is steepest in Commissioning as hyperscale operators outsource Uptime Institute ATD certification.
Technology:
Facility scale determines whether projects deploy traditional stick-built methods or factory-integrated modules shipped to site.
- Hyperscale:Multi-hundred-megawatt campuses require custom electrical rooms and centralized chiller plants engineered for 40kW+ rack densities. Cloud providers in São Paulo and Querétaro specify hyperscale configurations for 85% of new regional capacity.
- Modular:Prefabricated power and cooling modules cut commissioning cycles from 24 months to under 12 months through factory testing and phased capital deployment. This technology gains fastest uptake among operators prioritizing supply chain predictability over customization.
- Containerized:ISO-standard enclosures deploy edge computing nodes in secondary cities lacking permanent facility infrastructure.
- Micro Data Centers:Sub-500kW self-contained units serve latency-sensitive applications in Colombia's underpenetrated Andean corridor.
Hyperscale deployments absorb the largest capital allocations. Modular construction climbs the fastest as procurement patterns shift toward manufacturing-integrated delivery.
End User:
Customer type dictates redundancy requirements, with telecommunications and cloud providers demanding 99.999% uptime guarantees that enterprises rarely specify.
- Telecommunications:Carrier-neutral facilities require diverse fiber entry points and cross-connect architectures supporting multi-tenant interconnection. ANATEL's revised infrastructure sharing framework accelerates Brazilian telecom data center deployment.
- Cloud Service Providers:Hyperscale operators consolidate procurement under decade-spanning master service agreements covering design, construction, and operations. Three operators account for 85% of Querétaro's pipeline through 2026.
- Enterprises:Private facilities for financial services and manufacturing prioritize physical security over extreme power density.
- Government:Sovereign cloud mandates in Brazil and Mexico drive classified facility construction with domestic labor requirements.
Cloud service providers command the largest project scales. Government is gaining share fastest as digital sovereignty policies proliferate.
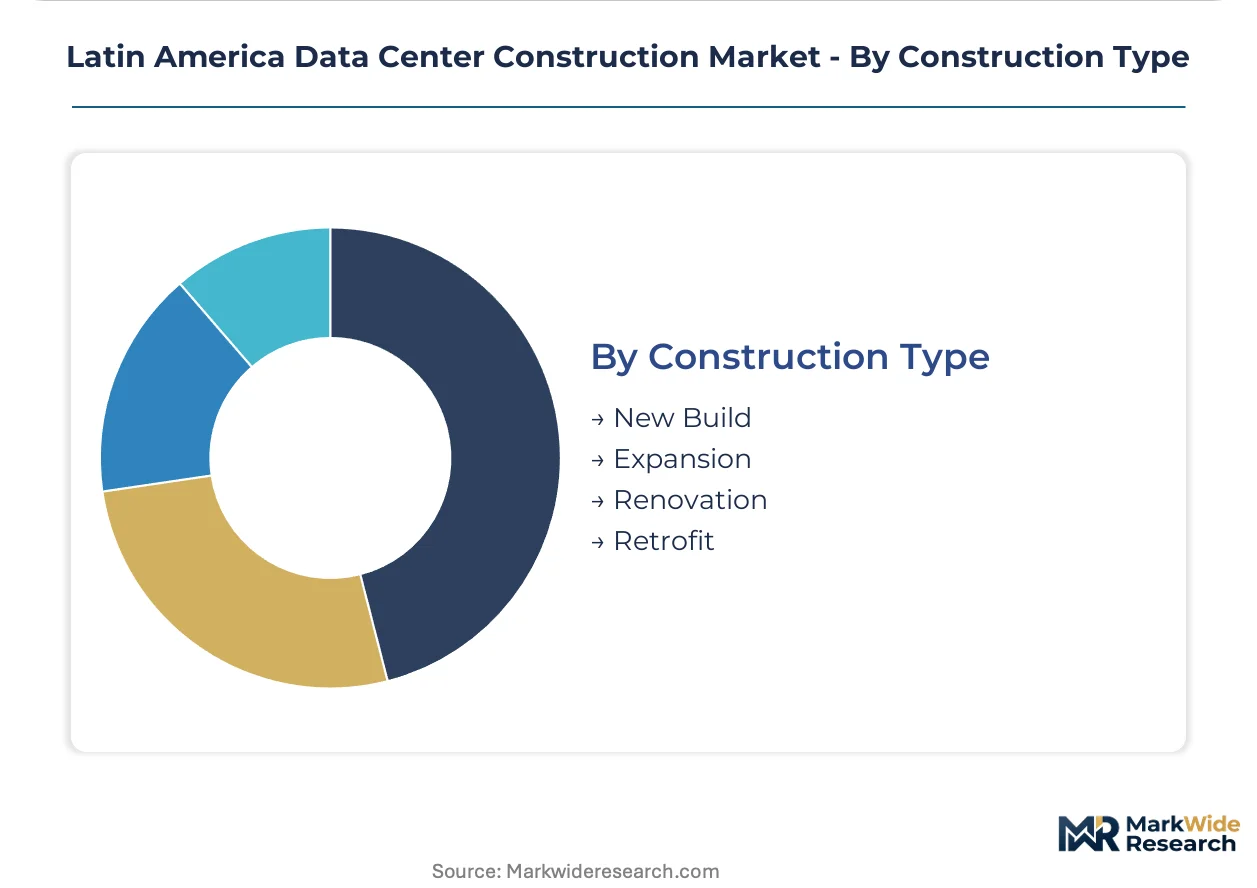
Construction Type:
Project origin—greenfield versus existing facility—determines permitting complexity and material procurement strategies.
- New Build:Greenfield developments on raw land absorb the majority of regional investment, particularly in Brazil's Campinas corridor and Mexico's Querétaro satellite cluster. Full design freedom enables liquid cooling integration from foundation phase.
- Expansion:Campus additions leverage existing substations and fiber backbones while adding megawatt-scale capacity. Phased expansion allows operators to match supply with actual cloud demand rather than speculative overbuild.
- Renovation:Structural upgrades to legacy facilities address seismic deficiencies and floor loading limitations for high-density racks.
- Retrofit:Cooling system replacements in aging São Paulo facilities convert air-cooled designs to liquid immersion for 30kW+ densities.
New build dominates capital deployment. Retrofit activity is expanding most quickly as aging facilities face power density obsolescence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center construction in Latin America traces its industrial lineage to Brazil's telecommunications privatization wave of the late 1990s, when carrier-neutral facilities first established the region's fiber interconnection architecture. Mexico's maquiladora-era industrial parks later adapted their utility-scale power infrastructure to attract hyperscale cloud campuses. These foundational developments now anchor a construction market spanning diverse regulatory environments and climate zones.
Brazil
Cloud service providers dominate capital deployment across the Brazilian market, with hyperscale operators commissioning multi-hundred-megawatt campuses in São Paulo's metropolitan fiber corridor. ANATEL's spectrum allocation policies and revised infrastructure sharing framework mandate open access to fiber ducts, accelerating interconnection buildouts. Campinas anchors the highest concentration of greenfield development, where contractors deploy liquid cooling systems to sustain 40kW+ rack densities in tropical conditions.
Mexico
Streamlined energy interconnection rules from CRE enable rapid campus scaling without redundant environmental impact studies for facilities exceeding 100MW. The Querétaro satellite cluster absorbs the majority of regional investment as three cloud operators consolidate procurement under decade-spanning master service agreements. Factory-built chiller plants integrate with prefabricated electrical rooms across this corridor, compressing commissioning timelines below 12 months.
Chile
Renewable power purchase requirements from the Ministry of Energy shape facility economics, though transmission bottlenecks in Valparaíso and Biobío regions constrain interconnection capacity. Santiago's data center pipeline faces commissioning engineer scarcity, with deficits exceeding 400 certified Uptime Institute ATD professionals for Tier III+ validation. Northern mining corridor cities attract edge computing nodes serving resource extraction operations.
Colombia
Bogotá and Medellín remain underpenetrated by hyperscale presence despite submarine cable landings at Barranquilla connecting to global backbone networks. The Andean corridor's elevation provides natural cooling advantages for high-density rack deployments absent in coastal markets. National broadband expansion programs are extending fiber infrastructure into secondary cities, creating phased entry opportunities for modular facility deployment.
Argentina
Buenos Aires concentrates enterprise facility investment, with financial services operators prioritizing physical security and seismic resilience in facility specifications. Currency volatility and import restrictions complicate equipment procurement for international contractors, elevating the role of locally integrated design-build entities. Mendoza's renewable energy zone offers power cost arbitrage for operators willing to locate outside the primary metropolitan market.
Latin America Data Center Construction Market Competitive Landscape
Premium-margin players sit above commodity-margin players across design-build integration depth, with full-cycle service providers capturing multi-year hyperscale campus contracts while pure construction labor providers compete for subcontractor roles. The market structure concentrates around three strategic archetypes: integrated engineering-construction platforms, specialized thermal efficiency consultants, and speed-to-market delivery specialists. Dominant competitive moves include geographic expansion into underpenetrated Andean corridors and backward integration into prefabricated module manufacturing.
Within the integrated platform tier, AECOM and Jacobs Engineering exemplify engineering-led construction entities with established local permitting expertise across Brazilian and Mexican jurisdictions. Turner Construction occupies a position among speed-to-market specialists competing for cloud provider campuses in Querétaro and Campinas. These three anchors represent divergent capability configurations: AECOM leverages its design-build platform for hyperscale contracts, Jacobs sustains leadership through tropical climate thermal specialization, and Turner competes on compressed delivery timelines for multi-megawatt developments.
| Leading Market Players |
|---|
| AECOM |
| Aceco TI |
| Jacobs Engineering |
| Fluor Corporation |
| Zeittec |
| Turner Construction |
| Sener |
| DLR Group |
| Gensler |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up engineering specialists in Brazil and Mexico exercise pricing discipline through captive relationships with hyperscale cloud providers, compressing procurement cycles while locking in multi-year master service agreements that insulate margins from commodity volatility.
Pricing Analysis
Project-based contracting with performance guarantees anchors pricing across Latin American data center construction. Price differentiation separates Tier III+ certified facilities with Uptime Institute validation from uncertified builds and retrofits. Cost compression in electrical infrastructure runs through copper and aluminum price exposure, with contractors hedging commodity risk through long-term supply agreements. Cloud service providers demonstrate lowest price sensitivity due to uptime SLA requirements, while enterprise retrofits face acute budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for prefabricated power modules and factory-built chiller plants. Manufacturing concentrates in China, Germany, and the United States for medium-voltage switchgear and precision cooling equipment. Raw material dependencies center on copper busbar, low-alkali cement, and aluminum cabling. Single-source vulnerability in specialized electrical components creates supply chain risk, particularly for Brazilian contractors facing import lead time variability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America data center construction market functions as a stable compounder, with cloud provider capex commitments providing revenue visibility across multi-year project pipelines.
For Market Incumbents: Acquire prefabricated module manufacturing capabilities to defend against pure-construction labor commoditization. Integrate backward into electrical room fabrication to capture margin currently flowing to German and Chinese OEMs. ANATEL's accelerated licensing templates for liquid cooling facilities create first-mover advantage for contractors with established Brazilian environmental permitting expertise. For New Entrants and Emerging Players: Colombia's government and enterprise segments remain underserved by integrated design-build platforms despite Barranquilla's submarine cable connectivity. Bogotá's elevation advantages for natural cooling and Medellín's fiber expansion create phased entry opportunities through modular micro-data center deployment. Lead with commissioning and ATD certification services to bypass capital-intensive construction barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Brazilian contractors lacking hyperscale master service agreements but holding ANATEL relationship infrastructure. Long-term viability hinges on CRE and ANATEL regulatory alignment sustaining cross-border project scalability. Watch for Chilean Ministry of Energy transmission bottleneck resolution as inflection signal for Santiago market activation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prefabricated Module Manufacturing | Captures 30% faster commissioning premiums currently paid to German OEMs. |
| Master Service Agreement Consolidation | Locks decade-spanning cloud provider relationships across Querétaro and Campinas corridors. |
| Liquid Cooling Certification Investment | Qualifies contractors for ANATEL's accelerated environmental licensing templates. |
| Andean Corridor Geographic Expansion | Positions builders for Colombia's national broadband fiber buildout into secondary cities. |
| Uptime Institute ATD Capability Acquisition | Addresses 400+ professional deficit constraining Tier III+ validation in Brazil and Mexico. |
Research Methodology
Bottom-up hyperscale and enterprise modeling reconciled against top-down contractor pipeline tracking forms the analytical core. Primary interviews with data center development executives, EPC project managers, ANATEL regulatory affairs leads, CRE interconnection specialists, and Uptime Institute commissioning engineers combined with secondary validation from SEC hyperscaler capex disclosures, ANATEL infrastructure reports, CRE energy interconnection filings, and Brazilian environmental licensing databases. Triangulation across these sources ensures demand-side project data aligns with supply-side capacity announcements.
Input-output matrices map construction spend across service type, technology tier, and end-user segment throughout the forecast period. Segmentation dimensions include facility scale, cooling topology, certification level, and regional regulatory cluster. CAGRs derive from project pipeline velocity analysis and capital deployment tracking. Forecast inputs incorporate ANATEL spectrum allocation timelines and CRE renewable energy certificate trading mechanics.
Underlying measurement precision varies by segment; hyperscale cloud provider contracts carry tighter precision than government sovereign cloud estimates. Forecasts reflect assumptions around regulatory continuity across Mercosur and Pacific Alliance jurisdictions. Commodity price volatility, transmission interconnection delays, and commissioning engineer scarcity represent primary revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
France Transportation Infrastructure Construction Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Rebar Tier Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
Global Transportation Infrastructure Market
Infrastructure Construction
Finland Transportation Infrastructure Construction Market