
 Heavy Movable Bridges Market | 2026-2036
Heavy Movable Bridges Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Movable Bridges Market Analysis
Municipalities are gaining procurement share as transportation departments is bifurcating between centralized state programs and localized urban renewal. Parsons Corporation leverages its engineering scale across North American port corridors. COWI anchors Nordic and North Sea bridge expertise through specialized marine infrastructure teams. Canadian National Railway Company sustains captive demand via railway bridge replacement cycles across its continental network.
Heavy movable bridges are engineered structures with rotating, lifting, or swinging decks that open to permit waterway traffic, typically fabricated from high-strength steel with counterweight systems rated for dynamic load cycles exceeding 100,000 operations. Their primary purpose is maintaining multimodal connectivity across navigable rivers, harbors, and industrial canals without permanent elevation. Bascule bridges occupy the dominant share due to proven reliability in highway and railway applications where rapid opening cycles matter. Steel construction leads material selection for load-bearing spans, though composite materials are gaining traction in corrosion-sensitive coastal environments. Port applications represent the fastest-growing segment as container shipping volumes drive channel widening projects requiring wider clearances.
The Federal Highway Administration mandates National Bridge Inspection Standards that dictate load rating frequency and rehabilitation triggers for structures on public roads. The European Committee for Standardization enforces EN 1993 and EN 1994 codes governing steel and composite bridge design, while the International Association of Bridge and Structural Engineers provides seismic and wind load guidance adopted across multiple jurisdictions. Japan's Ministry of Land, Infrastructure, Transport and Tourism maintains stringent earthquake-resistant specifications for movable bridges in seismically active zones. Stakeholders must monitor evolving climate resilience standards and determine whether to prioritize adaptive retrofit of existing structures or greenfield installations with integrated smart monitoring systems.
Market Dynamics
Federal bridge safety mandates are tightening inspection intervals and rehabilitation triggers across aging infrastructure portfolios, forcing transportation departments into accelerated replacement cycles.
Growth Catalysts
- Federal Highway Administration mandates:National Bridge Inspection Standards require load rating frequency increases for structures on public roads, driving systematic replacement demand.
- Port channel widening projects:Container shipping volumes in coastal cities necessitate wider clearances and modernized bascule systems.
- Composite material adoption:Fiber-reinforced polymers are displacing conventional steel in corrosion-sensitive marine environments, extending operational lifespans.
Market Restraints
- High-strength steel price volatility:Specialized alloy supply concentrates in limited production geographies, exposing project budgets to input cost swings.
- Seismic engineering complexity:Japan's Ministry of Land, Infrastructure, Transport and Tourism specifications for earthquake-resistant movable bridges impose design constraints that limit supplier pools.
- Fixed bridge substitution:Permanent elevation structures compete for crossings where navigational clearance permits, squeezing addressable project scope.
Strategic Opportunities
- Smart monitoring integration:Sensor networks and predictive maintenance platforms create white space for technology convergence between structural engineering and industrial IoT.
- Railway bridge replacement cycles:Continental freight networks require systematic renewal of aging lift and swing spans, generating captive demand streams.
- European transport resilience directives:EU infrastructure hardening mandates prioritize adaptive retrofit or greenfield installations with climate resilience specifications.
Industry Challenges
- Specialized welding certification timelines:Complex steel fabrication for dynamic load cycles requires extended qualification periods for skilled trades.
- Counterweight system integration complexity:Legacy mechanical systems resist seamless retrofit with modern automated controls, complicating upgrade pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Movable Bridges Market |
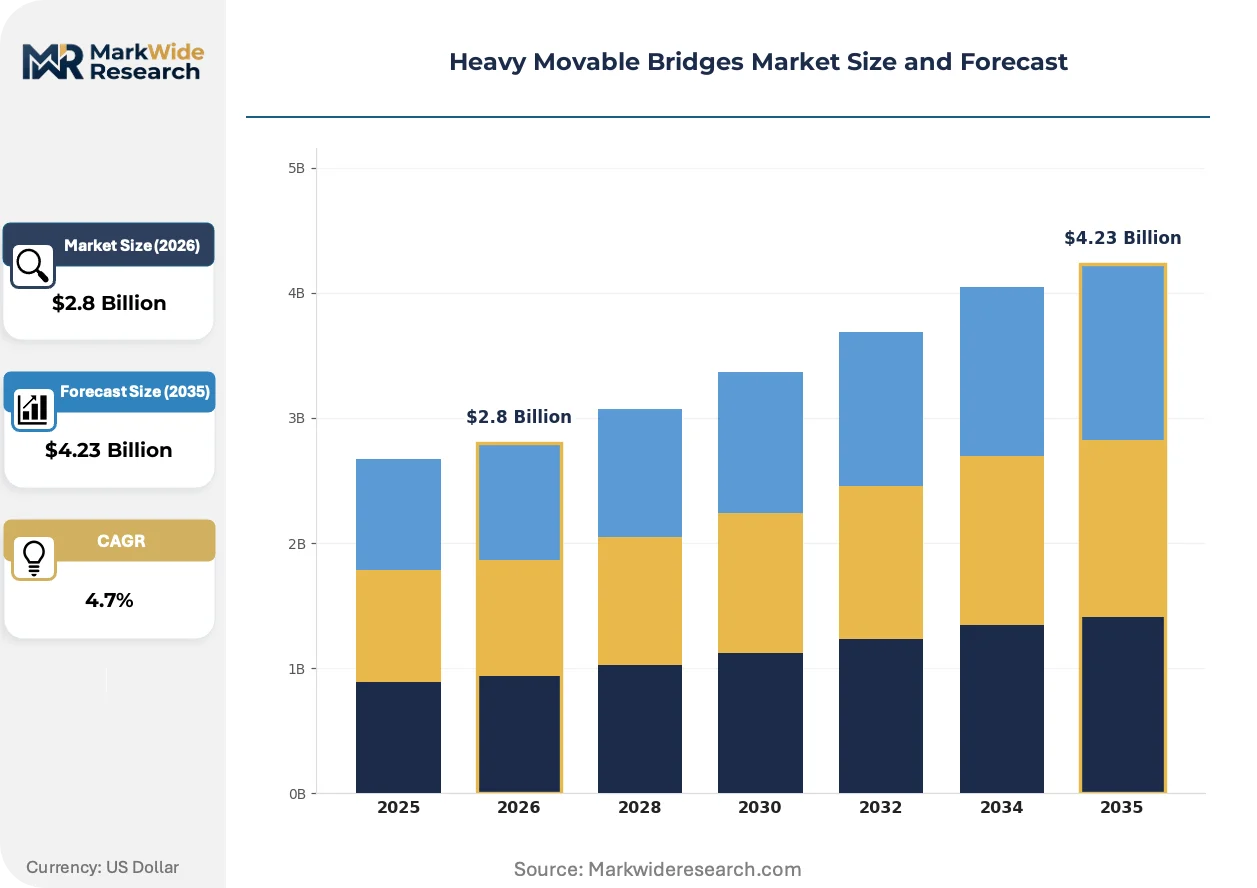
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bridge Type: Bascule, Lift, Swing, Folding Material: Steel, Aluminum, Composite, Concrete End User: Transportation Departments, Municipalities, Private Contractors, Engineering Firms Application: Highways, Railways, Ports, Industrial Sites |
| Companies Covered | Canadian National Railway Company, Parsons Corporation, Amtrak, COWI, Modjeski and Masters, CSX Corporation, BNSF Railway Company, SYSTRA, Canadian Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Movable Bridges Market Emerging Trajectories
Digitalization of structural health monitoring is compressing maintenance cycles and enabling predictive intervention models across port and rail corridors.
Embedded fiber-optic strain sensors are miniaturizing structural monitoring capabilities for heavy movable bridges. Port authorities in Germany and Japan are deploying these systems on bascule spans to track fatigue accumulation in real time. The technology is miniaturizing inspection labor requirements while extending safe operational intervals between physical assessments.
The European Committee for Standardization is enforcing EN 1993 and EN 1994 codes governing steel and composite bridge design with heightened climate resilience appendices. Industrial fabricators must now certify spans against intensified wind and thermal load scenarios. Coastal installations in the North Sea corridor face the steepest compliance ramps, accelerating design methodology turnover.
Transportation departments are consolidating procurement authority through centralized state programs while bifurcating localized urban renewal to municipal agencies. Engineering firms are reconfiguring service models to serve dual client tiers with differentiated technical support. This pattern concentrates most visibly across United States port cities where federal, state, and municipal funding streams intersect.
Heavy Movable Bridges Market Segmentation
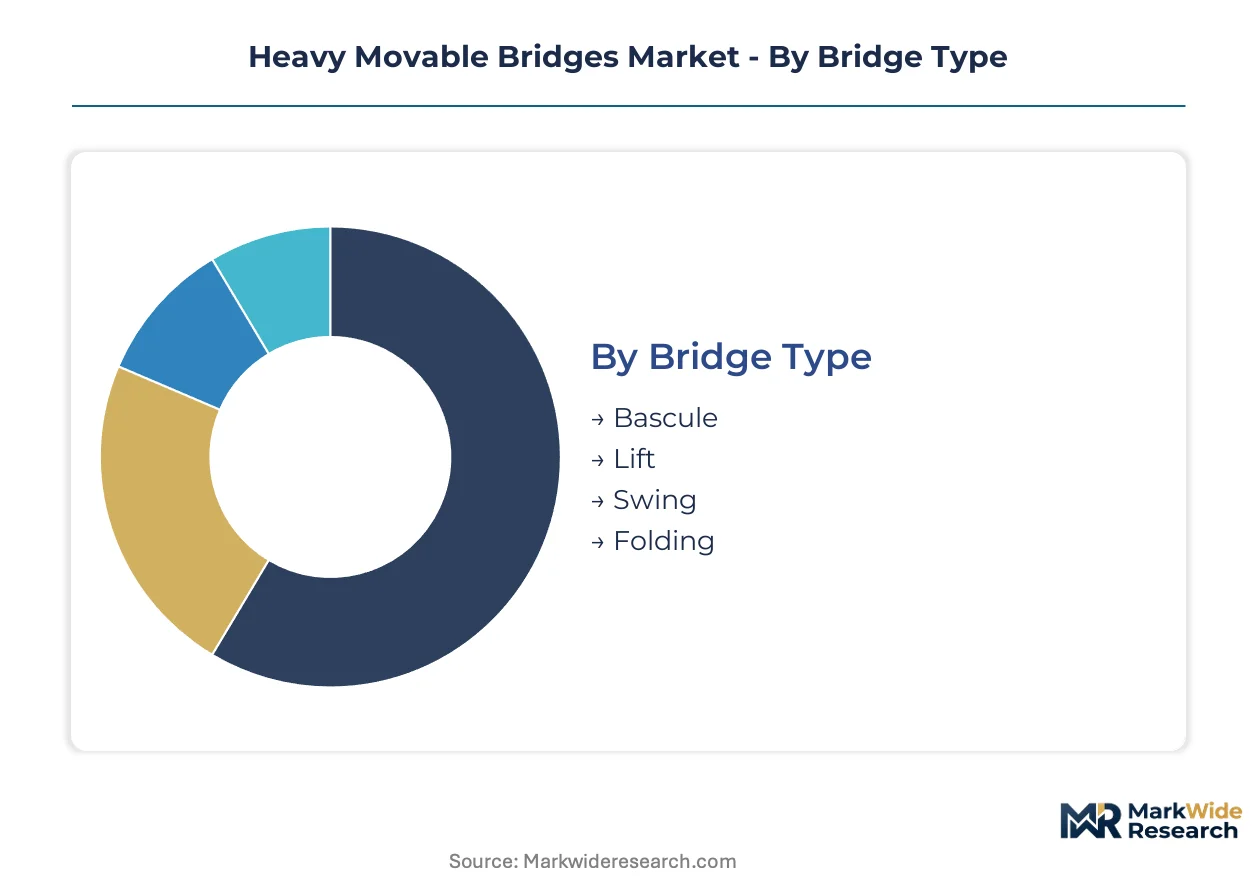
Heavy movable bridge procurement concentrates around four structural dimensions that determine engineering specifications, compliance pathways, and lifecycle economics. Bridge type and material selection drive capital intensity and maintenance burden, while end-user category and application context shape funding mechanisms and regulatory oversight.
Bridge Type:
Highest margin capture sits with designs requiring precision counterweight engineering and rapid cycling capability for high-traffic corridors.
- Bascule:Rotating leaf spans pivot on horizontal trunnions with concrete or steel counterweights balancing deck loads. Demand clusters in United States port cities where Federal Highway Administration mandates govern highway-rail intersections with frequent maritime openings.
- Lift:Vertical towers raise horizontal decks through cable-hoist or rack-and-pinion systems. German North Sea ports and Japanese industrial canals specify these for wide navigation channels where bascule leaf length becomes impractical.
- Swing:Center-bearing or rim-bearing turntables rotate entire spans perpendicular to waterways. Legacy installations across Great Lakes shipping corridors sustain replacement demand.
- Folding:Multiple hinged sections stack vertically during opening cycles. Niche deployments in constrained European urban waterways where horizontal clearance is unavailable.
The dominant share belongs to Bascule, while Lift is closing the gap fastest in coastal port modernization programs.
Material:
Cost tier stratification separates premium corrosion-resistant alloys from commodity structural grades, with lifecycle accounting shifting procurement calculus toward higher upfront specifications.
- Steel:High-strength low-alloy grades dominate load-bearing spans with yield strengths exceeding 345 MPa. Japanese seismic specifications and EN 1993 compliance requirements in European Union member states sustain premium alloy demand despite price volatility.
- Composite:Fiber-reinforced polymer decks and hybrid systems displace conventional steel in salt-air environments. German coastal authorities specify glass-fiber reinforced composites for bascule approaches where cathodic protection costs exceed material premiums.
- Aluminum:Lightweight extrusions serve pedestrian and light-vehicle spans with reduced counterweight requirements. Limited adoption in heavy highway and rail applications due to fatigue performance constraints.
- Concrete:Prestressed deck segments anchor counterweight masses and provide ballast stability. Standard in vertical lift towers and swing bridge piers where mass concentration benefits structural dynamics.
Steel retains volume leadership across all major procurement channels, though Composite is expanding most quickly in marine corrosion applications.
End User:
Customer type fragmentation creates divergent contracting models, with centralized state programs favoring design-build consortia and municipal agencies prioritizing localized maintenance integration.
- Transportation Departments:State and federal agencies administer interstate highway and primary rail corridor crossings with standardized procurement protocols. United States Department of Transportation funding mechanisms concentrate authority in centralized programs.
- Municipalities:Urban renewal authorities manage secondary road and pedestrian bridges with localized budget autonomy. Port cities across Germany and Japan bifurcate procurement between state trunk lines and harbor district infrastructure.
- Private Contractors:Design-build firms and concession operators deliver bundled construction-maintenance contracts. Growing presence in European public-private partnership structures for greenfield installations.
- Engineering Firms:Technical consultancies provide owner-engineer services and independent verification. Specialized marine infrastructure teams anchor project delivery in Nordic and North Sea markets.
Transportation Departments command the largest project pipeline, while Municipalities are gaining procurement share through harbor district autonomy.
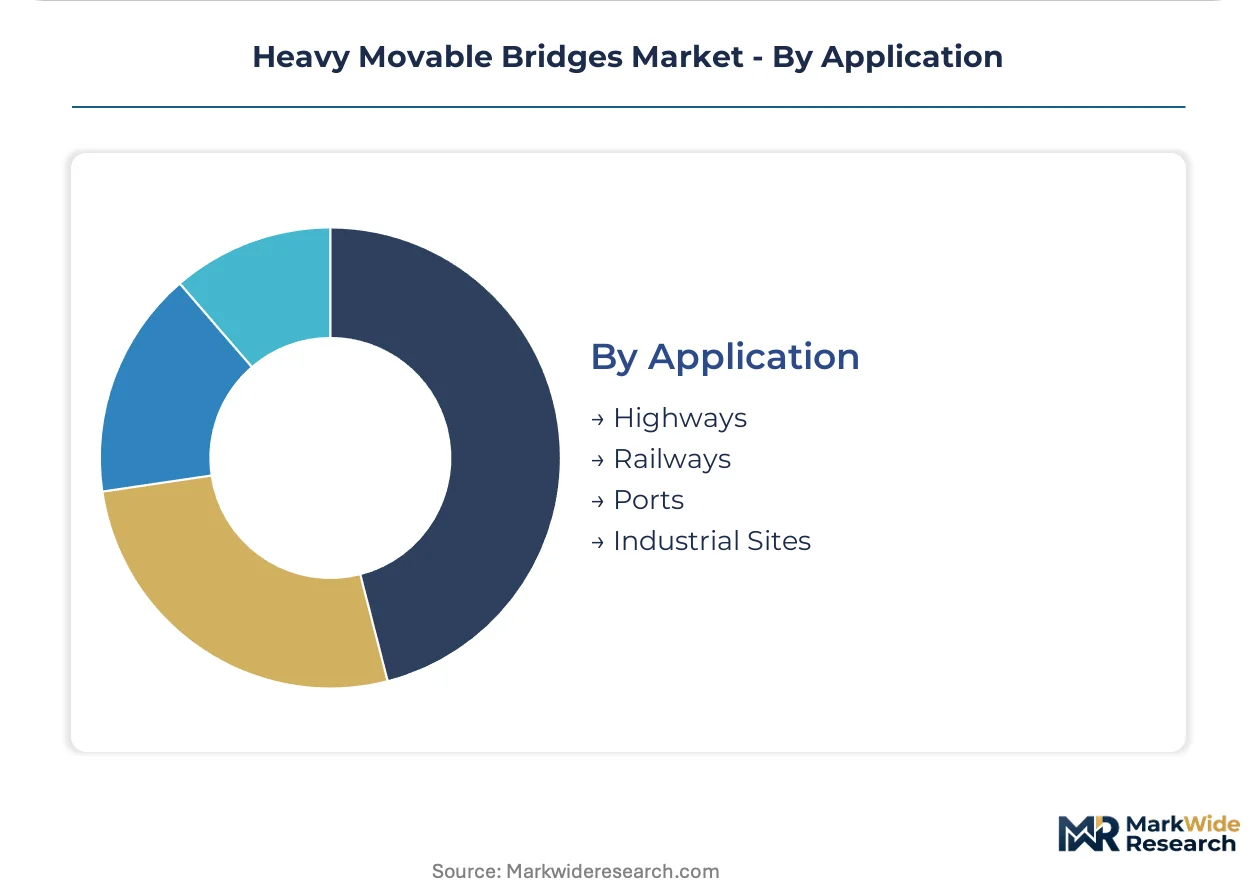
Application:
Application context determines load rating standards, cycling frequency requirements, and integration complexity with existing transport networks.
- Ports:Container shipping terminals demand widest clearances and fastest opening cycles for post-Panamax vessel access. Channel widening projects across United States Gulf Coast and Japanese industrial harbors drive specification escalation.
- Railways:Continental freight networks require systematic renewal of aging lift spans with continuous welded rail compatibility. Canadian and Japanese trunk lines sustain captive replacement cycles.
- Highways:State road departments balance vehicular capacity against maritime traffic volumes. Federal inspection mandates accelerate rehabilitation triggers for structures on public roads.
- Industrial Sites:Private manufacturing and energy facilities maintain internal canal crossings with specialized load requirements. Chemical processing and power generation complexes specify explosion-resistant control systems.
Highways retain installed base dominance, though Ports exhibit the steepest expansion trajectory from container volume growth and channel deepening investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering firms export bascule and lift bridge systems to port authorities across the United States and Japan, where federal infrastructure mandates and seismic resilience codes drive replacement cycles.
United States
Container shipping volumes through Gulf Coast and Atlantic port cities necessitate wider navigation clearances and modernized counterweight systems. The Federal Highway Administration enforces National Bridge Inspection Standards that accelerate rehabilitation triggers for structures on public roads. Houston and New Orleans harbor districts concentrate procurement activity around channel deepening projects.
Germany
North Sea port modernization and industrial canal upgrades sustain demand for vertical lift systems with rapid cycling capability. The European Committee for Standardization enforces EN 1993 and EN 1994 codes with heightened climate resilience appendices for steel and composite bridge design. Hamburg and Bremen anchor fabrication clusters serving Baltic and North Sea shipping corridors.
Japan
Seismically active zones require earthquake-resistant movable bridge specifications for railway and highway crossings over industrial waterways. The Ministry of Land, Infrastructure, Transport and Tourism maintains stringent seismic load criteria that limit qualified supplier pools. Osaka and Nagoya industrial harbors drive specification escalation for post-Panamax vessel clearances.
Canada
Continental freight networks require systematic renewal of aging lift spans across prairie and Great Lakes rail corridors. Transport Canada coordinates with provincial transportation departments on bridge safety protocols for structures on national highway systems. Toronto and Vancouver port authorities bifurcate procurement between federal trunk lines and harbor district infrastructure.
Heavy Movable Bridges Market Vendor Landscape
Player mix skews toward engineering-led diversified infrastructure conglomerates with captive railway operators and specialized marine fabrication boutiques. Market structure concentrates around firms with proven counterweight system integration and seismic certification capabilities. Two strategic archetypes dominate: integrated engineering-construction consortia delivering design-build-maintain bundles, and captive railway infrastructure divisions with continental replacement pipelines. Competitive moves center on strategic partnerships for smart monitoring technology convergence and geographic expansion into coastal port modernization programs.
Among North American engineering conglomerates, Parsons Corporation exemplifies the integrated design-build archetype with cross-border project delivery capabilities. Canadian National Railway Company and BNSF Railway Company occupy positions within the captive infrastructure tier, sustaining predictable demand streams through systematic bridge replacement cycles across continental networks. COWI anchors the specialized marine fabrication vector with concentrated expertise in Nordic and North Sea environments.
| Leading Market Players |
|---|
| Canadian National Railway Company |
| Parsons Corporation |
| Amtrak |
| COWI |
| Modjeski and Masters |
| CSX Corporation |
| BNSF Railway Company |
| SYSTRA |
| Canadian Pacific |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Japanese fabrication yards concentrates supply-side leverage among engineering conglomerates with integrated steel procurement, compressing price floors for mid-tier competitors while elevating premiums for seismic-certified and smart-monitoring-integrated systems.
Pricing Analysis
Next-generation smart-monitoring bascule systems command 40-60% premiums over prior-generation mechanically operated spans, while economy-tier swing bridge retrofits face margin compression from standardized component sourcing. Pricing stratifies across premium certified systems, standard highway-grade installations, and economy municipal retrofits, with differentiation anchored in seismic compliance tier and sensor integration depth. Cost compression in economy-tier steel fabrication is intensifying because Chinese mill overcapacity floods commodity structural grades. Municipal harbor authorities exhibit highest price sensitivity due to localized budget constraints, while state transportation departments with federal funding access show lowest sensitivity.
Supply Chain Analysis
Inbound logistics costs from Korean and Taiwanese high-strength alloy mills through congested Pacific gateways elevate landed costs for North American fabricators by 12-18% versus European sourcing. Supply concentrates in Germany, Japan, and the United States for precision counterweight engineering, while China dominates commodity structural steel. Raw material dependencies center on nickel-bearing high-strength alloys, fiber-reinforced polymer composites, and specialized bearing assemblies. Single-source vulnerability from limited qualified seismic welding certification pools in Japan constrains capacity expansion. Distribution runs through design-build consortia delivering bundled engineering-fabrication-installation contracts to port authorities and railway operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heavy movable bridge procurement sits in early-cycle expansion as federal infrastructure mandates and port channel widening projects accelerate replacement timelines beyond historical maintenance rhythms.
For Market Incumbents: Consolidate engineering-fabrication integration through captive counterweight system production in Germany and Japan, insulating margin structures from high-strength steel price volatility. Acquire specialized marine infrastructure boutiques in Nordic markets to defend against COWI's geographic concentration. Prioritize seismic certification investment to maintain qualified supplier status under Japan's Ministry of Land, Infrastructure, Transport and Tourism specifications.
For New Entrants and Emerging Players: Anchor in smart monitoring technology convergence as the most penetrable white space, where industrial IoT sensor networks and predictive maintenance platforms lack established structural engineering incumbents. Target German North Sea port authorities with climate-resilience-compliant composite bascule designs. Pursue design-build-maintain concession structures in European public-private partnership frameworks as the primary go-to-market pathway.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering-led diversified infrastructure conglomerates with captive railway replacement pipelines over pure-play fabrication boutiques. Five-to-ten-year viability hinges on counterweight system integration expertise and seismic certification depth rather than commodity steel capacity. Monitor container shipping volume trajectories through Gulf Coast and Japanese industrial harbors as the critical inflection signal for specification escalation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Monitoring Platform Integration | Sensor networks from industrial IoT specialists compress maintenance cycles for German port authorities. |
| Seismic Certification Investment | Japan's Ministry of Land, Infrastructure, Transport and Tourism specifications limit qualified supplier pools. |
| Composite Material Scale-Up | Fiber-reinforced polymer production capacity addresses corrosion-sensitive North Sea coastal installations. |
| Design-Build-Maintain Concession Expansion | European public-private partnership structures bundle construction and lifecycle service revenue streams. |
| Railway Replacement Pipeline Capture | Canadian and Japanese trunk line renewal cycles generate predictable captive demand for lift spans. |
Methodological Framework
A standing panel of bridge engineering directors, port authority procurement managers, railway infrastructure planners, and marine fabrication specialists provided ongoing calibration across the research cycle. Primary interviews with state transportation department officials and municipal harbor district engineers combined with secondary validation from Federal Highway Administration bridge inventory databases, EN 1993/1994 code documentation, and Japanese Ministry of Land, Infrastructure, Transport and Tourism technical circulars. Bottom-up project pipeline enumeration triangulated against top-down infrastructure spending forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled bridge type, material grade, end-user category, and application context as core segmentation dimensions, with regional regulatory cluster and seismic compliance tier as industry-specific overlays. CAGRs were derived from replacement cycle velocity analysis and infrastructure spending elasticity to container shipping growth. Forecast inputs incorporated Federal Highway Administration inspection mandate compliance timelines and European Committee for Standardization climate resilience appendix adoption curves.
Material uncertainties — steel alloy price volatility, seismic code revision timelines, and container shipping demand cyclicality — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding infrastructure funding continuity and regulatory enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
New Zealand Infrastructure Market