
 Global Robotic Rehabilitation and Assistive Technologies Market | 2026-2036
Global Robotic Rehabilitation and Assistive Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Robotic Rehabilitation and Assistive Technologies Market Foresight
Japanese electromechanical actuator suppliers is decoupling from legacy hydraulic architectures, enabling lighter exoskeleton platforms. ReWalk Robotics Ltd. leverages its FDA-cleared portfolio to anchor presence in spinal cord injury rehabilitation across United States clinical networks. Ekso Bionics Holdings, Inc. competes through specialized gait-training systems deployed in Veterans Affairs facilities. CYBERDYNE Inc. dominates the Japanese home-care segment with its HAL hybrid assistive limb technology.
Robotic rehabilitation and assistive technologies integrate electromechanical frameworks with wearable sensor arrays and AI-driven control algorithms to restore, augment, or substitute human motor function following neurological or orthopedic impairment. These systems operate through real-time motion capture and haptic feedback loops that translate patient intent into mechanical assistance, primarily serving stroke recovery, spinal cord injury, and neurodegenerative disorder populations in clinical and home settings. Exoskeleton devices command the largest installed base among product categories, reflecting mature reimbursement codes in North American and European rehabilitation facilities. AI-driven technology segments are expanding fastest as machine learning algorithms enable adaptive resistance protocols that reduce therapist supervision burden. Therapeutic robots capture concentrated margin pools where software subscription models overlay hardware placements in specialized clinics.
FDA 510(k) pathways and EU MDR conformity assessments govern market access for electromechanical rehabilitation devices, while Japan's PMDA reviews therapeutic claims for neurorehabilitation systems under pharmaceutical-adjacent frameworks. ISO 13485 quality management and IEC 60601 electrical safety standards constrain design architectures and extend validation timelines for new entrants. Stakeholders must monitor evolving reimbursement decisions by CMS and parallel agencies across Germany and Japan, as coverage determinations for home-use exoskeletons will reshape addressable population calculations and channel economics without reference to specific calendar milestones.
Market Dynamics
Electromechanical actuator miniaturization is compressing exoskeleton form factors while expanding deployable settings from inpatient wards to outpatient clinics and home environments. This hardware evolution intersects with reimbursement code expansion to reshape addressable patient populations.
Growth Catalysts
- EU MDR pathway streamlining:Conformity assessment templates for active implantable medical devices are reducing technical documentation burden for therapeutic robot manufacturers seeking CE marking.
- Stroke rehabilitation protocols:Neurological recovery programs in United States inpatient rehabilitation facilities are embedding robotic gait trainers into standardized care pathways.
- Japan's PMDA neurorehabilitation framework:Pharmaceutical-adjacent review structures for hybrid assistive limb systems are accelerating clinical evidence requirements for home-use authorization.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing capacity clusters in Chinese industrial zones, exposing exoskeleton manufacturers to input cost volatility and export control friction.
- FDA 510(k) predicate device scarcity:Novel electromechanical architectures lack established comparison benchmarks, extending regulatory review timelines for first-in-category submissions.
- Physical therapist workforce density:Specialized rehabilitation labor shortages in German ambulatory care networks constrain device utilization rates despite hardware availability.
Strategic Opportunities
- Indian rehabilitation infrastructure:Underpenetrated neurological recovery centers in tier-2 cities present first-mover positioning for lower-cost exoskeleton platforms.
- AI-driven adaptive resistance:Machine learning algorithm integration with wearable sensor arrays enables personalized therapy intensity modulation without continuous clinician oversight.
- Japan's long-term care insurance:Home-care reimbursement expansions for mobility assistance devices are creating channel economics favorable to rental-lease distribution models.
Industry Challenges
- ISO 13485 quality management implementation:Medical device software lifecycle processes require specialized documentation expertise scarce among robotics hardware engineering teams.
- Legacy electronic health record integration:Proprietary data formats in United States hospital systems complicate real-time therapy outcome capture for robotic rehabilitation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Robotic Rehabilitation and Assistive Technologies Market |
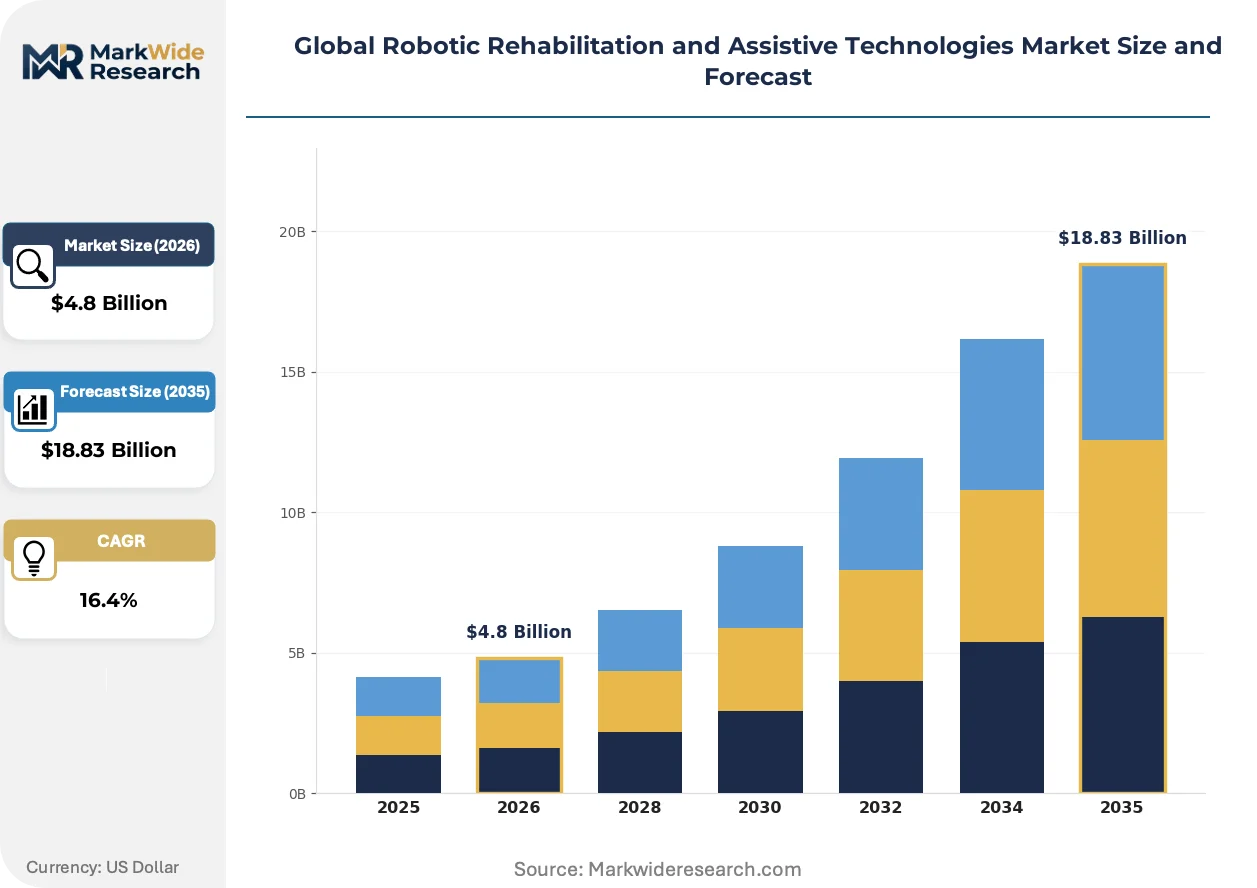
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.83 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exoskeleton Devices, Robotic Prosthetics, Therapeutic Robots, Assistive Communication Devices, Sensor Systems Technology: Electromechanical, AI-Driven, Motion Capture, Haptic Feedback, Machine Learning, Wearable Sensors Application: Stroke Recovery, Spinal Cord Injury, Neurodegenerative Disorders, Post-Operative Therapy, Gait Training End User: Rehabilitation Facilities, Specialized Clinics, Home Care Providers, Senior Care Centers, Military Recovery Units |
| Companies Covered | ReWalk Robotics Ltd., Ekso Bionics Holdings, Inc., CYBERDYNE Inc., Bionik Laboratories Corp., Hocoma AG, AlterG, Inc., Kinova Inc., Myomo Inc., Fourier Intelligence Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Robotic Rehabilitation and Assistive Technologies Market Shifts & Advancements
Control architecture evolution is fragmenting monolithic exoskeleton designs into component subsystems that interoperate across manufacturer ecosystems. This shift promises to decouple hardware procurement from software service commitments.
Soft robotic actuators employing pneumatic artificial muscles and fabric-based variable stiffness structures are modularizing lower-limb assistance platforms. Veterans Affairs facilities in the United States are piloting these systems for spinal cord injury populations. Component standardization is compressing repair cycle times and enabling field-replaceable unit strategies that reduce total cost of ownership.
Japan's PMDA has issued guidance documents distinguishing therapeutic claims from wellness positioning for wearable robotics, forcing manufacturers to restructure clinical trial investments. European notified bodies under EU MDR are applying enhanced scrutiny to electrical safety validation for home-use exoskeletons. Product development roadmaps are bifurcating into clinical-grade and consumer-grade variants with divergent certification timelines.
Hospital procurement committees are unbundling hardware acquisition from software subscription and maintenance contracts, reversing prior bundled-service preferences. Rehabilitation facility administrators in Germany are negotiating per-session utilization fees rather than capital expenditure approvals. This financial restructuring is most visible in United States academic medical centers where value-analysis committees now dominate technology acquisition decisions.
Global Robotic Rehabilitation and Assistive Technologies Market Segmentation
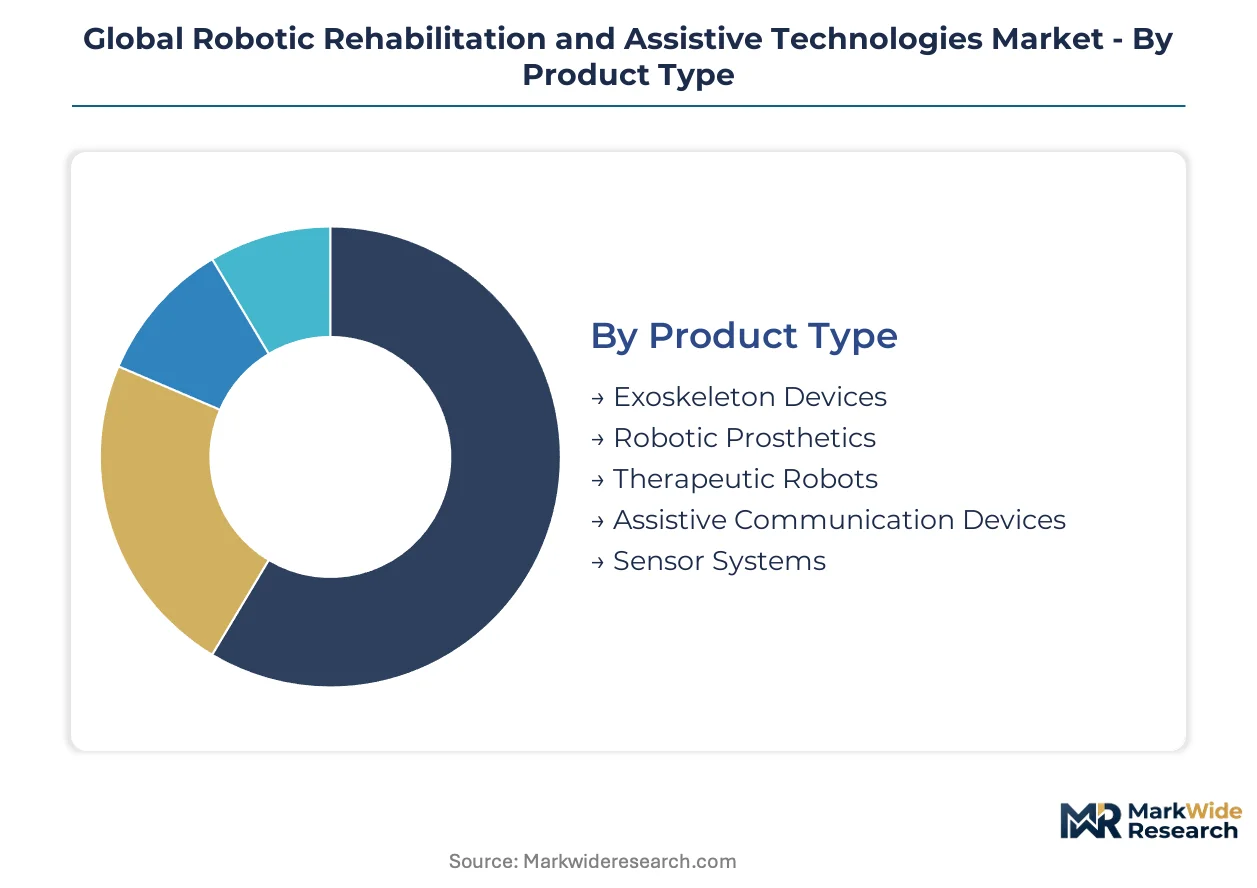
Segmentation in robotic rehabilitation reveals divergent commercial models across hardware platforms, software architectures, and care delivery settings. Product categories range from capital-intensive exoskeleton systems to recurring-revenue therapeutic software, while end-user fragmentation creates distinct channel economics between institutional procurement and home-care reimbursement.
Product Type:
Volume deployment clusters around lower-cost assistive peripherals, while premium capture concentrates in full-limb exoskeleton systems requiring specialized training and maintenance infrastructure.
- Exoskeleton Devices:Full-body and lower-limb electromechanical frameworks integrate brushless motors with carbon-fiber structural elements to provide powered gait assistance. Demand concentrates in United States Veterans Affairs spinal cord injury programs and German inpatient rehabilitation networks where CMS and statutory health insurance reimbursement codes support capital acquisition.
- Therapeutic Robots:Stationary and end-effector platforms deliver repetitive task-specific training for upper-extremity motor recovery through admittance-controlled robotic arms. Deployment accelerates in Japanese stroke rehabilitation facilities seeking to reduce therapist supervision burden amid workforce shortages.
- Robotic Prosthetics:Myoelectric and bionic limb systems translate neuromuscular signals into proportional motor response for amputee populations.
- Assistive Communication Devices:Eye-tracking and sip-and-puff interfaces enable environmental control and speech synthesis for locked-in syndrome and advanced ALS patients.
- Sensor Systems:Wearable inertial measurement units and pressure-sensitive insoles capture kinematic data for remote therapy monitoring and outcome quantification.
Mature deployment sits with exoskeleton devices in institutional settings. Newer deployment is concentrated in sensor systems enabling home-based monitoring.
Technology:
Technology segmentation tracks the shift from deterministic electromechanical control toward adaptive algorithmic systems that personalize assistance in real time.
- Electromechanical:Traditional servo-motor and harmonic drive architectures deliver position-controlled assistance through rigid linkages. These systems dominate installed bases in United States and European rehabilitation facilities where reliability certification under IEC 60601 electrical safety standards governs procurement decisions.
- AI-Driven:Deep learning models predict patient intent from multimodal sensor fusion, enabling anticipatory assistance modulation before explicit movement initiation. Adoption accelerates in Japanese home-care segments where PMDA neurorehabilitation frameworks reward clinical evidence generation.
- Motion Capture:Optical and inertial tracking systems reconstruct three-dimensional joint kinematics for therapy assessment and exoskeleton control input.
- Haptic Feedback:Force-reflecting interfaces restore tactile sensation for virtual reality rehabilitation and teleoperated assistance.
- Machine Learning:Supervised and reinforcement learning algorithms optimize therapy parameters based on historical patient response datasets.
- Wearable Sensors:Flexible electronics and textile-integrated biopotential electrodes enable continuous physiological monitoring outside clinical environments.
Electromechanical platforms anchor current revenue. AI-driven architectures are expanding most quickly as regulatory pathways clarify for software-as-medical-device claims.
Application:
Application segmentation reflects neurological condition prevalence and the availability of objective functional outcome measures that satisfy payer evidence requirements.
- Stroke Recovery:Upper and lower extremity motor rehabilitation following cerebrovascular events represents the largest addressable population. United States inpatient rehabilitation facilities embed robotic gait trainers into standardized care pathways, while German ambulatory networks deploy upper-limb systems for chronic-phase maintenance therapy.
- Spinal Cord Injury:Complete and incomplete lesions drive demand for powered exoskeletons that enable standing and stepping in paraplegic populations. Veterans Affairs facilities in the United States pilot soft robotic alternatives to rigid exoskeletons for improved comfort during extended wear.
- Neurodegenerative Disorders:Progressive conditions including Parkinson's disease and multiple sclerosis require adaptive assistance that evolves with declining motor function.
- Post-Operative Therapy:Orthopedic surgical recovery programs leverage robotic assistance for early mobilization and joint protection.
- Gait Training:General ambulation rehabilitation spans multiple etiologies with emphasis on fall prevention and endurance building.
Stroke recovery commands established reimbursement. Spinal cord injury applications are gaining share fastest through expanded CMS coverage determinations for personal use devices.
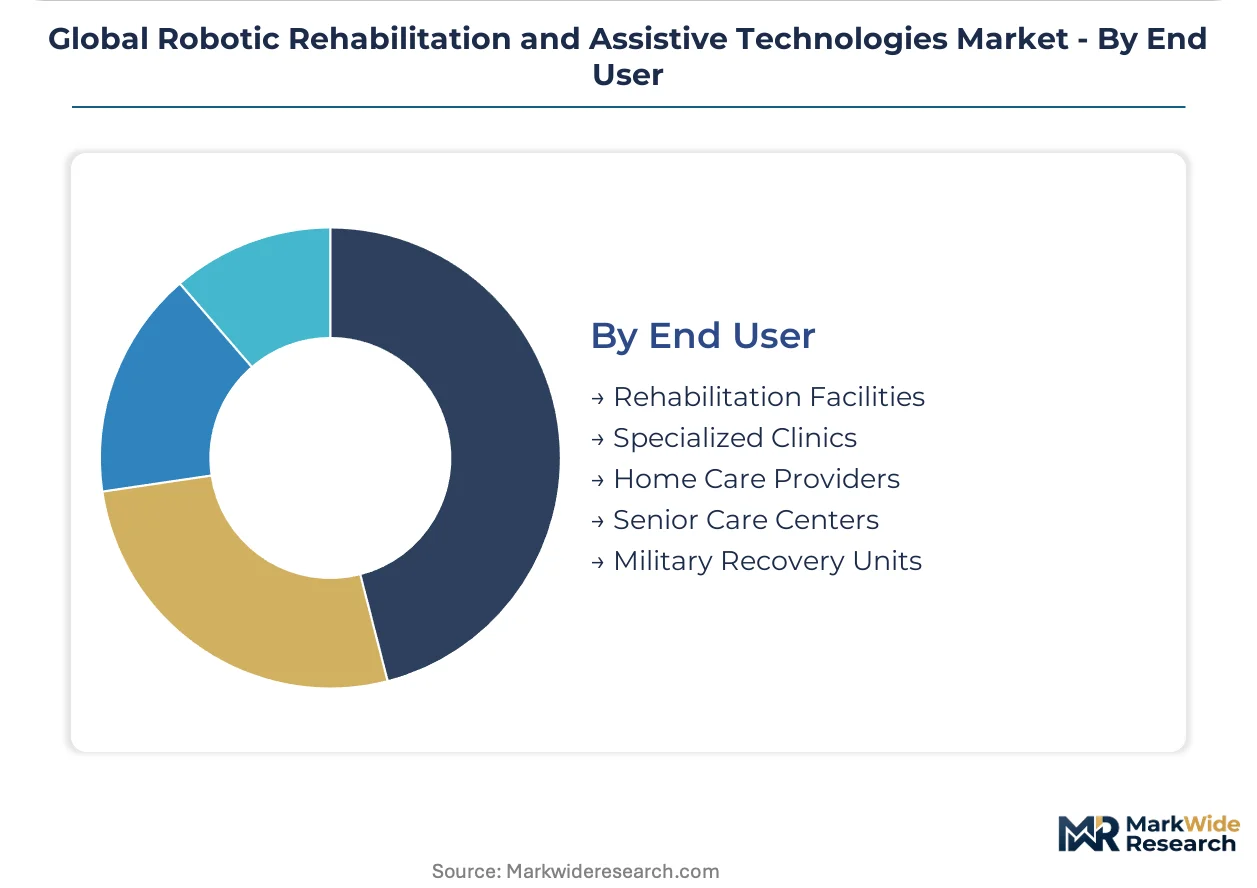
End User:
End-user segmentation distinguishes capital-intensive institutional procurement from recurring-revenue home-care models with divergent sales cycles and clinical support requirements.
- Rehabilitation Facilities:Comprehensive inpatient and outpatient centers deploy multi-station robotic systems serving diverse neurological populations. German statutory health insurance reimbursement frameworks favor these settings for intensive phase therapy, while Japanese long-term care insurance increasingly authorizes transition to home-based alternatives.
- Specialized Clinics:Single-modality centers concentrate on stroke, spinal cord, or pediatric populations with dedicated equipment configurations. United States value-analysis committees in academic medical centers now unbundle hardware from software subscriptions, compressing vendor margins.
- Home Care Providers:Durable medical equipment suppliers and visiting nurse organizations facilitate rental-lease distribution of lightweight exoskeletons.
- Senior Care Centers:Assisted living and skilled nursing facilities deploy fall-prevention and mobility maintenance technologies.
- Military Recovery Units:Defense health systems prioritize return-to-duty outcomes for service members with combat-related neurological trauma.
Rehabilitation facilities retain the deepest installed base. Home care providers represent the steepest expansion trajectory as reimbursement codes mature for personal-use exoskeleton authorization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-ion cathode material processing clusters in Chinese industrial zones supply electromechanical actuator manufacturers worldwide. This feedstock geography shapes cost structures for exoskeleton producers across North America, Europe, and Asia-Pacific rehabilitation markets.
United States
Veterans Affairs spinal cord injury programs and CMS reimbursement expansions for personal-use exoskeletons drive institutional and home-care demand. FDA 510(k) clearance pathways govern market access for electromechanical rehabilitation devices. Pittsburgh and Boston harbor robotics research clusters where academic medical centers pilot soft actuator systems for extended wear applications.
Germany
Statutory health insurance frameworks favor inpatient rehabilitation facilities for intensive-phase neurological therapy. EU MDR conformity assessments and CE marking requirements under active implantable medical device templates reshape commercialization timelines. The Baden-Württemberg industrial corridor hosts precision actuator manufacturers supplying carbon-fiber exoskeleton structural elements.
Japan
PMDA neurorehabilitation frameworks and long-term care insurance expansions for home-use mobility assistance accelerate domestic adoption. Aging demographics concentrate demand in Tokyo and Osaka metropolitan zones. Yokohama-based electromechanical suppliers decouple from legacy hydraulic architectures to enable lighter wearable platforms.
China
Domestic neurological rehabilitation infrastructure expansion in tier-2 cities creates positioning opportunities for lower-cost exoskeleton platforms. NMPA medical device registration and GB standards compliance govern product authorization. Shenzhen and Shanghai robotics manufacturing clusters scale brushless motor production for export markets.
India
Underpenetrated stroke recovery centers in secondary cities present first-mover opportunities for affordable assistive platforms. CDSCO medical device regulations and BIS quality standards constrain import-dependent supply chains. Bengaluru and Hyderabad med-tech hubs develop localized sensor integration capabilities for wearable rehabilitation systems.
Global Robotic Rehabilitation and Assistive Technologies Market Competitive Landscape
Global majors compete with regional champions across regulatory pathway expertise and reimbursement navigation capabilities. The vendor base fragments across specialized exoskeleton fabricators, therapeutic robot developers, and AI-driven software platforms. Three archetypes dominate: FDA-cleared portfolio holders, EU MDR first-movers, and PMDA-authorized home-care specialists. Competitive moves concentrate on M&A for regulatory asset accumulation and strategic partnerships for cathode material supply security.
Among FDA-cleared portfolio holders, ReWalk Robotics Ltd. and Ekso Bionics Holdings, Inc. occupy positions anchoring United States clinical network presence. CYBERDYNE Inc. represents the PMDA-authorized archetype within Japanese home-care segments. These three entities exemplify divergent geographic certification strategies that shape addressable population calculations and channel economics across their respective regulatory domains.
| Leading Market Players |
|---|
| ReWalk Robotics Ltd. |
| Ekso Bionics Holdings, Inc. |
| CYBERDYNE Inc. |
| Bionik Laboratories Corp. |
| Hocoma AG |
| AlterG, Inc. |
| Kinova Inc. |
| Myomo Inc. |
| Fourier Intelligence Co., Ltd. |
| Others |
Supply & Pricing Matrix
Lithium carbonate price volatility cascades through brushless motor production costs, compressing margins for mid-tier exoskeleton manufacturers while premium vendors absorb fluctuations through long-term cathode supply contracts. This feedstock exposure stratifies pricing tiers across institutional procurement channels.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium exoskeleton vendors from unbundled hardware competitors. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 13485 certification status and FDA clearance tier. Cost compression in economy-tier platforms is intensifying because Chinese motor suppliers are gaining IEC 60601 validation. Academic medical centers in the United States exhibit lowest price sensitivity; Indian tier-2 rehabilitation clinics face acute budget constraints.
Supply Chain Analysis
Dual-sourcing mandates from United States Veterans Affairs and German statutory health insurers force brushless motor qualification across at least two Asian suppliers. Electromechanical actuators draw from China, Japan, and South Korea; carbon-fiber structural elements rest on German and Japanese specialty chemical producers. Single-source vulnerability concentrates in rare-earth magnet processing. Distribution runs through GPO contracts in United States hospital systems and rental-lease channels in Japanese home-care markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
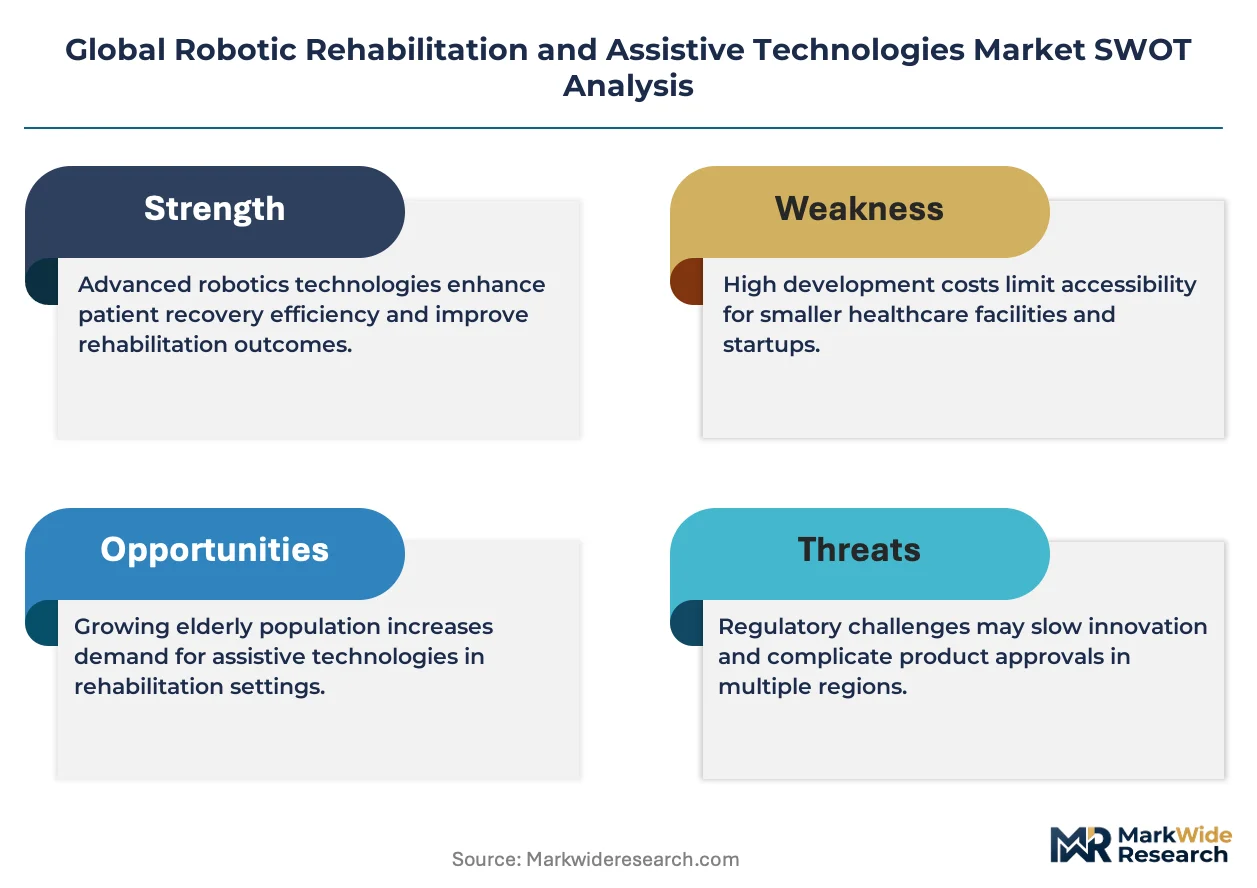
This market is consolidating around regulatory asset holders as EU MDR documentation burdens and FDA 510(k) predicate scarcity eliminate capital-constrained entrants.
For Market Incumbents: Cement reimbursement code ownership by deepening CMS and German statutory health insurance relationships before home-use authorization expands. Acquire distressed AI-software assets to overlay subscription revenue on hardware placements. Soft robotic actuator patents represent the critical defensive lever against emerging pneumatic alternatives. For New Entrants and Emerging Players: Capture Indian tier-2 city rehabilitation centers through localized sensor integration partnerships and CDSCO fast-track registration. Stroke recovery maintenance therapy in German ambulatory networks offers the most penetrable white space. Position through per-session utilization fee models that bypass capital expenditure approval cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor PMDA-authorized home-care specialists in Japan with proven long-term care insurance reimbursement traction. Five-to-ten year viability hinges on software-as-medical-device regulatory clarity. Watch for CMS national coverage determination signals on personal-use exoskeletons as the primary inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR active implantable templates reduce documentation burden for therapeutic robot manufacturers seeking European market access. |
| Hospital System Partnership | United States academic medical center value-analysis committees now unbundle hardware from software, reshaping vendor economics. |
| Software Companion Development | AI-driven adaptive resistance algorithms enable personalized therapy intensity modulation without continuous clinician oversight. |
| Reimbursement Strategy | Japan's long-term care insurance expansions for home-use mobility assistance create favorable rental-lease channel economics. |
| FDA Submission | 510(k) predicate device scarcity for novel electromechanical architectures extends regulatory timelines for first-in-category entrants. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with rehabilitation facility administrators, biomedical engineers, GPO contracts managers, and PMDA regulatory consultants combined with FDA 510(k) databases, EU MDR notified body records, and CMS coverage determination documents. Bottom-up exoskeleton shipment estimates and top-down healthcare expenditure allocations were triangulated to validate market sizing.
Data-stream reconciliation across product type, technology architecture, application indication, and end-user setting enabled segmentation-level projections over the analysis window. CAGRs were derived from fitted growth curves against historical reimbursement expansion patterns and cathode material cost trajectories. Modeled inputs included PMDA neurorehabilitation framework evolution and Veterans Affairs procurement cycle timing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion supply chain reconfiguration and CMS home-use coverage determinations. Deviation in Japanese long-term care insurance reimbursement rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Neurorehabilitation Gaming Systems Market
Rehabilitation Services
Exoskeleton and Rehabilitation Robot Safety and Performance Test Equipment Market
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
Asia-Pacific Repair and Rehabilitation Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
Global Home Rehabilitation Products and Services Market
Rehabilitation Services
Lower Extremity Rehabilitation Robotics Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
Wearable Neurorehabilitation Devices Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
Telerehabilitation Systems Market