
 Global Medical Exoskeleton Market | 2026-2036
Global Medical Exoskeleton Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Exoskeleton Market Foresight
Leasing and pay-per-use financing is reshaping capital access for medical exoskeleton procurement, allowing smaller rehabilitation centers to deploy active systems without full ownership burdens. Ekso Bionics Holdings leverages this shift through rental-based clinical partnerships. CYBERDYNE Inc. anchors its position in Japan via hospital-centric service models. ReWalk Robotics competes in the United States through specialized spinal cord injury programs.
A medical exoskeleton is a wearable robotic frame with electric motors, sensors, and control algorithms that augment or restore human limb movement, typically weighing 12-25 kg and operating on lithium-ion power systems for 2-8 hours per charge. These devices serve neurological and orthopedic rehabilitation by enabling repetitive, quantifiable gait training that manual therapy cannot replicate. Lower limb systems dominate installed base volumes due to stroke and spinal cord injury prevalence, while full body platforms capture premium pricing in advanced rehabilitation settings. Active technology leads R&D investment intensity, though semi-active systems occupy a growing middle ground balancing cost and performance for elderly care facilities.
FDA 510(k) pathways and the EU MDR frame product entry timelines, with software-as-medical-device classifications now extending to exoskeleton control algorithms. Japan's PMDA and Germany's BfArM similarly scrutinize real-world performance data for reimbursement eligibility. Stakeholders must monitor evolving reimbursement codes in the United States and Germany, as coverage decisions will determine whether clinical adoption scales beyond pilot installations into standard-of-care protocols.
Market Dynamics
Powered gait systems for spinal cord injury rehabilitation are restructuring competitive positioning as leasing models erode traditional capital equipment sales and FDA software validation requirements lengthen product entry timelines.
Growth Catalysts
- Reimbursement Pilot Expansion:Germany's BfArM real-world performance data requirements are creating pathways for hospital procurement of active exoskeleton systems through conditional coverage frameworks.
- Aging Demographics:Stroke rehabilitation centers in Japan are scaling repetitive gait training protocols that manual therapy cannot replicate, driving installed base expansion for lower limb platforms.
- Lithium-Ion Power Density:Advances in battery chemistry are extending operational runtime to 8 hours per charge, enabling full-day clinical deployment without mid-session recharging interruptions.
Market Restraints
- Software Validation Burden:FDA 510(k) pathways and EU MDR software-as-medical-device classifications are extending controller algorithm approval timelines by 12-18 months for active technology developers.
- Concentrated Component Supply:High-torque electric motor production concentrates in East Asian manufacturing clusters, exposing procurement to geopolitical friction and input cost volatility.
- Manual Therapy Substitution:Physical therapist labor remains cost-competitive for mild mobility impairment cases, limiting addressable market penetration for semi-active elderly care systems.
Strategic Opportunities
- Home-Based Rehabilitation:China's NMPA is streamlining Class II device registration for lightweight lower limb platforms, opening direct-to-consumer channels outside institutional settings.
- Neurological Indication Expansion:Multiple sclerosis and Parkinson's disease gait training protocols represent underpenetrated clinical applications with quantifiable outcome metrics for payer negotiation.
- Pay-Per-Use Financing:Rental-based clinical partnerships are collapsing upfront capital barriers for independent rehabilitation clinics previously excluded from active system ownership.
Industry Challenges
- Control Algorithm Talent Scarcity:Real-time gait phase detection and adaptive impedance control require specialized robotics expertise that outpaces current biomedical engineering program output.
- Legacy EMR Integration:Quantifiable gait training data from exoskeleton sensors lacks standardized interoperability with hospital electronic medical record systems, complicating outcome documentation workflows.
- Reimbursement Code Fragmentation:United States CPT code coverage varies by state Medicaid program, forcing manufacturers to maintain fifty distinct prior authorization support infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Exoskeleton Market |
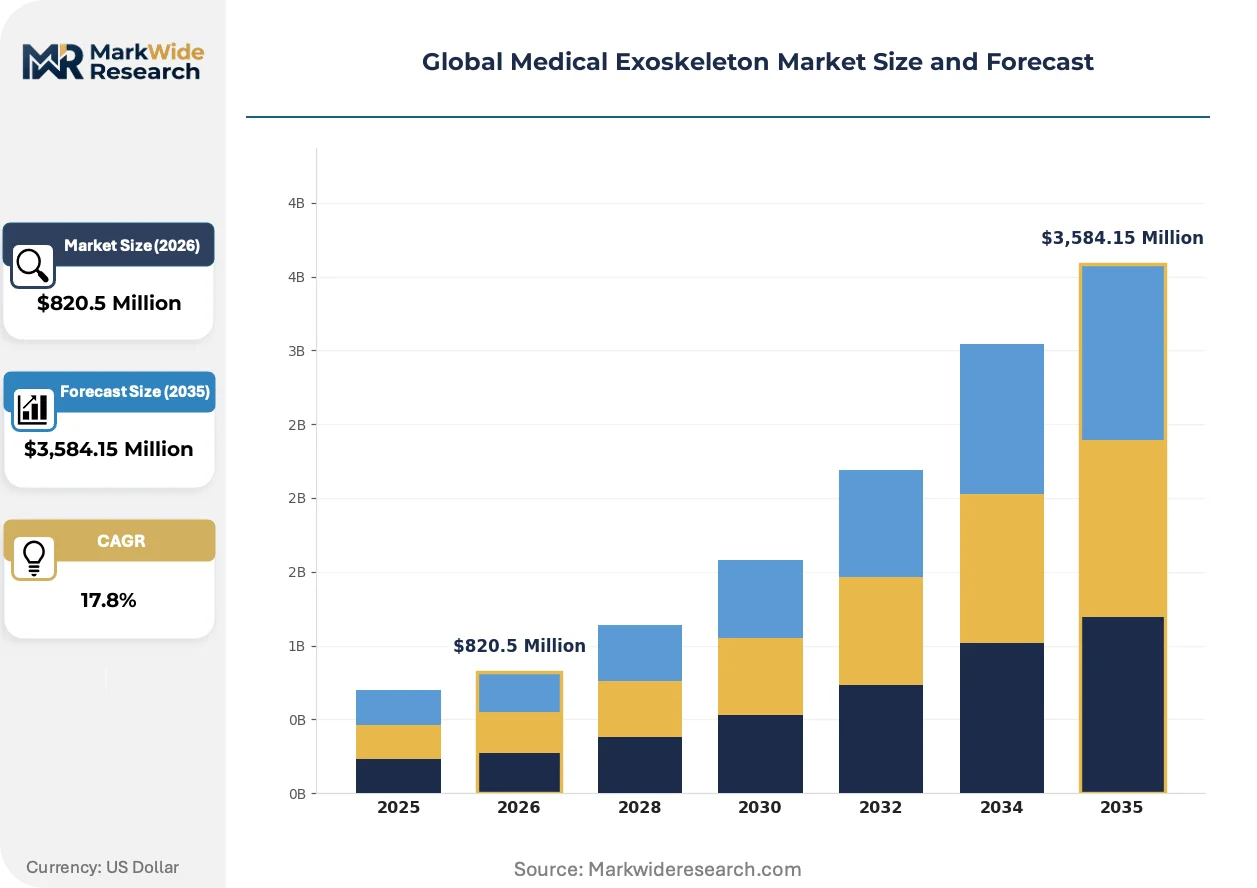
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $3,584.15 Million |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upper Limb, Lower Limb, Full Body, Hybrid Technology: Passive, Active, Semi-Active, Pneumatic Application: Neurological Rehabilitation, Orthopedic Rehabilitation, Assistive Mobility, Post-Surgery Recovery End User: Hospitals, Rehabilitation Centers, Elderly Care Facilities, Research Institutions |
| Companies Covered | Ekso Bionics Holdings, CYBERDYNE Inc., Ottobock SE & Co. KGaA, ReWalk Robotics, Parker Hannifin Corporation, Hocoma AG, BIONIK Laboratories, Rex Bionics, Sarcos Technology & Robotics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Exoskeleton Market Shifts & Advancements
Control architecture simplification and outcome-based contracting are compressing traditional hardware-software boundaries while regulatory convergence around real-world evidence is reshaping product development timelines.
Machine learning-based gait intention detection is collapsing the latency between neural signal interpretation and motor response in active exoskeleton controllers. Rehabilitation centers in Germany are piloting these predictive systems for incomplete spinal cord injury patients. The technology is collapsing the historical trade-off between responsiveness and safety redundancy that constrained earlier proportional myoelectric control schemes.
EU MDR Annex XVI classification expansion is capturing previously unregulated rehabilitation robotics under medical device surveillance. Software validation requirements now extend to exoskeleton firmware updates, mandating documented regression testing for each controller revision. Active technology developers with established quality management systems are absorbing compliance costs faster than emerging competitors, compressing the vendor base.
Leasing structures are displacing outright purchase for lower limb platforms in United States outpatient rehabilitation networks. Smaller clinic chains previously priced out of capital equipment markets are accessing powered gait systems through per-session fee arrangements. This channel shift concentrates most visible in California and Texas markets where private equity-backed clinic rollups favor operational expenditure models.
Global Medical Exoskeleton Market Segmentation
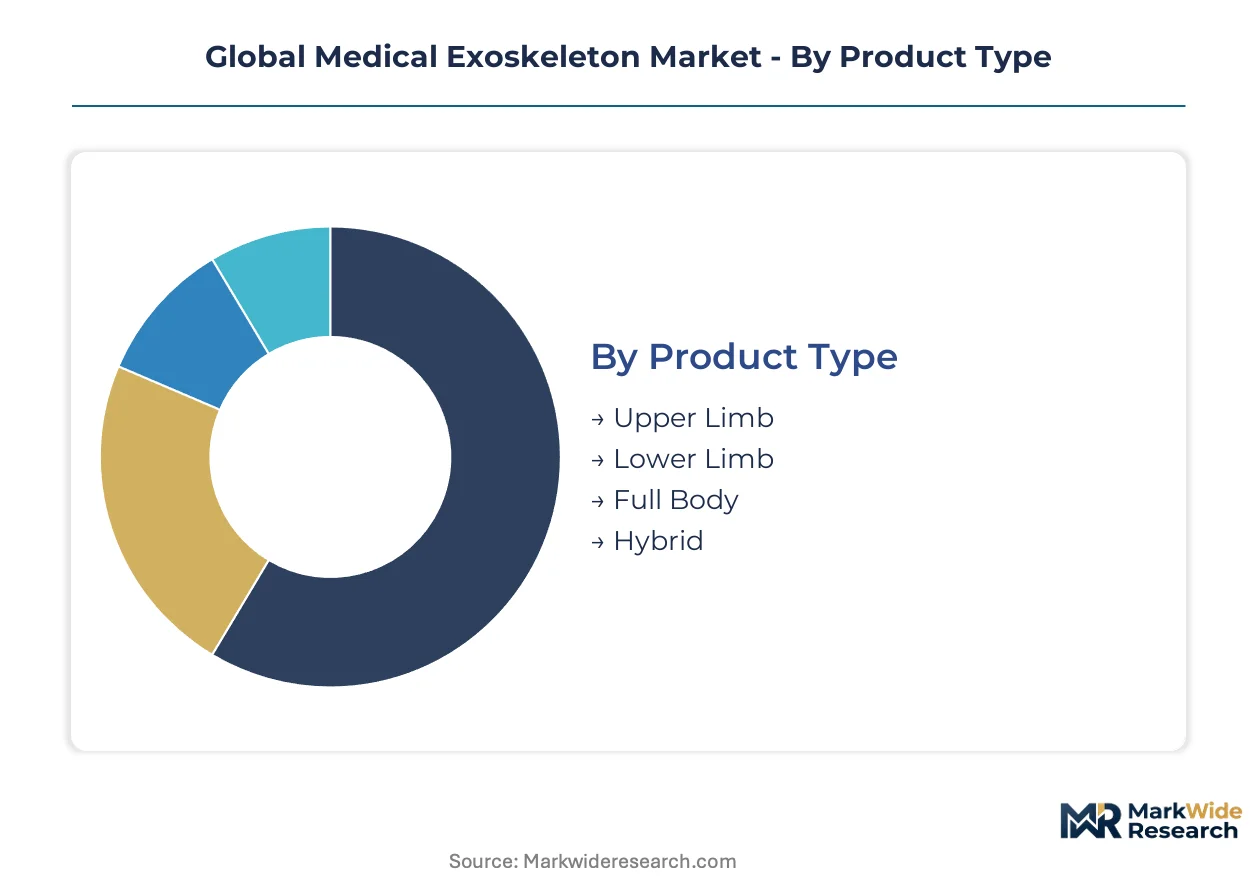
Medical exoskeleton segmentation reveals distinct procurement patterns across technology readiness levels and care settings. Product architecture and power system choices determine reimbursement pathways and clinical adoption velocity in institutional markets.
Product Type:
Lower limb systems anchor installed base volumes while full body platforms command premium positioning in advanced rehabilitation settings.
- Upper Limb:Shoulder-elbow-wrist actuation systems target stroke hemiparesis and spinal cord injury upper extremity dysfunction. Demand concentrates in United States veterans affairs hospitals where repetitive task training protocols show measurable functional gains.
- Lower Limb:Hip-knee-ankle powered gait systems weigh 12-25 kg with lithium-ion power delivering 2-8 hours operational runtime. Rehabilitation centers in Japan and Germany are scaling purchases for spinal cord injury and stroke populations where manual therapy cannot replicate quantifiable gait repetition.
- Full Body:Integrated upper-lower limb platforms enable complex multi-joint rehabilitation for severe neurological impairment. Research institutions in the United States deploy these systems for advanced mobility restoration protocols.
- Hybrid:Modular configurations combining passive and active elements balance cost and functionality for elderly care facilities with mixed patient acuity.
Lower limb systems retain volume leadership; full body platforms hold the steepest expansion curve.
Technology:
Power system architecture separates mature passive designs from emerging intelligent control platforms with adaptive impedance capabilities.
- Passive:Spring-loaded mechanical frames without external power sources support gravity compensation and joint stabilization. Elderly care facilities in Germany favor these systems for mild mobility impairment where cost constraints dominate procurement decisions.
- Active:Electric motor-driven systems with real-time gait phase detection and adaptive control algorithms enable powered movement assistance. FDA 510(k) software validation requirements extend approval timelines for developers integrating machine learning-based intention detection.
- Semi-Active:Selective joint actuation with clutch-based energy storage occupies the middle ground between cost and performance. Rehabilitation centers in China are piloting these systems for stroke populations under NMPA Class II registration pathways.
- Pneumatic:Compressed air actuation offers high power-to-weight ratios for research applications. Research institutions in Japan evaluate these platforms for soft exosuit configurations targeting home-based deployment.
Active technology captures R&D investment intensity; semi-active systems are climbing the fastest in elderly care facility procurement.
Application:
Clinical indication breadth determines addressable market scope and payer negotiation leverage for manufacturers.
- Neurological Rehabilitation:Stroke, spinal cord injury, and multiple sclerosis gait training protocols drive repetitive movement therapy demand. Rehabilitation centers in the United States and Germany concentrate purchases where quantifiable outcome metrics support reimbursement pilot programs.
- Orthopedic Rehabilitation:Post-trauma and degenerative joint disease mobility restoration targets hip and knee replacement populations. Hospitals in Japan integrate these systems into accelerated discharge protocols for aging surgical volumes.
- Assistive Mobility:Daily living support for permanent neurological impairment extends beyond clinical settings. China's NMPA is streamlining regulatory pathways for direct-to-consumer channels in this category.
- Post-Surgery Recovery:Early mobilization protocols for cardiac and major abdominal surgery reduce complication rates. Research institutions in Germany pilot these applications with real-world performance data collection for BfArM coverage frameworks.
Neurological rehabilitation retains volume leadership; assistive mobility holds the steepest expansion curve.
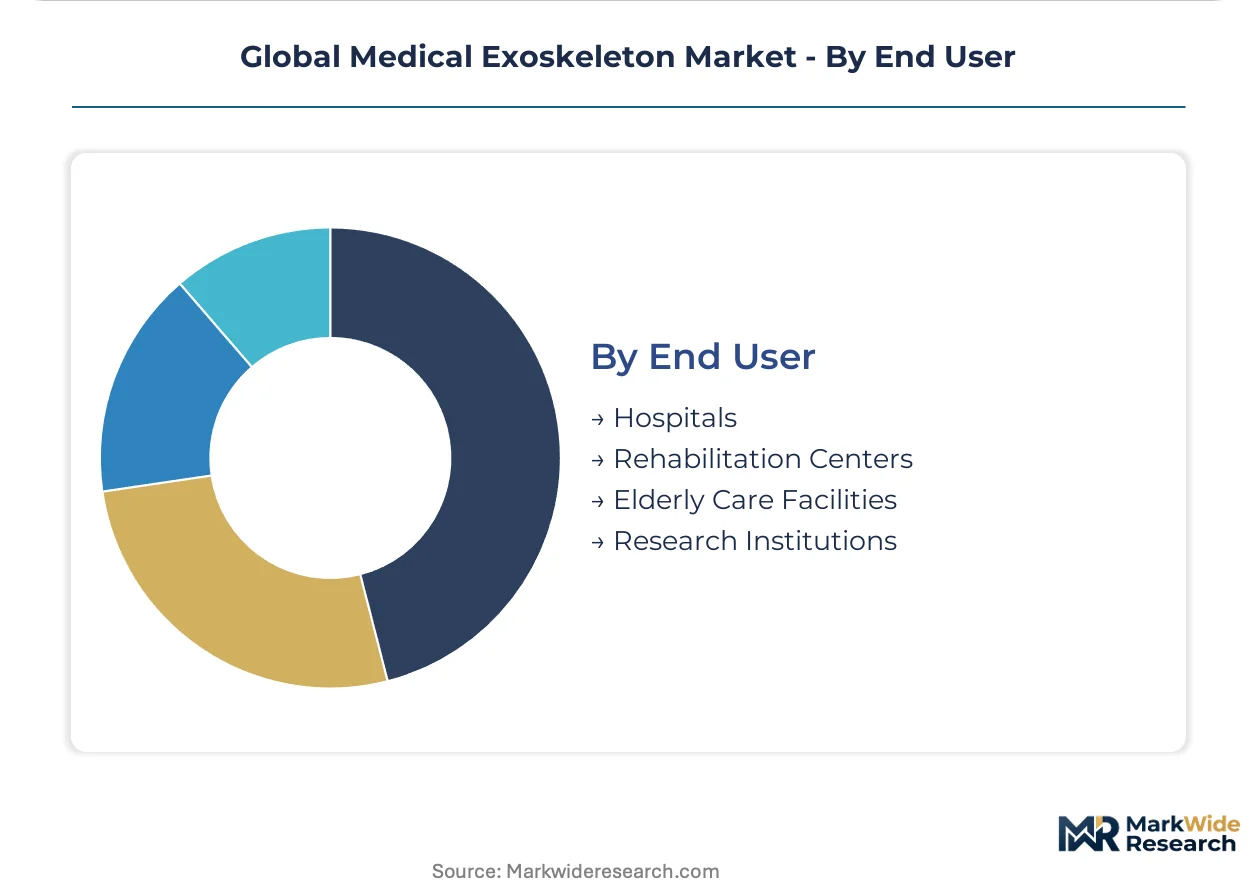
End User:
Capital availability and reimbursement access create distinct procurement behaviors across institutional categories.
- Hospitals:Acute care settings with established biomedical engineering departments manage FDA-cleared active systems for inpatient rehabilitation. United States hospital networks concentrate purchasing where bundled payment models reward functional outcome improvements.
- Rehabilitation Centers:Outpatient facilities specializing in neurological and orthopedic recovery represent the core installed base. Leasing and pay-per-use financing is collapsing upfront capital barriers for independent clinics in California and Texas markets.
- Elderly Care Facilities:Long-term care settings with cost-constrained procurement favor semi-active and passive systems. Japan's aging demographics are driving repetitive gait training protocol adoption where manual therapist labor shortages constrain service expansion.
- Research Institutions:Academic medical centers and technology developers pilot next-generation control algorithms and novel clinical indications. Germany's real-world evidence requirements position these sites as gatekeepers for subsequent reimbursement eligibility.
Rehabilitation centers retain volume leadership; elderly care facilities hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global medical exoskeleton trade flows reflect concentrated manufacturing in East Asian component clusters and final assembly integration across North American and European rehabilitation networks. Import dependency for high-torque electric motors creates strategic exposure for German and United States system integrators sourcing from East Asian suppliers.
United States
Veterans Affairs hospitals and private rehabilitation networks drive institutional procurement of FDA-cleared active systems. The FDA's 510(k) software-as-medical-device classifications extend validation timelines for machine learning-based gait controllers. California and Texas outpatient clinic rollups favor leasing models over capital purchases.
Germany
BfArM real-world performance data requirements are creating conditional coverage frameworks for hospital procurement of powered gait systems. Stroke rehabilitation centers in Bavaria and North Rhine-Westphalia scale repetitive training protocols. The country's automotive robotics talent pool feeds controller algorithm development for active exoskeleton platforms.
Japan
PMDA regulatory pathways and aging demographics concentrate demand in Tokyo and Osaka metropolitan rehabilitation centers. METI industrial policy supports soft exosuit research for home-based deployment. CYBERDYNE Inc. anchors hospital-centric service models through leasing partnerships with geriatric care facilities.
China
NMPA Class II device registration streamlines pathways for lightweight lower limb platforms targeting direct-to-consumer channels. Yangtze River Delta manufacturing clusters produce lithium-ion power systems and sensor modules. Stroke rehabilitation demand in Shanghai and Beijing drives pilot installations of semi-active systems.
South Korea
MFDS medical device approvals and national health insurance pilot programs support rehabilitation center procurement in Seoul Capital Area. Busan-Ulsan industrial zones manufacture precision electric motors for export to United States and European system integrators. Research institutions in Daejeon-Sejong evaluate pneumatic actuation for soft exosuit configurations.
Global Medical Exoskeleton Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: established rehabilitation robotics specialists with FDA-cleared platforms, diversified industrial conglomerates leveraging motion control expertise, and emerging soft exosuit developers targeting home-based deployment. Dominant competitive moves include technology licensing agreements between component suppliers and system integrators, plus geographic expansion through distributor partnerships in Asia-Pacific markets.
Within the rehabilitation specialist tier, Ekso Bionics Holdings exemplifies the rental-based clinical partnership model, while CYBERDYNE Inc. represents the hospital-centric service architecture. ReWalk Robotics occupies a position focused on spinal cord injury program specialization. These three companies illustrate divergent go-to-market strategies: capital-light leasing, integrated service delivery, and indication-specific clinical depth.
| Leading Market Players |
|---|
| Ekso Bionics Holdings |
| CYBERDYNE Inc. |
| Ottobock SE & Co. KGaA |
| ReWalk Robotics |
| Parker Hannifin Corporation |
| Hocoma AG |
| BIONIK Laboratories |
| Rex Bionics |
| Sarcos Technology & Robotics Corporation |
| Others |
Supply & Pricing Matrix
Yangtze River Delta manufacturing clusters anchor lithium-ion power system and high-torque electric motor production, concentrating component bargaining power among East Asian suppliers and compressing margin flexibility for United States and German system integrators downstream.
Pricing Analysis
Hospital procurement committees and independent rehabilitation clinics anchor a three-tier pricing structure across premium active systems, standard semi-active platforms, and economy passive frames. Price differentiation rests on FDA clearance tier and after-sales service bundling rather than hardware specifications alone. Cost compression in the semi-active tier is intensifying because NMPA Class II registration in China is streamlining competitive entry. Independent clinics in California and Texas markets exhibit highest price sensitivity, while Veterans Affairs hospitals tolerate premium positioning for indication-specific platforms.
Supply Chain Analysis
Tariff exposure between United States and Chinese suppliers dominates strategic procurement planning for German and Japanese system integrators. High-torque electric motor production draws from South Korea, China, and Japan; lithium-ion cells and sensor modules cluster in the same geography. Single-source vulnerability concentrates in precision motor winding and rare-earth magnet feedstock. Distribution runs through authorized medical device distributors with biomedical engineering service capabilities, bypassing general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical exoskeleton economics are shifting toward platform-ecosystem models where control algorithm interoperability and EMR integration determine vendor stickiness, collapsing traditional hardware-centric competitive moats.
For Market Incumbents: Pre-empt software-as-medical-device compliance cost escalation by consolidating quality management systems ahead of EU MDR firmware update surveillance requirements. Deepen backward integration into lithium-ion power systems to offset East Asian supplier concentration risk. Channel control through leasing infrastructure represents the priority defensive lever against emerging pay-per-use competitors. For New Entrants and Emerging Players: Pursue home-based assistive mobility applications in China where NMPA Class II registration streamlines direct-to-consumer pathways outside institutional procurement bottlenecks. Elderly care facilities in Japan present the most penetrable segment given manual therapist labor shortages and METI-supported soft exosuit research. A software companion development go-to-market angle collapses hardware margin dependence. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among leasing-enabled clinical partnership models with embedded service contracts rather than capital equipment vendors. Long-term viability across the projection horizon favors developers with established FDA 510(k) quality systems and real-world evidence collection infrastructure. Acquisition target archetype: semi-active platform specialists with NMPA registration and geriatric care channel relationships. The signal to watch is BfArM conditional coverage framework expansion for powered gait systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software Validation Investment | Accelerates controller algorithm approval timelines for machine learning-based gait intention detection systems. |
| Hospital System Partnership | Secures bundled payment model participation where functional outcome improvements drive procurement decisions. |
| Reimbursement Strategy Development | Positions systems for CPT code coverage expansion across United States state Medicaid programs. |
| Software Companion Development | Enables EMR interoperability for quantifiable gait training data documentation workflows. |
| CE Marking Pathway Execution | Captures EU MDR Annex XVI classification compliance for previously unregulated rehabilitation robotics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across rehabilitation centers, hospital purchasing committees, biomedical engineering departments, and active exoskeleton developers. Primary interviews captured procurement decision workflows, software validation burden assessments, and leasing model adoption patterns. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation, CMS Medicare reimbursement filings, and hospital GPO contract records. Bottom-up installed base estimates and top-down market sizing triangulated volume and value outputs.
Calibration against historical reimbursement pilot program expansion rates and regulatory approval timeline data shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, power system technology, clinical indication, and end-user institutional category. CAGRs were derived from slope analysis of reimbursement access trajectories and battery chemistry advancement curves. Forecast inputs incorporated PMDA real-world evidence requirements and NMPA Class II registration streamlining impacts.
Macroeconomic conditions sit as an overlay; deviation in lithium commodity pricing, East Asian manufacturing capacity utilization, or United States-Germany-Japan reimbursement policy synchronization would shift the trajectory. Forecasts reflect documented assumptions regarding software validation timeline normalization and leasing model penetration ceilings. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Global Medical Footwear Market
Medical Devices
Global Holter ECG Market
Medical Devices
Medical Device and Accessories Market
Medical Devices
Passive Prosthetics Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Global Wearable Injector Devices Market
Medical Devices
Global Venous Stents Market
Medical Devices
Global Breast Pumps Market
Medical Devices
GCC Implantable Medical Devices Market
Medical Devices
Europe Breast Pumps Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
Spine Bone Stimulators Market