
 Microneedling Cartridges Market | 2026-2036
Microneedling Cartridges Market Size, Share, and Industry Trends Forecast 2026-2036
Microneedling Cartridges Market Outlook
Aesthetic centers and medical spas is decoupling from dermatology clinics as the dominant procurement channel for microneedling cartridges. Dermapenworld leverages its established training academy network to lock in recurring cartridge orders from certified practitioners. MT. DERM GmbH anchors its position through German-engineered precision manufacturing that commands premium pricing across European aesthetic practices. Bomtech Electronics competes aggressively on automation-enabled production scale, driving cost efficiencies that pressure mid-tier suppliers.
Microneedling cartridges are precision-engineered needle arrays, typically 0.25–3.0 mm in length, manufactured from surgical-grade stainless steel or titanium and housed in sterile disposable hubs designed for controlled dermal puncture. These devices mechanically induce collagen neogenesis through controlled micro-injury, serving both therapeutic scar revision and elective skin rejuvenation protocols. Single-use cartridges dominate volume due to cross-contamination protocols, while 36-pin configurations capture expanding body-treatment applications where broader coverage accelerates procedure throughput. Titanium material grades sustain premium positioning as practitioners associate the alloy with reduced flexural fatigue and extended needle sharpness retention.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation (MDR) classification of microneedling devices above 0.3 mm as Class IIa instruments collectively elevate compliance costs and barrier thresholds for new entrants. ISO 13485 quality management certification has become table stakes for supplier qualification by multi-clinic purchasing organizations. Stakeholders must monitor evolving needle-length classification debates among regulators, as reclassification would force portfolio restructuring and redirect R&D investment toward sub-threshold device formats.
Market Dynamics
Aesthetic centers and medical spas are decoupling from dermatology clinics as the dominant procurement channel, redirecting volume toward direct-to-practitioner supply relationships that bypass traditional institutional purchasing hierarchies.
Growth Catalysts
- FDA 510(k) pathway refinement:Tightened clearance requirements for needle-based aesthetic devices are filtering out marginal suppliers and consolidating demand around certified manufacturers with established quality systems.
- Titanium alloy adoption:Surgical-grade titanium cartridges command preference among high-volume practitioners for reduced flexural fatigue and extended needle sharpness retention during multi-site treatment protocols.
- Aesthetic center channel expansion:Standalone medical spas in the United States and South Korea are building captive procurement operations that lock in recurring cartridge orders through training-certification bundling.
Market Restraints
- Surgical-grade stainless steel price volatility:Input material cost swings compress margin structures for mid-tier suppliers without backward integration into raw material sourcing.
- German precision manufacturing concentration:Premium cartridge supply clusters around specialized Mittelstand producers, creating geographic single-point-of-failure exposure for European aesthetic practices.
- EU MDR Class IIa classification:Elevated compliance documentation and notified body engagement timelines extend product registration cycles and freeze new entrant pipelines.
Strategic Opportunities
- United States body-treatment expansion:36-pin configurations for broader dermal coverage are penetrating non-facial applications where procedure throughput acceleration drives cartridge consumption.
- ISO 13485 certification arbitrage:Multi-clinic purchasing organizations are mandating quality management certification as table stakes, creating tiered supplier qualification tiers that reward early compliance investment.
- Automation-enabled production scale:Korean and Chinese manufacturers are deploying robotic needle array assembly to compress unit economics and challenge European premium positioning.
Industry Challenges
- Needle-length regulatory reclassification risk:Ongoing debates among FDA and EU regulators regarding 0.3 mm threshold definitions threaten forced portfolio restructuring and redirected R&D investment.
- Cross-contamination protocol enforcement:Single-use cartridge mandates intensify waste management costs and sustainability scrutiny from environmental compliance officers at large clinic chains.
- Practitioner certification standardization:Fragmented training requirements across state-level medical boards in the United States create compliance complexity for multi-location aesthetic operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microneedling Cartridges Market |
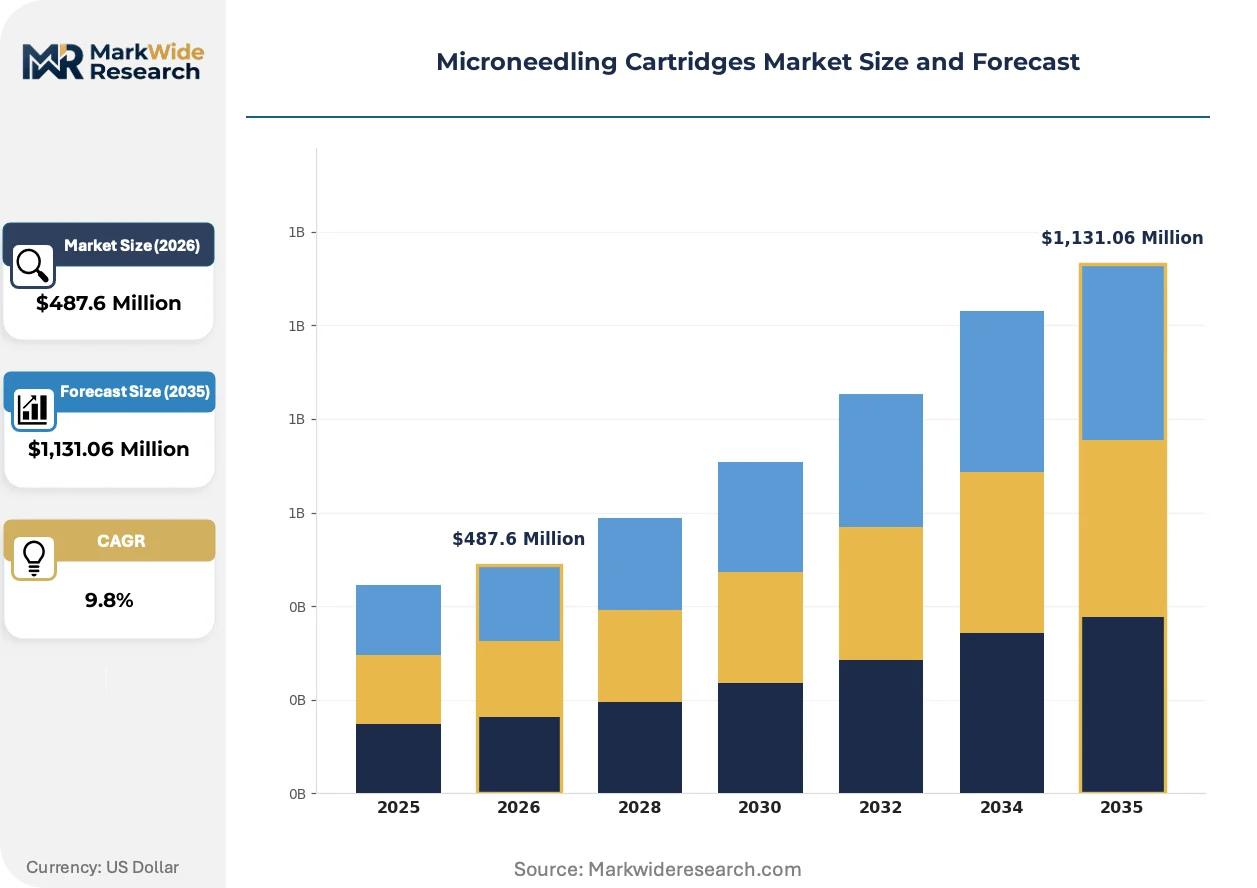
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,131.06 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Use, Multi Use, Disposable, Reusable Needle Configuration: 5 Pin, 12 Pin, 36 Pin, 42 Pin Material: Stainless Steel, Titanium, Plastic, Alloy End User: Clinics, Dermatologists, Spas, Aesthetic Centers |
| Companies Covered | Dermapenworld, MT. DERM GmbH, MD Needle Pen, Bomtech Electronics, Bellus Medical, Woorhi Mechatronics, Bellaire Industry, Salient Medical Solution, Beijing JAMI Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microneedling Cartridges Market Strategic Shifts
Electromechanical precision controls and sterile disposable hub designs are converging to reshape treatment protocol standardization, while regulatory classification debates force simultaneous investment in compliance infrastructure and product format diversification.
Radiofrequency-integrated microneedling cartridges are electrifying collagen neogenesis outcomes by delivering thermal energy through insulated needle arrays. Aesthetic centers in South Korea and Germany are adopting these hybrid devices at accelerated replacement cycles. This convergence is compressing demand for standalone mechanical cartridges in premium treatment tiers.
EU Medical Device Regulation needle-length classification thresholds are forcing portfolio segmentation between cosmetic and medical-grade device formats. Manufacturers with dual-registration capabilities are capturing shelf space from single-format competitors. German and Swiss aesthetic practices are most affected, redirecting procurement toward suppliers with established Class IIa technical documentation.
Direct-to-practitioner subscription models are displacing distributor-mediated supply relationships in the United States channel. Large medical spa chains are negotiating multi-year cartridge commitments tied to exclusive device platform adoption. This consolidation is most visible in California and Florida aesthetic markets where chain concentration exceeds independent clinic density.
Microneedling Cartridges Market Segmentation
Microneedling cartridge procurement patterns diverge sharply across product formats, needle densities, material grades, and end-user channels. Supply-side specialization and regulatory compliance requirements create distinct competitive arenas within each segmentation dimension.
Product Type:
Supply concentration clusters around sterile disposable formats where cross-contamination protocols and FDA 510(k) clearance requirements erect barrier thresholds.
- Single Use:Sterile pre-packaged cartridges dominate volume in United States aesthetic centers where joint commission protocols mandate disposable instrumentation. Waste management costs and sustainability scrutiny from large clinic chains intensify margin pressure on suppliers without biodegradable hub alternatives.
- Disposable:Hub-and-needle assemblies designed for immediate disposal post-procedure capture expanding share in German and South Korean markets where practitioner liability frameworks favor documented sterility chains. Premium positioning sustains against reusable alternatives despite per-procedure cost premiums.
- Multi Use:Autoclavable cartridge systems retain niche presence in cost-sensitive dermatology clinics with in-house sterilization infrastructure.
- Reusable:Metal hub designs with replaceable needle arrays persist in select European training academies where device familiarity outweighs convenience premiums.
Today's leader: Single Use. Tomorrow's challenger: Disposable.
Needle Configuration:
Procedure throughput requirements and treatment site anatomical variation drive divergence in pin density adoption across facial versus body applications.
- 36 Pin:Broader dermal coverage arrays accelerate procedure completion for non-facial applications in United States medical spa chains. California and Florida operators specify 36-pin formats for back and décolletage protocols where treatment area expansion justifies cartridge consumption premiums.
- 12 Pin:Mid-density configurations balance precision with coverage for periorbital and perioral facial zones where tissue delicacy demands controlled puncture density. German aesthetic practices favor 12-pin arrays for scar revision protocols requiring targeted collagen induction.
- 5 Pin:Minimal pin counts serve isolated lesion treatment and precision spot applications in dermatology clinic settings.
- 42 Pin:Maximum density formats penetrate body contouring segments where accelerated surface coverage drives throughput economics.
Volume concentrates in 12-pin facial applications. Steepest expansion trajectory belongs to 36-pin body treatment formats.
Material:
Raw material sourcing backwardness and alloy processing capabilities determine tiered supplier positioning across cost-performance spectra.
- Titanium:Surgical-grade Ti-6Al-4V alloy commands preference in high-volume South Korean aesthetic centers where extended needle sharpness retention reduces per-procedure cartridge consumption. Reduced flexural fatigue during multi-site treatment protocols justifies 40-60% price premiums over stainless alternatives.
- Stainless Steel:316L surgical-grade formulations retain volume leadership in price-sensitive clinic segments. Input material cost volatility from nickel and chromium spot markets compresses margin structures for mid-tier suppliers without captive raw material sourcing.
- Alloy:Proprietary metal blends target flexural strength optimization in premium device platforms.
- Plastic:Polymer hub materials dominate disposable cartridge housing cost structures regardless of needle metallurgy.
Revenue leadership: Titanium. Volume leadership: Stainless Steel.
End User:
Procurement autonomy and training certification bundling reshape channel power dynamics between institutional buyers and direct-to-practitioner relationships.
- Aesthetic Centers:Standalone medical spas in United States metropolitan markets are building captive procurement operations that bypass traditional distributor hierarchies. Direct subscription models tied to exclusive device platform adoption lock in multi-year cartridge commitments.
- Spas:Wellness-oriented operators in South Korea integrate microneedling into broader aesthetic service menus where cartridge consumption scales with membership program penetration.
- Dermatologists:Board-certified practitioners retain preference for titanium-grade precision formats in therapeutic scar revision protocols.
- Clinics:Institutional purchasing organizations consolidate volume across multi-location operators, mandating ISO 13485 certification as supplier qualification threshold.
Channel power shift: Aesthetic Centers. Certification gatekeeper: Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturing clusters in Baden-Württemberg and Bavaria anchor premium cartridge supply chains. United States aesthetic center chains in California and Florida are decoupling from dermatology clinic procurement hierarchies. South Korean automation hubs in Gyeonggi Province compress unit economics through robotic assembly lines.
United States
Medical spa chains in California and Florida are building captive procurement operations that bypass traditional distributor networks. FDA 510(k) clearance requirements for needle-based aesthetic devices filter out marginal suppliers and consolidate demand around certified manufacturers. Direct-to-practitioner subscription models in Miami and Los Angeles lock in multi-year cartridge commitments tied to exclusive device platform adoption.
Germany
Specialized Mittelstand producers in Stuttgart and Munich command premium pricing through precision-engineered needle arrays. EU Medical Device Regulation Class IIa classification for devices above 0.3 mm elevates compliance documentation and extends product registration cycles. Aesthetic practices in Düsseldorf and Frankfurt redirect procurement toward suppliers with established technical documentation for medical-grade formats.
South Korea
High-volume aesthetic centers in Seoul and Busan prefer surgical-grade titanium cartridges for extended needle sharpness retention during multi-site protocols. MFDS medical device registration requirements shape product development priorities for domestic and export markets. Automation-enabled production facilities in Suwon and Incheon deploy robotic needle array assembly to challenge European premium positioning.
China
Domestic manufacturers in Shenzhen and Guangzhou leverage scale economics to supply cost-sensitive clinic segments across Asia-Pacific. NMPA medical device classification guidelines for microneedling products influence registration strategies for local and multinational suppliers. Production clusters in the Yangtze River Delta are expanding capacity for disposable hub assemblies regardless of needle metallurgy.
Switzerland
Aesthetic practices in Zurich and Geneva sustain demand for premium titanium-grade formats in therapeutic scar revision protocols. Swissmedic medical device regulations align with EU MDR standards, creating dual-registration advantages for suppliers with established Class IIa documentation. Precision manufacturing heritage in the Swiss Mittelland region supports niche positioning for high-flexural-strength alloy configurations.
Microneedling Cartridges Market Competitive Environment
Training-certification bundling dominates the current landscape as device manufacturers lock in recurring cartridge orders from certified practitioners. Market structure consolidates around three tiers: premium German-engineered specialists, Korean automation-scale producers, and mid-tier suppliers facing margin compression from raw material volatility. Strategic archetypes include precision manufacturing anchors, academy-network bundlers, and cost-leadership assemblers. Geographic expansion and portfolio diversification represent the dominant competitive moves as players seek to offset regulatory compliance burdens.
Among academy-network bundlers, Dermapenworld exemplifies the training-certification model that secures recurring demand through practitioner lock-in. MT. DERM GmbH occupies a position within the German precision manufacturing archetype, representing engineering-driven premium positioning. Bomtech Electronics sits within the automation-scale tier, exemplifying Korean producers leveraging robotic assembly to compress unit economics.
| Leading Market Players |
|---|
| Dermapenworld |
| MT. DERM GmbH |
| MD Needle Pen |
| Bomtech Electronics |
| Bellus Medical |
| Woorhi Mechatronics |
| Bellaire Industry |
| Salient Medical Solution |
| Beijing JAMI Tech |
| Others |
Value Chain & Pricing Dynamics
Nickel and chromium spot market volatility cascades through 316L surgical-grade stainless steel procurement, compressing margin structures for mid-tier cartridge suppliers without captive raw material sourcing and forcing tiered pricing stratification across premium titanium, standard stainless, and economy plastic-hub formats.
Pricing Analysis
Input-cost pass-through from surgical-grade alloy markets sustains three-tier pricing structure across premium, standard, and economy levels. FDA 510(k) certification tier and ISO 13485 quality grade drive price differentiation between German-engineered titanium arrays and Asian stainless-steel alternatives. Cost compression in mid-tier stainless segments intensifies because of nickel price volatility and Korean automation-scale competition. Large medical spa chains exhibit lowest price sensitivity through subscription lock-in, while independent dermatology clinics remain most exposed to spot-market material swings.
Supply Chain Analysis
Dual-sourcing requirements from multi-clinic purchasing organizations mandate qualified supplier redundancy across German Mittelstand precision manufacturers, Korean automation-scale producers, and Chinese cost-leadership assemblers. Needle array production draws from surgical-grade titanium billet suppliers in Japan and Germany, 316L stainless steel mills in China and South Korea, and polymer hub injection molders in Shenzhen and Guangzhou. Single-source vulnerability concentrates in German precision grinding equipment for needle tip geometries. Distribution runs through direct-to-practitioner subscription platforms that displace traditional medical distributor networks in United States aesthetic center chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Microneedling Cartridges Market functions as a stable compounder anchored by recurring consumable demand from certified practitioner networks, with cartridge replacement cycles tied to training academy lock-in creating predictable revenue streams resistant to cyclical downturns.
For Market Incumbents: To counter Korean automation-scale competition compressing mid-tier margins, deepen backward integration into surgical-grade titanium billet sourcing and expand ISO 13485-certified capacity in Baden-Württemberg manufacturing clusters. Fortify training academy networks to extend practitioner certification bundling that secures recurring cartridge commitments against device platform switching. For New Entrants and Emerging Players: Begin with white-space capture in biodegradable hub alternatives for sustainability-focused United States medical spa chains and unbundled cartridge supply for independent dermatology clinics outside major metropolitan markets. Penetrate through compatibility certifications for widely deployed pen platforms rather than proprietary device development. For Investors and Strategic Acquirers: Asymmetric upside sits with automation-enabled mid-cap specialists possessing robotic needle array assembly capabilities and dual FDA-EU MDR registration infrastructure. Long-term viability rests on consumable recurring revenue models with practitioner switching costs. Watch for MFDS registration acceleration in South Korean domestic manufacturers as inflection signal for export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Training Academy Network Expansion | Dermapenworld's certification bundling locks practitioners into recurring cartridge orders through exclusive device platform adoption. |
| Backward Integration into Titanium Sourcing | MT. DERM GmbH's captive supply of surgical-grade Ti-6Al-4V alloy insulates margin structures from spot market volatility. |
| Robotic Needle Array Assembly Deployment | Bomtech Electronics' automation scale in Gyeonggi Province compresses unit economics to challenge European premium positioning. |
| Dual FDA-EU MDR Registration Investment | Swiss and German manufacturers with established Class IIa documentation capture shelf space from single-format competitors. |
| Direct-to-Practitioner Subscription Launch | United States medical spa chains in California and Florida bypass distributor hierarchies through multi-year cartridge commitments. |
Study Parameters
Direct dialogue with aesthetic center procurement directors, biomedical engineers at dermatology clinic chains, GPO contracts managers, and regulatory affairs leads at device manufacturers grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, MFDS medical device registration records, and hospital procurement contract disclosures. Bottom-up cartridge volume estimates triangulated against top-down market sizing from trade flow analysis and manufacturer capacity disclosures.
Segmentation-level projections across product type, needle configuration, material grade, and end-user channel fed into analytical framework spanning the projection horizon. CAGRs derived from procedure volume growth trajectories, replacement cycle compression, and penetration rate assumptions for radiofrequency-integrated formats. Industry-specific inputs included practitioner certification pipeline data from training academies and aesthetic center chain expansion plans in Florida and California metropolitan markets.
Several conditions sit outside the modeled scope, including potential FDA needle-length reclassification above 0.3 mm thresholds, abrupt titanium alloy supply disruptions from geopolitical trade restrictions, and breakthrough non-needle collagen induction technologies displacing mechanical microneedling protocols. Deviation in EU MDR notified body engagement timelines or MFDS registration acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Cystic Fibrosis Devices Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
Contrast Injection Lines Market
Medical Devices
Eccentric Tip Syringe Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Elbow Fixators Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
Directed Energy Based Surgical Systems Market
Medical Devices
Bronchial Blocker Devices Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Anti-Aging Devices Market