
 Injectable Drug Delivery Market | 2026-2036
Injectable Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Injectable Drug Delivery Market Analysis
Prefilled syringe-grade borosilicate glass and cyclic olefin polymer specifications is rotating upward as biologics manufacturers reject lower-performance materials. Becton Dickinson and Company leverages vertical integration across glass barrel and needle assembly operations. Gerresheimer anchors European supply through specialized pharmaceutical tubing facilities. Pfizer competes on fill-finish capacity tied to pandemic-scaled biologic drug networks.
Injectable drug delivery encompasses parenteral administration systems designed for direct vascular or tissue-level drug deposition, utilizing needle-syringe assemblies, spring-loaded autoinjectors, electromechanical infusion pumps, and wearable bolus devices engineered to maintain sterility, dosing precision within five percent variance, and patient self-administration compatibility. Autoinjectors command expanding share as monoclonal antibody volumes rise and patient adherence protocols shift from clinic to home. Pen injectors dominate diabetes therapy where Eli Lilly and Sanofi sustain decades of insulin delivery optimization. Subcutaneous delivery mode leads across oncology and neurology indications where prolonged absorption kinetics improve therapeutic windows.
FDA enforces combination product regulations under 21 CFR 4, while EMA applies MDR Annex I general safety and performance requirements to device-drug systems. Japan's PMDA mandates localized clinical bridging studies for foreign-manufactured injectables, shaping market entry timelines. Stakeholders must monitor evolving pharmacovigilance obligations for connected devices transmitting dosing data across HIPAA and GDPR jurisdictions.
Market Dynamics
Biologics manufacturers are consolidating fill-finish capacity around prefilled syringes and autoinjectors as chronic disease protocols migrate from clinic administration to patient self-management, compressing device qualification timelines and forcing material specification upgrades across the supply base.
Growth Catalysts
- FDA 21 CFR 4 combination product rules:Device-drug system harmonization is accelerating unified validation protocols for autoinjector submissions, reducing dual-track regulatory burden for sponsors.
- Homecare infusion protocols:United States, Germany, and Japan reimbursement frameworks now standardize ambulatory subcutaneous delivery for oncology and neurology biologics, expanding addressable patient populations.
- Cyclic olefin polymer (COP) barrel specifications:Glass-alternative materials are displacing borosilicate in protein-sensitive formulations, enabling larger-volume subcutaneous injections without delamination risk.
Market Restraints
- Specialized borosilicate tubing concentration:European pharmaceutical glass supply chains anchor around German and Italian tubing furnaces, creating single-source vulnerability for prefilled syringe barrel production.
- EU MDR Annex I technical documentation:General safety and performance requirements for combination products are extending device recertification timelines, delaying biologic drug-device launches.
- Silicone oil lubricant interaction limits:Protein aggregation risks in high-concentration monoclonal antibodies are constraining plunger-stopper material selection and forcing costly formulation compatibility studies.
Strategic Opportunities
- Wearable bolus injector convergence:Electromechanical pump technology and smartphone connectivity are merging into patch-based systems for large-volume subcutaneous delivery, opening neurology and immunology indications.
- Japan PMDA bridging study harmonization:Streamlined foreign-manufactured injectable approval pathways are compressing market entry timelines for device-drug systems with existing FDA or EMA clearance.
- Direct-to-patient distribution channels:Specialty pharmacy networks are bypassing traditional hospital procurement for chronic disease biologics, enabling device customization and adherence monitoring services.
Industry Challenges
- Combination product quality engineering talent:Cross-functional expertise spanning pharmaceutical GMP and ISO 13485 medical device standards remains scarce, elongating hiring cycles for device-drug development teams.
- HIPAA-GDPR data governance complexity:Connected autoinjectors transmitting dosing adherence data across United States and European jurisdictions face conflicting privacy architecture requirements, complicating cloud infrastructure design.
- Legacy fill-finish line retrofit costs:Existing aseptic processing equipment requires substantial capital redeployment to handle nested syringe tub formats and robotic handling systems for high-speed autoinjector assembly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injectable Drug Delivery Market |
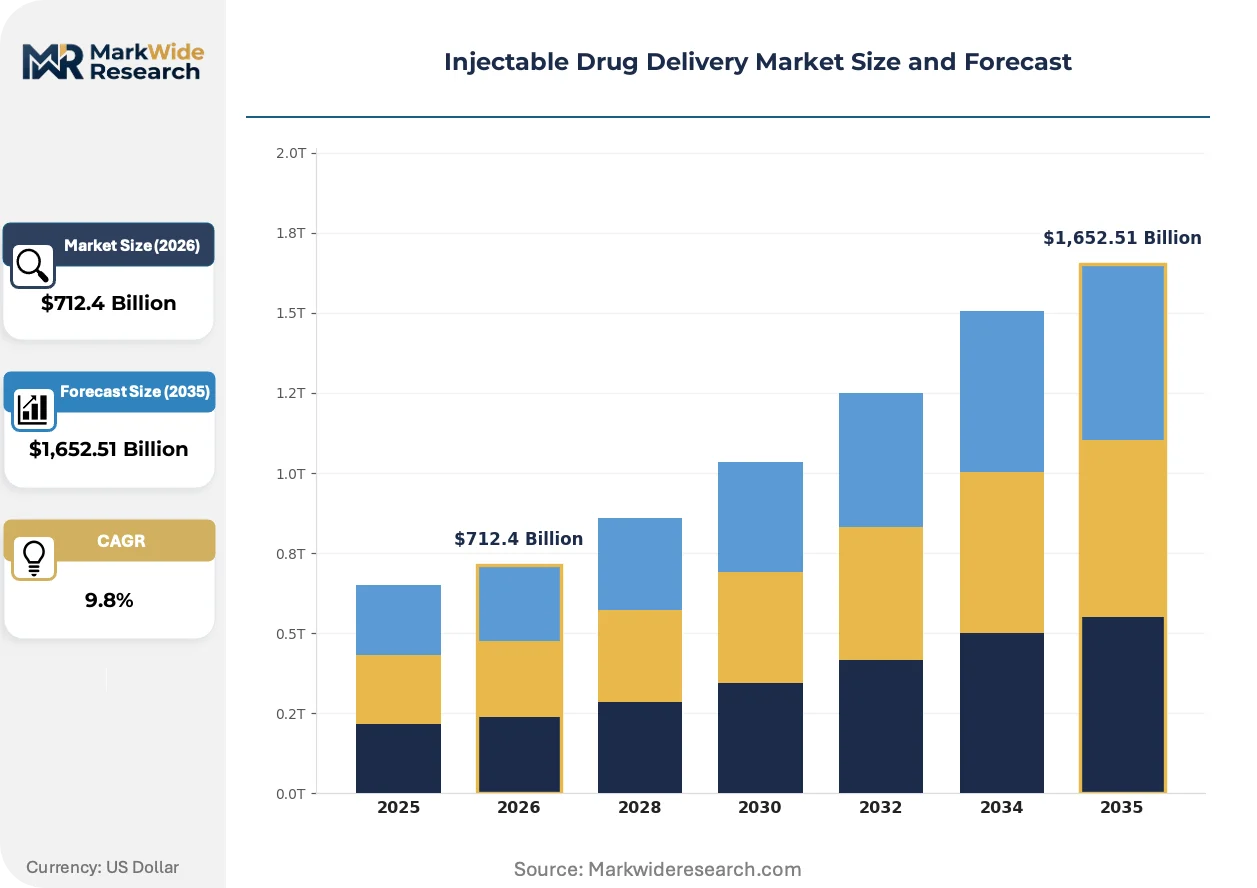
| Market Size in 2026 | $712.4 Billion |
| Market Size in 2035 | $1,652.51 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Pen Injectors, Infusion Pumps, Autoinjectors End User: Hospitals, Homecare, Clinics, Research Laboratories Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Intradermal Therapy Area: Oncology, Diabetes, Neurology, Vaccines |
| Companies Covered | Becton Dickinson and Company, Medtronic, Pfizer, Eli Lilly and Company, Sanofi, Gerresheimer, B. Braun Melsungen, Terumo Corporation, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injectable Drug Delivery Market Emerging Trajectories
Connected device ecosystems and material science advances are restructuring competitive advantage around data capture capabilities and supply chain control over specialized pharmaceutical-grade components.
Connected autoinjector platforms with embedded sensors and Bluetooth transmission are fragmenting the traditional device procurement model. Rheumatology and gastroenterology clinics are piloting adherence monitoring programs that integrate dosing data into electronic health records. This technology is fragmenting vendor relationships as pharmaceutical sponsors demand end-to-end data infrastructure partnerships rather than standalone hardware supply.
EMA MDR Annex I general safety and performance requirements are tightening post-market surveillance obligations for combination products. Device-drug system manufacturers must now maintain clinical evidence registries spanning the full product lifecycle, not just premarket submissions. Oncology autoinjector portfolios face the steepest compliance burden as EMA pharmacovigilance inspectors prioritize high-risk therapeutic areas.
Hospital purchasing consortia in the United States are consolidating injectable device procurement around single-source agreements with integrated fill-finish service providers. Group purchasing organizations are displacing fragmented multi-vendor sourcing for prefilled syringe and autoinjector combinations. This concentration is most visible in diabetes care, where pen injector contracts now bundle insulin supply with dedicated delivery hardware across integrated delivery networks.
Injectable Drug Delivery Market Segmentation
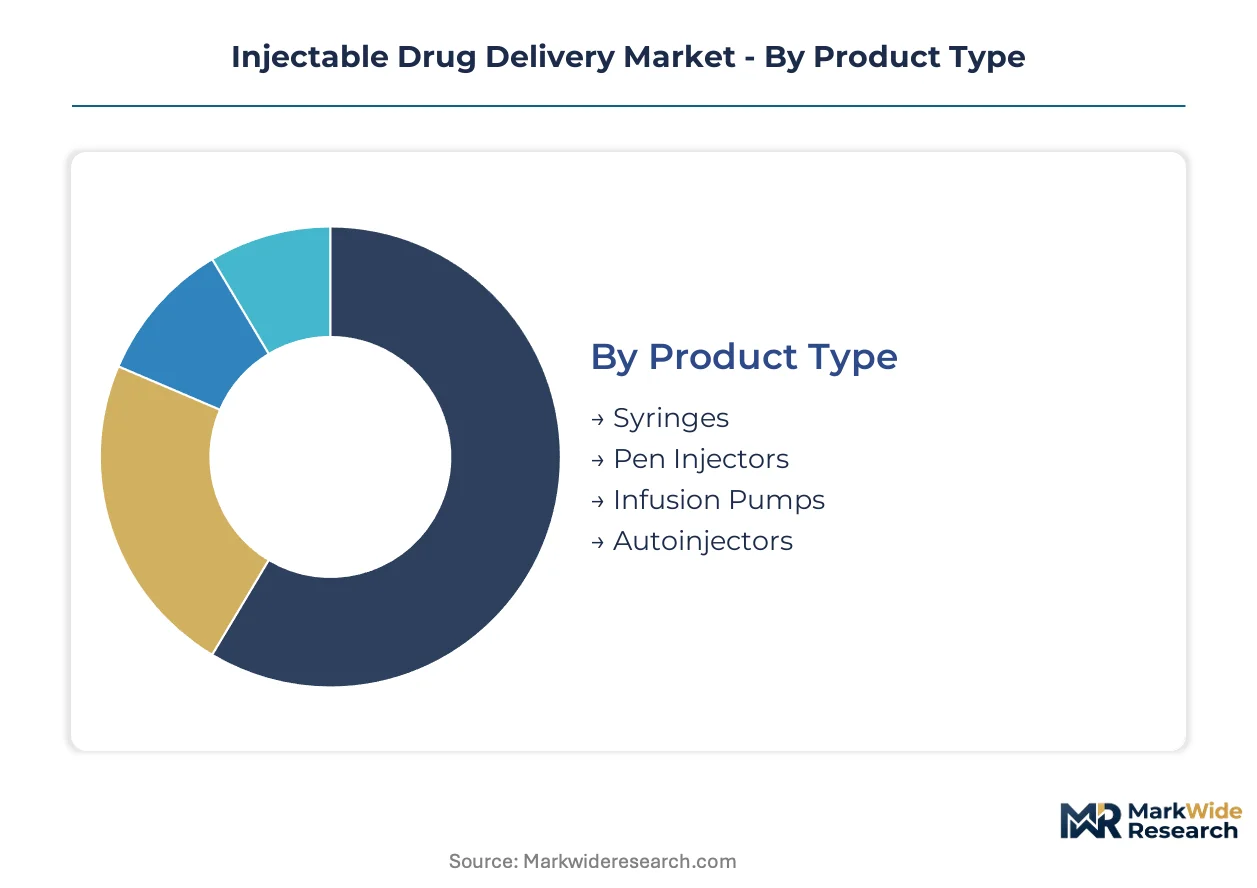
Injectable drug delivery segmentation reveals distinct procurement channels and clinical workflows governing device selection. Each dimension—product form, care setting, anatomical target, and therapeutic indication—carries unique regulatory pathways and reimbursement logic that shape vendor contracting strategies.
Product Type:
Channel distribution varies sharply across device categories, with hospital procurement consortia dominating high-volume syringe and infusion pump contracts while specialty pharmacy networks drive autoinjector and pen injector volumes for chronic disease management.
- Syringes:Borosilicate glass and COP barrel formats serve fill-finish operations at Becton Dickinson and Gerresheimer facilities. Demand concentrates in United States hospital systems and German clinic networks where bulk purchasing agreements standardize on luer-lock and safety-engineered designs for clinician-administered injections.
- Pen Injectors:Reusable and disposable insulin delivery systems dominate diabetes therapy with Eli Lilly and Novo Nordisk maintaining decades of dose-precision optimization. German and Japanese reimbursement frameworks now mandate pen injector coverage for Type 1 and Type 2 protocols, cementing installed base dominance.
- Infusion Pumps:Electromechanical large-volume devices anchor oncology and parenteral nutrition administration in United States academic medical centers.
- Autoinjectors:Spring-loaded and electronic wearable formats are displacing prefilled syringes for monoclonal antibody self-administration in rheumatology and gastroenterology.
Syringes dominate installed base. Autoinjectors are where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive hospital infrastructure from disposable-heavy homecare models, with reimbursement rates determining device sophistication at each level.
- Hospitals:Integrated delivery networks in the United States and university hospital chains in Germany deploy smart infusion pumps with dose-error reduction software and EHR connectivity. Capital budgets and group purchasing organization contracts favor multi-year service agreements over device ownership.
- Homecare:Ambulatory infusion services and patient self-administration protocols are expanding fastest in Japan and United States markets where specialty pharmacy networks manage biologic delivery. Reimbursement codes for subcutaneous administration are compressing hospital revenue and shifting device procurement to direct-to-patient channels.
- Clinics:Outpatient infusion centers in Germany and United States rely on prefilled syringe and autoinjector combinations for rapid patient turnover.
- Research Laboratories:Preclinical and clinical trial supply chains demand custom fill-finish configurations and nested tub packaging for investigational biologics.
Hospitals anchor capital expenditure. Homecare is climbing the fastest.
Delivery Mode:
Application requirements dictate material selection and device engineering, with protein stability and absorption kinetics driving route-specific formulation strategies.
- Subcutaneous:Large-volume wearable injectors and high-concentration monoclonal antibody formulations are enabling 5-10 mL administrations outside clinical settings. Oncology and immunology indications in United States and Japan are standardizing subcutaneous protocols to reduce infusion center burden.
- Intravenous:Precision infusion pumps with flow-rate sensors maintain therapeutic windows for chemotherapy and biologic loading doses in hospital settings. German and United States oncology wards require air-in-line detection and anti-free-flow mechanisms under device safety regulations.
- Intramuscular:Vaccine delivery in United States public health programs and Japanese routine immunization schedules depends on prefilled syringe and autoinjector stockpiling.
- Intradermal:Microneedle arrays and specialized syringes serve tuberculosis testing and emerging vaccine platforms in research-heavy clusters.
Intravenous dominates acute care infrastructure. Subcutaneous is gaining share fastest.
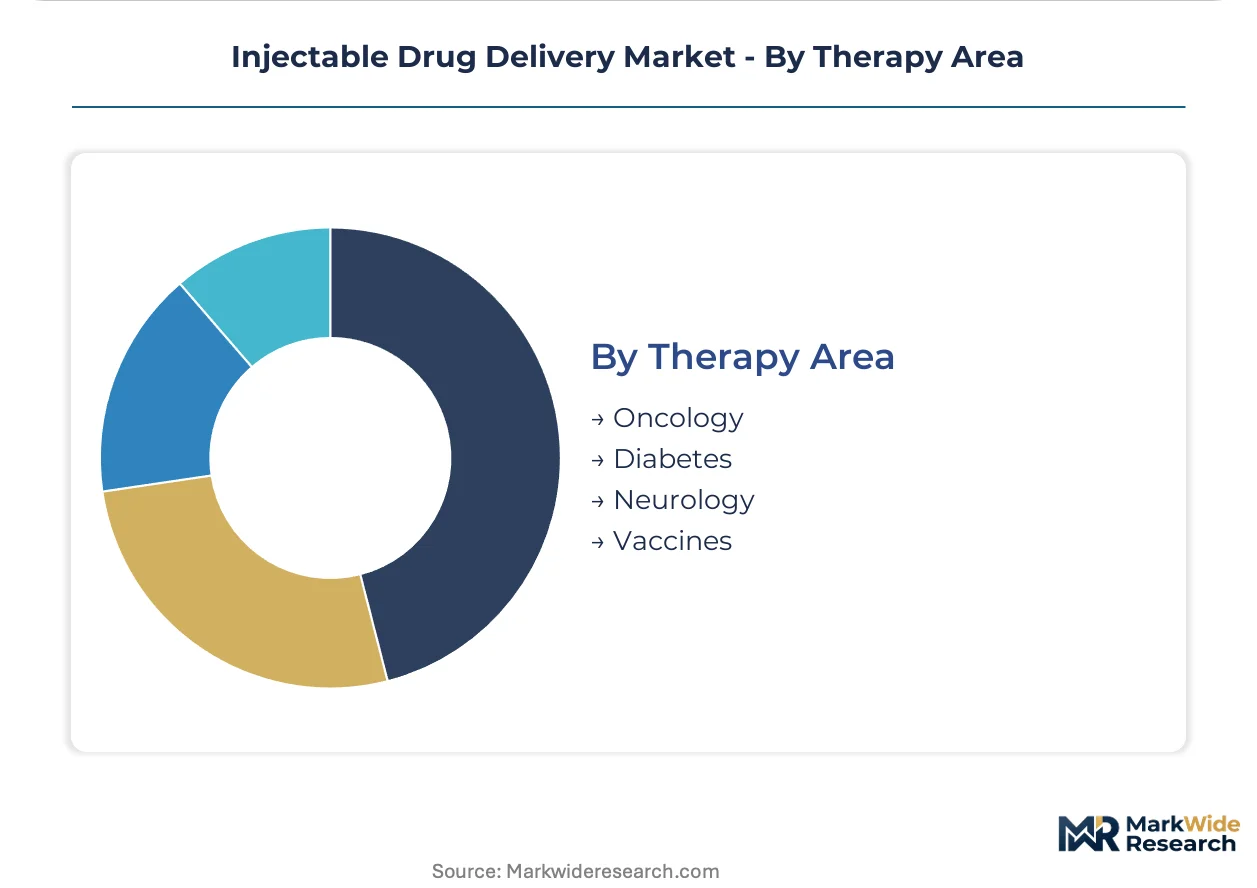
Therapy Area:
Customer type differentiation separates chronic disease management platforms from acute intervention devices, with adherence monitoring requirements fragmenting vendor relationships.
- Oncology:Combination product regulations under FDA 21 CFR 4 and EMA MDR Annex I impose the steepest compliance burden. United States and German oncology autoinjector portfolios require clinical evidence registries spanning full product lifecycles.
- Diabetes:Pen injector and insulin pump ecosystems sustain decades of patient loyalty through dose-logging apps and pharmacy benefit integration. United States and Japan reimbursement frameworks lock in multi-year contracts with integrated delivery networks.
- Neurology:Multiple sclerosis and migraine therapies are migrating to autoinjector and wearable bolus formats for home administration in United States and German markets.
- Vaccines:Pandemic-scaled fill-finish capacity at Pfizer and Moderna facilities has reconfigured prefilled syringe supply chains toward multi-dose vial alternatives for global immunization programs.
Diabetes anchors consumer device volumes. Oncology is where premium pricing concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical glass manufacturers export borosilicate tubing to United States fill-finish networks, while Japanese device specialists supply autoinjector assemblies to German and United States biologics sponsors.
United States
Specialty pharmacy networks and integrated delivery systems drive autoinjector procurement for rheumatology and gastroenterology biologics. FDA 21 CFR 4 combination product regulations enforce unified device-drug validation protocols. Greater Boston and San Diego clusters host biologics sponsors contracting directly with fill-finish service providers for nested syringe tub formats.
Germany
University hospital chains and outpatient infusion centers standardize on prefilled syringe and safety-engineered needle systems. EU MDR Annex I technical documentation requirements extend recertification timelines for combination products. North Rhine-Westphalia pharmaceutical tubing furnaces anchor European borosilicate supply for prefilled syringe barrel production.
Japan
Ambulatory infusion services and patient self-administration protocols expand fastest among aging populations requiring chronic disease management. PMDA mandates localized clinical bridging studies for foreign-manufactured injectables, compressing market entry for FDA-cleared devices. Kanto region device manufacturers supply spring-loaded autoinjector platforms to domestic biologics sponsors.
United Kingdom
NHS procurement frameworks consolidate pen injector contracts for diabetes therapy across integrated care systems. MHRA post-Brexit regulations maintain alignment with EU MDR general safety requirements while streamlining national approval pathways. London and Southeast England clusters concentrate biologics development teams seeking device-drug combination expertise.
India
CDSCO regulatory harmonization with ICH guidelines accelerates foreign-manufactured injectable approvals for domestic biologics manufacturing. Maharashtra and Gujarat pharmaceutical zones expand fill-finish capacity for export-oriented monoclonal antibody production. Contract development organizations in Hyderabad and Bangalore source prefilled syringe components from German and United States tubing suppliers.
Injectable Drug Delivery Market Vendor Landscape
Listed leaders compete with private specialists across device-drug combination expertise and fill-finish capacity ownership. The vendor base stratifies into three tiers: integrated healthcare conglomerates controlling glass-to-needle supply chains, pharmaceutical sponsors captive-producing delivery devices for proprietary biologics, and specialized component fabricators supplying barrel, plunger, and needle assemblies. Dominant competitive moves include backward integration into pharmaceutical tubing production and strategic partnerships between device manufacturers and biologics sponsors for co-development of combination products.
Among United States-based healthcare conglomerates, Becton Dickinson and Company exemplifies vertical control across glass barrel and needle assembly operations. German specialist Gerresheimer AG occupies a position anchoring European supply through dedicated pharmaceutical tubing facilities. Pharmaceutical sponsor Pfizer represents the captive-production archetype, leveraging pandemic-scaled fill-finish networks for device-drug integration.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Medtronic |
| Pfizer |
| Eli Lilly and Company |
| Sanofi |
| Gerresheimer |
| B. Braun Melsungen |
| Terumo Corporation |
| AstraZeneca |
| Others |
Supply Flow & Price Mechanics
Ninety-day safety stock requirements for borosilicate tubing and COP barrel components concentrate negotiating leverage with German and Italian furnace operators, translating directly into premium pricing tiers for prefilled syringe manufacturers serving FDA and EMA combination product markets.
Pricing Analysis
Hospital procurement consortia anchor contract-based long-term offtake structures for high-volume syringe and infusion pump purchases, while specialty pharmacy networks drive spot-market premiums for autoinjector customization. Price differentiation separates FDA-validated combination product tiers from standard disposable formats, with silicone oil compatibility certification commanding substantial uplifts. Cost compression in standard syringe categories intensifies as group purchasing organizations consolidate vendor panels. Research laboratories exhibit lowest price sensitivity due to investigational biologic timelines, whereas integrated delivery networks impose aggressive annual rebate requirements.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Japanese spring-loaded autoinjector assemblies destined for United States fill-finish networks. Pharmaceutical-grade borosilicate supply concentrates in Germany and Italy, while COP resin production centers on Japan and United States specialty chemical facilities. The supply chain rests on concentrated pharmaceutical tubing furnaces, silicone oil lubricant formulations, and precision needle grinding capacity. Single-source vulnerability in European glass tubing creates structural risk for prefilled syringe barrel production. Distribution runs through hospital purchasing consortia, specialty pharmacy direct-to-patient channels, and contract fill-finish service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected autoinjector platforms are restructuring this market around data-capture ecosystems, with Bluetooth-enabled adherence monitoring and EHR interoperability emerging as the decisive interoperability shift for vendor selection and reimbursement access.
For Market Incumbents: Fortify fill-finish capacity ownership through backward integration into pharmaceutical tubing production or captive supply agreements with German furnace operators. Combination product validation expertise under FDA 21 CFR 4 represents a defendable moat against contract manufacturers lacking device-drug cross-functional teams. Prioritize HIPAA-GDPR data architecture investments to capture connected device adherence monitoring contracts from rheumatology and gastroenterology clinics. For New Entrants and Emerging Players: Differentiate on wearable bolus injector electromechanical engineering for large-volume subcutaneous delivery in neurology and immunology indications. White-space targets include Japan PMDA bridging study facilitation services for FDA-cleared devices and direct-to-patient specialty pharmacy distribution partnerships bypassing hospital procurement. The most penetrable segment is ambulatory infusion services for aging populations in United States and Japanese homecare markets. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical sponsors' captive device divisions seeking operational focus on core biologic pipelines. Long-term viability favors contract development organizations with integrated fill-finish and autoinjector assembly capabilities spanning nested syringe tub formats and robotic handling systems. Watch for EMA MDR Annex I post-market surveillance obligation enforcement as the inflection indicator for compliance-cost-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Combination Product Co-Development Partnership | Biologics sponsors lock in device-drug validation pathways under FDA 21 CFR 4 unified submissions. |
| Pharmaceutical Tubing Furnace Acquisition | Backward integration secures borosilicate barrel supply for prefilled syringe production networks. |
| Connected Device Data Infrastructure Buildout | Bluetooth-enabled adherence monitoring captures EHR integration contracts from specialty clinics. |
| Japan PMDA Bridging Study Harmonization | Streamlined approval pathways compress market entry timelines for FDA-cleared autoinjector platforms. |
| Specialty Pharmacy Direct Distribution Channel | Direct-to-patient models bypass hospital GPO contracts for chronic disease biologic delivery. |
Methodological Framework
Desk research of FDA 510(k) filings, EMA combination product registrations, and hospital procurement database records preceded structured interviews with regulatory affairs directors, fill-finish operations managers, and specialty pharmacy network executives. Primary fieldwork captured device-drug validation timelines, material specification migration patterns, and connected device data governance practices. Secondary validation drew from ISO 13485 certification registries, GPO contract announcements, and pharmacovigilance inspection reports. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Variance decomposition across product type, end user, delivery mode, and therapy area segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base erosion rates, replacement cycle compression, and biologics pipeline conversion to self-administration formats. Modeled inputs included monoclonal antibody volume forecasts, EU MDR recertification timeline assumptions, and Japan PMDA bridging study completion rates for foreign-manufactured devices.
Decision-makers should treat outputs as directional under assumptions of sustained FDA-EMA regulatory harmonization and stable specialty pharmacy reimbursement codes; material deviation in combination product enforcement stringency or homecare infusion protocol coverage would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Cyclotron Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Blood Lancet Market
Medical Devices
Cervical Dilators Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Mexico Artificial Organs and Bionic Implants Market
Medical Devices
Deflectable Catheters Market
Medical Devices
India Clear Aligners Market
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Global Hernia Repair Devices Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Global Defibrillators Market
Medical Devices
Ambulatory Aids Market
Medical Devices
Manometry System Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market