
 Manual Wheelchair Market | 2026-2036
Manual Wheelchair Market Size, Share, and Industry Trends Forecast 2026-2036
Manual Wheelchair Market Analysis
Multi-source component procurement is broadening across the manual wheelchair supply chain as manufacturers diversify beyond captive frame production. Invacare Corporation leverages its North American manufacturing footprint to sustain domestic fulfillment capacity. Sunrise Medical Inc. anchors its competitive stance through European distribution density and titanium-frame specialization. Yuwell Medical competes aggressively on aluminum chassis cost structures across Asian markets.
A manual wheelchair constitutes a human-powered mobility device comprising a seating system, wheel assembly, and propulsion mechanism, typically fabricated from aluminum or steel tubing with pneumatic or solid tires, designed to transport individuals with impaired ambulatory function. Lightweight wheelchair configurations command premium positioning due to caregiver ergonomics and user self-propulsion efficiency, while standard wheelchair variants occupy volume-driven institutional procurement channels. Folding wheelchair designs dominate home care and travel segments where storage constraints dictate purchase decisions, and titanium material grades concentrate among active-user custom prescriptions where durability-to-weight ratios justify elevated price points.
The FDA regulates manual wheelchairs as Class II medical devices under 21 CFR 890.3850, mandating substantial equivalence or premarket notification for market entry, while the EU MDR requires notified-body conformity assessment and clinical evaluation for CE marking across member states. ISO 7176 technical standards govern static load testing, fatigue durability, and dimensional stability, directly shaping manufacturer R&D allocation and quality-system investments. Stakeholders must monitor evolving reimbursement coding under Medicare and national health systems, as payment determination increasingly ties to outcome metrics and preventive pressure-injury reduction.
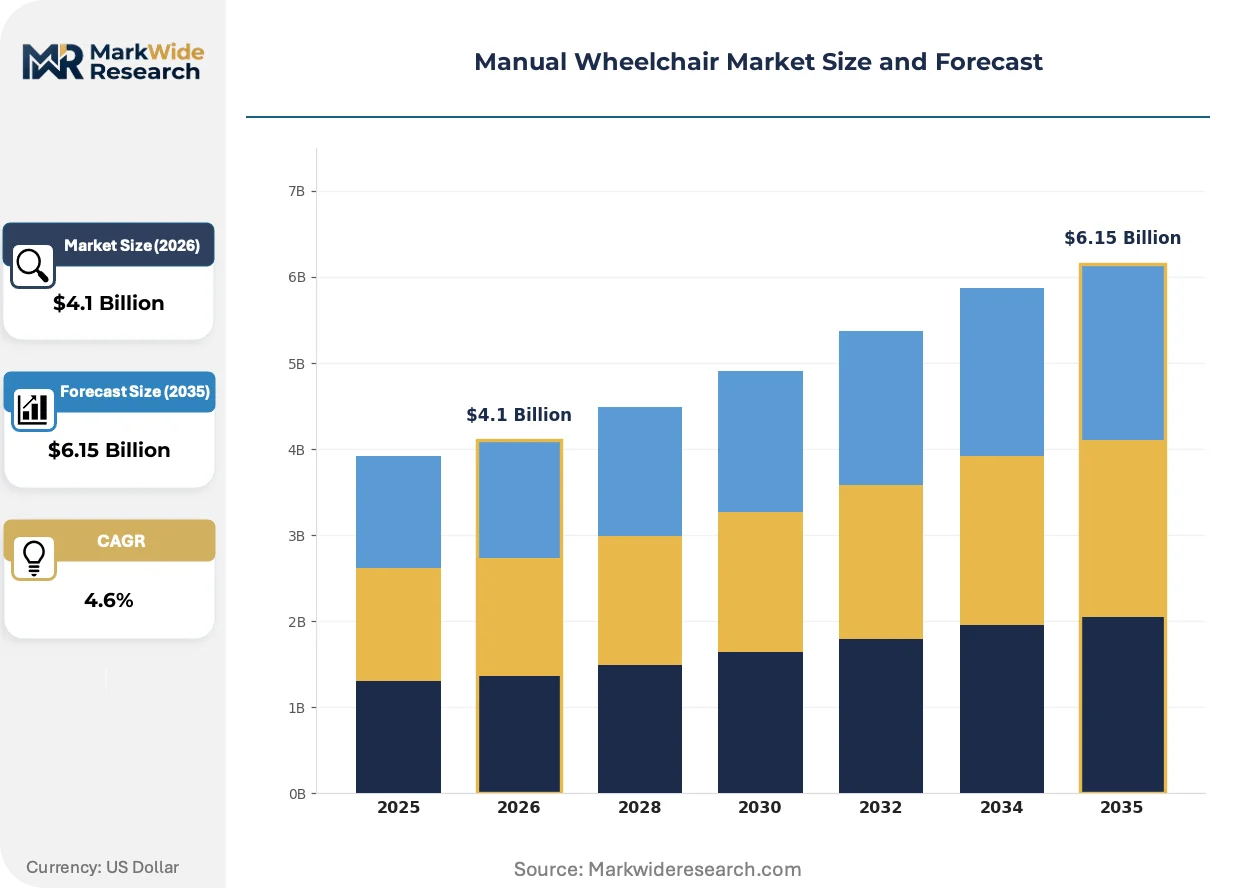
Market Dynamics
Lightweight material substitution and caregiver ergonomics mandates are compressing demand toward aluminum and titanium configurations, while institutional procurement consolidation favors standardized, volume-priced models over custom prescriptions.
Growth Catalysts
- Aging demographics in Japan:The country's super-aged population structure sustains replacement-cycle demand for mobility assistance devices, with municipal long-term care insurance expanding eligibility criteria.
- EU MDR clinical evaluation requirements:Stricter notified-body conformity assessment elevates barrier-to-entry for marginal suppliers, concentrating certified production among established manufacturers.
- Titanium-grade durability specifications:Active-user segments prioritize frame longevity-to-weight ratios, pulling R&D investment toward aerospace-derived tubing alloys and precision welding processes.
Market Restraints
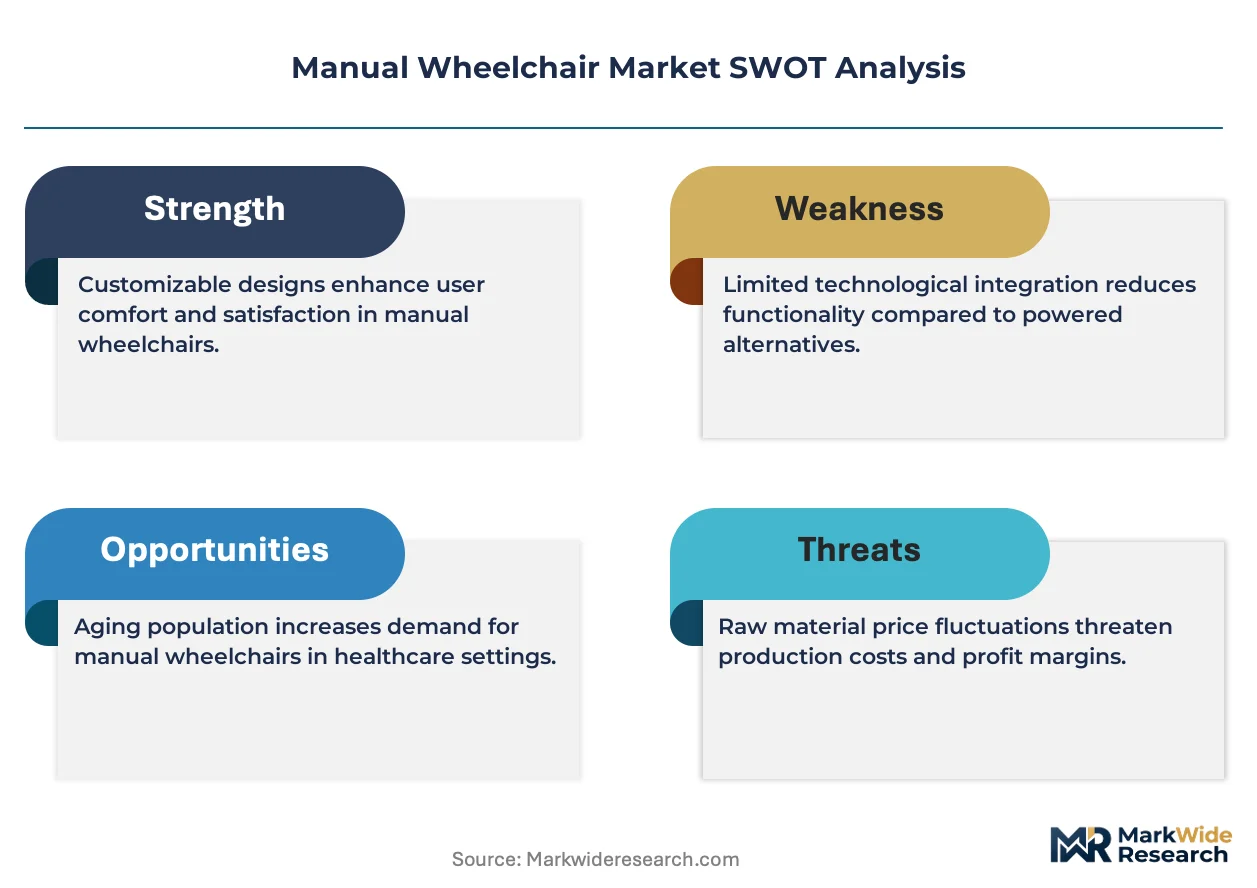
- Aluminum price volatility:Raw material input costs for chassis fabrication fluctuate with London Metal Exchange pricing, compressing margin predictability for mid-tier producers.
- Supply concentration in Chinese component manufacturing:Wheel casters, bearings, and quick-release axles concentrate among Zhejiang and Guangdong province suppliers, exposing procurement to logistics disruption.
- Reimbursement ceiling rigidity:Medicare's durable medical equipment fee schedules cap allowable charges for standard wheelchair configurations, constraining premium positioning in institutional channels.
Strategic Opportunities
- Indian home care expansion:The country's Ayushman Bharat health infrastructure investments and urban nuclear family structures create unmet demand for lightweight folding configurations suited to residential storage constraints.
- Carbon fiber composite convergence:Bicycle industry manufacturing techniques transfer to wheelchair frame production, enabling sub-5-kilogram transport weights for air travel segments.
- Direct-to-consumer digital channels:Specialized e-commerce platforms bypass durable medical equipment distributor markups, capturing margin and shortening fulfillment timelines for self-pay buyers.
Industry Challenges
- Biomechanical customization expertise scarcity:Seating and positioning specialists require cross-training in pressure mapping and spinal orthotics, lengthening workforce development timelines.
- ISO 7176 fatigue testing protocol compliance:Accelerated life-cycle validation for folding mechanisms demands capital-intensive test rig investment, disadvantaging smaller fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manual Wheelchair Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Wheelchair, Lightweight Wheelchair, Recliner Wheelchair, Folding Wheelchair End User: Hospitals, Rehabilitation Centers, Home Care, Nursing Homes Material: Aluminum, Steel, Titanium, Composite Feature: Adjustable Footrests, Anti-Tippers, Removable Armrests, Padded Seat |
| Companies Covered | Ottobock Healthcare, Karman Healthcare, Invacare Corporation, Yuwell Medical, TiLite, Sunrise Medical Inc., Karma Medical, Kaiyang Medical, Permobil AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manual Wheelchair Market Emerging Trajectories
Active-user customization and travel-portability requirements are fragmenting product architectures away from institutional standardization, while regulatory harmonization pressures reshape quality system investments across manufacturing footprints.
Titanium-alloy frame technology is converging with additive manufacturing processes to enable patient-specific geometry optimization. Custom wheelchair clinics in Germany and the United States adopt scan-to-fit workflows for competitive athletes and spinal cord injury users. This convergence is compressing lead times from six-week fabrication cycles to ten-day production windows while elevating price positioning.
The EU MDR's post-market surveillance requirements now mandate systematic collection of clinical performance data for Class IIa medical devices. Manufacturers must maintain electronic patient registries tracking pressure injury incidence and frame fatigue failures. German and French notified bodies are enforcing stricter technical documentation review timelines, extending CE marking cycles by four to six months for folding wheelchair variants.
Institutional procurement consolidation among United States hospital systems and German rehabilitation clinic chains is displacing distributor-mediated purchasing. Buyers now negotiate frame-and-accessory bundles directly with manufacturers, extracting volume discounts and dedicated inventory commitments. This concentration is most visible in Veterans Health Administration procurement, where national formulary standardization favors three-supplier frameworks over fragmented vendor panels.
Manual Wheelchair Market Segmentation
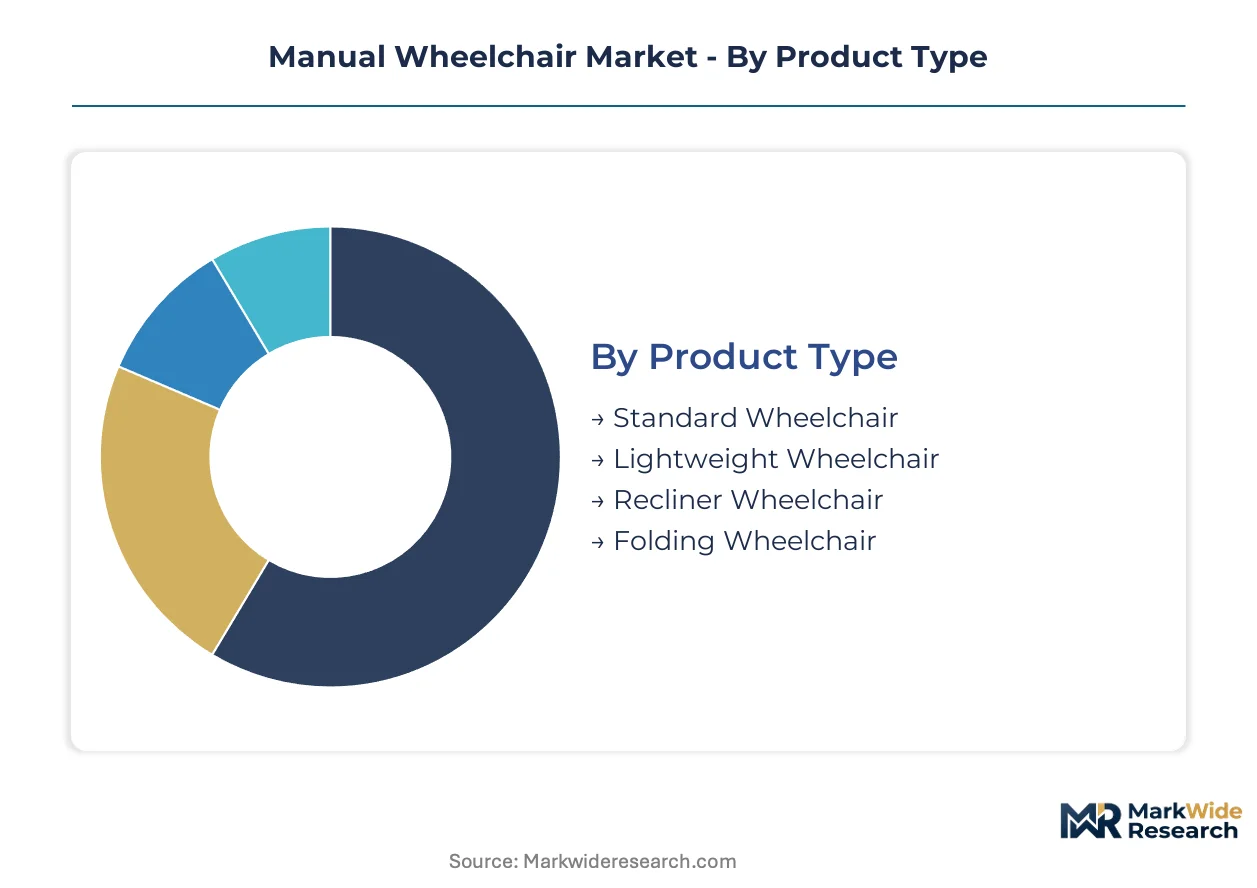
Product architecture in manual wheelchairs fragments across performance tiers, care settings, material grades, and ergonomic specifications. Each segmentation axis shapes procurement behavior, reimbursement pathways, and manufacturer R&D allocation differently.
Product Type:
Buyers differentiate primarily by weight-class requirements and storage constraints rather than clinical indication alone.
- Standard Wheelchair:Steel-tubing construction with fixed or swing-away footrests and 18-inch seat width defaults. Institutional procurement channels in the United States and Germany concentrate demand here, though Medicare fee schedule ceilings compress margin realization for suppliers.
- Lightweight Wheelchair:Aluminum frame configurations under 13 kilograms enable caregiver transport efficiency and limited user self-propulsion. Japanese municipal long-term care insurance expansion and Indian urban nuclear family structures are pulling demand fastest into this tier.
- Recliner Wheelchair:Backrest articulation to 180 degrees with elevating leg rests for pressure redistribution. Post-acute and bariatric applications dominate.
- Folding Wheelchair:X-frame collapse mechanisms for vehicle trunk storage and air travel compliance. Home care and travel retail segments prioritize this geometry.
Standard wheelchair configurations lead volumes today; lightweight wheelchair demand is climbing the fastest.
End User:
Procurement authority and reimbursement mechanics diverge sharply across institutional versus residential channels.
- Hospitals:Acute-care discharge planning drives short-term rental and purchase decisions, with materials management departments negotiating frame-and-accessory bundles directly with manufacturers. German rehabilitation clinic chains and United States hospital systems are consolidating vendor panels.
- Home Care:Family-paid or insurance-reimbursed purchases where storage constraints and caregiver physical capacity dictate lightweight folding selection. India's Ayushman Bharat infrastructure investments and Japan's super-aged municipal insurance programs are expanding eligibility.
- Rehabilitation Centers:Seating and positioning specialists prescribe custom configurations with pressure mapping and spinal orthotics integration.
- Nursing Homes:Volume-driven standardized procurement with durability emphasis for multi-user environments.
Hospital procurement leads volumes today; home care distribution channels are expanding most quickly.
Material:
Weight-to-strength ratios and raw material input costs structure competitive positioning across price tiers.
- Aluminum:6061-T6 or 7000-series tubing delivers the dominant cost-performance intersection for lightweight configurations. London Metal Exchange price volatility compresses margin predictability for mid-tier fabricators sourcing chassis materials.
- Titanium:Aerospace-derived Ti-3Al-2.5V tubing enables sub-10-kilogram active-user frames with superior fatigue life. German and United States custom clinics adopt scan-to-fit additive manufacturing workflows for competitive athletes.
- Steel:Chromoly or carbon steel tubing for institutional standard wheelchairs where capital cost minimization outweighs transport weight concerns.
- Composite:Carbon fiber layups transferring bicycle industry techniques for sub-5-kilogram transport weights in premium travel segments.
Aluminum chassis production leads volumes today; titanium-grade specifications are gaining share fastest.
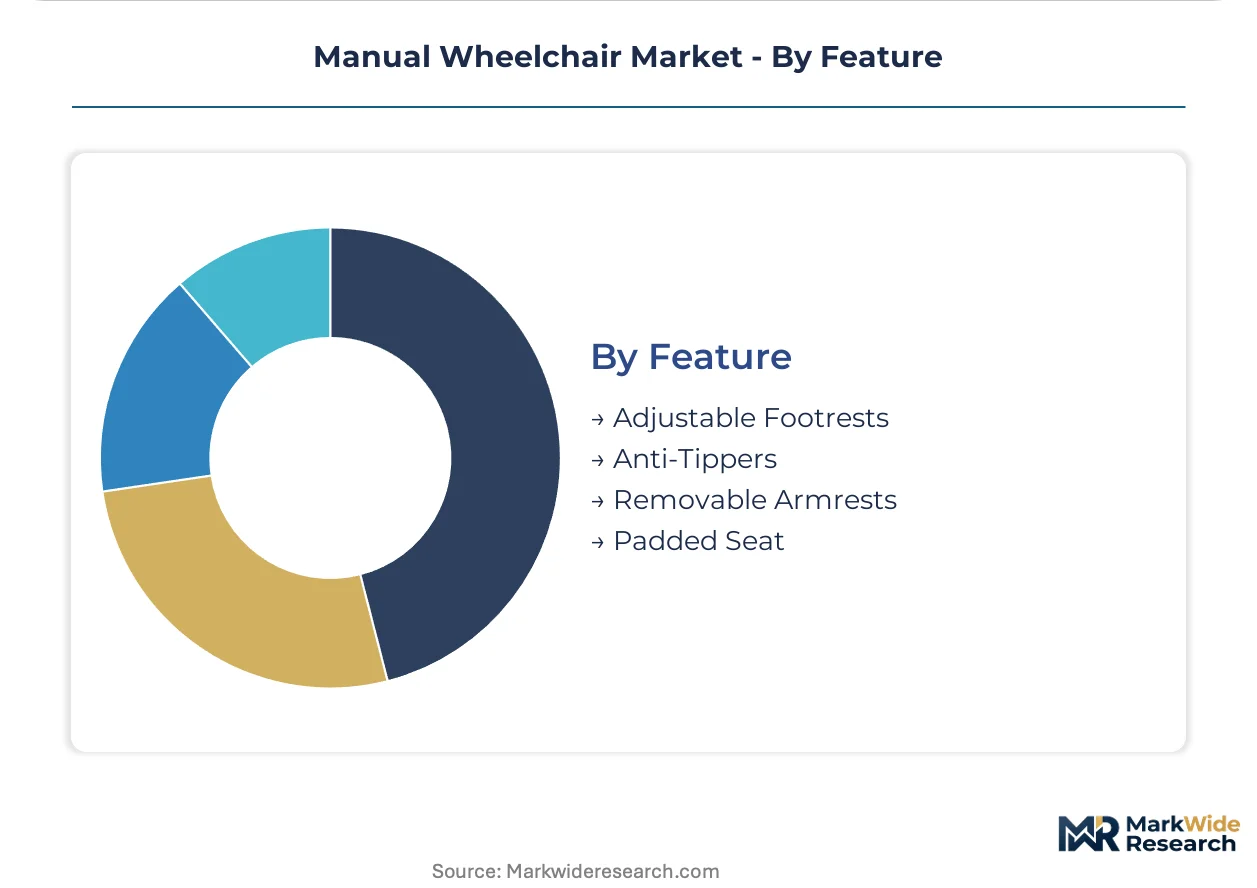
Feature:
Modularity and safety accessories differentiate configurations within otherwise similar frame architectures.
- Adjustable Footrests:Tool-free length and angle modification for user anthropometric variation and pressure injury prevention.
- Anti-Tippers:Rear-wheel extension bars preventing backward instability on inclines; mandatory in United States Veterans Health Administration procurement.
- Removable Armrests:Flip-back or detachable designs enabling lateral transfers and table access for active users.
- Padded Seat:Contoured cushion systems with pressure-relieving foam or gel inserts; ISO 7176 static load testing governs durability validation.
Adjustable footrests lead feature penetration today; anti-tipper specifications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EU MDR compliance costs drive frame fabrication toward lower-cost jurisdictions while finished-goods assembly concentrates near end markets to satisfy just-in-time procurement mandates.
United States
Veterans Health Administration national formulary standardization sustains institutional procurement volumes for standard configurations. FDA 21 CFR 890.3850 Class II device classification mandates substantial equivalence pathways that lengthen market entry timelines for foreign suppliers. Manufacturing clusters in Ohio and Pennsylvania anchor domestic frame production capacity to serve Medicare-reimbursed channels.
Germany
Super-aged municipal demographics and statutory long-term care insurance expansion sustain replacement-cycle demand for lightweight titanium configurations. BfArM notified-body oversight under EU MDR extends CE marking cycles by four to six months, compressing margin realization for folding wheelchair variants. Custom fabrication clinics in Bavaria and Baden-Württemberg adopt scan-to-fit additive manufacturing workflows for competitive athletes.
Japan
Municipal long-term care insurance eligibility expansion drives home care procurement of sub-13-kilogram aluminum folding models for nuclear family caregivers. PMDA device classification aligns with global harmonization initiatives, streamlining approval pathways for established manufacturers. Industrial concentration in the Chubu region around Nagoya sustains precision tubing and bearing supply chains.
China
Domestic aging demographics and Ayushman Bharat-equivalent rural health infrastructure investments create latent demand for cost-optimized standard configurations. NMPA Class II medical device registration requires in-country clinical testing, elevating barrier-to-entry for imported brands. Component manufacturing clusters in Zhejiang and Guangdong provinces concentrate wheel casters, bearings, and quick-release axle production.
India
Ayushman Bharat health infrastructure investments and urban nuclear family structures generate unmet demand for lightweight folding configurations suited to residential storage constraints. CDSCO medical device rules mandate import license and quality system documentation for foreign suppliers. Fabrication activity concentrates in Gujarat and Maharashtra for aluminum chassis assembly serving South Asian export markets.
Manual Wheelchair Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue carbon fiber composite specialization and direct-to-consumer digital channels. The vendor base stratifies across three maturity tiers: legacy diversified medical device conglomerates with captive distribution, mid-scale regional specialists with material-grade differentiation, and niche custom fabricators serving active-user prescriptions. Competitive moves center on backward integration into titanium tubing supply and strategic partnerships with seating-and-positioning clinics.
Among North American diversified manufacturers, Invacare Corporation and Sunrise Medical Inc. exemplify scale-driven archetypes with established institutional procurement relationships. TiLite occupies a position within the premium custom-fabrication segment where aerospace-derived material specifications command price premiums. Yuwell Medical represents cost-optimized Asian manufacturing capacity serving volume-driven developing market channels.
| Leading Market Players |
|---|
| Ottobock Healthcare |
| Karman Healthcare |
| Invacare Corporation |
| Yuwell Medical |
| TiLite |
| Sunrise Medical Inc. |
| Karma Medical |
| Kaiyang Medical |
| Permobil AB |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange aluminum pricing cascades through manual wheelchair supply chains, compressing margin buffers for mid-tier fabricators while concentrating pricing power among titanium-grade specialists with aerospace-derived supply contracts.
Pricing Analysis
Input-cost pass-through from raw material volatility structures a three-tier pricing architecture across premium, standard, and economy levels. Titanium-frame configurations command substantial premiums due to aerospace tubing scarcity and ISO 7176 fatigue certification investment, while Medicare fee schedule ceilings rigidify pricing for standard steel institutional models. Pricing pressure stems from reimbursement ceiling rigidity in United States institutional channels, compressing realization for volume suppliers. Home care buyers exhibit highest price sensitivity, whereas active-user custom clinics demonstrate inelastic demand for scan-to-fit additive manufacturing workflows.
Supply Chain Analysis
Reverse-logistics flows for frame refurbishment and component remanufacturing remain underdeveloped, exposing manufacturers to full replacement cost burdens. Component manufacturing concentrates in China's Zhejiang and Guangdong provinces for wheel casters, bearings, and quick-release axles, while frame fabrication clusters in Ohio, Pennsylvania, and Germany's Chubu region. Raw material dependencies rest on 6061-T6 aluminum tubing, Ti-3Al-2.5V aerospace alloys, and pneumatic tire compounds. Single-source vulnerability in Chinese bearing supply creates structural risk exposure. Distribution runs through durable medical equipment distributors, though direct-to-consumer digital channels are displacing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The manual wheelchair market functions as a geographic-arbitrage play where EU MDR compliance costs in Germany and France exceed United States FDA pathway expenses by substantial margins, redirecting new entrant investment toward North American regulatory jurisdictions.
For Market Incumbents: Anticipate margin compression from carbon fiber composite entrants by deepening backward integration into titanium tubing supply and securing exclusive seating-clinic partnerships. Certification investment for EU MDR post-market surveillance registries represents a critical defensive lever against notified-body bottleneck delays.
For New Entrants and Emerging Players: Indian urban nuclear family caregivers represent an underserved buyer archetype with unmet demand for sub-13-kilogram folding configurations. Direct-to-consumer digital platforms offer the most penetrable channel, bypassing distributor markups while capturing self-pay margin. Target lightweight aluminum folding models through specialized e-commerce fulfillment.
For Investors and Strategic Acquirers: Asymmetric upside sits with custom-fabrication specialists possessing scan-to-fit additive manufacturing capabilities and aerospace tubing supply contracts. Long-term viability hinges on clinical outcome data integration for reimbursement negotiation leverage. Monitor EU MDR CE marking cycle extensions as inflection indicator for competitive consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Tubing | Aerospace-derived Ti-3Al-2.5V supply contracts insulate margin from London Metal Exchange volatility. |
| CE Marking Pathway Acceleration | German and French notified-body relationships compress EU MDR conformity assessment timelines. |
| Hospital System Partnership | United States Veterans Health Administration formulary inclusion secures institutional volume commitment. |
| Direct-to-Consumer Digital Launch | Self-pay channels capture margin otherwise absorbed by durable medical equipment distributor markups. |
| Reimbursement Strategy Investment | Pressure injury reduction outcome data strengthens Medicare coding negotiation position. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and seating-and-positioning specialists with secondary validation against FDA 510(k) filings, CMS Medicare durable medical equipment fee schedules, ISO 7176 technical documentation, and EU MDR notified-body public assessment reports. Bottom-up patient-flow modeling and top-down procurement spend analysis were triangulated for segment sizing.
Segment-weighting approaches distributed value and volume across product type, material grade, end-user channel, and geographic regulatory cluster dimensions throughout the forecast period. CAGRs were derived from replacement-cycle demand modeling, demographic projection alignment, and reimbursement elasticity estimation. Titanium-grade adoption curves and carbon fiber manufacturing transfer rates from bicycle industry served as industry-specific forecast inputs.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time Medicare claims data introduce uncertainty bands around home care volume estimates. Forecasts reflect documented assumptions regarding EU MDR implementation timelines and aluminum price trajectory stability. Practitioners should monitor notified-body capacity constraints and London Metal Exchange aluminum volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Pleural Catheters Market
Medical Devices
Germany Spinal Surgery Devices Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
Global Breast Implants Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Global Bone Cement Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
Allergic Rhinitis Treatment Device Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Global Vaginal Sling Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Video Dermatoscope Market
Medical Devices
Dissolving Microneedle Eye Patch Market