
 Latin America Implantable Medical Devices Market | 2026-2036
Latin America Implantable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Implantable Medical Devices Market Intelligence
Brazil's Southeast is rewriting implantable device procurement patterns across Latin America. Medtronic plc leverages its established cardiac rhythm management infrastructure to sustain catheter lab partnerships in São Paulo and Rio de Janeiro. Abbott anchors neuromodulation growth through its deep spinal cord stimulation presence in Brazilian teaching hospitals. Boston Scientific Corporation differentiates via drug-eluting stent portfolios aligned with ANVISA's accelerated review pathways for coronary interventions.
Implantable medical devices are engineered systems designed for long-term residence within human tissue, typically incorporating biocompatible alloys, polymers, or biological coatings and manufactured under ISO 13485 quality management protocols with sterilization validation per ISO 11137. These devices restore physiological function, deliver therapeutics, or provide structural support across cardiology, orthopedics, neurology, and urology applications. Cardiac devices occupy the dominant revenue position given the prevalence of arrhythmia and heart failure interventions across Latin American tertiary centers, while bioresorbable implants represent the fastest-expanding technology segment as absorbable scaffolds reduce long-term complications in younger patient cohorts. Hospitals command the primary end-user channel, though ambulatory surgical centers are capturing share for routine orthopedic and urological implant procedures where minimally invasive techniques shorten recovery windows.
ANVISA governs pre-market registration and post-market surveillance for implantable devices in Brazil, while Mexico's national pharmaceutical regulator enforces NOM standards for sterile medical products; both frameworks mandate clinical evidence packages that shape manufacturer market entry timelines and localization requirements. The EU MDR's extraterritorial influence persists as Brazilian and Mexican reference laboratories align biocompatibility testing with updated European standards to facilitate dual-market approvals. Stakeholders must monitor how ANVISA's pending risk-based reclassification of neurostimulators alters clinical trial obligations and competitive positioning for active implantable portfolios across the region.
Market Dynamics
ANVISA's 2023 risk-based reclassification of neurostimulators is compressing clinical trial timelines and forcing manufacturers to recalibrate their Brazil market entry strategies around accelerated review pathways for Class III cardiac and orthopedic implants.
Growth Catalysts
- Cardiac catheterization infrastructure:Tertiary hospitals across São Paulo and Rio de Janeiro are expanding catheter lab capacity to accommodate rising arrhythmia and heart failure interventions.
- ANVISA accelerated review pathways:Brazil's updated registration framework compresses approval timelines for Class III implants, reducing manufacturer time-to-revenue.
- Bioresorbable scaffold demand:Younger Latin American patient cohorts are driving preference for absorbable cardiovascular and orthopedic implants that eliminate long-term foreign body complications.
Market Restraints
- Titanium alloy supply concentration:Biocompatible metal feedstock for orthopedic and dental implants concentrates among a limited supplier base, exposing manufacturers to input cost volatility.
- Clinical evidence requirements:ANVISA and Mexico's national pharmaceutical regulator mandate extensive local trial data, extending registration timelines for novel active implantable devices.
- Reimbursement fragmentation:Brazil's public SUS system and private insurance carriers maintain divergent coverage criteria for high-cost cardiac rhythm management devices.
Strategic Opportunities
- Northeast Brazil penetration:Underserved states including Pernambuco and Ceará present expansion potential as federal health infrastructure investments expand tertiary cardiac capacity.
- Ambulatory surgical center channel:Minimally invasive orthopedic and urological procedures are migrating to ASCs, creating demand for streamlined implant procurement models.
- EU MDR alignment:Brazilian reference laboratories adopting updated European biocompatibility standards enable manufacturers to leverage dual-market testing packages for accelerated regional entry.
Industry Challenges
- ISO 13485 auditor scarcity:Limited qualified certification bodies in Latin America extend quality management system validation timelines for new market entrants.
- Legacy hospital procurement systems:Tertiary centers in São Paulo and Mexico City maintain entrenched vendor relationships that complicate competitive displacement.
- Post-market surveillance integration:ANVISA's mandatory adverse event reporting requirements demand dedicated regulatory affairs infrastructure that strains mid-cap manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Implantable Medical Devices Market |
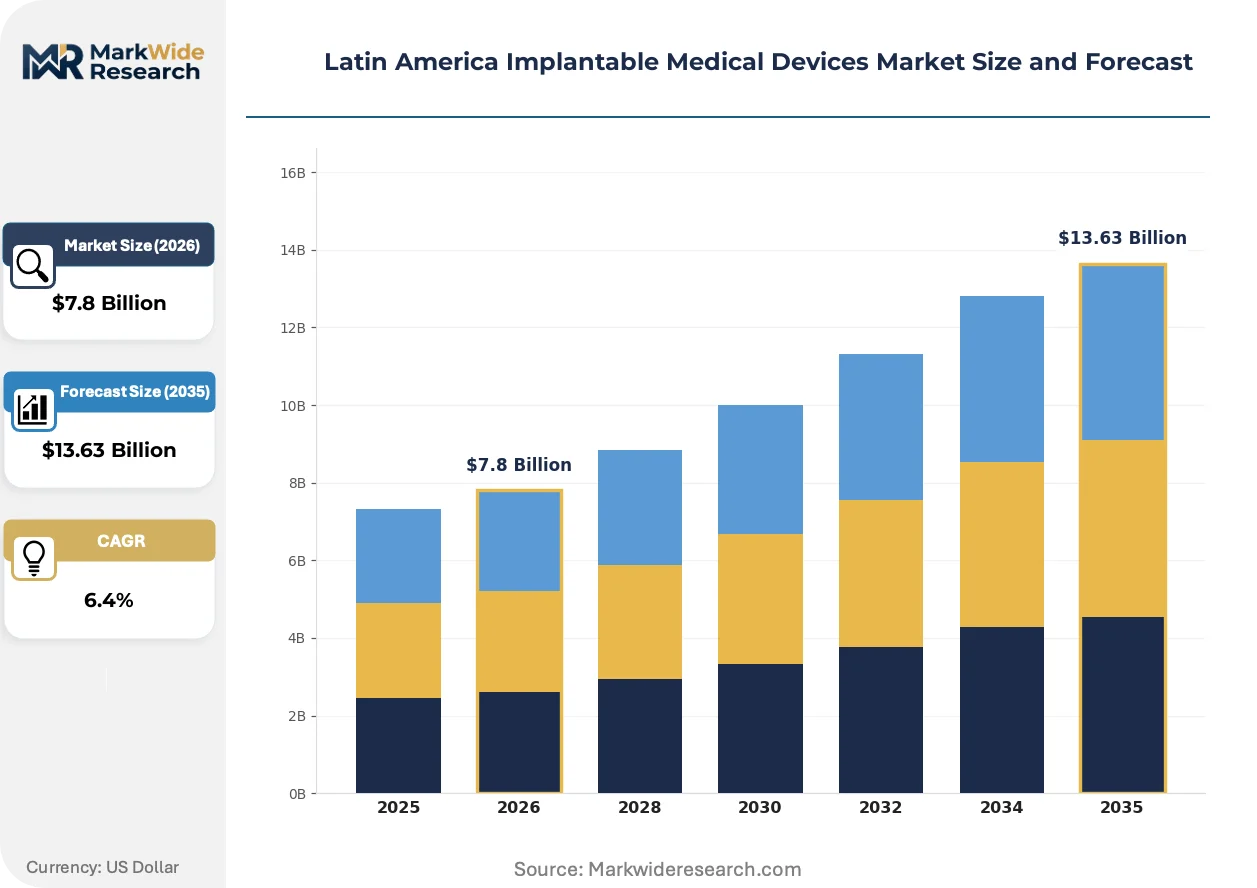
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Devices, Orthopedic Implants, Neurostimulators, Drug-Eluting Stents End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Facilities, Home Care Settings Technology: Active Implants, Passive Implants, Bioresorbable Implants, Injectable Devices Application: Cardiology, Orthopedics, Neurology, Urology |
| Companies Covered | Johnson & Johnson, BIOTRONIK SE & Co. KG, Medtronic plc, Smith+Nephew, LivaNova PLC, Abbott, Stryker Corporation, B. Braun Melsungen AG, Boston Scientific Corporation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Implantable Medical Devices Market Strategic Shifts & Innovations
Active implantable devices are converging with digital health platforms, creating new competitive battlegrounds around data interoperability and remote patient monitoring capabilities across Brazilian and Mexican tertiary care networks.
Bioresorbable cardiovascular scaffolds are hybridizing traditional metallic stent performance with polymer absorption kinetics. São Paulo's leading cardiac centers have adopted these platforms for younger patients requiring coronary revascularization. The technology is hybridizing competitive positioning by enabling manufacturers to command premium pricing while reducing long-term complication liability.
ANVISA's pending risk-based reclassification of spinal cord stimulators and deep brain neurostimulators is tightening clinical evidence requirements for active implantable devices. Manufacturers must now submit Brazil-specific safety and efficacy data rather than relying on foreign regulatory approvals. Neuromodulation portfolios face the steepest compliance burden as the framework prioritizes patient-accessible therapy adjustments.
Hospital purchasing consortia in Southeast Brazil are consolidating implant procurement decisions under centralized supply chain offices. Independent orthopedic and cardiac device representatives are losing direct access to catheter lab and operating room stakeholders. This concentration is most visible in São Paulo's network of teaching hospitals, where volume commitments now determine vendor selection criteria.
Latin America Implantable Medical Devices Market Segmentation
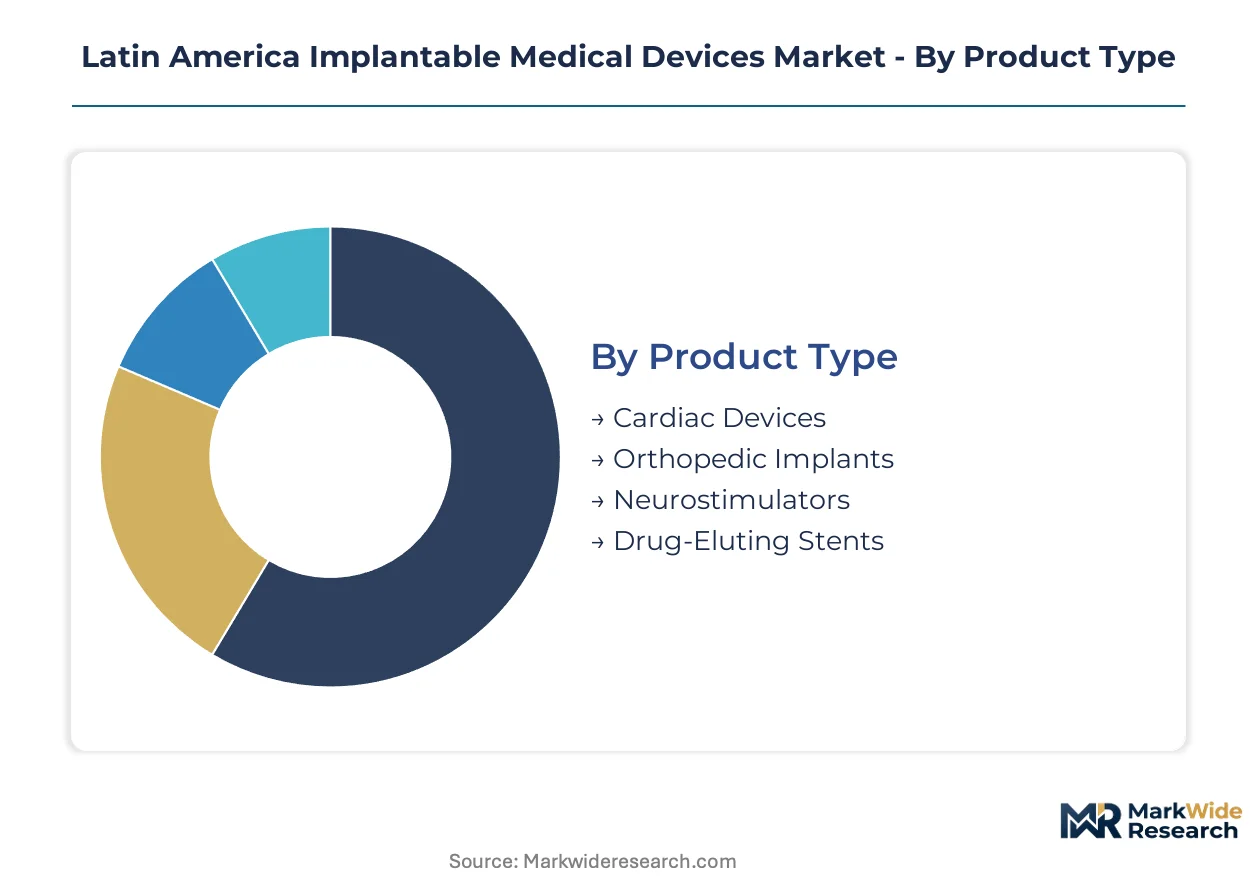
Implantable device procurement across Latin America fragments across clinical settings, technological generations, and therapeutic applications. Manufacturers must align service infrastructure and regulatory filing strategies to the distinct compliance burdens and patient throughput patterns of each segment.
Product Type:
After-sales service intensity varies sharply across implant categories, with active devices demanding dedicated technical support teams for battery management and parameter programming while passive implants require minimal ongoing manufacturer engagement.
- Cardiac Devices:Pacemakers and implantable cardioverter-defibrillators incorporate lithium-iodine power cells and telemetry modules for remote monitoring. São Paulo's tertiary cardiac centers concentrate demand as catheter lab expansions accommodate rising arrhythmia intervention volumes alongside ANVISA's compressed Class III review timelines.
- Orthopedic Implants:Joint replacements and spinal fixation systems utilize cobalt-chrome alloys and titanium porous coatings for osseointegration. Brazil's Southeast region anchors procurement through São Paulo's concentration of specialty orthopedic hospitals, though Northeast states present expansion corridors as federal infrastructure investments mature.
- Neurostimulators:Spinal cord and deep brain stimulation systems deliver electrical pulses via implanted pulse generators.
- Drug-Eluting Stents:Coronary scaffolds release antiproliferative agents from polymer matrices to inhibit restenosis.
Cardiac devices hold the largest share; momentum sits with bioresorbable platforms gaining preference among younger patient cohorts.
End User:
Procurement authority concentrates differently across channel tiers, with tertiary hospitals maintaining direct vendor relationships while ambulatory settings increasingly route through centralized purchasing consortia.
- Hospitals:Tertiary cardiac and orthopedic centers in São Paulo, Rio de Janeiro, and Mexico City command the dominant volume channel for complex implant procedures requiring extended postoperative monitoring.
- Ambulatory Surgical Centers:Minimally invasive orthopedic and urological procedures are migrating to these settings as recovery windows shorten and procurement consolidates under volume-commitment frameworks.
- Rehabilitation Facilities:Post-acute settings manage recovery protocols for joint replacement and cardiac implant patients.
- Home Care Settings:Remote monitoring infrastructure enables some cardiac device follow-up outside institutional settings.
Hospitals retain the dominant volume position; ambulatory surgical centers are climbing the fastest as procedure migration accelerates.
Technology:
Margin structures diverge across technological generations, with active implants commanding premium pricing supported by proprietary software ecosystems while passive devices compete on material specifications and surgeon preference.
- Active Implants:Battery-powered devices with sensing and therapeutic delivery capabilities, including cardiac rhythm management systems and neurostimulators, face tightening ANVISA clinical evidence requirements for Class III registration.
- Bioresorbable Implants:Absorbable cardiovascular scaffolds and orthopedic fixation devices eliminate long-term foreign body complications. São Paulo's leading cardiac centers have adopted these platforms for younger patients requiring coronary revascularization.
- Passive Implants:Structural devices without power components, including joint replacements and dental implants.
- Injectable Devices:Biodegradable drug delivery and tissue bulking systems administered via minimally invasive techniques.
Active implants dominate revenue; bioresorbable platforms are expanding most quickly as absorption kinetics improve.
Application:
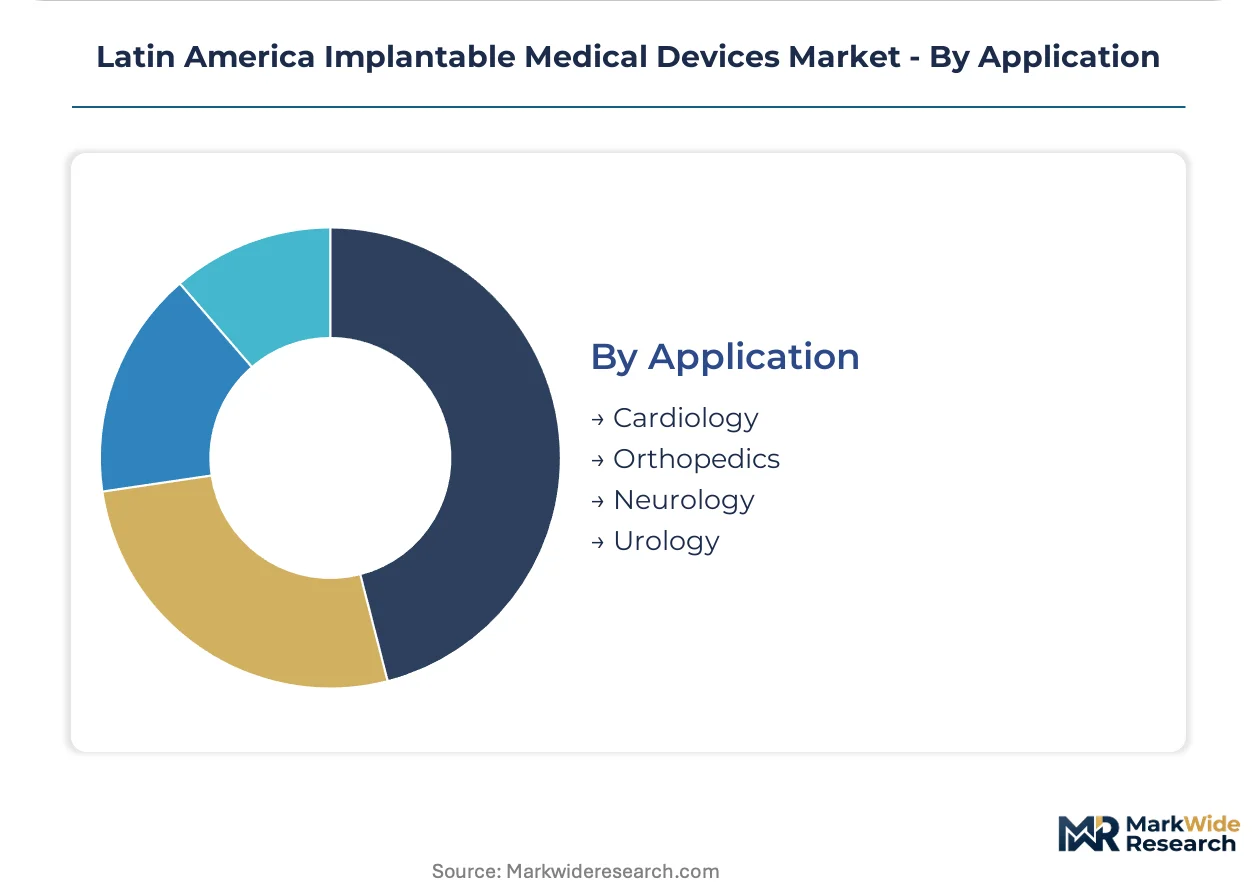
Application-level demand correlates with disease burden demographics and reimbursement accessibility, with cardiology and orthopedics presenting distinct patient access pathways through Brazil's public SUS and private insurance systems.
- Cardiology:Arrhythmia, heart failure, and coronary artery disease interventions occupy the dominant revenue position given prevalence across Latin American aging populations and tertiary center infrastructure concentration in Southeast Brazil.
- Orthopedics:Joint replacement and spinal procedures concentrate in São Paulo's specialty hospitals and Mexico City's orthopedic institutes, with demand fragmentation across public and private reimbursement channels.
- Neurology:Deep brain stimulation for movement disorders and spinal cord stimulation for chronic pain face elevated regulatory barriers under ANVISA's pending neurostimulator reclassification.
- Urology:Sacral nerve stimulation and penile implants serve smaller patient populations with specialized clinical infrastructure requirements.
Cardiology holds the largest share; neurology faces the steepest regulatory compliance burden as evidence requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA anchors regulatory gravity for implantable devices across Latin America, with Brazil's Southeast region commanding procurement volume through São Paulo's tertiary cardiac centers. Mexico's national pharmaceutical regulator enforces parallel sterilization standards, creating dual-compliance pathways for manufacturers seeking regional scale.
Brazil
Southeast Brazil concentrates demand through São Paulo's network of cardiac catheterization labs and Rio de Janeiro's orthopedic specialty hospitals. ANVISA's 2023 registration pathway updates compress Class III implant review timelines, accelerating manufacturer market entry. Northeast states including Pernambuco and Ceará present expansion corridors as federal health infrastructure investments mature tertiary capacity.
Mexico
Mexico City's metropolitan hospitals anchor procurement for complex cardiac and neurological implants, while Nuevo León's Monterrey cluster specializes in orthopedic device distribution. The national pharmaceutical regulator mandates NOM standards for sterile products, requiring localized biocompatibility testing. Northern border states leverage maquiladora infrastructure for device assembly serving US market adjacency.
Argentina
Buenos Aires province dominates implantable device consumption through its concentration of public hospital networks and private cardiovascular institutes. The national administration of drugs, foods and medical technology enforces registration requirements that prioritize clinical evidence from regional populations. Córdoba's medical device manufacturing corridor supplies passive orthopedic implants to Mercosur markets.
Chile
Santiago's private clinic networks drive premium-tier demand for active cardiac rhythm management devices and bioresorbable cardiovascular scaffolds. The public health institute maintains stringent post-market surveillance protocols that shape manufacturer service infrastructure requirements. Valparaíso's port logistics cluster facilitates import distribution for Andean regional markets.
Colombia
Bogotá's tertiary hospital network concentrates neurostimulator and drug-eluting stent procurement amid expanding catheterization capacity. The national food and drug surveillance institute harmonizes registration requirements with ANVISA frameworks to streamline multi-market approvals. Medellín's medical technology manufacturing zone supports regional assembly of passive orthopedic implants.
Latin America Implantable Medical Devices Market Key Industry Players
Capability concentration sits with diversified multinationals commanding cardiac rhythm management and neuromodulation portfolios; scale advantage sits with orthopedic specialists leveraging high-volume joint replacement platforms. The market structures around three archetypes: integrated device manufacturers with full cardiac-to-orthopedic coverage, active implant specialists focused on battery-powered therapeutic delivery, and bioresorbable technology developers commercializing next-generation absorption kinetics. Dominant competitive moves include strategic partnerships with São Paulo teaching hospitals for clinical validation, and portfolio diversification into ambulatory surgical center channels for routine orthopedic procedures.
Among US-based diversified manufacturers, Medtronic plc and Abbott exemplify the integrated cardiac-neuromodulation archetype, while Boston Scientific Corporation occupies a position within the interventional cardiology specialization tier. Germany's BIOTRONIK SE & Co. KG represents the European active implant specialist model with concentrated cardiac rhythm management capabilities.
| Leading Market Players |
|---|
| Johnson & Johnson |
| BIOTRONIK SE & Co. KG |
| Medtronic plc |
| Smith+Nephew |
| LivaNova PLC |
| Abbott |
| Stryker Corporation |
| B. Braun Melsungen AG |
| Boston Scientific Corporation |
| Others |
Cost & Logistics Intelligence
Santos Port's biocompatible alloy freight corridors carry titanium and cobalt-chrome feedstock from Asian smelters to São Paulo's orthopedic manufacturers, with container cost volatility transmitting directly into Class III implant pricing tiers across Brazil's Southeast region.
Pricing Analysis
Price spreads between São Paulo and Northeast Brazil exceed standard logistics premiums by double-digit factors, reflecting distribution inefficiency rather than product differentiation. Pricing stratifies across premium, standard, and economy tiers anchored by ANVISA certification grade and after-sales service bundling. Cost compression in economy-tier cardiac devices is intensifying as Mexican assembly operations gain scale. Public hospital procurement committees exhibit acute price sensitivity, while private tertiary centers prioritize device longevity and remote monitoring capabilities over unit cost.
Supply Chain Analysis
Extended payment terms from Brazilian distributors to Asian titanium suppliers now stretch 90-120 days, straining working capital across mid-cap manufacturers. Supply concentrates in China, Germany, and the United States for precision-machined components and polymer matrices. Raw material dependencies center on medical-grade titanium sponge, cobalt-chrome alloys, and bioresorbable polylactic acid. Single-source vulnerability persists for lithium-iodine battery cells powering cardiac rhythm management devices. Distribution runs through São Paulo-based medical device distributors with direct hospital sales forces, supplemented by Mexico City hubs serving northern Latin American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioresorbable scaffold platforms threaten to displace conventional metallic implants across younger patient cohorts, forcing incumbents to defend installed base relationships while accelerating next-generation absorption technology development.
For Market Incumbents: Pre-empt bioresorbable displacement by securing exclusive catheter lab partnerships in São Paulo's expanding tertiary network. Anchor backward integration into titanium alloy finishing to offset feedstock cost volatility from Asian suppliers. Accelerate ANVISA registration for next-generation drug-eluting platforms before risk-based reclassification tightens clinical evidence requirements. For New Entrants and Emerging Players: Establish a beachhead in Northeast Brazil's underserved cardiac centers as federal infrastructure investments mature tertiary capacity in Pernambuco and Ceará. Target ambulatory surgical center channels for routine orthopedic procedures where procurement consolidation has not yet entrenched incumbent relationships. Lead with streamlined service models and compressed delivery timelines rather than device innovation. For Investors and Strategic Acquirers: Active implant specialists with concentrated neuromodulation portfolios and established ANVISA regulatory affairs infrastructure offer the strongest acquisition profile. Long-term viability hinges on navigating Brazil's pending neurostimulator reclassification and capturing share in bioresorbable platform development. Watch ANVISA's adverse event reporting enforcement intensity as an inflection indicator for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Pathway Optimization | Compressed Class III review timelines accelerate revenue recognition for cardiac and orthopedic portfolios. |
| Hospital System Partnership | Exclusive catheter lab agreements in São Paulo teaching hospitals lock out competitor access to high-volume intervention sites. |
| Bioresorbable Platform Development | Absorption kinetics advancement commands premium pricing while reducing long-term complication liability exposure. |
| Software Companion Development | Remote monitoring ecosystems for cardiac rhythm management devices create recurring revenue and patient lock-in. |
| Reimbursement Strategy | SUS and private carrier coverage alignment determines patient access for high-cost active implantable devices. |
Research Approach
A spread of perspectives from cardiac catheterization lab directors, hospital purchasing committee members, biomedical engineers at tertiary centers, and GPO contracts managers converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation through ANVISA registration filings, hospital procurement databases, and CMS-equivalent SUS reimbursement records. Bottom-up implant volume estimates triangulated against top-down healthcare expenditure flows across the analysis window.
Demand-supply-balance framing anchored the analytical framework, with segmentation dimensions spanning product type, end-user channel, technology generation, and application area across the projection horizon. CAGRs derived from installed base growth rates, procedure volume trajectories, and replacement cycle dynamics. Industry-specific forecast inputs incorporated ANVISA regulatory timeline assumptions and bioresorbable scaffold adoption curves.
Stress conditions across titanium alloy price volatility, ANVISA reclassification timing, and SUS reimbursement rate adjustments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway efficiency and infrastructure investment continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
Non-Destructive Medical Technologies Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
Medical Coatings Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
Anti-Snore Device Market
Medical Devices
Water Bath Vaporizer Market
Medical Devices
Breast Localization System Market
Medical Devices
Wireless Breast Pump Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
Sphincterotomes Market
Medical Devices
UK Artificial Organs and Bionic Implants Market