
 Pulmonary Function Testing System Market | 2026-2036
Pulmonary Function Testing System Market Size, Share, and Industry Trends Forecast 2026-2036
Pulmonary Function Testing System Market Intelligence
The EU Green Deal's medical device circularity framework is repositioning procurement criteria toward reusable sensor modules and extended service contracts. Vyaire Medical leverages its installed base in acute care to sustain replacement revenue through multi-year calibration agreements. COSMED anchors European demand with portable systems designed for ambulatory settings. MGC Diagnostics Corporation differentiates through specialized body plethysmography chambers that dominate reference laboratory installations.
A pulmonary function testing system comprises integrated hardware and software platforms that measure respiratory mechanics, lung volumes, and gas exchange efficiency through calibrated airflow sensors, pressure transducers, and real-time analytics algorithms. These systems quantify forced vital capacity, diffusion capacity, and airway resistance to diagnose obstructive and restrictive pathologies, monitor disease progression, and evaluate surgical candidacy. Spirometry and body plethysmography technologies command the largest installed base, while impulse oscillometry represents the fastest-expanding segment due to its suitability for pediatric and geriatric populations unable to perform forced maneuvers. Gas analyzers and diffusion testers concentrate margin pools in tertiary referral centers managing interstitial lung disease portfolios.
The FDA's 510(k) clearance requirements for software-as-medical-device functionality shape product development timelines and predicate device selection for US manufacturers. The EU Medical Device Regulation mandates clinical evidence thresholds that favor established players with robust post-market surveillance infrastructure. Japan's PMDA enforces JIS-standard calibration protocols that create compliance barriers for non-domestic entrants. Stakeholders must monitor convergence between AI-enabled diagnostic interpretation and evolving liability frameworks governing autonomous clinical decision support.
Market Dynamics
The EU Medical Device Regulation's clinical evidence thresholds are compressing development timelines while forcing predicate device consolidation among established manufacturers. Hardware-software integration requirements under the FDA's 510(k) pathway are accelerating refresh cycles across acute care networks.
Growth Catalysts
- Statutory lung screening mandates:Germany's occupational health regulations for high-risk industries drive replacement volumes for calibrated spirometry systems in industrial medicine clinics.
- Impulse oscillometry adoption:Pediatric pulmonology departments deploy forced-maneuver-independent diagnostics for patients unable to perform standard spirometry protocols.
- Post-acute monitoring protocols:Hospital systems across North America expand respiratory diagnostic suites to meet tightened discharge surveillance requirements.
Market Restraints
- Calibration consumable costs:Precision airflow sensors require certified gas mixtures and annual factory recalibration, creating recurring cost burdens for mid-sized pulmonary clinics.
- EU MDR compliance barriers:Post-market surveillance infrastructure requirements favor large manufacturers with dedicated regulatory affairs teams, raising entry costs for specialized device developers.
- Technical limitation in home settings:Body plethysmography chambers require controlled temperature and barometric pressure environments that resist decentralization to ambulatory or residential use cases.
Strategic Opportunities
- Ambulatory care expansion:Portable systems designed for community health centers capture referral flows from congested tertiary hospital pulmonary function laboratories.
- EU Green Deal circularity framework:Reusable sensor modules and extended service contracts reposition procurement criteria toward total cost-of-ownership metrics rather than capital expenditure minimization.
- AI-enabled diagnostic interpretation:Machine learning algorithms for pattern recognition in obstructive versus restrictive disease classification converge with cloud-based analytics platforms to enable remote specialist oversight.
Industry Challenges
- Respiratory physiologist workforce gaps:Specialized technologists capable of performing complex body plethysmography maneuvers and quality-controlled spirometry interpretation remain concentrated in academic medical centers.
- Legacy system integration friction:Hospital information system connectivity requirements for electronic health record data exchange create implementation delays for software-as-medical-device platforms.
- Multi-jurisdictional certification timelines:Simultaneous FDA 510(k), CE marking under MDR, and PMDA JIS-standard calibration approvals extend product launch windows by eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulmonary Function Testing System Market |
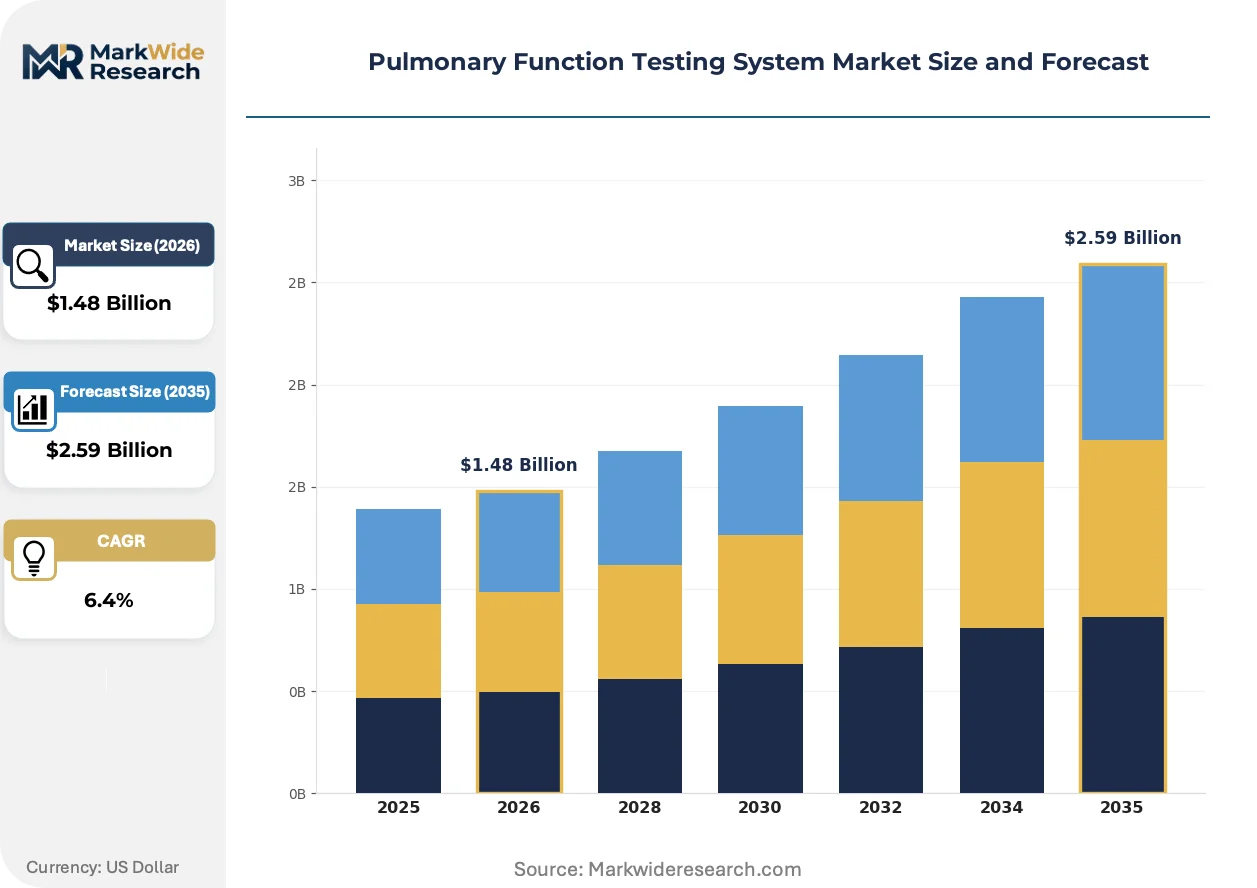
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirometer, Plethysmograph, Gas Analyzer, Peak Flow Meter, Diffusion Tester Application: Chronic Obstructive Pulmonary Disorder, Asthma Diagnosis, Pre-Surgical Evaluation, Occupational Lung Disease, Respiratory Therapy Assessment End User: Pulmonary Clinics, Diagnostic Laboratories, Research Institutes, Home Care Settings, Respiratory Therapy Centers Technology: FVC Measurement, Spirometry, Gas Dilution, Impulse Oscillometry, Body Plethysmography |
| Companies Covered | Vyaire Medical, MGC Diagnostics Corporation, COSMED, ndd Medical Technologies, Philips, Baxter, CHEST M.I., ECO MEDICS, Schiller, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulmonary Function Testing System Market Strategic Shifts & Innovations
Software-enabled diagnostic platforms are compressing the traditional hardware refresh cycle while repositioning margin capture toward recurring analytics subscriptions and remote calibration services.
Impulse oscillometry technology is converging with portable sensor miniaturization to enable point-of-care lung function assessment outside controlled laboratory environments. Community pulmonology practices in Germany and the United States adopt these systems for pediatric and geriatric populations unable to perform forced expiratory maneuvers. The structural consequence is displacement of centralized hospital-based testing toward distributed diagnostic networks.
Japan's PMDA enforces JIS-standard calibration protocols that create compliance barriers for non-domestic device manufacturers seeking market entry. The industrial consequence is concentration of installed base maintenance revenue among established suppliers with domestic service infrastructure. Reference laboratory segments respond by consolidating procurement toward vendors with proven post-market surveillance capabilities across multiple regulatory jurisdictions.
After-sales service unbundling is fragmenting the traditional capital-equipment-plus-maintenance bundle into discrete calibration, software update, and remote support subscriptions. Hospital procurement departments in North America negotiate these elements separately, compressing upfront capital commitments while extending vendor lock-in through multi-year service agreements. This pattern is most visible in integrated delivery networks managing respiratory diagnostic standardization across fifteen to twenty affiliated facilities.
Pulmonary Function Testing System Market Segmentation
Pulmonary function testing systems fragment across four structural dimensions that determine procurement patterns and margin capture. Capital intensity, clinical workflow integration, and regulatory compliance burden vary sharply by segment, reshaping vendor competitive positioning.
Product Type:
Capital-intensity differentiates these segments most sharply, with chamber-based systems demanding substantial facility investment while portable devices minimize infrastructure requirements.
- Plethysmograph:Sealed body chambers measure total lung capacity and airway resistance through pressure-volume relationships. German occupational health clinics and US academic medical centers absorb the majority of installed base as reference-standard installations for disability determination and surgical candidacy protocols.
- Spirometer:Calibrated airflow sensors quantify forced expiratory volumes and flow rates through disposable mouthpiece assemblies. Demand concentrates in high-volume screening environments where throughput economics favor rapid-turnover, technician-supervised testing.
- Gas Analyzer:Infrared and electrochemical sensors measure expired gas concentrations for diffusion capacity assessment. Tertiary interstitial lung disease programs drive replacement cycles.
- Peak Flow Meter:Mechanical or electronic devices track maximum expiratory flow for ambulatory monitoring. Home care and school-based asthma management programs dominate volume.
- Diffusion Tester:Single-breath carbon monoxide uptake systems isolate alveolar-capillary membrane function. Pulmonary hypertension and connective tissue disease portfolios anchor demand.
Plethysmograph installations absorb the bulk of capital expenditure per unit; impulse oscillometry-compatible spirometers are expanding most quickly into community settings.
Application:
Reimbursement density and testing frequency determine segment economics, with chronic disease monitoring generating recurring revenue streams versus one-time surgical clearances.
- Chronic Obstructive Pulmonary Disorder:Longitudinal forced expiratory volume tracking guides bronchodilator therapy adjustment and exacerbation risk stratification. US Medicare annual wellness visit mandates and German disease management program requirements sustain replacement demand across integrated delivery networks.
- Asthma Diagnosis:Bronchoprovocation testing and reversibility assessment differentiate allergic from non-allergic phenotypes. Pediatric pulmonology departments in Japan and France deploy oscillometry-first protocols for patients unable to perform forced maneuvers.
- Pre-Surgical Evaluation:Risk stratification for thoracic and upper abdominal procedures requires diffusion capacity and maximal voluntary ventilation assessment. Academic medical center perioperative medicine clinics concentrate volume.
- Occupational Lung Disease:Statutory surveillance programs for mining, construction, and chemical manufacturing sectors mandate periodic spirometry. Germany's Berufsgenossenschaften and US MSHA-regulated sites drive calibrated system procurement.
- Respiratory Therapy Assessment:Ventilator weaning readiness and rehabilitation progress monitoring utilize serial measurements. Long-term acute care hospitals and skilled nursing facilities represent emerging demand nodes.
Chronic obstructive pulmonary disorder monitoring absorbs the bulk of installed system utilization hours; asthma diagnosis applications are climbing the fastest as pediatric oscillometry protocols diffuse.
End User:
Procurement sophistication and service contract negotiation leverage vary by institutional scale, fragmenting pricing architecture across site categories.
- Diagnostic Laboratories:High-throughput reference facilities standardize on multi-modality platforms with automated quality control. US hospital-affiliated labs and German MVZ-structured networks dominate replacement volume.
- Pulmonary Clinics:Community-based specialty practices prioritize compact, technician-operable systems with remote interpretation connectivity. France's ville-santé networks and US accountable care organization medical homes anchor demand.
- Respiratory Therapy Centers:Post-acute and rehabilitation-focused sites require durable, high-duty-cycle equipment for repeated measurement protocols.
- Research Institutes:Methodology development and clinical trial endpoints drive demand for research-grade calibration and raw data export capabilities.
- Home Care Settings:Telehealth-integrated portable spirometers and peak flow devices enable remote monitoring. Reimbursement coding evolution in the US and Netherlands shapes adoption timing.
Diagnostic laboratories absorb the bulk of capital equipment procurement value; pulmonary clinics are gaining share fastest as decentralized testing protocols expand.
Technology:
Measurement physics and patient cooperation requirements determine addressable population and site-of-care feasibility.
- Body Plethysmography:Pressure-compensated chamber technology delivers absolute lung volumes and specific airway resistance without patient effort dependence. Reference laboratories in Switzerland, Austria, and the US maintain installed base concentration.
- Spirometry:Forced expiratory maneuver-based flow-volume loop generation remains the diagnostic standard for obstructive pattern recognition. Quality control infrastructure requirements favor established vendors with technician training programs.
- Impulse Oscillometry:External pressure oscillations measure respiratory system impedance during tidal breathing. Pediatric departments in Japan's National Center for Child Health and Development and Germany's university hospitals lead adoption for preschool and geriatric populations.
- Gas Dilution:Helium or nitrogen washout techniques determine functional residual capacity in patients unable to tolerate plethysmography chambers.
- FVC Measurement:Forced vital capacity quantification represents the foundational metric across all obstructive and restrictive disease classification schemes.
Spirometry platforms absorb the bulk of measurement volume; impulse oscillometry is gaining share fastest as pediatric and geriatric testing protocols evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for precision airflow sensors and pressure transducers clusters in Germany, Switzerland, and Japan, while consumption demand spreads across North American hospital networks and European occupational health clinics. This production-consumption divide shapes regulatory compliance strategies and service infrastructure investments.
United States
Hospital systems in Texas, California, and the Northeast Corridor expand respiratory diagnostic suites to meet tightened post-acute monitoring protocols. The FDA's updated 510(k) pathway for software-enabled spirometry accelerates device refresh cycles across integrated delivery networks. Boston's academic medical center cluster drives adoption of multi-modality platforms with automated quality control.
Germany
Statutory lung screening mandates for mining, construction, and chemical manufacturing sectors drive replacement volumes for calibrated spirometry systems. The EU Medical Device Regulation's clinical evidence thresholds compress development timelines while favoring established manufacturers with post-market surveillance infrastructure. Munich and Hamburg host the densest concentrations of industrial medicine clinics performing mandated occupational surveillance.
Japan
Pediatric pulmonology departments deploy impulse oscillometry systems for patients unable to perform forced expiratory maneuvers. The PMDA enforces JIS-standard calibration protocols that create compliance barriers for non-domestic device manufacturers. Tokyo's National Center for Child Health and Development leads protocol development for preschool and geriatric testing.
Switzerland
Reference laboratories maintain installed base concentration in pressure-compensated body plethysmography chambers for absolute lung volume measurement. Swissmedic's medical device surveillance requirements favor vendors with proven quality management systems. Zurich and Basel anchor demand from disability determination and surgical candidacy assessment protocols.
China
Community health centers in the Yangtze River Delta and Pearl River Delta pilot portable systems for decentralized lung function assessment. The NMPA's hardware-software integration requirements for software-as-medical-device platforms extend product registration timelines. Shanghai's tertiary hospital networks drive procurement of research-grade calibration systems for clinical trial endpoints.
Pulmonary Function Testing System Market Key Industry Players
The competitive structure tilts toward established manufacturers with dedicated regulatory affairs teams capable of navigating multi-jurisdictional certification timelines. Three strategic archetypes dominate: acute care incumbents leveraging installed base maintenance revenue, portable system specialists capturing ambulatory care expansion, and reference laboratory equipment providers dominating body plethysmography segments. Competitive moves concentrate on multi-year calibration agreements and extended service contracts that reposition procurement toward total cost-of-ownership metrics.
Within the acute care incumbent tier, Vyaire Medical and MGC Diagnostics Corporation exemplify players sustaining replacement revenue through service infrastructure investments. COSMED anchors the portable system specialist position, occupying a geography-first role in European ambulatory settings. These three represent the dominant competitive anchors across the hardware-software integration requirements reshaping procurement patterns.
| Leading Market Players |
|---|
| Vyaire Medical |
| MGC Diagnostics Corporation |
| COSMED |
| ndd Medical Technologies |
| Philips |
| Baxter |
| CHEST M.I. |
| ECO MEDICS |
| Schiller |
| Others |
Cost & Logistics Intelligence
Sensor miniaturization and software-as-medical-device platforms are compressing hardware refresh cycles while fragmenting procurement into discrete calibration subscriptions and remote service agreements. This transition concentrates margin capture among established vendors with multi-year service infrastructure, simultaneously reshaping buyer cost structures toward operational expenditure models and reducing upfront capital barriers for mid-sized pulmonary clinics.
Pricing Analysis
Cost-down pressure on mid-tier spirometry systems accelerates because EU MDR compliance investments favor manufacturers with dedicated regulatory affairs teams capable of absorbing certification overhead across larger installed bases. Three-tier pricing structure across premium, standard, and economy levels differentiates by calibration certification grade and after-sales bundling intensity. Price differentiation traces to FDA 510(k) predicate device selection versus CE marking under MDR clinical evidence thresholds. Community pulmonary clinics exhibit highest price sensitivity due to constrained capital budgets; tertiary academic medical centers demonstrate lowest sensitivity given reimbursement density for complex body plethysmography procedures.
Supply Chain Analysis
Precision airflow sensors and pressure transducers rest on manufacturing clusters in Germany, Switzerland, and Japan, creating geographic concentration for critical measurement components. Raw material dependencies include medical-grade aluminum alloys for plethysmography chambers, infrared gas detection elements for diffusion analyzers, and disposable bacterial filters for spirometry assemblies. Single-source vulnerability concentrates in JIS-standard calibration protocol compliance for Japanese market entry. Distribution runs through hospital procurement committees and group purchasing organizations in North America, direct sales to occupational health clinics in Germany, and specialized medical device distributors serving community pulmonology practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Impulse oscillometry technology is displacing forced-maneuver-dependent spirometry in pediatric and geriatric testing protocols, creating a transition window where portable system specialists can capture share from acute care incumbents anchored to chamber-based installed bases.
For Market Incumbents: Cement replacement revenue streams through multi-year calibration agreements that extend vendor lock-in across integrated delivery networks. Expand service infrastructure into German industrial medicine clinics to capture statutory screening mandate volumes. Prioritize backward integration into reusable sensor module production to align procurement criteria with EU Green Deal circularity frameworks and defend margin position against portable system specialists. For New Entrants and Emerging Players: FDA's updated 510(k) pathway for software-enabled spirometry opens a window for software-native entrants to bypass hardware-intensive predicate device requirements. Target community health centers in the United States and France's ville-santé networks as underpenetrated ambulatory settings lacking complex body plethysmography infrastructure. Pursue telehealth-integrated portable spirometers as the go-to-market angle, leveraging reimbursement coding evolution in the Netherlands and United States to accelerate adoption timing. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by acute care incumbents seeking software-as-medical-device capabilities and portable system specialists pursuing geographic expansion. Long-term viability favors vendors with proven post-market surveillance infrastructure across FDA, MDR, and PMDA jurisdictions. Watch impulse oscillometry protocol adoption rates in Japan's National Center for Child Health and Development and Germany's university hospitals as the signal indicating technology transition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Development | FDA 510(k) pathway acceleration enables faster product refresh cycles than hardware-dependent competitors. |
| Multi-Year Calibration Agreements | Extended service contracts reposition hospital procurement toward total cost-of-ownership metrics and vendor lock-in. |
| Reusable Sensor Module Production | EU Green Deal circularity framework alignment captures procurement criteria evolution in German occupational health clinics. |
| Impulse Oscillometry Platform Launch | Tidal breathing diagnostics address pediatric and geriatric populations unable to perform forced expiratory maneuvers. |
| Post-Market Surveillance Infrastructure Investment | MDR clinical evidence threshold compliance creates competitive moats against specialized device developers lacking regulatory scale. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR technical documentation, and Japanese PMDA approval records, complemented by interviews with respiratory physiologists, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement databases, German Berufsgenossenschaften occupational health expenditure reports, and customs records for precision sensor trade flows. Bottom-up installed base estimates triangulated against top-down market sizing derived from capital equipment procurement disclosures.
Segment-level value outputs across the analysis window reflect modeling of product type, application, end user, and technology dimensions with particular attention to impulse oscillometry diffusion rates. CAGRs were derived from regression analysis of replacement cycle timing, regulatory approval velocity, and statutory screening mandate expansion. Industry-specific forecast inputs include technician workforce availability constraints and hospital information system integration friction timelines.
The model assumes a particular technology adoption path; alternative pathways for AI-enabled diagnostic interpretation would alter the outlook if liability frameworks governing autonomous clinical decision support shift materially. Forecasts reflect assumptions regarding calibration consumable cost trajectories and multi-jurisdictional certification timeline convergence. A small set of triggers warrants ongoing watch: PMDA JIS-standard calibration protocol amendments, EU MDR post-market surveillance enforcement intensity, and CMS reimbursement coding changes for remote pulmonary function monitoring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Manufacturing Outsourcing Market
Medical Devices
Global Single-Use Medical Device Reprocessing Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Digital Reading Micropipettes Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Repetitive Transcranial Magnetic Stimulation Market
Medical Devices
Surgical Display Market
Medical Devices
At-Home Laser Hair Removal Devices Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Repositioning and Offloading Devices Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Global Nasal Cannula Market