
 Digital Magnifiers Market | 2026-2036
Digital Magnifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Magnifiers Market Insights
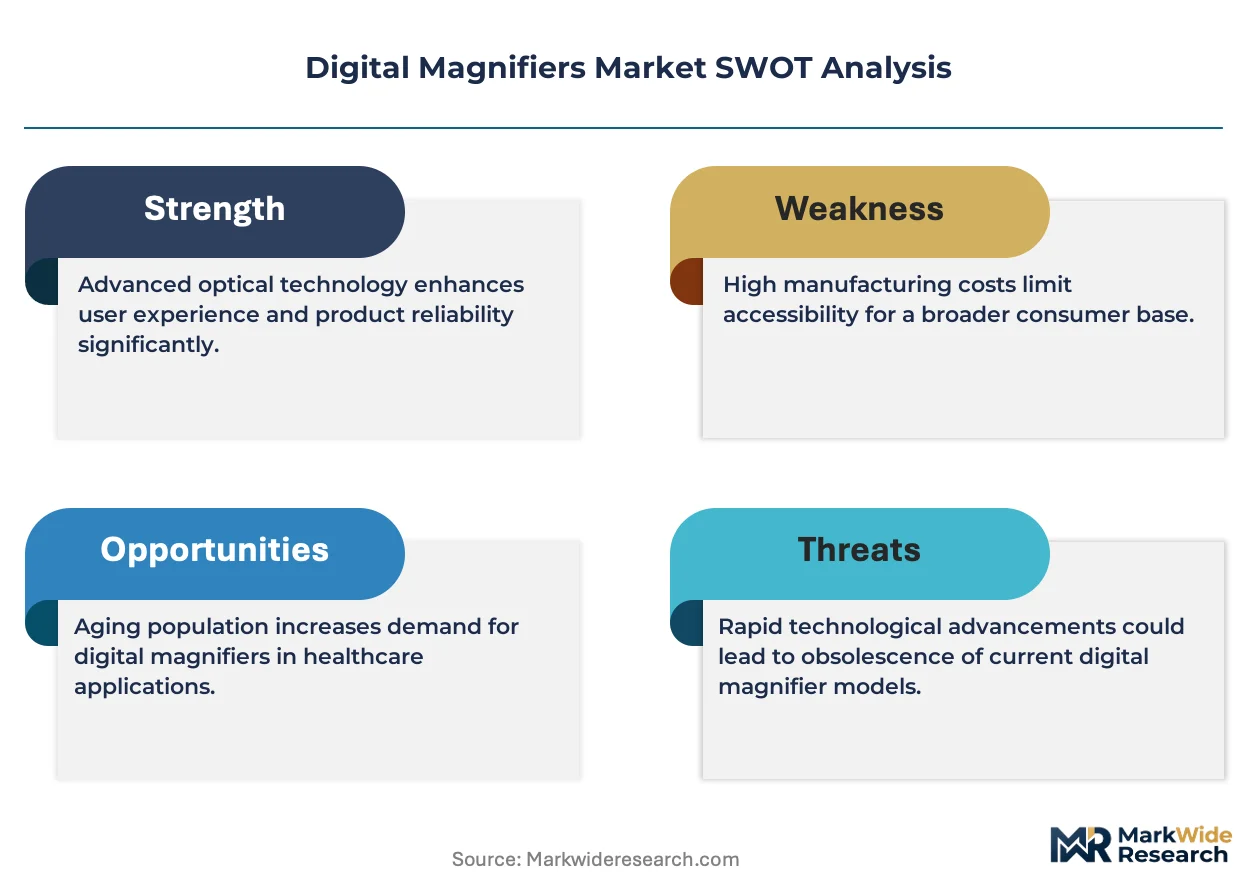
Subscription-based leasing and pay-per-use financing is fragmenting the competitive landscape for digital magnifiers, lowering upfront barriers for educational institutions and small clinics. HumanWare leverages its direct-to-consumer channel to sustain premium positioning across North America. Eschenbach Optik anchors European distribution through specialized optical retailers and rehabilitation centers. Freedom Scientific differentiates with software-integrated magnification platforms that serve institutional procurement frameworks.
Digital magnifiers are electro-optical devices that combine high-resolution camera sensors with liquid-crystal or OLED display panels to magnify printed text, images, and physical objects for users with visual impairment, typically offering variable magnification ratios from 2x to 80x and adjustable contrast modes. Handheld magnifiers lead unit volume due to portability and lower price points, while desktop magnifiers command the dominant share of value as healthcare providers and educational institutions prioritize large-screen displays with integrated XY reading tables. Wearable magnifiers represent the fastest-expanding category, with head-mounted designs incorporating augmented reality overlays that attract technology-oriented users seeking hands-free operation.
The FDA regulates digital magnifiers as Class I or II medical devices depending on software claims, requiring 510(k) premarket notification for units marketed with therapeutic intent. In Europe, the MDR and CE marking framework govern device safety and electromagnetic compatibility, while the EU Accessibility Act mandates procurement standards for public sector purchases. Stakeholders must monitor evolving reimbursement codes from Medicare and national health services, as coverage determinations directly shape addressable demand for prescription-grade versus retail-tier devices.
Market Dynamics
Subscription-based leasing models are fragmenting the competitive landscape for digital magnifiers, lowering upfront barriers for educational institutions and small clinics while pressuring traditional hardware margins across North America and Europe.
Growth Catalysts
- Aging demographics:Healthcare providers in Germany expand procurement of assistive vision devices as statutory health insurance covers prescribed electronic magnification systems for registered visually impaired patients.
- MDR compliance:The EU Medical Device Regulation creates standardized safety benchmarks that accelerate cross-border trade of CE-marked digital magnifiers among European rehabilitation centers.
- Camera sensor advances:High-resolution CMOS and OLED display technologies enable variable magnification ratios from 2x to 80x with adjustable contrast modes for low-vision users.
Market Restraints
- Reimbursement uncertainty:Medicare coverage determinations for prescription-grade versus retail-tier devices create demand volatility for manufacturers dependent on institutional procurement.
- Component concentration:Liquid-crystal and OLED display panel sourcing concentrates among Asian suppliers, exposing producers to supply disruption and input cost volatility.
- Smartphone substitution:Built-in accessibility magnification features on mainstream mobile devices threaten standalone handheld magnifier volumes at lower price points.
Strategic Opportunities
- Wearable convergence:Head-mounted designs incorporating augmented reality overlays attract technology-oriented users seeking hands-free operation in the fastest-expanding product category.
- Institutional leasing:Pay-per-use financing penetrates educational institutions and small clinics previously priced out of desktop magnifier acquisitions.
- EU Accessibility Act:Mandated procurement standards for public sector purchases create preferential sourcing channels for compliant device manufacturers.
Industry Challenges
- 510(k) timeline compression:FDA premarket notification requirements for units marketed with therapeutic intent extend product development cycles and delay revenue recognition.
- Software-hardware integration:Firmware validation for Class II medical device claims demands specialized regulatory affairs expertise scarce among traditional optical equipment engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Magnifiers Market |
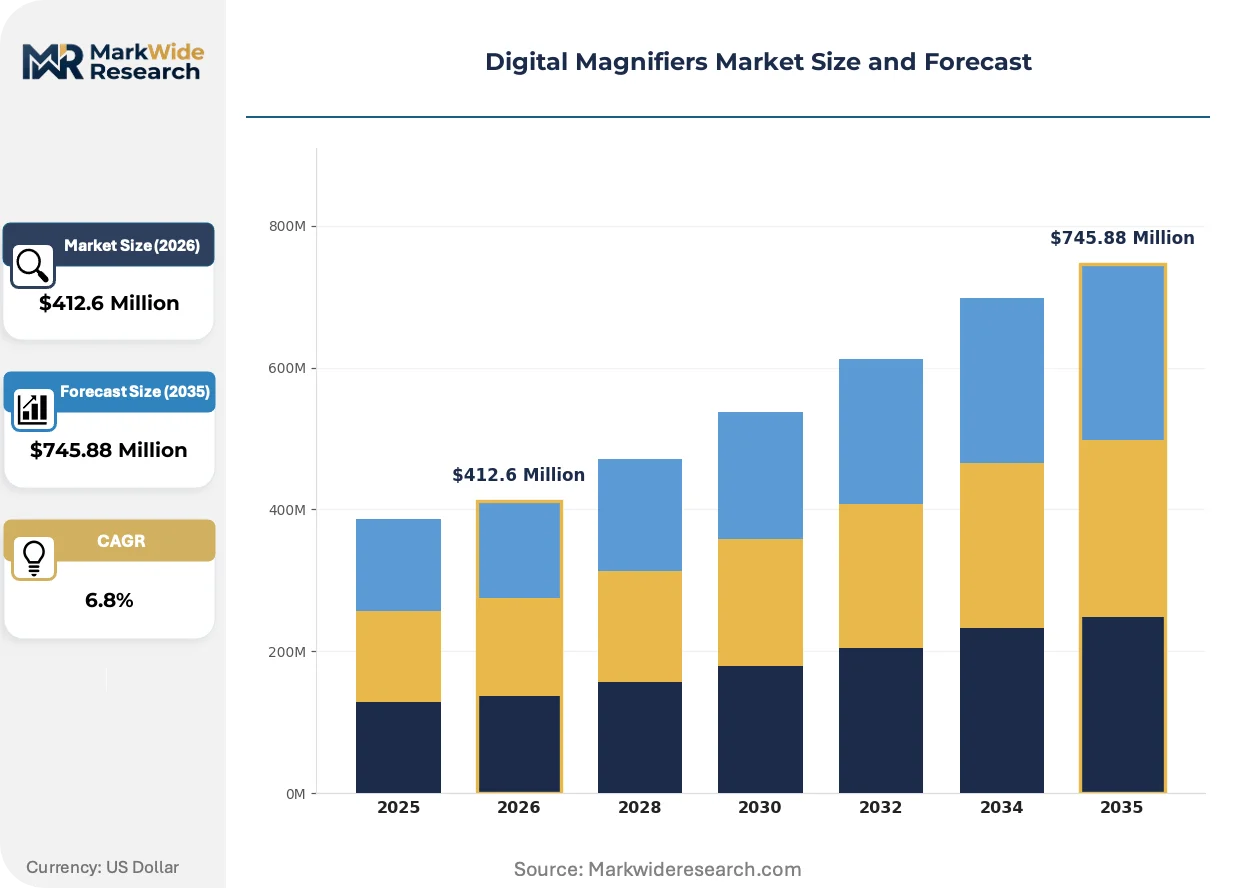
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Magnifiers, Desktop Magnifiers, Wearable Magnifiers, Portable Magnifiers Technology: Optical Technology, Digital Display, Image Processing, Cameras End User: Individuals with Low Vision, Educational Institutions, Healthcare Providers, Retail Users Distribution Channel: Online Retail, Specialty Stores, Medical Distributors, Direct Sales |
| Companies Covered | Vision Engineering, Eschenbach Optik, HumanWare, Freedom Scientific, Enhanced Vision, Dazor Lighting Technology, Koolertron, Vispero, Optelec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Magnifiers Market Trends and Innovations
Software-integrated magnification platforms are reshaping how institutional buyers evaluate procurement frameworks, shifting technical specifications from hardware-centric to ecosystem-driven purchasing criteria.
Head-mounted augmented reality overlays are collapsing the functional boundary between assistive vision devices and mainstream wearable electronics. Veterans' affairs hospitals in the United States pilot these systems for macular degeneration patients. The technology is collapsing price premiums previously commanded by specialized low-vision hardware vendors.
MDR electromagnetic compatibility testing requirements are tightening market entry standards for non-European manufacturers. CE marking validation now demands documented clinical performance data absent under prior directives. German rehabilitation centers favor suppliers with established notified body relationships, compressing vendor shortlists.
Direct-to-consumer channels now capture meaningful volume previously routed through specialized optical retailers. HumanWare and Eschenbach Optik compete for online visibility against general medical device distributors. This channel rotation is most visible in North American markets where insurance reimbursement bypasses traditional dispensing opticians.
Digital Magnifiers Market Segmentation
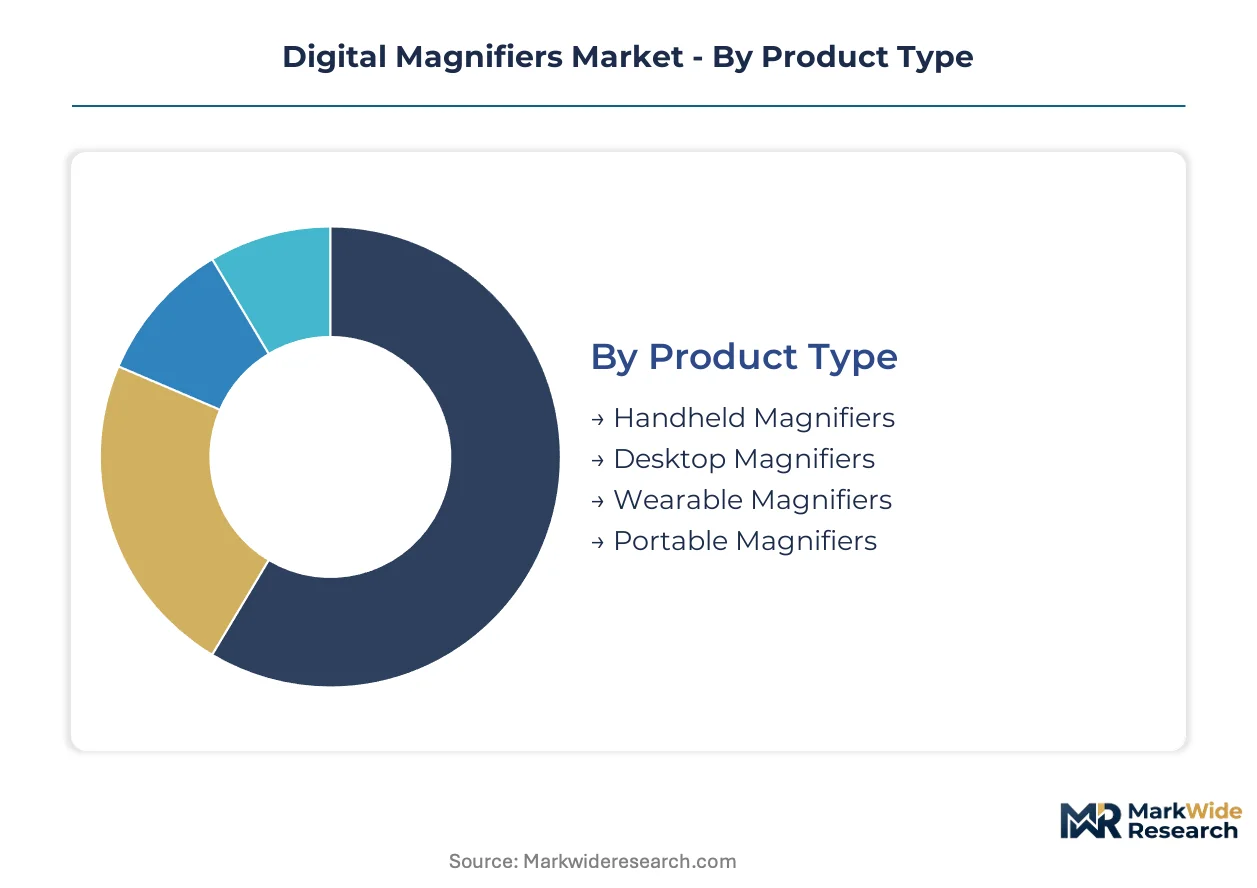
Product architecture in digital magnifiers determines reimbursement pathways, procurement cycles, and technology refresh rates. Segmentation reveals where hardware margins concentrate versus where software-integrated platforms displace legacy devices.
Product Type:
Replacement cycles vary dramatically across form factors, with handheld units turning over fastest and desktop installations persisting for seven to ten years in institutional settings.
- Handheld Magnifiers:Battery-powered units with CMOS sensors and LCD screens deliver 2x to 25x magnification for mobile reading tasks. German statutory health insurance covers prescribed handheld units for registered visually impaired patients, driving volume through optical retailer networks.
- Desktop Magnifiers:Stationary systems integrate XY reading tables with large OLED displays offering 2x to 80x variable magnification. Healthcare providers and educational institutions in the United States prioritize these for permanent installation, accepting higher upfront costs for durability and screen real estate.
- Wearable Magnifiers:Head-mounted augmented reality designs attract technology-oriented users seeking hands-free operation. Veterans' affairs hospitals pilot these systems for macular degeneration patients.
- Portable Magnifiers:Mid-size units bridge handheld convenience with desktop screen dimensions, targeting students and mobile professionals. FDA 510(k) clearance requirements extend development timelines for therapeutic claims.
Desktop magnifiers dominate installed base in healthcare and education. Wearable magnifiers represent the fastest-expanding trajectory as AR overlays collapse price premiums previously commanded by specialized hardware.
Technology:
Component sourcing geography shapes cost structures, with Asian suppliers concentrating display panel production while image processing firmware development clusters in North America and Europe.
- Optical Technology:Traditional lens-based magnification persists in entry-tier devices where digital processing adds unacceptable latency. Eschenbach Optik anchors European distribution through specialized optical retailers leveraging these familiar form factors.
- Digital Display:Liquid-crystal and OLED panels enable adjustable contrast modes critical for low-vision users with photophobia or specific retinal conditions. Supply disruption risk concentrates among Korean and Taiwanese component manufacturers.
- Image Processing:Software-integrated platforms reshape institutional procurement frameworks, shifting specifications from hardware-centric to ecosystem-driven criteria. Freedom Scientific differentiates through firmware validation for Class II medical device claims.
- Cameras:High-resolution CMOS sensors capture text and objects for real-time magnification, with sensor advances enabling 80x ratios previously impossible with optical lenses alone.
Digital display technology commands the largest component spend. Image processing is where vendor differentiation and margin expansion concentrate.
End User:
Reimbursement eligibility separates addressable demand, with prescription-grade procurement flowing through medical channels and retail-tier volume bypassing insurance entirely.
- Individuals with Low Vision:Medicare coverage determinations in the United States create demand volatility for prescription-grade versus retail-tier devices. Direct-to-consumer channels now capture meaningful volume previously routed through dispensing opticians.
- Educational Institutions:Subscription-based leasing and pay-per-use financing lower upfront barriers for schools and universities previously priced out of desktop magnifier acquisitions.
- Healthcare Providers:Rehabilitation centers in Germany favor suppliers with established notified body relationships under MDR electromagnetic compatibility requirements, compressing vendor shortlists.
- Retail Users:Smartphone substitution threat concentrates here, as built-in accessibility magnification features on mainstream mobile devices challenge standalone handheld volumes at lower price points.
Healthcare providers anchor premium pricing through reimbursement pathways. Educational institutions represent the fastest volume expansion as leasing models penetrate budget-constrained procurement.
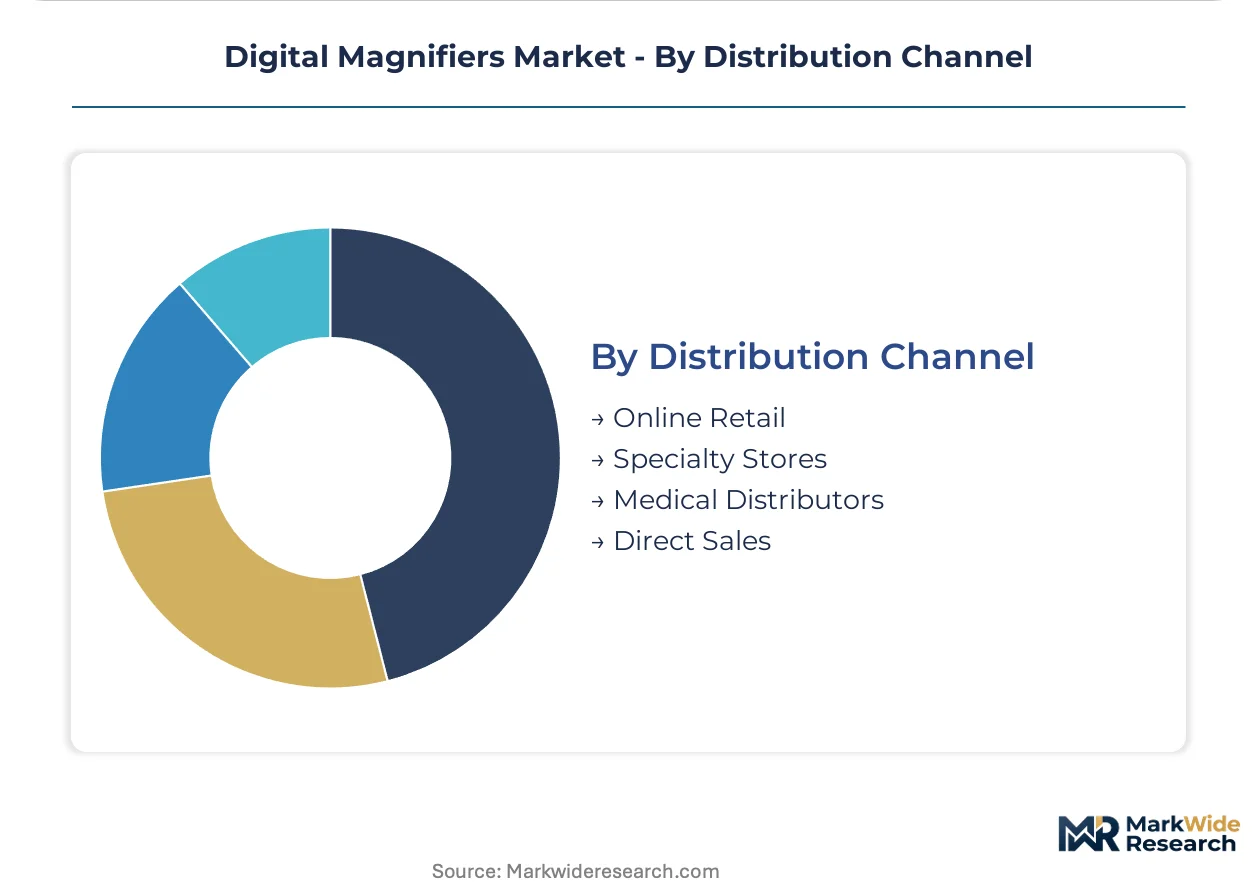
Distribution Channel:
Channel rotation accelerates where insurance reimbursement bypasses traditional intermediaries, fragmenting the competitive landscape between specialized and general medical device distributors.
- Online Retail:HumanWare leverages direct-to-consumer visibility against general medical distributors, competing for search placement and review aggregation. This channel is most visible in North American markets.
- Specialty Stores:Optical retailers and rehabilitation centers provide fitting services and training essential for complex desktop installations. German statutory insurance mandates dispensing through registered providers.
- Medical Distributors:Institutional procurement frameworks for hospitals and clinics require documented clinical performance data and CE marking validation under tightened MDR standards.
- Direct Sales:Enterprise contracts with educational systems and government agencies bypass channel margin, though sales cycles extend through budget approval processes.
Specialty stores dominate prescription-grade volume. Online retail is where price transparency and competitive pressure concentrate most intensely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of digital magnifiers concentrate from German and Japanese optical manufacturing clusters toward North American healthcare systems, while component imports of CMOS sensors and OLED panels stream from Taiwanese and Korean suppliers. This trade configuration shapes regional competitive positioning and regulatory compliance costs.
United States
Veterans' affairs hospitals in Palo Alto and Baltimore pilot head-mounted augmented reality systems for macular degeneration patients. The FDA's 510(k) clearance pathway for therapeutic intent devices extends product development timelines. Rehabilitation centers in the Boston-Cambridge cluster favor suppliers with documented clinical performance data.
Germany
Statutory health insurance covers prescribed electronic magnification systems for registered visually impaired patients, driving volume through optical retailer networks. The MDR electromagnetic compatibility framework tightens market entry standards for non-European manufacturers. Stuttgart and Munich host established notified body relationships that compress vendor shortlists.
Japan
Aging demographics expand procurement of assistive vision devices through municipal long-term care insurance programs. METI standards govern device safety and electromagnetic compatibility for domestic distribution. Osaka-based rehabilitation technology clusters integrate digital magnifiers into comprehensive low-vision service protocols.
United Kingdom
NHS England coverage determinations for prescription-grade versus retail-tier devices create demand volatility for institutional procurement. The EU Accessibility Act mandates procurement standards for public sector purchases despite post-Brexit regulatory divergence. London and Manchester rehabilitation centers favor leasing models for budget-constrained acquisitions.
South Korea
Display panel manufacturing concentrates among Seoul and Suwon suppliers, exposing producers to input cost volatility. The MFDS regulates digital magnifiers as medical devices requiring premarket notification. Busan-area distributors channel Korean-manufactured components into European and North American assembly operations.
Digital Magnifiers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor and display manufacturing. The vendor base spans three distinct strata: optical heritage houses with rehabilitation center relationships, software-integrated platform builders serving institutional procurement, and direct-to-consumer specialists leveraging online visibility. Competitive moves concentrate on geographic expansion through notified body relationships and portfolio diversification into wearable form factors.
Among North American platform builders, HumanWare and Freedom Scientific exemplify divergent channel strategies—one leveraging direct-to-consumer visibility, the other anchoring institutional procurement frameworks. Eschenbach Optik represents the optical heritage archetype with established European distribution through specialized retailers. These three occupy positions across the premium-system tier without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Vision Engineering |
| Eschenbach Optik |
| HumanWare |
| Freedom Scientific |
| Enhanced Vision |
| Dazor Lighting Technology |
| Koolertron |
| Vispero |
| Optelec |
| Others |
Pricing and Supply Chain Analysis
Seoul and Suwon display panel manufacturing clusters determine downstream pricing power for digital magnifier assemblers, with OLED and liquid-crystal capacity utilization directly translating into component cost volatility that squeezes hardware margins across North American and European finished goods markets.
Pricing Analysis
Healthcare providers and educational institutions anchor a three-tier pricing structure across premium, standard, and economy levels, with FDA 510(k) clearance tier and CE marking under MDR electromagnetic compatibility requirements commanding substantial premiums over retail-grade alternatives. Pricing pressure stems from smartphone substitution threatening handheld unit volumes at entry price points. Educational leasing subscribers exhibit highest price sensitivity, while Veterans' affairs hospital procurement demonstrates lowest sensitivity due to dedicated assistive technology budgets.
Supply Chain Analysis
Tariff exposure between South Korea and the United States dominates supply chain risk planning for display-dependent device manufacturers. Component sourcing concentrates in Taiwan, South Korea, and Japan for CMOS sensors, OLED panels, and image processing chipsets. Raw material dependencies span rare earth elements for display phosphors, high-purity silicon for sensor fabrication, and specialized optical glass for lens assemblies. Distribution runs through medical device distributors for institutional procurement and direct-to-consumer channels for retail-tier volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among healthcare procurement consortia and educational leasing platforms, fragmenting vendor pricing power as institutional frameworks displace individual purchasing decisions across North America and Europe.
For Market Incumbents: Build regulatory moats through accelerated FDA 510(k) submissions and MDR notified body relationship expansion in Stuttgart and Munich. Deepen backward integration into image processing firmware development to defend against software-integrated platform entrants. Eschenbach Optik's European optical retailer network demonstrates channel control value against direct-to-consumer erosion. For New Entrants and Emerging Players: Portable magnifiers for students and mobile professionals in budget-constrained educational systems represent the most penetrable entry point, with subscription-based leasing models lowering upfront adoption barriers. Veterans' affairs hospital pilot programs for head-mounted AR designs offer institutional validation pathways. Target pay-per-use financing partnerships with university disability services offices as primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-essential play because aging population assistive device demand exhibits inelastic reimbursement-backed characteristics through Medicare and German statutory health insurance. Acquisition targets should emphasize software-integrated platform builders with Class II medical device validation capabilities. Monitor FDA coverage determination expansions for prescription-grade wearable magnifiers as inflection indicator for category acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket notification timelines directly determine revenue recognition speed for therapeutic-claim devices. |
| MDR CE Marking Pathway Investment | Notified body relationships in Germany compress vendor shortlists for European rehabilitation center procurement. |
| Hospital System Partnership Development | Veterans' affairs pilot programs provide clinical validation and institutional reference accounts. |
| Software Companion Development | Firmware-integrated platforms shift procurement criteria from hardware specs to ecosystem value. |
| Reimbursement Strategy Expansion | Medicare and statutory insurance coverage determinations shape addressable demand for prescription-grade tiers. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with rehabilitation center directors, biomedical engineers, GPO contracts managers, and low-vision assistive technology specialists; and secondary validation through FDA 510(k) filings, CMS Medicare coverage determinations, MDR CE marking databases, and hospital procurement records. Bottom-up unit shipment estimates triangulated against top-down reimbursement flow analysis across the analysis window.
Forecast inputs span product type segmentation by handheld, desktop, portable, and wearable form factors; technology tier by optical, digital display, image processing, and camera sensor; and end user category by individuals with low vision, educational institutions, healthcare providers, and retail users. CAGRs were derived from modeled adoption curves incorporating camera sensor resolution advancement rates and reimbursement policy elasticity assumptions.
Practitioners should monitor FDA coverage determination revisions, MDR electromagnetic compatibility testing requirement changes, and OLED panel capacity utilization rates for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Middle East and Africa Aligner Sheet Market
Medical Devices
Brazil Cardiac Pacemakers Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
Luer Lock Connector Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Prefillable Inhalers Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Repositioning and Offloading Devices Market
Medical Devices
Electrosurgery Accessories Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Intraocular Lens (IOL) Market