
 North America Mini and Midi Horizontal Directional Drilling Market | 2026-2036
North America Mini and Midi Horizontal Directional Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mini and Midi Horizontal Directional Drilling Market Insights
Specification-grade rig upgrades toward automated rod handling and real-time bore telemetry is unwinding legacy equipment cycles across the contractor base. Vermeer Corporation leverages its manufacturing scale in Pella, Iowa to dominate the midi rig tier for gas utility contracts. The Charles Machines Works, Inc. (Ditch Witch) anchors the mini rig segment through its entrenched dealer network serving municipal water departments. Ellingson Companies differentiates by controlling specialized tooling supply for river crossing installations in the Upper Midwest.
Mini and midi horizontal directional drilling encompasses steerable trenchless excavation using rigs rated below 100,000 pounds of pullback force, employing mud motors, bent-sub housings, and wireline steering tools to install subsurface infrastructure without surface disruption. The primary purpose is utility corridor construction beneath obstacles including roadways, waterways, and existing infrastructure where open-cut methods prove infeasible or cost-prohibitive. The end user dimension shows telecom outpacing other verticals as fiber densification accelerates, while gas utilities represent the most mature margin pool with predictable replacement cycles. Within product type, midi drill rigs capture the fastest expansion as contractors upsize to handle larger diameter product pipes in single-pass operations.
OSHA excavation standards and DOT pipeline safety regulations in the United States, alongside Transport Canada integrity management requirements, collectively mandate documented bore path accuracy and pressure-testing protocols that elevate equipment specification thresholds. The Federal Communications Commission's broadband equity programs indirectly stimulate rig demand by funding last-mile fiber construction in underserved census tracts. Stakeholders must monitor how EPA methane emissions rules for distribution pipelines reshape contractor equipment specifications and maintenance intervals.
Market Dynamics
Specification-grade rig upgrades toward automated rod handling and real-time bore telemetry is unwinding legacy equipment cycles across the North American contractor base. The EPA's underground injection control standards are tightening borehole integrity requirements, pushing contractors toward higher-specification midi rigs and compressing replacement timelines for aging fleets.
Growth Catalysts
- Fiber-to-the-Home Deployment:Telecom carriers across the United States and Canada are accelerating rig utilization to meet last-mile construction targets in underserved census tracts.
- EPA Underground Injection Control Standards:The EPA's tightening borehole integrity requirements mandate documented bore path accuracy and pressure-testing protocols that elevate equipment specification thresholds.
- Permian Basin Utility Corridors:Texas concentrates demand where oilfield infrastructure and metropolitan fiber buildouts overlap, creating sustained rig utilization.
Market Restraints
- Steel Input Cost Volatility:Drill pipe and tooling fabrication faces margin pressure from fluctuating alloy steel prices and specialized heat-treatment energy costs.
- Dealer Network Concentration:The Upper Midwest and Great Plains rely on a limited set of authorized service points, creating geographic supply risk for parts and technical support.
- Horizontal Bore Length Limitations:Mini rigs face technical constraints pushing 600-foot continuous runs, forcing multi-pass operations that extend project timelines.
Strategic Opportunities
- Canadian Broadband Equity Programs:Federal funding for rural internet infrastructure in Ontario and Alberta creates white space for midi rig deployment outside traditional oilfield corridors.
- Mud Motor and Wireline Convergence:Integration of rotary steerable systems with conventional bent-sub housings enables single-pass installation of larger diameter product pipes.
- Rental and Lease Channel Expansion:Contractor preference for operational flexibility over capital ownership is opening fleet management partnerships with equipment financiers.
Industry Challenges
- Driller Certification Bottlenecks:OSHA excavation standards and DOT pipeline safety regulations mandate documented operator competency, creating talent pipeline constraints as experienced drillers retire.
- Legacy Fleet Integration Complexity:Contractors face friction retrofitting analog rod handling systems with digital telemetry packages, delaying specification compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mini and Midi Horizontal Directional Drilling Market |
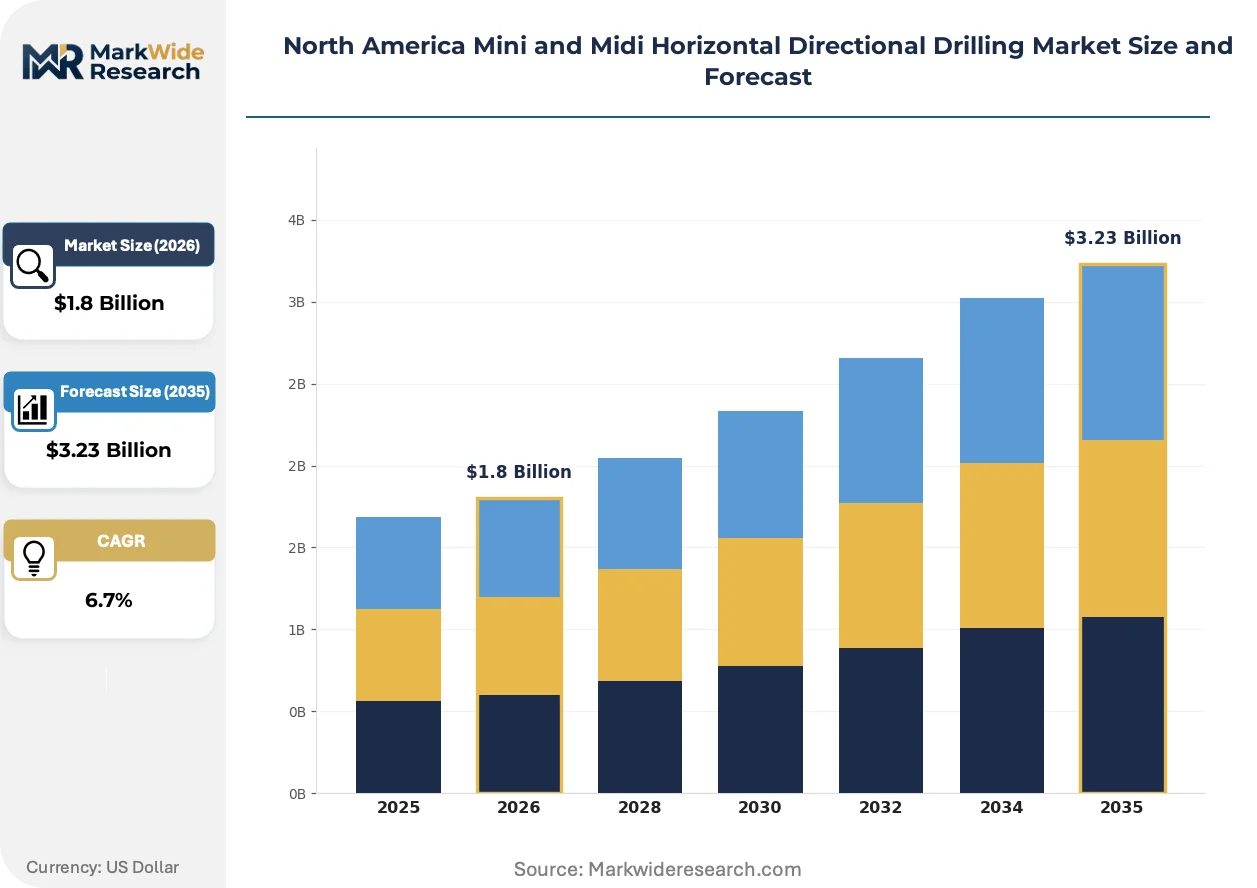
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Drill Rigs, Midi Drill Rigs, Accessories, Tools End User: Telecom, Water Utilities, Gas Utilities, Construction Installation Type: Onshore, Offshore, Urban, Rural Application: Pipeline Installation, Cable Installation, Utility Placement, Foundation Systems |
| Companies Covered | Creighton Rock Drill Ltd., Ellingson Companies, Barbco, Inc., Horizontal Technology, Inc., Ferguson Michiana Inc., Vermeer Corporation, Direct Horizontal Drilling, Inc., Inrock Drilling Systems, Incorporated, The Charles Machines Works, Inc. (Ditch Witch), Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mini and Midi Horizontal Directional Drilling Market Trends and Innovations
Automated drilling workflows and real-time subsurface imaging are compressing project timelines and reshaping contractor competitive positioning across North American utility corridors. Three distinct developments are accelerating this transformation.
Walk-over locating systems paired with magnetic steering tools are displacing traditional wireline guidance methods in urban fiber deployments. Municipal water departments and telecom contractors in Texas and California are adopting these integrated packages to reduce surface crew requirements. The technology is displacing manual stake-and-sight practices that previously required lane closures and traffic control.
The EPA's methane emissions rules for distribution pipelines are mandating tighter bore integrity documentation and extended pressure-testing intervals. Gas utilities in the United States must now demonstrate continuous casing monitoring capabilities that exceed legacy mechanical integrity standards. The regulation is forcing midi rig operators to upgrade telemetry packages and maintenance logging systems ahead of scheduled replacement cycles.
Outcome-based rental agreements are replacing traditional equipment purchase models among mid-size contractors serving municipal segments. Fleet availability guarantees and bundled tooling subscriptions now dominate procurement conversations in the Great Lakes region. Canada shows the fastest uptake, where provincial infrastructure programs favor contractors with demonstrated uptime metrics over asset ownership.
North America Mini and Midi Horizontal Directional Drilling Market Segmentation
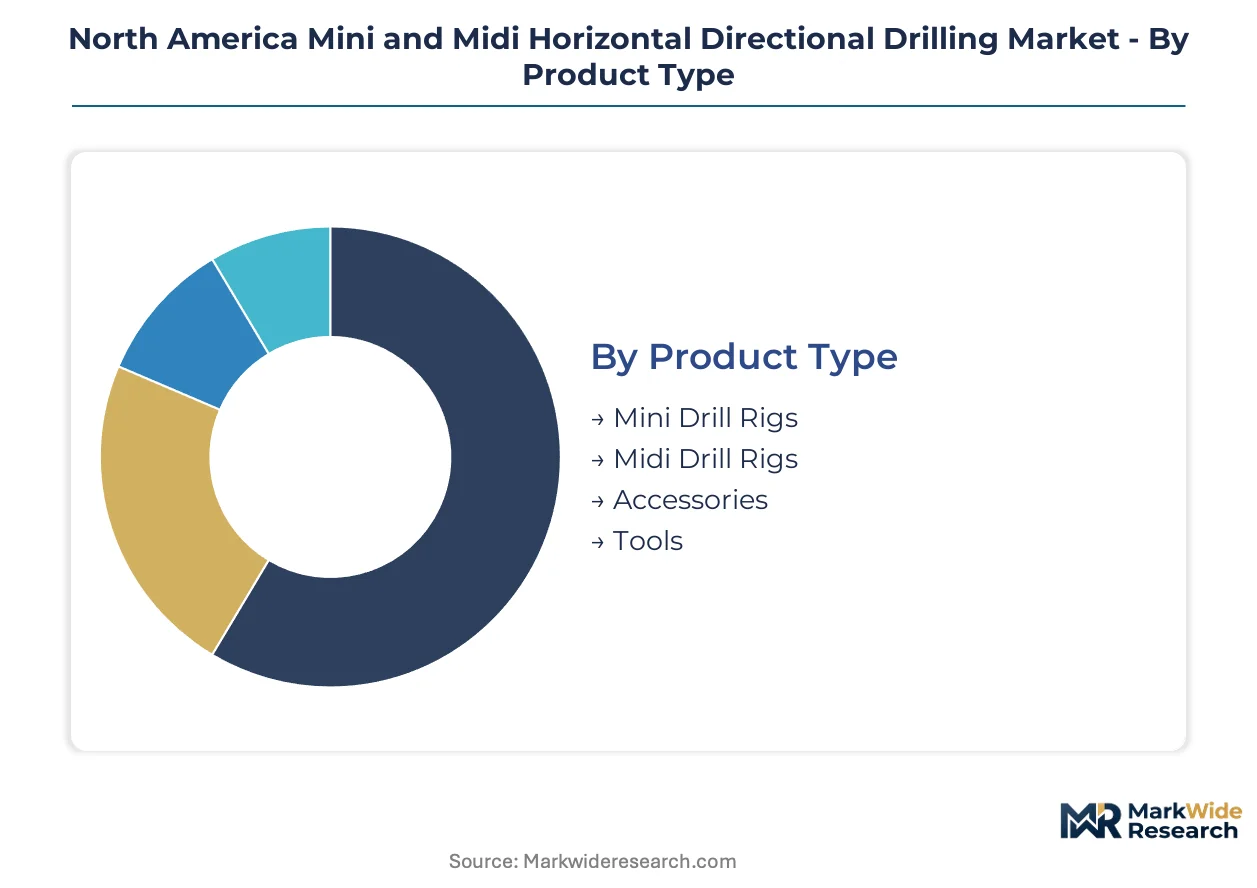
Horizontal directional drilling equipment segments by pullback force rating, end-use vertical, and operating environment. Channel configuration varies sharply: mini rigs move through municipal procurement channels, midi rigs through gas utility fleet programs, and tooling through specialized rental networks.
Product Type:
Channel mix splits sharply by specification tier. Mini rigs flow through municipal water department bids and telecom contractor lease pools. Midi rigs concentrate in gas utility direct procurement and oilfield service fleet rotations. Tooling and accessories distribute through regional dealer networks with OEM captive supply agreements.
- Mini Drill Rigs:Rated below 40,000 pounds pullback, these units deploy mud motors and walk-over locating systems for fiber-to-the-home drops and water service laterals. Municipal water departments in Texas and California concentrate demand as EPA underground injection control standards tighten bore integrity documentation requirements.
- Midi Drill Rigs:Spanning 40,000 to 100,000 pounds pullback, these systems handle gas distribution mains and larger diameter product pipes in single-pass operations. Gas utilities in the Permian Basin corridor and Upper Midwest drive replacement cycles as methane emissions rules mandate upgraded telemetry packages.
- Accessories:Rod racks, fluid recycling systems, and pressure-testing manifolds that contractors bundle into fleet availability guarantees.
- Tools:Drill pipe, reamers, and specialized housings fabricated from alloy steel grades subject to heat-treatment energy cost volatility.
Mini drill rigs dominate installed base count across municipal fleets. Midi drill rigs are where expansion concentrates as contractors upsize for larger diameter single-pass installations.
End User:
Margin structure varies by customer sophistication and replacement cycle predictability. Gas utilities command the most mature margin pool with documented maintenance intervals. Telecom carriers show the steepest volume trajectory but compress margins through competitive bidding.
- Telecom:Fiber densification projects across the United States and Canada accelerate rig utilization for last-mile construction. FCC broadband equity programs fund contractors serving underserved census tracts, concentrating demand in Texas metropolitan buildouts and rural Ontario corridors.
- Gas Utilities:Distribution pipeline replacement programs operate on predictable cycles with specification-grade equipment requirements. EPA methane emissions rules and DOT pipeline safety regulations mandate documented bore path accuracy and continuous casing monitoring capabilities.
- Water Utilities:Municipal departments prioritize mini rigs for service lateral installation beneath roadways without surface disruption.
- Construction:General contractors deploy rental fleets for foundation systems and temporary utility crossings on commercial development sites.
Gas utilities anchor specification-grade revenue. Telecom is climbing the fastest as fiber-to-the-home deployment accelerates rig utilization across North American markets.
Installation Type:
Operating environment dictates rig specification and crew certification requirements. Urban constraints elevate demand for automated rod handling and real-time bore telemetry. Rural deployments favor walk-over locating systems with reduced surface crew footprints.
- Onshore:Standard utility corridor construction beneath roadways, railways, and existing infrastructure across the United States and Canada. OSHA excavation standards mandate documented operator competency and bore path accuracy protocols.
- Offshore:Specialized river crossing installations in the Upper Midwest requiring bent-sub housings and wireline steering tools for continuous bore integrity.
- Urban:Dense metropolitan fiber buildouts in Texas and California cities where lane closures and traffic control costs drive trenchless method adoption.
- Rural:Canadian provincial infrastructure programs in Ontario and Alberta favor contractors with demonstrated uptime metrics over asset ownership.
Urban installations concentrate premium specification demand. Rural corridors are where Canadian broadband equity programs open white space for midi rig deployment outside traditional oilfield markets.
Application:
Project scale and product pipe diameter determine rig tier selection. Pipeline installation commands the highest specification thresholds with pressure-testing documentation requirements. Cable installation tolerates lighter mini rigs with reduced telemetry packages.
- Pipeline Installation:Gas distribution mains and oilfield gathering lines require midi rigs with automated rod handling and real-time bore telemetry. DOT pipeline safety regulations and EPA underground injection control standards elevate equipment specification thresholds.
- Cable Installation:Fiber optic and copper telecommunications cables deploy through mini rigs with walk-over locating systems in urban fiber densification projects.
- Utility Placement:Water and sewer force mains, electrical conduits, and district heating pipes.
- Foundation Systems:Geotechnical anchors and structural supports for commercial construction.
Pipeline installation anchors gas utility procurement volume. Cable installation is gaining share fastest as FCC broadband equity programs fund last-mile fiber construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian midi rig manufacturers supply equipment southward to American contractors building fiber corridors beneath the Great Lakes states. This cross-border trade flow intensifies as FCC broadband equity programs fund last-mile construction across underserved census tracts.
United States
Texas concentrates rig demand where Permian Basin oilfield corridors overlap with metropolitan fiber buildouts in Dallas-Fort Worth and Houston. EPA underground injection control standards tighten borehole integrity requirements, elevating equipment specification thresholds for contractors. The Upper Midwest industrial cluster around Minnesota and Wisconsin specializes in river crossing installations requiring bent-sub housings and wireline steering tools.
Canada
Federal broadband equity programs in Ontario and Alberta create white space for midi rig deployment outside traditional oilfield markets. Transport Canada integrity management requirements mandate documented bore path accuracy protocols that match American DOT pipeline safety regulations. Quebec's municipal water departments anchor mini rig procurement through provincial infrastructure tenders prioritizing trenchless methods beneath aging urban roadways.
Mexico
Cross-border utility corridor construction beneath the Rio Grande and shared infrastructure zones drives specialized tooling demand from American contractors. The country's national energy regulator oversees pipeline safety standards that increasingly align with US DOT protocols for bore integrity documentation. Northern border states concentrate deployment as telecom carriers extend fiber networks toward manufacturing clusters in Nuevo León and Tamaulipas.
North America Mini and Midi Horizontal Directional Drilling Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and specification-grade manufacturing dimensions. The vendor base splits between scale-driven OEMs with captive dealer networks and regional fabricators serving specialized tooling niches. Three archetypes dominate: integrated rig manufacturers controlling distribution channels, independent tooling specialists supplying mud motors and reamers, and contractor-affiliated equipment lessors bundling fleet availability guarantees. Competitive moves concentrate on vertical integration into fluid recycling systems and geographic expansion through authorized service point density.
Within the integrated manufacturing tier, Vermeer Corporation and The Charles Machines Works, Inc. (Ditch Witch) exemplify scale-driven OEMs with established dealer networks across the Great Plains and Upper Midwest. Ellingson Companies occupies a position as a contractor-affiliated specialist controlling river crossing tooling supply. These three entities represent distinct competitive vectors: manufacturing scale, distribution reach, and application-specific expertise.
| Leading Market Players |
|---|
| Creighton Rock Drill Ltd. |
| Ellingson Companies |
| Barbco, Inc. |
| Horizontal Technology, Inc. |
| Ferguson Michiana Inc. |
| Vermeer Corporation |
| Direct Horizontal Drilling, Inc. |
| Inrock Drilling Systems, Incorporated |
| The Charles Machines Works, Inc. (Ditch Witch) |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day lead times for alloy steel drill pipe from domestic forges concentrate pricing power with Tier-1 rig manufacturers who maintain captive heat-treatment capacity, while spot-market buyers face volatile surcharges tied to energy-intensive processing costs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the midi rig tier, with premium-mid-economy pricing differentiation driven by EPA certification grade and bundled telemetry service levels. Cost compression in the mini rig segment is intensifying because municipal procurement departments consolidate vendor lists around uptime guarantees. Telecom contractors show the highest price sensitivity due to competitive fiber buildout bidding, whereas gas utilities accept specification premiums for documented bore integrity compliance.
Supply Chain Analysis
Strait of Hormuz transit risk for alloy steel feedstock from specialty mills in Germany, Japan, and South Korea elevates inventory carrying costs across North American rig fabricators. Component fabrication draws from heat-treated drill pipe, bent-sub housings, and mud motor assemblies. Single-source vulnerability concentrates in wireline steering tool electronics sourced from limited semiconductor foundries. Distribution runs through authorized dealer networks with OEM captive supply agreements for tooling and aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against open-cut trenching methods that municipalities may revert to if fiber deployment timelines compress or regulatory enforcement loosens.
For Market Incumbents: Consolidate tooling supply chains through backward integration into fluid recycling systems and pressure-testing manifold fabrication. Defend against rental channel disruption by embedding fleet availability guarantees into municipal procurement specifications. Prioritize EPA methane emissions compliance certification as a procurement gate. For New Entrants and Emerging Players: Lead with outcome-based rental agreements targeting Canadian provincial infrastructure programs in Ontario and Alberta where asset-light contractors dominate. The most penetrable white space sits in river crossing specialized tooling for Upper Midwest installations. Pursue go-to-market partnerships with equipment financiers bundling maintenance subscriptions. For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle infrastructure play because fiber densification and gas utility integrity mandates sustain predictable equipment refresh demand. Acquisition targets should display captive distribution density across the Great Plains or specialized application expertise in automated rod handling. The signal to watch is EPA enforcement intensity for underground injection control standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment Capacity | Captive alloy steel processing insulates margins from energy cost volatility and EPA compliance timelines. |
| Automated Rod Handling Platform Launch | Reduces crew certification bottlenecks while meeting OSHA excavation standards for documented operator competency. |
| Fleet Availability Guarantee Partnership | Aligns procurement models with Canadian provincial infrastructure programs favoring uptime metrics over ownership. |
| Real-Time Bore Telemetry Certification | Positions midi rigs for EPA methane emissions rules mandating continuous casing monitoring capabilities. |
| Specialized Tooling Joint Venture | Combines river crossing expertise with wireline steering tool supply for Upper Midwest utility corridors. |
Research Methodology
Operator-level perspectives from rig fleet managers, municipal water department procurement officers, gas utility integrity engineers, and telecom construction project directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement databases, FCC broadband equity program disbursement records, DOT pipeline safety incident reports, and SEC filings from listed equipment manufacturers. Bottom-up rig count modeling triangulated against top-down utility capital expenditure forecasts.
Sensitivity analysis tested demand assumptions across the projection horizon, with segmentation modeled by pullback force tier, end-use vertical, and operating environment complexity. CAGRs derived from equipment replacement cycle analysis and fiber deployment velocity metrics. Industry-specific inputs included Permian Basin utility corridor construction permits and Canadian provincial broadband tender awards.
Forecasts assume regulatory continuity in EPA underground injection control standards and DOT pipeline safety protocols; material policy shifts would require re-modeling equipment specification thresholds and replacement timelines. Practitioners should keep alternative scenarios live as FCC broadband equity funding allocations and OSHA driller certification requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Bale Openers Market
Construction Equipment
Plasma Cutting Equipment Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Manual Welding Positioner Market
Construction Equipment
India Construction Equipment Rental Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Global Construction Dumper Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Electric Hot Chamber Die Casting Machines Market
Construction Equipment
Hoist and Winches Market