
 Geophysical Services Market | 2026-2036
Geophysical Services Market Size, Share, and Industry Trends Forecast 2026-2036
Geophysical Services Market Intelligence
Data processing and imaging subscriptions is realigning how geophysical contractors monetize their asset bases. CGG SA leverages its global multi-client library to sustain recurring revenue streams from repeat licensing. Schlumberger anchors its competitive position through integrated seismic-to-drilling workflows that reduce exploration cycle times. PGS ASA specializes in ocean-bottom node technology, differentiating its offering in deepwater environments where towed-streamer acquisition faces physical limits.
Geophysical services encompass the acquisition, processing, and interpretation of subsurface physical property data—seismic wave propagation, gravitational anomalies, magnetic field variations, and electrical conductivity—using specialized sensor arrays, source mechanisms, and high-performance computing clusters to render geological models for resource identification and engineering design. Seismic surveying dominates value generation due to its irreplaceable role in hydrocarbon trap delineation, while electromagnetic surveying represents the fastest-expanding modality as mining operators deploy airborne tensor systems to locate conductive ore bodies beneath cover. Oil and gas exploration commands the largest application share, though environmental assessment is gaining structural importance as regulators mandate baseline subsurface characterization before infrastructure approval.
The U.S. Bureau of Ocean Energy Management, Norway's Petroleum Safety Authority, and the UK's North Sea Transition Authority collectively shape operational parameters through environmental impact mandates, decommissioning liability frameworks, and emission disclosure requirements that elevate survey precision standards. The EU's CSRD and methane performance thresholds are forcing exploration firms to document subsurface integrity across the full project lifecycle, embedding geophysical monitoring into compliance architecture. Stakeholders must monitor how dual-use technology transfer restrictions between seismic imaging and defense applications reshape vendor qualification criteria and contract eligibility.
Market Dynamics
Post-Macondo environmental review protocols from the U.S. Bureau of Ocean Energy Management have extended seismic survey timelines while elevating data quality standards, forcing contractors to reconfigure acquisition strategies around compliance architecture rather than pure exploration economics.
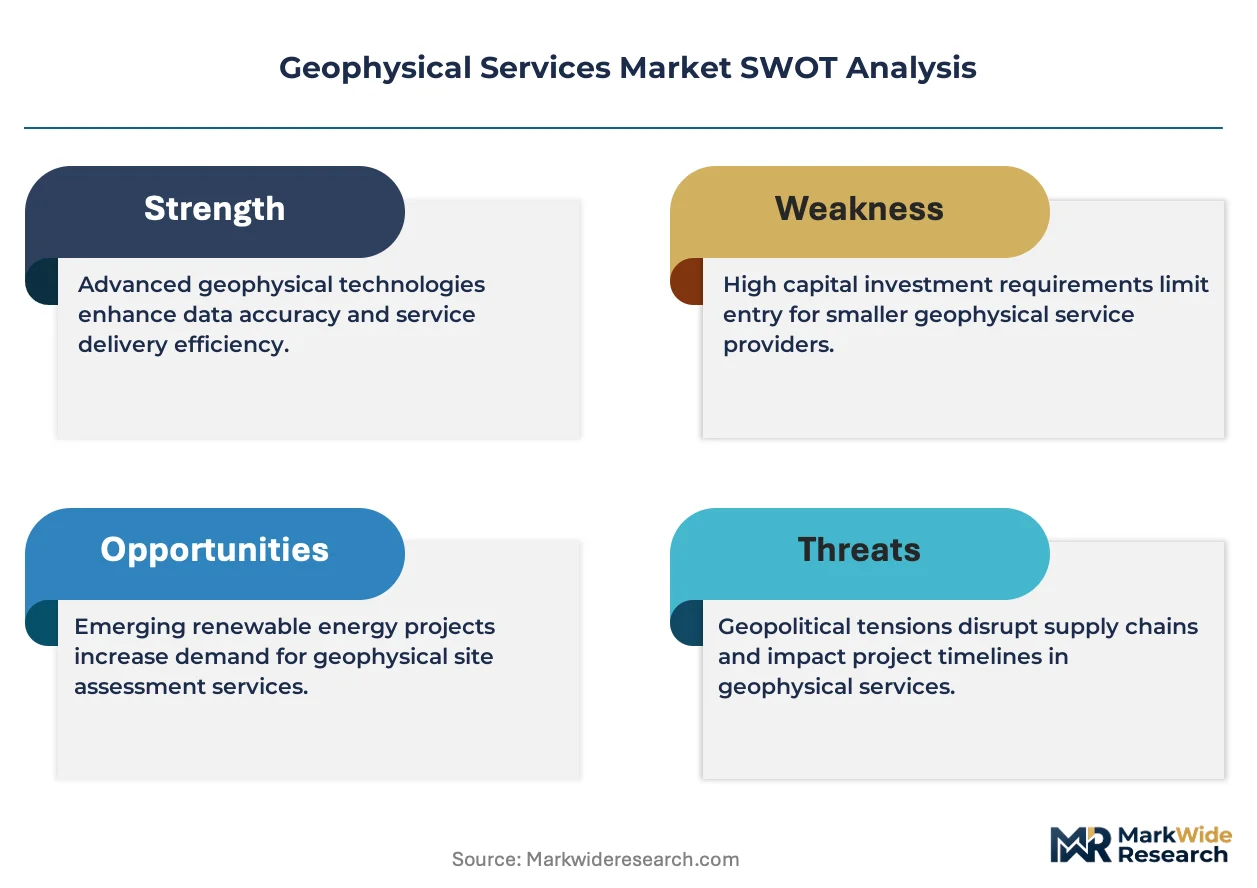
Growth Catalysts
- Offshore de-risking mandates:Oil exploration firms in the Gulf of Mexico basin are expanding 3D seismic procurement to satisfy tightened drilling commitment protocols. Multi-client library investments by contractors deepen data availability for repeat licensing.
- CSRD methane disclosure:The EU's Corporate Sustainability Reporting Directive forces exploration firms to document subsurface integrity across full project lifecycles, embedding continuous geophysical monitoring into compliance infrastructure.
- Airborne electromagnetic tensor systems:Mining operators deploy these sensor arrays to locate conductive ore bodies beneath cover, expanding addressable survey modalities beyond hydrocarbon applications.
Market Restraints
- Specialized vessel scarcity:Ocean-bottom node deployment requires purpose-built seismic vessels with limited global fleet capacity, creating acquisition bottlenecks in deepwater basins.
- Extended permitting cycles:The U.S. Bureau of Ocean Energy Management's post-Macondo protocols add 12-18 months to environmental review timelines, compressing contractor utilization rates.
- High-performance computing dependency:Advanced imaging algorithms require GPU clusters with volatile semiconductor supply chains, exposing processing margins to input cost swings.
Strategic Opportunities
- Carbon capture site characterization:Saline aquifer and depleted reservoir assessment for sequestration projects creates new demand for subsurface integrity verification beyond hydrocarbon extraction.
- Ocean-bottom node technology convergence:Integration of autonomous underwater vehicle deployment with nodal acquisition reduces vessel time and expands access to complex bathymetry.
- UK North Sea decommissioning liability:The North Sea Transition Authority's baseline characterization mandates before infrastructure removal generate recurring survey requirements in mature basins.
Industry Challenges
- Geophysicist talent scarcity:Specialized expertise in quantitative interpretation and full-waveform inversion faces generational replacement gaps as university programs contract.
- Legacy data integration friction:Decades of 2D seismic archives require costly reprocessing to align with modern 3D survey standards for reservoir monitoring workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geophysical Services Market |
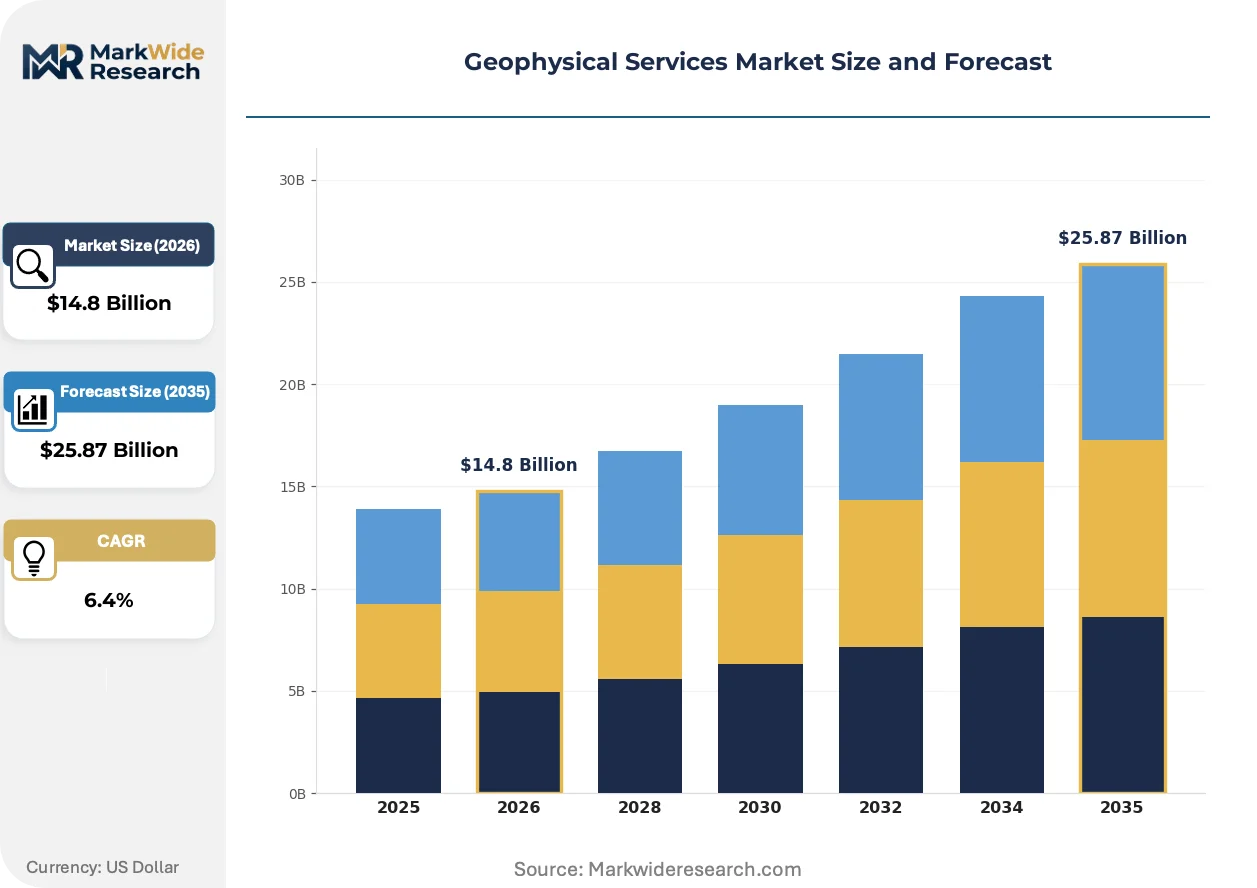
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Seismic Surveying, Magnetic Surveying, Gravity Surveying, Electromagnetic Surveying Application: Oil & Gas Exploration, Mineral Exploration, Environmental Assessment, Civil Engineering Projects Technology: 2D Seismic, 3D Seismic, Ground Penetrating Radar, Digital Elevation Model End User: Mining Companies, Oil Exploration Firms, Construction Contractors, Environmental Agencies |
| Companies Covered | CGG SA, COSL China Oilfield Services Limited, Schlumberger Limited, TGS Geophysical Company Limited, PGS ASA, Halliburton Company, BGP Inc., Shearwater GeoServices, Fugro N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geophysical Services Market Strategic Shifts & Innovations
Seismic-to-drilling workflow compression is reshaping how exploration firms consume geophysical intelligence, with real-time data transmission from acquisition vessels to cloud processing clusters collapsing decision cycles from months to weeks.
Full-waveform inversion is unifying velocity model building with reservoir characterization into single computational workflows. Supermajors and national oil companies are adopting this approach for pre-salt and deepwater projects where ray-based methods fail. The technology is unifying historically separate acquisition and processing vendor relationships into integrated performance contracts.
Norway's Petroleum Safety Authority has mandated continuous subsurface monitoring for all producing fields under revised facility regulations. Operators must now demonstrate trap integrity through 4D seismic repeat surveys at shortened intervals. This regulatory pressure is concentrating investment in permanent reservoir monitoring systems installed on the Norwegian continental shelf.
Subscription-based data licensing is displacing traditional single-use survey contracts across the Gulf of Mexico and West Africa. Exploration firms now prefer access to multi-client libraries with per-kilometer pricing over proprietary acquisition programs. This preference shift is most visible among independent operators in the U.S. outer continental lease rounds, where capital discipline favors variable cost structures over fixed seismic commitments.
Geophysical Services Market Segmentation
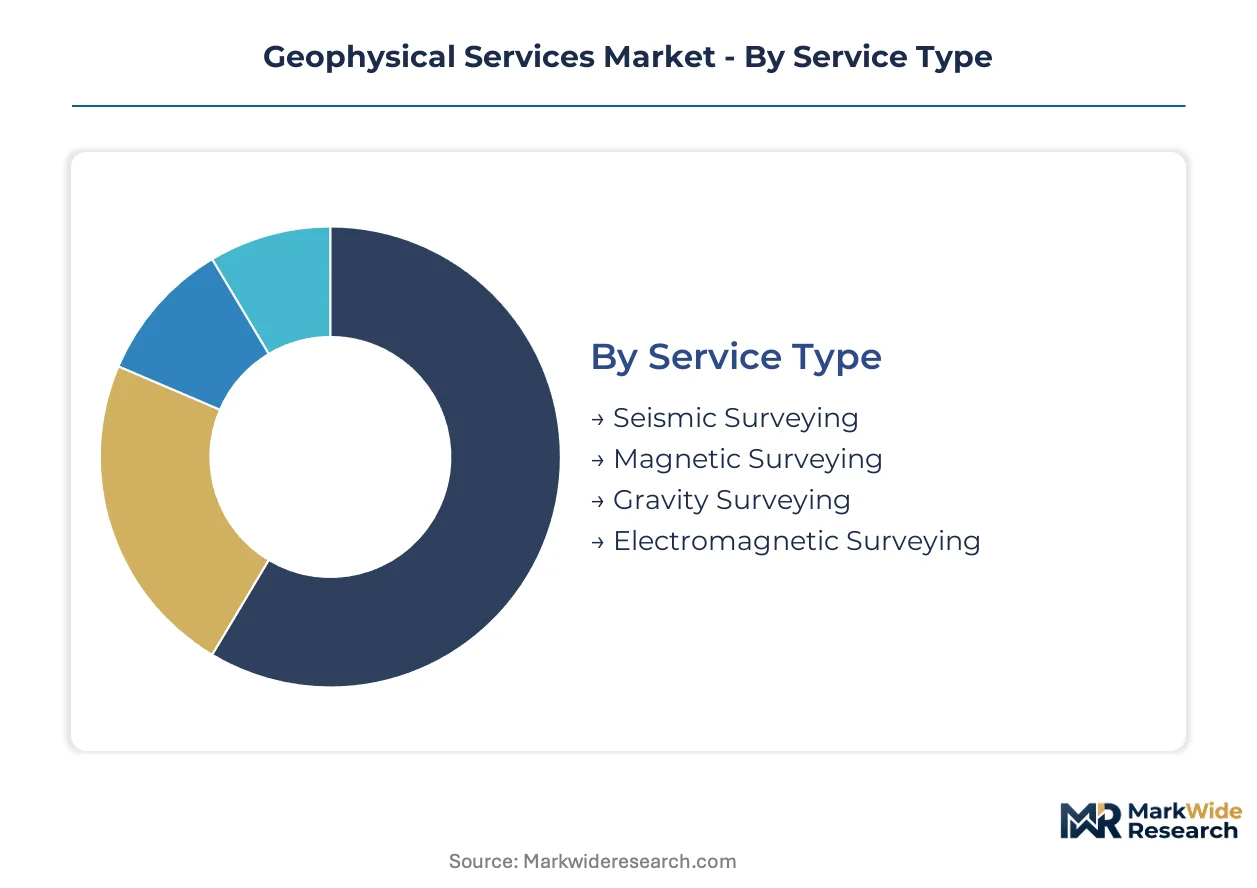
Geophysical service procurement decisions hinge on subsurface complexity, regulatory exposure, and capital efficiency requirements. Exploration firms calibrate survey modality against target depth, overburden density, and the economic consequences of interpretation error.
Service Type:
Buyers select survey modality based on target physical property contrast and interference tolerance.
- Seismic Surveying:Acoustic wave propagation imaging dominates hydrocarbon trap delineation through controlled source reflection profiling. Gulf of Mexico operators deploy 3D marine seismic to satisfy BOEM drilling commitment protocols, with multi-client library licensing displacing proprietary acquisition.
- Electromagnetic Surveying:Airborne tensor systems measure subsurface electrical conductivity variations to locate conductive ore bodies beneath cover. Mining operators in Australia and Canada are expanding fleet contracts for regional-scale greenfield screening.
- Magnetic Surveying:Total field and gradiometric measurements map ferromagnetic mineral distributions and basement structure.
- Gravity Surveying:Gravimeter arrays detect density contrasts for salt dome mapping and regional basin architecture definition.
Volume sits with Seismic Surveying; growth tilts toward Electromagnetic Surveying.
Application:
Regulatory mandate intensity and project lifecycle phase determine service procurement patterns.
- Oil & Gas Exploration:Trap delineation and reservoir characterization command the largest contract values through integrated seismic-to-drilling workflows. Norway's Petroleum Safety Authority mandates continuous subsurface monitoring, embedding 4D repeat surveys into production facility regulations.
- Environmental Assessment:Baseline characterization requirements precede infrastructure approval under EU CSRD methane disclosure frameworks. Saline aquifer assessment for carbon capture site selection is expanding electromagnetic and seismic deployment beyond extraction applications.
- Mineral Exploration:Greenfield screening and ore body delineation for base and precious metals.
- Civil Engineering Projects:Subsurface hazard identification for tunneling, dam foundation, and transportation corridor planning.
Revenue concentrates in Oil & Gas Exploration; Environmental Assessment is climbing the fastest.
Technology:
Resolution requirements and processing infrastructure availability shape technology adoption curves.
- 3D Seismic:Dense source-receiver geometries enable full-waveform inversion for velocity model building and reservoir characterization. Supermajors deploy this approach for pre-salt and deepwater projects where ray-based methods fail.
- Ground Penetrating Radar:High-frequency electromagnetic pulses resolve shallow subsurface structure for engineering and forensic applications. Construction contractors in urban environments deploy GPR for utility mapping and concrete integrity verification.
- 2D Seismic:Reconnaissance-scale profiling for regional basin screening where 3D economics are prohibitive.
- Digital Elevation Model:LiDAR and photogrammetric terrain products for geomorphological and hydrological analysis.
Investment flows toward 3D Seismic; GPR is gaining share fastest in near-surface applications.
End User:
Capital structure and technical staffing determine in-house versus outsourced survey execution.
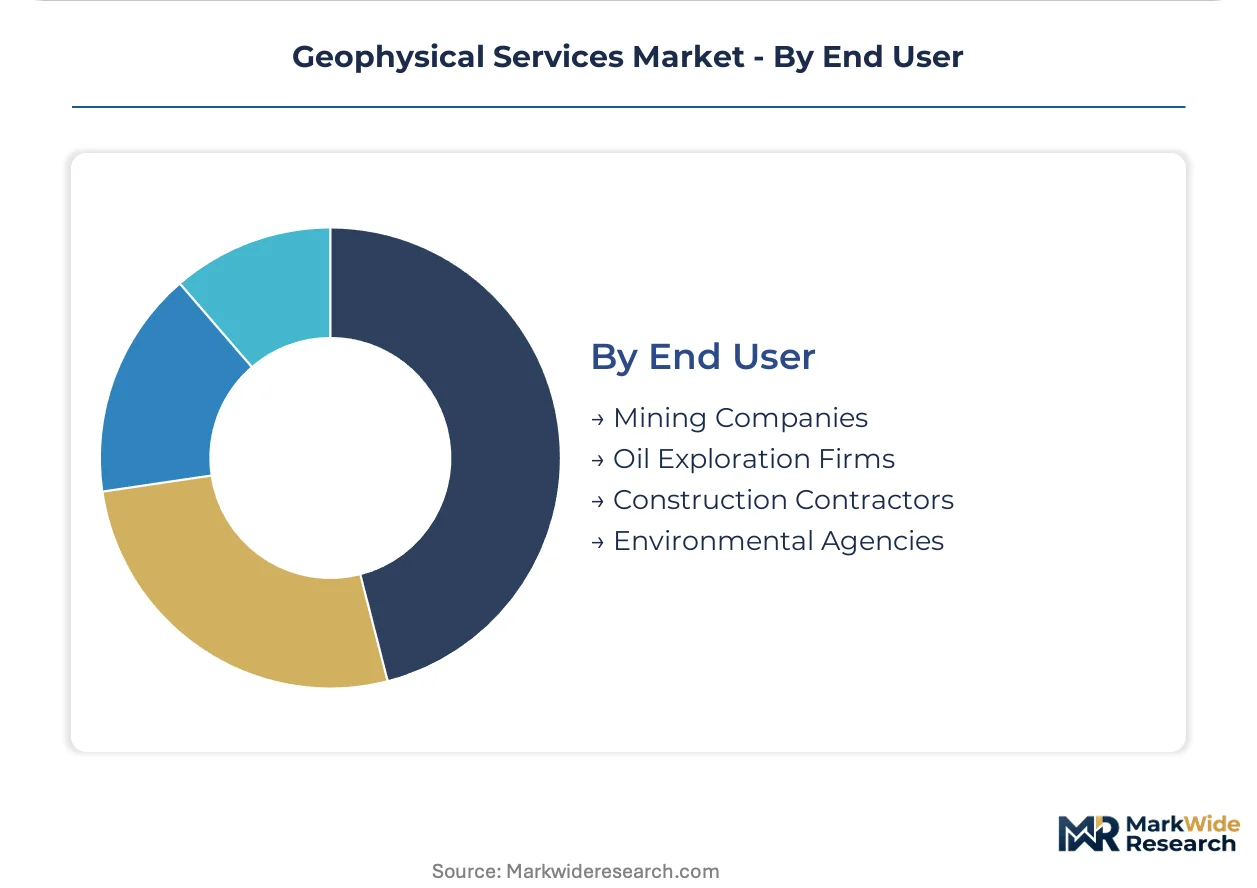
- Oil Exploration Firms:Integrated majors and independents procure seismic services through multi-client library subscriptions or proprietary acquisition programs. U.S. outer continental lease round participants favor per-kilometer pricing to preserve capital discipline.
- Mining Companies:Diversified majors and junior explorers contract airborne electromagnetic and magnetic surveys for greenfield screening. Australian and Canadian operators are expanding regional-scale fleet contracts for critical mineral target generation.
- Construction Contractors:Engineering firms procure GPR and seismic refraction for hazard identification.
- Environmental Agencies:Government bodies mandate baseline characterization and post-closure monitoring.
Contract value concentrates with Oil Exploration Firms; Mining Companies are expanding procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors geophysical service procurement through its concentration of supermajor headquarters and seismic contractor operations centers. The Gulf of Mexico basin drives contract volumes across the Americas, while North Sea decommissioning mandates and Asia-Pacific exploration programs shape demand patterns elsewhere.
United States
The Gulf of Mexico outer continental shelf sustains the largest 3D seismic procurement volumes globally as independent operators participate in BOEM lease rounds. The Bureau of Ocean Energy Management's post-Macondo environmental review protocols extend permitting timelines by 12-18 months while elevating data quality thresholds. Houston hosts CGG SA, Schlumberger, and Halliburton service coordination centers that manage multi-client library licensing across the basin.
Norway
Permanent reservoir monitoring systems command premium installation rates on the Norwegian continental shelf under revised facility regulations. The Petroleum Safety Authority mandates continuous subsurface monitoring for all producing fields, embedding 4D seismic repeat surveys into operational compliance. Stavanger and Bergen cluster specialized ocean-bottom node deployment vessels and quantitative interpretation expertise for pre-salt and deepwater projects.
United Kingdom
North Sea decommissioning liability frameworks generate recurring baseline characterization requirements before infrastructure removal. The North Sea Transition Authority mandates subsurface integrity verification for all cessation-of-production applications. Aberdeen concentrates specialist contractors performing legacy 2D seismic reprocessing and 4D monitoring system maintenance across mature basin assets.
China
BGP Inc. anchors domestic seismic acquisition capacity serving national oil company exploration programs in the South China Sea and Central Asian basins. The Ministry of Natural Resources regulates offshore survey permitting with environmental impact assessment requirements that align with international standards. Tianjin and Shenzhen host processing centers deploying high-performance computing clusters for full-waveform inversion workflows.
Brazil
Pre-salt polygon exploration drives demand for integrated seismic-to-drilling workflows where full-waveform inversion replaces ray-based methods. The National Petroleum Agency oversees environmental licensing for ultra-deepwater surveys with extended technical review cycles. Rio de Janeiro coordinates Petrobras procurement decisions and contractor vessel mobilization for Santos Basin multi-client programs.
Geophysical Services Market Key Industry Players
Capital-heavy seismic vessel operators compete with asset-light data processing specialists for contract margins and licensing revenue. The market structure concentrates around integrated energy service conglomerates, pure-play seismic contractors, and emerging autonomous survey technology developers. Three archetypes dominate: library-based multi-client licensors, integrated seismic-to-drilling workflow providers, and ocean-bottom node technology specialists. Competitive positioning depends on vessel fleet utilization rates, GPU cluster processing capacity, and proprietary algorithm differentiation.
Among French-based integrated geophysical service providers, CGG SA exemplifies the multi-client library archetype through recurring data licensing revenue streams. Schlumberger Limited anchors the integrated workflow tier, connecting seismic acquisition through drilling execution. PGS ASA represents the specialized technology vector with ocean-bottom node deployment capabilities for deepwater environments where conventional towed-streamer acquisition faces physical constraints.
| Leading Market Players |
|---|
| CGG SA |
| COSL China Oilfield Services Limited |
| Schlumberger Limited |
| TGS Geophysical Company Limited |
| PGS ASA |
| Halliburton Company |
| BGP Inc. |
| Shearwater GeoServices |
| Fugro N.V. |
| Others |
Cost & Logistics Intelligence
BOEM's post-Macondo environmental review protocols have forced exploration firms to absorb longer survey timelines and higher data quality thresholds, compelling seismic contractors to reprice contracts around compliance architecture rather than pure exploration economics. This demand-side specification shift concentrates pricing power with vessel operators possessing certified environmental management systems and GPU clusters capable of advanced imaging workflows.
Pricing Analysis
Margin tightening in proprietary acquisition reflects the displacement of single-use survey contracts by subscription-based multi-client library licensing across the Gulf of Mexico and West Africa. Three-tier pricing structure across premium, standard, and economy levels segments buyers by data vintage, resolution grade, and after-sales reprocessing rights. Pricing pressure stems from independent operators in U.S. outer continental lease rounds favoring per-kilometer variable cost structures over fixed seismic commitments. Mining companies deploying airborne electromagnetic tensor systems exhibit highest price sensitivity due to greenfield screening economics, while supermajors purchasing integrated seismic-to-drilling workflows demonstrate lowest sensitivity given cycle-time value capture.
Supply Chain Analysis
Regional distribution of ocean-bottom node deployment vessels follows a hub-and-spoke pattern centered on Stavanger, Houston, and Aberdeen, with specialized assets repositioning between basins based on permit activation schedules. Vessel manufacturing concentrates in Norway, South Korea, and Singapore, while GPU cluster processing capacity draws from semiconductor supply chains anchored in Taiwan and the United States. Raw material dependencies span high-tensile steel for streamer cables, rare-earth elements for electromagnetic sensors, and advanced ceramics for seismic source mechanisms. Single-source vulnerability in purpose-built seismic vessel hull construction creates acquisition bottlenecks during concurrent basin activation windows. Distribution runs through contractor-operated coordination centers managing multi-client library licensing and proprietary program execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geophysical service procurement operates as a supply-constrained market where specialized vessel scarcity and geophysicist talent gaps prop pricing power for qualified contractors. The limited global fleet of ocean-bottom node deployment assets creates structural bottlenecks that sustain margins despite demand volatility.
For Market Incumbents: Extend multi-client library depth in the Gulf of Mexico basin to capture recurring licensing revenue from repeat buyers, while expanding GPU cluster processing capacity to reduce dependency on volatile semiconductor supply chains. Defensive positioning requires investment in autonomous underwater vehicle integration for nodal deployment, addressing the emerging threat from asset-light data processing specialists capturing downstream margins. Certification investment in BOEM environmental management protocols preserves contract eligibility as regulatory thresholds tighten. For New Entrants and Emerging Players: Cloud-based seismic data marketplaces offer the most penetrable entry vector, enabling access to exploration firm procurement officers without vessel fleet capital requirements. Carbon capture site characterization for saline aquifer assessment represents an underserved application segment with lower incumbent saturation than hydrocarbon exploration. A direct-to-operator licensing model bypasses established contractor relationships in the environmental assessment vertical, where EU CSRD methane disclosure mandates create new demand for subsurface integrity verification. For Investors and Strategic Acquirers: The window for entry favors ocean-bottom node technology specialists with proprietary autonomous deployment capabilities and established relationships with Norway's Petroleum Safety Authority. Long-term viability hinges on positioning for the North Sea decommissioning wave, where baseline characterization mandates generate recurring survey requirements across mature basin infrastructure. The signal to watch is permanent reservoir monitoring system installation rates on the Norwegian continental shelf, indicating regulatory embedding of continuous geophysical monitoring into operational compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Client Library Expansion | CGG SA leverages recurring licensing revenue to reduce proprietary acquisition cyclicality in Gulf of Mexico contracting. |
| GPU Cluster Capacity Addition | Processing margin protection against semiconductor supply volatility enables full-waveform inversion workflow scaling. |
| Autonomous Underwater Vehicle Integration | Ocean-bottom node deployment cost reduction expands access to complex bathymetry previously excluded from survey economics. |
| Carbon Capture Site Characterization Service Launch | Saline aquifer assessment demand from EU CSRD compliance creates non-hydrocarbon revenue diversification. |
| Permanent Reservoir Monitoring System Installation | Norway's Petroleum Safety Authority mandates embed 4D seismic repeat surveys into production facility regulations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with seismic acquisition project managers, quantitative interpretation specialists, BOEM permitting officers, and exploration firm procurement directors. BOEM environmental review documentation, Norway Petroleum Safety Authority facility regulations, UK North Sea Transition Authority decommissioning frameworks, and EU CSRD implementation guidance provided regulatory boundary conditions. Bottom-up vessel fleet utilization modeling and top-down exploration capital expenditure triangulation validated market sizing across the analysis window.
Segmentation granularity modeled service type, technology modality, application vertical, and end-user capital structure at the country level for the United States, Norway, United Kingdom, China, and Brazil. CAGRs derived from regression against exploration well permit trajectories, offshore lease round participation rates, and mining greenfield investment flows. Industry-specific forecast inputs incorporated ocean-bottom node deployment vessel day-rate trends and GPU cluster processing capacity expansion schedules.
Inputs from contractor financial disclosures and regulatory agency permit databases were available through the study window; gaps in proprietary multi-client library licensing transaction data introduce uncertainty bands around recurring revenue projections. Forecasts reflect documented assumptions regarding BOEM permitting timeline stability and Norwegian continental shelf production facility regulation continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Foundation Repair Services Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
United States Engineering Services Market
Engineering Services
Bridge Inspection System Market
Engineering Services
Geotechnical Services Market
Engineering Services
Architectural Services Market
Engineering Services
Well Cementing Services Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Directional Drilling Services Market