
 Middle East Seismic Services Market | 2026-2036
Middle East Seismic Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Seismic Services Market Foresight
The capital-intensity divergence between full-stream providers and specialized contractors is collapsing as vessel-sharing agreements and multi-client libraries commoditize once-proprietary acquisition assets. Schlumberger Ltd leverages integrated geophysical-to-drilling workflows that anchor its position in Saudi Arabia's mega-field campaigns. CGG SA sustains competitive differentiation through high-performance computing clusters in Dubai that accelerate complex depth imaging for carbonate reservoirs. PGS ASA competes with Ramform vessel architecture optimized for broadband acquisition in the shallow-water Arabian Gulf.
Middle East seismic services encompass the subsurface data value chain spanning energy exploration, reservoir characterization, and geohazard identification through controlled-source acoustic surveys. These operations deploy towed streamer arrays, ocean-bottom nodes, or land vibroseis sources to capture reflected seismic waves, with modern surveys sampling at sub-10 meter receiver intervals to resolve thin-bed hydrocarbon traps beneath salt and anhydrite layers. Data acquisition commands the largest revenue share where vessel and crew day rates reflect tight supply of suitable offshore platforms, while 4D seismic represents the fastest-expanding technology segment as operators monitor waterflood fronts and gas-cap movement in mature fields. Processing and interpretation services capture concentrated margin pools where proprietary algorithms for anisotropic depth migration differentiate specialist providers serving national oil company tenders.
Saudi Arabia's national petroleum regulator mandates environmental impact assessments for offshore seismic operations, while the UAE's federal environmental authority enforces marine mammal observer protocols that constrain seasonal shooting windows. Kuwait's oil sector governance framework requires pre-qualification of seismic contractors against safety and data quality benchmarks that filter out smaller regional players. Stakeholders must weigh technology refresh cycles against contracting tenor structures as multi-year framework agreements lock in service pricing while fast-evolving sensor and source technologies threaten obsolescence of committed capital.
Market Dynamics
Capital deployment in offshore acquisition assets is bifurcating as national oil companies demand simultaneous access to proprietary sensor arrays and shared vessel economics, compressing contractor margins while expanding tender participation requirements.
Growth Catalysts
- Carbonate reservoir complexity:Anhydrite and salt-layer imaging challenges in the Arabian Gulf drive demand for high-density 3D surveys with sub-10 meter receiver spacing.
- SFDA marine protocols:Saudi Arabia's environmental regulator mandates seasonal shooting windows with marine mammal observers, creating standardized operational cadences that favor qualified contractors.
- Waterflood monitoring:Mature fields across Kuwait and the UAE deploy 4D time-lapse seismic to track fluid displacement fronts and optimize secondary recovery economics.
Market Restraints
- Specialized vessel scarcity:Shallow-draft broadband acquisition platforms suitable for Arabian Gulf operations face concentrated supply among Nordic shipyards with 18-24 month delivery backlogs.
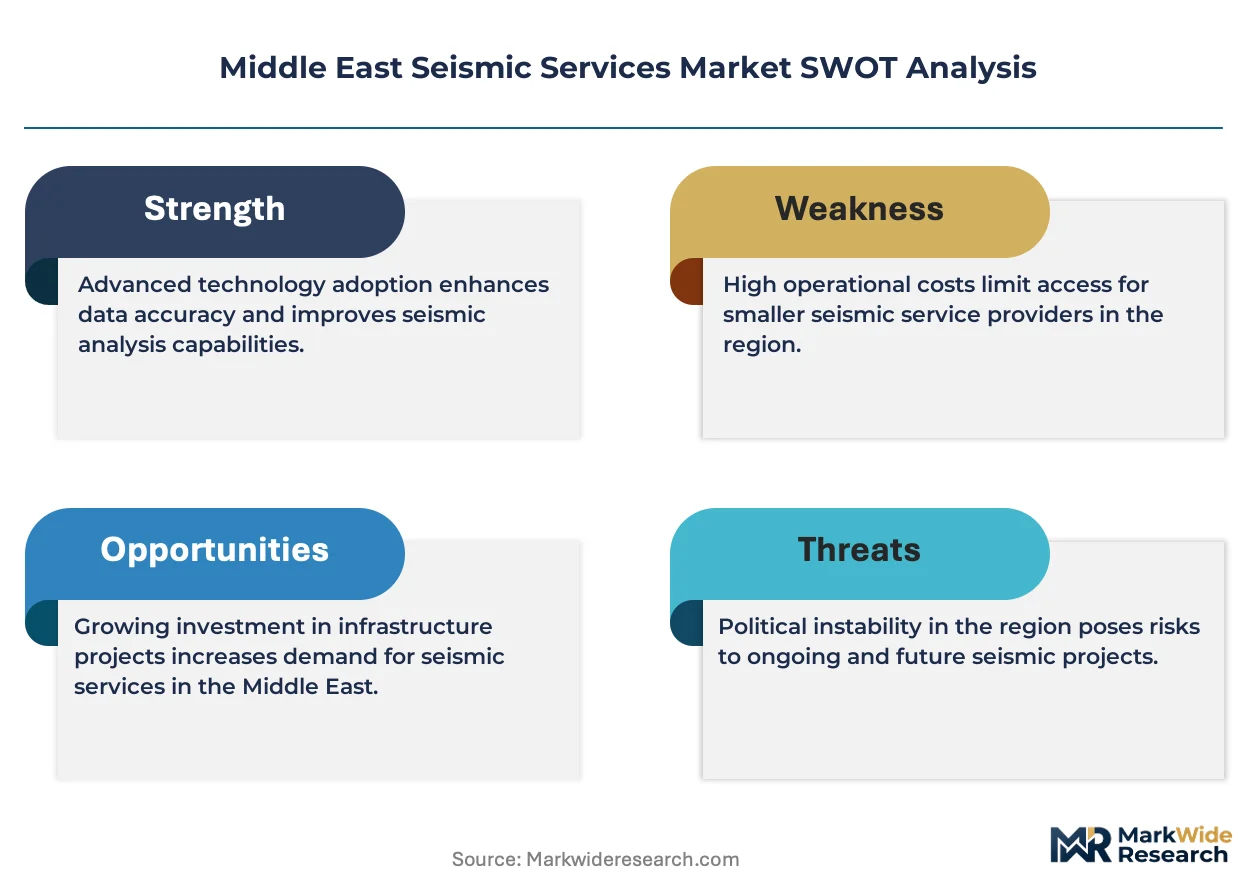
- High-performance computing costs:Anisotropic depth migration for carbonate imaging requires dedicated GPU clusters with energy-intensive operational footprints in Dubai's data center market.
- Multi-client library commoditization:Pre-existing seismic data repositories reduce pricing power for new acquisition programs in established offshore blocks.
Strategic Opportunities
- Ocean-bottom node expansion:Kuwait's northern offshore fields present untapped demand for permanent reservoir monitoring systems with 4D repeatability specifications.
- Geohazard assessment services:Pipeline route surveys and shallow gas hazard identification for new offshore infrastructure projects create adjacent revenue pools beyond hydrocarbon exploration.
- Processing algorithm licensing:Proprietary depth imaging workflows developed for regional carbonate geology can generate recurring software revenue from third-party operators.
Industry Challenges
- Geophysicist talent scarcity:Specialized expertise in anisotropic velocity model building for salt-proximal reservoirs commands premium compensation and limits project scaling.
- Sensor technology obsolescence: Multi-year framework agreements lock in acquisition specifications while solid-state accelerometer and MEMS technologies advance survey fidelity metrics.
- Integration with legacy interpretation platforms:New high-resolution datasets require workflow reengineering in established national oil company geoscience departments with entrenched software dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Seismic Services Market |
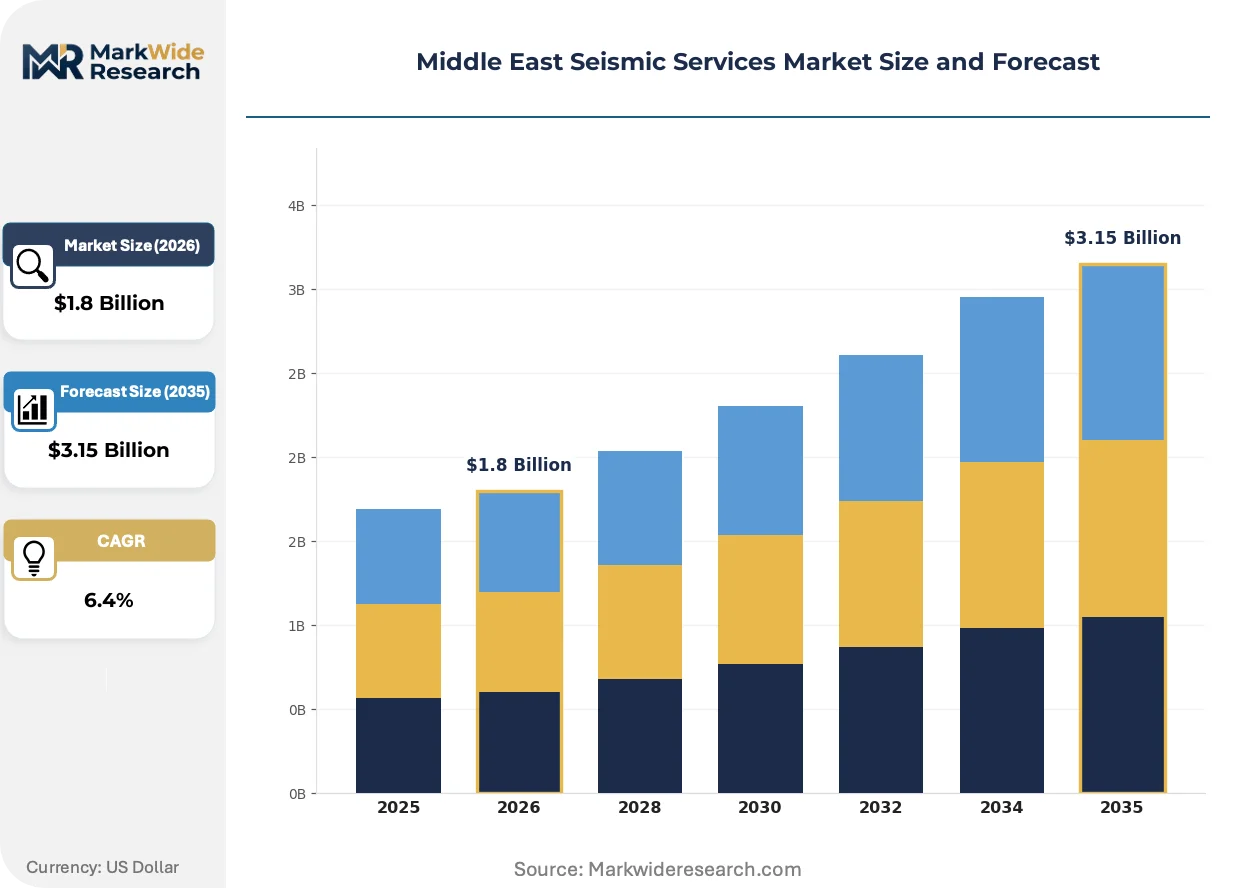
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Acquisition, Interpretation, Processing, Survey Design End User: Oil & Gas, Mining, Infrastructure, Environmental Technology: 2D Seismic, 3D Seismic, 4D Seismic, Passive Seismic Application: Exploration, Production, Site Characterization, Risk Assessment |
| Companies Covered | Schlumberger Ltd, CGG SA, PGS ASA, TGS ASA, Halliburton Company, BGP Inc., Shearwater GeoServices, ARGAS, Weatherford, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Seismic Services Market Shifts & Advancements
Seismic acquisition technology is fragmenting across competing hardware philosophies as operators balance capital efficiency against imaging fidelity requirements in carbonate-dominated geology.
Wide-azimuth towed streamer acquisition is bifurcating contractor fleets as Saudi Aramco and ADNOC simultaneously demand Ramform-style broadband vessels and compact source configurations for near-field obstacle avoidance. National oil companies now specify hybrid acquisition programs combining both architectures within single survey campaigns, forcing service providers to maintain dual capability sets or risk tender exclusion.
MOHAP's marine environmental protocols in the UAE now require real-time acoustic monitoring systems with automated source shutdown triggers when cetacean vocalizations exceed threshold frequencies. This regulatory architecture extends seasonal operational windows by reducing manual observer dependency, though it mandates capital investment in hydrophone arrays and signal processing infrastructure that smaller regional contractors cannot absorb.
Service unbundling is accelerating as Kuwait Oil Company separates data acquisition contracts from processing and interpretation workstreams, enabling specialist algorithm developers to compete against integrated providers. This procurement fragmentation rewards boutique velocity modeling firms with regional carbonate expertise while compressing margins for full-stream contractors dependent on bundled service economics.
Middle East Seismic Services Market Segmentation
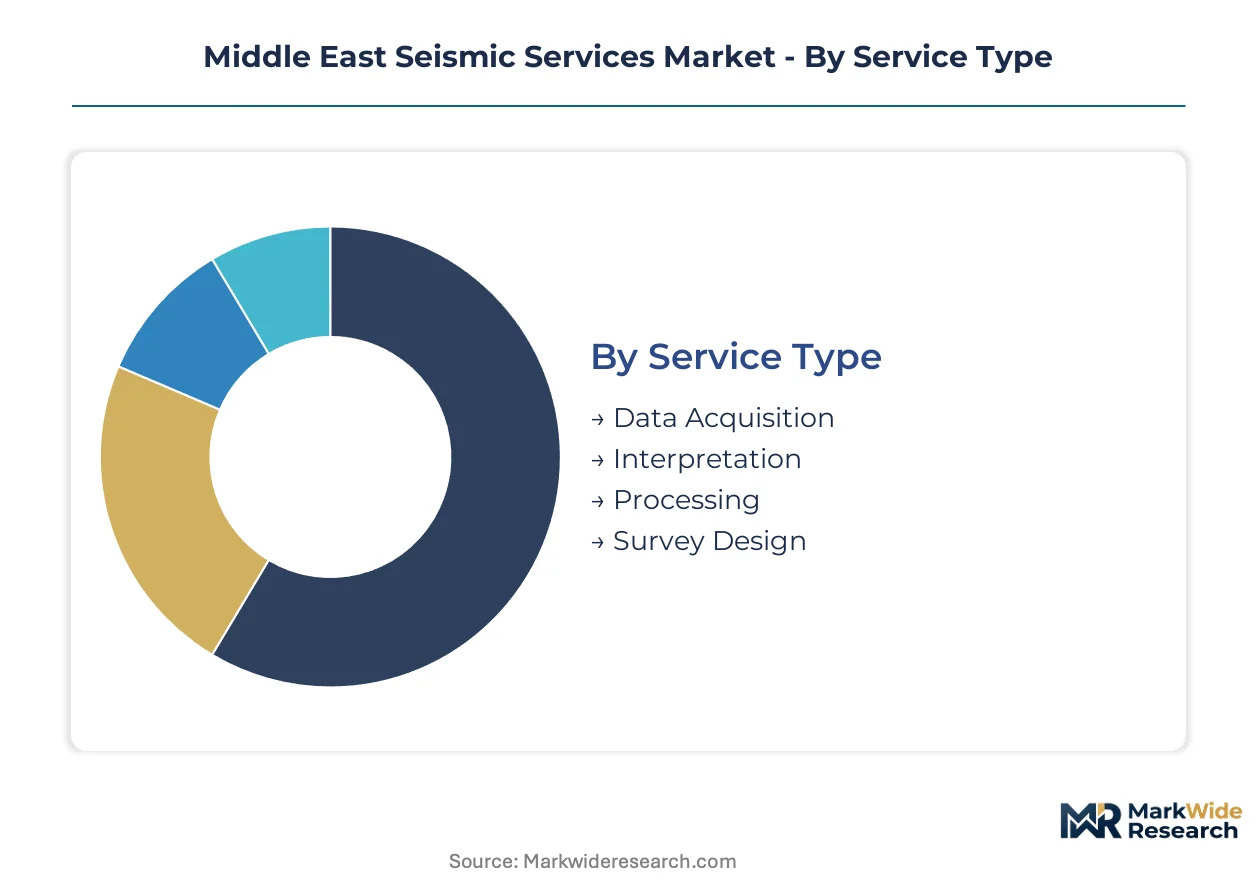
Segmentation in Middle East seismic services reveals how margin pools concentrate at distinct value chain stages, with technology-driven differentiation commanding premium positioning against commoditized acquisition labor. Understanding these fault lines enables contractors to target capability investments where proprietary algorithms and specialized vessel assets resist price erosion.
Service Type:
Margin concentration follows the data transformation curve, with highest returns accruing where proprietary algorithms convert raw signals into drillable subsurface intelligence.
- Data Acquisition:Towed streamer and ocean-bottom node operations deploy vessel crews at day rates reflecting tight supply of shallow-draft broadband platforms suitable for Arabian Gulf carbonate imaging. Saudi Aramco and ADNOC tenders now specify hybrid Ramform-compact source configurations that compress contractor margins while expanding technical qualification barriers.
- Processing:Anisotropic depth migration for salt-proximal reservoirs runs on GPU clusters in Dubai data centers, with proprietary velocity model building workflows differentiating specialist providers. Kuwait Oil Company's unbundled procurement rewards boutique algorithm developers against integrated full-stream competitors.
- Interpretation:Geoscientist teams translate processed volumes into drilling recommendations, with carbonate expertise commanding premium compensation in tight talent markets.
- Survey Design:Pre-acquisition modeling optimizes receiver spacing and source geometry for specific reservoir challenges, typically bundled into integrated tenders rather than standalone contracts.
Data Acquisition holds installed capacity. Processing is rotating up the share rankings.
End User:
Customer concentration tracks hydrocarbon investment cycles, with national oil company capital deployment patterns determining regional contractor utilization rates.
- Oil & Gas:National oil companies across Saudi Arabia, Kuwait, and the UAE drive demand through mature field redevelopment and frontier exploration, with 4D time-lapse programs expanding fastest for waterflood optimization.
- Mining:Mineral exploration programs in Oman and Saudi Arabia's Arabian Shield employ shallow seismic for bedrock depth mapping, though contract values remain fractional against petroleum budgets.
- Infrastructure:Pipeline route surveys and port expansion projects generate geohazard assessment demand beyond hydrocarbon applications, particularly for shallow gas identification in UAE offshore development zones.
- Environmental:Carbon storage site characterization and marine mammal monitoring protocols create adjacent service requirements under SFDA and MOHAP regulatory frameworks.
Oil & Gas dominates current revenue. Infrastructure is climbing the fastest as non-petroleum applications expand.
Technology:
Technology substitution patterns reveal where sensor innovation disrupts established acquisition economics and where legacy architectures retain defensive value.
- 3D Seismic:High-density surveys with sub-10 meter receiver spacing resolve thin-bed traps beneath anhydrite layers across Arabian Gulf carbonate reservoirs. Saudi Aramco's mega-field campaigns specify wide-azimuth geometries that strain contractor fleet flexibility.
- 4D Seismic:Time-lapse acquisition tracks fluid displacement fronts in mature Kuwait and UAE fields, with repeatability specifications driving ocean-bottom node adoption for permanent reservoir monitoring installations.
- 2D Seismic:Reconnaissance-scale profiling persists in frontier acreage evaluation where full 3D coverage remains economically unjustified.
- Passive Seismic:Microseismic monitoring of hydraulic stimulation and reservoir compaction operates without controlled sources, reducing environmental permitting complexity under seasonal marine mammal protocols.
3D Seismic holds installed capacity. 4D Seismic is expanding most quickly as secondary recovery optimization intensifies.
Application:
Application mix shifts with field life cycle stage, from frontier exploration requiring maximum imaging depth to mature production demanding temporal resolution.
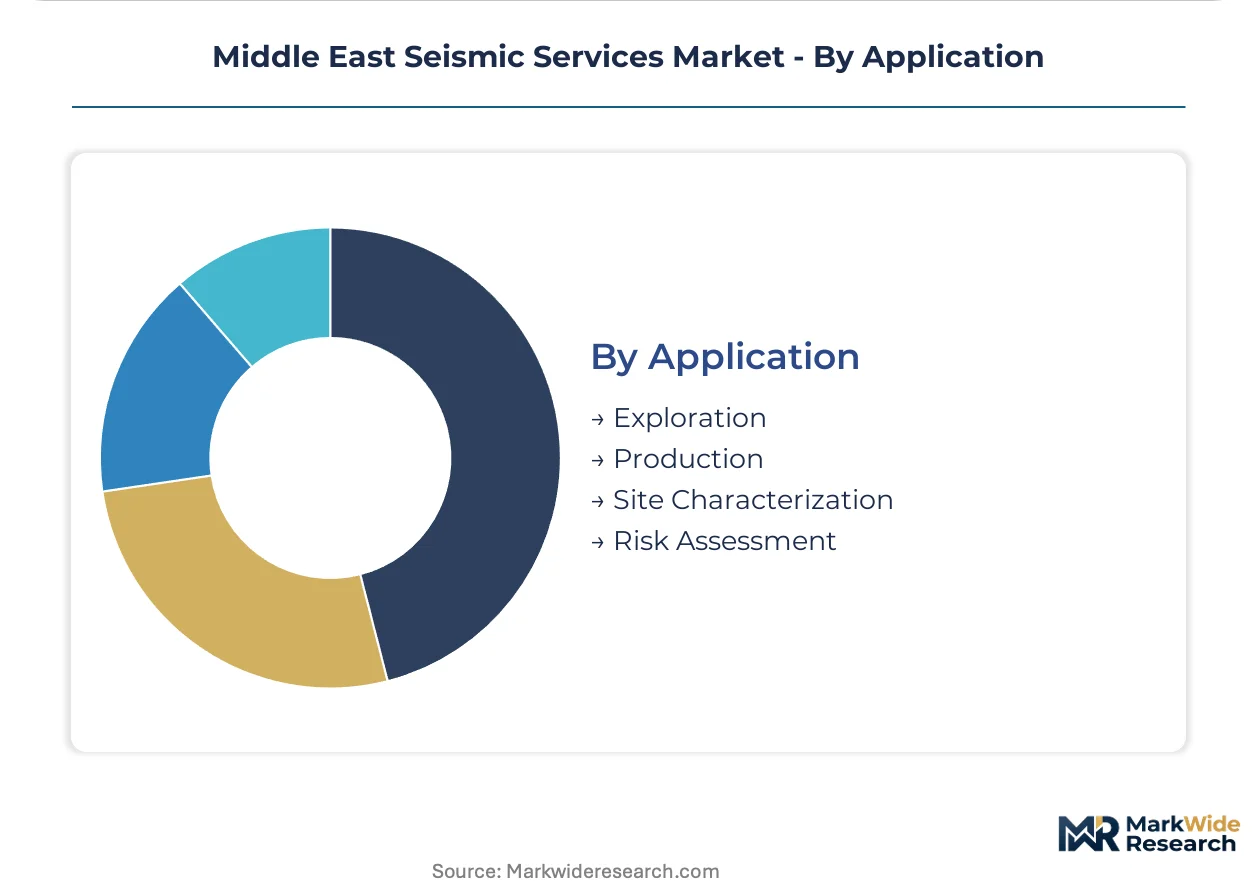
- Exploration:Frontier acreage evaluation in deep Arabian Gulf blocks and Red Sea rift basins employs full-azimuth 3D to delineate structures beneath salt canopies, with acquisition costs amortized across multi-client library licensing.
- Production:Reservoir surveillance through 4D seismic optimizes infill drilling and waterflood patterns in Kuwait's Burgan field and UAE's Zakum complex, with repeat surveys contracted on multi-year frameworks.
- Site Characterization:Geotechnical foundation studies for offshore platforms and subsea infrastructure employ high-resolution shallow seismic to map seabed stability and shallow gas hazards.
- Risk Assessment:Geohazard identification for pipeline routing and well placement integrates seismic interpretation with geomechanical modeling for drilling safety protocols.
Production holds installed capacity. Site Characterization is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Middle East seismic markets. Saudi Arabia and UAE national oil companies absorb premium pricing for integrated geophysical-to-drilling workflows, while Kuwait and smaller markets force sharper contractor competition on acquisition day rates.
Saudi Arabia
Saudi Aramco's mega-field redevelopment campaigns drive wide-azimuth 3D survey demand with hybrid vessel specifications. SFDA marine protocols mandate seasonal shooting windows with marine mammal observers, compressing operational calendars. Dhahran-based geoscience clusters anchor processing workflows for Ghawar and Safaniya field characterization.
United Arab Emirates
ADNOC's mature field 4D programs and frontier deepwater exploration create dual-track demand for broadband acquisition. MOHAP's real-time acoustic monitoring requirements with automated source shutdown triggers extend operational windows but raise capital barriers. Abu Dhabi serves as the regional hub for high-performance computing clusters processing carbonate depth imaging.
Kuwait
Kuwait Oil Company unbundles acquisition from processing contracts, enabling specialist algorithm developers to compete against integrated providers. The national petroleum regulator's contractor pre-qualification framework filters out smaller regional players. Northern offshore fields around Bubiyan Island present untapped demand for permanent ocean-bottom node installations.
Qatar
North Field expansion projects sustain demand for geohazard assessment and shallow gas identification services beyond pure exploration. The country's environmental authority enforces marine mammal protection protocols aligned with regional standards. Doha-based project management offices coordinate survey logistics across shared Arabian Gulf vessel pools.
Oman
Frontier exploration in the Makran offshore basin and Red Sea rift systems employs reconnaissance 2D profiling where full 3D coverage remains uneconomic. The national oil company's block licensing rounds attract multi-client library investment from international contractors. Muscat serves as the logistical coordination point for surveys spanning the Strait of Hormuz.
Middle East Seismic Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Middle East seismic services. Full-stream providers anchor mega-field campaigns through bundled acquisition-to-interpretation contracts, while boutique velocity modeling firms exploit unbundled procurement to capture processing margin pools. Three archetypes dominate: integrated geophysical-to-drilling workflow providers, high-performance computing specialists with proprietary depth imaging algorithms, and vessel-asset operators competing on Ramform architecture and shallow-draft broadband platforms. Competitive intensity concentrates on multi-year framework agreement capture and GPU cluster infrastructure deployment in Dubai's data center market.
Among integrated service providers, Schlumberger Ltd and Halliburton Company occupy positions anchoring geophysical-to-drilling workflow penetration in Saudi Aramco tenders. CGG SA exemplifies the high-performance computing specialist archetype through its Dubai-based GPU clusters accelerating anisotropic depth migration for carbonate reservoirs. PGS ASA represents the vessel-asset operator tier with Ramform architecture optimized for Arabian Gulf shallow-water broadband acquisition.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| CGG SA |
| PGS ASA |
| TGS ASA |
| Halliburton Company |
| BGP Inc. |
| Shearwater GeoServices |
| ARGAS |
| Weatherford |
| Others |
Supply & Pricing Matrix
Vessel day-rate scale economies concentrate pricing power among Nordic shipyard-backed operators while compressing margins for asset-light processing specialists. Multi-year framework agreements lock Saudi Aramco and ADNOC into fixed acquisition economics even as sensor technology refresh cycles accelerate obsolescence risk.
Pricing Analysis
Multi-client library licensing and processing algorithm subscriptions drive lifetime value beyond single-project margins. Three-tier pricing structure across integrated full-stream contracts, unbundled processing services, and spot vessel charters differentiates Schlumberger and CGG from regional boutique operators. Pricing pressure stems from Kuwait Oil Company's procurement unbundling, which fragments bundled service premiums. National oil companies exhibit lowest price sensitivity for proprietary depth imaging workflows, while independent operators in Oman frontier blocks demand aggressive day-rate competition.
Supply Chain Analysis
Strategic stockpiling of solid-state ocean-bottom nodes and MEMS accelerometers characterizes contractor inventory management against 18-24 month Nordic shipyard delivery backlogs. Vessel hull construction concentrates in Norway, Finland, and Singapore, while GPU cluster infrastructure for anisotropic depth migration anchors in Dubai's data center market. Supply chain risk centers on single-source dependency for shallow-draft broadband platforms suitable for Arabian Gulf carbonate imaging. Distribution runs through national oil company tender platforms with pre-qualification filters that exclude smaller regional contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in salt-proximal velocity model building commands premium compensation that limits project scaling across all contractor tiers. This capability scarcity rewards targeted capability investments over broad-based capacity expansion.
For Market Incumbents: Compound proprietary algorithm differentiation through Dubai-based GPU cluster expansion and carbonate-specific depth imaging workflow licensing. Defend against unbundled procurement by embedding processing services into multi-year framework agreements with embedded technology refresh clauses. Deepen backward integration into ocean-bottom node manufacturing to capture sensor economics from solid-state MEMS transitions. For New Entrants and Emerging Players: Lead with boutique velocity modeling specialization targeting Kuwait Oil Company's separated processing tenders. Capture white-space in permanent reservoir monitoring installations for Kuwait's northern offshore fields around Bubiyan Island. Establish credibility through partnership with established vessel operators for acquisition execution while building proprietary algorithm IP. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processing specialists with licensed depth imaging workflows rather than vessel-dependent acquisition operators. Long-term viability favors algorithm developers with regional carbonate geology expertise over capital-intensive fleet operators facing technology obsolescence cycles. Target acquisition profiles center on Dubai-based GPU cluster operators with anisotropic migration IP. Watch for inflection when SFDA marine protocol expansions trigger automated monitoring system mandates that favor capital-rich integrated providers.| Strategic Initiative | Industry Significance |
|---|---|
| GPU Cluster Infrastructure Expansion | Dubai-based high-performance computing accelerates anisotropic depth migration for ADNOC carbonate reservoirs. |
| Proprietary Algorithm Licensing Program | Licensed depth imaging workflows generate recurring revenue from third-party operators beyond bundled contracts. |
| Ocean-Bottom Node Manufacturing Integration | Backward integration into solid-state sensor production captures MEMS technology transition economics. |
| Multi-Client Library Development | Pre-existing seismic data repositories reduce new acquisition pricing power in established Arabian Gulf blocks. |
| Real-Time Acoustic Monitoring Deployment | MOHAP-compliant automated source shutdown systems extend operational windows beyond seasonal constraints. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings on contractor qualification frameworks. Geoscience directors at national oil companies, seismic vessel operations managers, Dubai data center infrastructure planners, and petroleum regulatory affairs specialists provided operational perspective. Secondary sources encompassed SFDA marine protocol documentation, MOHAP environmental filings, Kuwait Oil Company tender disclosures, and SEC filings from listed seismic contractors. Bottom-up vessel day-rate modeling and top-down national oil company capital expenditure triangulation validated segment sizing.
Sensitivity analysis tested forecast outputs against variable assumptions for carbonate reservoir complexity, seasonal shooting window constraints, and technology substitution rates across the projection horizon. Segmentation dimensions modeled encompassed service type, end-user archetype, technology generation, and application life-cycle stage with regional regulatory cluster overlays. CAGRs derived from fitted growth curves applied to disclosed contract values and announced framework agreement scopes. Industry-specific inputs included Saudi Aramco mega-field campaign timelines and ADNOC 4D program repeatability specifications.
The analysis sits within stated boundaries; outcomes outside sustained national oil company capital deployment or accelerated environmental protocol expansion would require recalibration. Forecasts reflect documented assumptions on vessel supply elasticity and GPU cluster capacity absorption. Revision becomes warranted when Nordic shipyard delivery backlogs exceed thresholds or MEMS sensor cost curves cross solid-state displacement points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Vacuum Excavation Service Market
Engineering Services
MEP Services Market
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Geotechnical Services Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Geosteering Services Market
Engineering Services
Metal Joining Services Market
Engineering Services
NDT Inspection Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Engineering Services Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Directional Drilling Services Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Sheet Metal Fabrication Services Market