
 United States Engineering Services Market | 2026-2036
United States Engineering Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Engineering Services Market Analytics
The gap between premium integrated engineering and commodity design work is realigning as owners prioritize risk transfer and single-point accountability. AECOM leverages its program management depth to capture complex federal infrastructure awards. Jacobs Engineering Group anchors its position through nuclear and advanced manufacturing specialization. Bechtel Corporation dominates energy and defense megaprojects where vertical scope control determines bid success.
Engineering services encompass technical consulting, design development, construction oversight, and feasibility analysis delivered across physical and digital infrastructure lifecycles. These services integrate CAD modeling, structural simulation, and project controls to reduce capital expenditure variance and schedule risk for asset owners. Infrastructure applications lead current revenue contribution, while environmental services represent the fastest-expanding segment as EPA enforcement and state decarbonization mandates tighten discharge and emissions standards. Energy vertical demand concentrates in grid modernization and renewable integration, where margin pools sit with firms offering combined engineering-procurement-construction capabilities.
OSHA workplace safety standards, EPA National Environmental Policy Act requirements, and state-level building codes shape project timelines and technical staffing needs across the sector. Federal Acquisition Regulation compliance and Davis-Bacon Act prevailing wage rules further filter market access for government contract pursuit. Stakeholders must monitor how infrastructure funding disbursement velocity and evolving carbon accounting rules reshape project origination patterns and talent deployment strategies.
Market Dynamics
Federal infrastructure disbursement velocity under the Infrastructure Investment and Jobs Act is compressing project origination timelines while concentrating award pools among firms with integrated design-build capabilities.
Growth Catalysts
- Grid Modernization Mandates:FERC Order 2222 and state renewable portfolio standards accelerate transmission and distribution engineering demand across Texas and California interconnection queues.
- EPA Enforcement Intensification:National Environmental Policy Act review expansion and emerging per- and polyfluoroalkyl substances remediation obligations drive environmental services procurement in industrial corridors.
- Megaproject Pipeline Concentration:Texas, California, and New York account for disproportionate transportation and energy project origination, pulling specialized technical staffing into these markets.
Market Restraints
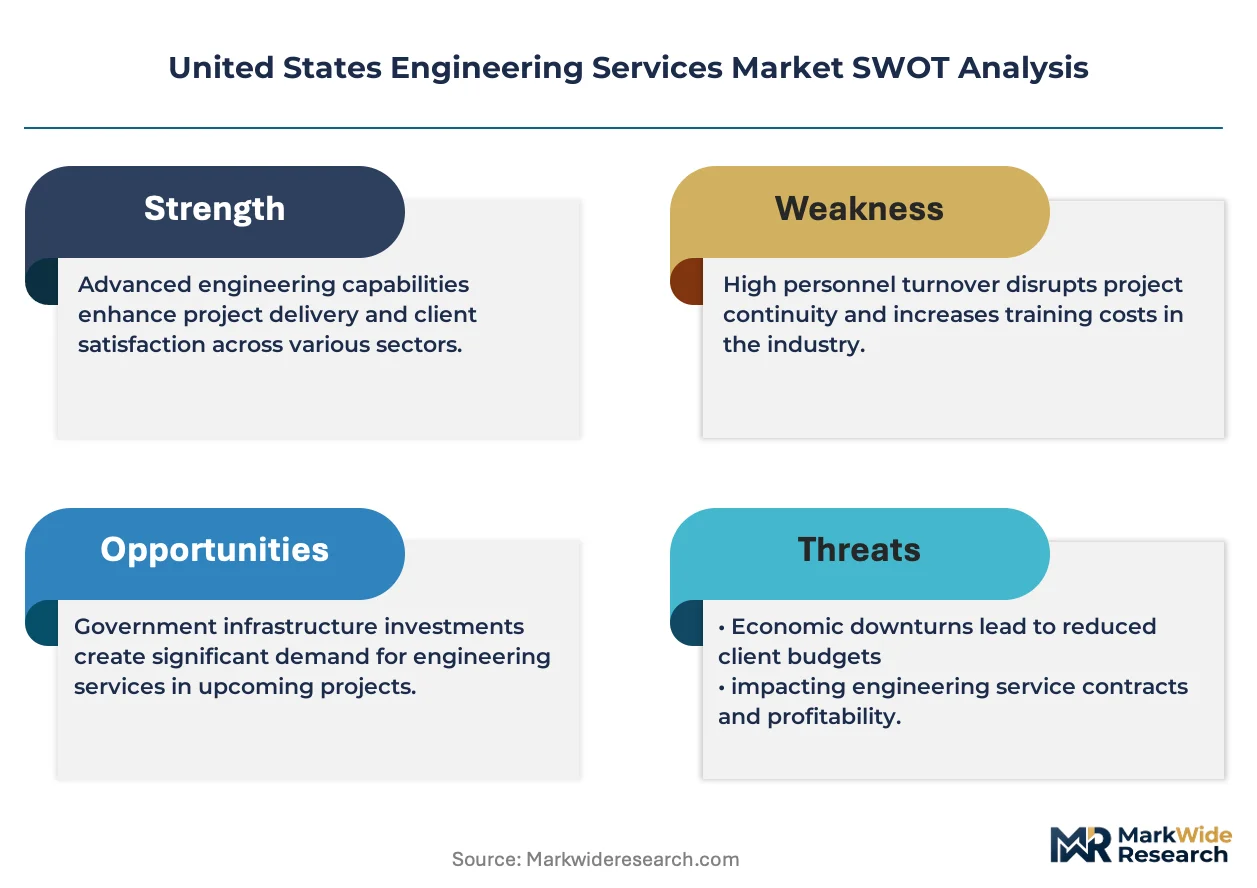
- Specialized Labor Scarcity:Licensed professional engineers with nuclear or advanced manufacturing credentials command premium compensation, compressing margin on fixed-price federal contracts.
- Prevailing Wage Compliance Burden:Davis-Bacon Act requirements and state-level prevailing wage laws inflate project cost structures in government-funded verticals relative to private commercial work.
- Supply Concentration in Critical Materials:Domestic steel and concrete supply bottlenecks in the Gulf Coast and Midwest regions delay mobilization and extend project schedules.
Strategic Opportunities
- Carbon Accounting Integration:Emerging SEC climate disclosure rules and state-level embodied carbon mandates create demand for lifecycle assessment services in building and infrastructure design.
- Advanced Manufacturing Reshoring:CHIPS Act and Inflation Reduction Act incentives pull semiconductor and battery facility engineering into Arizona, Texas, and Ohio markets.
- Digital Twin Deployment:Convergence of building information modeling with real-time sensor networks enables predictive maintenance service contracts in federal asset portfolios.
Industry Challenges
- Security Clearance Bottlenecks:Defense and intelligence agency projects require cleared personnel pools that lag demand, constraining Bechtel and AECOM expansion in classified verticals.
- Legacy System Interoperability:Federal agency asset management databases resist integration with modern project controls platforms, forcing redundant data entry and compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Engineering Services Market |
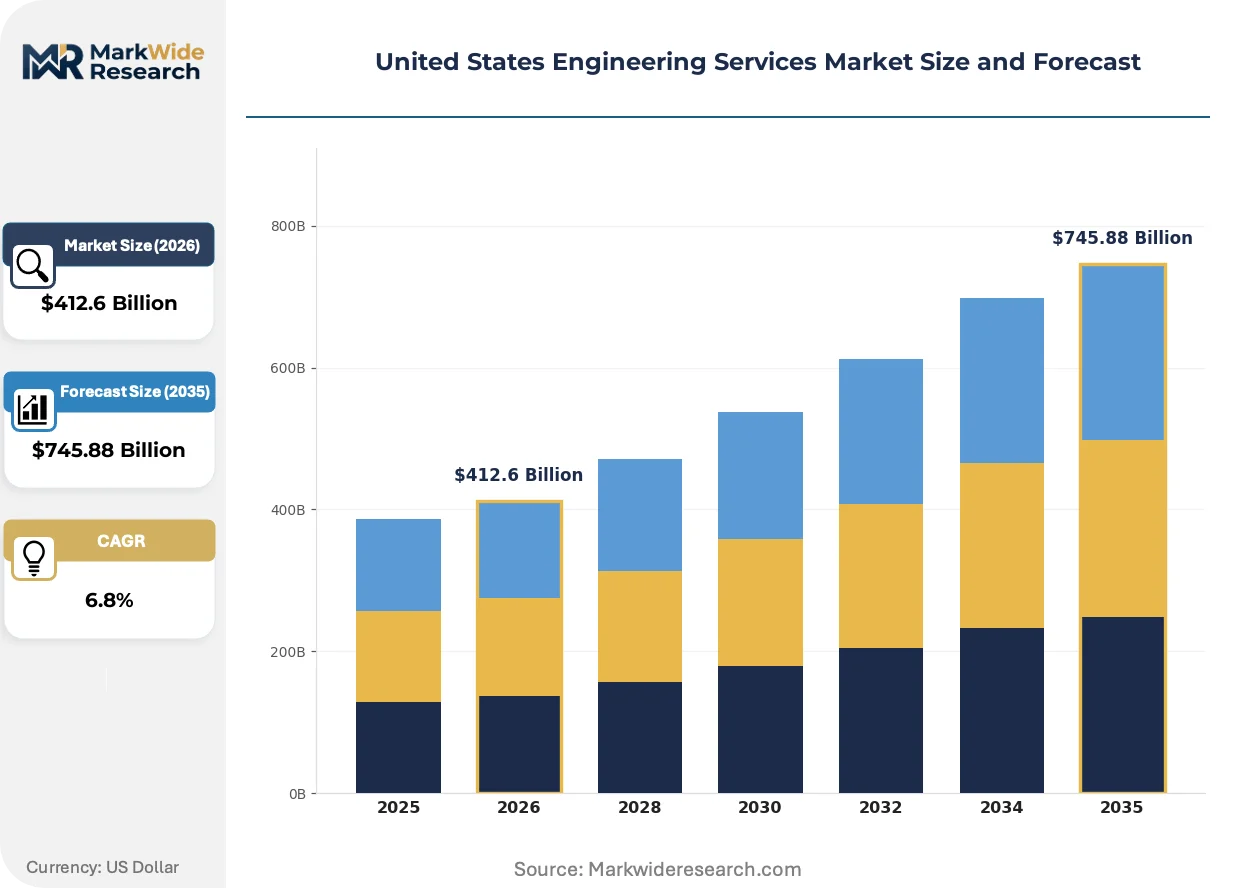
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $745.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
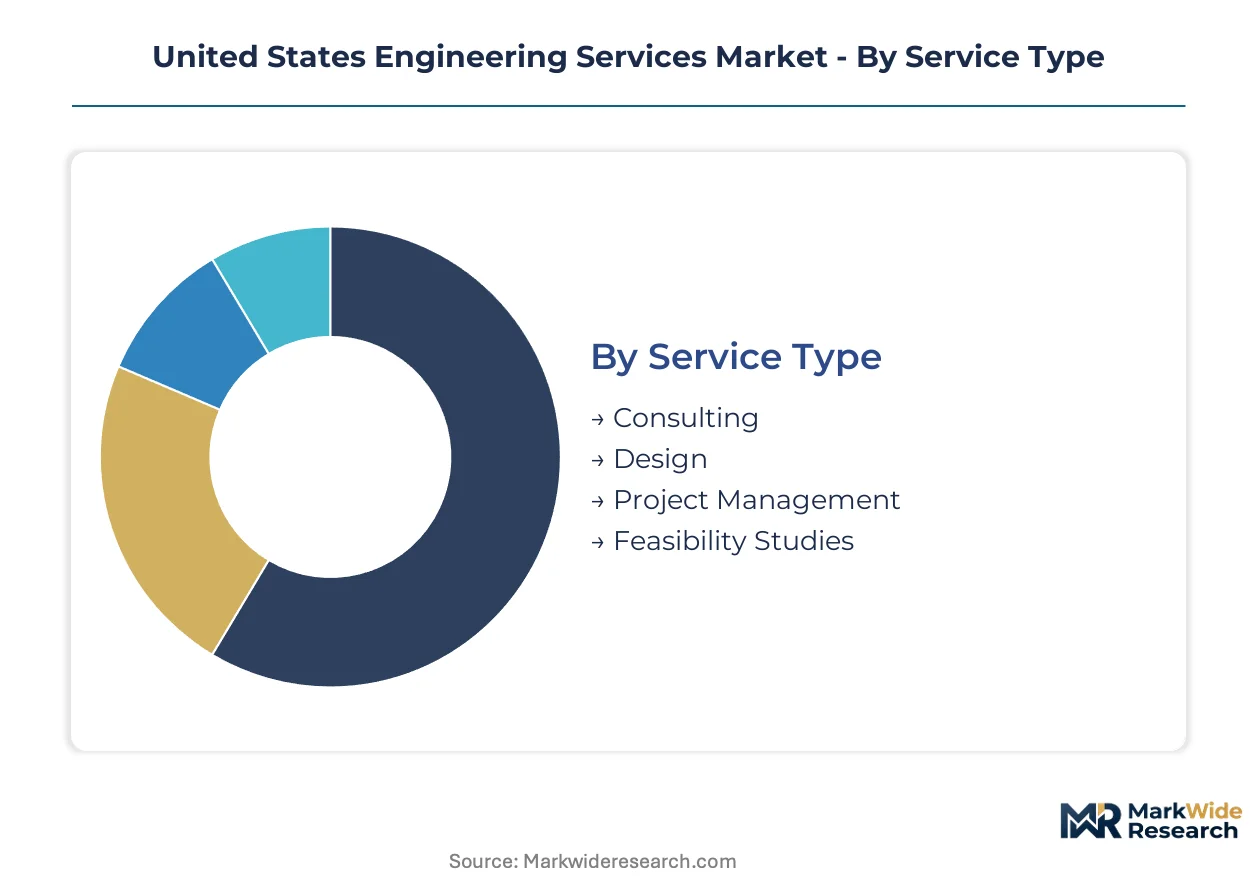
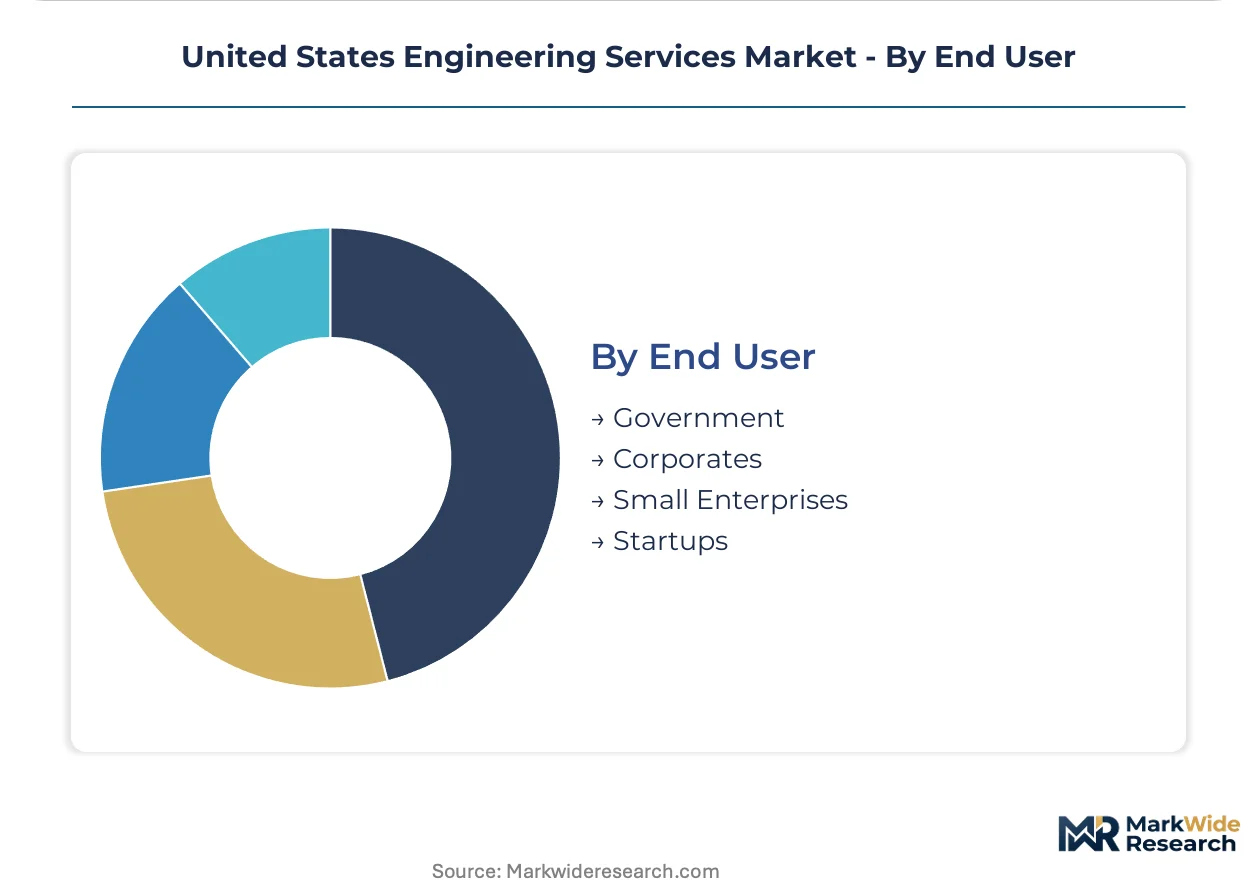
| Segmentation | Service Type: Consulting, Design, Project Management, Feasibility Studies Industry Vertical: Construction, Manufacturing, Energy, Telecommunications Application: Infrastructure, Aerospace, Automotive, Environmental End User: Government, Corporates, Small Enterprises, Startups |
| Companies Covered | AECOM, Jacobs Engineering Group, Bechtel Corporation, Fluor Corporation, KBR Inc., HDR Inc., WSP Global Inc, Kiewit Corporation, Black & Veatch Holding Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Engineering Services Market Evolving Landscape
Generative design tools and federated data environments are collapsing traditional phase-gate workflows, compressing the interval between concept and construction mobilization.
Parametric design software is rewriting how transportation agencies scope bridge and highway projects. State DOTs in California and Texas now mandate algorithmic optioneering for structures exceeding specific complexity thresholds. This capability is compressing preliminary engineering durations while elevating technical staffing requirements for firms competing in these procurements.
The EPA's evolving National Environmental Policy Act implementation rules are extending review timelines for linear infrastructure projects. Industrial clients now front-load environmental impact assessment spending to preempt litigation risk. Energy transmission developers in the Mountain West and Southwest regions are responding by bundling habitat mitigation credits into initial design packages.
Asset owners now unbundle commissioning and operational support from initial design contracts, creating discrete revenue pools for specialized facility performance firms. Federal building portfolios and university systems are driving this disintermediation, particularly in California and New York where energy performance contracting mandates require operational accountability separate from design liability.
United States Engineering Services Market Segmentation
Engineering services procurement patterns diverge sharply across buyer sophistication, project scale, and regulatory exposure. Segment-level strategy requires matching capability depth to client risk tolerance and compliance burden.
Service Type:
Buyers differentiate by how much technical risk they retain in-house versus transfer to external partners.
- Consulting:Strategic advisory on capital allocation, regulatory navigation, and technology selection dominates federal infrastructure planning cycles. Texas and California transportation agencies procure consulting separately from design execution to maintain optionality on delivery methods.
- Design:CAD modeling, structural simulation, and systems integration form the core technical deliverable. Demand concentrates in energy transmission and semiconductor fabrication facilities where FERC interconnection standards and CHIPS Act timelines compress design windows.
- Project Management:Schedule controls, cost forecasting, and contractor coordination services.
- Feasibility Studies:Front-end technical and economic validation for capital commitments.
Design leads volumes today; consulting is gaining share fastest as owners front-load risk assessment.
Industry Vertical:
Margin profiles vary by vertical based on regulatory density and asset owner procurement sophistication.
- Construction:Commercial, industrial, and civil building projects drive the largest absolute spend. Davis-Bacon Act compliance and OSHA multi-employer worksite rules elevate documentation burdens on federal and state-funded verticals.
- Energy:Grid modernization, renewable integration, and battery storage engineering command premium pricing. Texas ERCOT interconnection queues and California ISO resource adequacy mandates pull specialized transmission planners into these markets.
- Manufacturing:Process design, automation integration, and facility layout for reshoring initiatives.
- Telecommunications:Fiber deployment, 5G infrastructure, and data center engineering services.
Construction anchors revenue today; energy is climbing the fastest on IRA and IIJA disbursement velocity.
Application:
Technical staffing requirements and software tooling differ materially by application domain.
- Infrastructure:Transportation, water, and public building projects absorb the majority of federal IIJA funding. State DOTs in New York and California now mandate building information modeling deliverables for structures above defined complexity thresholds.
- Environmental:Remediation, compliance monitoring, and impact assessment services face the steepest demand trajectory. EPA enforcement intensification on PFAS obligations and NEPA review expansion pull environmental engineers into industrial corridor projects.
- Aerospace:Defense and commercial aviation engineering requiring security clearances and specialized materials expertise.
- Automotive:EV manufacturing facility design and battery plant engineering for OEM supply chain restructuring.
Infrastructure dominates current procurement; environmental is expanding most quickly on regulatory enforcement.
End User:
Contracting mechanisms and payment terms diverge sharply by organizational scale and capital access.
- Government:Federal agencies, state departments, and municipal authorities operate under FAR compliance and prevailing wage mandates. Award pools concentrate among firms with demonstrated past performance on similar contract vehicles.
- Corporates:Large industrial and technology companies with in-house engineering capabilities purchase supplemental specialized expertise. Semiconductor and battery manufacturers in Arizona and Ohio procure combined engineering-procurement-construction packages to compress facility startup timelines.
- Small Enterprises:Regional contractors and specialty trades requiring localized permitting support.
- Startups:Venture-backed technology firms with limited capital seeking fractional technical leadership.
Government leads absolute spend today; corporates are gaining share fastest on reshoring facility investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and California command disproportionate engineering procurement volumes, while New York's climate mandates reshape technical staffing patterns across the Northeast corridor.
Texas
ERCOT grid interconnection queues and Permian Basin energy infrastructure drive transmission and distribution engineering demand. The Texas Department of Transportation accelerates highway and bridge procurement under IIJA funding disbursements. Houston anchors energy sector engineering concentration, while Dallas-Fort Worth pulls technical talent into semiconductor fabrication facility design for CHIPS Act recipients.
California
California ISO resource adequacy mandates and SB 100 decarbonization targets compress renewable integration timelines. The California Department of Transportation mandates building information modeling deliverables for complex structures, elevating technical staffing requirements. Bay Area technology campuses and Los Angeles County transit expansions concentrate environmental impact assessment procurement among specialized consultancies.
New York
Metropolitan Transportation Authority capital programs and offshore wind lease obligations pull marine and structural engineers into the Northeast market. New York State's Climate Leadership and Community Protection Act tightens embodied carbon standards for public building procurements. New York City transit authority projects and Hudson Valley data center developments concentrate design-build contract awards among integrated firms.
Florida
Florida Department of Transportation resiliency spending and hurricane-hardened infrastructure standards elevate coastal engineering demand. The state's building code enforcement intensifies wind-load and flood-plain design requirements for commercial and residential verticals. Miami-Dade County transit expansions and Orlando theme park capital cycles concentrate project management staffing in the Southeast corridor.
Illinois
Chicago Transit Authority modernization and Midwest battery manufacturing investments pull process engineers into the Great Lakes region. Illinois EPA enforcement on legacy industrial remediation drives environmental services procurement in the Calumet and Rockford corridors. The state's position as a rail and logistics hub concentrates freight infrastructure engineering around Chicago metropolitan statistical area design offices.
United States Engineering Services Market Competitive Landscape
Top-tier vendors anchor federal megaproject procurement, while mid-tier specialists capture state-level climate mandate work and niche industrial verticals. The vendor base stratifies across three capability tiers: integrated design-build operators, discipline-specific technical consultancies, and regional permitting specialists. Three strategic archetypes dominate competitive positioning: program management generalists, nuclear and advanced manufacturing specialists, and energy infrastructure vertical integrators. M&A activity concentrates on environmental services capabilities and digital engineering tooling, while talent retention programs target licensed professional engineers with security clearances.
Within the integrated infrastructure tier, AECOM, Jacobs Engineering Group, and Bechtel Corporation exemplify divergent specialization vectors. AECOM occupies a position emphasizing program management depth for complex federal awards. Jacobs Engineering Group anchors its competitive stance through nuclear credentials and advanced manufacturing facility expertise. Bechtel Corporation sits within the defense and energy megaproject segment where vertical scope control determines bid success. These three entities collectively represent how scale, specialization, and security clearance access partition federal procurement pools.
| Leading Market Players |
|---|
| AECOM |
| Jacobs Engineering Group |
| Bechtel Corporation |
| Fluor Corporation |
| KBR Inc. |
| HDR Inc. |
| WSP Global Inc |
| Kiewit Corporation |
| Black & Veatch Holding Company |
| Others |
Value Network & Pricing Analysis
Federal infrastructure procurement pools concentrate award authority among agencies with design-build delivery mandates, compressing fee structures for commodity engineering while elevating premiums for integrated program management risk transfer. This buyer concentration rewards firms with vertical scope control and penalizes standalone design competitors.
Pricing Analysis
Project-based fee structures dominate government verticals under FAR compliance and Davis-Bacon Act prevailing wage rules, while corporates negotiate fixed-price EPC packages for semiconductor and battery facility compression. Price differentiation rests on security clearance access and nuclear credential density, with cleared professional engineers commanding substantial premiums over commercial counterparts. Cost compression in federal design-bid-build tiers is intensifying as IIJA disbursement velocity concentrates awards among integrated operators. Small regional firms exhibit highest price sensitivity, whereas defense and energy asset owners prioritize single-point accountability over fee minimization.
Supply Chain Analysis
Regional talent distribution centers in Houston, Dallas-Fort Worth, and Denver maintain hub-and-spoke staffing deployment patterns for Permian Basin energy and Mountain West transmission projects. Engineering labor supply draws from domestic university pipelines and Canadian credential reciprocity agreements, with specialized nuclear and advanced manufacturing expertise concentrated in Pittsburgh, Oak Ridge, and Idaho National Laboratory corridors. Single-source vulnerability sits with security-cleared personnel pools that lag demand across defense and intelligence agency verticals. Distribution runs through prime contractor-subcontractor networks with tiered risk allocation to specialty environmental and geotechnical consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in United States engineering services rests on carbon accounting service bundling and digital twin predictive maintenance contracts, as asset owners separate operational accountability from design liability and pay premiums for lifecycle performance guarantees.
For Market Incumbents: Deploy security clearance pipeline investments to capture classified defense and intelligence agency expansion as cleared personnel shortages constrain Bechtel and AECOM growth. Consolidate environmental services capabilities through targeted acquisition of PFAS remediation specialists in industrial corridor markets. Channel control through joint venture structures with regional permitting specialists defends position against mid-tier design-build competitors in Texas and California transportation verticals.
For New Entrants and Emerging Players: Generative design tooling and federated BIM environments offer technology-first entry points into state DOT algorithmic optioneering mandates that elevate technical staffing requirements. Carbon accounting and embodied carbon lifecycle assessment represent the most penetrable white-space segment, as SEC climate disclosure rules and New York State CLCPA procurement standards outpace incumbent capability buildout. Go-to-market execution through embedded partnerships with federal program management incumbents accelerates past performance credential accumulation.
For Investors and Strategic Acquirers: Integrated infrastructure operators are the most active acquirer in this space, targeting environmental consultancies and digital engineering software platforms to fill capability gaps. Long-term viability favors firms with combined federal past performance, security clearance infrastructure, and CHIPS Act facility delivery credentials. Acquisition target archetype: mid-tier environmental specialists with EPA enforcement response capabilities and established industrial corridor relationships. The signal to watch is infrastructure funding disbursement velocity against congressional appropriation timelines, as obligation delays compress project origination windows and strain working capital across fixed-price contract portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Security Clearance Infrastructure Expansion | Cleared personnel pipelines unlock defense and intelligence agency contract pools constrained by federal background investigation backlogs. |
| Carbon Accounting Service Integration | Lifecycle assessment capabilities capture SEC disclosure and state embodied carbon mandate premiums in public building procurements. |
| Digital Twin Platform Deployment | BIM-sensor convergence enables predictive maintenance contracts in federal asset portfolios with operational accountability separation. |
| Environmental Services Acquisition | PFAS remediation and NEPA compliance specialists address EPA enforcement intensification in industrial corridor markets. |
| CHIPS Act Facility Delivery Capability | Semiconductor fabrication engineering captures IRA and CHIPS disbursement velocity in Arizona, Texas, and Ohio markets. |
Research Methodology
Coverage spans Texas, California, New York, Florida, and Illinois, with primary inputs from each state-level transportation department and environmental regulatory authority. Primary interviews combined program management executives at integrated infrastructure operators, state DOT procurement officers, EPA regional enforcement leads, and nuclear facility engineering directors with secondary validation against FERC interconnection queue data, USDOT IIJA obligation dashboards, and SEC climate disclosure filings. Bottom-up project pipeline enumeration triangulates with top-down federal appropriation flow analysis.
Rate-of-change decomposition separates volume drivers from value mix shifts across the projection horizon. The analytical framework models service type, industry vertical, application domain, and end user scale segmentation dimensions throughout the forecast period. CAGRs derive from project origination velocity against specialized labor supply constraints, with inputs including Davis-Bacon Act wage inflation indices, professional engineer licensing pipeline data, and federal contract obligation acceleration curves.
The model holds under sustained IIJA and IRA disbursement velocity; deviation in congressional appropriation delays or security clearance processing backlogs would shift project mobilization timelines and margin compression patterns. Forecasts reflect documented assumptions around federal infrastructure spending continuity and state-level climate mandate enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Vacuum Excavation Service Market
Engineering Services
North America Engineering Research and Development (ER&D) Services Market
Engineering Services
Well Cementing Services Market
Engineering Services
Directional Drilling Services Market
Engineering Services
Architectural Services Market
Engineering Services
NDT Inspection Services Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Geotechnical Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Engineering Design Service Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
North America Seismic Survey Market
Engineering Services
MEP Services Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market