
 Turning Machining Product Market | 2026-2036
Turning Machining Product Market Size, Share, and Industry Trends Forecast 2026-2036
Turning Machining Product Market Insights
Modular tooling configurations are hardening as the dominant procurement pattern, with buyers favoring interchangeable insert-and-holder systems over fixed cutting tools. Sandvik AB leverages its carbide materials science to dominate premium insert grades across aerospace and medical applications. Kennametal Inc. anchors its position through captive supply of tungsten powders and cobalt binders. DMG MORI Co., Ltd. differentiates via integrated machine-tool-plus-software bundles that lock in aftermarket service revenue.
Turning machining products encompass cutting tools, workholding devices, and machine tools engineered to remove material from rotating workpieces through single-point cutting, typically achieving tolerances of ±0.005 mm for precision-grade inserts. These products serve primarily to produce cylindrical components—shafts, pins, bores, and threaded features—for high-volume manufacturing environments. CNC lathes command the largest installed base among product types, though their margin pools are thinning as Chinese producers compress pricing on standard two-axis machines. Inserts generate disproportionate recurring revenue due to predictable wear-cycle replacement schedules across automotive parts and aerospace manufacturing applications. Tool holders represent a concentrated profit segment where proprietary interface geometries—Sandvik's Coromant Capto, Kennametal's KM—create switching costs that protect incumbent positions.
ISO 9001 quality management and ISO/TS 16949 automotive-specific standards govern supplier qualification across major OEM procurement frameworks, while REACH chemical restrictions in Europe and EPA hazardous waste rules in the United States constrain coating chemistries and coolant formulations. Japan's METI enforces JIS precision standards that effectively filter non-compliant imports from Southeast Asian competitors. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied-carbon tracking requirements reshape material sourcing and energy consumption benchmarks for machine tool operations.
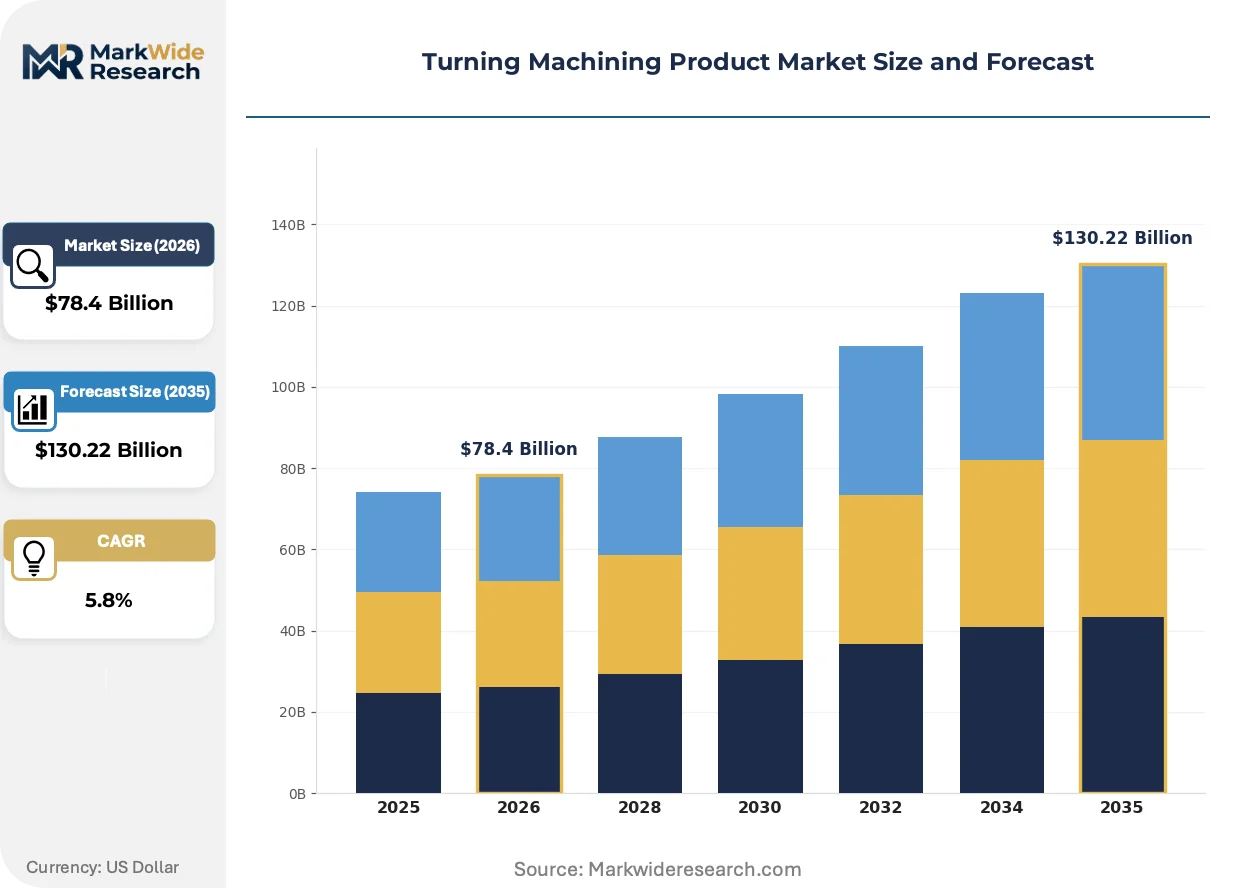
Market Dynamics
Modular tooling systems are compressing replacement cycles while China's GB precision standards and Japan's METI smart factory directives force quality upgrades across export-bound production lines.
Growth Catalysts
- Aerospace engine procurement:Tier-1 suppliers in Germany's Baden-Württemberg cluster are expanding long-term contracts for precision-turned turbine shafts and bearing housings.
- REACH chemical compliance:European coating reformulations are accelerating demand for PVD-coated inserts that eliminate hexavalent chromium processes.
- Dual carbon mandates:China's MEE energy-efficiency benchmarks for machine tool operations are retrofitting demand toward servo-driven CNC lathes.
Market Restraints
- Tungsten supply concentration:Over 80 percent of global tungsten ore processing sits in Chinese state-controlled refineries, exposing insert manufacturers to export quota volatility.
- Cobalt price instability:DRC mining disruptions and LME trading spreads are compressing margins on premium carbide grades.
- Two-axis lathe commoditization:Chinese producers have collapsed pricing on standard CNC machines below breakeven for European and Japanese incumbents.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for automotive component manufacturing are attracting greenfield turning capacity near Chennai and Pune industrial corridors.
- EU Green Deal embodied-carbon tracking:Machine tool OEMs can capture premium positioning by certifying energy consumption per machined part.
- Digital twin convergence:Real-time tool wear prediction through IoT sensor fusion is opening subscription revenue streams alongside hardware sales.
Industry Challenges
- ISO/TS 16949 certification timelines:Automotive supplier qualification cycles now extend 18-24 months, freezing out new entrants.
- Multi-axis programming expertise:Shortages of live-tooling and mill-turn operation specialists are constraining output at job shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turning Machining Product Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Lathes, Tool Holders, Workpieces, Inserts Application: Aerospace Manufacturing, Automotive Parts, Medical Devices, Electronics Production Technology: Hydraulic, Electric, Mechanical, CNC End User: Manufacturers, Job Shops, OEMs, Tier-1 Suppliers |
| Companies Covered | Sandvik AB, Kennametal Inc., Seco Tools AB, Walter AG, Mitsubishi Materials Corporation, DMG MORI Co., Ltd., Okuma Corporation, Sumitomo Electric Industries, Ltd., EMAG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turning Machining Product Market Trends and Innovations
Digital thread integration across machine-tool-plus-software bundles is rewriting how aftermarket service revenue gets captured and retained.
Artificial intelligence-driven predictive maintenance is electrifying competitive positioning among machine tool OEMs. Algorithms trained on spindle load and vibration signatures now forecast insert failure within 15-minute windows. Medical device manufacturers in Switzerland and orthopedic implant producers in Warsaw are adopting these systems fastest. The technology is electrifying the traditional break-fix service model into continuous uptime guarantees.
Japan's METI JIS B 6201 precision standard revisions are tightening radial runout tolerances for imported CNC lathes. Domestic machinery builders in Nagoya and Hamamatsu are recalibrating assembly lines to meet the 2024 benchmarks. Southeast Asian exporters without equivalent metrology capabilities face effective market exclusion from Japanese automotive supply chains.
Tool management as a service is displacing capital purchase models among mid-tier job shops. Sandvik Coromant and regional distributors in Michigan and Ohio are piloting per-part pricing for insert consumption. German automotive suppliers in Stuttgart and Munich are resisting this shift, preferring owned inventory buffers against supply disruption.
Turning Machining Product Market Segmentation
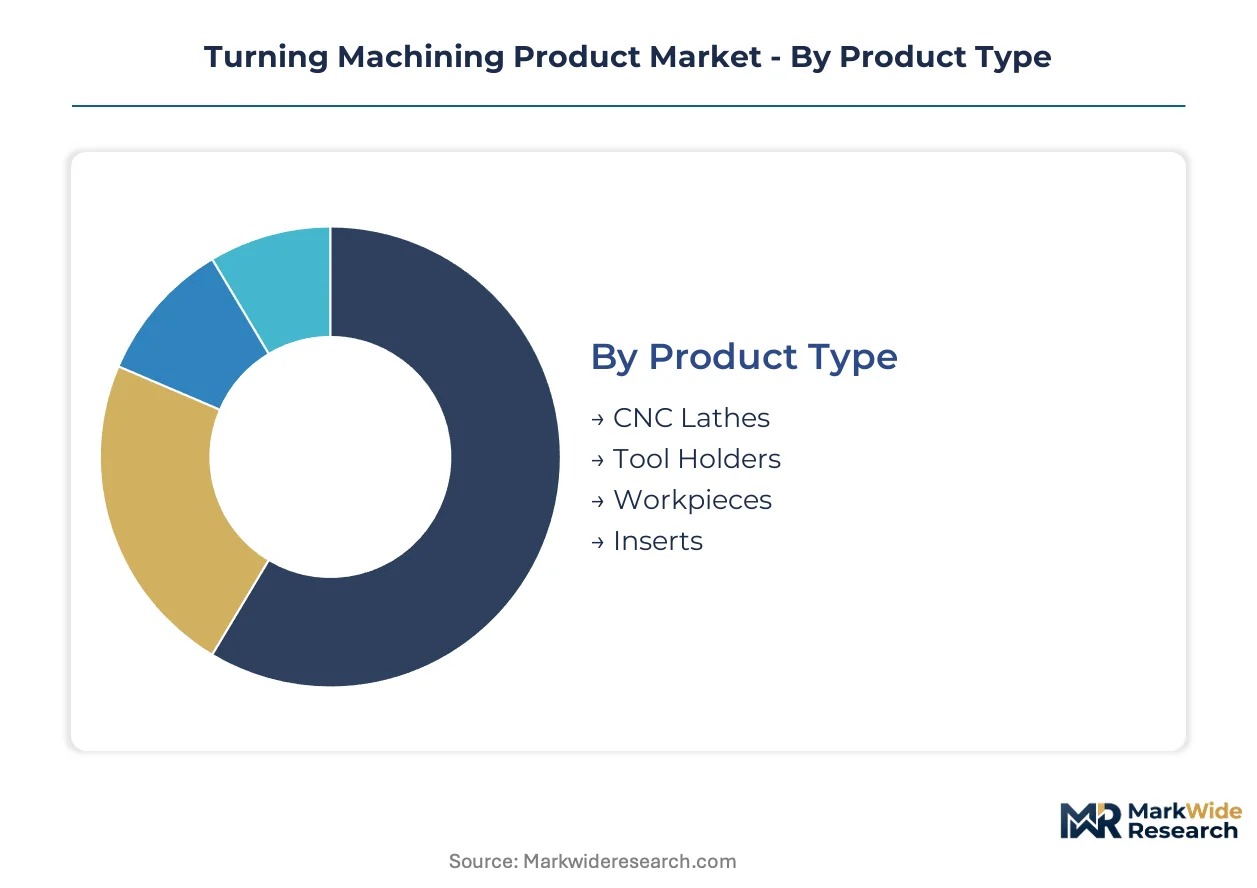
Segmentation in turning machining products reveals how upgrade cycles, precision requirements, and supply chain configurations concentrate margin pools across distinct equipment categories and customer tiers. Understanding these divisions exposes where procurement power sits and which segments command pricing leverage through technical differentiation or captive demand relationships.
Product Type:
Replacement cycles vary dramatically by product category, with consumable tooling demanding continuous replenishment while capital equipment triggers episodic procurement events tied to capacity expansion or technology obsolescence.
- CNC Lathes:Two-axis configurations dominate installed base volume in emerging manufacturing corridors, while multi-axis mill-turn centers command premium positioning in Germany's Baden-Württemberg cluster where automotive OEMs specify live-tooling capability for complex shaft geometries. China's domestic producers have compressed standard machine pricing through state-subsidized capacity additions.
- Inserts:Carbide substrates with PVD or CVD coatings generate predictable recurring revenue through wear-cycle replacement schedules averaging 45-90 minutes in high-speed steel cutting applications. Aerospace manufacturers in Toulouse and Hamburg specify ISO-certified insert grades that eliminate hexavalent chromium surface treatments under REACH compliance timelines.
- Tool Holders:Proprietary interface geometries create switching costs that protect incumbent supplier positions across precision machining operations.
- Workpieces:Chuck and fixture systems anchor workholding stability for repetitive high-volume production environments.
CNC Lathes sits at the top of the volume ranking, with Inserts climbing the fastest.
Application:
Cost tier stratification separates commodity component production from certified precision manufacturing where qualification barriers and regulatory compliance create defendable margin structures.
- Aerospace Manufacturing:Turbine shaft and bearing housing specifications demand ±0.005 mm tolerances with full material traceability through AS9100 quality frameworks. Tier-1 suppliers in Germany and France maintain decade-long supply agreements that freeze out unqualified competitors.
- Automotive Parts:Powertrain component volumes in Stuttgart and Munich drive demand for high-throughput turning centers with sub-30-second cycle times. Dual carbon mandates from China's MEE are retrofitting production lines toward servo-driven electric machines with regenerative braking.
- Medical Devices:Orthopedic implant producers in Warsaw and Swiss manufacturers specify turned titanium and cobalt-chrome components under ISO 13485 medical device quality management.
- Electronics Production:Miniaturized connector and pin manufacturing concentrates in Shenzhen and Taiwan with emphasis on sub-micron surface finish requirements.
Automotive Parts holds the largest addressable volume base, with Aerospace Manufacturing expanding most quickly through engine platform procurement cycles.
Technology:
Customer type differentiation separates high-mix job shops requiring programming flexibility from dedicated production facilities optimized for single-part high-volume output.
- CNC:Computer numerical control dominates precision turning through programmable tool paths and real-time adaptive feed rate modulation. Japan's METI-directed smart factory initiatives are accelerating IoT sensor integration for predictive maintenance across Nagoya and Hamamatsu machinery installations.
- Electric:Servo-driven spindle and axis motors displace hydraulic power units under energy-efficiency benchmarks in the EU Green Deal and China's dual carbon framework.
- Hydraulic:Legacy power transmission persists in heavy-duty roughing applications where torque density requirements exceed electric motor specifications.
- Mechanical:Cam-driven automatic lathes retain niche positioning in ultra-high-volume fastener production with minimal setup changeover.
CNC commands the dominant technology share, with Electric gaining share fastest through regulatory pressure on energy consumption metrics.
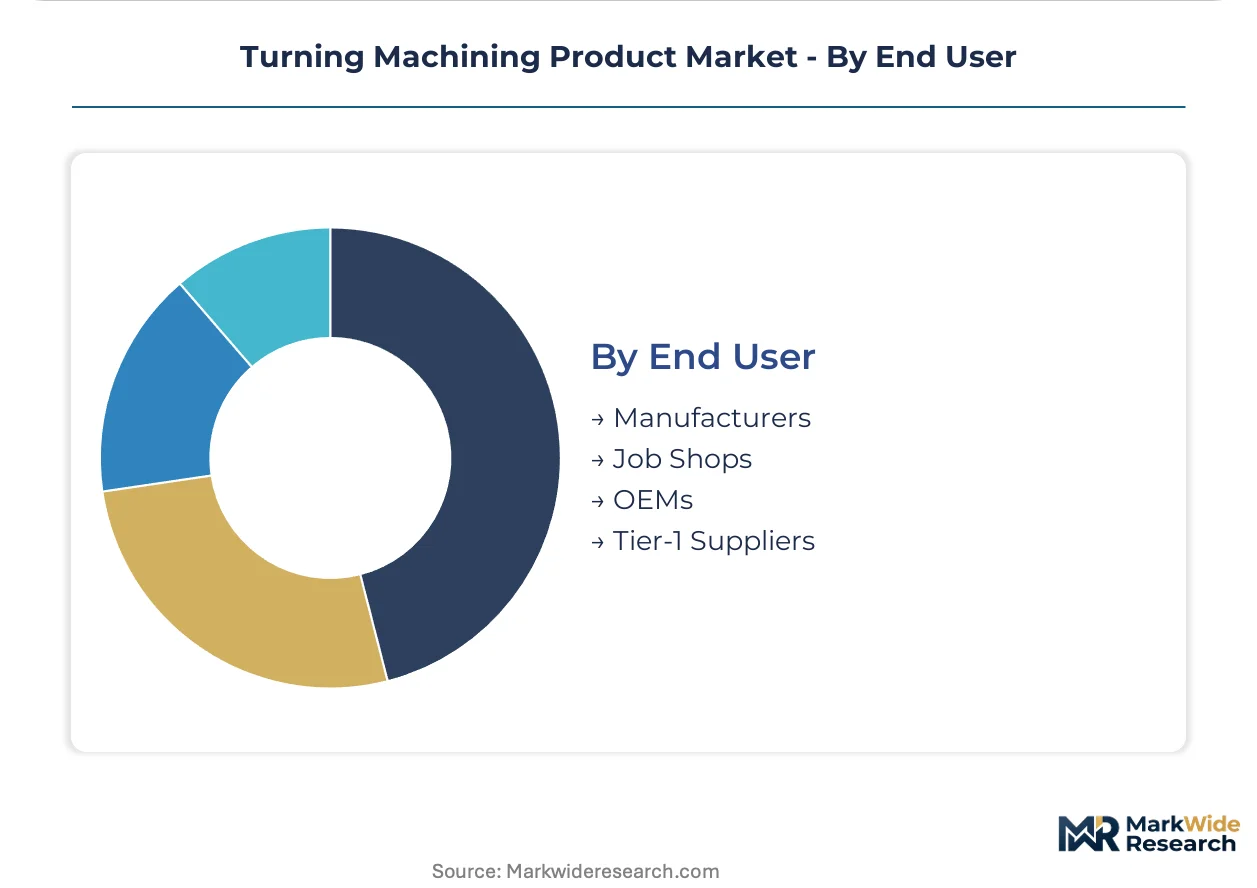
End User:
Geographic concentration of manufacturing capacity dictates regional equipment specification patterns and aftermarket service density requirements.
- Tier-1 Suppliers:Dense supplier networks in Germany's automotive corridor demand just-in-time delivery of precision-turned components with zero-defect quality protocols. ISO/TS 16949 certification cycles extending 18-24 months create structural barriers against new market entrants.
- OEMs:Captive machine shops at major automotive and aerospace manufacturers specify integrated machine-tool-plus-software bundles that lock in proprietary service relationships.
- Job Shops:High-mix low-volume operators in Michigan and Ohio are piloting tool-management-as-a-service models to convert capital expenditure into per-part operating costs.
- Manufacturers:Integrated production facilities with dedicated turning capacity optimize for total cost per machined part through volume purchasing leverage.
Tier-1 Suppliers represent the largest equipment procurement segment, with Job Shops adopting new commercial models most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Baden-Württemberg region pioneered precision turning for automotive powertrains in the post-war industrial reconstruction era. This historical foundation established the technical standards and supplier density that now define global procurement patterns for high-volume turned components.
Germany
Automotive OEMs in Stuttgart and Munich drive demand for multi-axis mill-turn centers with live-tooling capability. KBA vehicle certification requirements mandate traceable manufacturing processes for safety-critical shaft components. The Baden-Württemberg cluster maintains dense Tier-1 supplier networks executing just-in-time delivery contracts with zero-defect protocols.
China
Domestic producers have compressed standard CNC lathe pricing through state-subsidized capacity expansions in Yangtze River Delta manufacturing corridors. MEE dual carbon energy-efficiency benchmarks are retrofitting production lines toward servo-driven electric machines. GB precision standards for machine tools are tightening quality thresholds for export-bound equipment sales.
Japan
METI-directed smart factory initiatives are accelerating IoT sensor integration for predictive maintenance across Nagoya and Hamamatsu machinery installations. JIS B 6201 precision standard revisions are tightening radial runout tolerances for imported CNC lathes. Domestic machinery builders are recalibrating assembly lines to meet the 2024 benchmarks, effectively filtering non-compliant Southeast Asian competitors.
United States
Job shops in Michigan and Ohio are piloting tool-management-as-a-service models to convert capital expenditure into per-part operating costs. EPA hazardous waste rules constrain coating chemistries and coolant formulations for Midwest manufacturing operations. Aerospace manufacturers in Seattle and Wichita specify precision-turned turbine shafts under AS9100 quality frameworks with full material traceability.
India
Production-linked incentives for automotive component manufacturing are attracting greenfield turning capacity near Chennai and Pune industrial corridors. BIS certification requirements for imported machine tools are creating qualification barriers against unverified equipment. Tier-1 suppliers are expanding long-term contracts for precision-turned powertrain components to serve both domestic OEMs and export markets.
Turning Machining Product Market Competitive Landscape
Premium-margin players sit above commodity-margin players across materials science capability and proprietary interface geometry control. The vendor base stratifies into three tiers: carbide materials specialists commanding insert-grade pricing power, machine-tool-plus-software bundlers capturing aftermarket service revenue, and state-subsidized Chinese producers collapsing pricing on standard two-axis configurations. Strategic archetypes include captive tungsten supply operators, integrated digital thread providers, and regional job-shop distributors. Dominant competitive moves center on backward integration into raw material refining and technology licensing for predictive maintenance algorithms.
Among Swedish and American materials specialists, Sandvik AB and Kennametal Inc. occupy positions exemplifying the premium-insert archetype through carbide substrate control. Japanese machinery builders DMG MORI Co., Ltd. and Okuma Corporation anchor the integrated machine-tool-plus-software tier. These named entities represent how geographic origin and corporate structure correlate with strategic positioning across the value chain.
| Leading Market Players |
|---|
| Sandvik AB |
| Kennametal Inc. |
| Seco Tools AB |
| Walter AG |
| Mitsubishi Materials Corporation |
| DMG MORI Co., Ltd. |
| Okuma Corporation |
| Sumitomo Electric Industries, Ltd. |
| EMAG |
| Others |
Pricing and Supply Chain Analysis
Multi-axis programming specialists in Germany's Baden-Württemberg cluster command wage premiums that widen spreads between premium mill-turn centers and commoditized two-axis lathes. Labor-cost differentials between Nagoya's precision machinists and Yangtze River Delta operators feed directly into three-tier equipment pricing that separates aerospace-certified bundles from standard automotive configurations.
Pricing Analysis
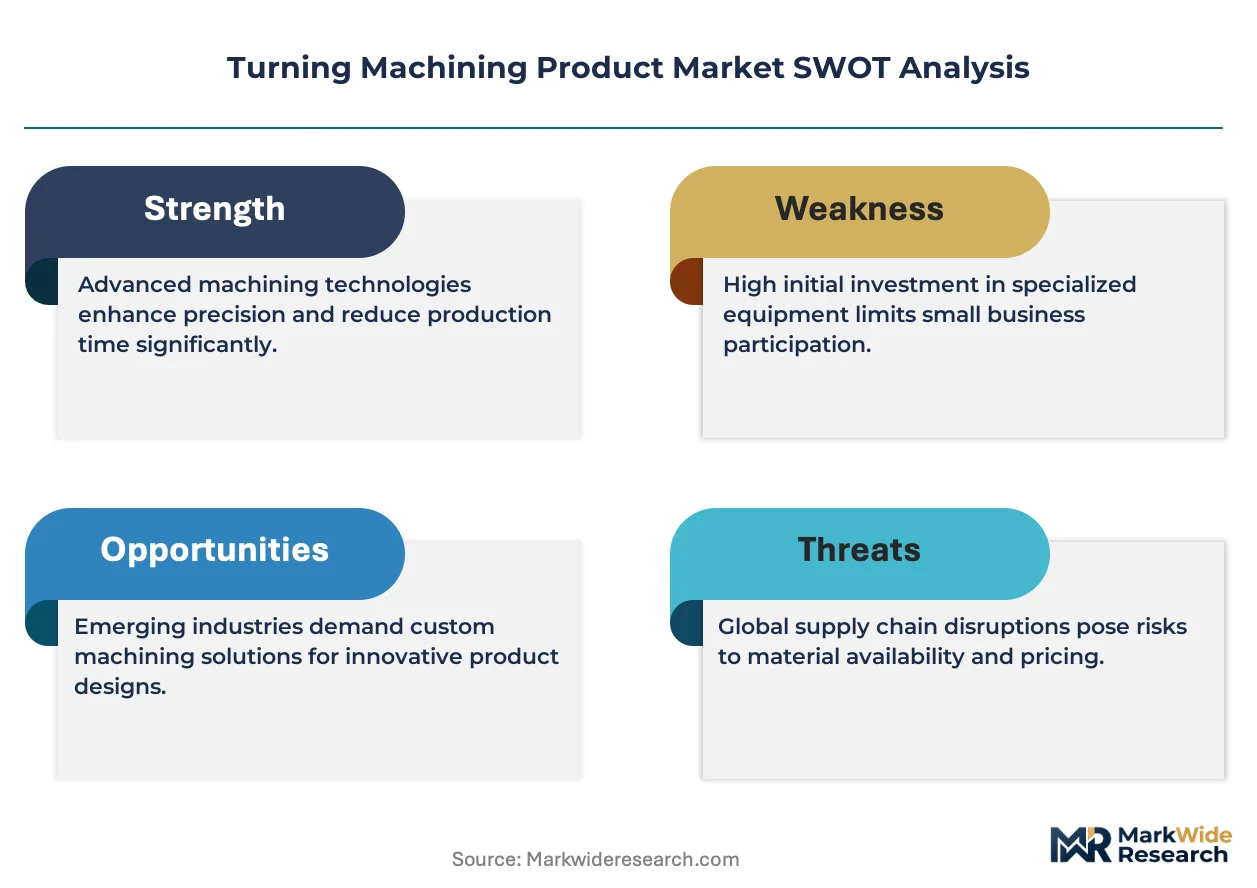
Three-tier pricing structure across premium, standard, and economy levels governs procurement patterns, with ISO/TS 16949 certification tiers and after-sales service bundling as primary differentiation drivers. Cost compression in economy-grade two-axis machines is intensifying because Chinese state-subsidized producers have collapsed pricing below European breakeven thresholds. Tier-1 automotive suppliers in Stuttgart exhibit lowest price sensitivity due to zero-defect protocol requirements, while Midwest job shops in Michigan and Ohio show highest sensitivity as they pilot tool-management-as-a-service conversions.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated machine-tool-plus-software bundles, while regional distributors serve fragmented job-shop demand. Tungsten ore processing concentrates in Chinese state-controlled refineries, with cobalt binder supply anchored in DRC mining operations and carbide substrate production centered in Japan and Sweden. Single-source vulnerability in tungsten supply exposes insert manufacturers to export quota volatility. Distribution runs through captive service networks for premium tiers and independent distributors for standard equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where aerospace engine procurement cycles are shifting specifications toward ±0.005 mm tolerance grades with full material traceability. Premium positioning now depends on certification depth rather than volume scale.
For Market Incumbents: Deepen captive tungsten powder supply through backward integration into refining operations, insulating margin structures from Chinese export quota volatility. Expand metrology-capable service networks in Germany's Baden-Württemberg cluster to lock in Tier-1 automotive supplier relationships against emerging Chinese competitors. Prioritize JIS B 6201 precision standard compliance investments to maintain access to Japan's METI-directed smart factory procurement channels.
For New Entrants and Emerging Players: India's PLI scheme for automotive component manufacturing opens a window for greenfield turning capacity near Chennai and Pune industrial corridors where BIS certification requirements have not yet frozen out unverified equipment. Target job-shop segments in Michigan and Ohio with tool-management-as-a-service offerings that convert capital expenditure into per-part operating costs, bypassing incumbent switching costs around proprietary holder geometries.
For Investors and Strategic Acquirers: Machine tool OEMs with integrated software bundles are the most active acquirer in this space, seeking predictive maintenance algorithm capabilities to electrify break-fix service models into continuous uptime guarantees. Five-to-ten year viability hinges on digital thread integration depth rather than hardware scale. Watch for inflection when EU Green Deal embodied-carbon tracking requirements trigger retrofit demand toward servo-driven electric machines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Refining | Captive supply of tungsten powders insulates Kennametal's margin structure from Chinese export quota volatility. |
| Predictive Maintenance Algorithm Licensing | DMG MORI's spindle load and vibration signature forecasting converts break-fix service into continuous uptime guarantees. |
| ISO/TS 16949 Certification Investment | Eighteen-to-twenty-four month qualification cycles create structural barriers that protect incumbent Tier-1 supplier positions. |
| Tool Management as a Service Pilot | Sandvik Coromant's per-part pricing models in Michigan and Ohio convert job-shop capital expenditure into operating costs. |
| JIS B 6201 Precision Compliance Recalibration | Domestic Japanese machinery builders in Nagoya and Hamamatsu filter non-compliant Southeast Asian competitors from automotive supply chains. |
Research Methodology
Coverage spans Germany, China, Japan, the United States, and India, with primary inputs from each regional manufacturing cluster. Primary interviews engaged plant engineers at Tier-1 automotive suppliers, aftermarket service heads at machine tool OEMs, procurement teams at aerospace manufacturers, and maintenance directors at precision job shops. Secondary validation drew from SEC 10-K filings, METI smart factory initiative documentation, EU Green Deal regulatory texts, and customs trade data for tungsten and cobalt flows. Bottom-up equipment shipment data triangulated against top-down manufacturing value-added estimates.
Granularity-level modeling operated at product-type, application, technology, and end-user dimensions, with additional precision-grade tier segmentation for aerospace versus automotive specifications. Volume and value outputs across the analysis window reflect equipment replacement cycle timing, regulatory retrofit deadlines, and capacity expansion announcements. CAGRs derived from trend-line analysis of historical shipment data and projected procurement cycles for engine platform introductions. Industry-specific inputs included tungsten ore export quota schedules and REACH chemical compliance timelines for coating reformulations.
Revisions become necessary when dual carbon mandate enforcement intensifies, tungsten export quotas tighten beyond historical ranges, or multi-axis programming expertise shortages constrain output at precision job shops. Forecasts reflect assumptions around continued aerospace engine procurement expansion and sustained automotive powertrain component volumes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
Precision Strain Wave Reducer Gearboxes Market
Precision Mechanics and Electrics
Laser Surface Texturing Market
Precision Mechanics and Electrics
Asia-Pacific Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Right Angle Fastener Market
Precision Mechanics and Electrics
Impression Die Forging Market
Precision Mechanics and Electrics
Precision Adjustment Screw Market
Precision Mechanics and Electrics
Laser Cladding Market
Precision Mechanics and Electrics
High Precision Worm Shaft Market
Precision Mechanics and Electrics
Precision Engineering Machines Market
Precision Mechanics and Electrics
Precision Roller Levelers Market
Precision Mechanics and Electrics
Global Ball Screw Market
Precision Mechanics and Electrics
Industrial Spindles Market
Precision Mechanics and Electrics
Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
North America Precision Turned Product Manufacturing Market