

Outsourcing Civil Engineering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Outsourcing Civil Engineering Services Market Insights
India's engineering workforce pool is repositioning global outsourcing flows toward South Asian delivery centers. Stantec leverages its integrated design-consulting model to anchor complex infrastructure programs across North American transit authorities. Tata Consultancy Services sustains competitive depth through captive digital-twin capabilities that reduce client site-visit costs. Cyient specializes in geospatial and survey-data processing, occupying a defensible niche against generalist IT competitors.
Outsourcing civil engineering services encompasses the external procurement of structural analysis, site inspection, project management, and environmental assessment functions from third-party specialists rather than in-house teams. These services typically deploy Building Information Modeling protocols, drone-based topography capture, and finite-element simulation to accelerate project timelines while reducing owner-side headcount. Structural design and project management command the largest revenue pools within service-type segmentation, reflecting their centrality to project risk allocation and permit approval. The dedicated-team delivery model is gaining share against fixed-price contracts for multi-year infrastructure engagements, as owners seek continuity in engineering judgment rather than transactional scope completion.
FERC guidelines on energy infrastructure permitting and India's CEA technical standards for power transmission shape compliance requirements that outsourced engineering partners must embed in deliverables. The EPA's National Environmental Policy Act review thresholds and state-level DOT design manuals in the US create layered regulatory terrain that specialists navigate more efficiently than generalist contractors. Stakeholders must monitor how BIM mandate expansions by infrastructure authorities in Germany, Japan, and the UK reshape competency requirements for offshore engineering teams.
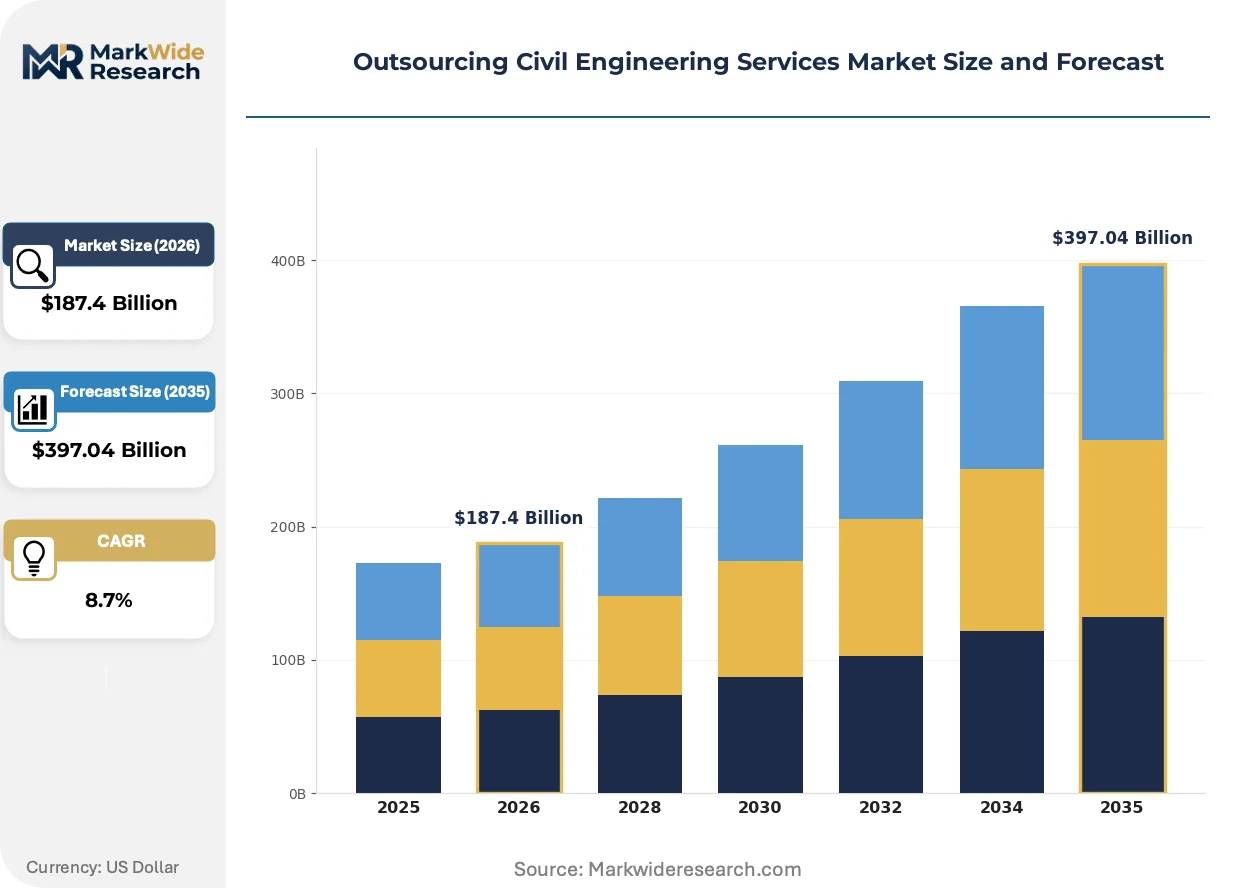
Market Dynamics
India's PLI scheme for infrastructure-linked manufacturing is accelerating outsourcing demand by subsidizing domestic engineering capacity expansion, while BIM mandate expansions across Germany, Japan, and the UK are reshaping competency requirements for offshore delivery teams.
Growth Catalysts
- India's Production-Linked Incentive scheme:Infrastructure-linked manufacturing subsidies under this program are driving captive engineering center expansion across Maharashtra and Gujarat. State transport agencies now bundle design-build contracts with mandatory local engineering presence.
- Drone-based topography capture:Survey-data processing automation is compressing site-assessment timelines from weeks to days. Rail and highway authorities in India specify drone-captured digital terrain models for bid submissions.
- FERC energy infrastructure guidelines:Permitting complexity for US transmission projects is pushing owners toward specialized engineering partners with embedded regulatory expertise. Outsourced teams now front-load environmental review documentation.
Market Restraints
- Licensed engineer scarcity:India's western corridor faces concentration risk as Maharashtra and Gujarat compete for the same chartered professional pool. Salary inflation in Mumbai and Ahmedabad is compressing margin structures.
- Proprietary BIM format fragmentation:Autodesk Revit, Bentley OpenRoads, and Graphisoft ArchiCAD maintain incompatible data schemas. Project handoffs between design and construction phases require costly translation protocols.
- Steel and cement price volatility:Input cost swings distort fixed-price contract viability. Owners resist indexation clauses, forcing engineering firms to absorb commodity risk.
Strategic Opportunities
- Digital-twin convergence with IoT sensor networks:Real-time structural health monitoring is creating recurring revenue streams beyond design-phase engagement. Indian IT services firms are acquiring sensor-integration capabilities to capture this whitespace.
- CEA technical standards for power transmission:India's Central Electricity Authority mandates are forcing foreign contractors to partner with domestic engineering validators. Compliance-as-a-service models are emerging for transmission line design.
- Environmental assessment unbundling:EPA National Environmental Policy Act review thresholds are pushing US infrastructure owners to separate ecological documentation from core design contracts. Specialized Indian environmental consultancies are capturing this work.
Industry Challenges
- Chartered structural engineer certification timelines:India's Institution of Engineers qualification backlog delays project staffing. Firms maintain bench capacity to cover six-month credentialing windows.
- Legacy CAD-to-BIM migration friction:State-level DOT design manuals in the US still reference 2D deliverable standards. Hybrid workflow maintenance drains technical resources.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outsourcing Civil Engineering Services Market Trends and Innovations
Generative design algorithms and AI-assisted code-checking are compressing iteration cycles, while regulatory authorities harden data-integrity requirements for model-based submissions. Procurement patterns are fragmenting as owners unbundle environmental, structural, and project-management scopes.
Digital-twin platforms are integrating finite-element simulation with real-time sensor feeds to enable predictive maintenance contracts. Indian rail authorities now require digital-twin handoffs for new corridor projects. This convergence is integrating lifecycle service revenue into traditionally design-only relationships.
REACH chemical substance restrictions and the EU Green Deal embodied-carbon thresholds are mandating material passport documentation for infrastructure steel and concrete. German transport ministries now reject bids lacking environmental product declarations. Engineering firms serving European export markets are rebuilding material libraries to comply.
Consortium-based procurement is displacing single-source engineering contracts for complex transit projects. Mumbai Metro and Delhi MRT Corporation now split design validation across multiple specialist vendors. This pattern is most visible in India's western corridor, where risk-averse public agencies fragment accountability.
Outsourcing Civil Engineering Services Market Segmentation
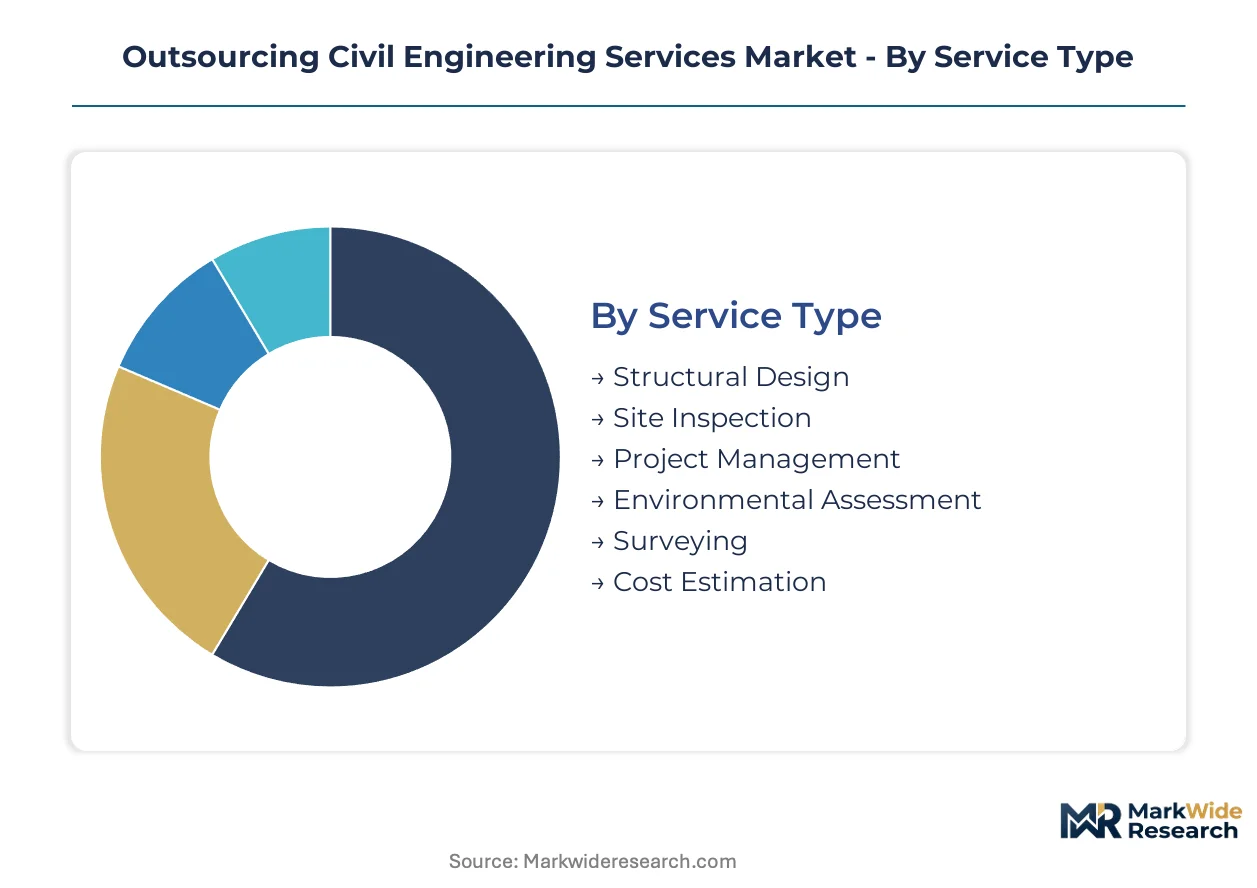
Segmentation in civil engineering outsourcing reveals how procurement patterns fragment across project complexity tiers and client risk appetites. Understanding these divides clarifies where specialized engineering competencies command premium positioning versus commoditized execution.
Service Type:
Buyers differentiate by technical depth required and liability exposure in final deliverables.
- Structural Design:Finite-element simulation and load-bearing calculations form the technical core. Highway and rail authorities in India bundle these services with mandatory BIM compliance, driving captive center expansion across Maharashtra and Gujarat.
- Project Management:Risk allocation and milestone governance dominate scope definitions. US transit authorities now front-load environmental review documentation through specialized partners with embedded FERC expertise.
- Site Inspection:Drone-based topography capture compresses assessment timelines from weeks to days.
- Environmental Assessment:EPA National Environmental Policy Act thresholds push ecological documentation separation from core design contracts.
- Surveying:Geospatial data processing automation reduces client site-visit costs.
- Cost Estimation:Steel and cement price volatility distorts fixed-price contract viability.
Volume sits with Structural Design; growth tilts toward Environmental Assessment.
Project Scale:
Contract terms harden around capital commitment thresholds and regulatory scrutiny intensity.
- Mega Projects:Consortium-based procurement fragments single-source engineering contracts. Mumbai Metro and Delhi MRT Corporation split design validation across multiple specialist vendors, concentrating accountability in India's western corridor.
- Large Scale:Dedicated-team delivery models displace fixed-price structures as owners seek continuity in engineering judgment.
- Mid Scale:Hybrid workflow maintenance drains technical resources where legacy CAD standards persist.
- Small Scale:Time-and-material arrangements dominate given scope uncertainty.
Revenue concentrates in Mega Projects; margin expansion favors Large Scale engagements.
Client Type:
Procurement sophistication varies by balance-sheet capacity and regulatory compliance burden.
- Government Agencies:State transport agencies bundle design-build contracts with mandatory local engineering presence under India's PLI scheme. CEA technical standards for power transmission force foreign contractors toward domestic validator partnerships.
- Construction Firms:BIM mandate expansions across Germany, Japan, and the UK reshape competency requirements for offshore delivery teams.
- Real Estate Developers:Cost pressure drives commoditized surveying and estimation outsourcing.
- Infrastructure Operators:Digital-twin handoff requirements for new corridor projects integrate lifecycle service revenue.
Government Agencies anchor current volume; Infrastructure Operators capture steepest expansion trajectory.
Delivery Model:
Payment structure selection signals client confidence in scope definition precision.
- Dedicated Team:Multi-year infrastructure engagements favor continuity over transactional completion. Indian rail authorities now require embedded engineering presence for corridor projects.
- Fixed Price:Commodity risk absorption strains margin structures where owners resist indexation clauses.
- Time & Material:Early-phase exploration work tolerates scope fluidity.
- Managed Services:Recurring revenue streams emerge from digital-twin convergence with IoT sensor networks.
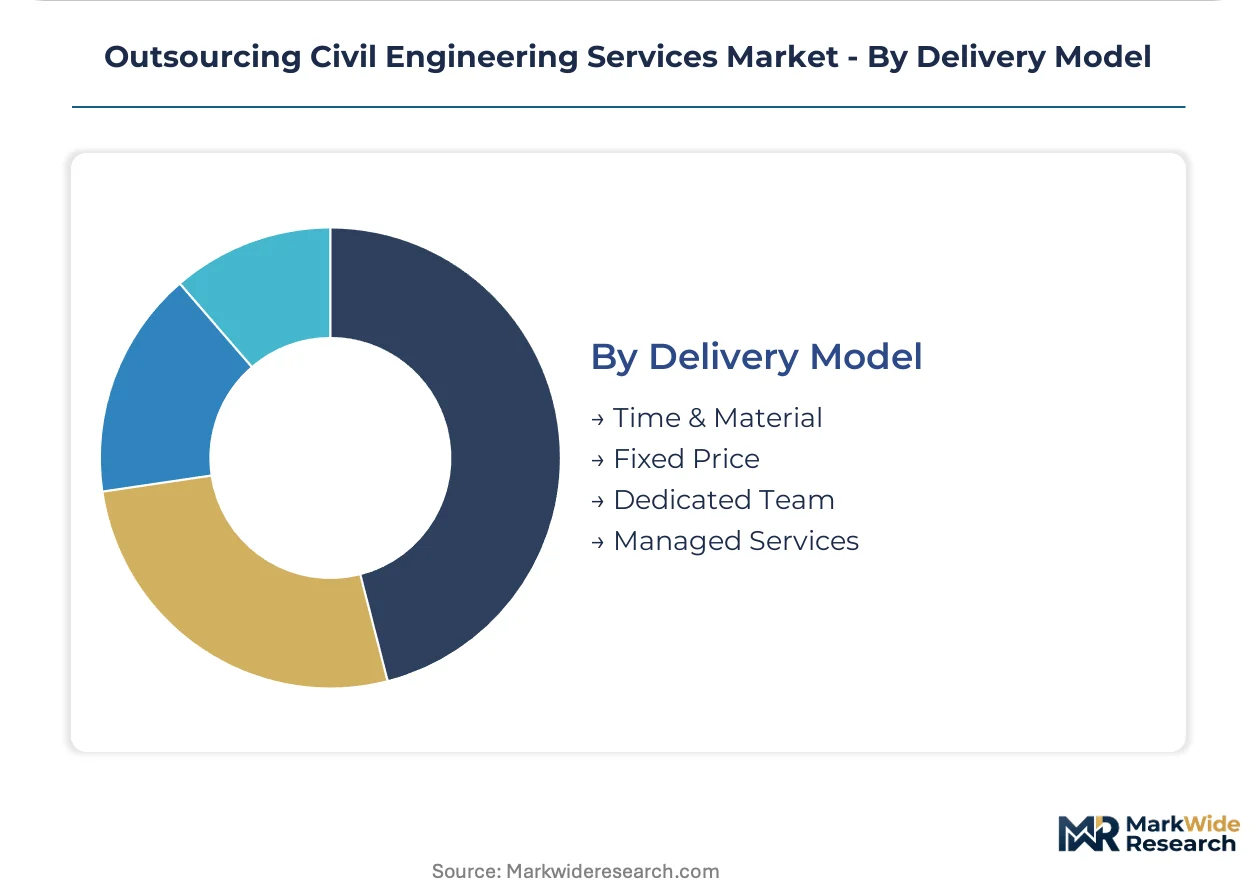
Fixed Price retains largest share; Dedicated Team gains fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portland cement production clusters in India's western corridor anchor the strongest outsourcing demand concentration for civil engineering services worldwide.
United States
FERC permitting complexity for transmission projects drives specialized engineering partnerships. EPA National Environmental Policy Act review thresholds push ecological documentation toward external specialists. Texas and California host the densest clusters of infrastructure operators seeking embedded regulatory expertise.
India
State transport agencies in Maharashtra and Gujarat bundle design-build contracts with mandatory local engineering presence. The PLI scheme for infrastructure-linked manufacturing subsidizes captive center expansion across Mumbai and Ahmedabad. Chartered engineer scarcity in this corridor compresses margin structures through salary inflation.
Germany
Transport ministries now reject bids lacking environmental product declarations under EU Green Deal embodied-carbon thresholds. REACH chemical substance restrictions mandate material passport documentation for infrastructure steel. Engineering firms serving export markets rebuild material libraries in the Ruhr industrial basin.
Japan
METI pushes BIM mandate expansions that reshape competency requirements for offshore delivery teams. Rail authorities require digital-twin handoffs for new corridor projects. The Kanto region around Tokyo concentrates demand for lifecycle-integrated service contracts.
United Kingdom
Infrastructure authorities harden data-integrity requirements for model-based submissions. The Midlands and North England host emerging engineering delivery centers serving European transit programs. Consortium-based procurement fragments single-source contracts for complex projects.
Outsourcing Civil Engineering Services Market Competitive Landscape
Global majors compete with regional champions across regulatory embedding and digital-twin capability depth. The vendor base stratifies between integrated design-consulting platforms, IT services conglomerates with captive engineering arms, and geospatial processing specialists. Three archetypes dominate: full-service infrastructure consultants, technology-enabled delivery platforms, and niche survey-data processors. Competitive moves concentrate on strategic partnerships for regulatory access and technology licensing for BIM convergence.
Within the integrated consulting tier, Stantec anchors complex infrastructure programs across North American transit authorities. Tata Consultancy Services exemplifies the technology-enabled archetype through digital-twin capabilities that reduce client site-visit costs. Cyient occupies the specialist position in geospatial and survey-data processing, creating defensible positioning against generalist IT competitors.
| Leading Market Players |
|---|
| Stantec |
| HCL Technologies |
| Infosys |
| Tata Consultancy Services |
| Wipro |
| Capgemini |
| Cyient |
| Altair Engineering |
| EPAM Systems |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal embodied-carbon thresholds gate qualified supply for infrastructure steel and concrete while commanding premium-tier pricing access for engineering firms with compliant material libraries. German transport ministry bid rejections for non-compliant documentation reshape procurement cost structures across European-facing delivery centers.
Pricing Analysis
Warranty and service bundling separates premium engineering contracts from transactional scope arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales digital-twin maintenance commitments. Cost compression in the standard tier intensifies because steel and cement price volatility forces margin absorption where owners resist indexation clauses. Real estate developers exhibit highest price sensitivity; government agencies anchor premium-tier willingness-to-pay through multi-year dedicated-team engagements.
Supply Chain Analysis
Licensed engineer supply rests on India's western corridor concentration across Maharashtra and Gujarat state labor pools. Chartered structural engineer credentialing feeds from Institution of Engineers qualification pipelines; drone hardware and BIM software licensing draw from US and European technology vendors. Single-source vulnerability concentrates in Mumbai-Ahmedabad salary inflation zones. Distribution runs through captive delivery centers serving North American transit authorities and European infrastructure operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where India's CEA technical standards for power transmission create barrier-to-entry moats for domestic validator partnerships.
For Market Incumbents: Acquire sensor-integration capabilities to capture digital-twin convergence revenue streams. Backward integration into drone-based topography hardware reduces third-party survey-data costs. Chartered engineer scarcity in Maharashtra threatens staffing velocity; maintain bench capacity covering six-month credentialing windows. For New Entrants and Emerging Players: AI-assisted code-checking technology offers wedge positioning against legacy CAD-dependent incumbents. Environmental assessment unbundling from core design contracts presents the most penetrable whitespace for specialized Indian consultancies. Front-load FERC regulatory expertise partnerships to access US transmission project workflows. For Investors and Strategic Acquirers: PLI scheme subsidy announcements are the leading indicator that captive center expansion economics are shifting. Five-to-ten-year viability favors technology-enabled delivery platforms over pure-play design consultancies. Watch for BIM mandate expansion signals from METI or German transport ministries as inflection triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Digital-Twin Platform Integration | Indian rail authority mandates for corridor handoffs lock in recurring revenue streams. |
| Regulatory Compliance Partnership | CEA validator alliances unlock foreign contractor access to India's transmission market. |
| Geospatial Capability Acquisition | Drone-based topography automation compresses site-assessment timelines from weeks to days. |
| Material Library Rebuild | REACH chemical restrictions and EU Green Deal thresholds gate European export market entry. |
| Consortium-Based Procurement Positioning | Mumbai Metro and Delhi MRT fragmentation patterns favor multi-vendor accountability structures. |
Research Methodology
Regulatory filings from FERC, EPA, and India's CEA, trade databases tracking engineering services exports, and infrastructure authority procurement records formed the secondary backbone. Primary interviews with project management officers at state transport agencies, BIM technical leads at design-consulting firms, regulatory compliance heads at power transmission developers, and procurement managers at rail authorities combined with bottom-up and top-down triangulation.
Bottom-up modeling anchored volume estimates while top-down cross-checks validated segment splits across service type, project scale, client archetype, and delivery model dimensions. CAGRs derived from historical trend extrapolation adjusted for PLI scheme subsidy trajectories and BIM mandate expansion schedules across Germany, Japan, and the UK. Digital-twin adoption curves and chartered engineer supply constraints fed industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel and cement commodity price spikes or licensed engineer credentialing backlogs. Forecasts reflect assumptions around regulatory mandate implementation timelines and PLI scheme continuity. A small set of named triggers—METI BIM mandate acceleration, EU Green Deal threshold tightening, and India's western corridor salary inflation spikes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.