
 Asia-Pacific Seismic Services Market | 2026-2036
Asia-Pacific Seismic Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Seismic Services Market Outlook
High-performance computing integration with seismic imaging algorithms is reshaping subsurface interpretation workflows across the Asia-Pacific. Schlumberger Ltd leverages proprietary full-waveform inversion platforms to anchor its technology leadership in complex geologies. BGP Inc dominates onshore acquisition across Central Asian republics and western China through state-backed fleet scale. Halliburton Company differentiates via integrated well-seismic solutions that tighten the loop between exploration and drilling decisions.
Seismic services encompass the acquisition, processing, and interpretation of elastic wave propagation data to map subsurface geological structures, typically employing source arrays generating 10-200 Hz frequencies and receiver networks sampling at 1-4 millisecond intervals. These services enable hydrocarbon prospect evaluation, mineral deposit delineation, and geohazard assessment for infrastructure planning. Data Processing commands premium margins where algorithmic sophistication determines interpretation fidelity, while 4D Seismic represents the fastest-expanding technology segment as producers prioritize reservoir surveillance over greenfield discovery. Oil & Gas Industry end users sustain the dominant revenue share, though Renewable Energy applications for geothermal and offshore wind site characterization are expanding the addressable base.
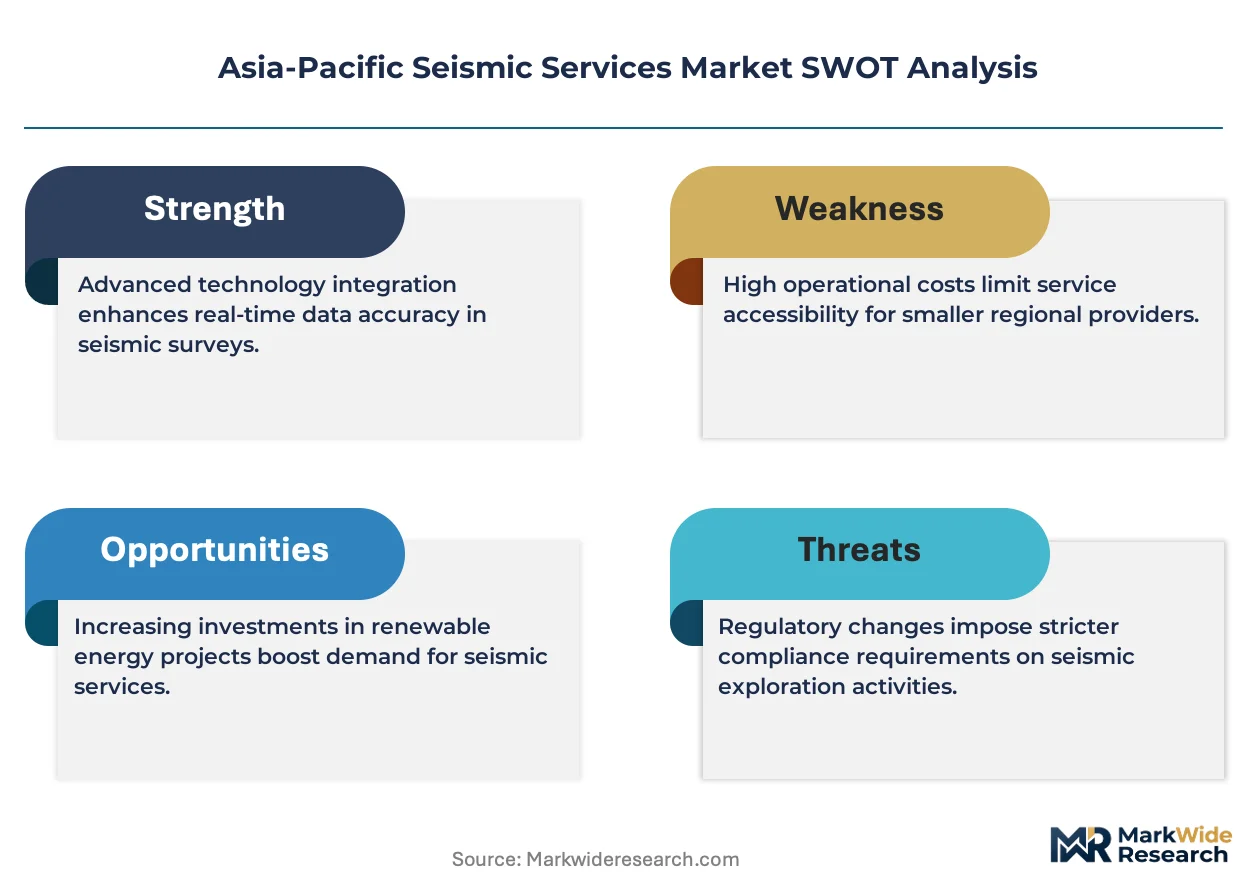
China's MEE enforces environmental impact assessments for offshore seismic operations, tightening vessel permitting timelines and elevating compliance costs. Australia's NOPSEMA mandates wellbore integrity verification through seismic monitoring, directly stimulating 4D and microseismic service contracts. Japan's METI subsidizes next-generation ocean bottom seismology for earthquake early-warning systems, creating parallel demand from government agencies. Stakeholders must weigh state-backed fleet expansion in China against Western technology sanctions when calibrating partnership and procurement strategies across the region.
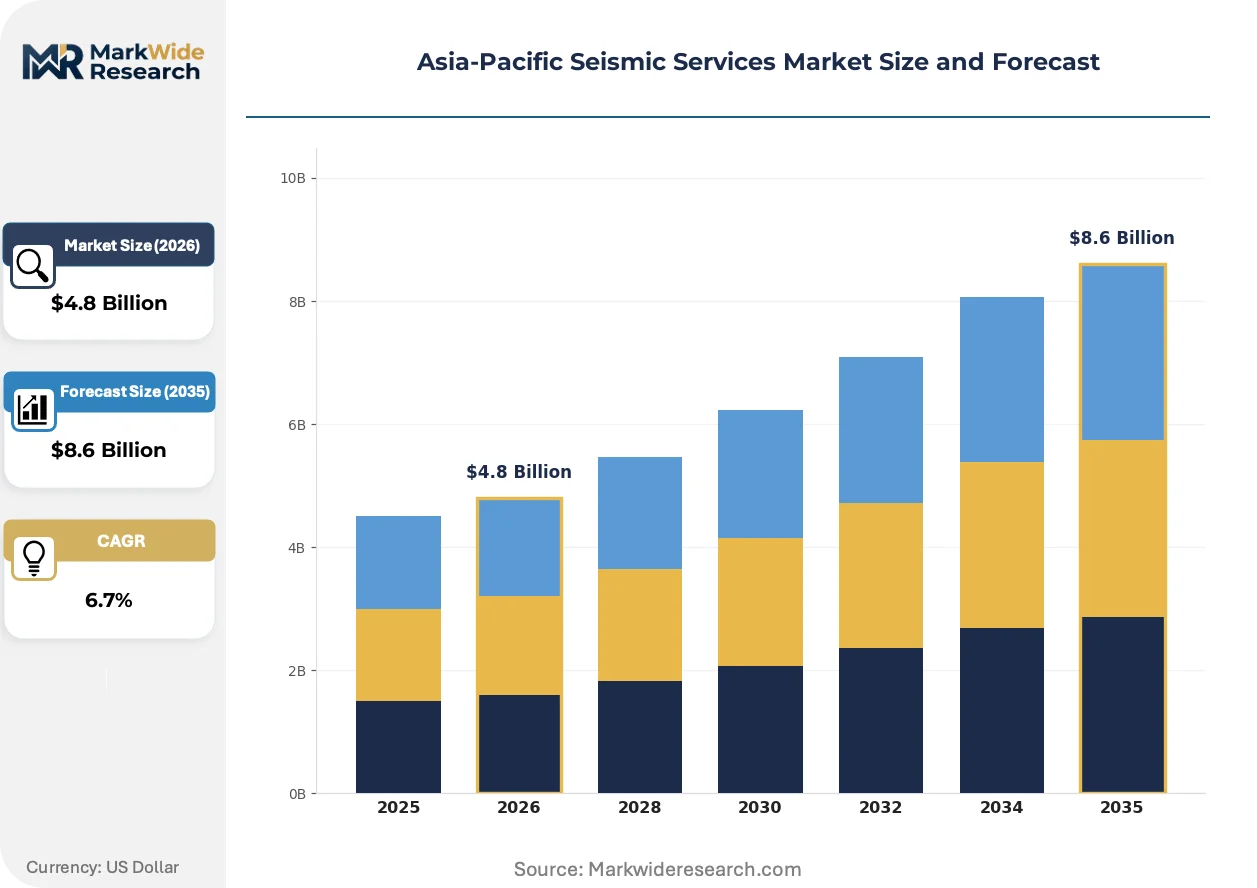
Market Dynamics
State-backed fleet expansion in China is compressing contract margins for Western seismic contractors while redirecting regional procurement toward integrated subsurface monitoring packages. This supply-side concentration is forcing technology licensors to recalibrate partnership models across Southeast Asian offshore basins.
Growth Catalysts
- Dual carbon goals:China's MEE mandates subsurface characterization for carbon capture and storage projects, redirecting state capital toward 4D seismic monitoring infrastructure.
- LNG field optimization:Australia's offshore basins require high-resolution 3D surveys to maximize recovery factors from mature gas fields, sustaining demand for advanced acquisition vessels.
- Ocean bottom seismology:Japan's METI subsidizes next-generation seabed sensor networks for earthquake early-warning systems, creating parallel government demand alongside hydrocarbon applications.
Market Restraints
- Marine diesel volatility:Offshore vessel fuel costs constitute 35-45% of acquisition contract values, exposing operators to bunker price swings that compress bid margins.
- Permitting timeline extension:China's MEE environmental impact assessments for offshore seismic operations now require 8-14 month review cycles, delaying project commencement.
- Geophone supply concentration:MEMS-based sensor manufacturing concentrates in East Asian fabs, creating single-source risk for high-channel-count receiver systems.
Strategic Opportunities
- Geothermal site characterization:Indonesia's volcanic arc provinces lack subsurface imaging for renewable energy development, opening greenfield contracts for onshore 3D crews.
- Offshore wind foundation mapping:South Korea's renewable energy mandates require geotechnical seismic surveys for turbine base design, expanding addressable demand beyond oil and gas.
- Full-waveform inversion convergence:Integration of quantum computing prototypes with seismic imaging algorithms promises order-of-magnitude processing speed gains for complex salt geometries.
Industry Challenges
- Geophysicist talent scarcity:Interpretation of elastic wave propagation data requires specialized training in quantitative geoscience, with university programs failing to match industry retirement rates.
- Legacy data integration:2D seismic libraries from the 1980s-1990s require algorithmic reprocessing to align with modern 3D survey coordinate systems, consuming analyst bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Seismic Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Acquisition, Data Processing, Interpretation, Monitoring Technology: 2D Seismic, 3D Seismic, 4D Seismic, Ocean Bottom Seismology End User: Oil & Gas Industry, Mining Sector, Renewable Energy, Government Agencies Deployment: Onshore, Offshore, Marine, Hybrid |
| Companies Covered | Schlumberger Ltd, Halliburton Company, China Oilfield Services Limited, Fugro NV, CGG, SAExploration Holdings Inc, BGP Inc, PGS ASA, ASIAN Energy Services Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Seismic Services Market Strategic Shifts
Distributed acoustic sensing is rewiring how subsurface data is acquired across Asia-Pacific energy and infrastructure sectors. Three interconnected developments are compressing traditional service boundaries.
Full-waveform inversion is digitizing subsurface velocity model building by replacing ray-based tomography with elastic wave equation solvers. Australia's LNG developers now mandate FWI-derived depth imaging for pre-salt carbonate reservoirs, compressing drilling uncertainty windows from months to weeks. This algorithmic shift is digitizing the handoff between exploration and field development teams, collapsing sequential workflow stages into parallel interpretation environments.
Australia's NOPSEMA mandates wellbore integrity verification through 4D seismic monitoring for all offshore production licenses, directly stimulating microseismic service contract growth. Operators must demonstrate reservoir compaction and caprock seal performance using time-lapse elastic property maps, with non-compliance triggering production suspension. This regulatory architecture is forcing acquisition contractors to bundle permanent seabed sensor installations with conventional vessel-based surveys.
Integrated well-seismic solutions are displacing standalone exploration contracts as the preferred procurement model across Southeast Asian national oil companies. Buyers now demand real-time geosteering support that tightens the feedback loop between seismic interpretation and directional drilling decisions, unbundling traditional survey-then-drill sequences. This pattern is most visible in Malaysia's deepwater blocks, where production sharing contracts penalize non-productive time through explicit service integration clauses.
Asia-Pacific Seismic Services Market Segmentation
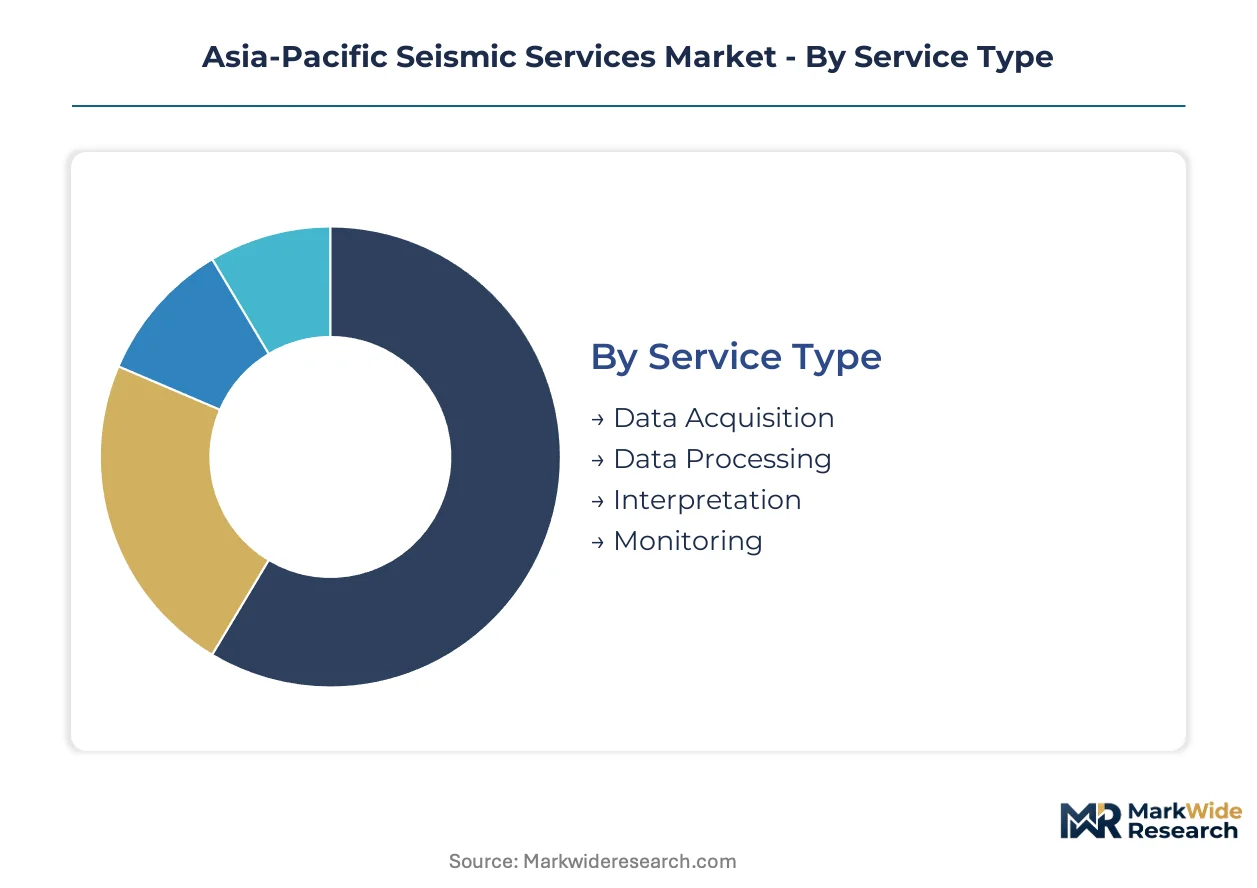
Seismic services fragment across four dimensions that determine contract structure, capital intensity, and margin profile. Procurement cycles vary from single-vessel surveys lasting weeks to multi-year reservoir monitoring programs. Understanding these segment boundaries clarifies where technology investments concentrate and where price competition intensifies.
Service Type:
Data Acquisition turns over fastest with vessel mobilization cycles measured in months, while Monitoring extends across decades. Processing and Interpretation sit between, with software refresh cycles driving replacement demand.
- Data Acquisition:Field operations deploy source arrays and receiver networks to record elastic wave propagation, consuming 60-70% of project capital expenditure. Australia's offshore LNG developers anchor regional vessel demand through high-channel-count 3D surveys in the Browse and Carnarvon basins. Crew availability constraints in Southeast Asia inflate day rates during peak exploration windows.
- Data Processing:Algorithmic refinement of raw seismic traces into migration-ready image volumes commands premium pricing where full-waveform inversion complexity escalates. China's state-backed research institutes are building captive processing centers for carbon capture site characterization, redirecting contract flow from Western service providers. Turnaround pressure from drilling schedules compresses acceptable delivery windows.
- Interpretation:Geoscientist-led structural and stratigraphic analysis translates seismic images into drilling recommendations. Indonesia's national oil company now mandates integrated interpretation teams embedded within asset development units rather than external deliverables.
- Monitoring:Time-lapse seismic surveillance tracks reservoir depletion and caprock integrity across production life cycles. Australia's NOPSEMA regulations mandate 4D monitoring for all offshore production licenses, creating contractual minimums.
Data Acquisition dominates installed base. Data Processing is where expansion concentrates.
Technology:
Cost tiers separate legacy 2D methods from premium 4D and ocean bottom systems, with 3D occupying the volume middle ground.
- 2D Seismic:Single-profile reconnaissance surveys persist in frontier basin screening where capital discipline restricts upfront investment. Papua New Guinea's onshore fold belts still rely on 2D for initial prospect ranking before 3D commitment.
- 3D Seismic:Multi-azimuth volume acquisition generates the structural detail required for development drilling in complex geology. Malaysia's deepwater blocks anchor regional 3D demand through production sharing contract terms that penalize dry holes.
- 4D Seismic:Repeated 3D surveys over producing fields capture time-lapse reservoir changes, with Australia's mature LNG fields driving repeat survey frequency. This segment climbs fastest as producers prioritize recovery optimization over greenfield discovery.
- Ocean Bottom Seismology:Seabed-emplaced sensor networks deliver multi-component data for subsalt imaging and earthquake monitoring. Japan's METI subsidies for early-warning infrastructure are expanding addressable demand beyond hydrocarbon applications.
3D Seismic commands current revenue concentration. 4D Seismic shows the steepest expansion trajectory.
End User:
Customer type determines contract structure, with oil and gas majors demanding integrated solutions while government agencies procure through tender frameworks.
- Oil & Gas Industry:Integrated majors and national oil companies sustain the dominant revenue share, with procurement shifting from discrete surveys to multi-service frame agreements. Southeast Asian NOCs now bundle acquisition, processing, and geosteering support into single-source contracts.
- Mining Sector:Hard rock mineral exploration employs shallow seismic for deposit delineation, with Australia's iron ore and coal operators representing the primary regional demand. Survey parameters emphasize near-surface resolution over deep imaging.
- Renewable Energy:Geothermal developers in Indonesia's volcanic arc and offshore wind planners in South Korea require subsurface characterization for infrastructure siting. This segment is expanding most quickly from a small base as renewable mandates harden.
- Government Agencies:Earthquake monitoring, nuclear test detection, and carbon storage verification drive non-commercial demand. China's MEE and Japan's METI operate parallel procurement channels with distinct technical specifications.
Oil & Gas Industry anchors contract volume. Renewable Energy is where new customer formation concentrates.
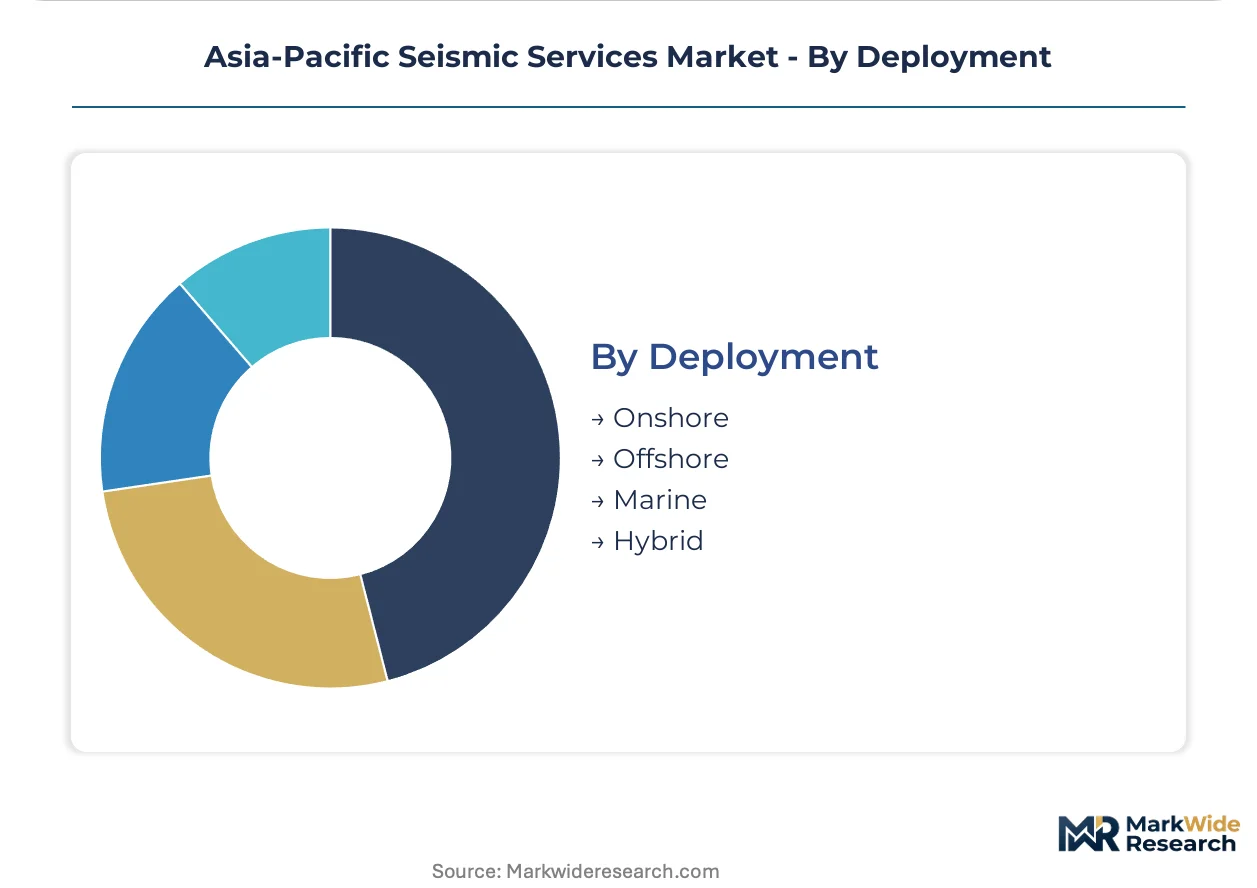
Deployment:
Geography and environment dictate equipment configuration, with marine operations commanding premium pricing and onshore facing margin compression from fleet oversupply.
- Onshore:Crew-based operations using vibrator trucks or explosive sources cover desert, jungle, and mountainous terrain. Western China and Central Asian republics concentrate regional onshore activity through BGP's state-backed fleet scale.
- Offshore:Deepwater vessel operations deploy streamer arrays for shelf and slope environments. Australia's northwest shelf and Malaysia's deepwater blocks sustain premium pricing through technical complexity and regulatory stringency.
- Marine:Ocean-bottom and transition-zone methods bridge the gap between land and deepwater, with Indonesia's archipelagic geography creating specialized demand. Equipment corrosion and deployment logistics elevate cost structures.
- Hybrid:Combined onshore-offshore programs address contiguous basins spanning coastal plains and continental shelves. Procurement integration across deployment modes tests contractor coordination capabilities.
Offshore dominates revenue per contract. Hybrid deployments are where service integration investments concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific seismic services trade flows reflect divergent national energy strategies. Import dependence for advanced acquisition vessels concentrates in Australia and Southeast Asian offshore markets, while China and Russia-linked Central Asian republics sustain export-oriented onshore crew capacity through state-backed fleet expansion.
China
BGP Inc anchors onshore acquisition capacity across western provinces and Central Asian republics through state-backed vessel and crew scale. The Ministry of Ecology and Environment enforces 8-14 month environmental impact assessment cycles for offshore seismic permits, compressing Western contractor bid windows. Sichuan-Chongqing shale basins and Xinjiang oil fields concentrate domestic crew deployment for subsurface carbon storage characterization.
Australia
LNG field optimization in the Browse and Carnarvon basins sustains premium demand for high-channel-count 3D and 4D seismic surveys. NOPSEMA mandates wellbore integrity verification through time-lapse seismic monitoring for all offshore production licenses, directly stimulating microseismic service contract growth. Perth anchors regional contractor coordination for northwest shelf deepwater operations.
Japan
METI subsidies for next-generation ocean bottom seismology drive government procurement parallel to hydrocarbon applications, expanding sensor network deployment for earthquake early-warning systems. Tokyo Bay and Nankai Trough offshore zones concentrate seabed sensor emplacement for subduction zone monitoring. National energy security priorities redirect state capital toward domestic subsurface imaging capabilities.
Indonesia
Volcanic arc provinces across Sumatra and Java lack subsurface imaging for geothermal renewable energy development, opening greenfield contracts for onshore 3D crews. Archipelagic geography creates specialized marine and transition-zone demand bridging onshore-offshore operations. Pertamina's national oil company procurement now bundles acquisition, processing, and geosteering support into single-source contracts.
South Korea
Renewable energy mandates require geotechnical seismic surveys for offshore wind turbine foundation design, expanding addressable demand beyond traditional oil and gas. West and South Sea offshore zones concentrate wind farm site characterization contracts. State-backed research institutes are building captive processing capabilities for carbon capture site evaluation.
Asia-Pacific Seismic Services Market Competitive Environment
On the supply side, the industry is consolidating around integrated subsurface monitoring packages that collapse traditional boundaries between acquisition, processing, and interpretation. Western technology licensors face margin compression from Chinese state-backed fleet expansion while recalibrating partnership models across Southeast Asian offshore basins. Three archetypes dominate: full-service integrated majors, state-backed national champions, and specialized technology licensors. Competitive moves concentrate on strategic partnerships for technology access and portfolio diversification into renewable energy applications.
Within the integrated services tier, Schlumberger Ltd and Halliburton Company exemplify technology leadership through proprietary full-waveform inversion platforms and integrated well-seismic solutions. BGP Inc occupies a position as the state-backed national champion archetype, leveraging fleet scale across Central Asian republics and western China. Among specialized technology licensors, CGG and PGS ASA represent the premium-tier vessel-based acquisition segment focused on complex offshore geologies.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Halliburton Company |
| China Oilfield Services Limited |
| Fugro NV |
| CGG |
| SAExploration Holdings Inc |
| BGP Inc |
| PGS ASA |
| ASIAN Energy Services Ltd |
| Others |
Value Chain & Pricing Dynamics
Western China's Xinjiang and Sichuan-Chongqing shale basins concentrate state-backed crew capacity, feeding BGP Inc's fleet scale into contract pricing that undercuts Western seismic contractors across Central Asian republics and domestic carbon capture site characterization projects.
Pricing Analysis
Oil and gas majors anchor contract pricing through multi-year frame agreements that bundle acquisition, processing, and geosteering support. Pricing stratifies across premium full-waveform inversion processing, standard 3D vessel surveys, and economy-tier 2D reconnaissance based on algorithmic sophistication and channel count. Cost compression in standard 3D acquisition is intensifying because BGP's state-backed fleet expansion floods Southeast Asian tender markets. National oil companies exhibit highest price sensitivity, while integrated majors prioritize technology access over rate competition.
Supply Chain Analysis
Export controls on advanced seismic processing hardware limit technology flows from US and European suppliers into Chinese state-backed research institutes. Manufacturing concentrates in China for MEMS-based geophone sensors, Norway for ocean bottom node systems, and Singapore for vessel outfitting. Component dependencies include high-channel-count receiver arrays, marine diesel propulsion systems, and full-waveform inversion software licenses. Single-source vulnerability concentrates in East Asian MEMS fabrication for high-channel-count receiver systems. Distribution runs through integrated service contractors that bundle permanent seabed installations with conventional vessel mobilizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as carbon capture site characterization and offshore wind foundation mapping open greenfield demand beyond hydrocarbon applications.
For Market Incumbents: Harden technology differentiation through proprietary full-waveform inversion platforms that anchor premium processing margins against BGP's state-backed rate competition. Deepen captive relationships with Australia's LNG developers by embedding permanent seabed sensor networks that satisfy NOPSEMA's 4D monitoring mandates. Vertical integration into ocean bottom node manufacturing reduces exposure to East Asian MEMS supply concentration. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's geothermal site characterization segment where volcanic arc provinces lack subsurface imaging for renewable energy development. Target South Korea's offshore wind foundation mapping contracts driven by renewable energy mandates requiring geotechnical surveys for turbine base design. Lead with specialized transition-zone acquisition capabilities that address archipelagic geography constraints. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-mandated infrastructure play because Australia's NOPSEMA and China's MEE are hardening seismic monitoring requirements that create contractual minimums across production lifecycles. Target acquisition candidates with integrated well-seismic solutions and permanent seabed sensor installation capabilities. Monitor permitting timeline extensions under China's MEE environmental impact assessments as a signal for Western contractor margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Subsurface Monitoring Platform Development | Schlumberger's full-waveform inversion platforms anchor technology leadership in complex pre-salt carbonate reservoirs. |
| Permanent Seabed Sensor Network Deployment | NOPSEMA's wellbore integrity mandates force acquisition contractors to bundle installations with vessel surveys. |
| Geothermal Site Characterization Capability Buildout | Indonesia's volcanic arc provinces lack imaging for renewable energy development, opening greenfield contracts. |
| Carbon Capture Site Evaluation Service Launch | China's MEE dual carbon goals redirect state capital toward 4D seismic monitoring infrastructure. |
| Ocean Bottom Seismology Technology Licensing | Japan's METI subsidies expand sensor network deployment beyond hydrocarbon into earthquake early-warning systems. |
Study Parameters
A spread of perspectives from seismic acquisition vessel operators, processing center technical directors, national oil company procurement managers, and carbon storage project developers converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation against customs data for geophone imports, NOPSEMA permit filings, and METI subsidy disclosures. Bottom-up project pipeline tracking across Australia's Browse and Carnarvon basins triangulated against top-down state capital allocation flows from China's MEE.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type, technology tier, end-user industry, and deployment mode. CAGRs derived from project-level contract value aggregation and fleet utilization rates. Industry-specific inputs included vessel day-rate trajectories, environmental permitting cycle durations, and algorithmic processing turnaround benchmarks.
Stress conditions across marine diesel price volatility, geophone supply disruption, and permitting timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about state-backed fleet expansion rates and regulatory mandate enforcement intensity. Material shifts in Western technology sanctions scope or carbon capture subsidy allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Engineering Services Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
MEP Services Market
Engineering Services
Architectural Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
United States (US) MEP Services Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Well Cementing Services Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
North America Seismic Survey Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
Geotechnical Services Market
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market