
 Europe Automated Material Handling (AMH) Market | 2026-2036
Europe Automated Material Handling (AMH) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automated Material Handling (AMH) Market Insights
Central and Eastern European manufacturing corridors are narrowing the automation gap with Western Europe as automotive and electronics suppliers build greenfield facilities. KUKA AG leverages its Stuttgart engineering base to dominate robotic arm integration for German OEM lines. SSI SCHAEFER AG anchors its position through dense service networks across the DACH region. Vanderlande Industries BV competes on baggage-handling expertise translated into parcel sortation dominance at Amsterdam and Leipzig hubs.
Automated material handling encompasses conveyor systems, robotic arms, automated guided vehicles, and automatic storage and retrieval systems that transport, store, and control materials through software-coordinated workflows with throughput rates exceeding manual operations by an order of magnitude. These systems serve industrial and commercial facilities seeking to synchronize inventory velocity with order fulfillment windows measured in hours rather than days. Conveyor systems and robotic arms currently occupy the largest installed base, though automatic storage and retrieval systems generate superior margin pools due to vertical space optimization and software dependency. IoT-enabled predictive maintenance within the technology dimension is displacing reactive service contracts and reshaping vendor-customer relationships toward uptime-guarantee pricing.
The EU Machinery Directive and CE marking requirements enforce functional safety standards on robotic installations, while the EU AI Act imposes risk-classification obligations on autonomous decision-making systems in warehouse environments. The F-Gas Regulation further constrains climate-control equipment within temperature-sensitive pharmaceutical and food-handling installations, directing retrofit budgets toward compliant refrigeration-integrated systems. Stakeholders must weigh the capital intensity of full-stack integrated systems against modular software overlays that preserve hardware flexibility amid evolving compliance thresholds.
Market Dynamics
The EU Green Deal's binding energy-efficiency mandates are forcing warehouse operators across the continent to retrofit legacy conveyor networks with regenerative-drive systems and IoT-enabled power management, compressing payback period calculations and reshaping vendor selection criteria toward full-stack energy guarantees.
Growth Catalysts
- CE marking convergence:Harmonized functional safety standards under the EU Machinery Directive reduce cross-border certification costs for German and Italian system integrators deploying robotic arms in Polish automotive plants.
- Pharmaceutical cold chain:Temperature-sensitive biologics distribution networks in Belgium and the Netherlands require AS/RS installations with integrated F-Gas-compliant climate control, driving specification upgrades.
- Port cluster automation:Rotterdam and Hamburg container terminals are expanding AGV fleets to synchronize intermodal handoffs with barge and rail schedules, creating anchor demand for heavy-load navigation systems.
Market Restraints
- Steel and rare-earth input volatility:Permanent magnet costs for AGV drive motors fluctuate with Chinese export quotas, squeezing margin predictability for mid-tier European integrators.
- Software talent scarcity:PLC programming and warehouse management system integration expertise concentrates in Stuttgart, Munich, and Eindhoven, inflating project timelines for facilities outside these clusters.
- Retrofit compatibility limits:Legacy rack infrastructure in 1980s-era distribution centers cannot support the dynamic load profiles of modern shuttle systems without structural reinforcement.
Strategic Opportunities
- Romanian and Bulgarian greenfield corridors:EU cohesion fund infrastructure investments are attracting automotive suppliers to build automated facilities with native AMH specification rather than retrofit constraints.
- CSRD reporting mandates:Corporate sustainability reporting requirements create demand for AMH vendors offering embedded carbon-footprint tracking and Scope 3 emission attribution tools.
- 5G private networks:Ultra-reliable low-latency connectivity is virtualizing AGV fleet coordination, enabling real-time path optimization that was previously hardware-dependent.
Industry Challenges
- Functional safety certification timelines:The EU AI Act's risk-classification process for autonomous decision-making systems in warehouse environments extends validation cycles by 8-14 months for novel robotic deployments.
- Interoperability fragmentation:Proprietary communication protocols between AS/RS, conveyor, and robotic subsystems force buyers into single-vendor dependencies or expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automated Material Handling (AMH) Market |
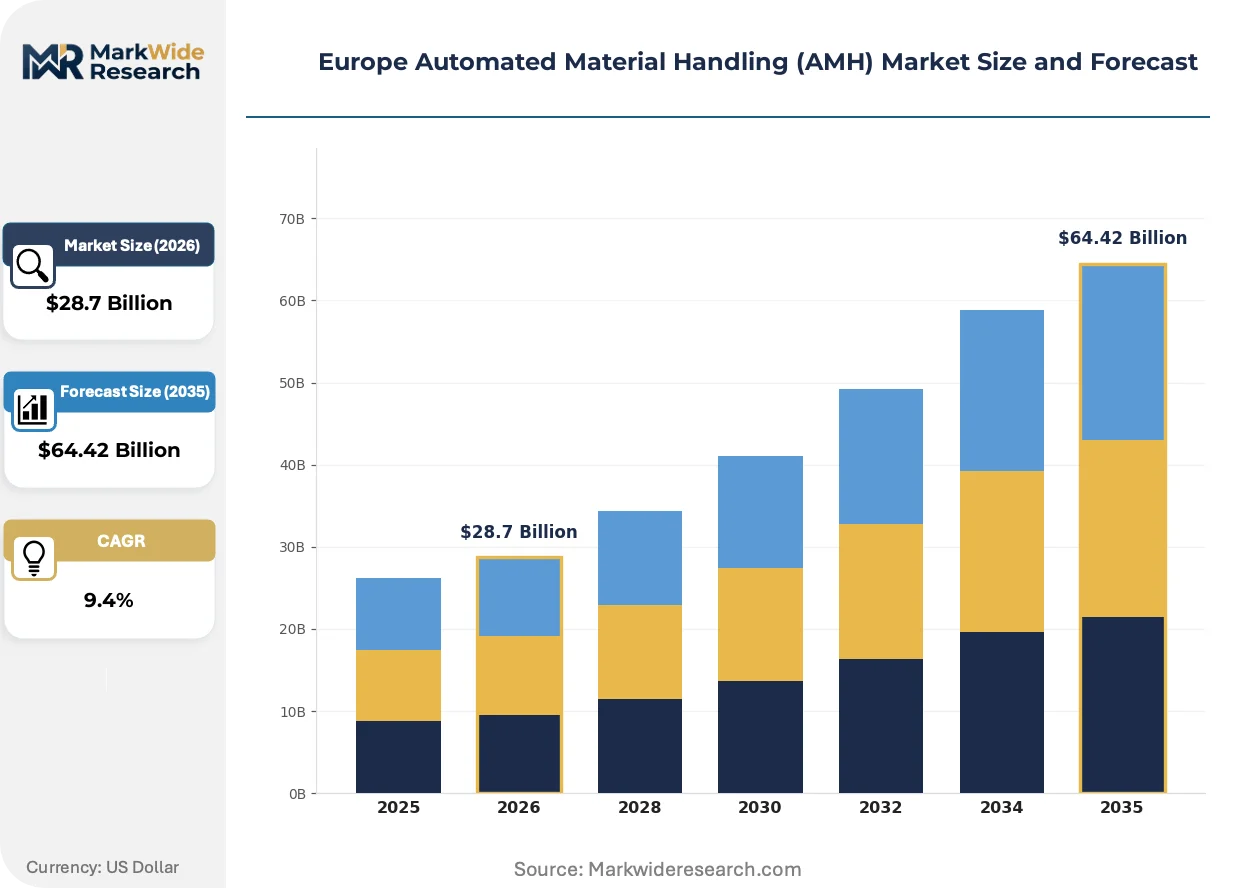
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $64.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Conveyor Systems, Robotic Arms, Automatic Storage and Retrieval Systems Technology: IoT, AI, Machine Learning, Robotics End User: Manufacturing, Warehousing, Retail, Pharmaceuticals Solution: Software, Integrated Systems, Consulting, Maintenance |
| Companies Covered | Viastore Systems GmbH, Murata Machinery Ltd, Vanderlande Industries BV, BEUMER Group, KUKA AG, SSI SCHAEFER AG, Daifuku Co., Ltd., TGW Logistics Group GmbH, Dematic Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automated Material Handling (AMH) Market Trends and Innovations
Digital twin technology is collapsing the boundary between physical asset commissioning and virtual scenario testing, compressing deployment risk and enabling predictive performance guarantees that reshape contract structures.
Digital twin platforms are virtualizing warehouse layout optimization and throughput simulation before steel is cut. German automotive OEMs and Dutch pharmaceutical distributors are adopting these tools to de-risk capital commitments exceeding eight-figure euro thresholds. The technology is virtualizing traditional pilot-phase expenditures into software subscriptions, shifting vendor revenue toward recurring SaaS models.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on autonomous mobile robots making real-time navigation decisions. Industrial facilities in France and Spain face expanded documentation requirements for high-risk AI deployments in shared human-robot zones. Pharmaceutical and food-handling installations are responding by specifying AMH systems with deterministic, rule-based control architectures that fall outside the Act's most stringent tier.
Buyer procurement committees are unbundling hardware acquisition from software licensing and maintenance services, forcing vendors to compete on each layer independently. Third-party system integrators in the DACH region are capturing margin previously retained by original equipment manufacturers through modular software overlays. This pattern is most visible in e-commerce fulfillment, where platform operators prioritize API-accessible control systems over vertically integrated stacks.
Europe Automated Material Handling (AMH) Market Segmentation
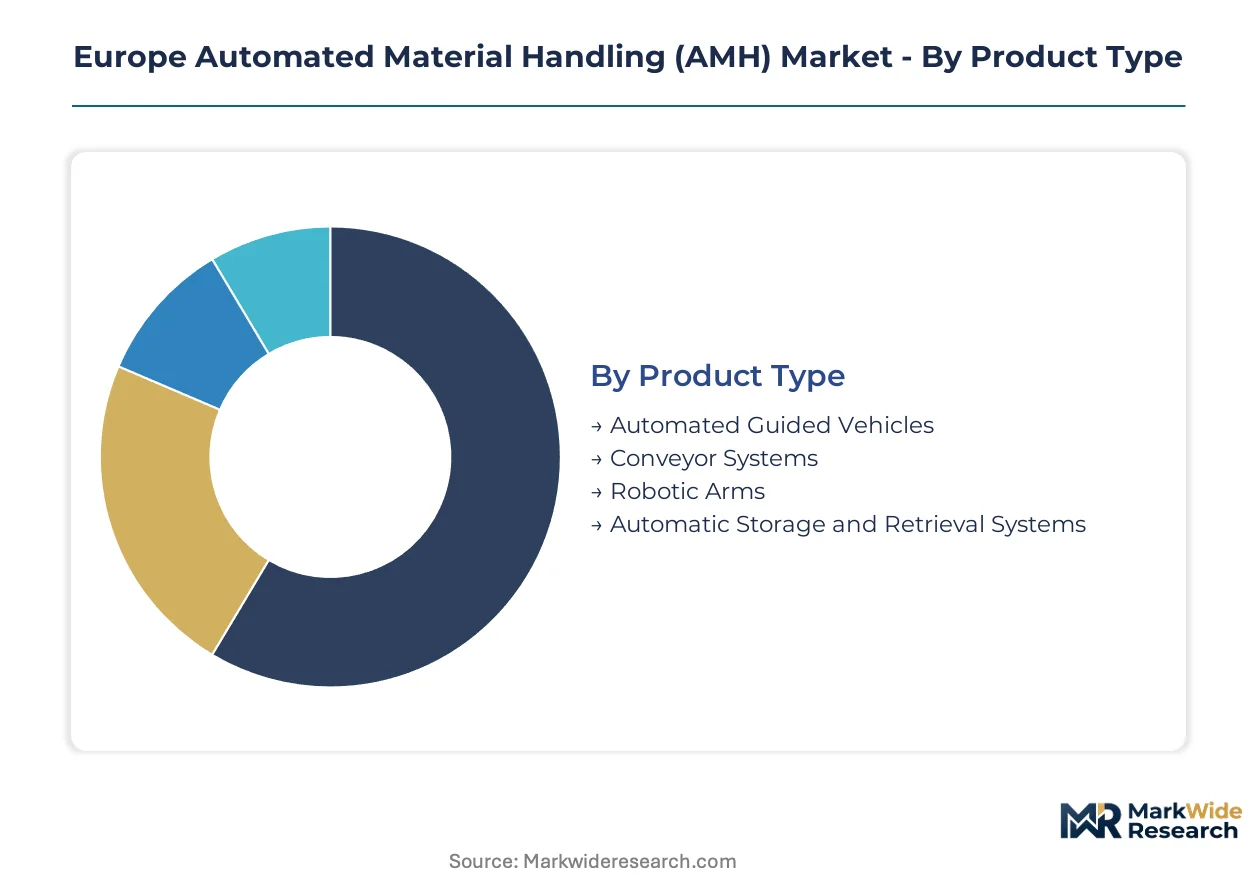
Segmentation reveals how vendor business models diverge across hardware intensity, software dependency, and service attachment rates. Understanding these divides exposes where margin pools concentrate and which configurations face commoditization pressure from modular competitors.
Product Type:
After-sales-service intensity varies dramatically across product categories, with robotic arms and AS/RS demanding specialized technician networks while conveyor systems rely on standardized maintenance protocols.
- Automated Guided Vehicles:Battery-powered mobile platforms navigate via magnetic tape, laser guidance, or vision systems to transport pallets and totes across facility floors. German automotive plants and Dutch port terminals anchor demand as AGV fleets synchronize with just-in-sequence production lines and intermodal handoff schedules. CE marking requirements under the EU Machinery Directive extend validation timelines for navigation safety systems.
- Conveyor Systems:Belt, roller, and chain mechanisms form the backbone of material flow infrastructure, moving goods through sortation, accumulation, and transfer zones. Retrofit demand concentrates in France and Belgium as warehouse operators replace legacy fixed-speed drives with regenerative systems to meet EU Green Deal energy mandates. These installations generate recurring revenue through spare parts and belt replacement programs.
- Robotic Arms:Articulated manipulators perform pick-and-place, palletizing, and assembly operations with repeatability exceeding manual labor. Polish automotive suppliers and Hungarian electronics manufacturers drive specification growth for collaborative variants operating in shared human-robot zones.
- Automatic Storage and Retrieval Systems:Crane-based or shuttle-based vertical storage systems optimize cube utilization through dense racking and precise inventory positioning. Pharmaceutical cold chain facilities in Belgium and the Netherlands require F-Gas-compliant climate integration for temperature-sensitive biologics storage.
Conveyor Systems holds the largest share; momentum sits with Automatic Storage and Retrieval Systems.
Technology:
Technology layers determine pricing power, with AI-enabled systems commanding premium positioning against commodity sensor networks.
- IoT:Sensor networks and connectivity infrastructure enable real-time equipment monitoring, predictive maintenance triggers, and energy consumption tracking. E-commerce fulfillment centers across Germany deploy these systems to convert unplanned downtime into scheduled service windows.
- AI:Autonomous decision-making systems optimize routing, demand forecasting, and dynamic slotting in warehouse management software. The EU AI Act imposes risk-classification obligations on high-risk deployments in shared human-robot environments, extending conformity assessment cycles.
- Machine Learning:Pattern recognition algorithms improve demand prediction accuracy and anomaly detection in throughput optimization. Retail distribution networks in Spain and Italy apply these tools to seasonal demand volatility.
- Robotics:Hardware-software integration spans kinematic control, vision guidance, and force-feedback systems for manipulation tasks. Stuttgart and Munich engineering clusters concentrate development talent for German OEM supply chains.
Robotics captures the dominant revenue position; AI is climbing the fastest as regulatory frameworks mature.
End User:
End-use concentration shapes go-to-market economics, with pharmaceutical and warehousing segments offering contrasting margin profiles.
- Manufacturing:Automotive, electronics, and food processing facilities deploy AMH for work-in-process movement, finished goods handling, and line-side replenishment. Central and Eastern European greenfield corridors in Romania and Bulgaria attract automotive suppliers building native automation specifications.
- Warehousing:Distribution centers and fulfillment hubs prioritize throughput velocity, order accuracy, and labor cost reduction. Rotterdam and Hamburg port clusters drive heavy-load AGV demand for container terminal operations.
- Retail:Omnichannel fulfillment operations require flexible systems handling store replenishment, e-commerce orders, and returns processing. French and Dutch retailers concentrate investment near port infrastructure for import efficiency.
- Pharmaceuticals:Temperature-controlled distribution networks for biologics and vaccines demand validated systems with audit trails and contamination controls. Belgian and Dutch cold chain hubs specify AS/RS with integrated climate management meeting F-Gas Regulation requirements.
Warehousing holds the largest share; momentum sits with Pharmaceuticals as serialization and cold chain requirements intensify.
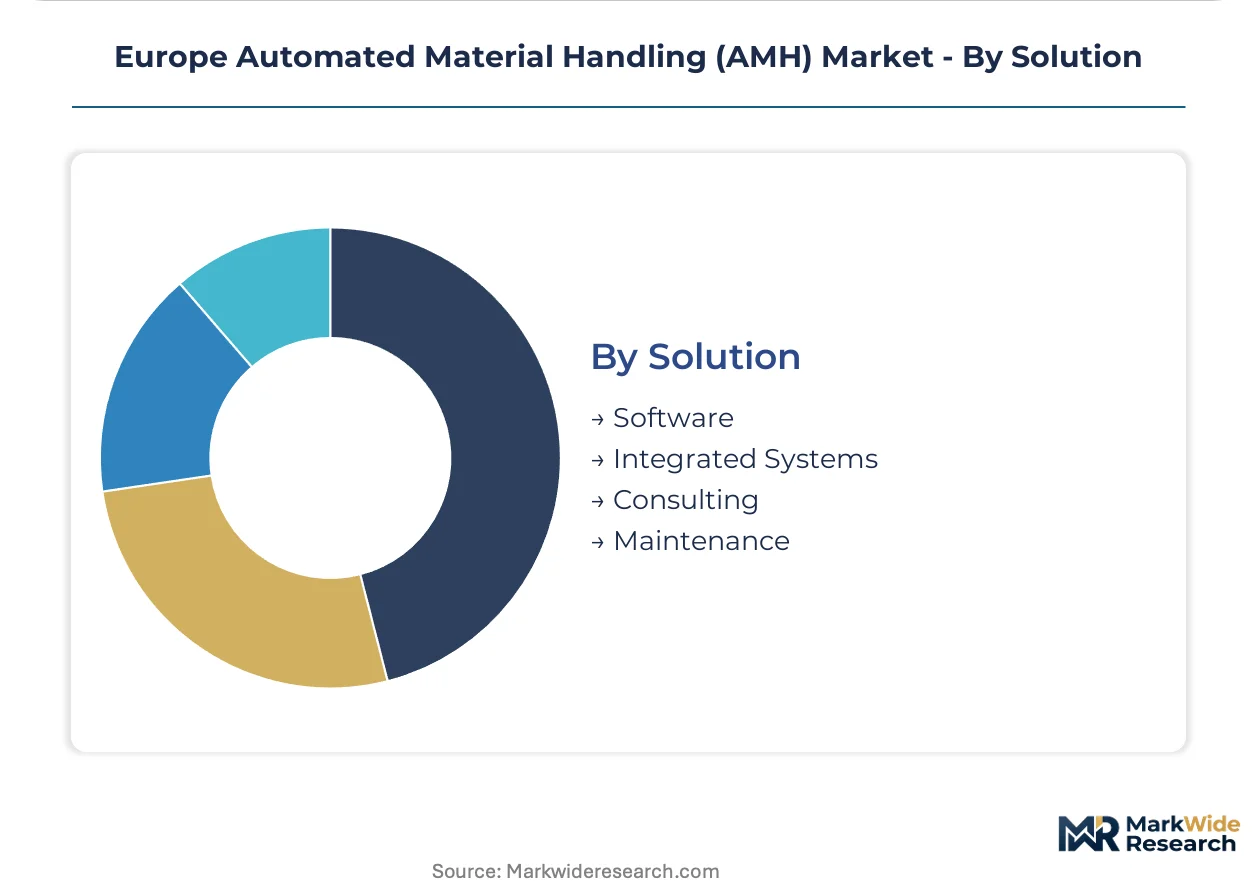
Solution:
Solution architecture determines customer lock-in duration, with integrated systems capturing long-term relationships against transactional software licenses.
- Software:Warehouse management systems, warehouse control systems, and fleet management platforms coordinate hardware subsystems through centralized optimization engines. API-accessible architectures gain preference among e-commerce operators seeking modular integration.
- Integrated Systems:Turnkey hardware-software combinations deliver specified throughput guarantees with single-vendor accountability. German automotive OEMs favor these arrangements for production-critical applications.
- Consulting:Layout optimization, process engineering, and automation roadmap services precede capital deployment decisions. Digital twin virtualization compresses pilot-phase expenditures for Dutch pharmaceutical distributors.
- Maintenance:Preventive service contracts, spare parts programs, and remote monitoring subscriptions generate recurring revenue streams. IoT-enabled predictive maintenance is displacing reactive service agreements across the DACH region.
Integrated Systems holds the largest share; momentum sits with Software as procurement committees unbundle hardware from control layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CE marking under the EU Machinery Directive anchors German market leadership, while Rotterdam and Hamburg port clusters drive heavy-load automation demand. Energy-efficiency mandates from the EU Green Deal compress payback calculations for retrofit investments across the continent. The analysis spans five national markets where automation intensity varies by industrial base and regulatory enforcement.
Germany
Automotive OEMs in Stuttgart and Munich demand just-in-sequence robotic integration for production lines. The EU AI Act imposes risk-classification obligations on autonomous mobile robots in shared human-robot zones, extending validation timelines. KUKA AG leverages its Stuttgart engineering base to dominate robotic arm deployments for German manufacturers.
Netherlands
Rotterdam container terminals expand AGV fleets to synchronize intermodal handoffs with barge schedules. The F-Gas Regulation constrains climate-control equipment in pharmaceutical cold chain facilities, directing AS/RS specification upgrades. Vanderlande Industries BV competes on baggage-handling expertise translated into parcel sortation dominance at Amsterdam hubs.
France
Omnichannel retailers concentrate investment in automated warehousing near Le Havre and Marseille port clusters for import efficiency. CSRD reporting mandates create demand for AMH vendors offering embedded carbon-footprint tracking tools. French pharmaceutical distributors specify deterministic control architectures to avoid the EU AI Act's most stringent tier.
Belgium
Temperature-sensitive biologics distribution networks in Antwerp require AS/RS installations with integrated F-Gas-compliant climate control. The EU Green Deal's binding energy-efficiency mandates force warehouse operators to retrofit legacy conveyor networks with regenerative-drive systems. Belgian cold chain hubs drive specification growth for validated systems with audit trails.
Poland
Automotive suppliers in Silesia and Greater Poland build greenfield facilities with native AMH specification rather than retrofit constraints. Harmonized functional safety standards under the EU Machinery Directive reduce cross-border certification costs for German and Italian system integrators deploying robotic arms. Polish electronics manufacturers drive collaborative robot specification for shared human-robot zones.
Europe Automated Material Handling (AMH) Market Competitive Landscape
Full-stack integrators and modular software specialists split the market along the hardware-software boundary. German and Dutch engineering clusters concentrate development talent, creating geographic moats around Stuttgart, Munich, and Eindhoven. Three archetypes dominate: vertically integrated turnkey providers, component specialists with dense service networks, and software-native challengers unbundling control layers. Competitive moves center on API-accessible architecture development and predictive maintenance service contracts that displace reactive agreements.
Within the vertically integrated tier, KUKA AG and SSI SCHAEFER AG exemplify divergent geographic anchoring strategies. KUKA AG occupies a position tied to Stuttgart's automotive engineering density, while SSI SCHAEFER AG anchors its market presence through service network coverage across the DACH region. Among Dutch specialists, Vanderlande Industries BV represents the translation of domain expertise from adjacent verticals into parcel automation dominance.
| Leading Market Players |
|---|
| Viastore Systems GmbH |
| Murata Machinery Ltd |
| Vanderlande Industries BV |
| BEUMER Group |
| KUKA AG |
| SSI SCHAEFER AG |
| Daifuku Co., Ltd. |
| TGW Logistics Group GmbH |
| Dematic Corporation |
| Others |
Pricing and Supply Chain Analysis
Rare-earth export quota volatility from Chinese suppliers compresses margin predictability for AGV motor manufacturers and simultaneously widens pricing spreads between premium European-integrated systems and economy-tier Asian imports. This input cost instability forces buyers to weight total-cost-of-ownership calculations more heavily toward energy-efficiency guarantees and predictive maintenance bundles that stabilize lifecycle expenditure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Stuttgart-engineered robotic integrations from mid-tier DACH service-network offerings and Eastern European commodity hardware. Price differentiation hinges on CE marking complexity and after-sales technician density, with German automotive OEMs least sensitive due to production-line downtime costs while Bulgarian greenfield entrants negotiate aggressively on upfront capital. Cost compression in the economy tier is intensifying because Romanian and Polish facilities prioritize native AMH specification over retrofit premiums.
Supply Chain Analysis
EU dual-use export controls on high-precision servo motors and AI-enabled navigation chipsets limit technology flows from German and Dutch engineering clusters toward non-EU assembly operations. Component sourcing draws from Chinese rare-earth processing, South Korean battery cell manufacturing, and Italian steel rack fabrication, creating single-source vulnerability in permanent magnet supply. Distribution runs through SSI SCHAEFER AG and KUKA AG service networks across the DACH region, with third-party system integrators capturing margin through modular software overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement committee unbundling of hardware from software layers fragments vendor lock-in and creates niche entry points for API-native challengers across e-commerce fulfillment and pharmaceutical cold chain verticals.
For Market Incumbents: Build dense service technician networks as the primary moat against modular software competitors. Capture recurring revenue through IoT-enabled predictive maintenance contracts that displace reactive service agreements in the DACH region. Deepen backward integration into regenerative drive systems to meet EU Green Deal energy mandates before retrofit demand peaks. For New Entrants and Emerging Players: Pursue Bulgarian and Romanian greenfield corridors where native AMH specification eliminates retrofit compatibility constraints. Target pharmaceutical cold chain facilities in Belgium and the Netherlands with F-Gas-compliant climate-integrated AS/RS offerings. Lead with API-accessible control architectures that appeal to unbundling procurement committees in French omnichannel retail. For Investors and Strategic Acquirers: EU AI Act risk-classification timelines reshape the acquisition landscape toward deterministic control architecture specialists that sidestep high-risk conformity assessments. Five-to-ten-year viability favors software-native challengers with embedded carbon-footprint tracking tools for CSRD reporting mandates. Watch for validation cycle compression signals as digital twin virtualization de-risks capital commitments exceeding eight-figure euro thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Control Architecture Development | Unbundles hardware from software layers for e-commerce procurement committees seeking modular integration flexibility. |
| Predictive Maintenance Service Contract Expansion | Converts reactive service agreements into uptime-guarantee pricing with IoT-enabled remote monitoring subscriptions. |
| Regenerative Drive System Integration | Compresses EU Green Deal compliance payback periods for French and Belgian warehouse retrofit investments. |
| Digital Twin Platform Commercialization | Virtualizes pilot-phase expenditures into recurring SaaS revenue for Dutch pharmaceutical distributors. |
| CE Marking Convergence Investment | Reduces cross-border certification costs for German integrators deploying robotic arms in Polish automotive plants. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with warehouse operations directors, AMH procurement leads at automotive OEMs, system integration engineers, and aftermarket service heads; and secondary validation against EU Machinery Directive filings, F-Gas Regulation compliance databases, SEC disclosures from listed automation vendors, and customs records for AGV and robotic arm trade flows. Bottom-up installation base modeling triangulated against top-down market sizing from capital expenditure tracking across German, Dutch, and French port clusters.
Forecast inputs span product type intensity, technology layer penetration, end-use vertical concentration, and solution architecture preference across the projection horizon. Segmentation dimensions modeled include hardware category, software dependency tier, regulatory compliance cluster, and geographic adoption pattern. CAGRs derive from scenario-weighted capacity expansion timelines, retrofit cycle compression rates, and greenfield facility commissioning schedules anchored in EU cohesion fund infrastructure disbursements.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial production indices, Chinese rare-earth export quota enforcement, and EU AI Act implementation timelines would shift the trajectory. Forecasts reflect documented assumptions on energy-efficiency mandate stringency and 5G private network deployment pace. Material shifts in CE marking mutual recognition agreements or F-Gas Regulation amendment schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Vertical Lifts Market
Material Handling Equipment
Industrial Jacks Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Pipe Clamp Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Vibrating Screen Market