
 Engineering Services Outsourcing Market | 2026-2036
Engineering Services Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Engineering Services Outsourcing Market Analysis
Aftermarket service revenue is rewriting how engineering service providers capture lifetime value from product ecosystems. Tata Consultancy Services Limited leverages its global delivery footprint to anchor multi-year automotive embedded systems contracts. HCL Technologies Limited competes through deep vertical specialization in aerospace avionics testing and certification support. Alten Group sustains premium positioning across European industrial clients by maintaining dense engineer populations near OEM engineering centers.
Engineering services outsourcing encompasses the contracted provision of technical design, analysis, testing, and product lifecycle support performed by external specialists using CAD, CAE, and digital twin platforms with defined SLA structures and IP governance frameworks. The practice enables manufacturers to access specialized talent pools without fixed R&D infrastructure commitments. Design Services occupies the largest value pool as product complexity rises across electrified automotive platforms and next-generation aerostructures. Testing Services registers the fastest structural expansion as regulatory certification cycles lengthen and simulation-based verification displaces physical prototyping. The Hybrid delivery model captures disproportionate growth as clients demand timezone-overlapping collaboration combined with cost-optimized offshore execution.
FDA medical device design controls, EU AI Act conformity requirements for autonomous systems, and India's BIS product safety certifications collectively elevate compliance rigor in outsourced engineering engagements. EMA medical technology standards and REACH substance restrictions further shape material selection protocols and biocompatibility documentation demands. Stakeholders must monitor how regulatory fragmentation across jurisdictions affects contract structuring, liability allocation, and the geographic siting of specialized engineering centers.
Market Dynamics
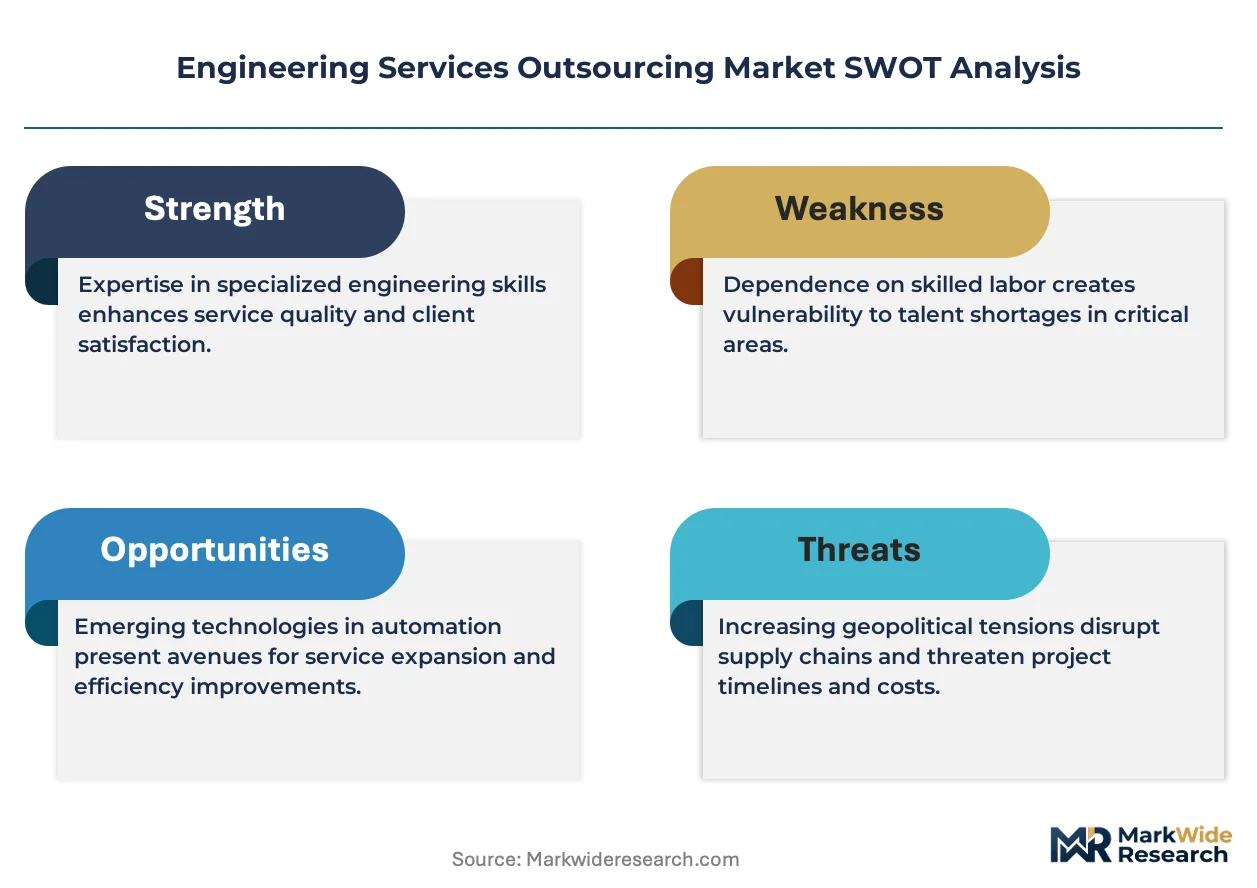
Cloud-native simulation platforms are compressing physical prototyping cycles and redistributing engineering talent toward software-centric skill clusters. This structural shift concentrates high-value design work near OEM engineering centers while pushing execution to cost-optimized delivery locations.
Growth Catalysts
- India's PLI-linked localization mandates:Automotive OEMs now contract embedded systems design to domestic engineering partners under production-linked incentive schemes requiring indigenous R&D footprints.
- EU AI Act conformity requirements:Autonomous system developers must document algorithmic decision pathways, expanding demand for external verification and certification engineering services.
- Digital twin adoption:Industrial manufacturers deploy virtual commissioning environments to compress product validation timelines and reduce physical test facility capital requirements.
Market Restraints
- Specialized talent scarcity:Electrified automotive platforms require power electronics expertise that concentrates in Germany's industrial corridor around Munich and Stuttgart, creating recruitment bottlenecks.
- IP governance complexity:Cross-border engineering engagements trigger jurisdictional disputes over foreground and background intellectual property ownership, particularly in aerospace avionics development.
- Regulatory fragmentation:FDA medical device design controls, EU MDR conformity assessment routes, and India's BIS certification requirements impose non-harmonized documentation standards that inflate compliance overhead.
Strategic Opportunities
- Aftermarket service unbundling:Product ecosystem lifetime value capture is shifting toward predictive maintenance engineering and remote diagnostic platform development.
- Hybrid delivery model expansion:Clients demand timezone-overlapping collaboration hubs in Poland and Romania combined with offshore execution centers in India and Vietnam.
- REACH substance restriction compliance:Material selection protocols and biocompatibility documentation for medical technology and industrial equipment create specialized engineering service demand.
Industry Challenges
- Simulation-to-physical correlation gaps:CAE-based verification requires calibration against physical test data that remains scarce for novel materials and manufacturing processes.
- Multi-jurisdictional liability allocation:Contract structures must specify responsibility distribution when design defects surface across FDA, EMA, and BIS regulatory domains simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineering Services Outsourcing Market |
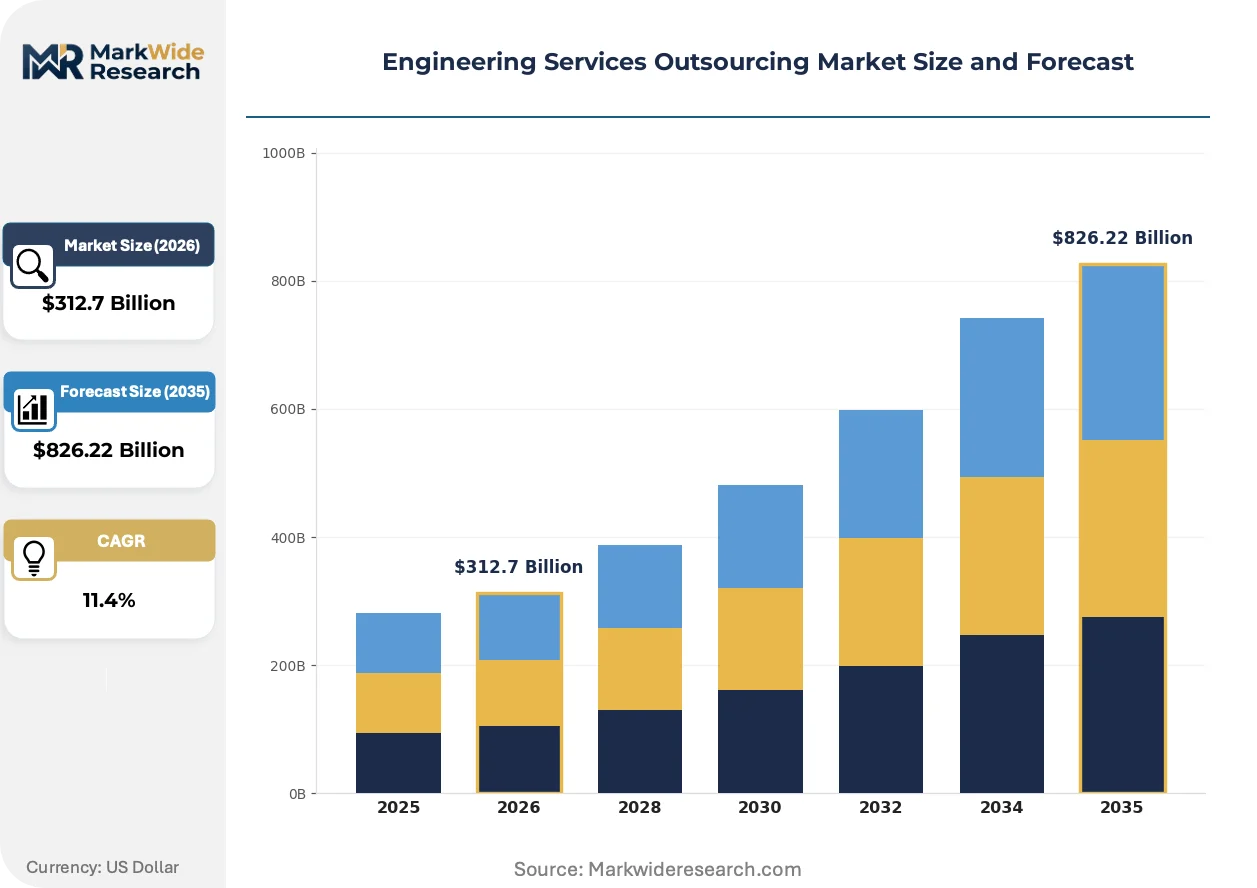
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $826.22 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design Services, Testing Services, Quality Assurance, Prototyping Services Industry Vertical: Aerospace, Automotive, Electronics, Construction Delivery Model: Onshore, Offshore, Hybrid, Dedicated Center Client Type: Startups, SMEs, Large Enterprises, Government Agencies |
| Companies Covered | Tata Consultancy Services Limited, HCL Technologies Limited, Infosys Limited, Wipro Limited, Capgemini Engineering, Alten Group, Tech Mahindra Limited, Akkodis, Tata Elxsi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineering Services Outsourcing Market Emerging Trajectories
Generative design algorithms and physics-informed machine learning are restructuring how engineering teams allocate effort between creative synthesis and validation discipline. These capabilities compress iteration cycles while elevating the premium on domain expertise that can constrain and interpret automated outputs.
Generative topology optimization software is digitizing structural design workflows for aerostructure and powertrain components. Tier-1 automotive suppliers deploy these tools to explore non-intuitive load path geometries that conventional CAD approaches cannot conceive. The technology is digitizing the front-end of product development, compressing concept-to-detailed-design timelines by eliminating manual iteration loops.
The EU AI Act's risk-based classification system for autonomous functions is mandating human-in-the-loop verification protocols and algorithmic audit trails. Medical device manufacturers must now document training data provenance and model performance drift monitoring. Aerospace developers in Germany and France face the steepest compliance ramps as existing certification frameworks lack precedents for machine learning-enabled flight control systems.
Outcome-based engineering contracts are displacing time-and-materials arrangements in industrial equipment sectors. Buyers now specify functional performance guarantees rather than deliverable checklists, transferring outcome risk to service providers. This shift concentrates most visibly in German manufacturing automation and US energy infrastructure verticals, where asset uptime metrics dominate vendor selection criteria.
Engineering Services Outsourcing Market Segmentation
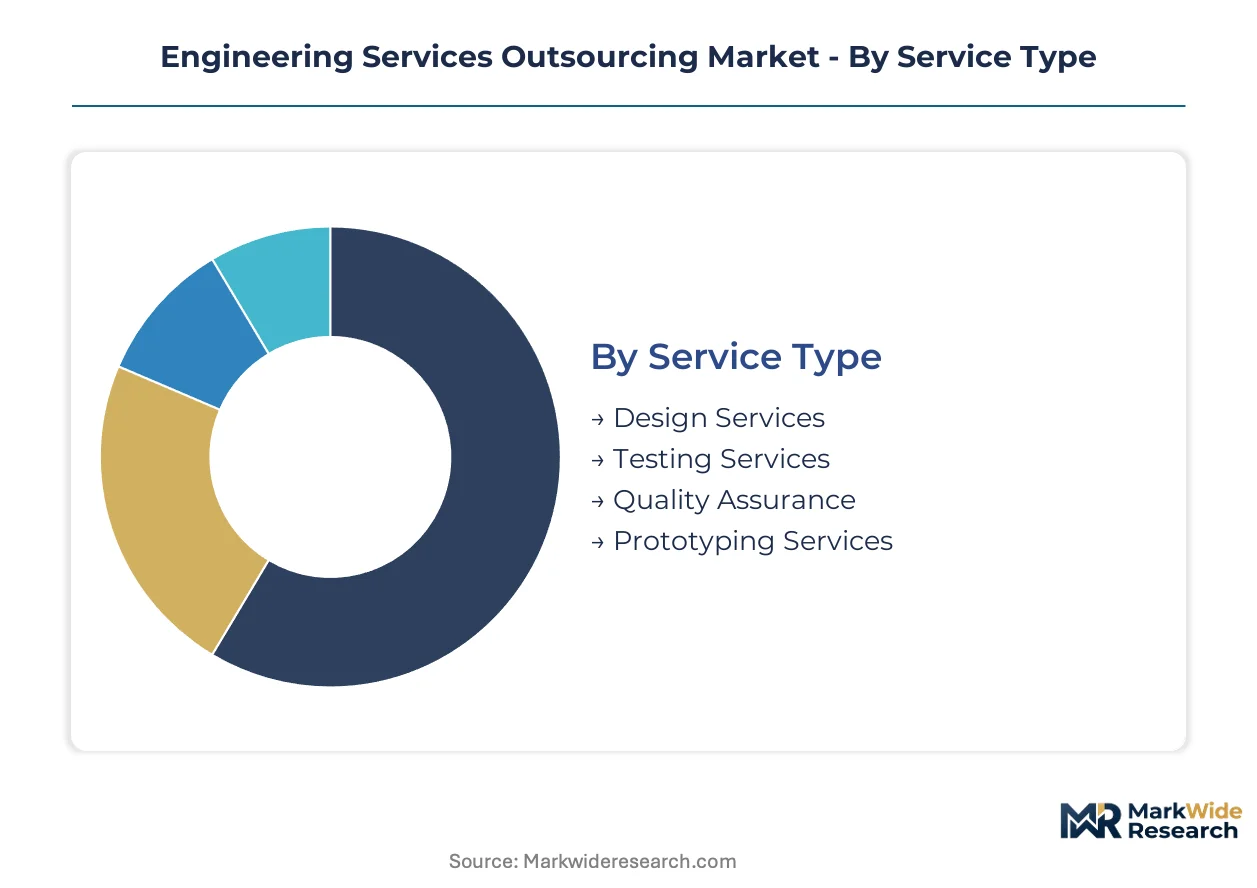
Engineering services outsourcing fragments across four structural dimensions that determine contract economics, talent deployment, and regulatory exposure. Service type and delivery model dictate margin profiles, while industry vertical and client type shape risk tolerance and engagement complexity.
Service Type:
Technical sophistication spans concept-stage creativity through validation discipline, with each service tier commanding distinct pricing and IP frameworks.
- Design Services:CAD-driven concept development and detailed engineering for electrified automotive platforms and next-generation aerostructures. German OEMs concentrate demand around Munich and Stuttgart for power electronics architecture, constrained by scarce embedded systems talent pools.
- Testing Services:Simulation-based verification and physical validation cycles that displace prototype-heavy development. India's BIS certification requirements and EU AI Act conformity mandates lengthen regulatory verification timelines, expanding external testing demand fastest.
- Quality Assurance:Process auditing and compliance documentation for FDA medical device design controls and EMA medical technology standards.
- Prototyping Services:Rapid physical model generation bridging digital twin environments and manufacturing readiness.
The dominant share belongs to Design Services, while Testing Services is closing the gap fastest.
Industry Vertical:
End-use concentration varies sharply by regulatory intensity and product lifecycle duration.
- Automotive:Electrified platform development and autonomous system engineering under India's PLI-linked localization mandates. Pune and Bengaluru engineering centers capture embedded systems outsourcing as domestic R&D footprints become mandatory.
- Aerospace:Avionics certification support and aerostructure analysis governed by FAA and EASA airworthiness protocols. German and French developers face steepest compliance ramps for machine learning-enabled flight control systems.
- Electronics:Semiconductor packaging design and thermal management for industrial automation and consumer devices.
- Construction:Structural engineering and building information modeling for infrastructure and commercial development.
Automotive verticals generate the highest contract volumes, though Aerospace commands premium pricing through certification complexity.
Delivery Model:
Geographic deployment strategy determines cost structure, collaboration bandwidth, and timezone coverage.
- Onshore:Proximity-based execution near OEM engineering centers for sensitive IP and rapid iteration cycles. Germany's industrial software corridor concentrates high-value design work requiring physical presence.
- Offshore:Cost-optimized delivery from India and Vietnam for standardized engineering tasks with defined specifications.
- Hybrid:Timezone-overlapping hubs in Poland and Romania paired with offshore execution centers. This model captures disproportionate growth as clients demand synchronous collaboration without premium onshore pricing.
- Dedicated Center:Captive engineering facilities built for single-client exclusivity with embedded governance frameworks.
Hybrid deployment is expanding most quickly, while Dedicated Centers retain share among aerospace and defense contractors with classified program requirements.
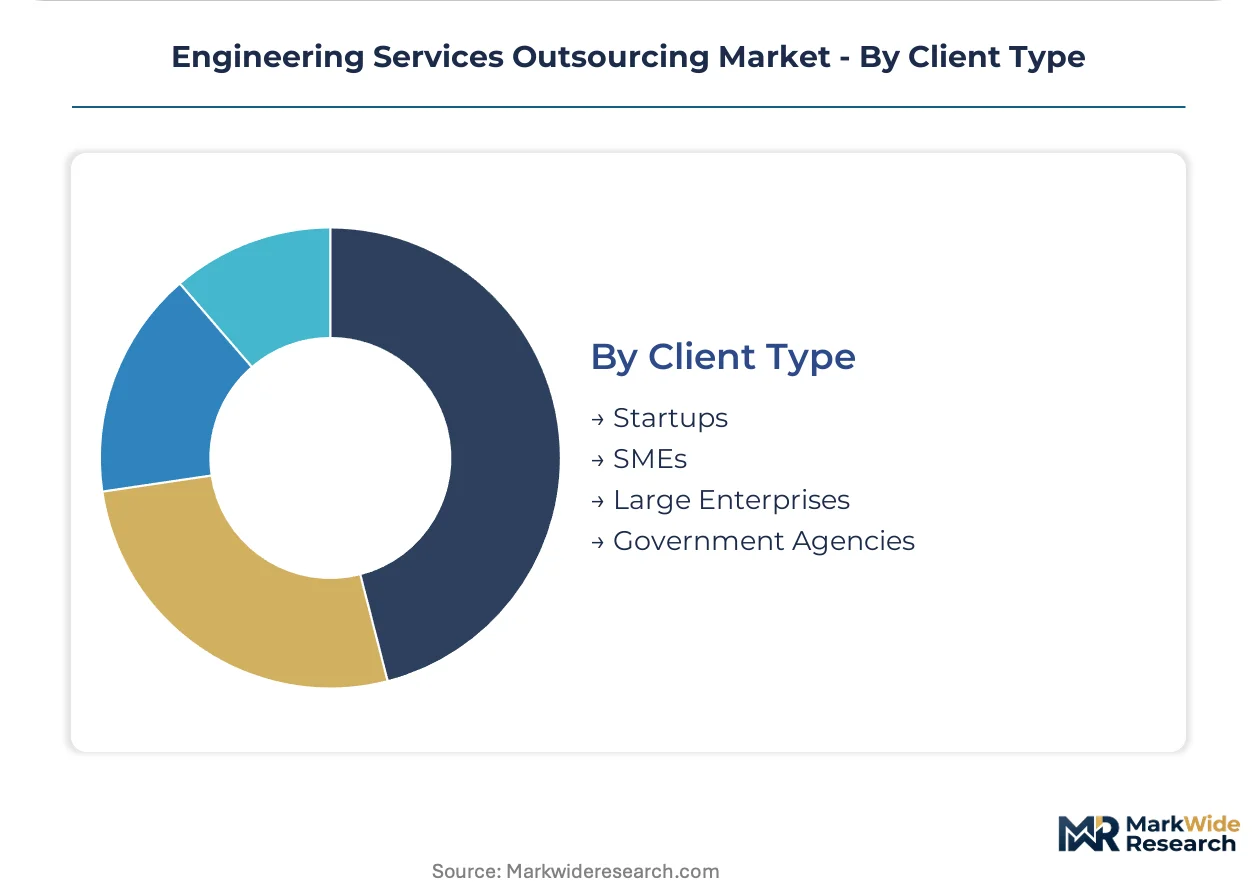
Client Type:
Organizational scale dictates contract structure, from outcome-based performance guarantees to milestone-driven deliverables.
- Startups:Equity-constrained ventures accessing specialized talent without fixed R&D infrastructure commitments. These clients favor time-and-materials flexibility over long-term engagements.
- SMEs:Mid-tier manufacturers unbundling predictive maintenance engineering and remote diagnostic platform development to capture aftermarket lifetime value.
- Large Enterprises:Multi-year automotive embedded systems contracts with global delivery footprints and defined SLA structures. Tata Consultancy Services and HCL Technologies anchor these relationships through vertical specialization.
- Government Agencies:Defense and infrastructure projects with stringent security clearance and domestic content requirements.
Large Enterprises dominate absolute spending, though Startups represent the steepest expansion trajectory as venture-backed hardware ventures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools concentrate in India and Germany, creating distinct supply nodes for embedded systems and industrial software respectively. India's PLI-linked localization mandates redirect automotive R&D spending toward domestic engineering partners. Germany's industrial corridor around Munich and Stuttgart retains high-value design work requiring physical OEM proximity.
United States
FDA medical device design controls and FAA airworthiness protocols drive specialized compliance engineering demand. NHTSA autonomous vehicle guidelines expand external verification services for algorithmic safety systems. Detroit and Austin engineering centers capture electrified powertrain development as domestic OEMs reshore critical R&D functions.
Germany
KBA certification requirements and EU AI Act conformity mandates lengthen regulatory verification cycles for autonomous systems. REACH substance restrictions shape material selection protocols across industrial equipment sectors. Munich and Stuttgart anchor cloud-native simulation platform development, concentrating scarce power electronics expertise near OEM engineering headquarters.
India
PLI scheme localization mandates require automotive OEMs to maintain indigenous R&D footprints for embedded systems design. BIS product safety certifications elevate documentation standards for medical technology and industrial automation exports. Pune and Bengaluru engineering centers absorb multi-year automotive contracts as global delivery footprints expand under government incentive structures.
France
EASA airworthiness protocols and EU AI Act risk-based classification systems impose steep compliance ramps for machine learning-enabled flight control systems. ANSM medical technology standards govern biocompatibility documentation for device manufacturers. Paris and Toulouse aerospace clusters sustain premium engineering service demand through certification complexity and defense program requirements.
Japan
METI industrial digitization initiatives accelerate digital twin adoption across automotive and electronics manufacturing. PMDA medical device standards require rigorous design control documentation for export-oriented manufacturers. Tokyo and Nagoya engineering centers concentrate robotics and industrial automation expertise as domestic OEMs unbundle predictive maintenance platform development.
Engineering Services Outsourcing Market Vendor Landscape
Global systems integrators and European specialist firms split the market between scale-driven delivery footprints and proximity-based premium positioning. Tier-1 IT services conglomerates anchor multi-year automotive and aerospace contracts through vertical specialization. Boutique engineering consultancies compete on domain depth in regulated sectors. Dominant competitive moves include hybrid delivery model expansion and outcome-based contract structuring that transfers performance risk to service providers.
Within the global systems integrator tier, Tata Consultancy Services Limited and HCL Technologies Limited exemplify scale-driven positioning through multi-year automotive embedded systems engagements. Alten Group occupies a specialist position among European industrial clients, sustaining premium pricing through engineer density near OEM engineering centers. These three entities represent contrasting archetypes: the India-anchored global delivery model, the vertically specialized certification support provider, and the proximity-focused European engineering partner.
| Leading Market Players |
|---|
| Tata Consultancy Services Limited |
| HCL Technologies Limited |
| Infosys Limited |
| Wipro Limited |
| Capgemini Engineering |
| Alten Group |
| Tech Mahindra Limited |
| Akkodis |
| Tata Elxsi |
| Others |
Supply Flow & Price Mechanics
Pune and Bengaluru engineering clusters anchor capacity expansion for automotive embedded systems under India's PLI-linked localization mandates, concentrating pricing power among domestic partners with indigenous R&D footprints as OEMs face mandatory domestic content thresholds.
Pricing Analysis
Aftermarket service revenue tiers spanning predictive maintenance engineering and remote diagnostic platform development now drive lifetime value capture beyond initial project delivery. Three-tier pricing structure across premium, standard, and economy levels separates Tier 1 automotive suppliers requiring ISO 26262 functional safety certification from mid-tier industrial equipment clients and commodity prototyping services. Pricing pressure stems from outcome-based contract structures transferring performance risk to service providers, with German automotive OEMs least price-sensitive due to regulatory verification complexity while startup hardware ventures exhibit acute sensitivity to upfront engineering costs.
Supply Chain Analysis
Upstream feedstock for engineering talent draws from India's technical universities, Germany's applied research institutes, and Poland's emerging timezone-overlapping hubs for hybrid delivery models. Specialized skill dependencies rest on power electronics expertise concentrated around Munich and Stuttgart, embedded systems architects in Pune and Bengaluru, and simulation platform engineers across Romania's technical centers. Single-source vulnerability characterizes scarce certification-capable talent pools for EU AI Act conformity documentation. Distribution runs through multi-year automotive contracts with defined SLA structures and IP governance frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering services outsourcing functions as a defensive-moat market where regulatory entrenchment creates sticky multi-year relationships, as OEMs face prohibitive switching costs when migrating embedded systems design between partners under PLI-linked localization mandates.
For Market Incumbents: Insulate core automotive embedded systems relationships through captive certification investment in EU AI Act conformity documentation and BIS product safety accreditation. Vertical integration into cloud-native simulation platform development counters margin compression from outcome-based contract structures. Expand engineer density near Stuttgart and Munich OEM headquarters to defend premium positioning against offshore challengers.
For New Entrants and Emerging Players: Establish a beachhead in predictive maintenance engineering and remote diagnostic platform development for SME industrial equipment manufacturers unbundling aftermarket service revenue. Poland and Romania present the most penetrable geography for hybrid delivery model hubs with timezone overlap to Western European clients. Target equity-constrained hardware startups through flexible time-and-materials arrangements absent long-term infrastructure commitments.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized engineering service divisions lacking vertical specialization in aerospace avionics certification or medical device design controls. Long-term viability favors providers with embedded regulatory relationships spanning FDA, EMA, and BIS domains. Watch for inflection when outcome-based contract penetration crosses threshold levels in German manufacturing automation.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Delivery Model Expansion | Timezone-overlapping hubs in Poland and Romania paired with offshore execution capture disproportionate growth. |
| Certification Investment in EU AI Act | Algorithmic audit trail capabilities open autonomous system verification contracts with German automotive OEMs. |
| Outcome-Based Contract Structuring | Functional performance guarantees displace time-and-materials arrangements in industrial equipment sectors. |
| Vertical Integration into Simulation Platforms | Cloud-native CAE development compresses physical prototyping cycles for Tier 1 aerostructure suppliers. |
| Aftermarket Service Unbundling | Predictive maintenance engineering captures lifetime value from product ecosystems beyond initial delivery. |
Methodological Framework
Cross-validation between primary interviews with embedded systems architects, automotive platform engineers, regulatory compliance officers, and aftermarket service directors and secondary validation through SEC filings, EU AI Act implementation guidance, BIS certification databases, and PLI scheme disbursement records anchors the qualitative findings. Bottom-up triangulation across service type, delivery model, and industry vertical segmentation combines with top-down macroeconomic calibration across the analysis window.
Calibration against historical contract value trajectories and disclosed automotive R&D localization commitments shapes the analytical framework. Segmentation dimensions modeled include service type sophistication, delivery model geography, industry vertical regulatory intensity, and client scale archetype. CAGRs derive from disclosed multi-year automotive embedded systems engagements and simulation platform adoption curves.
Stress conditions across talent pool scarcity, regulatory verification timeline extension, and outcome-based contract risk transfer were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PLI scheme continuity and EU AI Act enforcement pacing. Material shifts in India's localization mandate structure or REACH substance restriction scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Engineering Design Service Market
Engineering Services
NDT Inspection Services Market
Engineering Services
Geophysical Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Directional Drilling Services Market
Engineering Services
Geosteering Services Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
MEP Services Market
Engineering Services
North America Engineering Research and Development (ER&D) Services Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Construction Engineering Services Outsourcing Market
Engineering Services
Architectural Services Market
Engineering Services
Seismic Services Market