
 NDT Inspection Services Market | 2026-2036
NDT Inspection Services Market Size, Share, and Industry Trends Forecast 2026-2036
NDT Inspection Services Market Outlook
Software-defined inspection analytics is decoupling hardware ownership from service value in the NDT sector. Applus+ leverages its global laboratory network to sustain long-term aerospace contracts across multiple continents. MISTRAS Group anchors its position through specialized refinery and pipeline integrity programs in North American energy corridors. SGS SA differentiates by controlling certification workflows that bridge European regulatory requirements with Asian manufacturing supply chains.
Non-destructive testing inspection services encompass methods that evaluate material properties, component integrity, and structural conditions without impairing future usefulness, employing techniques that detect surface and subsurface discontinuities through acoustic, electromagnetic, or radiographic energy propagation. These services primarily assure safety compliance, prevent catastrophic failures, and extend operational lifecycles across capital-intensive industries. Ultrasonic testing commands the largest service revenue pool due to its versatility across weld inspection and thickness measurement applications, while phased array technology is displacing conventional methods in complex geometry assessments. Pipeline integrity applications generate concentrated demand from oil and gas operators facing regulatory renewal deadlines, and structural health monitoring is expanding fastest in aging civil infrastructure portfolios.
The American Society of Mechanical Engineers Boiler and Pressure Vessel Code shapes North American demand by mandating periodic inspection intervals for pressure-retaining equipment. The EU's MDR and CE marking requirements force medical device manufacturers to document validated NDT protocols within quality management systems. Germany's KBA enforces rail and automotive component testing standards that cascade through European supplier tiers. Stakeholders must decide whether to build captive inspection capabilities or deepen reliance on third-party specialists as regulatory scope broadens into renewable energy installations and hydrogen infrastructure.
Market Dynamics
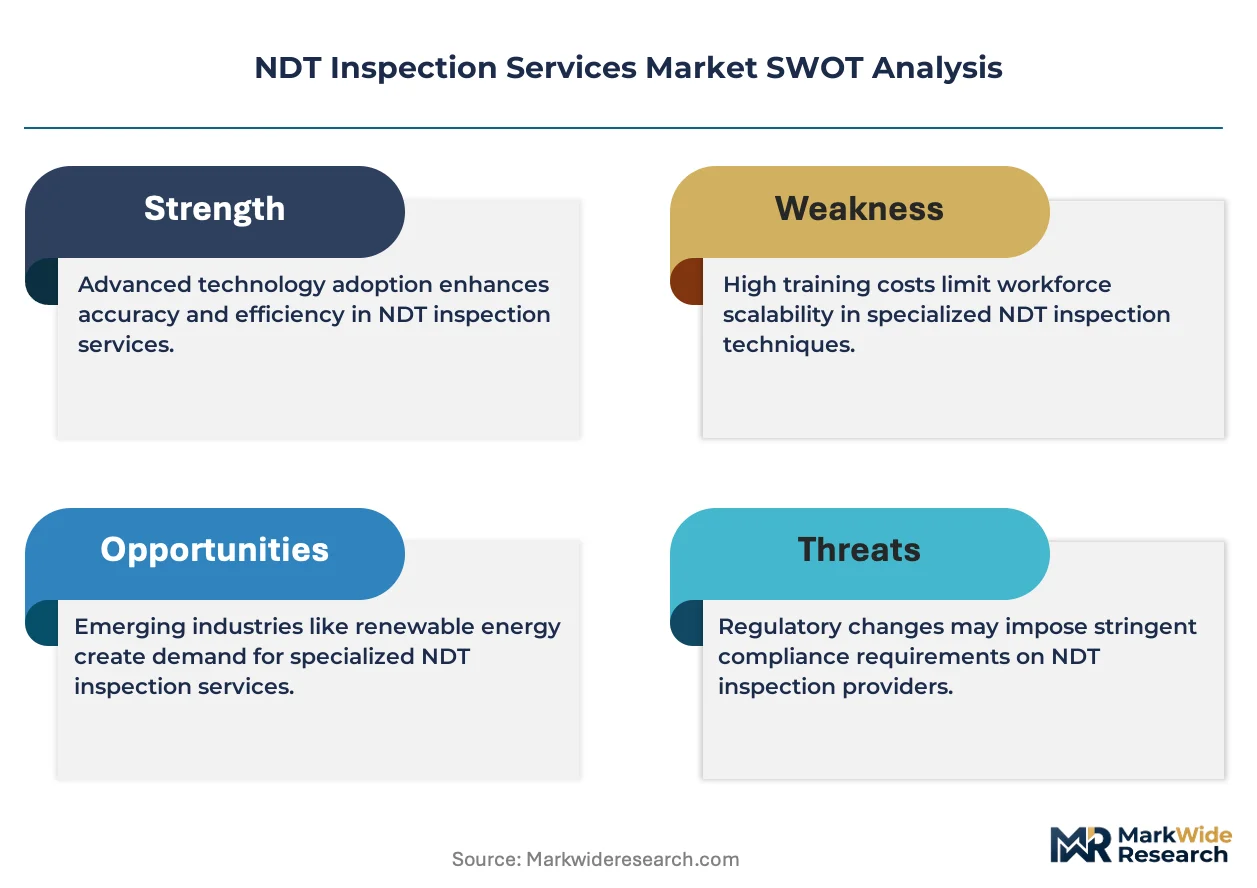
Software-defined inspection analytics is decoupling hardware ownership from service value, forcing incumbents to rebuild revenue models around data interpretation rather than equipment deployment. This structural shift compresses capital barriers for new entrants while elevating algorithmic capabilities as the primary competitive moat.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based leak detection methods accelerates adoption of infrared thermography and ultrasonic alternatives across European refrigeration and HVAC supply chains.
- Aerospace OEM service contracts:Long-term in-service monitoring agreements for commercial fleets generate recurring revenue streams that stabilize inspection provider cash flows and deepen technical integration with airframe manufacturers.
- German industrial corridor concentration:Automotive and power generation clusters in Bavaria and Baden-Württemberg sustain dense demand for phased array ultrasonic testing through integrated supplier networks.
Market Restraints
- Certified inspector scarcity:The specialized training required for ASME Boiler and Pressure Vessel Code compliance creates talent bottlenecks that limit service capacity expansion in North American pressure equipment markets.
- Isotope supply concentration:Radiographic testing depends on cobalt-60 and iridium-192 sources controlled by a handful of nuclear processing facilities, exposing inspection schedules to geopolitical supply disruptions.
- Conventional radiography displacement friction:Digital radiography adoption stalls in cost-sensitive segments where legacy film-based workflows remain entrenched despite regulatory pressure for traceability improvements.
Strategic Opportunities
- Offshore wind foundation inspection:Monopile and jacket structure monitoring in the North Sea and Baltic Sea creates demand for automated underwater vehicle-deployed ultrasonic systems as European offshore capacity scales.
- Hydrogen infrastructure protocols:The EU's hydrogen backbone initiative mandates new testing standards for high-pressure storage and pipeline materials, opening certification service white space ahead of infrastructure deployment.
- AI-assisted defect classification:Machine learning convergence with phased array data is unifying interpretation workflows, enabling tier-two providers to match specialist diagnostic accuracy without comparable human capital investment.
Industry Challenges
- Multi-standard certification burden:Service providers must maintain parallel accreditations under ISO 9712, ASME, and EN 473 frameworks to serve cross-border contracts, multiplying audit and training costs.
- Legacy system integration complexity:Digital inspection platforms face friction connecting with decades-old asset management databases in established industrial facilities, delaying analytics deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NDT Inspection Services Market |
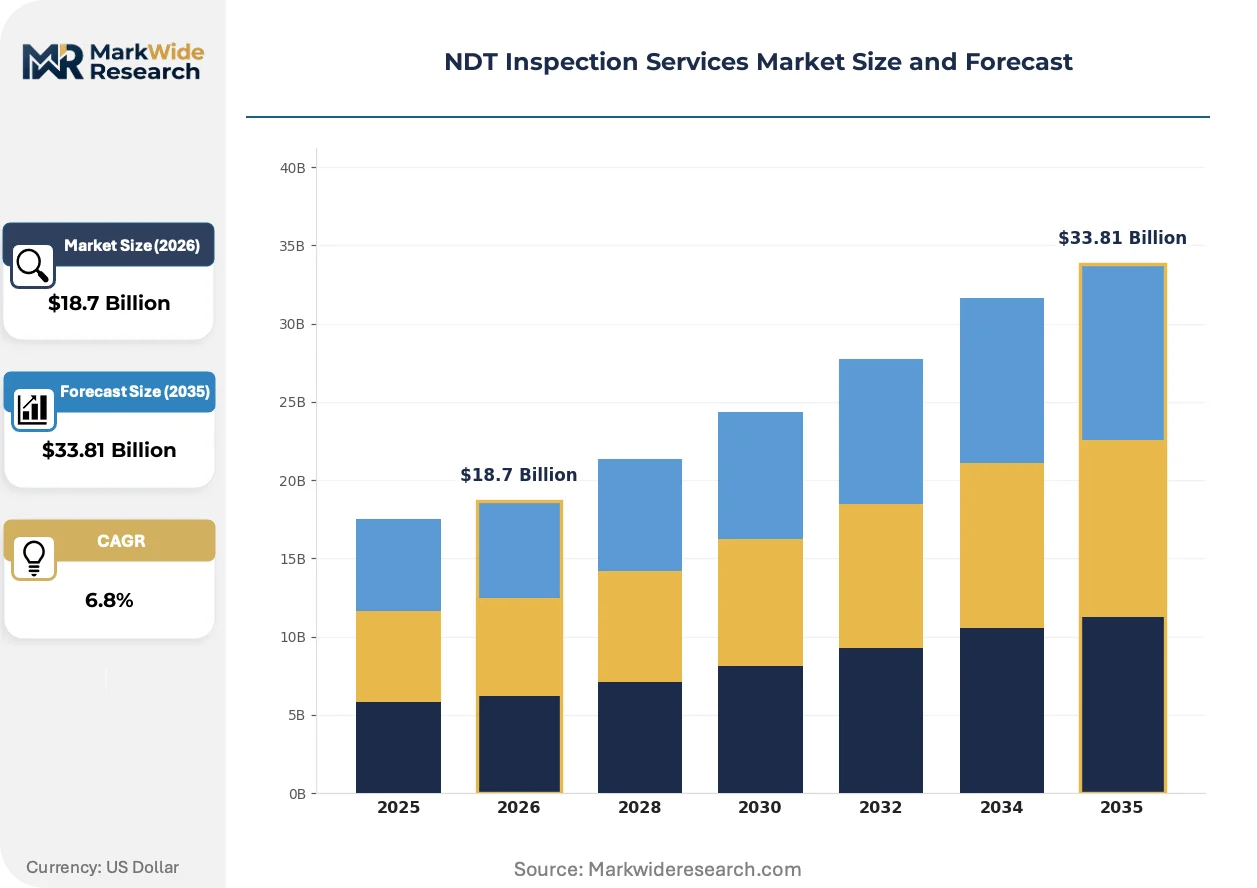
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ultrasonic Testing, Radiographic Testing, Magnetic Particle Testing, Visual Inspection End User: Aerospace, Manufacturing, Oil & Gas, Power Generation Technology: Drones, Robots, Phased Array, Conventional Application: Pipeline Integrity, Structural Health, Weld Inspection, Component Reliability |
| Companies Covered | Applus+, MISTRAS Group, SGS SA, DEKRA, TÜV Rheinland, Bureau Veritas, Intertek Group plc, Acuren Inspection, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NDT Inspection Services Market Strategic Shifts
Computational inspection methods are compressing the gap between raw sensor data and actionable engineering decisions, shifting competitive advantage toward software architecture and domain-specific algorithm training rather than hardware specifications alone.
Phased array ultrasonic testing is unifying formerly separate weld inspection and thickness measurement workflows into single-scan protocols. Pipeline operators facing regulatory renewal deadlines adopt these systems to compress inspection windows without extending shutdown durations. The technology is unifying data formats across previously incompatible equipment generations, reducing vendor lock-in and enabling mixed-fleet procurement strategies.
The EU's Medical Device Regulation tightens traceability requirements for implantable and high-risk devices, forcing manufacturers to document validated NDT protocols within quality management systems. German notified bodies interpret these provisions strictly, creating compliance friction for Asian suppliers seeking CE marking access. Medical device contract manufacturers respond by embedding inspection stations directly within cleanroom production lines rather than outsourcing to separate facilities.
Asset operators now unbundle inspection services from maintenance contracts, selecting specialists through competitive tender for each campaign rather than accepting bundled offerings from incumbent service providers. This fragmentation compresses contract durations and elevates price transparency, particularly visible in North American refinery turnaround planning where integrated service providers face disintermediation from niche ultrasonic and eddy current specialists.
NDT Inspection Services Market Segmentation
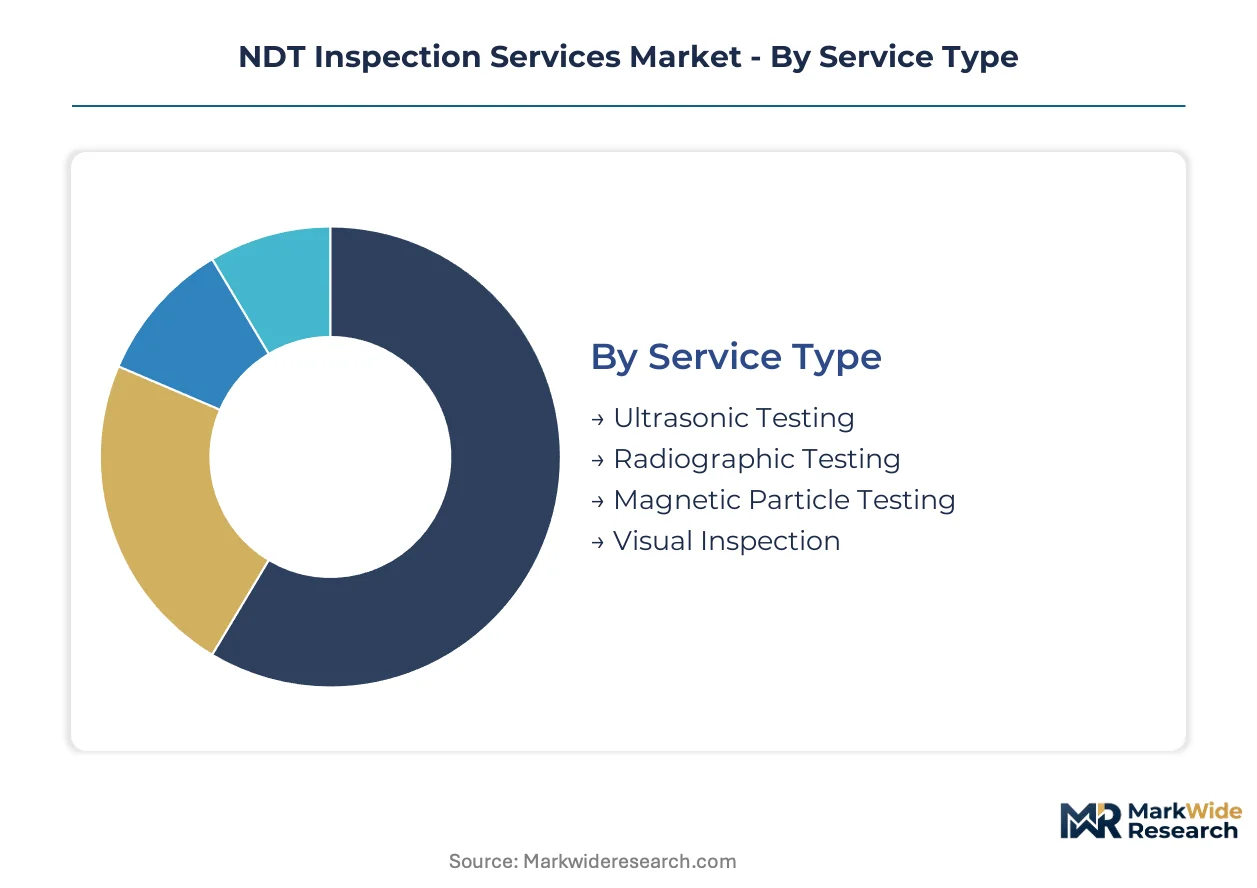
Segmentation in NDT inspection services reveals how technical specialization, regulatory pressure, and asset lifecycle demands fragment procurement decisions across industrial buyers. Service providers must align capability portfolios with distinct compliance regimes and inspection frequencies that vary sharply by end-use sector.
Service Type:
Customization intensity spans from fully automated drone deployments to technician-dependent manual techniques, creating divergent margin structures and capital requirements across the service spectrum.
- Ultrasonic Testing:High-frequency acoustic wave propagation detects subsurface discontinuities and measures wall thickness in pressure vessels and piping systems. Bavarian automotive suppliers and Baden-Württemberg power equipment manufacturers sustain concentrated demand for phased array variants that compress inspection windows during scheduled outages.
- Radiographic Testing:Gamma and X-ray sources penetrate dense materials to reveal internal voids, cracks, and inclusions in castings and welds. Pipeline operators in the Permian Basin and North Sea corridors depend on this method for girth weld verification, though isotope supply concentration from limited nuclear processing facilities constrains scheduling flexibility.
- Magnetic Particle Testing:Surface-breaking defect detection for ferromagnetic components through magnetic field distortion and particle accumulation. Aerospace landing gear manufacturers specify this method for fatigue crack monitoring.
- Visual Inspection:Direct optical assessment augmented by borescopes and remote cameras for accessible surface conditions. Cost-sensitive maintenance programs deploy this as a screening layer before advanced methods.
Most installed capacity flows through Ultrasonic Testing. Expansion is steepest in Radiographic Testing as digital detector arrays displace film-based workflows.
End User:
Procurement sophistication correlates with regulatory scrutiny intensity, separating buyers with embedded inspection engineering teams from those relying entirely on third-party specialists.
- Aerospace:Airframe OEMs and MRO providers execute long-term in-service monitoring contracts covering commercial fleets under FAA and EASA airworthiness directives. Boeing and Airbus supplier tiers mandate AS9100-aligned NDT protocols with full digital traceability.
- Manufacturing:Automotive and industrial equipment producers integrate inspection stations within production lines to satisfy ISO 9001 and sector-specific quality mandates. German KBA enforcement cascades testing standards through European supplier networks.
- Oil & Gas:Refinery and pipeline operators face ASME Boiler and Pressure Vessel Code inspection intervals plus PHMSA integrity management deadlines. Turnaround planning compresses campaign windows and elevates demand for rapid-deployment ultrasonic crews.
- Power Generation:Nuclear, fossil, and renewable asset managers balance regulatory compliance with outage cost minimization. Offshore wind foundation monitoring in the North Sea creates emerging demand for automated underwater vehicle deployment.
Contract value concentrates in Aerospace. Volume expansion is accelerating fastest in Power Generation as renewable capacity scales.
Technology:
Capital intensity and data architecture requirements stratify providers between asset-light analytics platforms and equipment-heavy field service operators.
- Phased Array:Electronically steerable ultrasonic beams enable single-scan coverage of complex geometries previously requiring multiple probe configurations. Weld inspection and thickness measurement workflows unify, reducing vessel entry requirements.
- Conventional:Fixed-angle ultrasonic probes and single-source radiography equipment serve cost-sensitive applications where inspection frequency exceeds capital recovery timelines.
- Drones:Aerial platforms equipped with thermal and visual sensors access elevated or hazardous structures without scaffolding. Wind turbine blade and storage tank roof inspections adopt these systems for cost and safety advantages.
- Robots:Crawler and snake-arm systems navigate confined spaces and radioactive environments. Nuclear pressure vessel inspections and offshore platform structural surveys deploy these for technician hazard reduction.
Phased Array dominates current revenue contribution. Drone-based services are gaining share fastest as flight autonomy and sensor miniaturization mature.
Application:
Inspection scope ranges from discrete component verification to continuous structural monitoring, with data integration requirements scaling accordingly.
- Pipeline Integrity:In-line inspection tools and direct assessment methods verify corrosion, cracking, and deformation threats under PHMSA and national regulator mandates. North American and European operators face renewal deadline clusters.
- Weld Inspection:Fabrication quality verification and in-service fatigue monitoring for pressure equipment, bridges, and ship hulls. ASME Section IX and ISO 5817 standards dictate acceptance criteria.
- Structural Health:Continuous or periodic assessment of civil infrastructure, offshore platforms, and wind turbines. Acoustic emission and vibration analysis supplement periodic NDT campaigns.
- Component Reliability:Critical rotating machinery, valves, and fasteners undergo targeted inspection to prevent operational failure. Medical device manufacturers under EU MDR embed validated protocols within cleanroom production.
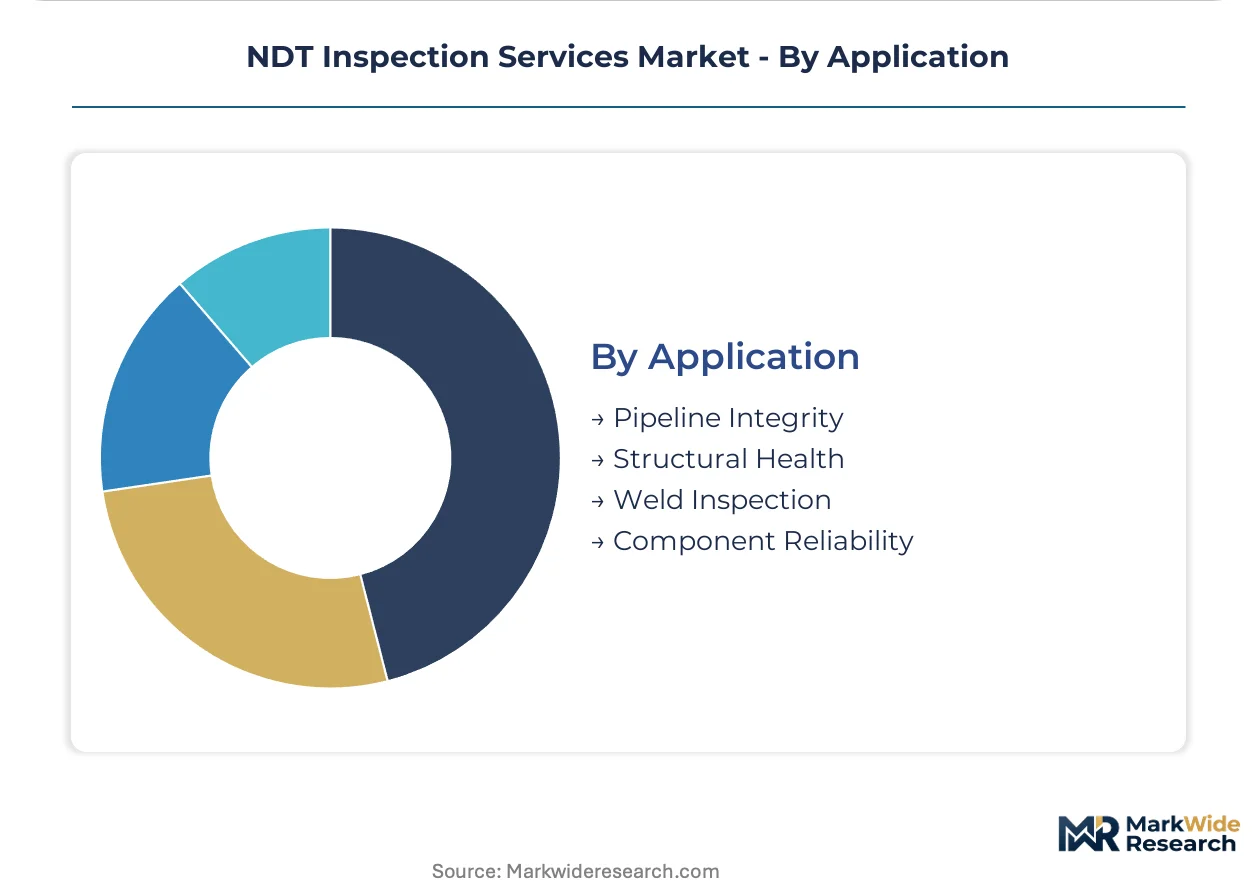
Pipeline Integrity commands the largest contract values. Structural Health is climbing the fastest as aging infrastructure portfolios expand monitoring budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more phased array ultrasonic capacity than any other single country, while the United States generates larger contract values through aerospace OEM service agreements. Regulatory fragmentation across inspection standards creates distinct procurement patterns in each national market.
United States
Pipeline operators in the Permian Basin and Gulf Coast corridor face clustered PHMSA integrity management deadlines that compress inspection campaign windows. The FAA mandates recurrent airworthiness directives for commercial fleets, locking MRO providers into long-term monitoring contracts. Houston anchors the largest concentration of refinery turnaround specialists serving integrated oil and gas majors.
Germany
Automotive suppliers in Bavaria and power equipment manufacturers in Baden-Württemberg sustain dense demand for automated ultrasonic systems. The KBA enforces rail and automotive component testing standards that cascade through European supplier tiers. Stuttgart's industrial cluster integrates inspection stations directly within powertrain production lines to satisfy ISO 9001 mandates.
China
Nuclear power expansion along the eastern seaboard and offshore wind deployment in the Yellow Sea create demand for robotic inspection platforms. The NMPA tightens medical device quality protocols that mirror EU MDR traceability requirements. Shanghai's port infrastructure cluster drives adoption of drone-based storage tank inspection for chemical handling facilities.
United Kingdom
North Sea oil and gas decommissioning schedules and offshore wind foundation installation create overlapping demand for subsea inspection services. The Health and Safety Executive enforces pressure equipment inspection intervals under retained EU-derived regulations. Aberdeen's energy services corridor hosts specialized providers for platform structural health monitoring.
France
Aerospace manufacturing around Toulouse and nuclear maintenance at Flamanville generate concentrated demand for radiographic and ultrasonic testing. The ANSM interprets EU MDR provisions strictly for implantable medical device manufacturers. Île-de-France's research institutions pilot AI-assisted defect classification algorithms for phased array data interpretation.
NDT Inspection Services Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated service providers dominating aerospace and oil and gas while regional laboratories capture medical device and automotive work. The market structure tilts toward consolidation at the top tier, where global networks sustain multi-year OEM contracts, and fragmentation at the specialist tier, where niche techniques command premium pricing. Three archetypes prevail: diversified testing conglomerates with cross-sector certification authority, energy-focused integrity specialists with embedded refinery relationships, and technology-forward analytics platforms decoupling hardware from service value. Competitive moves concentrate on strategic partnerships for digital platform integration and selective M&A to fill geographic or technique gaps.
Within the diversified testing conglomerate tier, Applus+, SGS SA, and Bureau Veritas exemplify providers that leverage global laboratory networks to sustain long-term aerospace contracts across multiple continents. These entities occupy positions where certification authority and cross-border regulatory fluency create defensive moats against regional competitors. MISTRAS Group anchors the energy-focused integrity specialist archetype through concentrated presence in North American refinery and pipeline corridors. The company exemplifies how embedded relationships with asset operators translate into recurring turnaround and integrity management revenues.
| Leading Market Players |
|---|
| Applus+ |
| MISTRAS Group |
| SGS SA |
| DEKRA |
| TÜV Rheinland |
| Bureau Veritas |
| Intertek Group plc |
| Acuren Inspection |
| Baker Hughes Company |
| Others |
Value Chain & Pricing Dynamics
Certified ASME inspector concentration in Houston and the Gulf Coast corridor generates labor-cost differentials that widen pricing-tier spreads between premium-code-compliant specialists and economy-tier generalists.
Pricing Analysis
Capacity additions in Eastern European training centers are reshaping price floors for conventional radiographic testing, compressing margins on film-based workflows while phased array ultrasonic specialists maintain premium positioning through ASME and EN 473 certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates code-specialist providers from volume operators and entry-level technicians. Pricing pressure stems from software-defined analytics platforms decoupling hardware ownership from service value, forcing equipment-heavy incumbents to absorb capital depreciation without corresponding rate premiums. Mid-tier manufacturing buyers exhibit highest price sensitivity, while aerospace OEMs prioritize technical integration over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Canadian and Russian nuclear processing facilities controlling cobalt-60 and iridium-192 isotope supply for gamma radiography. Equipment manufacturing concentrates in Germany, the United States, and Japan, with probe assemblies and digital detector arrays drawing from semiconductor fabrication networks in Taiwan and South Korea. Tariff exposure on Chinese-manufactured phased array systems creates procurement friction for North American service providers. Distribution runs through authorized regional distributors with factory-trained calibration capabilities, limiting direct manufacturer-to-operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NDT Inspection Services Market functions as a geographic-arbitrage play where German KBA-enforced testing standards create compliance premiums unavailable in less regulated jurisdictions, rewarding providers with multi-jurisdiction certification authority.
For Market Incumbents: Anticipate displacement from AI-assisted defect classification platforms by embedding algorithm development partnerships within existing aerospace and refinery relationships. Deepen vertical integration into isotope logistics and probe manufacturing to insulate margin structures from supply concentration risks. Prioritize EN 473 and ISO 9712 certification maintenance as regulatory scope broadens into hydrogen infrastructure and offshore wind. For New Entrants and Emerging Players: The 40-60% price-point gap between premium-code specialists and economy-tier generalists in North American manufacturing creates white-space opportunity for mid-tier providers offering ASME-compliant capacity without global network overhead. Target German automotive supplier tiers seeking CE-marked inspection documentation for EU market access. Pursue drone-based structural health monitoring in offshore wind corridors as the most penetrable application segment with lowest incumbent density. For Investors and Strategic Acquirers: Valuations sit cheapest among regional radiographic testing laboratories lacking phased array or software-analytics capabilities. Long-term viability hinges on algorithmic interpretation assets rather than equipment fleets, favoring targets with proprietary training datasets over hardware-heavy balance sheets. Watch EU hydrogen backbone infrastructure deployment timelines as the signal indicating certification service demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Defect Classification Development | Machine learning convergence with phased array data unifies interpretation workflows for tier-two providers. |
| Phased Array Ultrasonic Capacity Expansion | Single-scan protocols compress inspection windows during refinery turnarounds and pipeline shutdowns. |
| Multi-Standard Certification Investment | Parallel ISO 9712, ASME, and EN 473 accreditations unlock cross-border aerospace and energy contracts. |
| Offshore Wind Foundation Monitoring Partnership | North Sea and Baltic Sea deployment creates demand for automated underwater vehicle systems. |
| Isotope Supply Chain Backward Integration | Cobalt-60 and iridium-192 source control insulates scheduling from geopolitical disruption exposure. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with NDT service operations directors, aerospace quality assurance managers, refinery turnaround planners, and pipeline integrity engineers with secondary validation through ASME code filings, FAA airworthiness directives, EU MDR guidance documents, and customs trade data on ultrasonic equipment imports.
Input-output matrices map inspection demand across service type, end-user sector, technology tier, and application scope, with CAGRs derived from regression analysis of historical contract values and forward projection of regulatory deadline clusters. Modeled dimensions include ultrasonic versus radiographic method split, aerospace OEM service contract duration, and hydrogen infrastructure protocol development status.
Caveats apply where EU F-Gas Regulation phase-down acceleration or isotope supply disruptions could materially shift the outlook for radiographic testing demand and pricing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Geotechnical Services Market
Engineering Services
Geophysical Services Market
Engineering Services
MEP Services Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
United States (US) MEP Services Market
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
Engineering Services Market
Engineering Services
Geosteering Services Market
Engineering Services
North America Seismic Survey Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Vacuum Excavation Service Market