
 Artificial Wood Beams Market | 2026-2036
Artificial Wood Beams Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Wood Beams Market Outlook
ASTM E119 fire-resistance certification is unwinding competitive access across the artificial wood beams sector, raising the capital threshold for new entrants. Ekena Millwork leverages extensive molding catalogs and direct-to-contractor distribution to sustain pricing power in decorative beam segments. AZ Faux anchors its position through faux-wood polyurethane formulations that dominate renovation channels where lightweight installation matters. Barron Designs differentiates via hand-finished textures that replicate heritage timber grades for high-end residential clients.
Artificial wood beams encompass structural and decorative members manufactured from engineered composites, laminated veneers, or fiber-reinforced polymers, typically rated for spans between 15 and 40 feet and surface-burning characteristics of 25 or less. These products substitute for solid sawn timber in applications requiring consistent dimensional stability, fire resistance, or reduced dead load. Engineered beams and cross-laminated timber command the deepest project backlogs as commercial mass-timber construction expands, while laminated veneer lumber occupies mature replacement cycles in conventional light-frame housing. Aesthetic features represent the fastest-growing application slice as interior designers specify exposed beams for biophilic retail and hospitality environments.
EPA formaldehyde emission standards under TSCA Title VI, California Air Resources Board certification, and EU Construction Products Regulation harmonization shape material sourcing and cross-border product acceptance. US builders must navigate ICC-ES evaluation reports alongside state-level amendments, while European manufacturers face CE marking under harmonized EN 14080 for glued laminated timber. Stakeholders should monitor evolving model building codes that may recategorize engineered timber fire ratings, as these revisions will determine which beam technologies retain structural designation in multi-story construction.
Market Dynamics
Mass-timber construction codes are compressing specification cycles for artificial wood beams as architects and engineers race to meet carbon-reduction mandates in commercial building portfolios.
Growth Catalysts
- California Title 24 energy code:The state's stringent envelope performance standards push builders toward engineered beam systems that deliver predictable thermal bridging performance.
- Biophilic interior design:Hospitality and retail developers specify exposed artificial timber to create natural aesthetic environments without the weight and fire-risk of solid wood.
- Germany's updated fire-safety standards:Tighter material compliance requirements accelerate replacement of legacy timber in renovation projects across multi-family housing.
Market Restraints
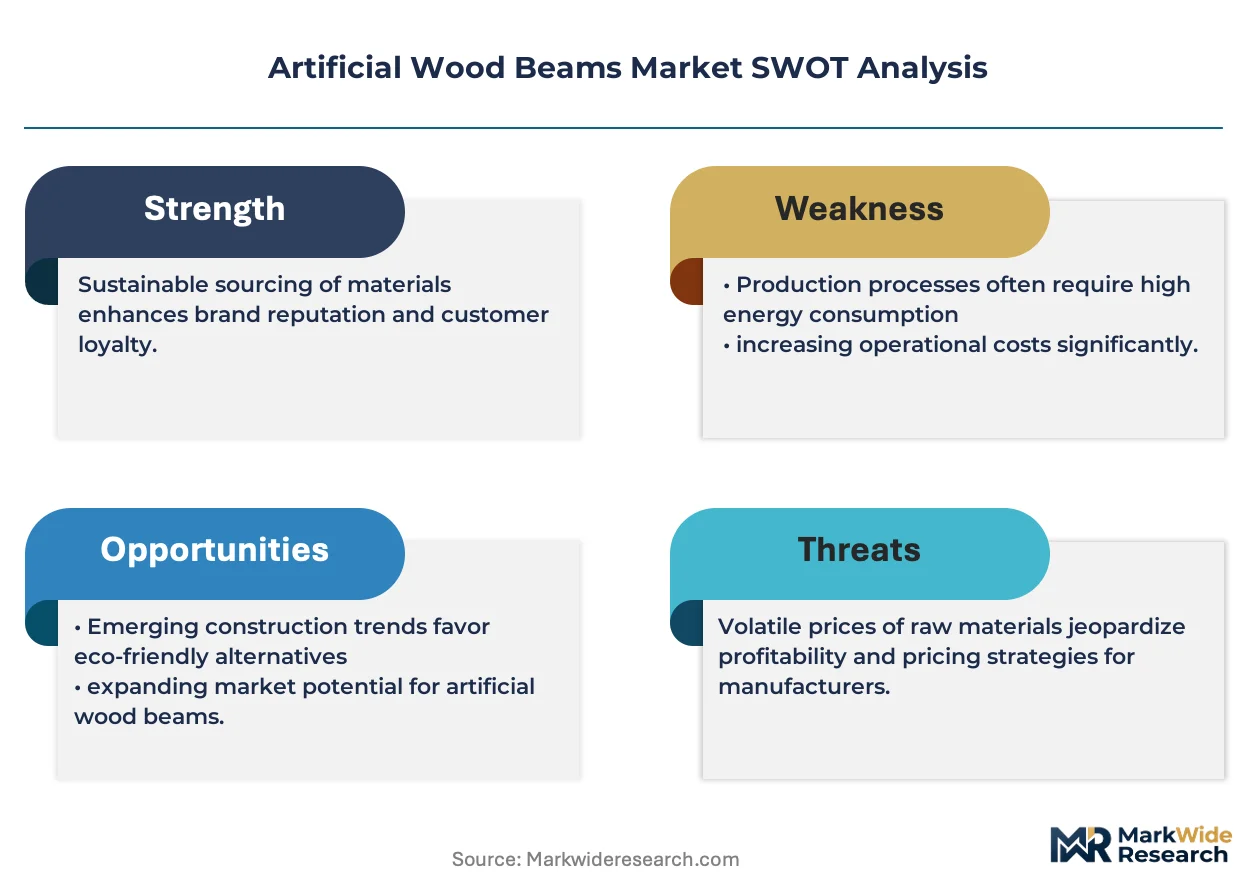
- Resin and adhesive cost volatility:Formaldehyde-based binding agents face feedstock price swings tied to petrochemical supply chains, squeezing laminated veneer lumber margins.
- ASTM E119 certification concentration:Fire-resistance testing infrastructure clusters in North American and Western European laboratories, creating geographic bottlenecks for Asian manufacturers seeking market entry.
- Solid sawn timber substitution:Regional softwood gluts in Pacific Northwest and Nordic markets periodically undercut engineered beam pricing in light-frame residential segments.
Strategic Opportunities
- Japan's mass-timber adoption:METI-promoted wooden high-rise initiatives create specification pull for fire-rated engineered beams in seismic-resistant commercial construction.
- Direct-to-contractor digital platforms:Specialized procurement channels bypass traditional lumberyard distribution, capturing margin and shortening lead times for renovation contractors.
- EU Green Deal embodied carbon tracking:Building-level carbon accounting favors engineered timber with verified environmental product declarations over steel and concrete alternatives.
Industry Challenges
- Cross-laminated timber certification timelines:ICC-ES evaluation report processes stretch 18-24 months, delaying product launches and freezing capital in pre-approval inventory.
- Fire-rating recategorization risk:Model building code revisions under consideration by the International Code Council could reclassify certain engineered beam technologies, forcing costly reformulation or market exit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Wood Beams Market |
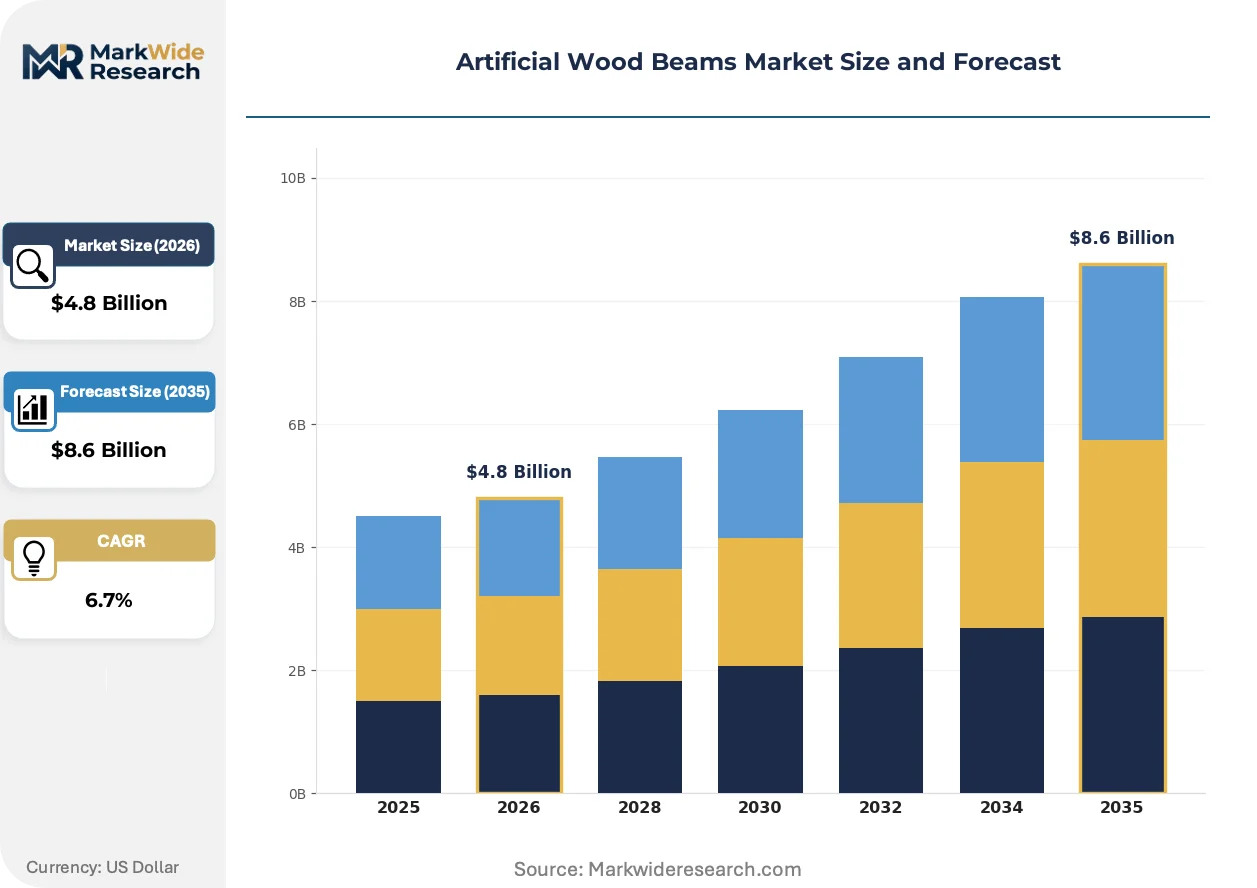
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engineered Beams, Laminated Veneer Lumber, Glued Laminated Timber, Cross-Laminated Timber End Use: Residential Construction, Commercial Construction, Renovation, Infrastructure Projects Material: Plywood, Medium Density Fiberboard, Oriented Strand Board, Solid Wood Application: Support Beams, Roof Systems, Flooring Systems, Aesthetic Features |
| Companies Covered | Ekena Millwork, AZ Faux, Architectural Depot, Barron Designs, Woodstock Architectural Products, Royal Corinthian, Volterra Products, Weber Custom Interiors, Woodland Custom Beam Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Wood Beams Market Strategic Shifts
Fire-performance engineering and digital fabrication are converging to expand artificial wood beams from structural commodity into architectural statement piece.
Fiber-reinforced polymer hybridization is miniaturizing the gap between structural performance and decorative flexibility. High-end residential developers specify these composite beams for cantilevered spans exceeding conventional laminated veneer lumber limits. The technology is miniaturizing installation crew requirements from specialized rigging teams to standard carpentry labor.
EU Construction Products Regulation harmonization under EN 14080 is consolidating quality assurance protocols across member states. Manufacturers holding CE marking gain automatic acceptance in 27 national markets without redundant testing. German and Austrian glued laminated timber producers are consolidating certification assets to exploit this regulatory efficiency.
Design-build firms now bundle engineered beam specification with interior aesthetic packages. Single-source accountability replaces fragmented architect-contractor-subcontractor handoffs. This integration is most visible in US coastal metropolitan markets where labor scarcity and schedule compression dominate project economics.
Artificial Wood Beams Market Segmentation
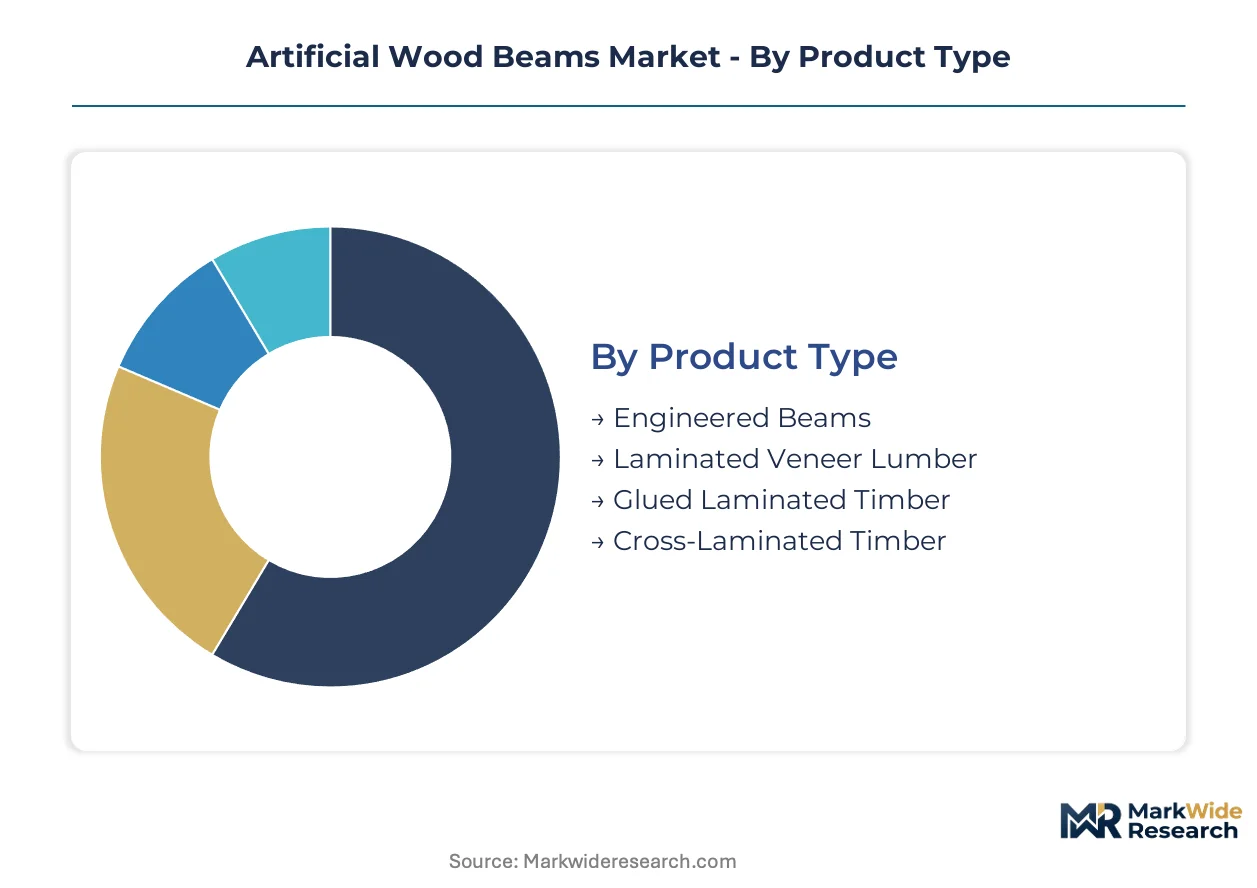
Artificial wood beams fragment across four intersecting dimensions that reshape procurement economics. Product type determines structural certification requirements, while end-use application dictates fire-rating specifications and aesthetic finishing intensity.
Product Type:
Margin pools concentrate in fire-rated structural segments where ASTM E119 certification creates supply scarcity.
- Engineered Beams:Composite assemblies of wood strands bonded with moisture-resistant adhesives, rated for spans exceeding conventional lumber limits. Demand clusters in California multi-family housing where Title 24 thermal bridging standards mandate predictable dimensional stability. ICC-ES evaluation timelines of 18-24 months constrain new supplier entry.
- Cross-Laminated Timber:Orthogonally layered solid-sawn boards pressed into massive structural panels, enabling 10-story-plus mass-timber construction. Germany and Austria lead specification as EU Green Deal embodied carbon tracking favors verified environmental product declarations over steel alternatives. Certification bottlenecks freeze capital in pre-approval inventory.
- Laminated Veneer Lumber:Rotary-peeled veneer sheets bonded in parallel grain orientation for consistent strength properties.
- Glued Laminated Timber:Dimension lumber laminations bonded with structural adhesives, curved during manufacturing for architectural expression.
The dominant share belongs to Engineered Beams, while Cross-Laminated Timber is closing the gap fastest.
End Use:
Application intensity varies sharply between new construction and retrofit environments.
- Residential Construction:Single-family and multi-family housing drives volume procurement of standardized beam dimensions. California, Germany, and Japan concentrate demand where green building certifications and mass-timber codes accelerate specification. Fire-rated alternatives to solid timber command premium positioning in wildland-urban interface zones.
- Renovation:Lightweight faux-wood polyurethane formulations dominate channel flow where existing structural capacity limits dead load. Interior designers specify exposed beams for biophilic retail and hospitality environments without the weight and fire-risk of solid wood. Direct-to-contractor digital platforms capture margin by bypassing traditional lumberyard distribution.
- Commercial Construction:Mass-timber office and institutional buildings requiring seismic-resistant engineered systems.
- Infrastructure Projects:Bridge and heavy civil applications with specialized load-bearing specifications.
Residential Construction retains the deepest project backlogs, though Renovation channels are expanding most quickly.
Material:
Feedstock chemistry determines emission compliance and cross-border market access.
- Medium Density Fiberboard:Refined wood fibers bonded with resin systems, offering uniform density for precision machining. EPA formaldehyde emission standards under TSCA Title VI and California Air Resources Board certification shape sourcing decisions for US-bound production.
- Oriented Strand Board:Flaked wood strands arranged in cross-directional layers for dimensional stability in high-moisture environments.
- Plywood:Cross-laminated veneer construction with established supply chains and commodity pricing.
- Solid Wood:Heritage timber grades for hand-finished architectural applications in high-end residential segments.
Medium Density Fiberboard holds the broadest regulatory acceptance, while Oriented Strand Board climbs fastest in commercial envelope applications.
Application:
Functional role determines whether beams remain concealed or become visible design elements.
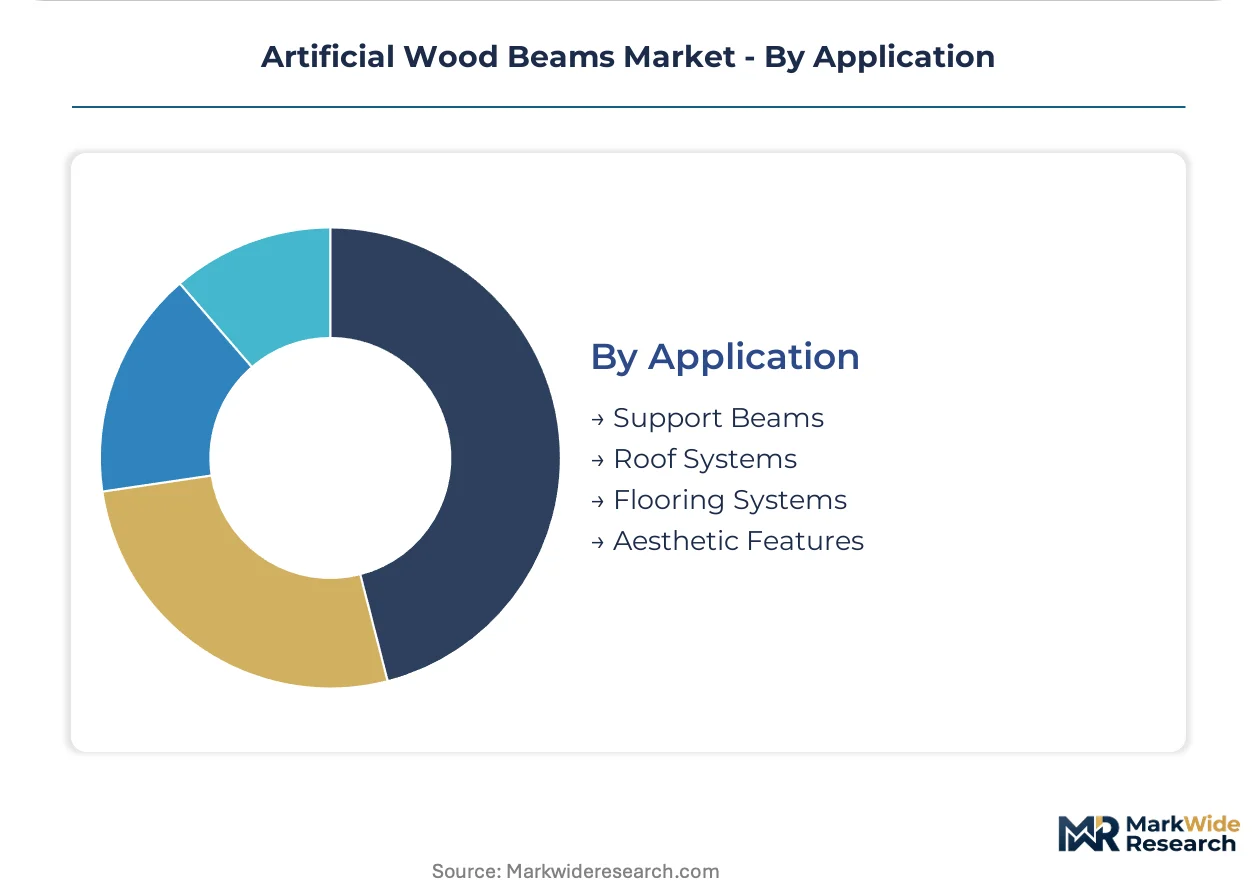
- Support Beams:Primary structural members carrying gravity and lateral loads, concealed within wall assemblies or exposed as architectural features. Fire-resistance ratings of 25 or less on surface-burning characteristics determine code compliance in multi-story construction.
- Aesthetic Features:Non-structural decorative members specified for biophilic interior environments. Hospitality and retail developers drive specification as exposed artificial timber creates natural aesthetic without solid wood weight. This slice gains share fastest as design-build firms bundle engineered beam specification with interior packages.
- Roof Systems:Rafter and purlin applications spanning 15 to 40 feet with snow load ratings.
- Flooring Systems:Joist and header applications requiring vibration control and point load distribution.
Support Beams anchor structural specification volumes, though Aesthetic Features are gaining share fastest as interior exposure trends accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Architects and contractors in wildland-urban interface zones and carbon-mandate jurisdictions drive specification intensity. Germany, Japan, and the United States concentrate procurement volume where fire codes and green building standards intersect.
United States
California multi-family developers specify engineered beams to satisfy Title 24 thermal bridging standards. EPA formaldehyde emission rules under TSCA Title VI shape cross-border sourcing from Canadian veneer mills. Pacific Northwest softwood gluts periodically compress pricing in light-frame residential segments.
Germany
Mass-timber commercial towers in Berlin and Munich pull fire-rated cross-laminated timber from Austrian and domestic suppliers. EU Construction Products Regulation harmonization under EN 14080 accelerates CE-marked product acceptance across 27 markets. Baden-Württemberg glue-lam producers consolidate certification assets to exploit regulatory efficiency.
Japan
METI-promoted wooden high-rise initiatives create specification demand for seismic-resistant engineered systems in Tokyo and Osaka. Updated fire-safety standards tighten material compliance for multi-family renovation projects. Chubu region fabricators expand capacity to serve commercial mass-timber adoption.
Canada
British Columbia mass-timber building codes position Vancouver and Toronto as North American specification hubs for cross-laminated timber. ICC-ES evaluation report requirements delay Asian manufacturer entry into provincial markets. Quebec laminated veneer lumber producers serve US Northeast renovation channels.
Australia
New South Wales and Victoria biophilic retail developers specify exposed artificial timber for hospitality interiors without solid wood weight. State-level amendments to National Construction Code shape fire-resistance rating requirements. Sydney design-build firms bundle engineered beam specification with interior aesthetic packages.
Artificial Wood Beams Market Competitive Environment
Player mix skews toward specialized molding fabricators and polyurethane formulation specialists. The vendor base clusters around decorative beam catalogs and lightweight renovation products rather than structural commodity producers. Two strategic archetypes dominate: direct-to-contractor distributors with extensive SKU breadth, and hand-finished texture specialists serving high-end residential. Competitive moves concentrate on molding catalog expansion and digital platform development to bypass traditional lumberyard channels.
Among US-based fabricators, Ekena Millwork occupies a position within the catalog-breadth archetype, while AZ Faux and Barron Designs exemplify formulation and finish specialization respectively. These three anchors represent distinct competitive vectors—distribution scale, material innovation, and artisan positioning—without overlap in core capability claims.
| Leading Market Players |
|---|
| Ekena Millwork |
| AZ Faux |
| Architectural Depot |
| Barron Designs |
| Woodstock Architectural Products |
| Royal Corinthian |
| Volterra Products |
| Weber Custom Interiors |
| Woodland Custom Beam Company |
| Others |
Value Chain & Pricing Dynamics
Formaldehyde-based adhesive substitution for soy-derived alternatives is simultaneously shifting supply geography toward North American feedstock clusters and compressing laminated veneer lumber margins as resin chemistry transitions disrupt established petrochemical supply contracts.
Pricing Analysis
Cost-plus contracts with formaldehyde feedstock indexation dominate procurement between laminated veneer lumber producers and adhesive suppliers. Three-tier pricing structure across premium, standard, and economy levels separates ASTM E119-certified structural beams from decorative polyurethane beams and commodity-grade support members. Pricing pressure stems from Pacific Northwest softwood gluts periodically undercutting engineered beam premiums in light-frame residential segments. Renovation contractors show highest price sensitivity due to project-based bidding, while mass-timber commercial developers prioritize fire-rating certification over unit cost.
Supply Chain Analysis
Great Lakes vessel transit through the St. Lawrence Seaway underwrites raw veneer movement from Quebec mills to US Northeast fabrication plants. Geographic supply concentrates in the United States, Germany, and Japan where ICC-ES evaluation infrastructure and CE marking authorities cluster. Raw material dependencies include formaldehyde resins, rotary-peeled hardwood veneers, and fiber-reinforced polymer feedstocks. Single-source vulnerability runs through petrochemical-derived binding agents exposed to energy price volatility. Distribution runs through direct-to-contractor digital platforms bypassing traditional lumberyard intermediaries in renovation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial wood beams are positioned for cyclical recovery as residential construction permit volumes rebound from interest-rate suppressed troughs, with multi-family housing starts serving as the lead indicator.
For Market Incumbents: Consolidate certification assets to exploit EU Construction Products Regulation harmonization, acquiring CE-marked production capacity in Austria and Baden-Württemberg to serve cross-border demand without redundant testing. Deepen backward integration into rotary-peeling operations to secure veneer supply against Pacific Northwest softwood price volatility. Prioritize ASTM E119 testing infrastructure partnerships to defend against Asian manufacturers seeking market entry. For New Entrants and Emerging Players: Lead with lightweight faux-wood polyurethane formulations targeting Japan's multi-family renovation channel where updated fire-safety standards tighten compliance requirements for legacy timber replacement. Japan's METI-promoted wooden high-rise initiatives create specification pull for seismic-resistant engineered systems with shorter certification timelines than cross-laminated timber. Deploy direct-to-contractor digital procurement platforms to capture margin and shorten lead times against established lumberyard distribution. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed molding fabricators holding extensive SKU breadth but lacking fire-rated structural certification capabilities. Long-term viability over a 5-10 year window hinges on mass-timber code adoption velocity in commercial construction segments. Watch ICC-ES evaluation report queue lengths as the inflection signal—compression from 18-24 months toward 12 months would indicate regulatory capacity expansion enabling faster product launches and capital velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM E119 Certification Investment | Fire-resistance testing infrastructure creates supply scarcity and pricing power for certified producers. |
| Direct-to-Contractor Platform Launch | Digital procurement channels capture margin by bypassing traditional lumberyard distribution in renovation segments. |
| CE Marking Asset Consolidation | Harmonized EN 14080 compliance enables automatic acceptance across 27 EU member markets without redundant testing. |
| Formaldehyde-Free Formulation R&D | EPA TSCA Title VI and CARB certification requirements favor low-emission resin systems for US-bound production. |
| Seismic-Resistant Product Line Extension | Japan's METI wooden high-rise initiatives create specification pull for engineered beams in Tokyo and Osaka commercial construction. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with mass-timber developers, fire-resistance testing laboratory directors, laminated veneer lumber procurement managers, and renovation contractor purchasing leads; alongside secondary validation through ICC-ES evaluation report databases, EPA TSCA Title VI certification registries, EU Construction Products Regulation harmonization documents, and customs trade data on veneer and adhesive imports. Bottom-up project pipeline enumeration triangulated against top-down construction spending allocation models.
Across the projection horizon, the analytical framework modeled demand across product type, end-use application, material composition, and functional application dimensions. CAGRs were derived from segment-level growth rate synthesis anchored to construction permit forecasts and green building certification adoption curves. Key inputs included Title 24 thermal bridging compliance timelines, mass-timber code amendment schedules, and biophilic design specification rates in hospitality and retail development.
Forecasts assume regulatory continuity in EPA TSCA Title VI, California Air Resources Board, and EU Construction Products Regulation regimes; material policy shifts such as fire-rating recategorization by the International Code Council would require re-modeling. Practitioners should keep alternative scenarios live as model building code revision timelines and resin feedstock price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Global Hydraulic Door Closer Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Industrial Flooring Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market
Building & Construction Materials
Roofing Materials Market
Building & Construction Materials
Africa Construction Chemicals Market