
 Satellite Simulator Market | 2026-2036
Satellite Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Simulator Market Analytics
Capability gaps in digital twin fidelity and RF channel emulation is reorganizing competitive hierarchies among satellite simulator providers. Lockheed Martin leverages its captive satellite manufacturing heritage to anchor integrated training ecosystems for government end users. Keysight Technologies sustains technology leadership through precision instrumentation for signal propagation modeling. Kratos Defense & Security Solutions competes on specialized threat-replication suites for electronic warfare training scenarios.
A satellite simulator is a test and measurement system that replicates orbital mechanics, link budgets, and RF propagation environments to validate spacecraft payloads and ground segment performance without physical space access. Modern platforms integrate software-defined radio cores with GPU-accelerated channel emulation to achieve real-time multipath and Doppler shift fidelity. Hardware deployments still occupy the largest revenue share among technology segments, though cloud-based architectures represent the fastest-expanding margin pool as constellation operators seek elastic simulation capacity. Defense applications lead absolute spending, while telecommunications is accelerating fastest as LEO broadband providers scale pre-launch payload verification protocols.
FCC spectrum coordination rules and DoD cybersecurity frameworks shape product certification requirements for US-deployed systems, while ESA procurement standards and EU Space Programme security guidelines govern European market access. ISO 9001 and AS9100 quality certifications remain baseline qualifications for defense contractor eligibility across NATO supply chains. Stakeholders must monitor how ITAR export control revisions and emerging national space traffic management regimes reshape cross-border simulator deployment permissions.
Market Dynamics
Software-defined radio architectures and GPU-accelerated channel emulation are compressing hardware refresh cycles while elevating fidelity requirements for orbital mechanics replication.
Growth Catalysts
- Space Force Modernization:United States defense procurement protocols mandate simulator-based training for constellation operators, displacing live-mission validation costs with synthetic environments.
- LEO Broadband Expansion:Commercial constellation operators deploy pre-launch payload verification protocols at scale, creating sustained demand for RF propagation fidelity.
- Digital Twin Integration:NATO member states adopt software-defined architectures for electronic warfare training scenarios, linking ground segment performance validation to satellite manufacturing workflows.
Market Restraints
- ITAR Export Controls:United States International Traffic in Arms Regulations restrict cross-border deployment permissions for high-fidelity threat-replication suites, fragmenting vendor addressable markets.
- GPU Supply Concentration:Taiwan-based semiconductor foundries dominate accelerator chip fabrication, exposing simulator manufacturers to single-source input volatility.
- Legacy Hardware Lock-in:Defense agencies maintain decade-old hardware-centric platforms with proprietary interfaces, creating integration friction for software-defined replacements.
Strategic Opportunities
- Cloud-Native Architectures:Constellation operators in the United States seek elastic simulation capacity through consumption-based licensing, displacing perpetual hardware ownership models.
- ESA Procurement Standards:European Space Programme security guidelines create certification pathways for vendors meeting EU Space Programme security guidelines, opening continental defense contracts.
- RF-AI Convergence:Machine learning inference at the edge of channel emulation hardware enables real-time adaptive jamming scenarios, creating premium pricing tiers for electronic warfare applications.
Industry Challenges
- AS9100 Certification Timelines:Quality management system audits for defense contractor eligibility extend 18-24 months, compressing product launch windows.
- Multiphysics Simulation Talent:Scarcity of engineers combining orbital mechanics expertise with RF propagation modeling forces vendors to train specialists internally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Simulator Market |
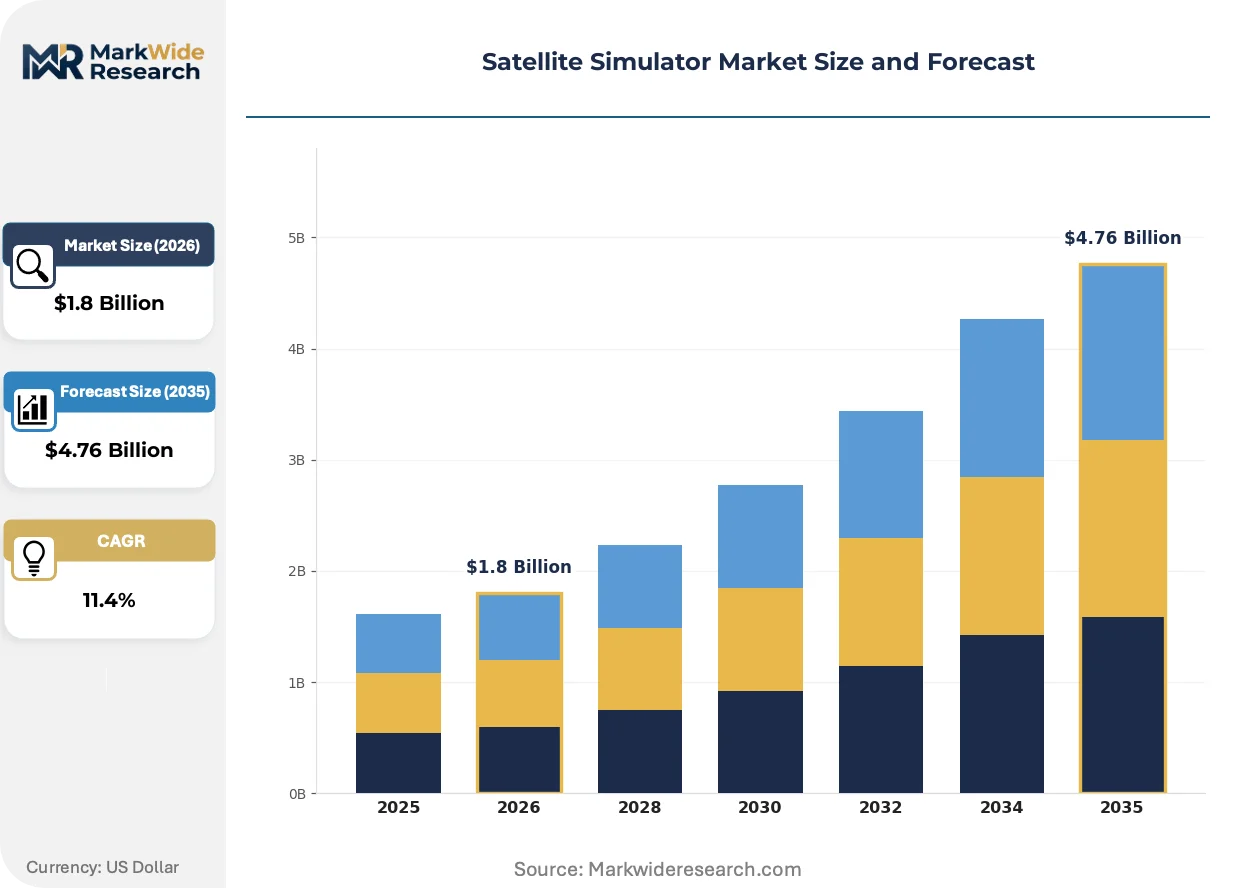
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hardware, Software, Hybrid, Cloud-based Application: Aerospace, Defense, Telecommunications, Research End User: Commercial, Government, Educational, Research Institutions Deployment: On-premises, Cloud, Managed Services, Others |
| Companies Covered | Lockheed Martin Corporation, Keysight Technologies, Kratos Defense & Security Solutions, GMV, Indra, Hollis Electronics, Anritsu, IFEN GmbH, Atlantic Microwave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Simulator Market Evolving Landscape
Simulation fidelity requirements are escalating as constellation density increases and regulatory frameworks harden around spectrum coordination and cybersecurity validation.
Software-defined radio cores with FPGA-based signal processing are displacing discrete component architectures in channel emulation subsystems. Defense procurement agencies in the United States now specify SDR modularity as mandatory for electronic warfare training contracts. This displacement compresses hardware refresh cycles from seven years to three while elevating vendor R&D intensity.
EU Space Programme security guidelines now mandate end-to-end encryption for ground segment interfaces, affecting simulator-to-hardware-in-the-loop connections. European constellation operators must demonstrate compliance with ESA procurement standards before accessing public funding. Manufacturers are responding by embedding hardware security modules directly into RF front-end designs.
Constellation operators now unbundle pre-launch verification from long-term maintenance contracts, creating discrete procurement events for each satellite batch. This fragmentation favors specialized simulator vendors over integrated prime contractors. The pattern is most visible among LEO broadband providers in the United States seeking competitive separation between payload validation and operational training systems.
Satellite Simulator Market Segmentation
Segmentation in satellite simulators reveals how procurement priorities split between capital-intensive hardware installations and elastic software architectures. Understanding these divides exposes where vendors can defend pricing power versus where commoditization pressures concentrate.
Technology:
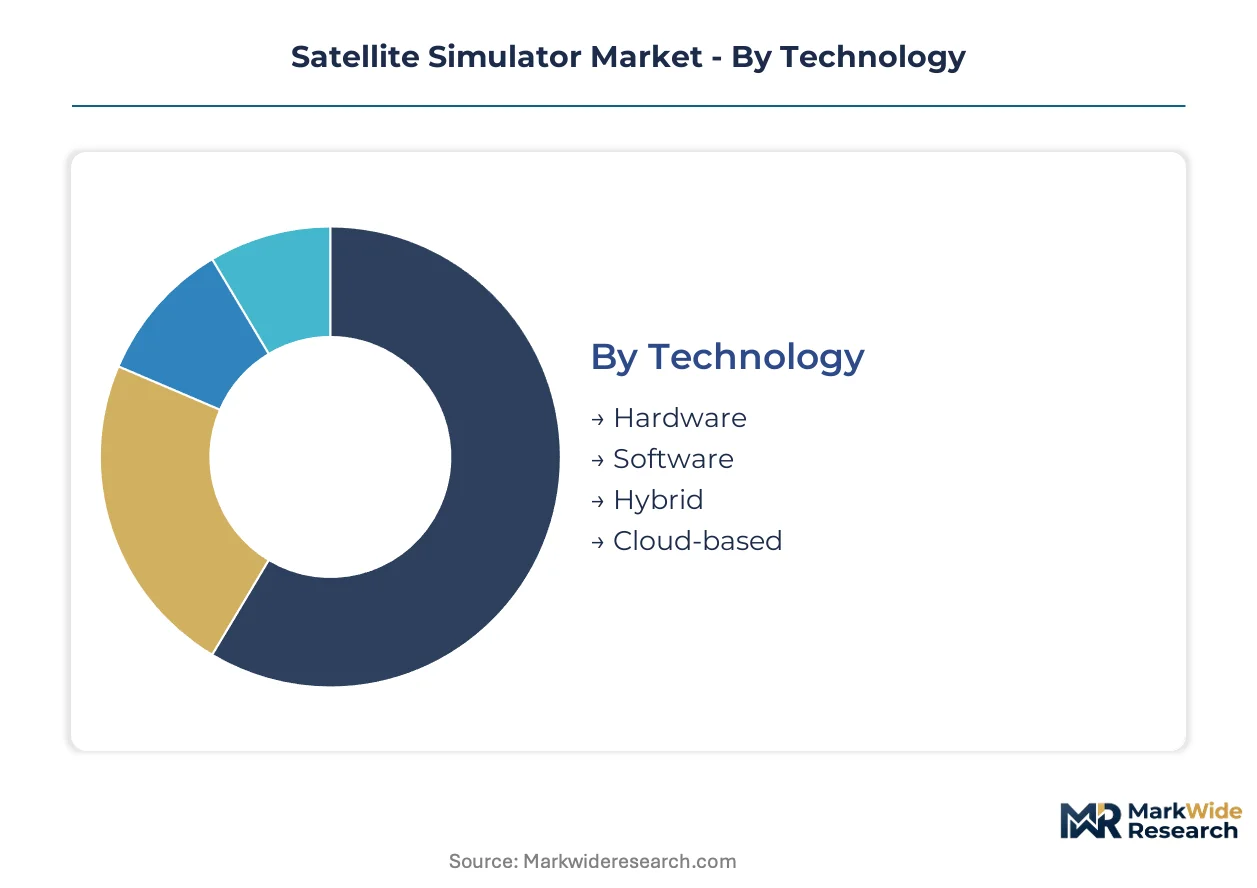
Margin pools concentrate in software-defined architectures that compress refresh cycles and elevate recurring licensing revenue.
- Hardware:Discrete RF components and FPGA-based signal processing chains dominate legacy defense installations. Pentagon procurement protocols still mandate hardware-in-the-loop validation for threat-replication suites, sustaining premium pricing despite longer sales cycles.
- Software:GPU-accelerated channel emulation and orbital mechanics engines enable real-time multipath fidelity without dedicated RF front-ends. Space Force training contracts now specify software modularity as mandatory, displacing seven-year refresh cycles with three-year upgrade timelines.
- Hybrid:Combines software-defined radio cores with selective hardware acceleration for specialized jamming scenarios.
- Cloud-based:Consumption-based licensing models attract LEO constellation operators seeking elastic pre-launch verification capacity.
Hardware holds installed capacity. Cloud-based is rotating up the share rankings.
Application:
Volume concentrates in defense procurement, though telecommunications is climbing fastest as commercial constellation density escalates.
- Aerospace:Satellite manufacturing workflows integrate simulators for payload verification and ground segment qualification. Lockheed Martin and Northrop Grumman anchor demand through captive integration with production lines.
- Defense:Electronic warfare training scenarios drive the steepest expansion trajectory, with NATO members mandating simulator-based protocols to displace live-mission costs.
- Telecommunications:LEO broadband providers deploy pre-launch verification at scale, creating sustained RF propagation fidelity demand.
- Research:University and laboratory procurement focuses on educational licensing and orbital mechanics visualization tools.
Defense commands absolute spending. Telecommunications is gaining share fastest.
End User:
Customer type determines contract structure, with government buyers demanding AS9100 certification and commercial buyers prioritizing speed-to-deployment.
- Commercial:Constellation operators unbundle pre-launch verification from maintenance contracts, creating discrete procurement events favoring specialized vendors.
- Government:Space Force modernization programs and NATO defense agencies mandate simulator-based training, sustaining multi-year framework agreements.
- Educational:Universities prioritize cost-efficient licensing for aerospace engineering curricula and student laboratory access.
- Research Institutions:National laboratories and space agencies procure high-fidelity platforms for fundamental orbital mechanics research and spectrum coordination studies.
Government anchors contract value. Commercial is expanding most quickly.
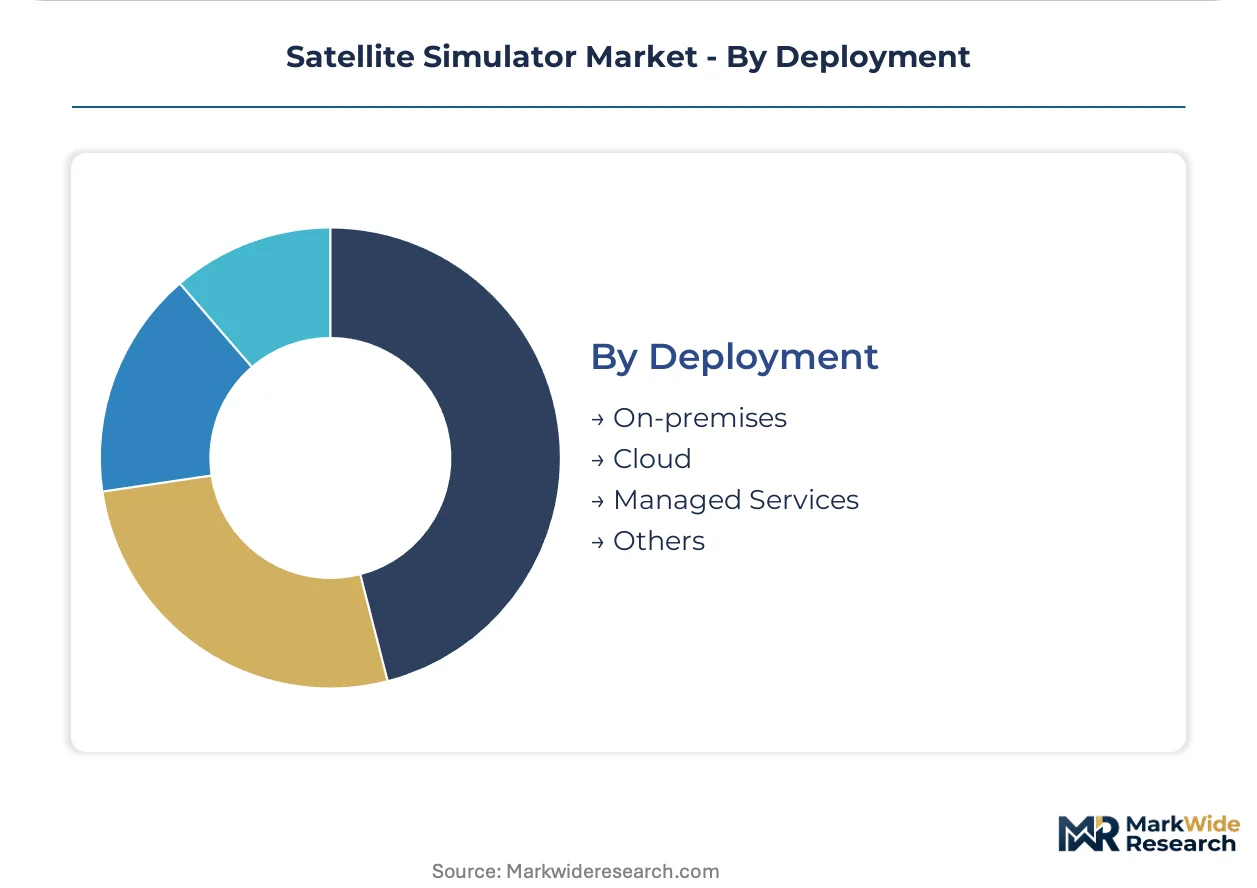
Deployment:
Delivery model selection tracks IT security posture, with classified programs resisting cloud migration despite cost advantages.
- On-premises:Air-gapped installations dominate classified defense applications where FCC spectrum coordination and DoD cybersecurity frameworks mandate physical isolation.
- Cloud:Elastic capacity appeals to commercial constellation operators scaling verification workloads across satellite batches.
- Managed Services:Vendors operate simulator infrastructure under long-term service agreements, transferring operational burden to specialized providers.
- Others:Edge-deployed and containerized architectures for distributed ground segment validation.
On-premises holds classified program share. Cloud is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial constellation operators in the United States show the least price sensitivity, absorbing premium licensing for software-defined architectures, while educational institutions across India and Southeast Asia demand aggressively discounted hardware packages. Defense procurement in NATO member states sits between these extremes, prioritizing certification compliance over unit economics.
United States
Space Force modernization programs and LEO broadband constellation deployments anchor procurement volumes for high-fidelity threat-replication suites. FCC spectrum coordination rules and DoD cybersecurity frameworks mandate AS9100 certification for ground segment interface validation. Colorado Springs hosts concentrated defense contractor activity, with simulator integration into Space Operations Command training protocols accelerating through 2025.
Germany
European Space Agency procurement standards drive demand for end-to-end encrypted ground segment simulators among satellite manufacturers in Bavaria and Baden-Württemberg. EU Space Programme security guidelines require hardware security module integration for public funding eligibility. Munich's aerospace cluster anchors GMV and Indra integration activity, linking orbital mechanics engines to Galileo constellation qualification workflows.
United Kingdom
UK Space Agency national space traffic management initiatives create procurement pathways for RF propagation modeling platforms supporting OneWeb and emerging domestic constellations. Ministry of Defence electronic warfare training mandates displace live-mission validation with synthetic environments. Harwell Science and Innovation Campus concentrates simulator R&D, with Atlantic Microwave anchoring specialized threat-replication development for NATO interoperability.
Japan
METI space industry promotion policies accelerate domestic constellation operator investment in pre-launch payload verification systems. QZSS augmentation service expansion drives demand for multipath and Doppler shift fidelity in regional navigation simulators. Tokyo-Osaka industrial corridor hosts Anritsu precision instrumentation development, with RF channel emulation products penetrating both defense and commercial telecommunications procurement.
France
CNES launch vehicle qualification protocols sustain demand for hardware-in-the-loop validation among ArianeGroup supply chain participants. ANSSI cybersecurity certification requirements shape ground segment interface encryption standards for EU-funded programs. Toulouse aerospace cluster concentrates GMV simulator integration with satellite manufacturing workflows, linking digital twin architectures to production line qualification protocols.
Satellite Simulator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision instrumentation specialists commanding premium pricing for RF propagation fidelity while scale-oriented vendors compete on simulator deployment velocity. The market structures around three tiers: integrated prime contractors with captive satellite manufacturing heritage, specialized RF test and measurement houses, and emerging cloud-native platform providers. Consolidation pressure concentrates among mid-scale hybrid vendors caught between software-defined refresh cycles and legacy hardware maintenance obligations. Dominant competitive moves include strategic partnerships linking simulator platforms to constellation operator pre-launch workflows, and technology licensing agreements transferring GPU-accelerated channel emulation IP across defense supply chains.
Within the integrated prime contractor tier, Lockheed Martin Corporation and Northrop Grumman occupy positions defined by captive satellite manufacturing workflows and multi-year Space Force framework agreements. Among specialized test and measurement providers, Keysight Technologies exemplifies precision instrumentation leadership through signal propagation modeling architectures, while Kratos Defense & Security Solutions anchors the threat-replication specialization segment for electronic warfare training scenarios. European competitors GMV and Indra sit within the hybrid tier, leveraging ESA procurement standard compliance to access continental defense contracts.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Keysight Technologies |
| Kratos Defense & Security Solutions |
| GMV |
| Indra |
| Hollis Electronics |
| Anritsu |
| IFEN GmbH |
| Atlantic Microwave |
| Others |
Value Network & Pricing Analysis
Software-defined radio cores replacing discrete RF components are redrawing procurement geography toward Taiwan-based semiconductor foundries while compressing hardware refresh cycles from seven years to three. This substitution simultaneously elevates GPU accelerator dependency and fragments pricing power between legacy hardware vendors and cloud-native platform providers.
Pricing Analysis
Post-deployment service contracts and consumption-based licensing tiers drive lifetime value capture across satellite simulator deployments. Three-tier pricing structure across premium, standard, and economy levels segments buyers by AS9100 certification status and threat-replication fidelity requirements. Price differentiation hinges on RF channel emulation precision and embedded hardware security module integration. Cost compression in standard-tier hardware is intensifying because LEO constellation operators unbundle pre-launch verification from long-term maintenance. Commercial telecommunications buyers exhibit highest price sensitivity, while Space Force procurement protocols absorb premium licensing for electronic warfare training suites.
Supply Chain Analysis
Strategic stockpiling of GPU accelerators dominates vendor inventory strategy as Taiwan-based foundry concentration creates single-source vulnerability for channel emulation hardware. Semiconductor fabrication draws from Taiwan, South Korea, and the United States for advanced node production. FPGA-based signal processing chains and RF front-end components rest on discrete component suppliers in Japan and Germany. Tariff exposure on ITAR-controlled subsystems fragments cross-border deployment permissions. Distribution runs through defense contractor prime channels for government end users and direct OEM relationships for commercial constellation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Satellite simulator procurement is entering a cyclical upswing as Space Force modernization programs and LEO broadband constellation deployments synchronize replacement cycles. Defense budget authorization patterns and commercial constellation launch cadence jointly govern the recovery trajectory.
For Market Incumbents: Secure multi-year framework agreements with NATO defense agencies before ESA procurement standard revisions reshape certification requirements. Deepen backward integration into GPU-accelerated channel emulation IP to displace third-party semiconductor dependency. Lockheed Martin and Keysight Technologies anchor positions through captive satellite manufacturing workflows and precision instrumentation leadership respectively.
For New Entrants and Emerging Players: Differentiate on cloud-native deployment velocity targeting commercial LEO broadband providers unbundling pre-launch verification from operational training systems. White-space concentration sits with European constellation operators seeking ESA procurement standard compliance without legacy hardware lock-in. GMV and Indra demonstrate viable pathways through Galileo constellation qualification workflows.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale hybrid vendors caught between software-defined refresh obligations and legacy hardware maintenance revenue streams. Five-to-ten year viability favors specialized RF test and measurement houses with threat-replication specialization over integrated prime contractors facing margin compression. Watch Space Force training contract award velocity as inflection indicator for defense procurement cyclicality.
| Strategic Initiative | Industry Significance |
|---|---|
| GPU-Accelerated Channel Emulation Investment | SDR modularity mandates from Space Force contracts displace seven-year hardware refresh cycles. |
| ESA Procurement Standard Certification | EU Space Programme security guidelines unlock continental defense contracts for compliant vendors. |
| Cloud-Native Platform Launch | Consumption-based licensing attracts LEO constellation operators seeking elastic verification capacity. |
| Hardware Security Module Integration | End-to-end encryption mandates from ANSSI and ESA reshape ground segment interface requirements. |
| Threat-Replication Specialization Partnership | Electronic warfare training scenarios drive premium pricing for adaptive jamming capability vendors. |
Research Methodology
A spread of perspectives from Space Force procurement officers, satellite manufacturing engineers, RF test and measurement specialists, and constellation operator technical directors converged on the working assumptions for this analysis. Primary fieldwork combined structured interviews with defense contractor program managers and commercial telecommunications procurement leads. Secondary validation drew from FCC spectrum coordination filings, ESA procurement standard documentation, DoD cybersecurity framework releases, and NATO electronic warfare training protocol disclosures. Bottom-up demand modeling from individual constellation operator procurement events triangulated against top-down defense budget authorization analysis.
Segmentation dimensions modeled include technology architecture, application vertical, end-user type, and deployment model across the projection horizon. Hardware, software, hybrid, and cloud-based technology tiers combined with defense, telecommunications, aerospace, and research applications structured the analytical framework. CAGRs were derived from elasticity-adjusted procurement volume projections and technology substitution curves. Space Force modernization program timelines and LEO broadband constellation launch cadence served as primary forecast inputs alongside ITAR export control revision scenarios.
Material uncertainties — ITAR regulatory revisions, Taiwan semiconductor foundry supply disruptions, and NATO electronic warfare training protocol shifts — sit outside the modeled envelope. Forecasts reflect assumptions about defense procurement continuity and commercial constellation deployment velocity. Revision becomes warranted when GPU supply concentration or export control stringency crosses thresholds that fragment vendor addressable markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
RADAR Simulator Market
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Dynamic Flight Training Compartments Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
Military Simulation Virtual Training Market
Simulation and Training
Live Laser-Based Training and Simulation Platforms Market
Simulation and Training
Air Traffic Control Simulation and Training Market
Simulation and Training
Middle East Civil Aviation Flight Training and Simulation Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Flight Simulator Market
Simulation and Training
Drone Simulator Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Trainer Aircraft Market