
 Shotgun and Rifles Market | 2026-2036
Shotgun and Rifles Market Size, Share, and Industry Trends Forecast 2026-2036
Shotgun and Rifles Market Analytics
The National Firearms Act framework is recalibrating the cost-of-entry calculus for domestic manufacturers and importers alike. Savage Arms leverages its vertically integrated barrel production to sustain margin control across bolt-action and semi-automatic lines. Sturm, Ruger & Co anchors its position through dominant channel presence in the lever-action segment, while Sig Sauer differentiates via modular rifle architectures that appeal to tactical units and sport shooters.
Shotguns and rifles are shoulder-fired long guns engineered around specific action types, barrel configurations, and chamber specifications to propel metallic cartridges or shotshells with controlled ballistic performance. Break-action and pump-action shotguns retain structural dominance in hunting applications where reliability and field-serviceability outweigh rate-of-fire considerations. Semi-automatic platforms represent the fastest-expanding product category, driven by modular receiver designs and aftermarket customization demand that concentrates margin pools in accessory ecosystems rather than base firearms alone.
The Bureau of Alcohol, Tobacco, Firearms and Explosives enforces serialization, background check, and interstate transfer protocols that directly shape distribution topology and dealer network economics. State-level assault weapons restrictions and magazine capacity limits fragment product availability maps, compelling manufacturers to maintain SKU flexibility across compliant and non-compliant configurations. Stakeholders must monitor pending federal brace-rule litigation and state preemption battles that threaten to bifurcate compliance standards and channel strategies without legislative clarity.
Market Dynamics
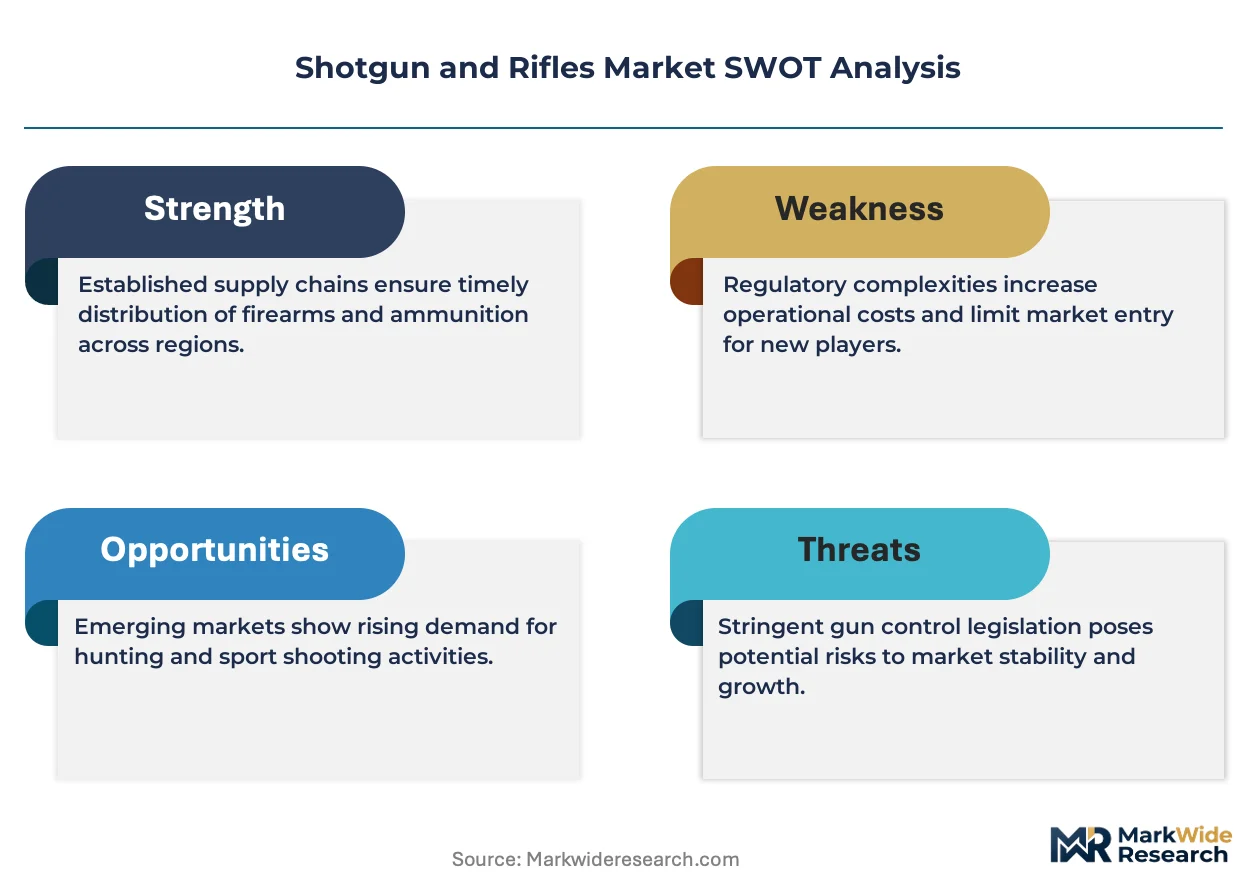
The National Firearms Act compliance burden is compressing manufacturer margins while simultaneously concentrating production among vertically integrated barrel forgers capable of absorbing serialized-component serialization costs.
Growth Catalysts
- Modular chassis architectures:Precision rifle builders are retrofitting legacy receivers with aftermarket aluminum bedding blocks. This extends platform lifecycles and drives recurring accessory revenue.
- ATF Form 4473 digital modernization:Streamlined background check processing reduces dealer inventory holding periods. Faster clearance times improve working capital velocity for FFL holders.
- Polymer stock injection molding:Glass-reinforced nylon compounds now match walnut dimensional stability at one-third unit cost. Manufacturers are shifting barrelled action production to polymer-integrated lines.
Market Restraints
- Chrome-molybdenum steel price volatility:Barrel blank feedstock costs swing with scrap metal commodity indices. Smaller forges lack hedging instruments to smooth input cost spikes.
- Import serialization bottlenecks:ATF import permit backlogs stretch lead times for Turkish and Italian shotgun manufacturers. Distribution networks face seasonal stockout risk ahead of waterfowl hunting windows.
- State-level magazine capacity fragmentation:California and New York capacity restrictions force SKU proliferation. Production runs split across compliant and standard configurations erode scale economies.
Strategic Opportunities
- Suppressor-integrated rifle platforms:Hearing Protection Act momentum would deregulate NFA Title II devices. Manufacturers are pre-positioning threaded-barrel SKUs for civilian expansion.
- 3D-printed receiver prototyping:Metal laser sintering compresses R&D cycles for boutique bolt-action designers. Rapid iteration capabilities lower capital barriers for market entry.
- Direct-to-consumer ammunition bundling:Subscription-based cartridge replenishment locks in recurring revenue. Precision shooters value matched lot consistency for load development.
Industry Challenges
- Master gunsmith talent scarcity:Action timing and headspacing expertise concentrates among retiring craftsmen. Vocational pipeline gaps threaten custom shop throughput.
- ITAR compliance documentation burden:Export-controlled technical data management requires dedicated compliance personnel. Smaller manufacturers face fixed cost absorption challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shotgun and Rifles Market |
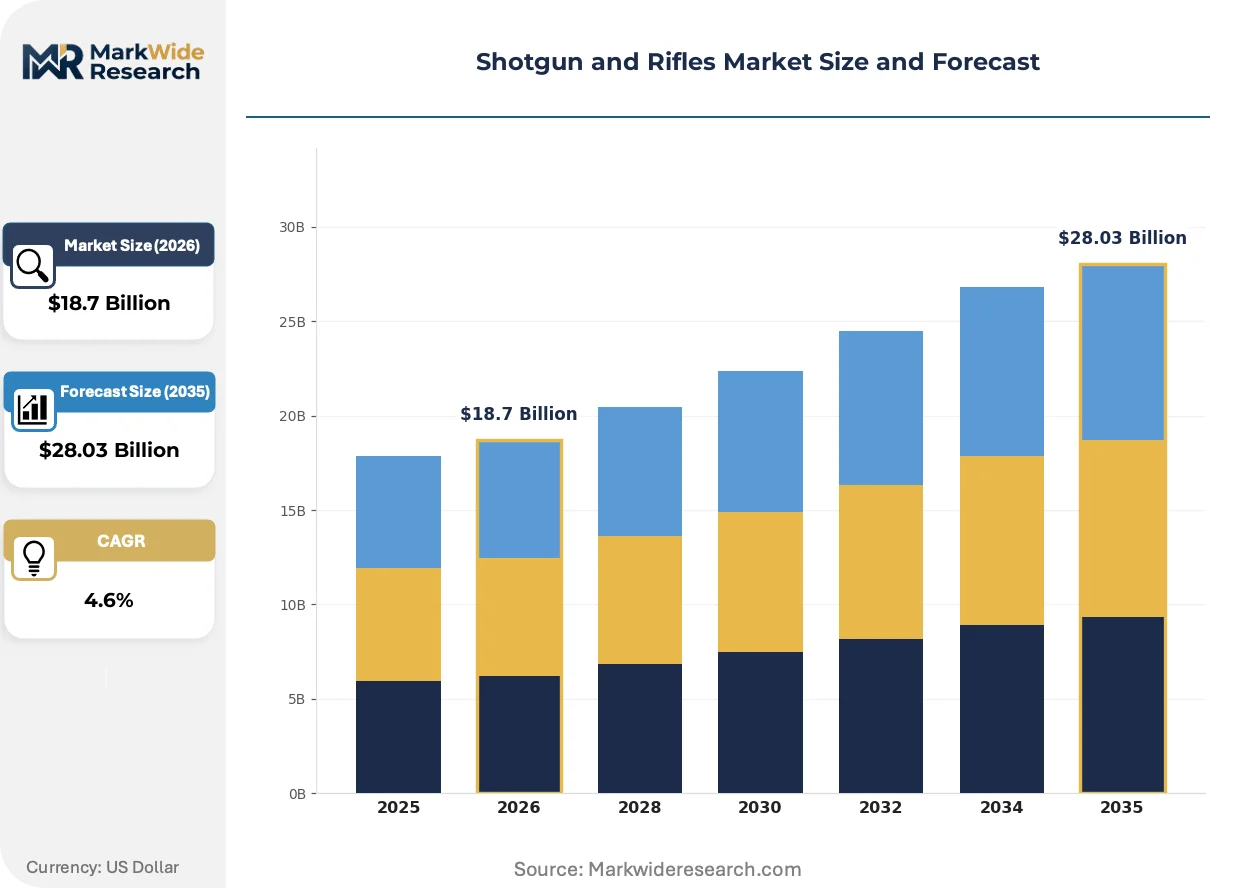
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Break Action, Pump Action, Bolt Action, Semi-Automatic, Lever Action Caliber: 12 Gauge, 20 Gauge, .22 LR, .308 Winchester, .223 Remington Application: Hunting, Sport Shooting, Law Enforcement, Military Training, Wildlife Control End User: Sportsmen, Security Agencies, Licensed Hunters, Tactical Units, Hunting Clubs |
| Companies Covered | Savage Arms, Henry Arms, Sturm, Ruger & Co, Beretta USA, Mossberg, Sig Sauer, Palmetto State Armory, Remington, Smith & Wesson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shotgun and Rifles Market Evolving Landscape
Receiver modularity is dissolving traditional boundaries between hunting, tactical, and competition platforms. Manufacturers now engineer around interchangeable component ecosystems rather than fixed-configuration product lines.
Carbon fiber-wrapped barrel technology is unifying previously separate performance tiers. Benchrest competitors and backcountry hunters alike are specifying tensioned carbon sleeves for weight reduction. This convergence is collapsing premium-tier pricing premiums that once separated match-grade from field-grade offerings.
ATF brace-rule litigation uncertainty is fragmenting pistol-stabilizing product strategies. Manufacturers face inventory stranding risk as federal district courts issue conflicting injunctions. Tactical-oriented lines are pivoting toward rifle-length configurations to preempt regulatory reclassification.
Buyers are consolidating purchases through shooting sports club collective procurement. League coordinators negotiate volume pricing for precision rifle series participants. This channel shift is compressing dealer markup capture in competitive shooting verticals.
Shotgun and Rifles Market Segmentation
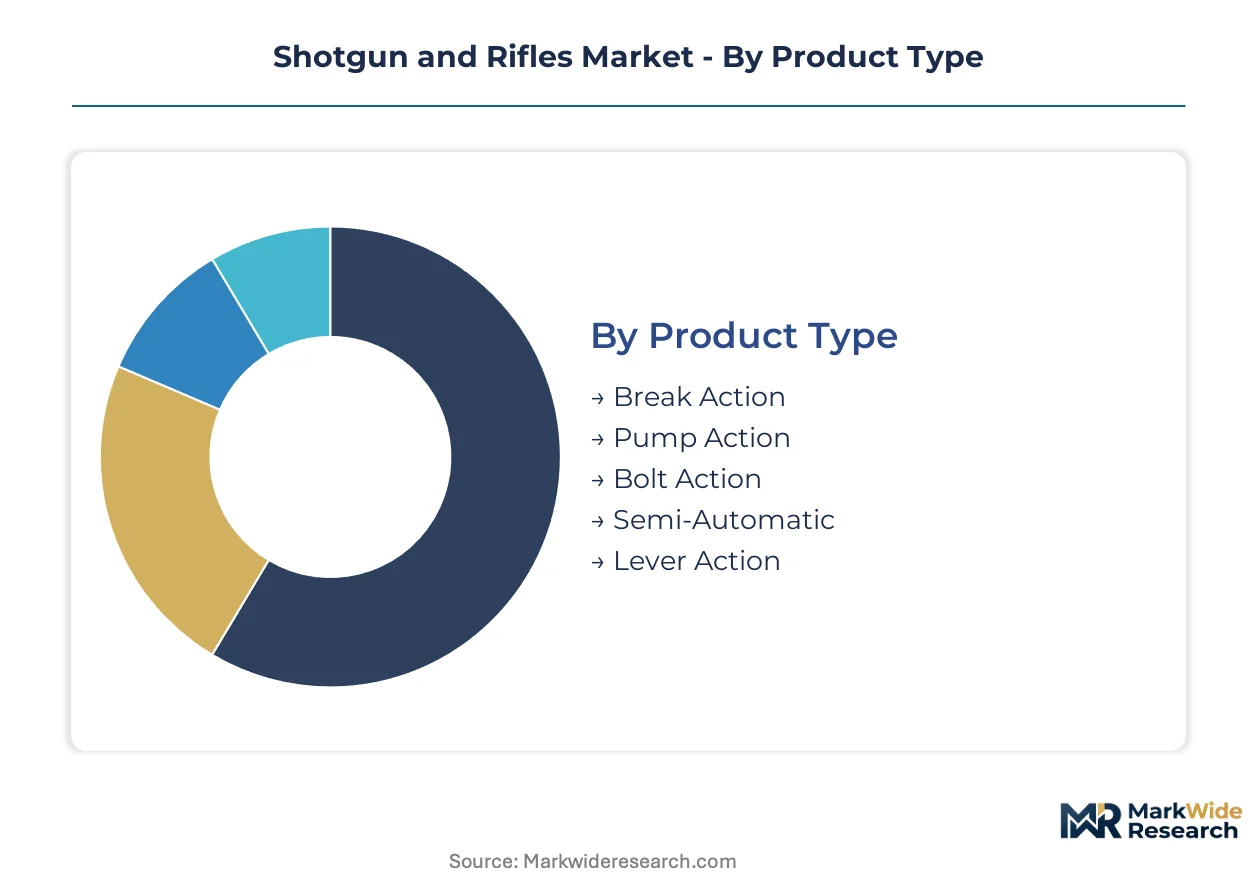
Long gun manufacturers engineer platform architectures around distinct action mechanisms, cartridge specifications, and user proficiency levels. Segmentation discipline determines which production lines absorb fixed tooling costs and which SKUs warrant modular component sharing across multiple end-use verticals.
Product Type:
Break-action and pump-action designs dominate standalone field applications where mechanical simplicity outweighs cycling speed, while semi-automatic and bolt-action platforms embed into precision shooting ecosystems with extensive aftermarket customization.
- Break Action:Hinged receivers expose the chamber for direct loading and immediate visual safety confirmation. Upland bird hunters in the United States specify these for instantaneous gauge switching between quail and pheasant loads.
- Pump Action:Sliding forend mechanisms eject and chamber rounds without gas-system complexity. Waterfowlers facing freezing marsh conditions prioritize this reliability over semi-automatic alternatives.
- Bolt Action:Rotating lugs lock the breech for exceptional headspace consistency. Precision rifle competitors and long-range hunters drive specification for aftermarket chassis compatibility.
- Semi-Automatic:Gas or recoil-operated cycling enables rapid follow-up shots. Three-gun competitors and tactical training programs absorb volume shipments of modular receiver configurations.
- Lever Action:Tubular magazines beneath the barrel feed rimmed cartridges through wrist-operated levers. Western heritage shooting sports and dense-woods deer hunters sustain legacy production lines.
Volume placements concentrate in pump-action field guns; the faster expansion belongs to semi-automatic modular platforms.
Caliber:
Cartridge selection stratifies across cost-per-shot economics, recoil tolerance curves, and terminal ballistic requirements for specific game weights or target distances.
- 12 Gauge:Standard bore diameter accepting heavy waterfowl and turkey payloads. Clay target leagues and migratory bird hunters in North American flyway states anchor procurement.
- 20 Gauge:Reduced bore diameter cuts recoil impulse for younger shooters and smaller-framed hunters. Upland bird enthusiasts and youth program coordinators specify these for training progression.
- .22 LR:Rimfire ignition delivers minimal report and ammunition cost. Appleseed marksmanship clinics and small-game trappers sustain high-volume consumption.
- .308 Winchester:Short-action cartridge balancing trajectory efficiency against barrel life. Precision rifle series competitors and military reserve training programs standardize on this chambering.
- .223 Remington:Intermediate cartridge optimized for varmint control and economical high-volume shooting. Predator hunters and high-power rifle competitors drive steady replacement demand.
12 Gauge and .308 Winchester absorb the heaviest shipment volumes; .22 LR climbs fastest through youth introduction programs and ammunition subscription services.
Application:
End-use context determines whether platforms require corrosion-resistant finishes, optic mounting interfaces, or compliance with specific jurisdiction restrictions on magazine capacity or barrel length.
- Hunting:Field deployment demands weatherproofing and optic compatibility for dawn and dusk visibility. Big-game and waterfowl seasons create concentrated procurement windows tied to licensing calendars.
- Sport Shooting:Competition rules dictate precision requirements and equipment divisions. National Rifle Association and precision rifle series match directors influence specification through equipment approval lists.
- Law Enforcement:Patrol and tactical units require reliability under duty-cycle stress. Municipal procurement officers prioritize manufacturer warranty terms and armorer training availability.
- Military Training:Reserve and cadet programs simulate service rifle handling without select-fire capability. Cost-conscious acquisition favors rimfire and intermediate cartridge platforms for marksmanship fundamentals.
- Wildlife Control:Agricultural and airport operators need immediate dispatch capability with reduced ricochet risk. Specialized ammunition compatibility shapes platform selection for non-lead projectile requirements.
Hunting and sport shooting concentrate the installed base; military training contracts expand most quickly through reserve component modernization.
End User:
Buyer sophistication and procurement authority create distinct channel requirements, from retail counter education for individual sportsmen to sole-source contracting for agency acquisition.
- Sportsmen:Individual enthusiasts research specifications through online communities and manufacturer content. Their purchase cycles align with tax refund timing and seasonal anticipation.
- Security Agencies:Private firms and government departments issue standardized platforms to armed personnel. Their procurement runs through competitive bidding with technical evaluation committees.
- Licensed Hunters:Permit holders must demonstrate safety certification and compliance with game regulations. State wildlife agency partnerships influence their equipment choices through hunter education curricula.
- Tactical Units:Specialized law enforcement and military elements require mission-configurable systems. Their acquisition flows through federal procurement vehicles with security clearance requirements.
- Hunting Clubs:Collective organizations negotiate volume pricing for member benefit. League coordinators aggregate demand for competitive shooting disciplines and property management.
Licensed hunters and individual sportsmen drive the highest unit volumes; security agencies and tactical units command premium pricing tiers through specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 81 corridor in Pennsylvania anchors North American shotgun and rifle manufacturing through clustered forges and federally licensed firearm manufacturers. This concentration attracts precision barrel producers and polymer stock molders seeking proximity to ATF compliance infrastructure.
United States
Recreational shooting culture and civilian firearm ownership sustain consistent procurement volumes across hunting and sport shooting verticals. The Bureau of Alcohol, Tobacco, Firearms and Explosives enforces serialization and interstate transfer protocols that shape dealer network economics. Pennsylvania's Lehigh Valley hosts vertically integrated barrel production facilities serving bolt-action and semi-automatic lines.
Germany
Precision engineering traditions support match-grade rifle exports to competitive shooting federations worldwide. The KBA (Kraftfahrt-Bundesamt) coordinates with federal police on firearm safety certifications affecting import specifications. Suhl's historic gunsmithing cluster now specializes in carbon fiber-wrapped barrel technology for weight-critical applications.
Italy
Artisanal shotgun manufacturers command premium positioning in upland bird hunting and clay target disciplines. ANVISA-equivalent health and safety frameworks intersect with EU CE marking requirements for sporting arms export. Brescia's Gardone Val Trompia valley concentrates family-owned forges producing break-action and over-under configurations.
Brazil
Expanding licensed hunter programs and agricultural wildlife control contracts drive shotgun demand from estate managers and rural cooperatives. ANVISA oversight of industrial chemical applications affects polymer stock compound formulations for domestic assembly. São Paulo state's Sorocaba region hosts assembly operations for South American distribution.
Canada
Remote wilderness hunting and indigenous wildlife management sustain bolt-action rifle procurement through provincial conservation authorities. Health Canada and PMRA regulate lead-free ammunition transitions affecting platform specifications for migratory bird hunting. Ontario's Kitchener-Waterloo corridor concentrates precision machining subcontractors serving US cross-border supply chains.
Shotgun and Rifles Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across action-type segments, creating a tiered structure where scale economies clash with craftsmanship premiums. Market concentration varies by product category: break-action shotguns favor heritage manufacturers with generational brand equity, while modular rifle platforms reward rapid design-cycle capabilities. Two strategic archetypes dominate—vertically integrated barrel forgers controlling input costs, and chassis-system integrators capturing accessory ecosystem margins. Competitive moves center on SKU proliferation for state-level compliance fragmentation and direct-to-consumer ammunition bundling to lock recurring revenue.
Within the heritage manufacturer tier, Beretta USA and Remington exemplify multi-generational brand positioning anchored in field-proven reliability narratives. Savage Arms occupies a position among vertically integrated specialists leveraging captive barrel production for margin control across bolt-action configurations. Sig Sauer sits within the modular architecture vector, representing the shift toward interchangeable component ecosystems that dissolve boundaries between tactical and sporting applications.
| Leading Market Players |
|---|
| Savage Arms |
| Henry Arms |
| Sturm, Ruger & Co |
| Beretta USA |
| Mossberg |
| Sig Sauer |
| Palmetto State Armory |
| Remington |
| Smith & Wesson |
| Others |
Value Network & Pricing Analysis
Master gunsmith concentration in the Lehigh Valley and Suhl gunsmithing clusters connects labor-cost differentials to three-tier spreads across custom, production, and entry-level long gun tiers.
Pricing Analysis
Lead-time premiums reward expedited delivery of serialized components through ATF-compliant distribution channels, while spot inventory of non-compliant configurations trades at discount. Pricing stratifies across premium, standard, and economy tiers based on barrel specification grade and aftermarket chassis compatibility. Cost compression in economy pump-action lines is intensifying because polymer stock injection molding transfers margin from wood suppliers to chemical compounders. Youth program coordinators and first-time buyers exhibit highest price sensitivity; tactical units and precision rifle competitors demonstrate lowest.
Supply Chain Analysis
Freight cost volatility from Italian and Turkish manufacturers through East Coast ports feeds into landed cost calculations for seasonal hunting inventory. Barrel blank production concentrates in the United States, Germany, and Italy; polymer stock molding clusters in Pennsylvania and São Paulo state. Chrome-molybdenum steel and glass-reinforced nylon compounds constitute critical input dependencies. Single-source vulnerability concentrates in Turkish shotgun forges facing ATF import permit backlogs. Distribution runs through federally licensed firearm dealers with ATF Form 4473 compliance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shotgun and rifles market is a vertical-integration race where captive barrel production and polymer compounding capabilities determine margin capture against commodity feedstock volatility.
For Market Incumbents: Acquire precision machining assets in the Interstate 81 corridor to secure barrel forging capacity ahead of chrome-molybdenum price spikes. Deepen in-house production of carbon fiber-wrapped barrel technology to preempt Suhl competitors. Consolidate dealer network relationships before ATF digital modernization shifts power toward direct-to-consumer ammunition bundlers. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier entry path around FFL dealer markup capture. White-space availability concentrates in rimfire trainer platforms for youth marksmanship programs and suppressor-integrated rifle configurations pending Hearing Protection Act momentum. Partner with shooting sports league coordinators for collective procurement volume aggregation. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists given carbon fiber barrel technology convergence collapsing premium-tier pricing premiums. Long-term viability favors manufacturers with captive polymer compounding and serialized-component serialization cost absorption. Monitor federal brace-rule litigation resolution as inflection indicator for pistol-stabilizing product inventory stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrel Forging | Captive chrome-molybdenum steel processing insulates margin from scrap metal commodity index swings. |
| Polymer Stock Compound Development | Glass-reinforced nylon formulation control transfers cost advantage from wood suppliers to chemical partners. |
| Suppressor-Ready Platform Pre-positioning | Threaded-barrel SKU development captures Hearing Protection Act deregulation upside in civilian expansion. |
| Direct-to-Consumer Ammunition Bundling | Subscription-based cartridge replenishment locks recurring revenue from precision shooters seeking lot consistency. |
| Carbon Fiber Barrel Technology Licensing | Tensioned carbon sleeve IP monetization unifies benchrest and backcountry hunter demand segments. |
Research Methodology
Independent corroboration across firearm manufacturer production executives, federally licensed dealer network operators, ATF compliance officers, and precision shooting league coordinators underwrites the qualitative findings. Secondary validation draws from ATF firearm commerce reports, Bureau of Labor Statistics occupational data for gunsmithing trades, and customs import records for Turkish and Italian shotgun shipments. Bottom-up shipment volume triangulation against top-down consumer expenditure surveys anchors the market sizing framework.
Comparable-period anchoring to historical production and import data establishes baseline trajectory calibration across the projection horizon. Segmentation modeling spans action mechanism, cartridge specification, end-use application, and buyer procurement authority dimensions. CAGRs derive from fitted trend extrapolation with elasticity adjustments for regulatory intervention scenarios. Forecast inputs incorporate seasonal hunting license issuance patterns and state-level magazine capacity restriction proliferation.
The model holds under stable NFA compliance cost structures; deviation in federal brace-rule litigation outcomes or chrome-molybdenum commodity spikes would shift volume and value trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Smart Bullets Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
Tank Ammunition Market
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Global Submarine Launched Missile Market
Weapons and Ammunition
Smart Bombs Market