
 Electromagnetic Weapons Market | 2026-2036
Electromagnetic Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Electromagnetic Weapons Market Analysis
Mil-spec power density thresholds is redrawing procurement criteria across the electromagnetic weapons landscape. Lockheed Martin Corporation leverages its Sandia National Laboratories partnerships to sustain pulsed-power breakthroughs. Raytheon Technologies anchors naval laser integration programs with the US Navy. Northrop Grumman Corporation specializes in airborne high-power microwave pod development for tactical aircraft.
Electromagnetic weapons generate and direct intense energy pulses—radio frequency, microwave, or particle streams—to disable electronics, intercept missiles, or neutralize threats without conventional explosives, with power outputs measured in megawatts and pulse durations in nanoseconds. High-Power Microwave systems dominate current procurement budgets due to their proven counter-electronics effectiveness against drone swarms. Laser Systems capture expanding naval deployment slots as shipboard integration matures, while Electromagnetic Railgun programs face funding redirection toward more compact directed-energy alternatives. Particle Beam research occupies specialized defense laboratory portfolios with longer development horizons.
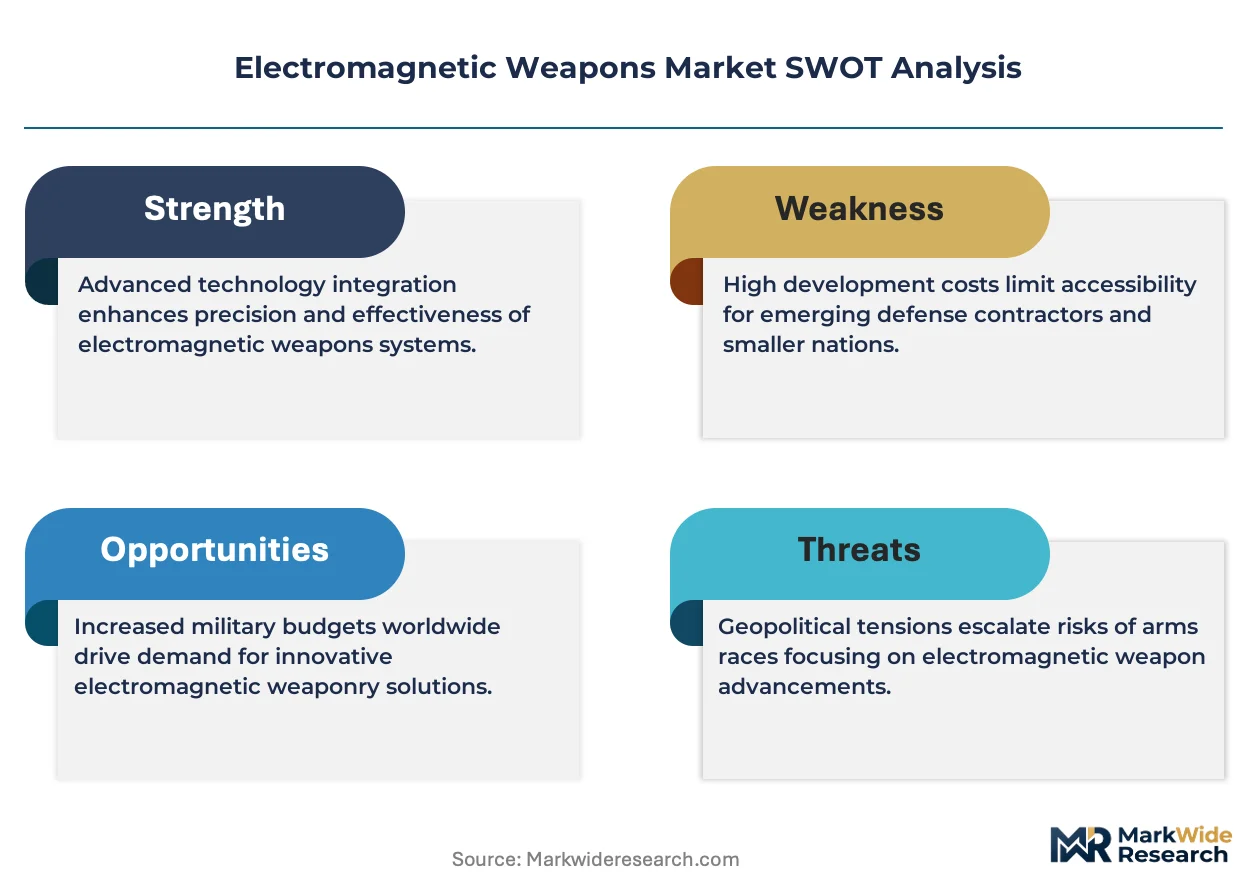
The US Department of Defense directs classification and operational standards through its Joint Directed Energy Transition Office, while NATO's electromagnetic environmental effects guidelines shape interoperability requirements for allied procurement. The US Congress mandates annual reporting on directed-energy readiness through National Defense Authorization Act provisions, compressing vendor qualification timelines. Stakeholders must monitor congressional appropriation shifts between service branches and assess which deployment platform—naval, aerial, or ground-based—secures sustained multi-year funding commitments.
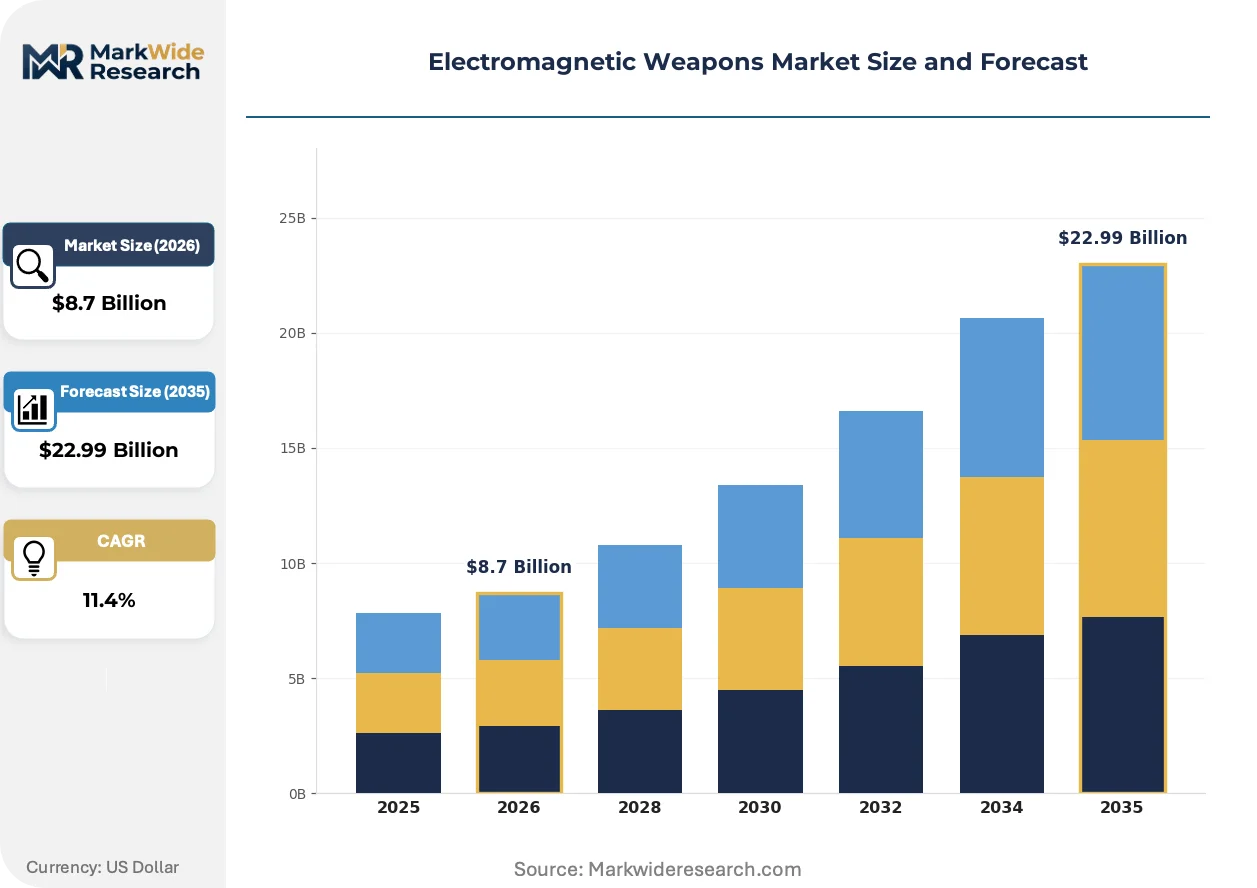
Market Dynamics
The Pentagon's rapid prototyping pathways are compressing vendor qualification timelines from years to months, forcing defense contractors to restructure engineering workflows around iterative test cycles rather than traditional waterfall development.
Growth Catalysts
- Directed-Energy Mandates:The US Congress mandates annual directed-energy readiness reporting through National Defense Authorization Act provisions, accelerating procurement cycles across all service branches.
- Drone Swarm Proliferation:Counter-electronics demand from naval and ground forces is pulling high-power microwave systems into active deployment faster than planned replacement schedules.
- Sandia National Laboratories Partnerships:Federally funded research facilities are transferring pulsed-power breakthroughs to prime contractors under streamlined technology transition agreements.
Market Restraints
- Capacitor Supply Concentration:High-energy density capacitor manufacturing concentrates among a handful of US and Japanese suppliers, creating single-source vulnerability for pulsed-power subsystems.
- Atmospheric Attenuation Limits:Laser weapon effectiveness degrades in maritime humidity and dust conditions, constraining operational envelopes for shipboard installations.
- ITAR Classification Friction:US International Traffic in Arms Regulations restrict component sharing with NATO allies, fragmenting supply chains for multinational platform integration.
Strategic Opportunities
- Ground-Based Air Defense Gaps:US Army mobile short-range air defense programs represent underpenetrated demand for vehicle-mounted high-power microwave systems.
- AI-Driven Targeting Convergence:Machine learning-enabled threat classification is merging with directed-energy fire control, enabling engagement decisions in under one millisecond.
- Congressional Earmark Expansion:Next-generation warfare system allocations in defense appropriations bills are creating multi-year funding pools outside traditional program-of-record channels.
Industry Challenges
- Pulsed-Power Engineering Talent Scarcity:Universities produce fewer plasma physicists and pulsed-power specialists than defense primes require, forcing costly in-house apprenticeship programs.
- Platform Integration Complexity:Electromagnetic weapons demand electrical system redesigns on existing naval vessels, requiring dry-dock availability that competes with hull maintenance schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electromagnetic Weapons Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: High-Power Microwave, Electromagnetic Railgun, Laser Systems, Particle Beam Application: Military, Defense, Law Enforcement, Research End User: Government, Private Security, Armed Forces, Research Institutions Deployment: Ground-Based, Naval, Aerial, Space-Based |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies, Northrop Grumman Corporation, BAE Systems, Boeing, Thales Group, General Atomics, L3Harris Technologies, Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electromagnetic Weapons Market Emerging Trajectories
Directed-energy weapons are transitioning from experimental demonstrators to program-of-record systems, with integration priorities shifting from raw power output to thermal management and beam control sophistication.
Solid-state laser arrays are miniaturizing shipboard footprint requirements while maintaining megawatt-class output. The US Navy's surface fleet is adopting these compact systems for close-in defense against anti-ship missiles. This compression is enabling installation on smaller hull classes previously excluded from directed-energy consideration.
The US Department of Defense's Joint Directed Energy Transition Office is harmonizing classification and operational standards across service branches. This coordination reduces redundant testing protocols and accelerates cross-platform technology transfer. Naval laser programs are the primary beneficiaries, gaining faster airworthiness certification through shared safety baselines.
Defense procurement officers are consolidating vendor relationships around primes capable of delivering integrated weapon systems rather than subcomponents. This concentration favors contractors with captive pulsed-power and beam control capabilities. The shift is most visible in Pentagon budgeting, where system-level contracts are displacing discrete technology development awards.
Electromagnetic Weapons Market Segmentation
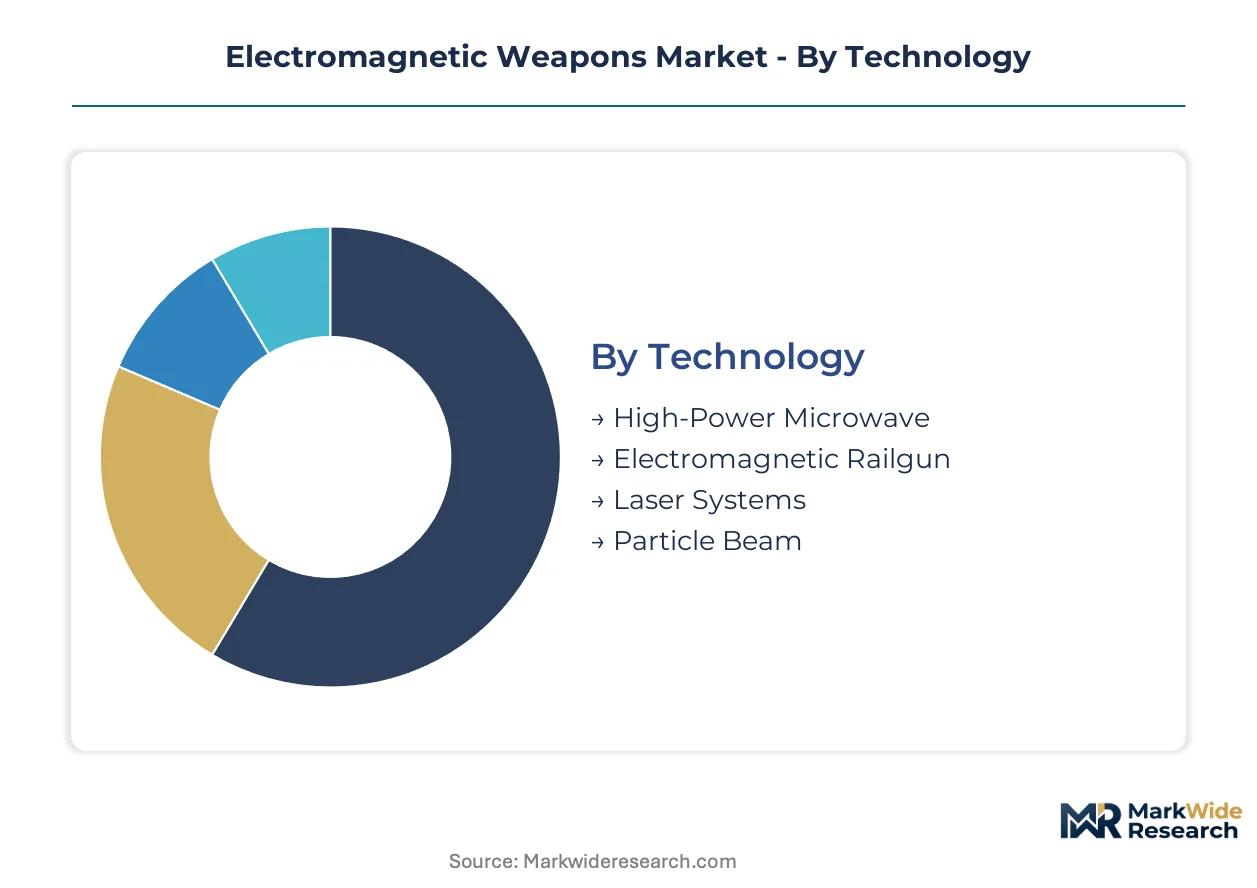
Technology differentiation in electromagnetic weapons determines procurement pathways, ITAR classification tiers, and platform integration complexity. Procurement officers segment investments by operational envelope, counter-electronics effectiveness, and power subsystem maturity.
Technology:
FCC spectrum allocation rules and Pentagon classification protocols create divergent commercialization timelines across directed-energy modalities.
- High-Power Microwave:Pulsed radio frequency emissions in gigawatt peaks disable unhardened electronics through front-door and back-door coupling. US Army mobile short-range air defense programs are pulling vehicle-mounted HPM systems into active procurement faster than planned replacement schedules, driven by drone swarm proliferation in contested logistics environments.
- Laser Systems:Solid-state and fiber laser arrays deliver continuous-wave or pulsed optical energy with precision targeting for missile interception. US Navy surface fleet adoption concentrates demand as shipboard thermal management and beam control systems mature for close-in defense against anti-ship missiles.
- Electromagnetic Railgun:Kinetic energy launch using Lorentz force acceleration of conductive projectiles without chemical propellants.
- Particle Beam:Charged or neutral particle streams for specialized deep-space or strategic applications with extended development horizons.
Established volume favors High-Power Microwave; emerging adoption favors Laser Systems.
Application:
Operational use case determines power output specifications, engagement rules of engagement, and congressional appropriation committee jurisdiction.
- Military:Tactical battlefield applications including counter-UAS, counter-missile, and counter-electronics missions requiring rapid retargeting and deep magazine capacity. Pentagon directed-energy readiness mandates through NDAA provisions are accelerating program-of-record transitions for operational units.
- Defense:Strategic homeland protection and critical infrastructure defense with longer engagement timelines and higher reliability requirements. Congressional earmarks for next-generation warfare systems are creating dedicated funding pools outside traditional service branch channels.
- Law Enforcement:Non-lethal area denial and vehicle or vessel stop capabilities with restricted power thresholds.
- Research:Federally funded laboratory demonstrators and university consortium programs advancing pulsed-power physics.
Defense commands the largest committed budgets; Military shows the steepest expansion trajectory.
End User:
Budget authority and classification clearance levels segment procurement access and vendor qualification requirements.
- Government:Civilian agency programs including border protection and critical infrastructure security with standardized federal acquisition regulation compliance.
- Private Security:Corporate and facility protection applications with restricted system capabilities and commercial export control limitations.
- Armed Forces:Uniformed service branch programs across Army, Navy, Air Force, and Marine Corps with joint operational requirements. The Joint Directed Energy Transition Office harmonizes standards across services, reducing redundant testing protocols and accelerating cross-platform technology transfer.
- Research Institutions:National laboratory and university partnerships under technology transition agreements with prime contractors.
Armed Forces dominate platform integration demand; Research Institutions anchor fundamental breakthrough pipelines.
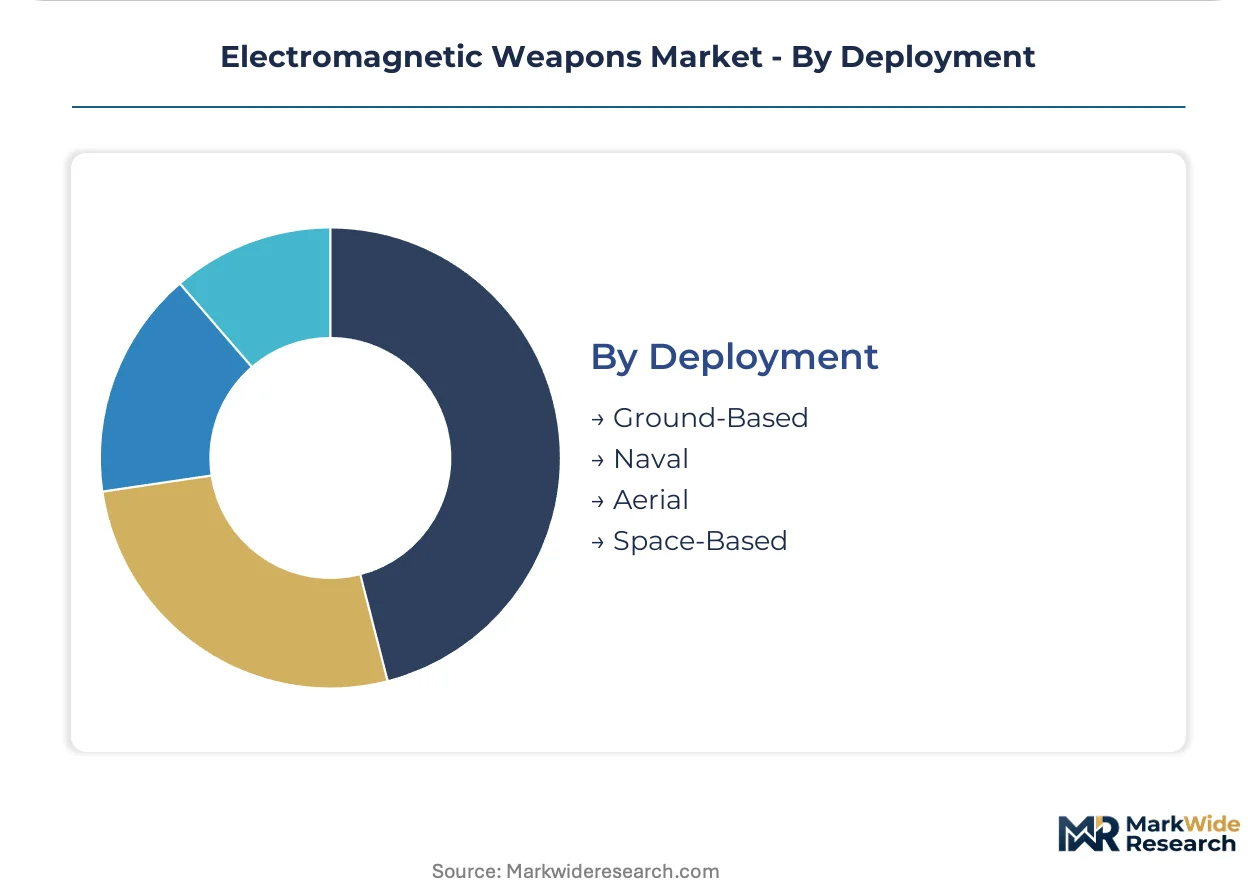
Deployment:
Platform constraints dictate power supply architecture, thermal management mass budgets, and atmospheric propagation compensation.
- Ground-Based:Fixed-site and mobile vehicle installations with access to substantial prime power and cooling infrastructure. US Army programs are consolidating around vehicle-mounted high-power microwave systems for maneuver force protection.
- Naval:Shipboard integration on surface combatants with dry-dock installation requirements competing against hull maintenance schedules. The US Navy's surface fleet is adopting solid-state laser arrays on smaller hull classes previously excluded from directed-energy consideration.
- Aerial:Tactical aircraft podded systems with severe mass and aerodynamic constraints requiring airborne high-power microwave development.
- Space-Based:Orbital platforms with vacuum propagation advantages and extreme thermal radiation challenges.
Naval deployment captures the most mature integration programs; Ground-Based systems are gaining share fastest as mobile short-range air defense gaps drive procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export controls on pulsed-power components concentrate supply among US and Japanese suppliers, while procurement demand clusters in NATO-aligned defense budgets. Import dependency for high-energy density capacitors creates vulnerability in European and Indo-Pacific assembly operations.
United States
Pentagon directed-energy readiness mandates through NDAA provisions accelerate service branch procurement cycles. The Joint Directed Energy Transition Office harmonizes classification standards across Army, Navy, and Air Force programs. Albuquerque's Sandia National Laboratories transfers pulsed-power breakthroughs to prime contractors under streamlined technology transition agreements.
United Kingdom
BAE Systems anchors domestic electromagnetic weapons development for naval laser integration programs. Ministry of Defence procurement aligns with NATO electromagnetic environmental effects guidelines for allied interoperability. Glasgow's shipbuilding cluster adapts dry-dock schedules to accommodate electrical system redesigns for directed-energy installation.
Germany
Rheinmetall AG drives counter-electronics research for European ground-based air defense gaps. Federal Office for Equipment, Information Technology and In-Service Support procurement follows EU defense fund coordination protocols. Bavaria's aerospace engineering concentration supports airborne high-power microwave pod development for tactical aircraft integration.
France
Thales Group specializes in naval combat system integration for directed-energy fire control architectures. Direction Générale de l'Armement procurement prioritizes solid-state laser miniaturization for smaller hull classes. Paris-Saclay research cluster advances AI-driven targeting convergence with millisecond engagement decision capabilities.
Israel
Rafael Advanced Defense Systems develops mobile high-power microwave systems for drone swarm defense in contested logistics environments. Ministry of Defense rapid prototyping pathways compress vendor qualification timelines from years to months. Tel Aviv's defense technology corridor concentrates pulsed-power engineering talent scarce across broader European markets.
Electromagnetic Weapons Market Vendor Landscape
Listed leaders compete with private specialists across prime contractor qualification tiers, concentrating procurement access among entities with captive pulsed-power capabilities. Market structure tilts toward system-level consolidation as Pentagon budgeting displaces discrete technology development awards. Three archetypes dominate: vertically integrated defense primes, federally partnered research contractors, and specialized subsystem suppliers. Competitive moves center on strategic partnerships with national laboratories and portfolio diversification into adjacent directed-energy modalities.
Within the prime contractor tier, Lockheed Martin Corporation and Raytheon Technologies exemplify the vertically integrated archetype, while Northrop Grumman Corporation occupies a position among federally partnered specialists. These entities anchor procurement consolidation as defense officers prioritize integrated weapon systems over subcomponent sourcing.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies |
| Northrop Grumman Corporation |
| BAE Systems |
| Boeing |
| Thales Group |
| General Atomics |
| L3Harris Technologies |
| Rheinmetall AG |
| Others |
Supply Flow & Price Mechanics
ITAR classification protocols gate both supplier qualification tiers and contract price differentiation simultaneously, forcing defense primes to absorb compliance overhead that fragments procurement access across NATO allies. Pentagon rapid prototyping mandates compress vendor onboarding timelines, concentrating pricing power among established contractors with captive pulsed-power capabilities.
Pricing Analysis
Armed Forces procurement officers anchor contract pricing around system-level awards displacing discrete technology development. Pricing stratifies across mil-spec certification tiers, pulse-power output thresholds, and platform integration complexity. Cost compression in naval laser programs intensifies as solid-state arrays miniaturize for smaller hull classes. Research Institutions exhibit highest price sensitivity due to fixed grant funding, while Pentagon program offices demonstrate lowest sensitivity given congressional earmark protection.
Supply Chain Analysis
United States and Japan anchor high-energy density capacitor manufacturing for pulsed-power subsystems. The electromagnetic weapons supply chain draws from specialized semiconductor foundries, precision optical component fabricators, and cryogenic cooling system producers. Single-source vulnerability concentrates in Japanese ceramic dielectric suppliers. Distribution runs through prime contractor integration facilities with direct-to-government contracting bypassing commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform integration complexity fragments vendor tiers, creating white-space opportunities as drone swarm proliferation demands faster counter-electronics deployment than incumbent timelines permit.
For Market Incumbents: Compound captive pulsed-power capabilities through Sandia National Laboratories partnership expansion, defending against emerging subsystem specialists capturing discrete technology awards. Accelerate thermal management R&D to offset atmospheric attenuation constraints degrading naval laser operational envelopes. Vertically integrate into high-energy density capacitor sourcing to neutralize Japanese supplier concentration risk. For New Entrants and Emerging Players: AI-driven targeting convergence represents the most penetrable service layer, with millisecond engagement decision algorithms underdeveloped across prime contractor portfolios. Target US Army mobile short-range air defense gaps where vehicle-mounted high-power microwave demand outpaces Lockheed Martin and Raytheon production capacity. Pursue technology transition agreements with Albuquerque national laboratories as primary go-to-market pathway. For Investors and Strategic Acquirers: NDAA directed-energy readiness reporting mandates reshape the acquisition landscape, elevating primes with program-of-record transitions over experimental demonstrator developers. Five-to-ten year viability favors vertically integrated contractors with naval, aerial, and ground-based platform certification across all three domains. Monitor congressional appropriation shifts between service branches as inflection signal for sustained multi-year funding commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration Certification | Joint Directed Energy Transition Office harmonization accelerates cross-service technology transfer for naval laser programs. |
| Pulsed-Power Partnership | Sandia National Laboratories agreements transfer breakthroughs to primes under streamlined technology transition protocols. |
| Capacitive Supply Diversification | Backward integration into high-energy density components neutralizes single-source vulnerability from Japanese suppliers. |
| AI Fire Control Convergence | Machine learning-enabled threat classification merges with directed-energy systems for sub-millisecond engagement decisions. |
| Congressional Earmark Positioning | Next-generation warfare system allocations outside traditional program-of-record channels create dedicated funding pools. |
Methodological Framework
Operator-level perspectives from Pentagon program officers, naval systems engineers, pulsed-power physicists, and congressional defense appropriation staff anchored the qualitative base. Primary interviews combined with secondary validation from NDAA provisions, FCC spectrum allocation records, and SEC contractor filings. Bottom-up platform deployment modeling triangulated against top-down congressional budget authorization analysis.
Sensitivity analysis tested forecast robustness across atmospheric attenuation scenarios, capacitor supply disruption events, and ITAR classification friction variations. Segmentation dimensions spanned technology modality, application mission profile, end-user budget authority tier, and deployment platform constraint. CAGRs derived from iterative test cycle compression rates and program-of-record transition velocities across the analysis window. Industry-specific inputs included directed-energy readiness mandate compliance timelines and dry-dock availability competition schedules.
Forecasts assume regulatory continuity in ITAR and NDAA provisions; material policy shifts would require re-modeling. Classification protocol changes or NATO electromagnetic environmental effects guideline revisions represent specific revision triggers. Recalibration cycles align with material shifts in congressional appropriation patterns and national laboratory technology transition agreement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Recoilless Rifle Market
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Directed Energy Weapons Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Nuclear Bombs and Missiles Market
Weapons and Ammunition
Military Helmet Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
US Small Caliber Ammunition Market