
 High Power Microwave Directed Energy Weapons Market | 2026-2036
High Power Microwave Directed Energy Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
High Power Microwave Directed Energy Weapons Market Analysis
The capability gap between prime contractors and emerging specialists is unwinding as venture-backed firms achieve fieldable power densities. Northrop Grumman Corporation leverages decades of radar transmitter heritage to dominate high-power vacuum tube architectures. Epirus Inc. competes with solid-state gallium nitride arrays that slash logistics footprints for expeditionary forces.
High power microwave directed energy weapons generate electromagnetic pulses in the gigawatt range to disrupt or damage electronic systems through front-door and back-door coupling. These systems typically operate between one and ten gigahertz with pulse widths from nanoseconds to microseconds, enabling non-kinetic defeat of drones, missiles, and sensors at speed-of-light engagement timelines. Mobile platforms now lead procurement volumes as militaries prioritize deployable counter-UAV coverage over fixed-site protection. Solid-state technology is capturing the fastest expansion trajectory, though vacuum tube systems still anchor margin pools in the highest-power tier where few suppliers possess hardened traveling-wave tube expertise.
The US Department of Defense shapes demand through Joint Directed Energy Transition Office roadmaps and congressional earmarks for operational prototyping. NATO standardization efforts under STANAG guidelines are beginning to align European member requirements, though procurement fragmentation persists. Stakeholders must monitor how export control revisions affect cross-border subsystem flows before committing to international supply arrangements.
Market Dynamics
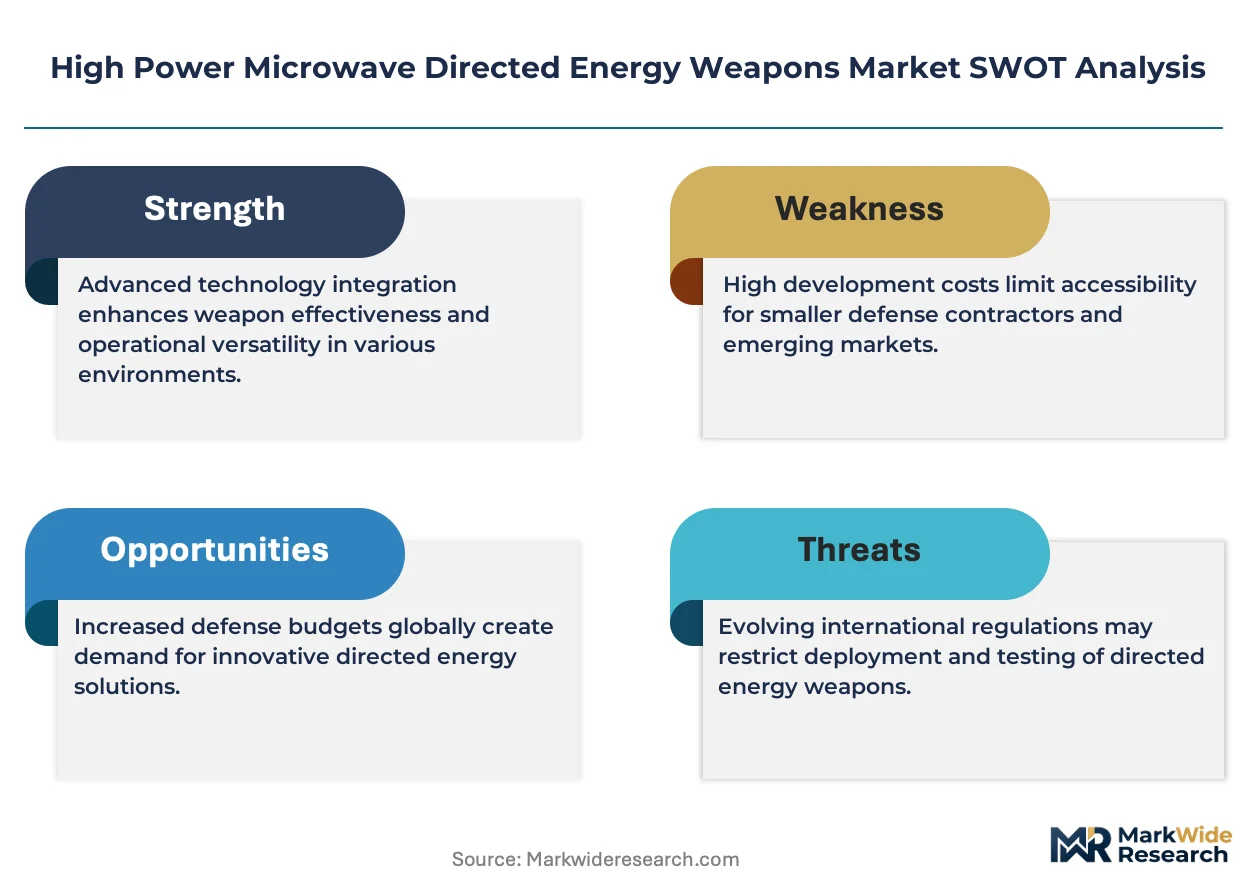
Solid-state gallium nitride transmitter architectures are compressing field deployment timelines for expeditionary forces while vacuum tube suppliers defend margin pools through hardened traveling-wave tube expertise that emerging competitors cannot replicate.
Growth Catalysts
- Joint Directed Energy Transition Office roadmaps:The US DoD's operational prototyping mandates accelerate field testing cycles and validate performance benchmarks for counter-UAV systems.
- Asymmetric aerial threat multiplication:Drone swarm tactics in contested airspace drive urgent procurement of speed-of-light engagement capabilities for mobile defense platforms.
- Solid-state thermal management advances:Reduced cooling burdens and lighter system weights enable helicopter and tactical vehicle integration previously impossible with legacy architectures.
Market Restraints
- Traveling-wave tube supply concentration:Hardened vacuum tube expertise resides with a handful of defense primes, creating single-source risk for highest-power tier systems.
- Export control friction:International Traffic in Arms Regulations and State Department licensing timelines delay cross-border subsystem flows for European and Indo-Pacific partners.
- Pulse power subsystem cost volatility:Specialized capacitor banks and modulator components face price instability from limited qualified suppliers.
Strategic Opportunities
- Expeditionary counter-UAV coverage gaps:Forward operating bases in Eastern Europe and the Pacific theater lack deployable high-power microwave protection against loitering munitions.
- NATO STANAG standardization alignment:Emerging interoperability guidelines create first-mover advantage for subsystem vendors who certify early against draft electromagnetic compatibility protocols.
- Dual-use energy storage convergence:Advances in electric vehicle battery thermal management transfer directly to pulsed power subsystem design for reduced logistics footprints.
Industry Challenges
- Electromagnetic effects modeling talent scarcity:Front-door and back-door coupling simulation expertise resides with aging government laboratory workforces and lacks university pipeline replenishment.
- Operational test and evaluation timeline compression:Congressional earmarks demand accelerated fielding while electromagnetic environmental effects certification requires extended anechoic chamber validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Power Microwave Directed Energy Weapons Market |
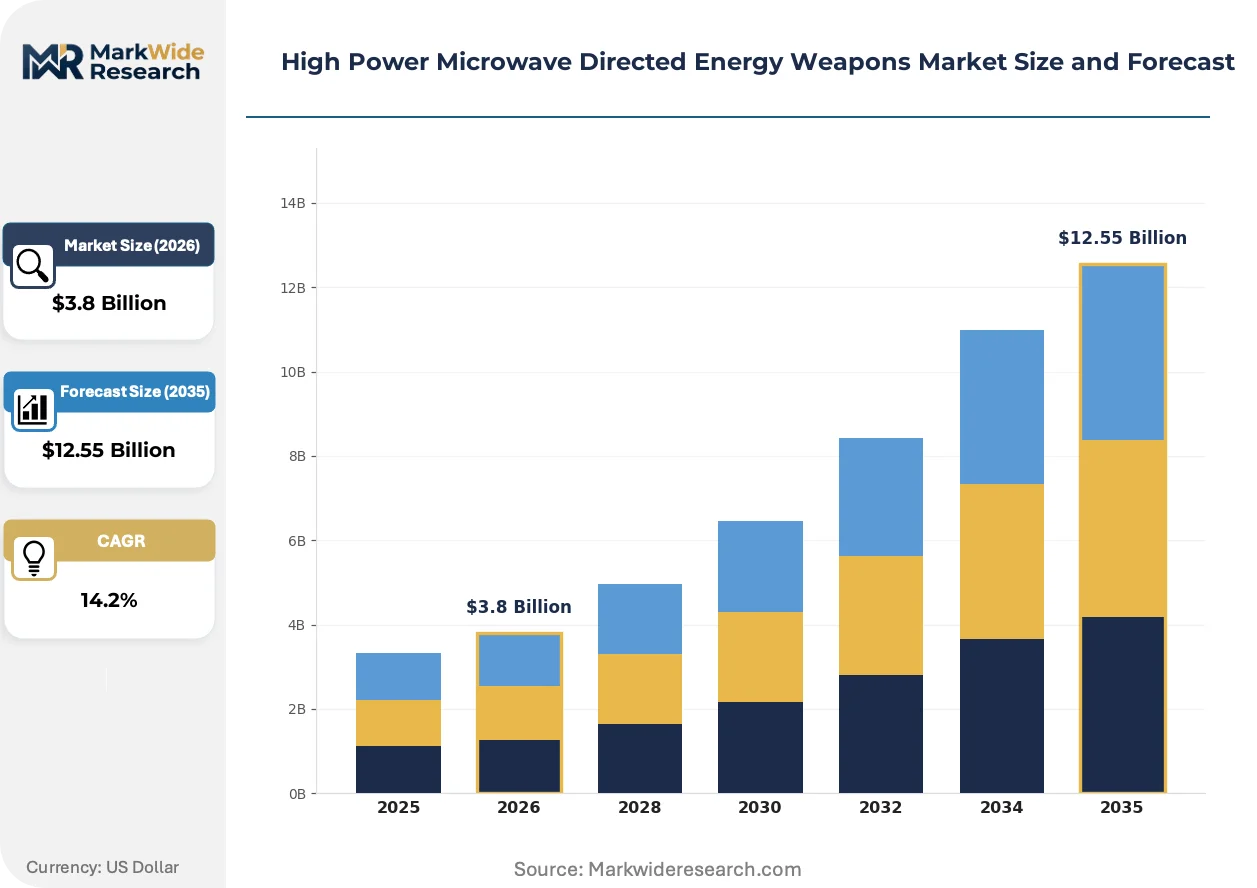
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Mobile, Shipborne Technology: Solid-State, Vacuum Tube, Pulsed, Continuous Wave End User: Military, Defense Contractors, Government Agencies, Research Institutions Application: Counter UAV, Anti-Drone, Personnel Dispersal, Equipment Disabling |
| Companies Covered | Northrop Grumman Corporation, Thales Group, Raytheon Technologies Corporation, Leidos Holdings Inc., L3Harris Technologies Inc., The Boeing Company, BAE Systems plc, Epirus Inc., Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Power Microwave Directed Energy Weapons Market Emerging Trajectories
Electromagnetic pulse delivery mechanisms are fragmenting across competing architectures as militaries weigh expeditionary mobility against raw power output for layered defense strategies.
Gallium nitride monolithic microwave integrated circuits are replacing silicon LDMOS in solid-state transmitter chains for higher power-added efficiency and wider instantaneous bandwidth. Naval surface warfare centers and expeditionary Marine units are piloting these arrays for shipboard and austere-base counter-UAV missions. The technology is bifurcating procurement into two distinct tiers: mobile solid-state systems for rapid deployment and fixed-site vacuum tube installations for area defense.
The US Department of Defense's electromagnetic spectrum superiority strategy imposes new hardening requirements on all fielded electronic warfare assets. This policy compresses design cycles for contractors who must now integrate resilience testing against high-power microwave threats into standard development protocols. Air Force Research Laboratory rapid capability offices are prioritizing these survivability standards for next-generation airborne platforms.
Defense procurement officers are unbundling system integration from subsystem supply, creating direct purchasing relationships with gallium nitride foundries and pulsed power component specialists. This disintermediation bypasses traditional prime contractor markups for established programs while requiring buyers to absorb integration risk. The Army's Rapid Capabilities and Critical Technologies Office exemplifies this behavioral shift through its direct awards to venture-backed directed energy firms.
High Power Microwave Directed Energy Weapons Market Segmentation
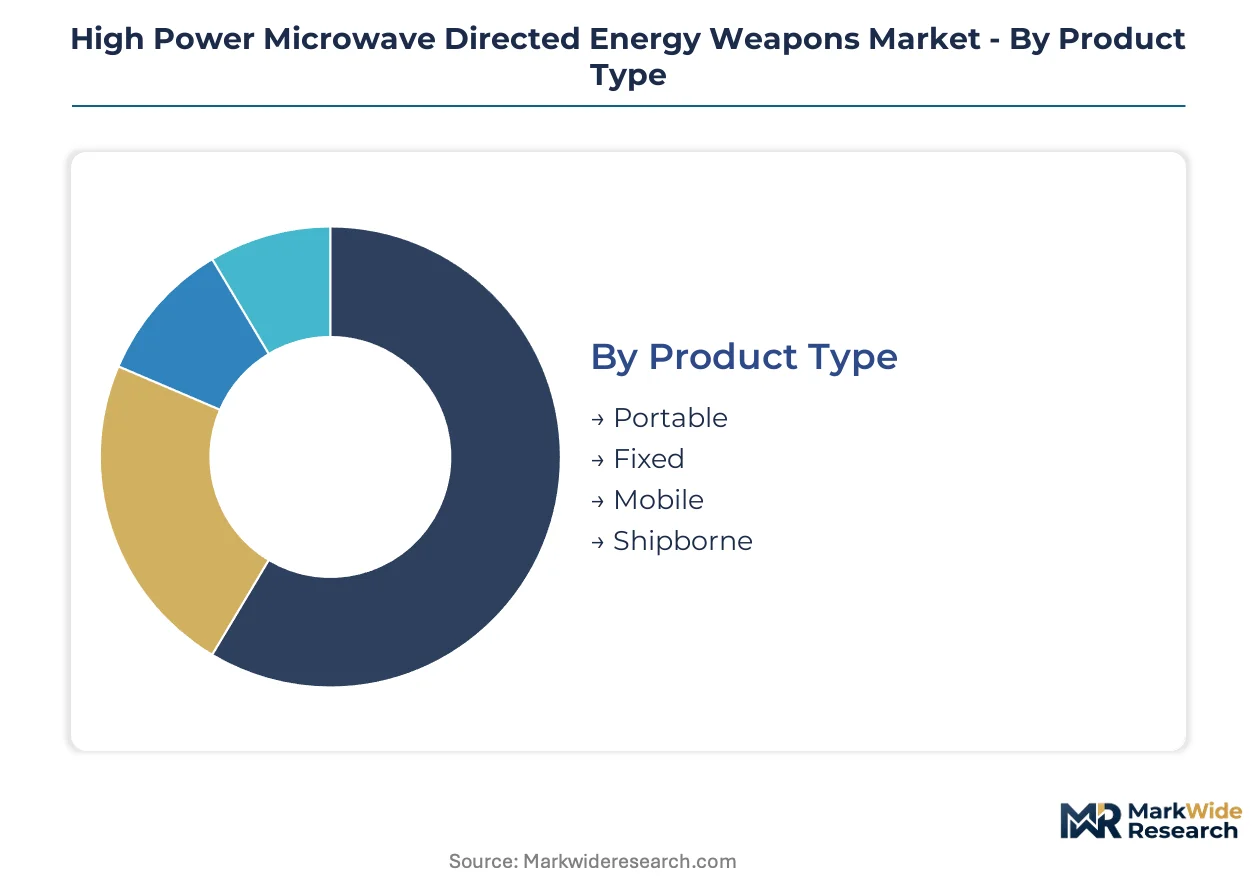
Procurement officers segment high power microwave directed energy weapons across four critical dimensions that determine operational deployment constraints and electromagnetic spectrum management requirements. Each segmentation axis carries distinct regulatory, technical, and logistical implications for acquisition budgeting.
Product Type:
FCC equipment authorization thresholds and FAA airspace coordination requirements create divergent compliance burdens across mobility tiers, with fixed installations facing localized zoning while portable and mobile systems trigger interstate transport regulations.
- Mobile:Tactical vehicle and helicopter-mounted systems integrate gallium nitride arrays with reduced cooling infrastructure. The US Army Rapid Capabilities and Critical Technologies Office prioritizes these platforms for Pacific theater counter-UAV coverage against loitering munitions, though electromagnetic environmental effects certification extends anechoic chamber validation timelines.
- Fixed:Permanent installations anchor area defense for critical infrastructure and forward operating bases with highest power output from vacuum tube architectures. Pentagon directed-energy budgets concentrate procurement here, with hardened traveling-wave tube expertise residing among a handful of defense primes.
- Portable:Man-portable units deliver expeditionary flexibility for dismounted forces in austere environments.
- Shipborne:Naval surface warfare centers pilot these arrays for fleet defense against drone swarms in contested maritime chokepoints.
Established volume favors Fixed; emerging adoption favors Mobile.
Technology:
Cost tier differentiation separates mature vacuum tube systems with proven gigawatt output from solid-state alternatives competing on logistics footprint and procurement price point.
- Solid-State:Gallium nitride monolithic microwave integrated circuits replace silicon LDMOS for higher power-added efficiency. Expeditionary Marine units and naval surface warfare centers drive demand for these arrays in shipboard and austere-base missions where thermal management advances reduce weight penalties.
- Vacuum Tube:Hardened traveling-wave tube architectures deliver gigawatt-range electromagnetic pulses through front-door and back-door coupling mechanisms. Margin pools concentrate here for highest-power tier systems where few suppliers possess replicated expertise.
- Pulsed:Nanosecond to microsecond pulse widths enable speed-of-light engagement timelines against electronic systems.
- Continuous Wave:Sustained emission modes suit personnel dispersal and sustained area denial applications.
Legacy procurement favors Vacuum Tube; steepest expansion trajectory belongs to Solid-State.
End User:
Customer type determines funding mechanism flexibility, with defense contractors accessing venture capital for rapid prototyping while government agencies navigate congressional appropriations cycles.
- Military:Joint Directed Energy Transition Office roadmaps operational prototyping mandates for counter-UAV systems across expeditionary and fixed-site missions. Operational test and evaluation timeline compression from congressional earmarks accelerates field testing cycles.
- Defense Contractors:Prime contractors and emerging specialists compete for subsystem supply relationships as procurement officers unbundle integration from component sourcing.
- Government Agencies:Homeland security and federal law enforcement explore dual-use applications within constrained budgets.
- Research Institutions:Air Force Research Laboratory rapid capability offices prioritize electromagnetic spectrum superiority strategy compliance for survivability standards development.
Current procurement concentration favors Military; emerging diversification targets Defense Contractors.
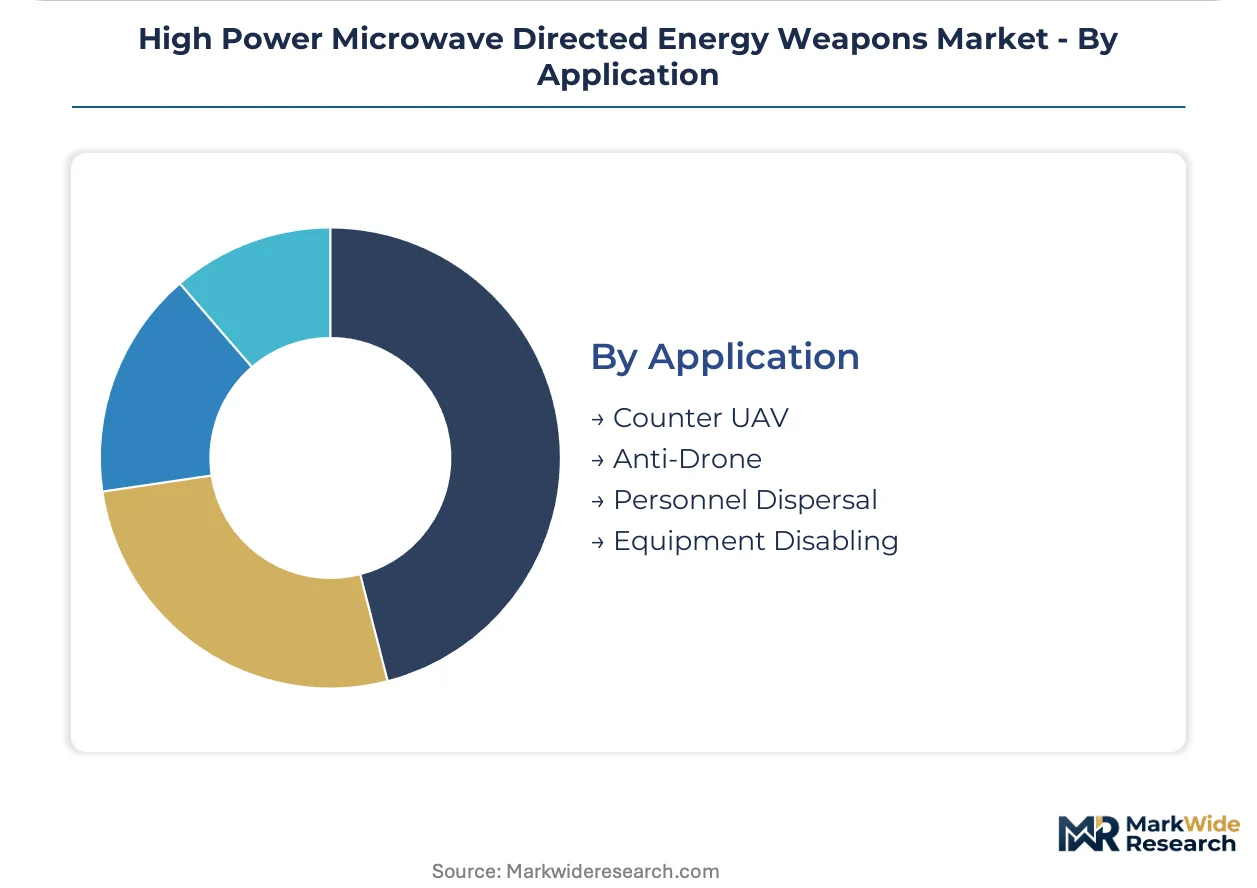
Application:
Application segmentation tracks mission profile urgency, with kinetic-threat defeat commanding priority funding over non-lethal personnel effects.
- Counter UAV:Drone swarm tactics in contested airspace drive urgent speed-of-light engagement capabilities. Asymmetric aerial threat multiplication concentrates procurement volumes here for layered defense strategies against loitering munitions.
- Anti-Drone:Overlapping technical requirements with Counter UAV but distinct rules of engagement for civilian airspace integration.
- Personnel Dispersal:Non-lethal crowd control applications face stricter electromagnetic exposure safety thresholds.
- Equipment Disabling:Electronic warfare applications target sensor and communication system disruption through front-door coupling mechanisms.
Defense urgency prioritizes Counter UAV; regulatory complexity constrains Personnel Dispersal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the least price sensitivity, absorbing premium costs for hardened vacuum tube systems, while European defense ministries face tighter procurement cycles under consolidated national budgets. Emerging specialists in Israel and South Korea compete aggressively on solid-state gallium nitride arrays, compressing margins for expeditionary platforms. Export licensing friction from ITAR regulations creates arbitrage opportunities for non-US suppliers in NATO standardization efforts.
United States
Pentagon directed-energy budgets concentrate procurement volumes for counter-UAV systems across fixed-site and mobile platforms. The Joint Directed Energy Transition Office mandates operational prototyping timelines that accelerate field testing cycles. Huntsville, Alabama and Albuquerque, New Mexico anchor defense contractor clusters where prime contractors integrate hardened traveling-wave tube expertise with emerging solid-state specialists.
Israel
Asymmetric threat exposure from regional drone deployments drives urgent demand for speed-of-light engagement capabilities in layered air defense. The country's national defense regulator prioritizes electromagnetic spectrum superiority standards for survivability certification. Tel Aviv and Haifa metropolitan areas concentrate venture-backed directed energy firms competing on gallium nitride array miniaturization for expeditionary forces.
United Kingdom
Ministry of Defence procurement officers navigate congressional-style appropriations constraints while pursuing NATO STANAG interoperability alignment. REACH and RoHS regulations constrain subsystem material sourcing for European supply arrangements. The Defence Science and Technology Laboratory at Porton Down coordinates electromagnetic environmental effects testing with Farnborough aerospace clusters for anechoic chamber validation protocols.
Germany
Bundeswehr modernization programs prioritize deployable counter-UAV coverage for Eastern European forward operating bases under NATO collective defense commitments. The KBA and federal procurement office impose extended electromagnetic compatibility certification timelines. Munich and Stuttgart industrial corridors concentrate automotive-battery thermal management expertise transferable to pulsed power subsystem design for reduced logistics footprints.
South Korea
Agency for Defense Development roadmaps emphasize indigenous solid-state transmitter development to reduce dependency on US vacuum tube imports. The MFDS and national standards body coordinate dual-use energy storage convergence from electric vehicle supply chains. Seoul Capital Area and Busan-Ulsan manufacturing belts integrate gallium nitride foundry capacity with naval surface warfare center requirements for fleet defense against drone swarms.
High Power Microwave Directed Energy Weapons Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with prime contractors defending margin pools through hardened traveling-wave tube expertise that emerging competitors cannot replicate. The specialist tier captures fastest expansion on solid-state gallium nitride architectures competing for expeditionary counter-UAV procurement. Three archetypes define positioning: heritage radar transmitter primes, venture-backed solid-state disruptors, and diversified aerospace conglomerates with captive directed energy divisions. Competitive moves concentrate on unbundling subsystem supply from integration to bypass traditional markups, and backward integration into gallium nitride foundry capacity to secure component availability.
Within the heritage prime tier, Northrop Grumman Corporation and Raytheon Technologies Corporation exemplify decades-long radar transmitter heritage applied to high-power vacuum tube dominance. Among venture-backed specialists, Epirus Inc. occupies a position representing solid-state gallium nitride array disruption for reduced logistics footprints. The Boeing Company and Lockheed Martin Corporation anchor the diversified aerospace conglomerate archetype, integrating directed energy capabilities within broader defense portfolios. BAE Systems plc and Thales Group represent European-based alternatives navigating NATO standardization requirements outside ITAR constraints. L3Harris Technologies Inc. and Leidos Holdings Inc. sit within the systems integration specialist tier, competing for disintermediated subsystem supply relationships as procurement officers bypass traditional prime contractor channels.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Thales Group |
| Raytheon Technologies Corporation |
| Leidos Holdings Inc. |
| L3Harris Technologies Inc. |
| The Boeing Company |
| BAE Systems plc |
| Epirus Inc. |
| Lockheed Martin Corporation |
| Others |
Supply Flow & Price Mechanics
ITAR licensing timelines and electromagnetic environmental effects certification gates both supply qualification and price differentiation, forcing buyers to absorb premium costs for pre-cleared subsystems while vendors stratify offerings around anechoic chamber validation status.
Pricing Analysis
After-sales service contracts for traveling-wave tube replacement and gallium nitride array recalibration drive lifetime value in this market. Three-tier pricing structure across expeditionary-mobile, fixed-site-area-defense, and portable-dismounted tiers separates buyers by cooling infrastructure requirements and power output specifications. Cost compression in solid-state transmitter chains is intensifying because gallium nitride foundry capacity expansion reduces component scarcity premiums. Defense contractors exhibit the least price sensitivity, absorbing hardened system premiums, while research institutions face the tightest budget constraints.
Supply Chain Analysis
Extended lead times for specialized capacitor banks and modulator assemblies compress procurement flexibility for expeditionary programs. Component sourcing concentrates in the United States for pulsed power subsystems, in South Korea for gallium nitride monolithic microwave integrated circuits, and in Germany for automotive-derived thermal management systems. Manufacturing draws from hardened traveling-wave tube foundries, high-voltage capacitor specialists, and anechoic chamber calibration facilities. Single-source vulnerability sits with traveling-wave tube suppliers where decades of radiation-hardening expertise cannot replicate quickly. Distribution runs through prime contractor integration channels and direct awards from rapid capability offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through ITAR-controlled technology and electromagnetic environmental effects certification creates switching costs that lock buyers into qualified supplier relationships.
For Market Incumbents: Secure backward integration into gallium nitride foundry capacity to neutralize emerging solid-state disruptors threatening vacuum tube margin pools. Harden traveling-wave tube supply agreements with multi-year sole-source contracts before NATO STANAG standardization opens European procurement to non-US alternatives. For New Entrants and Emerging Players: Differentiate on expeditionary logistics footprint by miniaturizing gallium nitride array thermal management for helicopter and tactical vehicle integration. Target Pacific theater forward operating bases where deployable counter-UAV coverage gaps outpace incumbent fielding timelines. Pursue direct subsystem supply relationships with Army Rapid Capabilities and Critical Technologies Office to bypass prime contractor markups. For Investors and Strategic Acquirers: NATO STANAG standardization reshapes the acquisition landscape by creating certification arbitrage opportunities for European-based suppliers outside ITAR constraints. Long-term viability centers on dual-use energy storage convergence from electric vehicle battery thermal management transferable to pulsed power design. Acquisition target archetype: venture-backed solid-state specialists with fieldable power densities and existing electromagnetic environmental effects validation. Monitor export control revision announcements as the primary inflection signal for cross-border subsystem flow viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gallium Nitride Foundry Capacity | Captive supply of monolithic microwave integrated circuits neutralizes emerging competitor component access. |
| Electromagnetic Environmental Effects Certification Investment | Anechoic chamber validation protocols lock in buyer switching costs for hardened system procurement. |
| Direct Award Relationship with Rapid Capability Offices | Bypass of traditional prime contractor channels captures disintermediated subsystem supply margins. |
| NATO STANAG Standardization Alignment | Early certification against draft electromagnetic compatibility protocols creates first-mover advantage in European procurement. |
| Dual-Use Energy Storage Technology Licensing | Transfer of electric vehicle battery thermal management to pulsed power subsystems reduces expeditionary logistics footprints. |
Methodological Framework
A spread of perspectives from program managers at rapid capability offices, electromagnetic environmental effects test engineers, gallium nitride foundry operations directors, pulsed power subsystem procurement leads, and traveling-wave tube manufacturing specialists converged on the working assumptions. Primary interview insights triangulated against secondary sources including Pentagon budget justification documents, Joint Directed Energy Transition Office roadmaps, FCC equipment authorization filings, and SEC 10-K disclosures from defense primes. Bottom-up build from subsystem component flows and top-down validation against congressional appropriations cycles anchored the quantitative framework.
Segmentation dimensions modeled span mobility tier, transmitter architecture, end-user funding mechanism, and mission application profile across the projection horizon. CAGRs derived from deployment timeline assumptions for counter-UAV systems and solid-state technology substitution rates. Industry-specific forecast inputs incorporated electromagnetic spectrum superiority strategy compliance deadlines and expeditionary platform integration weight thresholds.
Material uncertainties — export control revision timing, traveling-wave tube supplier consolidation, and gallium nitride foundry yield improvements — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Global Ammunition Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Military Helmet Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market