
 Nuclear Bombs and Missiles Market | 2026-2036
Nuclear Bombs and Missiles Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Bombs and Missiles Market Analysis
Strategic deterrence procurement is bifurcating between peer-competitor modernization and asymmetric counter-proliferation missions. Lockheed Martin dominates sea-based delivery systems through its Trident II D5LE program and leverages vertical integration in solid-rocket motor production. Raytheon Technologies sustains dominance in ballistic missile defense interceptors and specializes in kill-vehicle guidance architectures for midcourse engagement.
Nuclear bombs and missiles comprise fission-fusion warheads paired with precision-guided delivery vehicles engineered to specific yield-to-weight ratios and circular error probable tolerances. These systems serve national strategic deterrence and extended assurance commitments under mutual defense treaties. Ballistic missiles occupy the largest value pool given their intercontinental range and MIRV complexity, while cruise missiles represent the fastest-growing segment due to hypersonic glide vehicle integration and reduced radar cross-section requirements. Guidance systems command premium margins as GPS-denied navigation and stellar-inertial hybrids displace legacy architectures.
The US Department of Defense, Russia's Ministry of Defense procurement arm, and China's Central Military Commission Equipment Development Department each enforce distinct warhead certification protocols that shape supplier qualification and technology transfer boundaries. The US Nuclear Regulatory Commission and Department of Energy's National Nuclear Security Administration jointly govern plutonium pit production standards that constrain supply-side expansion. Stakeholders must monitor fissile material stockpile stewardship commitments and emerging hypersonic test-ban diplomacy to anticipate program acceleration or contraction.
Market Dynamics
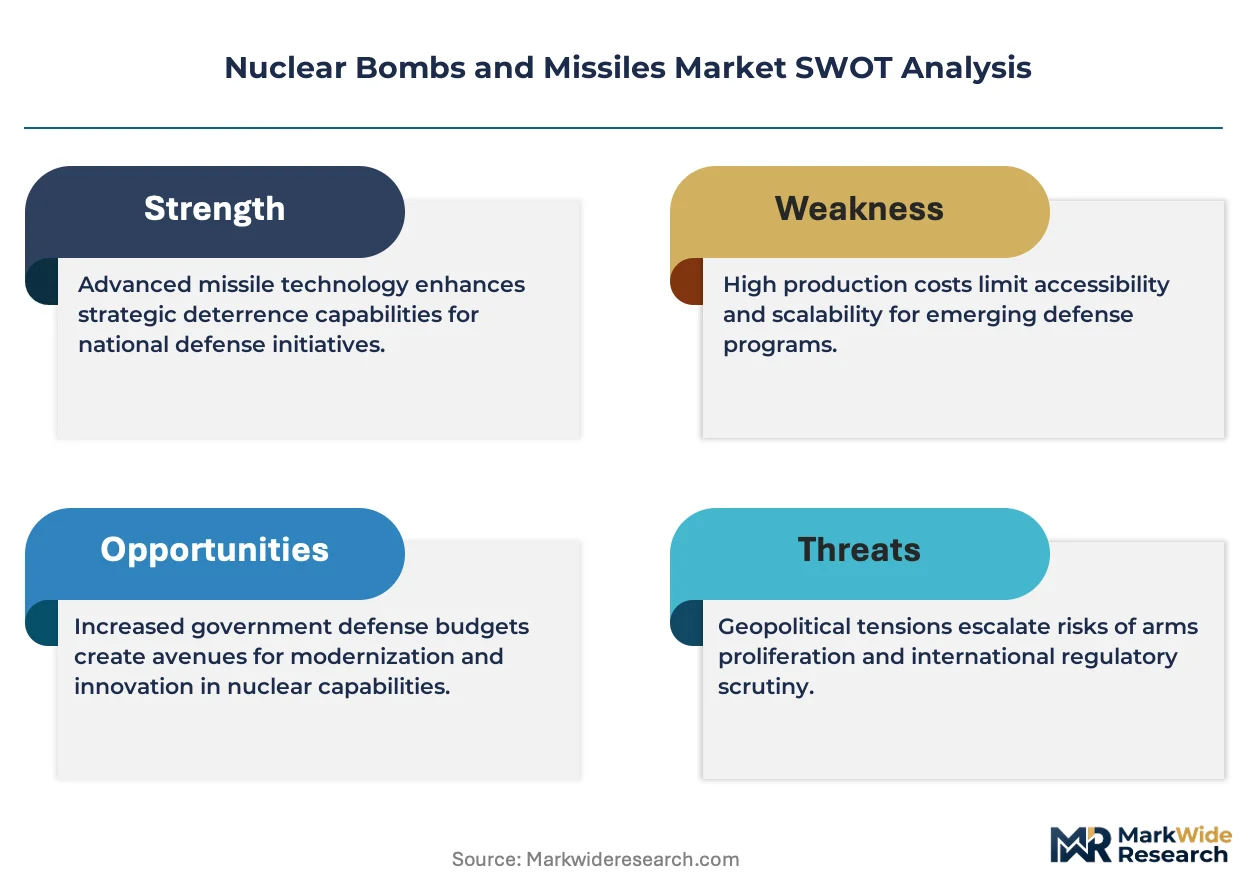
Hypersonic glide vehicle integration is compressing development timelines across strategic delivery platforms. Weapon systems must now achieve Mach 5+ terminal velocities while maintaining maneuverability against layered missile defense architectures.
Growth Catalysts
- US Nuclear Modernization Roadmap:The Department of Energy's warhead life-extension programs sustain demand for plutonium pit production and tritium harvesting infrastructure.
- Submarine-Launched Ballistic Missile Recapitalization:Columbia-class ballistic missile submarine procurement drives multi-decade contracts for solid-rocket motor and guidance system suppliers.
- Extended Deterrence Commitments:NATO's nuclear sharing arrangements and Indo-Pacific bilateral security treaties sustain forward-deployment requirements for tactical gravity bombs.
Market Restraints
- Plutonium Pit Production Bottleneck:Los Alamos National Laboratory remains the sole certified US facility for weapons-grade pit manufacturing, constraining warhead refurbishment throughput.
- Highly Enriched Uranium Feedstock Concentration:Downblending of Cold War stockpiles limits fresh fissile material availability for new warhead designs.
- International Test Moratorium Compliance:The Comprehensive Nuclear-Test-Ban Treaty framework restricts full-yield validation, forcing reliance on subcritical experiments and computational modeling.
Strategic Opportunities
- Hypersonic Cruise Missile Convergence:Scramjet propulsion integration with reduced radar cross-section airframes opens new mission profiles for prompt global strike.
- UK Trident Successor Program:The Dreadnought-class submarine build sustains transatlantic supply chain continuity for pressurized water reactor and missile tube suppliers.
- Stellar-Inertial Guidance Hybridization:Astro-trackers paired with ring laser gyroscopes enable GPS-denied navigation for contested electromagnetic environments.
Industry Challenges
- Weapons Physicist Talent Pipeline:The National Nuclear Security Administration competes with commercial fusion energy ventures for neutron transport and hydrodynamics specialists.
- Legacy System Integration Complexity:Minuteman III silo infrastructure dating to the 1960s requires bespoke engineering to accommodate Sentinel ICBM command-and-control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Bombs and Missiles Market |
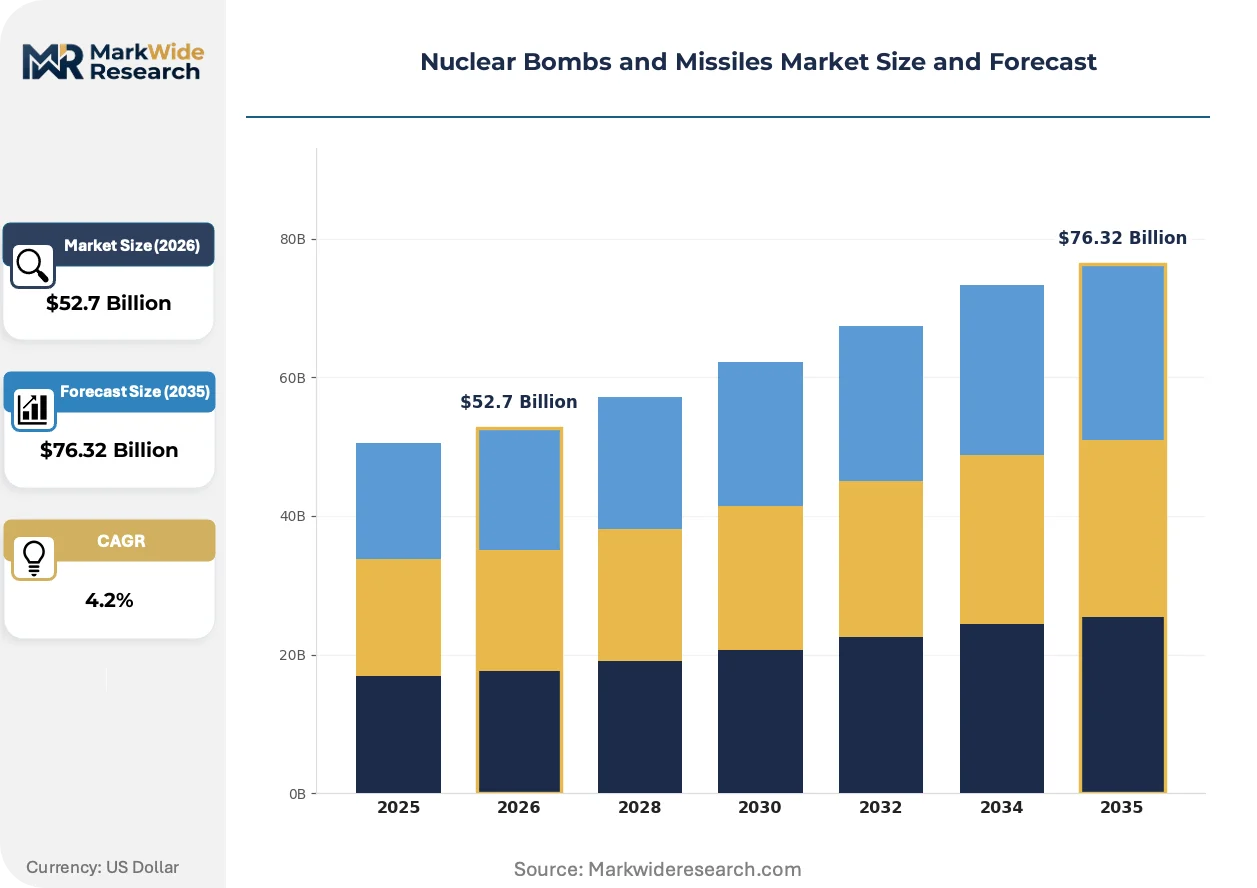
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $76.32 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Missiles, Cruise Missiles, Tactical Nuclear Weapons, Strategic Nuclear Weapons Deployment Mode: Land-based, Sea-based, Air-launched, Mobile Platforms End User: Military, Government, Defense Contractors, Research Institutions Technology: Guidance Systems, Propulsion Systems, Warhead Technology, Communication Systems |
| Companies Covered | Lockheed Martin, Raytheon Technologies, Northrop Grumman, BAE Systems, MBDA, Boeing, Thales, Rafael Advanced Defense Systems, General Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Bombs and Missiles Market Emerging Trajectories
Warhead miniaturization and precision-strike accuracy are converging to enable lower-yield options with comparable strategic effect. Delivery platform diversification is fragmenting traditional triad procurement concentration.
Solid-fuel ramjet propulsion is displacing liquid-fuel sustainer stages in cruise missile architectures. China's Central Military Commission Equipment Development Department has accelerated adoption of boron-fueled ramjets for anti-ship variants. This propulsion shift is displacing turbofan-dependent designs in contested airspace penetration missions.
The US Department of Energy's Stockpile Responsiveness Program mandates accelerated warhead design-to-certification cycles. This compresses traditional decade-long development timelines into five-year windows. The W93 warhead program represents the first full-scale implementation of this accelerated framework.
France's Direction Générale de l'Armement now requires modular warhead architectures supporting yield-selectable configurations. Procurement officers prioritize platforms accommodating multiple mission sets without physical reconfiguration. This specification pattern is most visible in the ASN4G air-launched cruise missile program.
Nuclear Bombs and Missiles Market Segmentation
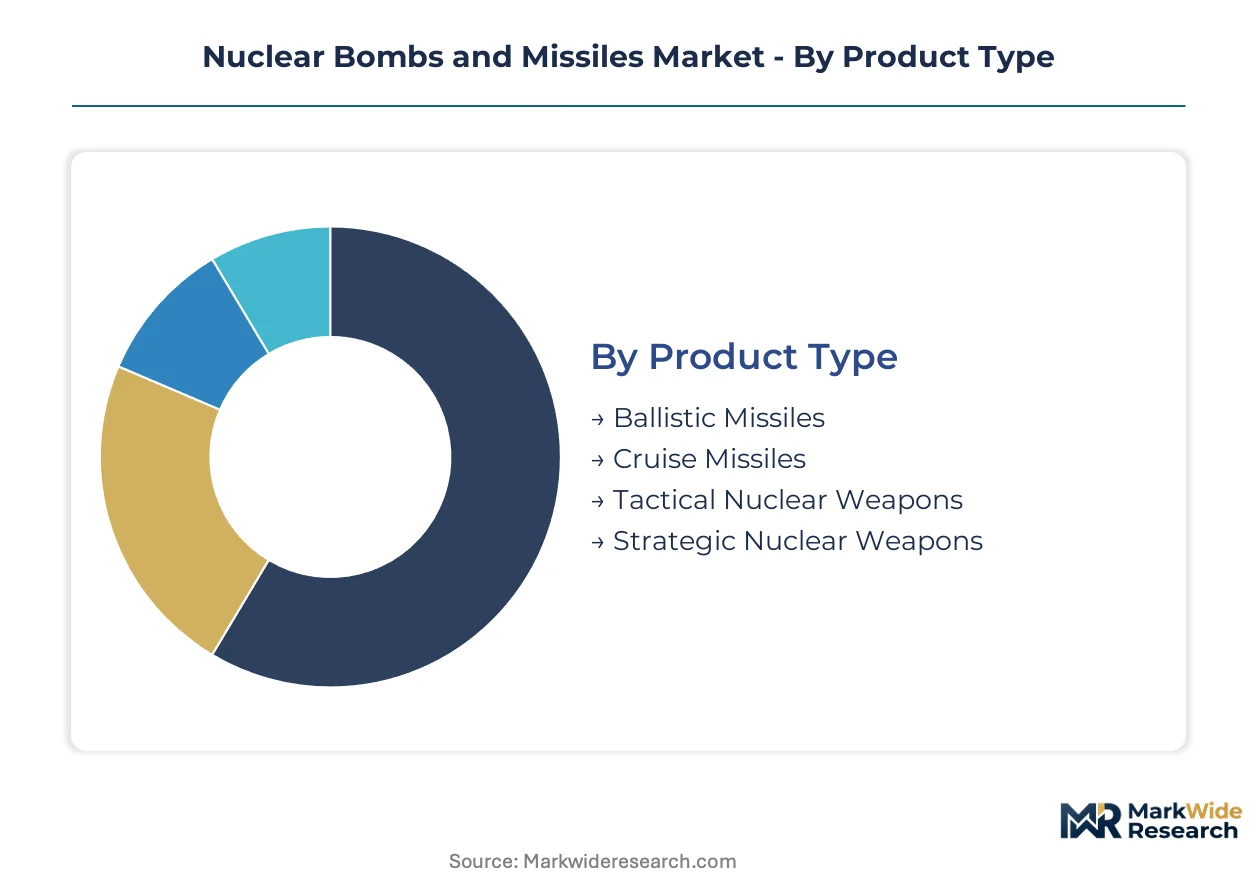
Nuclear weapons procurement fragments across delivery platform physics, operational basing modes, and classified technology tiers. Each segmentation dimension shapes supplier qualification pathways and program funding cycles differently.
Product Type:
Ballistic missiles dominate domestic procurement budgets in the United States, Russia, and China, while cruise missile development attracts export-oriented research partnerships.
- Ballistic Missiles:Solid-fuel intercontinental systems with MIRV payloads constitute the capital-intensive core of nuclear triad modernization. The US Air Force's Sentinel ICBM and Navy's Trident D5LE drive multi-billion dollar propulsion and guidance contracts concentrated at Los Alamos and Pantex facilities.
- Cruise Missiles:Turbofan and scramjet-powered air-breathing vehicles enable terrain-following delivery with reduced radar signatures. Hypersonic glide vehicle integration accelerates development timelines for prompt global strike missions across the US and Chinese defense research establishments.
- Tactical Nuclear Weapons:Low-yield gravity bombs and artillery shells serve NATO nuclear sharing arrangements and regional deterrence postures.
- Strategic Nuclear Weapons:High-yield warheads for ICBM and SLBM delivery undergo life-extension programs at Department of Energy national laboratories.
Ballistic missiles hold the largest share; momentum sits with cruise missiles as hypersonic integration reshapes mission profiles.
Deployment Mode:
Sea-based systems command premium unit costs due to reactor integration and pressure-hull engineering, while land-based silo infrastructure spreads fixed costs across decades.
- Land-based:Fixed silo complexes and mobile transporter-erector-launchers provide survivable basing against counterforce strikes. The US Minuteman III replacement and Russia's RS-28 Sarmat program concentrate solid-rocket motor demand at domestic production facilities.
- Sea-based:Submarine-launched ballistic missiles deployed from Ohio-class and Columbia-class hulls require specialized launch tube engineering and pressurized water reactor integration. The UK Dreadnought program sustains transatlantic supply chain continuity for missile tube forgings.
- Air-launched:Strategic bombers and tactical aircraft deliver gravity bombs and standoff cruise missiles with rapid retargeting flexibility.
- Mobile Platforms:Road-mobile ICBMs and rail-based systems enhance survivability through dispersion and concealment.
Sea-based deployment captures the highest contract values; mobile platforms are gaining share fastest as survivability requirements intensify.
End User:
Military service branches control operational system procurement, while government agencies govern warhead certification and stockpile stewardship.
- Military:Service-specific commands—US Strategic Command, Russia's Strategic Rocket Forces, China's Rocket Force—define operational requirements for range, payload, and response timelines.
- Government:The Department of Energy's National Nuclear Security Administration and equivalent Russian and Chinese agencies oversee plutonium pit production and warhead certification protocols.
- Defense Contractors:Prime integrators and subsystem suppliers execute design-to-production transitions under cost-plus incentive fee structures.
- Research Institutions:Los Alamos, Lawrence Livermore, and Sandia National Laboratories conduct subcritical experiments and computational validation.
Military end users dominate procurement volumes; government agencies control the critical path through certification bottlenecks.
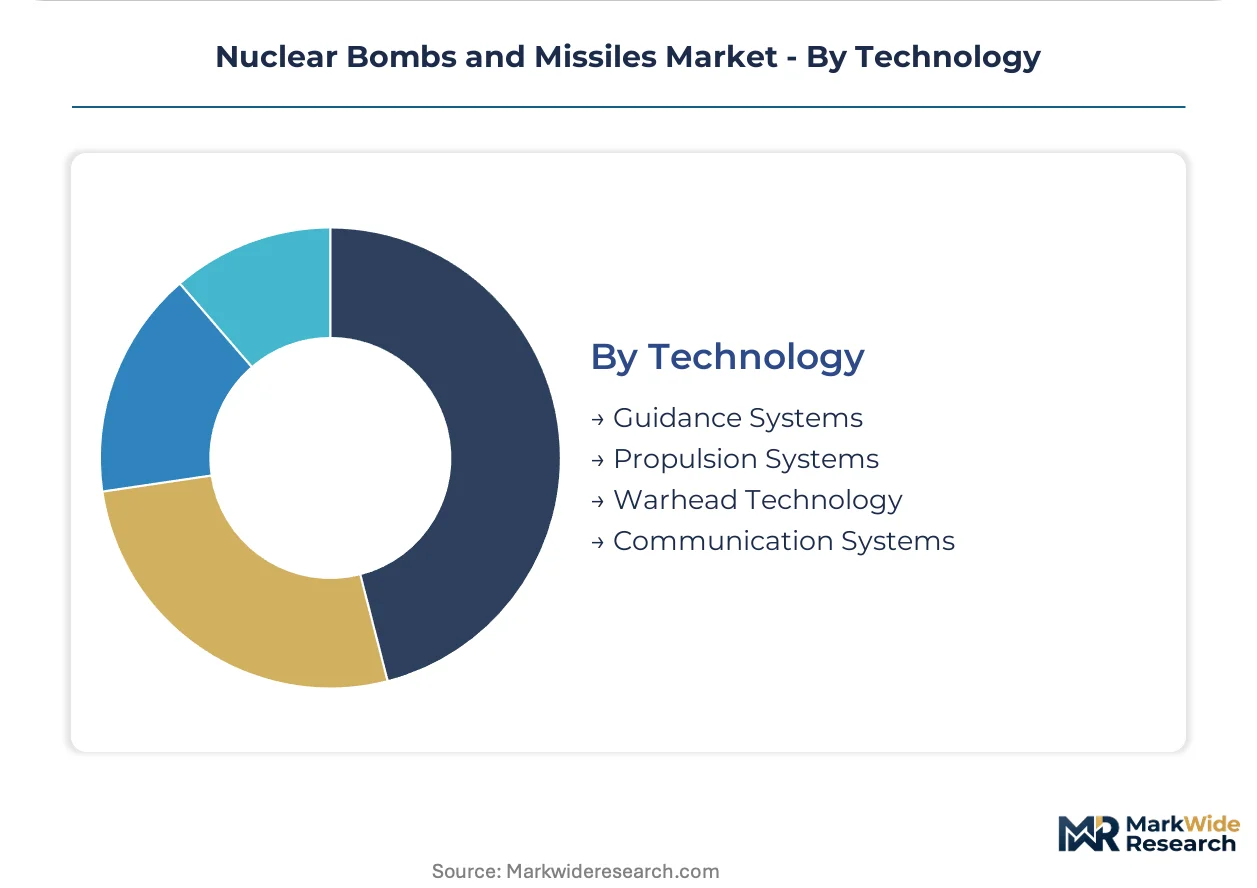
Technology:
Guidance and propulsion systems concentrate specialized supplier bases, while warhead technology remains captive to national laboratory infrastructure.
- Guidance Systems:Ring laser gyroscopes, stellar trackers, and GPS-denied navigation architectures enable precision targeting in contested electromagnetic environments. Raytheon and Northrop Grumman sustain dominance in kill-vehicle guidance for midcourse engagement.
- Propulsion Systems:Solid-rocket motors for boost-phase acceleration and scramjet sustainers for hypersonic cruise depend on ammonium perchlorate supply chains and advanced composite casing manufacturing.
- Warhead Technology:Fission-fusion physics packages require weapons-grade plutonium pits and tritium boosting gas under strict NNSA stewardship.
- Communication Systems:Extremely high frequency satellite links and hardened landline networks ensure command continuity under nuclear attack scenarios.
Guidance systems claim the steepest margin structure; propulsion systems face the most acute supply concentration risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement officers in the United States, Russia, and China control the majority of nuclear weapons system acquisition budgets. Each national buyer operates under distinct warhead certification protocols and triad recapitalization timelines. Supplier qualification pathways diverge sharply across these three procurement centers.
United States
The Department of Defense and Department of Energy jointly fund Columbia-class submarine construction and Sentinel ICBM deployment. The National Nuclear Security Administration enforces plutonium pit production standards at Los Alamos National Laboratory. Huntsville, Alabama anchors solid-rocket motor manufacturing through concentrated propulsion industry presence.
Russia
Rosatom and the Ministry of Defense coordinate RS-28 Sarmat heavy ICBM and Borei-class submarine programs. State Armament Program ten-year procurement cycles lock in multi-decade supplier commitments. Sarov and Snezhinsk host closed nuclear cities sustaining weapons physicist employment and pit fabrication.
China
The Central Military Commission Equipment Development Department accelerates DF-41 mobile ICBM and JL-3 SLBM fielding. Civil-military fusion directives redirect commercial aerospace suppliers toward strategic delivery systems. Mianyang and Beijing concentrate hypersonic glide vehicle research institutes with adjacent test ranges.
United Kingdom
The Ministry of Defence sustains Trident successor commitments through Dreadnought-class submarine procurement. The Office for Nuclear Regulation oversees warhead certification continuity with US technical cooperation. Barrow-in-Furness hosts BAE Systems submarine construction with specialized pressure-hull forging capacity.
France
The Direction Générale de l'Armement mandates modular warhead architectures for the ASN4G cruise missile program. The Commissariat à l'Énergie Atomique maintains independent pit production at Valduc and simulation capabilities at Bruyères-le-Châtel. Île-de-France concentrates prime contractor headquarters with government procurement authority.
Nuclear Bombs and Missiles Market Vendor Landscape
Player mix skews toward prime integrators with captive national laboratory relationships and multi-decade platform franchises. The vendor base concentrates around five major defense conglomerates holding sole-source positions on strategic delivery systems. Two strategic archetypes dominate: triad prime integrators with submarine-aircraft-missile portfolios, and subsystem specialists in guidance and propulsion. Competitive moves center on securing life-extension program contracts and penetrating allied export programs through government-to-government agreements.
Within the triad prime tier, Lockheed Martin and Northrop Grumman occupy positions defined by sea-based and air-based leg dominance respectively. Raytheon Technologies represents the guidance and missile defense specialization archetype. These three US-based contractors exemplify the market structure where national procurement concentration produces durable incumbent positions.
| Leading Market Players |
|---|
| Lockheed Martin |
| Raytheon Technologies |
| Northrop Grumman |
| BAE Systems |
| MBDA |
| Boeing |
| Thales |
| Rafael Advanced Defense Systems |
| General Dynamics |
| Others |
Supply Flow & Price Mechanics
Solid-rocket motor ammonium perchlorate substitution for legacy liquid-fuel stages simultaneously concentrates propulsion sourcing in Huntsville, Alabama and Pantex-adjacent corridors while compressing unit economics through batch-scale manufacturing efficiencies. This input transition reshapes supplier qualification pathways and locks in cost-plus contract structures with multi-decade indexation horizons.
Pricing Analysis
Cost-plus incentive fee contracts with producer price index escalation clauses dominate warhead life-extension and missile modernization programs. Price differentiation rests on NNSA certification tier and volume scale, with boutique guidance system suppliers commanding premium margins over commoditized solid-rocket motor producers. Pricing pressure stems from congressional appropriations volatility and competing domestic discretionary spending demands. Tier 2 subsystem suppliers exhibit highest price sensitivity due to sole-source dependency on Los Alamos and Pantex facility access.
Supply Chain Analysis
The United States anchors weapons-grade plutonium pit production at Los Alamos National Laboratory while Russia concentrates pit fabrication at Sarov and Snezhinsk closed nuclear cities. China draws from Mianyang and Beijing-adjacent research complexes for hypersonic glide vehicle propulsion systems. Raw material dependencies center on weapons-grade plutonium feedstock, tritium boosting gas, and ammonium perchlorate oxidizer supply. Single-source vulnerability permeates the pit production bottleneck where Los Alamos remains the sole certified US facility. Distribution runs through prime integrator captive supply chains with NNSA oversight at each transfer node.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks cyclical defense procurement waves with modernization roadmap acceleration serving as the recovery engine. Congressional appropriations cycles and triad recapitalization timelines create predictable demand cadences for qualified suppliers.
For Market Incumbents: Shield long-term franchise positions through backward integration into solid-rocket motor propellant mixing and stellar-inertial guidance component manufacturing. Lockheed Martin and Northrop Grumman should deepen captive supply of ring laser gyroscopes to offset Raytheon Technologies' kill-vehicle guidance dominance. Counter the emerging threat of civil-military fusion suppliers in China's Central Military Commission pipeline by accelerating US-UK-Australia AUKUS technology sharing protocols.
For New Entrants and Emerging Players: NNSA certification fast-track programs for subcritical test support equipment offer the most penetrable entry vector. Target stellar tracker and astro-navigation subsystem supply to prime integrators seeking GPS-denied alternatives. Pursue UK Trident successor and Dreadnought-class submarine component supply through BAE Systems vendor qualification pathways as the transatlantic bridge strategy.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed defense services firms holding NNSA facility management contracts and warhead life-extension program support franchises. Five-to-ten year viability hinges on Columbia-class and Sentinel program appropriations continuity. Watch congressional budget resolution markup timing as the inflection signal for program acceleration or contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| Hypersonic Glide Vehicle Integration | Mach 5+ terminal velocity requirements compress development timelines at DARPA and Chinese defense research institutes. |
| Plutonium Pit Production Expansion | Los Alamos capacity addition would alleviate warhead refurbishment bottlenecks constraining Sentinel ICBM fielding. |
| Stellar-Inertial Guidance Hybridization | Astro-tracker and ring laser gyroscope pairing enables contested electromagnetic environment operations for US Strategic Command. |
| Modular Warhead Architecture Adoption | France's ASN4G yield-selectable specifications are reshaping procurement requirements across NATO nuclear sharing arrangements. |
| Civil-Military Fusion Supplier Redirect | China's commercial aerospace supplier redirection toward DF-41 and JL-3 programs accelerates indigenous solid-rocket motor capacity. |
Methodological Framework
Operator-level perspectives from weapons physicists at Los Alamos and Lawrence Livermore National Laboratories, NNSA program managers, US Strategic Command operations officers, and prime integrator supply chain directors anchored the qualitative base. Secondary validation drew from Department of Energy budget justifications, Department of Defense Selected Acquisition Reports, Congressional Research Service nuclear forces analyses, and UK Ministry of Defence major projects portfolio disclosures. Bottom-up platform procurement quantification triangulated against top-down national laboratory spending allocation patterns.
Sensitivity analysis around plutonium pit production throughput assumptions and Columbia-class submarine construction cadence shaped the forecast framework. Segmentation modeling spanned delivery platform physics, operational basing modes, warhead certification tiers, and guidance system technology trajectories across the projection horizon. CAGRs derived from procurement timeline phasing and appropriations growth patterns with cross-reference to historical program execution rates at Pantex and Y-12 facilities.
Decision-makers should treat outputs as directional under sustained triad modernization appropriations and Comprehensive Nuclear-Test-Ban Treaty compliance assumptions; material deviation would warrant model refresh. Specific risk factors include congressional continuing resolution disruptions, warhead certification protocol changes, and emergent hypersonic arms control diplomacy. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Recoilless Rifle Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Anti-Tank Missile System Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Small Caliber Ammunition Market