
 Man-Portable Anti-Armor Weapons Market | 2026-2036
Man-Portable Anti-Armor Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Man-Portable Anti-Armor Weapons Market Outlook
Platform licensing revenue from legacy system upgrades is narrowing as defense ministries shift procurement toward next-generation guided munitions. Lockheed Martin leverages its Javelin production infrastructure to sustain dominance in fire-and-forget missile architectures. Saab specializes in disposable recoilless weapons that compete on unit cost against reusable launcher systems. RTX Corporation anchors its position through infrared seeker supply chains that extend across multiple NATO armament programs.
Man-portable anti-armor weapons are shoulder-fired or tripod-mounted systems designed to defeat armored vehicles through shaped-charge warheads, kinetic penetrators, or top-attack profiles, typically operating at ranges from 300 meters to 4 kilometers depending on guidance architecture. These systems serve infantry squads as organic counter-armor capability without requiring vehicle transport or dedicated fire support platforms. Guided Systems command premium pricing due to semiconductor-limited seeker production, while Unguided Systems retain volume share in asymmetric conflict zones where cost-per-shot governs procurement. Multi-Role Platforms represent the fastest-expanding technology category as militaries demand single launchers configurable for anti-armor, anti-structure, and air defense roles.
The US Department of State's Directorate of Defense Trade Controls governs International Traffic in Arms Regulations export licensing, constraining technology transfer to allied nations and shaping supplier market access. NATO's Standardization Agreement 4172 establishes interoperability requirements for 84mm and larger caliber systems, while the EU's Common Position 2008/944/CFSP harmonizes export criteria across member states. Stakeholders must monitor how ITAR waiver expansions for AUKUS and selected Indo-Pacific partners redirect supplier relationships and manufacturing location decisions.
Market Dynamics
Defense ministries are consolidating procurement around next-generation guided munitions, compressing demand for legacy unguided systems while amplifying competition among seeker-component suppliers.
Growth Catalysts
- ITAR Waiver Expansions:The US Department of State's Directorate of Defense Trade Controls has broadened licensing exemptions for AUKUS partners, accelerating technology transfer velocity and manufacturing co-location decisions.
- NATO Standardization Agreement 4172:Interoperability mandates for 84mm and larger caliber systems are harmonizing procurement specifications across member arsenals, reducing supplier qualification friction.
- Shaped-Charge Warhead Advances:Tandem warhead configurations capable of defeating explosive reactive armor are penetrating procurement specifications for frontline infantry units.
Market Restraints
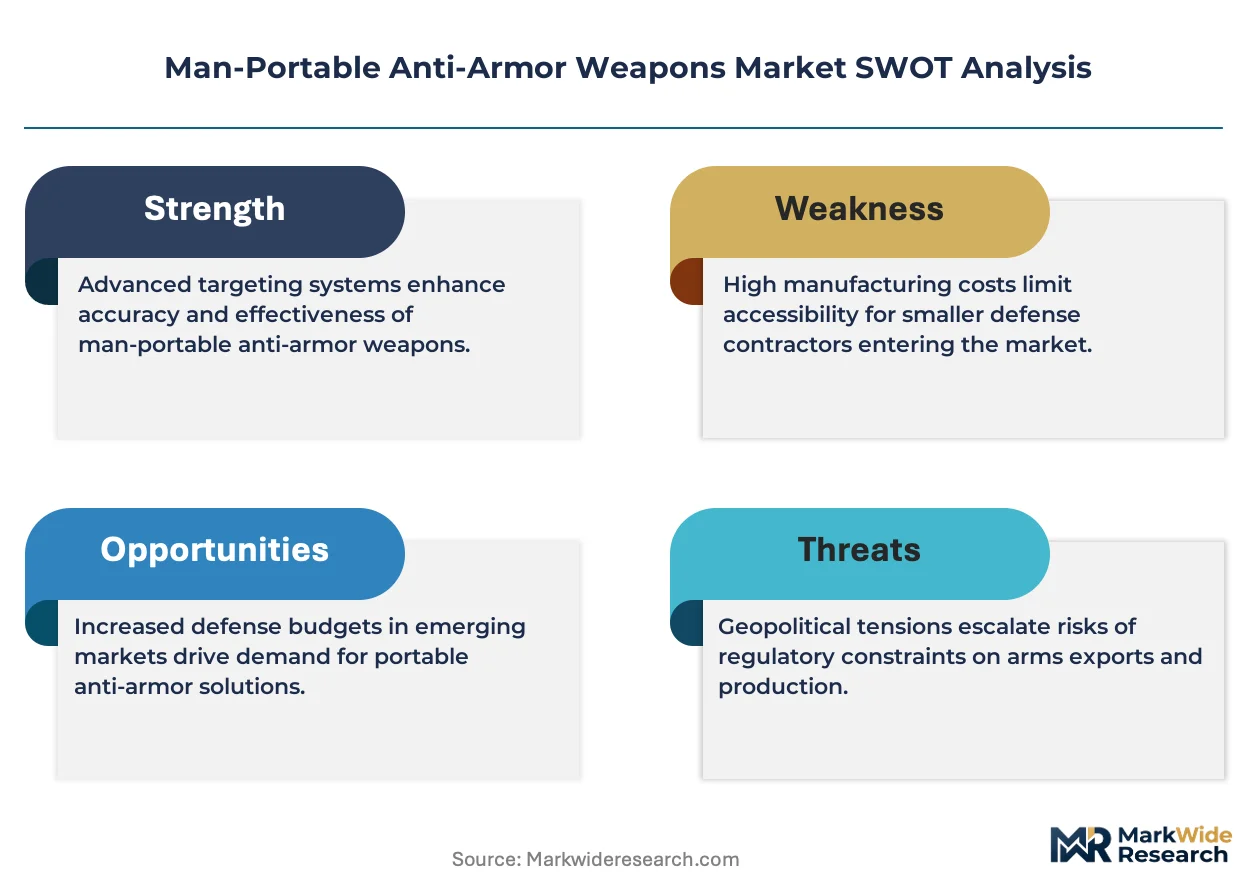
- Semiconductor-Limited Seeker Production:Infrared focal plane array foundry capacity constraints in the United States and Western Europe are throttling output rates for fire-and-forget guidance systems.
- Export Control Fragmentation:The EU's Common Position 2008/944/CFSP creates divergent national interpretations that delay licensing timelines for cross-border transfers within allied blocs.
- Unguided System Substitution:Disposable recoilless weapons retain procurement preference in asymmetric conflict zones where unit cost governs acquisition decisions over precision performance.
Strategic Opportunities
- Multi-Role Platform Convergence:Single launchers configurable for anti-armor, anti-structure, and air defense roles are capturing procurement attention from mechanized infantry commands seeking load-out flexibility.
- Indo-Pacific Manufacturing Relocation:ITAR waiver expansions for selected partners are redirecting supplier relationships toward Australia and Japan for regional supply chain resilience.
- Top-Attack Profile Demand:Infantry modernization programs in Poland and Ukraine are prioritizing shoulder-fired weapons with overhead detonation capabilities against roof-armor vulnerabilities.
Industry Challenges
- Seeker Integration Complexity:Fire-and-forget missile architectures require specialized cleanroom assembly protocols that strain available technical workforce pools in defense manufacturing clusters.
- Legacy System Obsolescence Management:Defense ministries face sustainment cost escalation for discontinued guidance electronics as production lines shift toward next-generation semiconductor architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Man-Portable Anti-Armor Weapons Market |
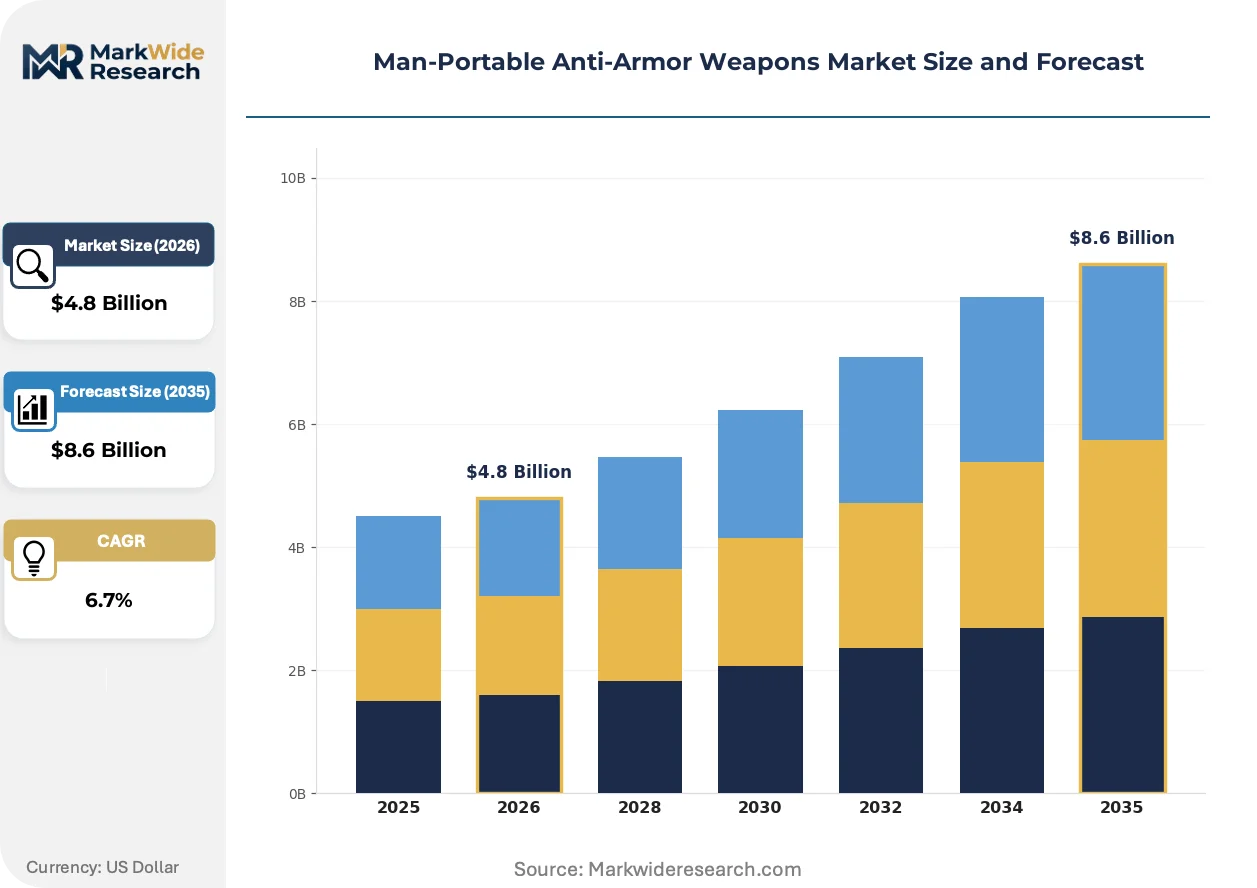
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rocket Launchers, Anti-Tank Guided Missiles, Grenade Launchers, Recoiless Rifles Technology: Guided Systems, Unguided Systems, Multi-Role Platforms, Laser Targeting End User: Military, Defense Contractors, Law Enforcement, Security Personnel Deployment: Field Operations, Training Exercises, Urban Warfare, Covert Missions |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, General Dynamics Corporation, Saab AB, MBDA, Bharat Dynamics Limited, Raytheon Technologies Corporation, BAE Systems, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Man-Portable Anti-Armor Weapons Market Strategic Shifts
Guidance architecture evolution is compressing the performance gap between man-portable systems and vehicle-mounted anti-tank missiles, reshaping infantry organic fire support doctrine.
Uncooled infrared seeker technology is migrating from military-exclusive applications toward dual-use manufacturing bases, enabling cost reduction trajectories previously unattainable with cryogenically cooled alternatives. Polish and Ukrainian procurement authorities are accelerating adoption timelines for these seeker variants. The technology is migrating from premium-tier fire-and-forget systems toward mid-range disposable launchers, collapsing traditional price stratification across guidance categories.
The EU's Common Position 2008/944/CFSP harmonization efforts are tightening end-use monitoring requirements for exported man-portable systems, extending compliance obligations through operational lifecycle documentation. Defense contractors must now maintain traceability records for transferred units that previously terminated at point of sale. Smaller caliber disposable systems face disproportionate compliance burden relative to their unit value, advantaging suppliers with established export licensing infrastructure.
Buyer concentration around national stockpile programs is displacing fragmented unit procurement, with Poland and Ukraine negotiating multi-year framework agreements that lock in production capacity. Defense ministries are consolidating orders into single-source arrangements to secure supply continuity during semiconductor-constrained periods. This pattern is most visible in United States and NATO member state contracting, where distributed lethality concepts prioritize squad-level organic capability over centralized fire support allocation.
Man-Portable Anti-Armor Weapons Market Segmentation
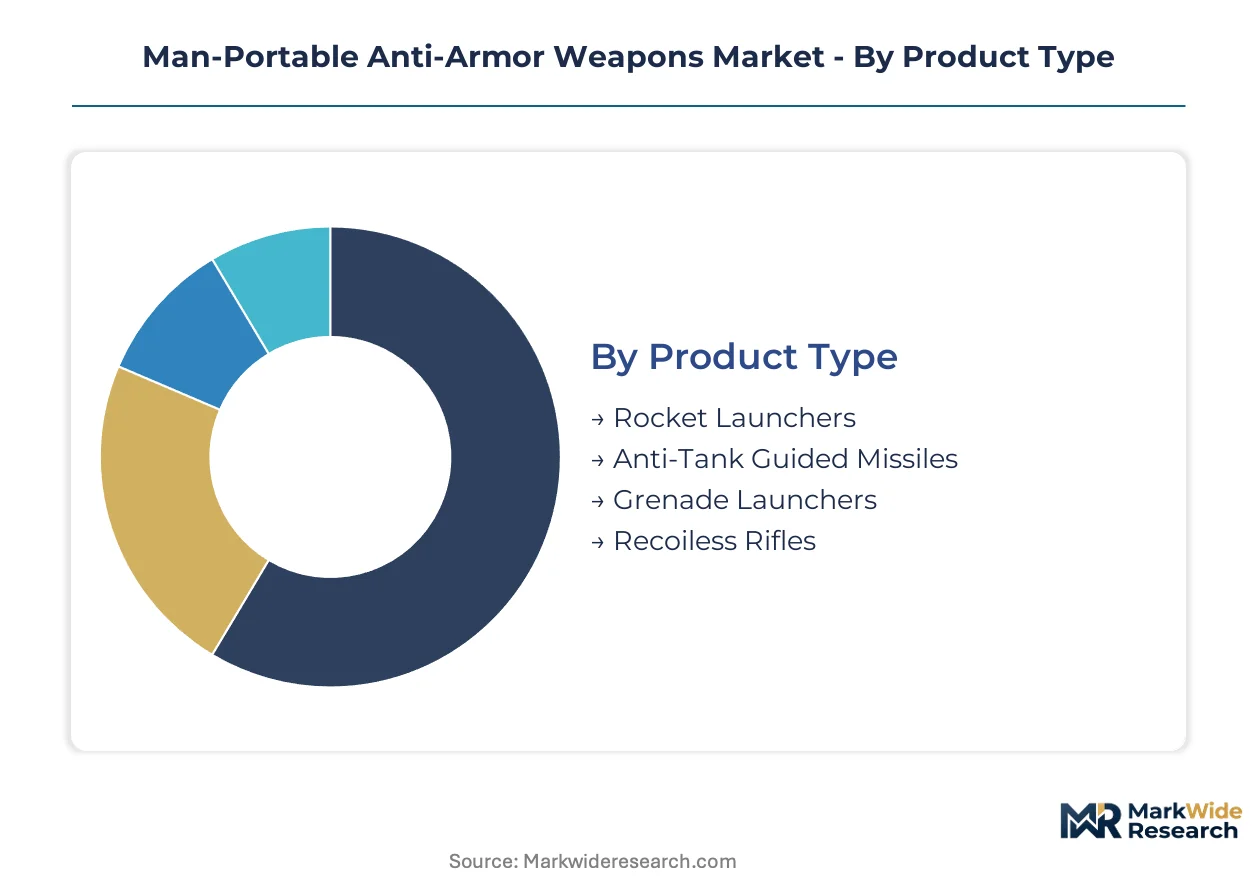
Segmentation in the man-portable anti-armor weapons market reveals how procurement priorities diverge across guidance architectures, end-user doctrines, and operational environments. Defense ministries allocate budgets differently based on threat profiles, force structure, and interoperability requirements within alliance frameworks.
Product Type:
Shoulder-fired systems span a use-case spectrum from disposable close-range defense to precision standoff engagement, with each category optimized for specific armor defeat mechanisms and squad-level tactical integration.
- Anti-Tank Guided Missiles:Fire-and-forget architectures with infrared or electro-optical seekers enable engagement beyond 2 kilometers against moving armor. Procurement concentrates in the United States and Poland as infantry modernization programs prioritize distributed lethality concepts for light forces.
- Rocket Launchers:Unguided systems deliver shaped-charge warheads through disposable tube launchers at ranges under 500 meters. Ukrainian territorial defense units and asymmetric conflict operators favor these systems where unit cost governs acquisition volume over precision performance.
- Grenade Launchers:Compact systems firing high-explosive anti-tank rounds provide squad-level organic capability against light armor and fortified positions.
- Recoiless Rifles:Reusable launchers firing 84mm and larger projectiles balance portability against sustained firepower for mechanized infantry support.
Established volume favors Rocket Launchers; emerging adoption favors Anti-Tank Guided Missiles.
Technology:
Cost tiers separate legacy unguided systems from semiconductor-intensive precision munitions, with mid-range categories capturing procurement attention through seeker cost reduction trajectories.
- Guided Systems:Infrared focal plane array seekers and electro-optical trackers enable fire-and-forget engagement with top-attack profiles. Production constraints at US and Western European foundries throttle output rates for these premium-tier systems.
- Multi-Role Platforms:Configurable launchers accepting anti-armor, anti-structure, and air defense munitions from common tube architectures. Polish mechanized commands and NATO rapid response forces are accelerating procurement timelines for these flexible systems.
- Unguided Systems:Simple point-and-shoot mechanics with iron sights or basic optics minimize unit cost and training burden.
- Laser Targeting:Beam-riding guidance requires continuous designation but reduces seeker complexity and cost relative to autonomous homing systems.
Price stratification concentrates procurement volume in Unguided Systems; capability investment flows fastest toward Multi-Role Platforms.
End User:
Customer type determines acquisition scale, specification stringency, and lifecycle support requirements across national military structures and specialized security formations.
- Military:National defense ministries procure through multi-year framework agreements with stringent NATO Standardization Agreement 4172 compliance. The US Department of Defense and Polish Ministry of National Defense dominate order volume through distributed lethality and territorial defense programs.
- Defense Contractors:Private military companies and security firms acquire systems for protective services in high-threat environments, driving demand for compact disposable launchers with simplified logistics.
- Law Enforcement:Specialized tactical units require limited quantities for counter-terrorism and high-risk warrant service scenarios.
- Security Personnel:Critical infrastructure protection details seek man-portable systems for vehicle-borne threat mitigation.
Institutional procurement favors Military end users; operational flexibility requirements favor Defense Contractors.
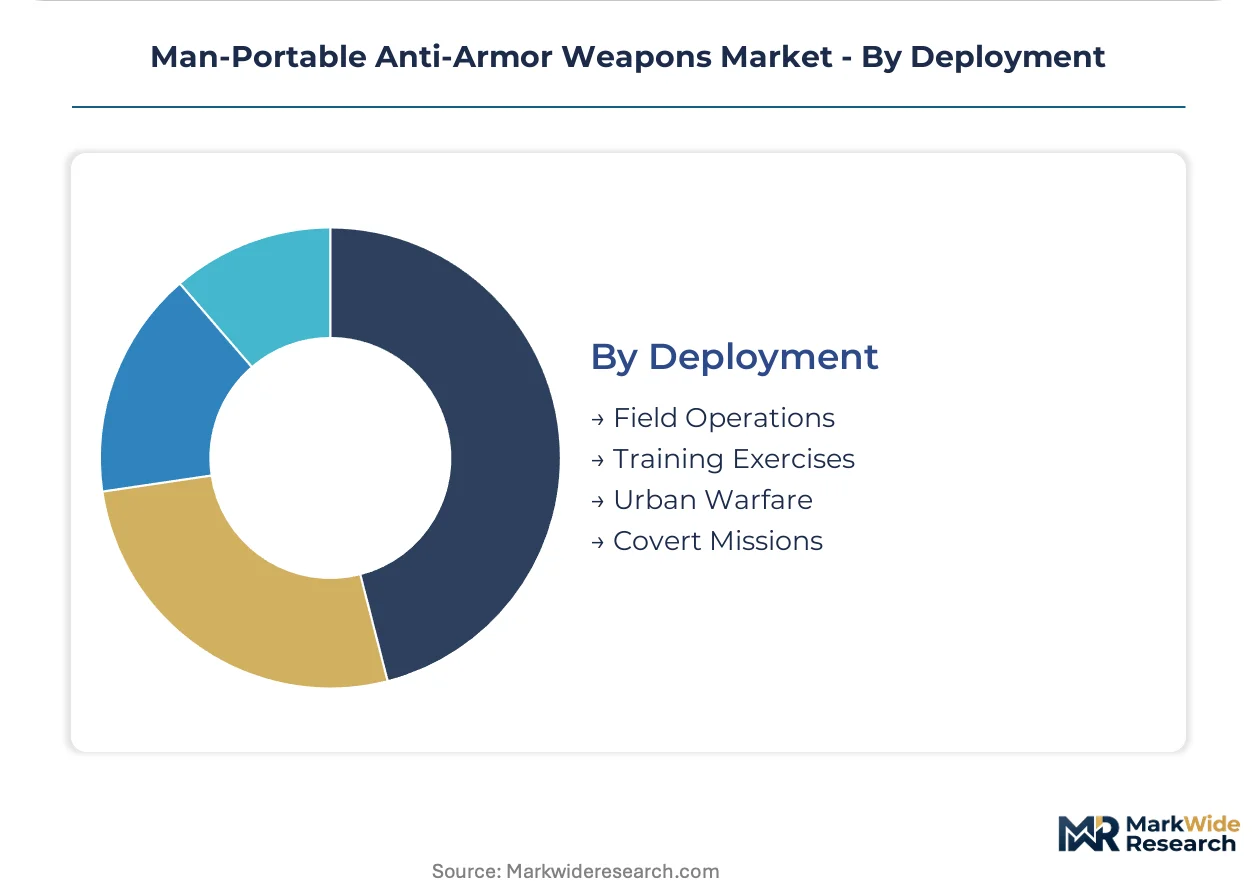
Deployment:
Operational environment shapes launcher selection through range requirements, collateral damage constraints, and signature management priorities.
- Field Operations:Open terrain engagements favor long-range guided missiles with thermal targeting capabilities. NATO member state exercises in Poland and Baltic regions emphasize these scenarios for combined arms coordination.
- Urban Warfare:Confined space operations demand compact systems with reduced backblast and minimum arming distances. Ukrainian forces have accelerated procurement of short-range disposable launchers for built-up area defense.
- Training Exercises:Inert and reduced-range munitions consumption creates recurring demand for simulation-compatible systems.
- Covert Missions:Signature-suppressed launchers with disposable components enable deniable deployment scenarios.
Conventional doctrine centers procurement on Field Operations; contingency planning drives fastest investment growth toward Urban Warfare configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across procurement theaters: NATO members prioritize precision-guided systems with top-attack profiles, while frontline states facing immediate armor threats favor high-volume disposable launchers for territorial defense saturation.
United States
The Department of Defense's distributed lethality doctrine drives squad-level organic firepower procurement through multi-year framework agreements. ITAR licensing administered by the Directorate of Defense Trade Controls constrains technology transfer velocity to allied nations. Huntsville, Alabama and Tucson, Arizona host concentrated defense manufacturing clusters where infrared seeker integration facilities operate at semiconductor-limited capacity.
Poland
Mechanized infantry modernization programs prioritize shoulder-fired weapons with overhead detonation capabilities against roof-armor vulnerabilities. NATO Standardization Agreement 4172 compliance mandates shape procurement specifications for 84mm and larger caliber systems. The Wojska Lądowe (Polish Land Forces) headquarters in Warsaw coordinates framework agreements that lock in multi-year production capacity from Western suppliers.
Ukraine
Territorial defense units consume disposable recoilless weapons at volumes exceeding precision-guided system procurement by an order of magnitude. End-use monitoring requirements under EU Common Position 2008/944/CFSP extend compliance obligations through operational lifecycle documentation. Kyiv and Lviv serve as distribution nodes where asymmetric conflict logistics favor simplified point-and-shoot mechanics over seeker-dependent architectures.
Germany
The Bundeswehr's mechanized infantry commands accelerate adoption of multi-role launchers configurable for anti-armor, anti-structure, and air defense roles. Federal Office of Bundeswehr Equipment, Information Technology and In-Service Support (BAAINBw) procurement guidelines emphasize interoperability with NATO partner arsenals. Rheinmetall's manufacturing presence in Unterlüß anchors domestic production capacity for 84mm recoilless systems.
Australia
ITAR waiver expansions for AUKUS partners redirect supplier relationships toward regional manufacturing co-location for supply chain resilience. The Department of Defence's LAND 400 program integrates man-portable systems into combined arms modernization. Adelaide hosts emerging defense manufacturing infrastructure where seeker-component assembly protocols are being established under technology transfer agreements.
Man-Portable Anti-Armor Weapons Market Competitive Environment
Capability concentration sits with prime contractors possessing captive infrared focal plane array supply chains; scale advantage sits with disposable launcher specialists competing on unit cost and production velocity. The vendor base separates into three distinct tiers: vertically integrated seeker manufacturers, reusable launcher system integrators, and disposable weapon fabricators. Dominant competitive moves include manufacturing co-location decisions following ITAR waiver geography and portfolio diversification into multi-role configurable platforms.
Within the prime contractor tier, Lockheed Martin Corporation and RTX Corporation anchor positions through established production infrastructure and component supply chain control. Saab AB occupies a distinct position among European specialists emphasizing unit cost optimization against reusable system alternatives. These three exemplify the capability-scale tension shaping procurement outcomes across NATO member states and frontline defense programs.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| General Dynamics Corporation |
| Saab AB |
| MBDA |
| Bharat Dynamics Limited |
| Raytheon Technologies Corporation |
| BAE Systems |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
Infrared focal plane array foundry capacity in the United States and Western Europe anchors downstream margin capture for fire-and-forget missile architectures, while disposable recoilless weapon fabricators compete away profitability through production velocity.
Pricing Analysis
Long-term framework agreements dominate procurement for guided munitions, locking in multi-year production capacity for prime contractors while spot-market fragmentation governs disposable launcher transactions. Three-tier pricing structure across fire-and-forget, beam-riding, and unguided systems reflects seeker complexity and semiconductor content. Pricing pressure stems from foundry capacity constraints throttling output rates for infrared seekers. Territorial defense units in frontline states exhibit highest price sensitivity, prioritizing unit cost over precision performance.
Supply Chain Analysis
International Traffic in Arms Regulations administered by the US Department of State's Directorate of Defense Trade Controls restricts infrared seeker technology flows to licensed allied nations, fragmenting supplier access. Manufacturing concentrates in the United States, Poland, and Australia following ITAR waiver expansions for AUKUS partners. Production draws from indium antimonide detector substrates, cryogenic cooling assemblies, and precision-machined launch tubes. Single-source vulnerability sits with focal plane array foundries in Huntsville and Tucson. Distribution runs through national stockpile programs and defense ministry procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-role platform interoperability is reshaping competitive positioning as NATO Standardization Agreement 4172 harmonization creates winner-take-most dynamics for configurable launcher architectures.
For Market Incumbents: Harden captive supply chains for infrared focal plane arrays through backward integration into detector substrate production or exclusive offtake agreements with foundry operators. Consolidate manufacturing co-location decisions in Australia and Poland ahead of ITAR waiver geography finalization. Priority defensive investment centers on cleanroom assembly workforce pipelines strained by fire-and-forget seeker integration complexity. For New Entrants and Emerging Players: Mid-range disposable launchers with uncooled infrared seekers represent the most penetrable entry point as cost reduction trajectories collapse traditional price stratification. Ukrainian territorial defense logistics and Polish mechanized infantry load-out flexibility offer adjacent demand pools outside prime contractor lock-in. Go-to-market execution should emphasize simplified training protocols and NATO interoperability certification as qualification accelerators. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated seeker manufacturers with established export licensing infrastructure and multi-year framework agreement backlogs. Long-term viability hinges on semiconductor supply chain positioning and ITAR waiver beneficiary status. The signal to watch is foundry capacity expansion announcements in Huntsville or Adelaide indicating supply constraint resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Role Platform Development | Configurable launchers for anti-armor, anti-structure, and air defense capture Polish and NATO rapid response procurement. |
| Uncooled Seeker Technology Migration | Cost reduction trajectories enable mid-range disposable systems to compete with fire-and-forget architectures. |
| ITAR Waiver Manufacturing Co-Location | Australia and Japan production facilities secure regional supply chain resilience for AUKUS partners. |
| Tandem Warhead Configuration Investment | Explosive reactive armor defeat capabilities penetrate procurement specifications for frontline infantry units. |
| Export Licensing Infrastructure Expansion | EU Common Position 2008/944/CFSP compliance capabilities advantage suppliers against fragmented national interpretations. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with defense procurement officers, program managers at prime contractors, infrared seeker manufacturing engineers, and export compliance specialists; and secondary validation through NATO standardization documentation, US Department of State licensing records, EU Common Position implementation reports, and defense ministry budget appropriations. Bottom-up triangulation across product type, technology tier, and end-user segment was cross-checked against top-down market sizing.
Forecast inputs considered infantry modernization program timelines, semiconductor foundry capacity expansion schedules, ITAR waiver implementation progress, and territorial defense unit formation rates across frontline states. Segmentation modeling spanned guidance architecture, launcher reusability, caliber class, and deployment environment. CAGRs were derived from production capacity constraints and procurement commitment visibility across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in defense budget appropriations, semiconductor capital expenditure cycles, or alliance framework stability would shift the trajectory. Material shifts in ITAR waiver geography or focal plane array foundry capacity allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Torpedo Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
Ammunition Storage Market