
 Explosives for Civil Uses Market | 2026-2036
Explosives for Civil Uses Market Size, Share, and Industry Trends Forecast 2026-2036
Explosives for Civil Uses Market Insights
The split between premium precision blasting systems and commodity bulk explosives is shifting as mining operators demand blast optimization software alongside physical product. Orica Mining Services differentiates through integrated drill-and-blast technology platforms that command service-linked premiums. Solar Industries anchors its position in the Indian subcontinent and African markets through backward integration into ammonium nitrate production. Maxam Corp competes on specialized emulsion formulations for challenging geological conditions where standard products underperform.
Explosives for civil uses encompass energetic materials engineered for rock fragmentation, earthmoving, and structural demolition rather than military application, typically formulated with ammonium nitrate-fuel oil blends, water-gel emulsions, or detonating cords with defined velocity of detonation parameters measured in meters per second. Bulk explosives dominate volume flows in surface mining where economies of scale in blast hole loading reduce per-ton costs, while emulsion explosives capture margin pools in wet-hole applications and environmentally sensitive sites where water resistance and reduced fume signatures justify premium positioning. Detonators represent a technology-intensive segment where electronic timing systems are displacing traditional pyrotechnic caps in controlled blasting programs requiring millisecond precision.
OSHA workplace safety standards, EPA clean air requirements for blast fume emissions, and the EU's REACH chemical registration framework collectively elevate compliance costs while restricting market entry for non-compliant suppliers. China's SAMR enforces GB standards on explosive manufacturing and transport that shape product formulation and packaging specifications for domestic consumption. Stakeholders must monitor regulatory divergence between jurisdictions as digital blast planning tools face divergent data localization and safety certification requirements across the US, Europe, and Asia-Pacific operational theaters.
Market Dynamics
The explosives for civil uses sector is experiencing a fundamental restructuring as mining contractors consolidate procurement around integrated blast optimization platforms rather than discrete chemical products, forcing suppliers to reconfigure their value propositions around software-enabled services.
Growth Catalysts
- Copper extraction intensity:Australian and Chilean open-pit operations are expanding bulk explosive consumption to access deeper ore bodies, with contractors specifying higher-density emulsion formulations for improved fragmentation efficiency.
- REACH chemical registration:The EU's framework is accelerating product reformulation toward lower-toxicity alternatives, creating competitive advantage for suppliers with advanced environmental compliance capabilities.
- Electronic detonator adoption:Millisecond-precision timing systems are displacing pyrotechnic caps in controlled blasting programs, enabling complex vibration management for urban infrastructure projects.
Market Restraints
- Ammonium nitrate supply concentration:Production of this critical feedstock clusters in select manufacturing corridors, exposing downstream formulators to input cost volatility and transport security constraints.
- F-Gas environmental restrictions:The EU's regulation on fluorinated gases is tightening compliance requirements for emulsion explosive manufacturing, elevating capital expenditure for emission control systems.
- Mechanical rock breaking alternatives:Hydraulic splitting and microwave fragmentation technologies are gaining traction in noise-sensitive urban demolition, constraining addressable market for traditional explosives in select applications.
Strategic Opportunities
- Western China infrastructure corridor:Rail tunnel and hydropower construction in Sichuan and Yunnan provinces is generating specialized demand for underground blasting systems with wet-hole compatibility and reduced fume signatures.
- Blast optimization software bundling:Integration of drill-pattern design algorithms with physical explosive supply creates service-linked revenue streams and strengthens customer switching costs.
- India PLI scheme alignment:Domestic manufacturing incentives for critical chemicals are enabling backward integration into ammonium nitrate production, reducing import dependency for regional suppliers.
Industry Challenges
- Electronic systems integration:Mining operators face complexity in retrofitting legacy blast control infrastructure with digital timing networks, requiring specialized field engineering support that strains supplier technical service capacity.
- OSHA workplace certification timelines:Extended approval processes for new explosive formulations and initiation systems delay product commercialization, compressing effective patent windows for proprietary technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosives for Civil Uses Market |
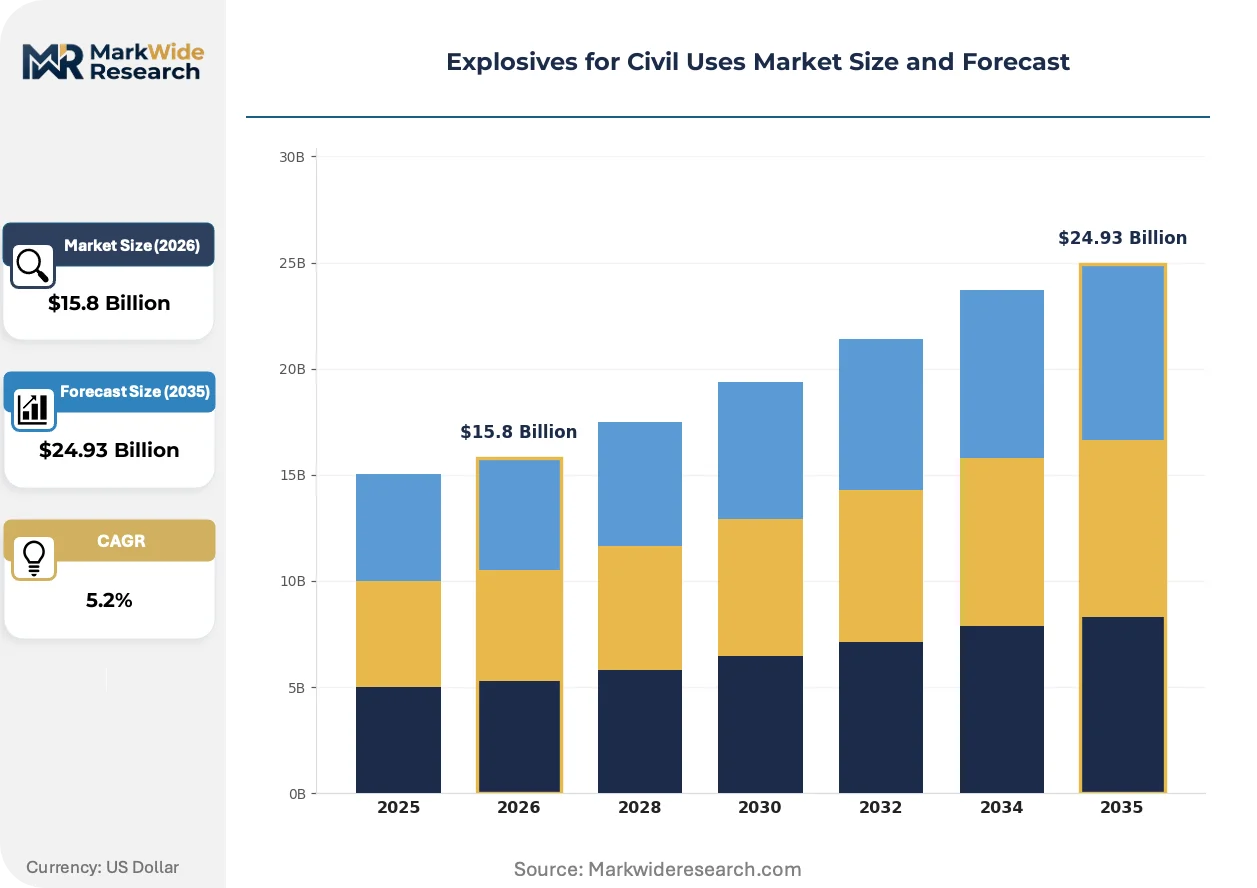
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $24.93 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Explosives, Emulsion Explosives, Detonators, Primers, Safety Fuses Application: Mining, Quarrying, Construction Demolition, Seismic Exploration, Road Building End User: Mining Contractors, Civil Engineering Firms, Survey Companies, Infrastructure Developers Deployment: Surface Blasting, Underground Blasting, Controlled Demolition, Blast Hole Drilling |
| Companies Covered | Austin Powder Company, Solar Industries, Orica Mining Services, Hanwha Corp, Incitec Pivot, Enaex, AEL Mining Services, AECI Group, Maxam Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosives for Civil Uses Market Trends and Innovations
Digital blast planning tools are converging with physical explosive chemistry to reshape how mining and construction operators specify, procure, and deploy energetic materials across project lifecycles.
Electronic blasting systems is integrating precision timing control with real-time vibration monitoring to enable complex delay sequencing for sensitive geology. Underground mining contractors in Scandinavia and North America are adopting these platforms at accelerated rates to manage ground stability in deep ore extraction. The technology is integrating fragmentation prediction algorithms with actual blast outcomes, compressing the feedback loop between design and execution.
REACH and the EU F-Gas Regulation are mandating progressive reduction in toxic fume emissions and fluorinated compound content across emulsion formulations. Manufacturers are reformulating water-gel chemistries to meet stricter environmental release thresholds while maintaining detonation velocity specifications. Wet-hole applications in European quarrying and tunneling face the most acute compliance pressure, driving premium positioning for certified low-emission products.
Service unbundling is separating blast design engineering from physical explosive supply in procurement negotiations at large mining houses. Tier-one operators are insourcing fragmentation modeling while outsourcing chemical manufacturing, forcing suppliers to compete on formulation performance rather than bundled technical support. This pattern is most visible in Australian iron ore and Canadian potash operations where centralized technical teams manage multi-site blasting programs.
Explosives for Civil Uses Market Segmentation
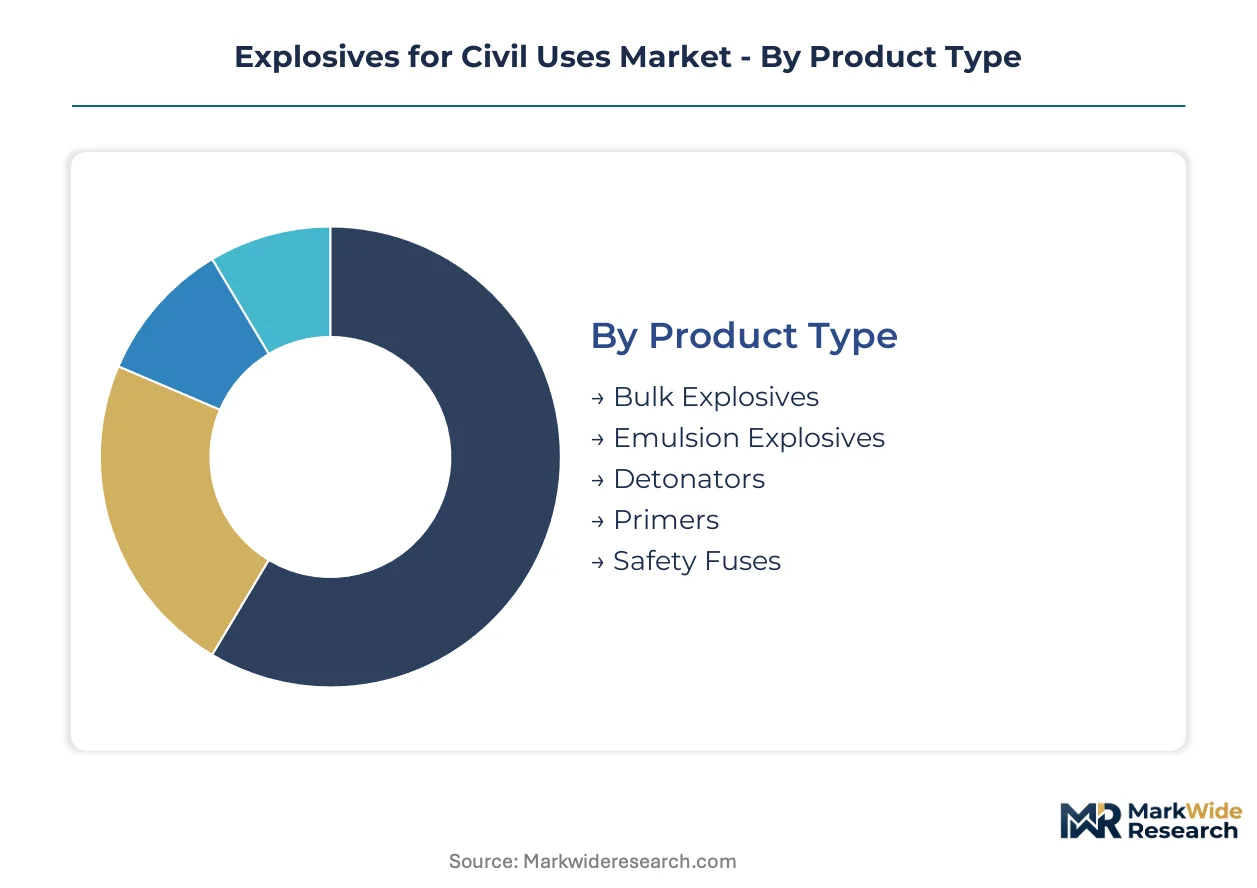
Segmentation in explosives for civil uses reveals how capital deployment, regulatory exposure, and technical service intensity vary dramatically across product categories and deployment modes. Procurement patterns diverge between bulk commodity buyers and precision-systems adopters, reshaping supplier economics.
Product Type:
Capital intensity peaks in emulsion manufacturing infrastructure, where controlled crystallization and water-gel stabilization require specialized reactor systems and emission control investments.
- Bulk Explosives:Ammonium nitrate-fuel oil blends dominate tonnage flows in surface mining. Australian and Chilean copper contractors specify higher-density formulations for deeper ore body fragmentation, driving continuous formulation refinement.
- Emulsion Explosives:Water-gel chemistries with defined velocity of detonation parameters command premium positioning in wet-hole applications. REACH and EU F-Gas Regulation compliance is accelerating reformulation toward reduced fume signatures in European quarrying and tunneling.
- Detonators:Electronic timing systems displace pyrotechnic caps where millisecond precision manages ground vibration.
- Primers:Booster charges initiate detonation sequences in bulk explosive columns.
- Safety Fuses:Traditional ignition systems persist in remote blasting applications with limited electronic infrastructure.
Bulk explosives absorb the bulk of installed capacity; emulsion explosives are expanding most quickly.
Application:
Application segmentation tracks blast scale, from million-tonne open-pit benches to precision urban demolition with strict vibration limits.
- Mining:Surface and underground extraction consumes the majority of explosive volumes, with copper intensity in Australia and Chile driving specification evolution. Contractors integrate blast optimization software with physical supply to manage fragmentation economics.
- Construction Demolition:Controlled structural takedown in dense urban environments demands electronic detonation networks with real-time vibration monitoring. Hydraulic splitting and microwave fragmentation technologies constrain addressable market in noise-sensitive European and North American cities.
- Quarrying:Dimension stone and aggregate production favors bulk loading economies.
- Seismic Exploration:Energy sector geophysical surveys require portable explosive charges with precise initiation timing.
- Road Building:Mountain corridor construction in China's western provinces generates demand for wet-hole compatible systems.
Mining commands the dominant share of explosive consumption; construction demolition is gaining share fastest as urban renewal intensifies.
End User:
End user structure reflects procurement consolidation around integrated service platforms versus discrete chemical purchasing.
- Mining Contractors:Large operators in Australian iron ore and Canadian potash insource fragmentation modeling while outsourcing manufacturing, forcing suppliers to compete on formulation performance rather than bundled technical support.
- Civil Engineering Firms:Tunnel and hydropower specialists in Sichuan and Yunnan provinces specify underground blasting systems with reduced fume signatures for confined-space worker safety.
- Survey Companies:Seismic contractors procure portable initiation systems for geophysical data acquisition.
- Infrastructure Developers:Rail and highway agencies specify blast programs through tendered subcontractor arrangements.
Mining contractors control the largest procurement volumes; civil engineering firms are climbing the fastest as tunnel construction accelerates.
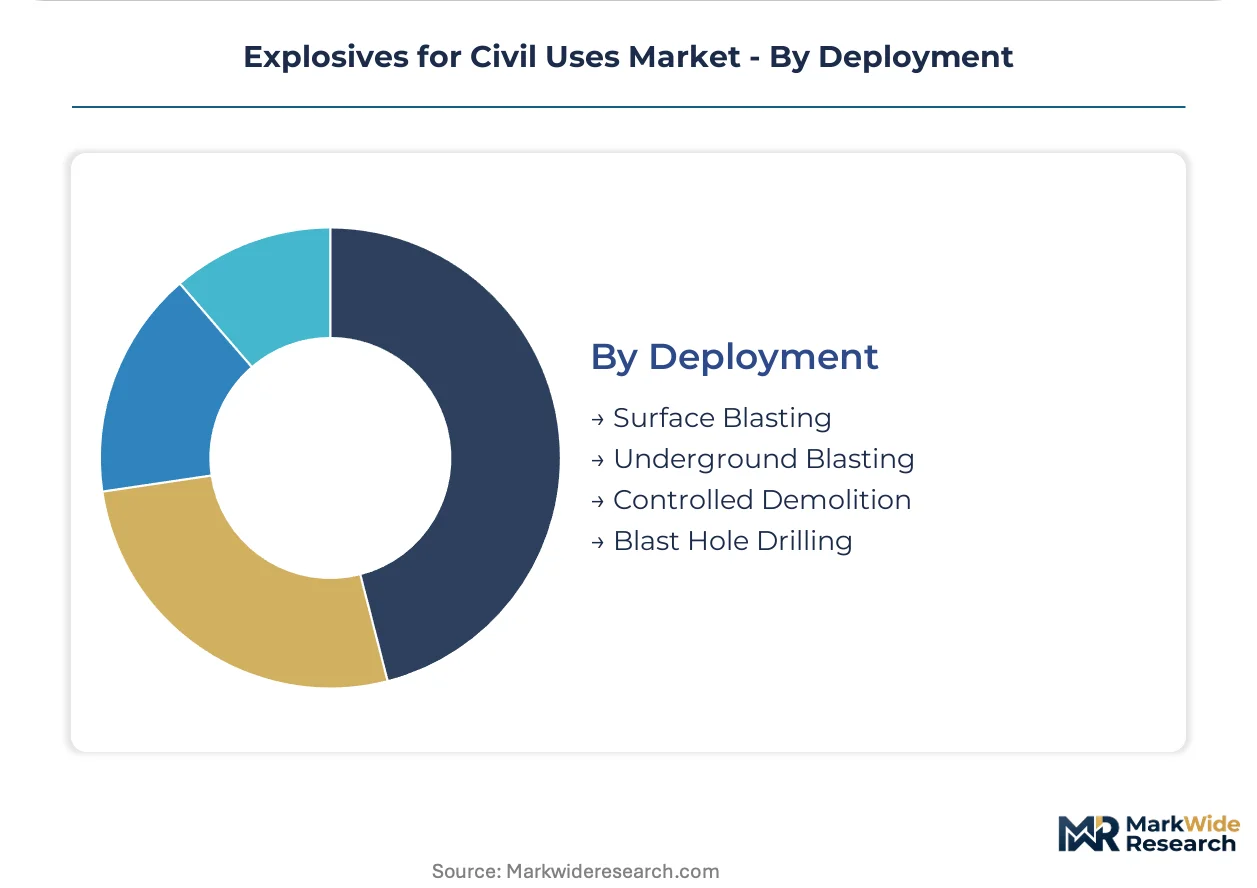
Deployment:
Deployment mode determines regulatory jurisdiction, with surface operations facing EPA clean air requirements and underground work governed by OSHA workplace safety standards.
- Surface Blasting:Open-pit operations achieve economies through bulk loading and large-diameter blast holes. China's SAMR enforces GB standards on manufacturing and transport that shape packaging specifications for domestic surface mining consumption.
- Underground Blasting:Confined-space detonation demands wet-hole compatibility and ventilation-compatible fume profiles. Scandinavian and North American contractors adopt electronic timing systems at accelerated rates to manage ground stability in deep extraction.
- Controlled Demolition:Urban structural takedown requires millisecond-precision delay sequencing and vibration monitoring.
- Blast Hole Drilling:Pre-splitting and production drilling patterns determine explosive loading density and initiation timing.
Surface blasting retains the greatest share of explosive deployment; underground blasting is expanding most quickly as ore bodies deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kalgoorlie and the Pilbara corridor anchor Australian mining explosive consumption, with open-pit copper and iron ore operations driving bulk emulsion demand. Chile's Atacama Desert mining belt and China's Sichuan-Yunnan tunneling corridor complete the triad of highest-intensity consumption zones worldwide.
Australia
Western Australia's Pilbara iron ore operations and Queensland's Bowen Basin coal deposits consume high-density bulk explosives for deep ore body fragmentation. EPA clean air requirements govern fume emissions from surface blasting operations. Kalgoorlie's Super Pit and Mount Whaleback operations specify integrated drill-and-blast optimization platforms from major contractors.
Chile
Atacama Desert copper mines expand explosive consumption to access deeper sulfide ore bodies below oxide layers. The national mining regulator enforces workplace safety standards for initiation system transport and storage. Antofagasta and Calama form the core consumption cluster where contractors specify premium emulsion formulations for arid-condition fragmentation efficiency.
China
Sichuan and Yunnan provinces generate specialized demand for wet-hole compatible explosives in rail tunnel and hydropower construction. SAMR enforces GB standards on manufacturing, transport, and packaging specifications for domestic consumption. The Chengdu-Kunming railway corridor and Baihetan hydropower project employ reduced-fume underground blasting systems for confined-space worker safety.
United States
Appalachian coal operations and Western copper-molybdenum mines balance bulk explosive economies with electronic detonator precision for vibration management. OSHA workplace safety standards and EPA clean air requirements elevate compliance costs for surface and underground operations. Arizona's Morenci complex and Wyoming's Powder River Basin represent the largest single-site consumption clusters.
India
Jharkhand's coal belt and Rajasthan's zinc-lead mines drive ammonium nitrate demand for bulk explosive formulation. The PLI scheme for critical chemicals enables domestic backward integration into feedstock production. Singrauli and Udaipur industrial corridors concentrate procurement volumes as mining contractors reduce import dependency for explosive precursors.
Explosives for Civil Uses Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration and environmental compliance capabilities. The sector exhibits tiered consolidation with integrated service platforms commanding service-linked premiums over discrete chemical suppliers. Three archetypes dominate: multinational mining service integrators with software-enabled blast optimization, regional formulators with captive ammonium nitrate supply, and specialized emulsion developers for challenging geology. Capacity expansion in Western China and strategic partnerships for electronic detonation technology represent the dominant competitive moves.
Within the integrated service tier, Orica Mining Services and AEL Mining Services represent platform-based competitors bundling physical supply with drill-pattern optimization software. Solar Industries anchors the regional formulator archetype through Indian subcontinent and African market presence with upstream chemical manufacturing integration. Maxam Corp exemplifies the specialized formulation developer, competing on emulsion chemistry for wet-hole and environmentally sensitive applications where standard products underperform.
| Leading Market Players |
|---|
| Austin Powder Company |
| Solar Industries |
| Orica Mining Services |
| Hanwha Corp |
| Incitec Pivot |
| Enaex |
| AEL Mining Services |
| AECI Group |
| Maxam Corp |
| Others |
Pricing and Supply Chain Analysis
Ammonium nitrate feedstock costs cascade through emulsion manufacturing tiers, with procurement scale separating integrated miners from spot-market quarry operators across Australian copper belts and European tunneling corridors.
Pricing Analysis
Fragmentation efficiency per tonne of rock moved anchors value-based pricing for bulk explosives, with Australian iron ore contractors paying premiums for blast optimization software bundling. Price differentiation rests on environmental certification grade and wet-hole performance specifications under EU F-Gas Regulation compliance tiers. Cost compression in commodity ANFO blends is intensifying because mining houses are insourcing fragmentation modeling. Junior quarry operators in emerging markets exhibit highest price sensitivity, while tier-one copper miners prioritize detonation precision over unit cost.
Supply Chain Analysis
REACH chemical registration and OSHA workplace certification create multi-year qualification gates that freeze out non-compliant suppliers from European and North American procurement lists. Manufacturing concentrates in China, India, and select EU chemical corridors for emulsion precursors. The supply chain draws from ammonia synthesis, fuel oil blending, and specialized detonator electronics as critical inputs. Single-source vulnerability runs through concentrated ammonium nitrate production nodes. Distribution feeds from regional blending plants through mining contractor logistics networks to blast hole loading operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
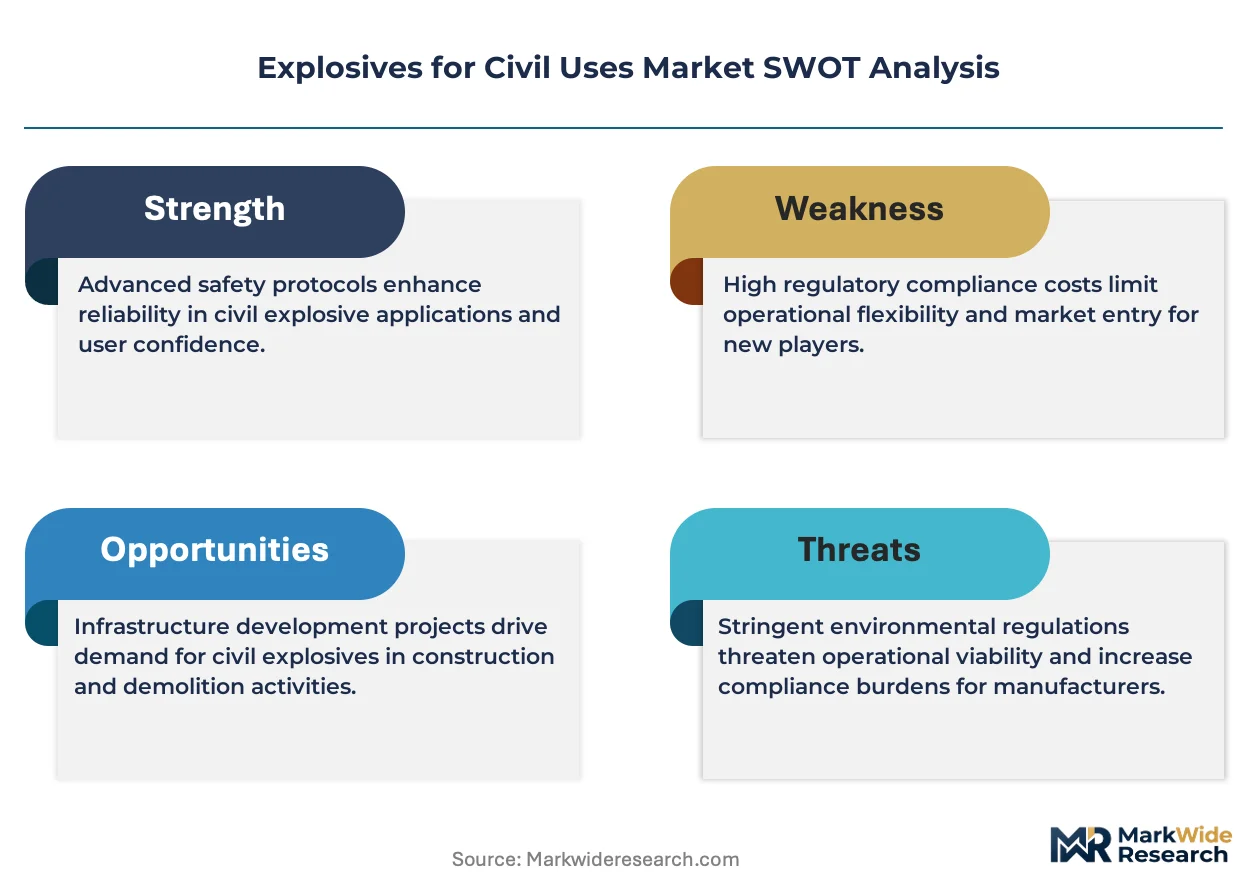
The explosives for civil uses market operates as a cost-of-compliance story where REACH and EU F-Gas Regulation create regulatory moats that reward pre-qualified incumbents while raising entry barriers for unproven suppliers.
For Market Incumbents: Cement service-linked pricing power by deepening backward integration into ammonium nitrate production in Indian and African chemical corridors. Defend against mechanical rock breaking substitutes by accelerating electronic detonator deployment for vibration-sensitive urban demolition. Capacity addition in Western China's Sichuan-Yunnan tunneling belt captures infrastructure-driven demand growth.
For New Entrants and Emerging Players: The mid-tier price gap between premium emulsion systems and commodity ANFO offers white-space entry for certified regional formulators. Target wet-hole compatible explosives for hydropower construction in Southeast Asian markets where established players lack local blending infrastructure. Pursue joint venture licensing with state-owned mining contractors to bypass capital-intensive manufacturing buildout.
For Investors and Strategic Acquirers: Electronic detonator adoption rates crossing threshold penetration in Scandinavian underground mining is the leading indicator that digital blast optimization platforms will command sustained premium multiples. Long-term viability favors suppliers with integrated software-chemistry capabilities over discrete chemical manufacturers. Monitor SAMR enforcement actions against non-compliant Chinese producers as signal for regional consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonium Nitrate | Captures feedstock margin and insulates against supply concentration risk in key manufacturing corridors. |
| Electronic Detonator Platform Deployment | Displaces pyrotechnic caps in Australian and Chilean copper operations requiring millisecond precision timing. |
| REACH-Compliant Emulsion Reformulation | Unlocks premium positioning in European quarrying where F-Gas Regulation tightens emission thresholds. |
| Blast Optimization Software Bundling | Creates switching costs for mining contractors insourcing fragmentation modeling while outsourcing chemistry. |
| Western China Manufacturing Footprint | Positions for rail tunnel and hydropower demand in Sichuan-Yunnan infrastructure corridor. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with mining procurement directors, emulsion plant managers, blasting engineers, and explosives distribution channel partners. Primary fieldwork covered Australian iron ore operations, Chilean copper belts, and Chinese tunneling projects. Secondary sources included EPA emission databases, ECHA REACH registration filings, SAMR GB standard publications, and mining contractor procurement disclosures. Bottom-up volume modeling triangulated against top-down market sizing across product and application segments.
Reconciliation of production capacity data, import-export flows, and end-use consumption patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, deployment mode, and regional regulatory cluster. CAGRs derived from weighted average of historical trajectory and demand driver elasticity. Industry-specific inputs incorporated copper extraction intensity curves, tunnel construction project pipelines, and electronic initiation system replacement rates.
Underlying measurement precision varies by segment; electronic detonators and premium emulsion systems carry tighter precision than commodity bulk explosives due to concentrated supplier reporting. Forecasts incorporate assumptions regarding regulatory enforcement continuity, raw material price stability, and substitution technology penetration. A model refresh is warranted upon material change in EU F-Gas Regulation implementation timelines or major ammonium nitrate supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Land-Based Remote Weapon Stations Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Middle East and Africa Ammunition Market
Weapons and Ammunition
Tank Ammunition Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Space Weapons Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Detonator Market