
 Asia-Pacific Self-Adhesive Labels Market | 2026-2036
Asia-Pacific Self-Adhesive Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Self-Adhesive Labels Market Outlook
Food-grade adhesive specifications is redrawing procurement priorities across the Asia-Pacific Self-Adhesive Labels Market. Avery Dennison Corporation leverages its materials science portfolio to dominate premium pressure-sensitive segments. LINTEC Corporation anchors Japanese demand through precision coating capabilities and pharmaceutical-grade certifications. 3M competes on industrial durability standards for logistics and electronics applications.
Self-adhesive labels are pressure-sensitive constructions comprising a face stock, adhesive layer, and release liner, manufactured through coating, lamination, and die-cutting processes to enable peel-and-stick application without heat or moisture activation. Plastic labels lead value contribution due to moisture resistance and shelf-life extension in tropical climates, while digital printing technology is displacing flexographic workflows for short-run customization and variable-data compliance coding. The food and beverage application segment sustains the largest volume footprint, though healthcare labeling is deepening traceability requirements with serialization mandates.
China's SAMR enforces GB standards for food-contact label materials, while India's BIS mandates adhesive safety certifications for consumer goods packaging. Japan's METI guidelines shape chemical disclosure protocols for electronics and pharmaceutical labels. Stakeholders must monitor evolving substrate restrictions under REACH-aligned regulations in export-facing supply chains and calibrate capital allocation between digital press upgrades and liner recycling infrastructure.
Market Dynamics
Food-contact safety mandates and serialization requirements for pharmaceuticals are compressing label procurement cycles across the Asia-Pacific region. Manufacturers must now validate adhesive formulations against evolving national standards while integrating track-and-trace capabilities into existing production lines.
Growth Catalysts
- India's BIS certification tightening:Consumer goods packaging now requires documented adhesive safety testing, forcing converters to upgrade material specifications and creating premium-grade demand.
- Pharmaceutical serialization mandates:Healthcare regulators in Japan and South Korea require unit-level traceability codes, expanding variable-data label volumes for cold-chain therapeutics.
- Digital press adoption:Short-run customization for craft beverages and specialty foods is displacing conventional flexographic workflows in Guangdong and Zhejiang manufacturing clusters.
Market Restraints
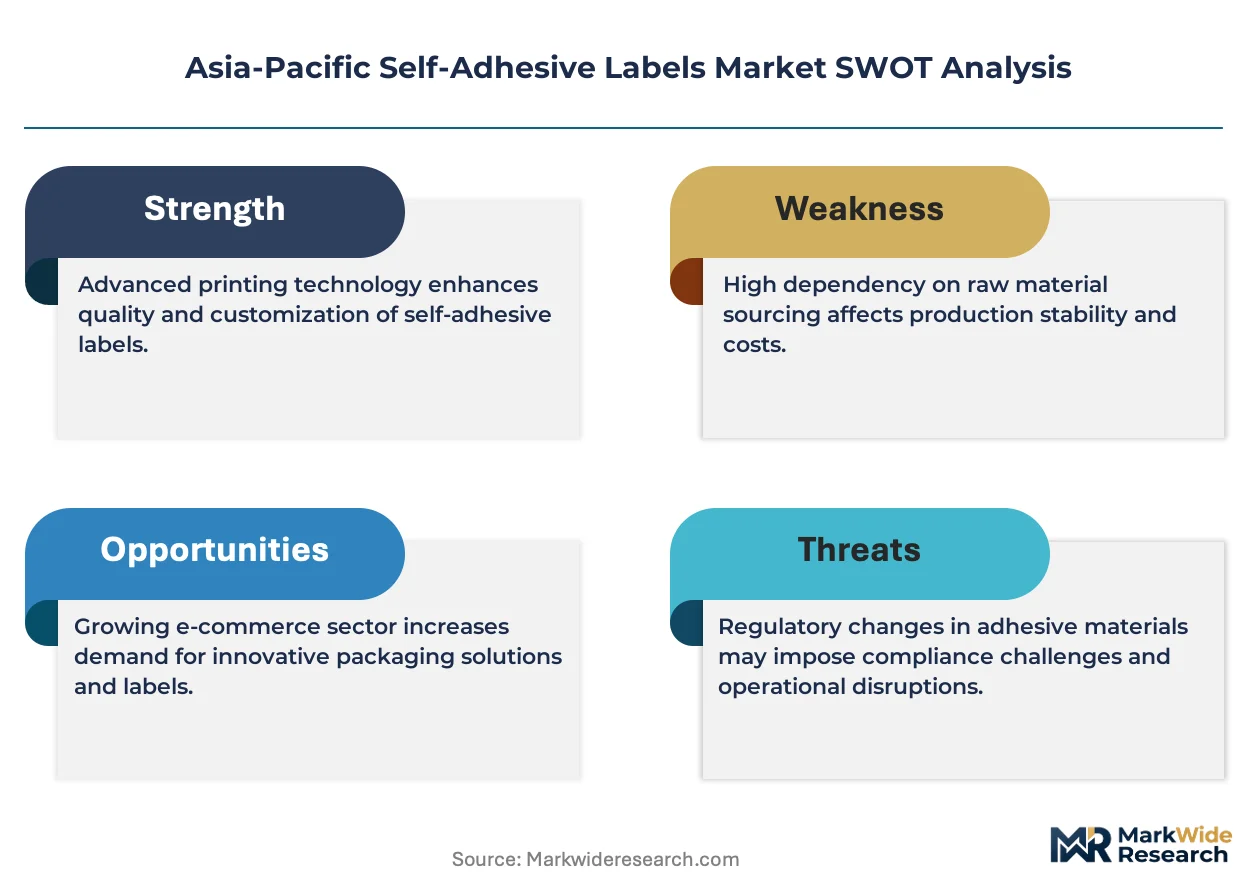
- Silicone release liner cost volatility:Petrochemical feedstock fluctuations constrain margin stability for pressure-sensitive constructions, particularly affecting mid-tier converters.
- Substrate concentration in East Asian suppliers:Face stock films and specialty papers cluster among limited Japanese and South Korean producers, creating supply vulnerability during logistics disruptions.
- Substitution by direct-to-container printing:Inkjet and laser marking systems for rigid packaging bypass label application entirely in high-volume beverage and personal care lines.
Strategic Opportunities
- Southeast Asian manufacturing expansion:Vietnam and Indonesia's electronics assembly growth creates demand for anti-static and high-temperature resistant labels currently underserved by local suppliers.
- China's dual carbon goals:SAMR incentives for recyclable packaging accelerate linerless and wash-off adhesive development for export-facing food brands.
- E-commerce logistics labeling:Thermal transfer and direct thermal formats for last-mile tracking represent white space as regional parcel volumes outpace infrastructure investment.
Industry Challenges
- Cross-border certification timelines:Harmonizing GB standards, JIS specifications, and BIS requirements for multi-territory product launches extends qualification periods by 6-12 months.
- Digital workflow integration:Legacy flexographic operations face capex burdens for hybrid presses capable of both long-run efficiency and short-run personalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Self-Adhesive Labels Market |
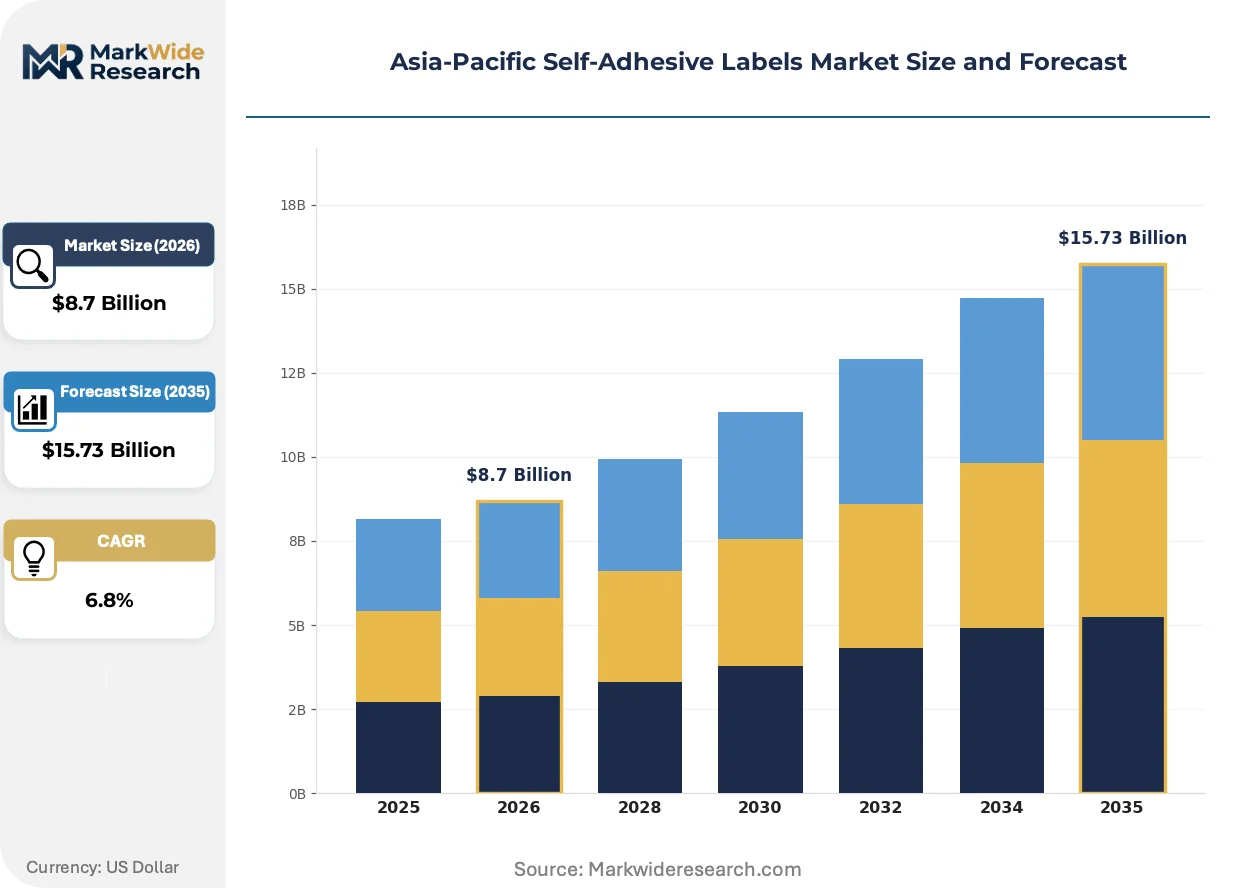
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Labels, Plastic Labels, Vinyl Labels, Hybrid Labels Application: Food & Beverage, Healthcare, Retail, Logistics Technology: Flexographic, Digital, Gravure, Letterpress End User: Manufacturers, Distributors, Retailers, Exporters |
| Companies Covered | LINTEC Corporation, H B Fuller Company, Avery Dennison Corporation, UPM, Multi-Color Corporation, 3M, CCL Industries, JK Labels, Fuji Seal Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Self-Adhesive Labels Market Strategic Shifts
Material science advances and regulatory disclosure requirements are fragmenting traditional supply relationships across the Asia-Pacific label value chain. Converters now compete on formulation transparency and circularity credentials rather than unit cost alone.
Water-based acrylic adhesives with food-contact compliance are decomposing the dominance of solvent-borne systems in tropical-climate packaging. Japanese beverage exporters and Australian dairy processors have adopted these formulations to meet METI and FSANZ migration limits. The shift is compressing solvent recovery infrastructure investments while expanding coating line modifications for humidity-stable acrylic polymerization.
China's SAMR enforcement of GB 4806 series standards for food-contact materials is disqualifying legacy adhesive chemistries from import channels. Foreign-owned food brands operating in Shanghai and Shenzhen must now submit comprehensive substance migration testing. The pharmaceutical and infant nutrition segments have responded fastest, requiring suppliers to maintain dual-certified stock inventories.
Brand owners in Australia's premium wine and Japan's craft spirits sectors now mandate batch-level provenance coding accessible via smartphone scan. This behavioral pivot disrupts traditional trade-only label specifications, forcing converters to embed NFC or QR-linked variable data as standard. The requirement is most visible in export-facing operations where consumer-facing transparency commands shelf price premiums.
Asia-Pacific Self-Adhesive Labels Market Segmentation
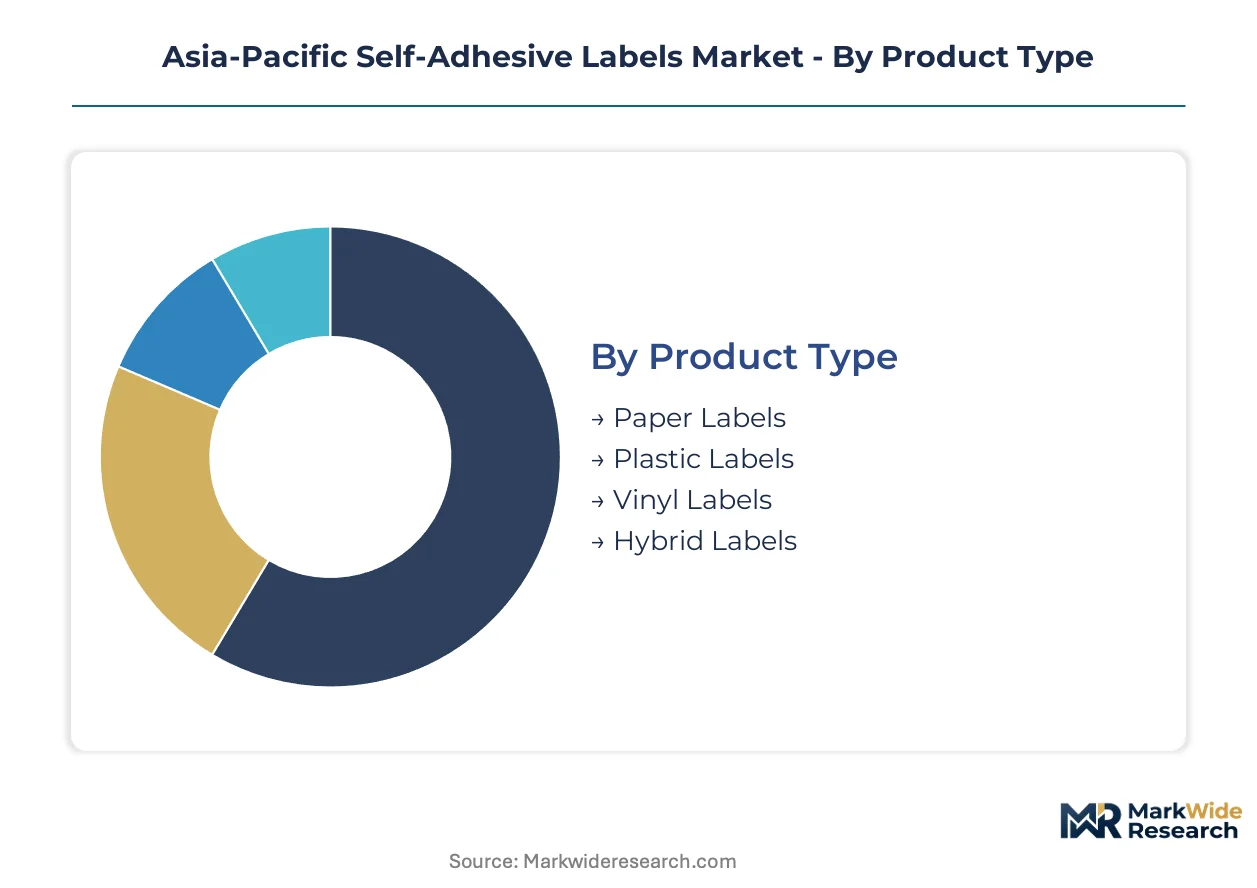
Segmentation in the Asia-Pacific Self-Adhesive Labels Market reveals how substrate choices and printing technologies diverge across tropical climate requirements, pharmaceutical serialization mandates, and e-commerce logistics expansion. Understanding these splits enables converters to align capital deployment with the highest-margin application clusters.
Product Type:
Substitution pressure from direct-to-container inkjet systems weighs heaviest on commodity paper grades, while moisture-resistant synthetics defend their position through climate-specific performance advantages.
- Plastic Labels:Polypropylene and polyethylene face stocks deliver moisture resistance and dimensional stability critical for refrigerated beverage logistics across Guangdong and Zhejiang manufacturing belts. Japanese pharmaceutical exporters specify these substrates for cold-chain compliance with METI migration limits.
- Paper Labels:Uncoated and coated paper stocks dominate cost-sensitive retail tagging and dry-goods packaging, though tropical humidity accelerates adhesive failure rates and drives converter migration toward synthetic alternatives.
- Vinyl Labels:PVC and cast vinyl constructions serve outdoor durability requirements for industrial equipment tagging and automotive component tracking in Southeast Asian assembly operations.
- Hybrid Labels:Paper-film laminates combine printability with moisture barriers for premium food exports facing Australia's FSANZ contact-material scrutiny.
Plastic labels retain volume leadership; hybrid labels hold the steepest expansion curve as export-facing brands seek dual-performance specifications.
Application:
Margin concentration follows regulatory stringency, with healthcare and food-contact segments commanding certification premiums over generic retail applications.
- Food & Beverage:The largest volume footprint spans packaged goods, bottled beverages, and ready-to-eat meals across China's manufacturing belts. SAMR enforcement of GB 4806 standards forces adhesive migration testing and disqualifies uncertified suppliers from import channels.
- Healthcare:Pharmaceutical serialization mandates in Japan and South Korea require unit-level traceability codes, expanding variable-data label volumes for cold-chain therapeutics and compressing procurement cycles.
- Retail:Price marking and promotional labels face margin compression from direct thermal printing adoption in fast-fashion and mass-market grocery chains.
- Logistics:Thermal transfer and direct thermal formats for last-mile tracking represent white space as regional parcel volumes outpace infrastructure investment across Vietnam and Indonesia.
Food and beverage retains volume leadership; healthcare holds the steepest expansion curve driven by serialization compliance.
Technology:
Capital efficiency divides the installed base, with digital presses capturing short-run flexibility while flexographic lines defend long-run unit economics.
- Digital:Inkjet and toner-based systems enable short-run customization for craft beverages and specialty foods, displacing conventional workflows in Guangdong and Zhejiang clusters. Variable-data integration supports pharmaceutical serialization mandates.
- Flexographic:Rotary letterpress and flexo units maintain cost leadership for high-volume beverage and personal care lines, though legacy operations face capex burdens for hybrid press upgrades.
- Gravure:Cylinder-based printing sustains premium cosmetic and decorative label segments requiring metallic effects and fine-line detail reproduction.
- Letterpress:Relief printing persists in security document and tax stamp applications where substrate thickness and ink opacity specifications exceed flexographic tolerances.
Flexographic retains volume leadership; digital holds the steepest expansion curve as converter fleets modernize.
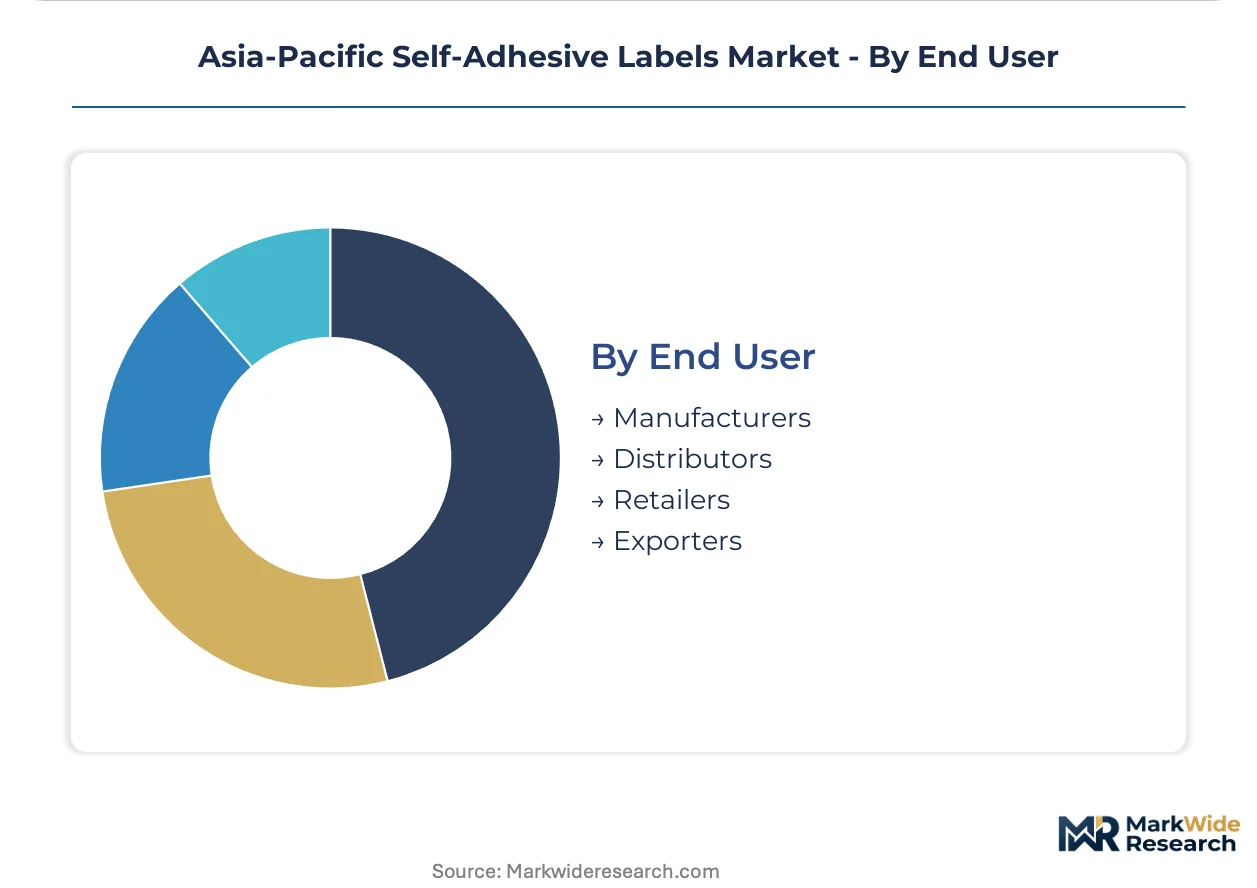
End User:
Procurement sophistication stratifies across the value chain, with exporters and manufacturers driving specification upgrades while distributors prioritize inventory velocity.
- Manufacturers:Consumer goods producers in China's Pearl River Delta specify food-contact-compliant adhesives and batch-level provenance coding accessible via smartphone scan, forcing converter transparency on formulation disclosure.
- Exporters:Australian wine and Japanese craft spirits brands mandate dual-certified stock inventories meeting both domestic and destination-market migration limits, extending qualification periods.
- Distributors:Wholesale label converters aggregate demand from mid-tier food processors and regional retailers, competing on turnaround speed rather than certification depth.
- Retailers:Private-label grocery chains and fast-fashion outlets source standardized thermal and direct thermal formats through centralized procurement, squeezing converter margins on volume contracts.
Manufacturers retain volume leadership; exporters hold the steepest expansion curve as cross-border certification requirements deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows across the Asia-Pacific Self-Adhesive Labels Market reveal stark asymmetries. China and Japan dominate outbound shipments of certified label stocks. Vietnam and Indonesia remain net importers of specialized adhesive formulations.
China
Guangdong and Zhejiang manufacturing belts generate the region's highest label consumption volumes for electronics and food packaging. SAMR enforces GB 4806 series standards for food-contact materials, disqualifying legacy adhesive chemistries from import channels. Shanghai and Shenzhen converters now maintain dual-certified stock inventories for foreign-owned food brands.
Japan
Pharmaceutical serialization mandates and precision coating capabilities anchor domestic demand for premium pressure-sensitive labels. METI guidelines shape chemical disclosure protocols for electronics and pharmaceutical labels. Kanto and Kansai industrial corridors concentrate coating line investments serving beverage exporters and cold-chain therapeutics.
India
Consumer goods packaging drives label procurement across Maharashtra and Gujarat manufacturing clusters. BIS mandates adhesive safety certifications, forcing converters to upgrade material specifications and creating premium-grade demand. Delhi-NCR and Bangalore distribution hubs aggregate demand from mid-tier food processors requiring documented migration testing.
South Korea
Electronics assembly and semiconductor logistics generate demand for anti-static and high-temperature resistant labels. MFDS pharmaceutical serialization requirements expand variable-data label volumes for cold-chain therapeutics. Seoul Capital Area and Busan-Ulsan corridors concentrate thermal transfer format production for regional parcel tracking.
Australia
Premium wine and craft spirits exports mandate batch-level provenance coding accessible via smartphone scan. FSANZ contact-material scrutiny drives adoption of water-based acrylic adhesives with food-contact compliance. New South Wales and Victoria converters embed NFC or QR-linked variable data as standard for export-facing operations.
Asia-Pacific Self-Adhesive Labels Market Competitive Environment
Concentration sits with diversified materials science conglomerates and precision coating specialists. The vendor base stratifies across three tiers: multinational adhesive and substrate suppliers with integrated coating capabilities, regional converters serving national certification requirements, and specialty players focused on pharmaceutical-grade or electronics-grade specifications. Dominant competitive moves include backward integration into silicone release liner production and strategic partnerships with digital press manufacturers for hybrid workflow deployment.
Within the multinational tier, Avery Dennison Corporation, LINTEC Corporation, and 3M occupy positions defined by materials science depth and regulatory certification breadth. Avery Dennison exemplifies the premium pressure-sensitive archetype through its integrated face stock and adhesive portfolio. LINTEC anchors Japanese demand through precision coating capabilities and pharmaceutical-grade certifications. 3M represents industrial durability standards for logistics and electronics applications. These entities sit within a competitive set where formulation transparency and circularity credentials now outweigh unit cost in procurement decisions.
| Leading Market Players |
|---|
| LINTEC Corporation |
| H B Fuller Company |
| Avery Dennison Corporation |
| UPM |
| Multi-Color Corporation |
| 3M |
| CCL Industries |
| JK Labels |
| Fuji Seal Inc |
| Others |
Value Chain & Pricing Dynamics
Water-based acrylic adhesive migration from solvent-borne systems simultaneously redistributes coating capacity toward Guangdong humidity-controlled facilities and compresses premium pricing spreads for legacy formulations. This substitution dynamic forces converters to recalibrate procurement between Japanese precision coaters and emerging Chinese suppliers with SAMR-certified polymerization lines.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on BIS certification depth and volume scale, with pharmaceutical-grade adhesives commanding substantial premiums over commodity retail grades. Pricing pressure stems from silicone release liner petrochemical volatility squeezing mid-tier converter margins. Fast-fashion retailers exhibit highest price sensitivity, while Japanese pharmaceutical exporters demonstrate lowest sensitivity due to METI-mandated compliance requirements.
Supply Chain Analysis
Inventory cycles for specialty face stocks now stretch 8-12 weeks as Japanese and South Korean substrate producers throttle output. Geographic concentration centers on China, Japan, and South Korea for coated films and release liners. Raw material dependencies include silicone polymers, acrylic resins, and biaxially oriented polypropylene. Single-source vulnerability pervades pharmaceutical-grade adhesive formulations qualified to MFDS specifications. Distribution runs through converter networks in Pearl River Delta and Kanto industrial corridors serving brand-owner specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified coating capacity scarcity defines competitive advantage, as converters struggle to dual-qualify stocks for both GB 4806 and BIS migration limits. The gap between qualified supply and cross-border demand expansion creates asymmetric returns for capability holders.
For Market Incumbents: Shield premium positioning through captive silicone release liner production and accelerated certification for India's BIS adhesive safety mandates. Direct-to-container inkjet substitution threatens commodity paper label volumes; backward integration into specialty face stock coating defends margin structure against petrochemical volatility. For New Entrants and Emerging Players: Lead with anti-static and high-temperature resistant label formulations targeting Vietnam and Indonesia electronics assembly growth. Southeast Asian manufacturing expansion remains the most penetrable geography. A technical sales model emphasizing SAMR pre-certification accelerates qualification timelines for export-facing food brands. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision coating specialists with dual-territory certification depth. Long-term viability hinges on converter acquisition of pharmaceutical-grade capabilities and linerless technology IP. Watch MFDS serialization mandate expansion as the inflection signal for variable-data label demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Release Liner Production | Captive silicone supply stabilizes margins against petrochemical volatility for Guangdong converters. |
| Dual Certification Investment | Simultaneous GB 4806 and BIS qualification opens multi-territory procurement for export-facing brands. |
| Digital Press Fleet Modernization | Hybrid inkjet-flexographic capacity captures pharmaceutical serialization and craft beverage personalization demand. |
| Linerless Adhesive Development | Wash-off formulations align with SAMR recyclable packaging incentives for carbon-neutral export brands. |
| Southeast Asian Distribution Partnership | Vietnam and Indonesia electronics assembly creates localized supply for anti-static label specifications. |
Study Parameters
Operator-level perspectives from label converters, adhesive formulators, brand-owner procurement managers, and SAMR compliance consultants anchored the qualitative base. Primary interviews triangulated against secondary sources including BIS certification registries, SAMR GB standard filings, Japan Pharmaceutical Excipients Council disclosures, and MFDS serialization guidance documents. Bottom-up volume estimates from substrate consumption patterns reconciled with top-down value projections across coating capacity utilization.
Sensitivity analysis tested forecast robustness across adhesive raw material cost scenarios and regulatory implementation timelines. Segmentation modeling incorporated product type, application vertical, printing technology, and end-user procurement sophistication dimensions. CAGRs derived from fitted growth curves applied to base-year consumption estimates, with cross-validation against capital expenditure announcements from precision coating line investments.
The analysis sits within stated boundaries; outcomes outside sustained BIS enforcement intensity or accelerated SAMR substrate restrictions would require recalibration. Forecasts reflect documented assumptions regarding certification timeline standardization and digital press adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Barcode Label Printer Market
Labels
Braille Labels Market
Labels
Pin Feed Labels Market
Labels
Freezer Label Market
Labels
Eco-Friendly Labels Market
Labels
HAZMAT Labels Market
Labels
Multi-Part Labels Market
Labels
Laser Markable Labels Market
Labels
India Print Label Market
Labels
Waterproof and Weatherproof Label Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Thermal Labels Market
Labels
Holographic Scratch-Off Labels Market
Labels
Europe Self Adhesives Label Market
Labels
Glue Applied Automotive Labels Market
Labels
Domed Labels Market