
 Global QR Code Labels Market | 2026-2036
Global QR Code Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Global QR Code Labels Market Foresight
The EU Green Deal is rebalancing material sourcing priorities across European label converters. Avery Dennison Corporation leverages its pressure-sensitive materials portfolio to serve pharmaceutical and logistics clients with certified sustainable substrates. CCL Industries Inc. anchors its position through specialized healthcare and consumer packaging divisions across multiple continents. Zebra Technologies Corporation competes on printing hardware and enterprise software integration, extending its influence beyond labels into full traceability ecosystems.
QR code labels are optically machine-readable tags comprising square matrix patterns encoded with data, typically printed on paper, polyester, or polypropylene substrates using thermal transfer or digital processes, designed to link physical products to digital information repositories. Thermal transfer printing dominates pharmaceutical serialization due to durability and regulatory compliance requirements, while digital printing captures fastest growth in short-run retail and apparel customization where variable data and rapid turnaround matter. Permanent adhesive formulations lead logistics and electronics applications where label detachment creates liability, though removable adhesives gain share in apparel and promotional retail where clean removal protects brand presentation.
The FDA enforces drug supply chain security requirements that mandate unit-level traceability, while EMA serialization rules under the Falsified Medicines Directive compel QR-enabled verification across EU member states. REACH chemical restrictions and evolving substrate sustainability criteria from ECHA reshape adhesive and face-stock formulation choices for converters serving regulated industries. Stakeholders must monitor alignment between printer hardware refresh cycles, substrate certification timelines, and evolving serialization mandates across multiple jurisdictions to capture replacement demand and avoid compliance gaps.
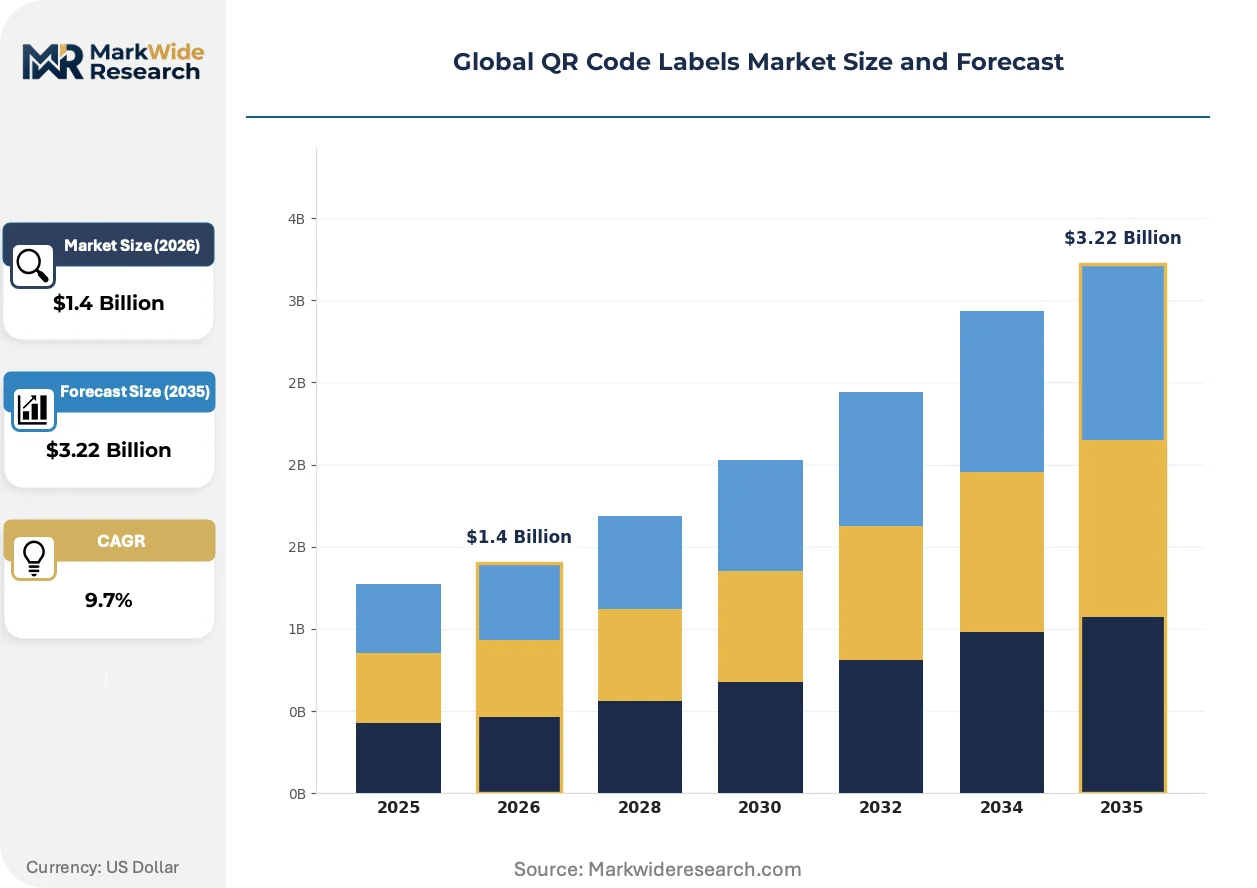
Market Dynamics
Serialization mandates across pharmaceutical supply chains are forcing label converters to reconfigure production lines for unit-level traceability, compressing equipment refresh cycles and substrate certification timelines simultaneously.
Growth Catalysts
- Falsified Medicines Directive:EMA serialization rules compel QR-enabled verification across EU member states, creating mandatory replacement demand for pharmaceutical packaging converters.
- Anti-counterfeiting protocols:Pharmaceutical manufacturers deploy QR codes for supply chain traceability, driving substrate durability requirements and thermal transfer printing upgrades.
- Germany:Pharmaceutical packaging investments and industrial automation spending remain elevated, concentrating demand for high-performance adhesive formulations and certified substrates.
Market Restraints
- Petrochemical substrate volatility:Polyester and polypropylene face-stock costs fluctuate with crude oil derivatives, squeezing converter margins on long-term pharmaceutical contracts.
- Adhesive formulation constraints:REACH chemical restrictions from ECHA limit solvent-based adhesive options, forcing R&D redirection toward water-based and UV-curable alternatives.
- NFC tag substitution:Near-field communication tags capture share in high-value electronics authentication where contactless verification outweighs optical scanning economics.
Strategic Opportunities
- India:CDSCO pharmaceutical traceability guidelines are tightening, opening demand for serialization-capable label converters as domestic generic drug exports expand.
- Digital printing convergence:Variable data capabilities merge with short-run retail customization, enabling apparel and promotional segments to bypass minimum order constraints of flexographic workflows.
- EU Green Deal:Certified sustainable substrate mandates create premium positioning for converters with FSC-certified paper and bio-based polyethylene portfolios.
Industry Challenges
- Printer hardware obsolescence:Legacy thermal transfer systems lack the resolution and speed for next-generation 2D barcode densities, forcing capital-intensive line upgrades.
- Multi-jurisdiction compliance:FDA drug supply chain security requirements diverge from EMA serialization protocols, complicating label specification standardization for multinational pharmaceutical clients.
- Substrate certification lag:ECHA evolving sustainability criteria create timing mismatches between adhesive formulation approvals and pharmaceutical customer qualification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global QR Code Labels Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Material: Paper, Polyester, Polyethylene, Vinyl, Polypropylene, Synthetic End User Industry: Retail, Food & Beverage, Electronics, Logistics, Pharmaceuticals, Apparel Printing Technology: Thermal Transfer, Inkjet, Flexography, Laser, Digital, Offset Adhesive Type: Permanent, Removable, Repositionable, High-Tack, Heat-Activated, Water-Resistant |
| Companies Covered | Avery Dennison Corporation, CCL Industries Inc., Zebra Technologies Corporation, Lintec Corporation, Packtica SDN Bhd, Hibiscus plc, Label Logic Inc., Multi-Color Corporation, HERMA GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global QR Code Labels Market Shifts & Advancements
Digital printing architectures are reshaping production economics across short-run segments, while regulatory fragmentation accelerates demand for multi-protocol compliance capabilities in pharmaceutical and logistics verticals.
Digital inkjet systems with single-pass UV curing are expanding into apparel customization and promotional retail, where brands require lot sizes below 500 units with individualized QR-encoded landing pages. Fast-fashion retailers in Spain and Italy adopt these workflows to compress sampling-to-shelf cycles. The technology is expanding into territory previously dominated by thermal transfer, collapsing minimum viable order thresholds and enabling geographic redistribution of production.
EMA serialization amendments under the Falsified Medicines Directive now mandate aggregation of unit-level codes to case and pallet hierarchies. This compels pharmaceutical manufacturers to integrate line-level vision systems with warehouse management software. German and French packaging lines are retrofitting mid-production to capture compliance deadlines, driving demand for print-apply automation with real-time verification.
Brand owners now specify blockchain-verified QR code authentication to combat gray-market diversion, particularly in cosmetics and premium spirits. Distributors in Dubai and Singapore are piloting scan-to-claim loyalty integrations that tie physical product verification to digital wallet incentives. This behavioral pivot is most visible in Gulf Cooperation Council markets, where regulatory scrutiny of parallel imports intensifies alongside consumer smartphone penetration rates.
Global QR Code Labels Market Segmentation
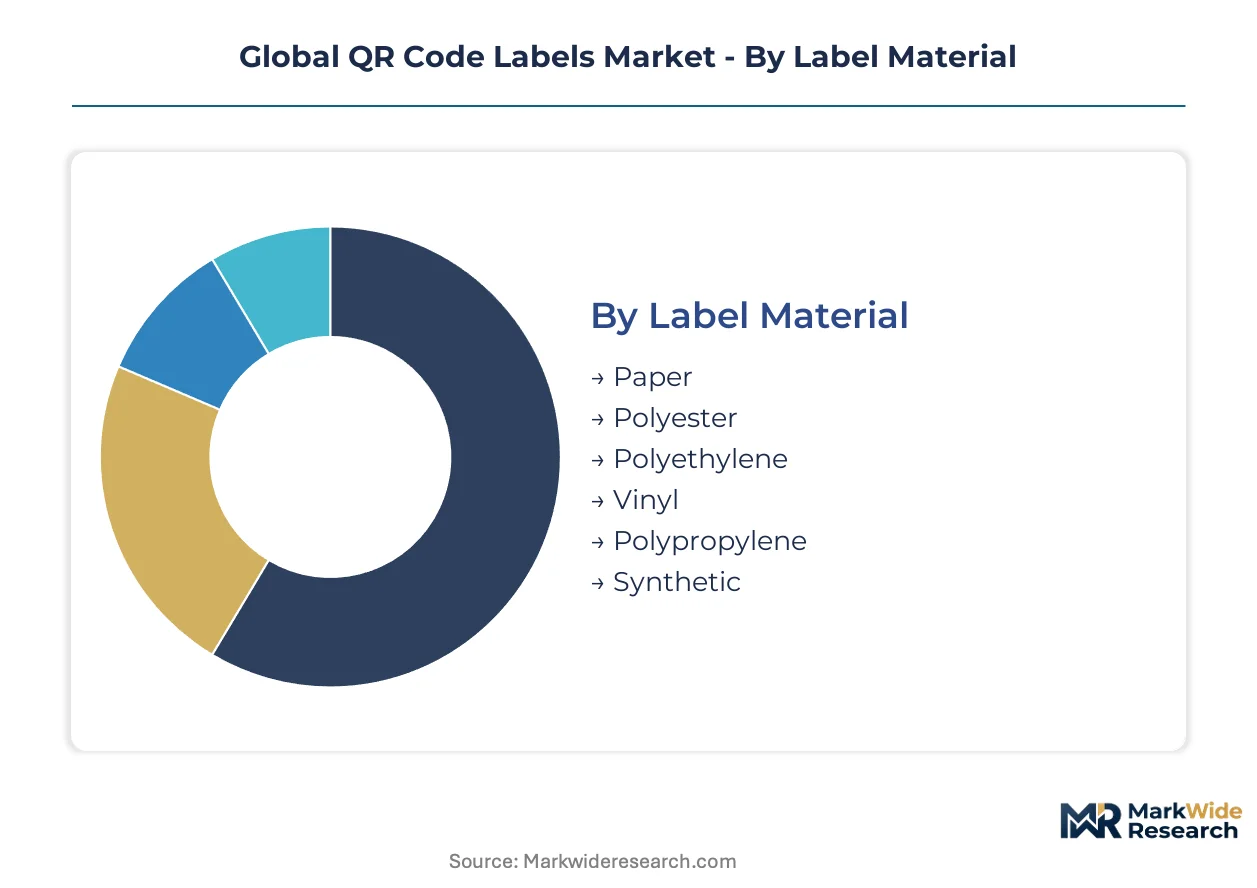
QR code label specifications diverge sharply across end-use environments, from freezer-grade pharmaceuticals to abrasion-resistant electronics. Material selection, printing fidelity, and adhesive chemistry each determine compliance eligibility and unit economics for converters.
Label Material:
Buyers prioritize substrate durability against environmental stressors and regulatory acceptance timelines.
- Paper:Cellulose-based face-stock with pressure-sensitive adhesive backing dominates cost-sensitive retail and promotional applications. German pharmaceutical packagers specify FSC-certified grades to satisfy EU Green Deal procurement mandates.
- Polyester:PET film substrates deliver dimensional stability and chemical resistance for electronics and industrial asset tracking. Demand concentrates in Bavaria's automotive supplier clusters where heat exposure exceeds 150°C during component processing.
- Polyethylene:Flexible LDPE and HDPE variants conform to curved packaging surfaces in personal care and beverage segments.
- Vinyl:PVC-based stocks offer outdoor UV resistance for construction equipment and fleet management tagging.
- Polypropylene:Biaxially oriented PP balances moisture resistance with printability for food packaging requiring refrigeration.
- Synthetic:Engineered non-woven and polymer-blend substrates target extreme environments including cryogenic laboratory storage.
Paper leads on scale; polyester leads on momentum.
End User Industry:
Regulatory serialization mandates and supply chain traceability requirements reshape volume allocation across verticals.
- Retail:Variable-data QR codes enable scan-to-pay integration and dynamic promotional landing pages. Fast-fashion retailers in Spain deploy digital-printed labels for lot sizes below 500 units.
- Food & Beverage:Smart packaging with blockchain-verified provenance addresses consumer transparency demands. French dairy exporters adopt temperature-logging QR labels for cold-chain compliance.
- Electronics:Miniaturized 2D barcodes track component genealogy through multi-tier assembly. Japanese consumer electronics manufacturers specify laser-marked QR codes for space-constrained semiconductor packages.
- Logistics:Unit-load and pallet-level serialization supports warehouse automation and last-mile tracking.
- Pharmaceuticals:EMA Falsified Medicines Directive and FDA Drug Supply Chain Security Act mandate unit-level traceability. German packaging lines retrofit thermal transfer systems to capture compliance deadlines.
- Apparel:Size-specific QR codes link physical garments to digital care instructions and resale authentication platforms.
Pharmaceuticals dominates absolute spend; retail climbs fastest on digital printing convergence.
Printing Technology:
Resolution requirements and run-length economics determine technology selection across converter portfolios.
- Thermal Transfer:Wax-resin and full-resin ribbon systems produce durable, chemically resistant marks for pharmaceutical serialization. EMA aggregation mandates drive line-level upgrades in French and German facilities.
- Inkjet:Piezoelectric drop-on-demand systems enable high-speed variable data without plate changes. Indian generic drug exporters adopt single-pass UV inkjet for export-compliant serialization.
- Flexography:Rotary letterpress analog workflow retains cost advantage in long-run beverage and food primary packaging.
- Laser:Ablation and annealing processes create permanent marks on metal, glass, and synthetic substrates without consumables.
- Digital:Electrophotographic and inkjet architectures collapse minimum order thresholds for short-run customization.
- Offset:Lithographic reproduction maintains quality leadership in high-volume commercial printing with subsequent QR overprinting.
Thermal transfer leads on regulatory compliance attach rate; inkjet gains share fastest on variable-data flexibility.
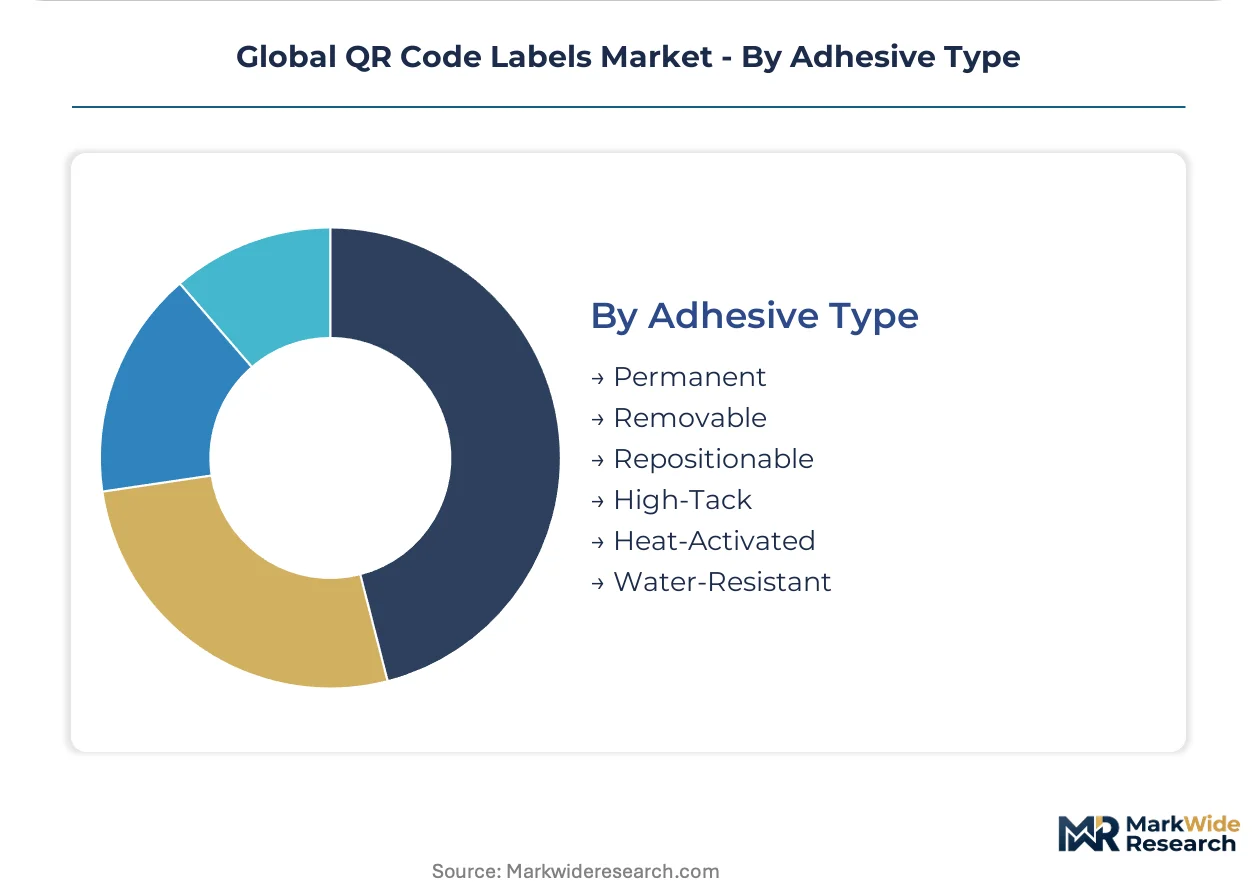
Adhesive Type:
Surface chemistry and removal requirements dictate formulation selection more than label face-stock specifications.
- Permanent:Acrylic and rubber-based pressure-sensitive adhesives form irreversible bonds with metals, glass, and corrugated substrates. Electronics manufacturers in Shenzhen specify solvent-free permanent formulations for RoHS compliance.
- Removable:Low-tack acrylics enable clean removal from premium packaging without residue or fiber tear. Italian cosmetics brands mandate removable adhesives for limited-edition promotional cartons.
- Repositionable:Microsphere adhesive structures allow multiple attachment cycles for inventory management and temporary signage.
- High-Tack:Aggressive initial grab formulations adhere to low-surface-energy plastics and powder-coated metals.
- Heat-Activated:Thermosetting adhesives require thermal triggering for bonding to silicone-treated release liners and textile applications.
- Water-Resistant:Cross-linked polymer matrices maintain adhesion through condensation, immersion, and pressure-wash exposure.
Permanent dominates volume; removable expands most quickly on premium packaging presentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized label converting talent clusters in Germany's Rhine-Main and Bavaria regions anchor European pharmaceutical serialization capacity, while comparable concentrations in Shenzhen and Mumbai support electronics and generic drug export demand respectively.
United States
FDA Drug Supply Chain Security Act mandates drive pharmaceutical unit-level traceability investments across New Jersey and North Carolina packaging corridors. Serialization hardware upgrades concentrate near Princeton and Research Triangle Park, where contract packagers serve multinational drug manufacturers.
Germany
EMA aggregation requirements under the Falsified Medicines Directive compress equipment refresh cycles for Bavarian and North Rhine-Westphalian converters. Düsseldorf-area label producers retrofit thermal transfer lines to capture compliance deadlines for export-bound pharmaceutical clients.
China
Domestic generic drug serialization guidelines from NMPA tighten alongside electronics traceability requirements for export markets. Shenzhen and Dongguan manufacturing clusters integrate QR-enabled component tracking for consumer electronics supply chains serving global brands.
India
CDSCO pharmaceutical traceability mandates expand as domestic generic drug exports accelerate toward regulated markets. Ahmedabad and Hyderabad label converters invest in serialization-capable equipment to qualify for EU and US pharmaceutical packaging contracts.
Japan
METI industrial traceability standards and PMDA pharmaceutical serialization rules shape converter investment priorities. Osaka-area electronics manufacturers specify miniaturized 2D barcode solutions for space-constrained semiconductor and component packaging applications.
Global QR Code Labels Market Competitive Landscape
Capital-heavy substrate producers compete with asset-light design and software integrators across divergent margin structures. The market exhibits tiered consolidation, with multinational material science conglomerates controlling high-volume pharmaceutical contracts while regional specialists capture short-run customization segments. Three archetypes dominate: integrated substrate-to-label converters, hardware-software ecosystem providers, and niche healthcare packaging specialists. Capacity expansion and certified sustainable substrate portfolios represent the primary competitive vectors as regulatory compliance windows narrow.
Within the integrated materials tier, Avery Dennison Corporation and CCL Industries Inc. exemplify capital-intensive positioning through pressure-sensitive and healthcare packaging specializations respectively. Zebra Technologies Corporation occupies a distinct ecosystem-architect role, extending influence from printing hardware into enterprise traceability software. These three entities represent divergent strategic postures: substrate dominance, vertical healthcare focus, and hardware-software convergence.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries Inc. |
| Zebra Technologies Corporation |
| Lintec Corporation |
| Packtica SDN Bhd |
| Hibiscus plc |
| Label Logic Inc. |
| Multi-Color Corporation |
| HERMA GmbH |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters across Germany's Rhine-Main corridor anchor pricing discipline through long-term pharmaceutical contracts, while private-equity-rolled-up specialists in North America compress margins via volume-based substrate procurement. This ownership bifurcation shapes supply behavior: family operators prioritize certification retention over price competition, whereas financial sponsors extract working-capital efficiency from adhesive and face-stock inventories.
Pricing Analysis
Service bundling separates hardware-integrated subscription models from unbundled per-label transactional pricing. Three-tier pricing structure across pharmaceutical-grade certified, industrial-performance, and economy retail levels reflects substrate durability and regulatory qualification depth. Cost compression in economy paper labels is intensifying because Asian converters flood spot markets with non-certified inventory. Pharmaceutical manufacturers show least price sensitivity due to compliance failure costs, while fast-fashion retailers in Southern Europe negotiate aggressively on short-run digital orders.
Supply Chain Analysis
Pharmaceutical-grade substrate qualification gates supply participation, freezing out uncertified converters from EU and US drug packaging contracts. Manufacturing concentrates in Germany, China, and the United States, with Bavarian clusters specializing in thermal transfer ribbon formulation. Raw material sourcing draws from petrochemical derivatives for polyester and polypropylene face-stocks, plus specialty adhesive resins from Japan and South Korea. Single-source vulnerability runs through European adhesive resin suppliers subject to REACH regulatory restrictions. Distribution runs through converter-direct relationships with pharmaceutical contract packagers and electronics OEM procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through substrate certification premiums and digital printing automation that collapses per-unit labor costs. The shift from analog flexographic to single-pass inkjet workflows enables tier-up pricing on previously commoditized short-run segments.
For Market Incumbents: Anticipate NFC tag substitution in high-value electronics authentication by securing thermal transfer line upgrades for pharmaceutical serialization mandates. Defensive positioning requires FSC-certified substrate portfolio expansion to capture EU Green Deal procurement preferences, plus backward integration into adhesive formulation to offset petrochemical volatility.
For New Entrants and Emerging Players: The pricing gap between pharmaceutical-certified and economy retail tiers creates entry space for mid-grade industrial label specialists. India's CDSCO compliance deadline expansion offers the most penetrable geography for serialization-capable equipment investment. Go-to-market execution should target generic drug exporters in Ahmedabad and Hyderabad with equipment-leasing plus substrate bundling.
For Investors and Strategic Acquirers: Healthcare packaging conglomerates are the most active acquirer in this space, rolling up regional converters to secure pharmaceutical contract scale. Long-term viability hinges on digital printing technology transition completion and sustainable substrate certification penetration. The inflection signal to monitor is EMA aggregation mandate compliance failure rates among mid-tier European converters.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Sustainable Substrate Portfolio Expansion | FSC-certified paper and bio-based polyethylene capture EU Green Deal procurement mandates from German pharmaceutical packagers. |
| Single-Pass Digital Inkjet Capacity Addition | UV-cured inkjet systems collapse minimum order thresholds for Spanish fast-fashion retailers requiring sub-500 unit runs. |
| Serialization-Capable Equipment Retrofit | Thermal transfer line upgrades enable EMA Falsified Medicines Directive compliance for French and German packaging facilities. |
| Adhesive Formulation Backward Integration | In-house production of water-based and UV-curable adhesives reduces REACH regulatory exposure and petrochemical cost volatility. |
| Blockchain-Verified Authentication Platform Launch | Scan-to-claim loyalty integrations in Gulf Cooperation Council markets tie physical verification to digital wallet incentives. |
Research Methodology
Multiple input streams — converter production data, pharmaceutical packaging procurement records, and regulatory filing repositories — were reconciled through structured primary interviews and secondary validation. Conversations with label converter operations managers, pharmaceutical packaging procurement directors, adhesive formulation chemists, and digital printing equipment specialists informed demand-side assumptions. Secondary sources included EMA serialization guidance documents, FDA Drug Supply Chain Security Act implementation records, customs trade data for substrate imports, and SEC filings from listed materials companies. Bottom-up volume builds across material, end-use, printing technology, and adhesive segments were cross-checked against top-down market sizing from industry associations.
Historical volume trajectories were cross-referenced against panel input from equipment manufacturers and substrate suppliers to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include label material durability grade, end-use regulatory intensity, printing technology resolution capability, and adhesive permanence specification. CAGRs were derived from fitted growth curves calibrated to equipment installation rates and compliance deadline phasing. Forecast inputs incorporated pharmaceutical serialization mandate timelines, digital printing adoption curves in apparel customization, and sustainable substrate certification penetration rates.
The model assumes a particular technology adoption path; alternative pathways for single-pass UV inkjet would alter the outlook if flexographic cost reduction accelerates unexpectedly. Forecasts reflect assumptions about regulatory enforcement consistency and petrochemical price stability. A model refresh is warranted upon material change in EMA or FDA serialization protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Thermal Transfer Label Market
Labels
Direct Thermal Linerless Labels Market
Labels
Wash Off Labels Market
Labels
Extended Text Labels Market
Labels
Retro-Reflective Labels Market
Labels
Direct Thermal Labels Market
Labels
Industrial Label Printers Market
Labels
Wet Glue Labeling Machines Market
Labels
United States Print Label Market
Labels
Laser Markable Labels Market
Labels
Inventory Tags Market
Labels
Hot Melt Glue Labeler Market
Labels
Linerless Labels Market
Labels
Wire Marking Labels Market
Labels
Glue-Applied Labels Market
Labels
Multi-Part Labels Market