
 Kraft Labels Market | 2026-2036
Kraft Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Labels Market Foresight
Skilled press operators familiar with water-based flexographic ink systems is reorganizing output capacity across the Kraft Labels Market. Avery Dennison Corporation leverages its adhesive science portfolio to dominate high-performance food-contact grades. Mondi Group anchors European supply through integrated pulp-to-label manufacturing. UPM Raflatac competes on sustainable forestry certification, extending its reach into premium personal care accounts.
Kraft labels comprise unbleached wood-pulp paper substrates, typically 60–150 gsm, with alkali-resistant adhesives formulated for cold-chain and moisture-exposed applications. Their primary commercial purpose is to signal ecological authenticity while surviving variable humidity in food logistics. Roll labels lead volume throughput in automated packaging lines, while die-cut labels command margin pools in artisan cosmetics and craft spirits where irregular container geometries predominate. Sheet labels sustain relevance in short-run digital print environments serving boutique home and garden brands.
FDA food-contact substance notifications govern adhesive migration limits in US applications, while EU REACH and Packaging and Packaging Waste Regulation impose recyclability verification and extended producer responsibility fees. These frameworks compel converters to maintain dual-certified substrate inventories and document chain-of-custody for recycled fiber claims. Stakeholders must monitor evolving state-level packaging EPR laws and ink chemistry restrictions to avoid stranded inventory positions.
Market Dynamics
EU Packaging and Packaging Waste Regulation is forcing converters to reengineer adhesive chemistries and fiber sourcing documentation, compressing margins while creating certification-based competitive moats.
Growth Catalysts
- Craft brewing clusters:Germany's dense network of artisan breweries sustains premium die-cut label demand for irregular bottle geometries and moisture-resistant cold-chain performance.
- REACH alkali-resistance mandates:EU adhesive migration limits accelerate adoption of water-based flexographic systems validated for direct food contact.
- Unbleached fiber preference:North American specialty food producers specify tactile kraft substrates to signal ecological authenticity on retail shelves.
Market Restraints
- Pulp cost volatility:Unbleached softwood fiber prices fluctuate with Nordic forestry harvest cycles, squeezing converter margins on fixed-price annual contracts.
- Adhesive supply concentration:European acrylic emulsion production clusters in the Rhine-Ruhr corridor, creating single-source vulnerability for alkali-resistant grades.
- Digital print substrate incompatibility:Standard kraft surfaces exhibit uneven toner adhesion versus coated papers, limiting short-run color variability.
Strategic Opportunities
- Indian FSSAI labeling mandates:New packaged food traceability rules create virgin demand for moisture-resistant kraft labels in emerging cold-chain logistics.
- Home and garden e-commerce:Direct-to-consumer seed and botanical brands adopt sheet-fed digital kraft labels for seasonal SKU proliferation.
- EU Green Deal procurement incentives:Public-sector food service contracts now weight sustainable forestry certification in label supplier selection.
Industry Challenges
- Water-based flexographic expertise scarcity:Skilled press operators capable of managing viscosity and dot gain on uncoated stocks command wage premiums that inflate unit economics.
- Dual-certified inventory complexity:Maintaining parallel FDA food-contact and EU REACH substrate stocks strains working capital and forecasting accuracy.
- Chain-of-custody documentation burden:Recycled fiber claims require third-party audit trails from pulp mill to converter, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Labels Market |
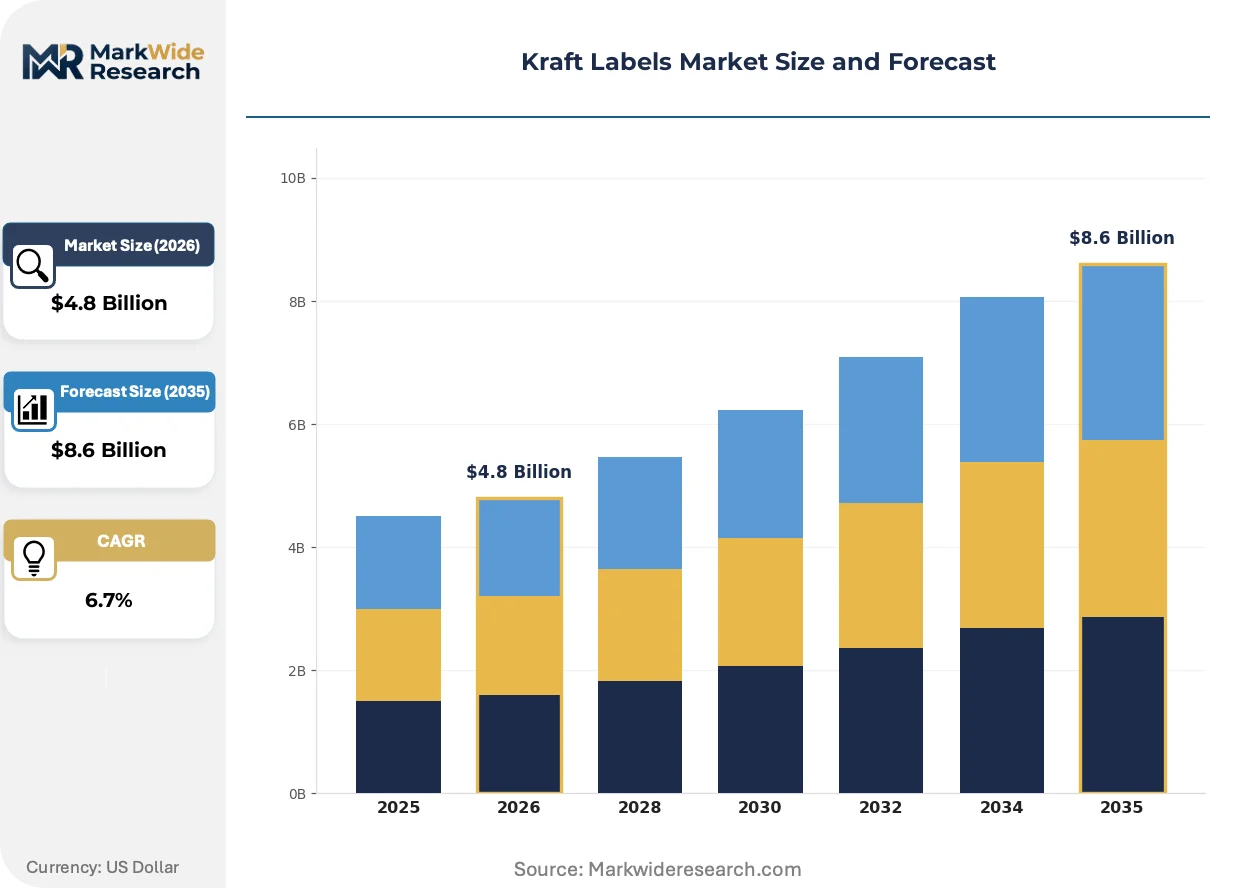
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Kraft Paper, Synthetic, Recycled Paper, Vinyl Label Format: Sheet Labels, Roll Labels, Die-Cut Labels, Custom Shapes End User: Food & Beverage, Personal Care, Home & Garden, Retail Application: Product Labeling, Packaging, Shipping, Branding |
| Companies Covered | Avery Dennison Corporation, Mondi Group, UPM Raflatac, CCL Industries, 3M Company, Multi-Color Corporation, Brady Corporation, Smurfit Westrock, Ahlstrom-Munksjö Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Labels Market Shifts & Advancements
Active developments across substrate engineering, regulatory chemistry, and procurement models are compressing traditional competitive advantages while opening new margin pools for certified specialists.
Algae-derived barrier coatings are fragmenting conventional polyethylene-laminated kraft structures in premium food applications. Artisan cheese and charcuterie producers in France and Italy specify these bio-based layers for compostable packaging claims. The technology is fragmenting incumbent supply relationships by enabling smaller coating houses to compete with integrated pulp majors on performance specifications.
EU F-Gas Regulation phase-down schedules are accelerating ammonia-based refrigeration adoption in European cold-chain logistics. Kraft label adhesives must now validate performance across wider temperature swings from -25°C distribution centers to ambient retail environments. German brewers and Dutch dairy processors are driving reformulation priorities for converters serving these temperature-variable supply chains.
Boutique brand procurement is consolidating through specialized label aggregators that bundle short-run digital print with substrate sourcing. These intermediaries displace direct converter relationships for home and garden, craft spirits, and specialty food accounts. The model is most visible in UK and Scandinavian markets where micro-brand density exceeds in-house procurement team scale.
Kraft Labels Market Segmentation
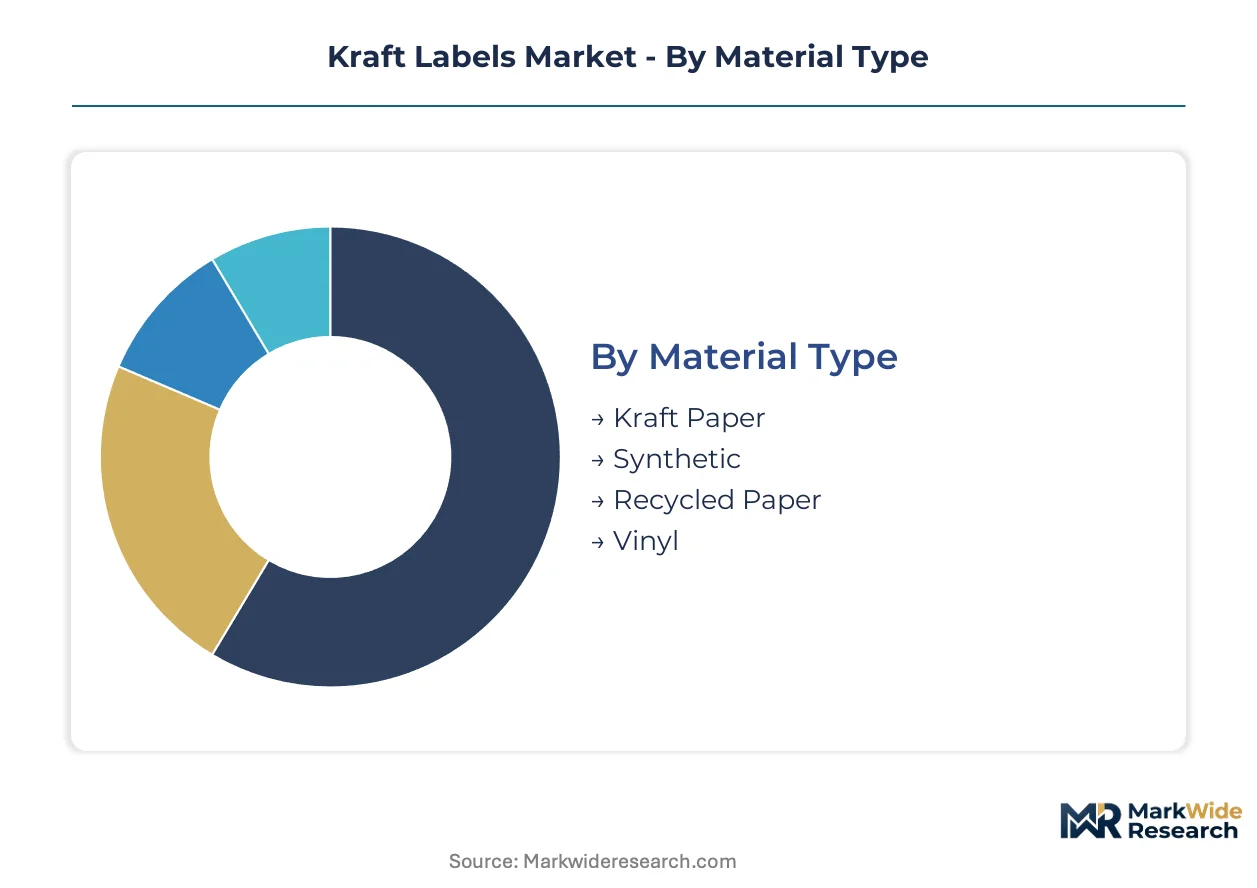
Material chemistry and format geometry determine which supply channels converters prioritize. Kraft labels fragment across four structural dimensions where substrate certification, adhesive migration limits, and container irregularities dictate procurement patterns.
Material Type:
Channel mix splits between integrated pulp majors serving high-volume food accounts and specialty converters supplying boutique cosmetic brands with certified sustainable grades.
- Kraft Paper:Unbleached softwood pulp substrates ranging 60–150 gsm anchor moisture-resistant food-contact applications. German craft brewers and Dutch dairy processors specify these grades for cold-chain performance under EU Packaging and Packaging Waste Regulation traceability mandates.
- Recycled Paper:Post-consumer fiber content requires chain-of-custody documentation from pulp mill to converter. Artisan food producers in France and Italy specify these substrates for compostable packaging claims in premium cheese and charcuterie segments.
- Synthetic:Polypropylene and polyethylene facestocks offer superior tear resistance for industrial logistics applications where humidity extremes exceed paper performance thresholds.
- Vinyl:PVC-based substrates persist in outdoor and chemical-exposure applications despite sustainability headwinds from EU Green Deal procurement incentives.
By volume, Kraft Paper leads. By growth pace, Recycled Paper is expanding most quickly.
Label Format:
Cost tiers separate automated packaging line throughput from short-run digital customization serving micro-brand proliferation.
- Roll Labels:Continuous web formats optimize flexographic and digital press throughput on automated bottling and filling lines. German brewing clusters and Scandinavian dairy processors drive specification standardization for cold-chain moisture resistance.
- Die-Cut Labels:Precision-cut geometries accommodate irregular bottle shapes in craft spirits and artisan cosmetics where container differentiation commands retail shelf attention. UK and Scandinavian label aggregators bundle these with substrate sourcing for micro-brands lacking procurement scale.
- Sheet Labels:Flat formats sustain relevance in short-run digital environments where seasonal SKU proliferation outstrips roll-fed minimum order quantities. Home and garden e-commerce brands in North America specify these for direct-to-consumer seed and botanical packaging.
- Custom Shapes:Irregular die patterns serve premium personal care and gift packaging segments where geometric novelty supports brand positioning.
Roll Labels dominate unit economics through automation. Die-Cut Labels capture the steepest margin expansion trajectory.
End User:
Application maturity varies from regulated food-contact compliance to discretionary retail branding where certification premiums are harder to extract.
- Food & Beverage:Direct-contact adhesives must satisfy FDA food-contact substance notifications and EU REACH migration limits simultaneously. German craft brewing density and Dutch cold-chain dairy infrastructure concentrate converter relationships around dual-certified inventory.
- Personal Care:Premium cosmetic accounts specify sustainable forestry certification from UPM Raflatac and comparable suppliers, extending kraft aesthetics beyond food into tactile brand signaling.
- Home & Garden:Seasonal demand volatility favors sheet-fed digital workflows and aggregator-mediated procurement for seed packets and botanical extracts.
- Retail:General merchandise applications compete on cost with coated paper alternatives, limiting kraft penetration outside sustainability-positioned private labels.
Food & Beverage anchors volume commitments. Personal Care delivers the highest certification premiums per square meter.
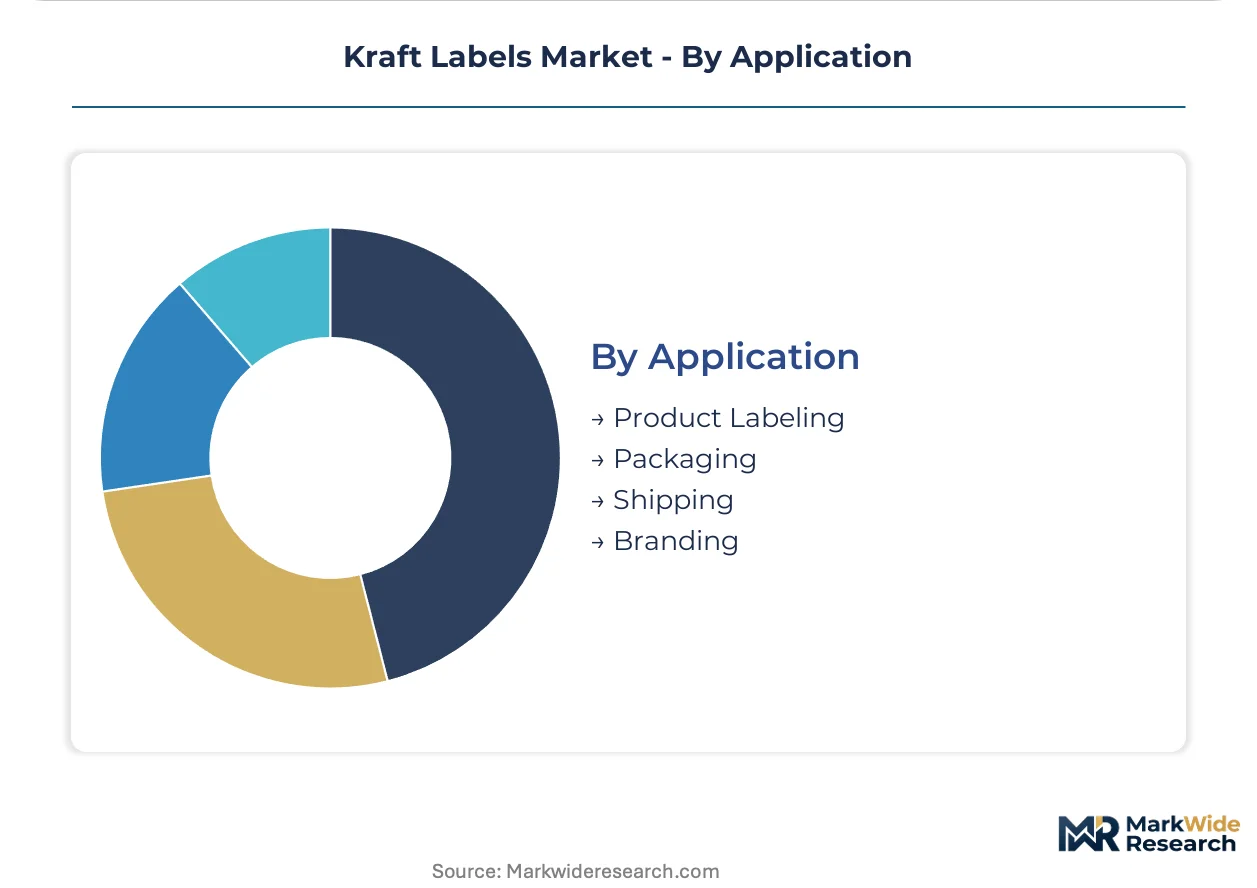
Application:
Functional requirements separate permanent primary labeling from removable logistics marking where adhesive performance specifications diverge.
- Product Labeling:Permanent adhesion on primary packaging demands alkali-resistant formulations validated for moisture and temperature cycling. EU F-Gas Regulation phase-downs are widening temperature swing requirements from -25°C distribution to ambient retail.
- Packaging:Secondary containment labeling balances sustainability signaling with structural integrity for e-commerce shipment.
- Shipping:Removable or destructible adhesives serve logistics tracking where label permanence is undesirable.
- Branding:Promotional and seasonal applications prioritize visual texture over functional durability, opening entry points for algae-derived barrier coatings in compostable claims.
Product Labeling commands the tightest specification compliance. Branding shows the fastest uptake of bio-based coating alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German craft brewers demand die-cut labels for irregular bottle geometries, while Indian cold-chain expansion drives moisture-resistant roll formats. US specialty food producers prioritize tactile unbleached substrates for retail shelf differentiation.
Germany
Artisan brewing clusters in Bavaria and Baden-Württemberg sustain premium die-cut label specifications for moisture-resistant cold-chain performance. EU Packaging and Packaging Waste Regulation imposes strict material traceability documentation on converters serving these accounts. The Rhine-Ruhr corridor concentrates acrylic emulsion adhesive production, creating supply vulnerability for alkali-resistant grades.
United States
Specialty food producers across California and the Pacific Northwest specify unbleached kraft substrates to signal ecological authenticity on retail shelves. FDA food-contact substance notifications govern adhesive migration limits, compelling dual-certified inventory maintenance. Wisconsin and New York dairy processors anchor roll-label demand for automated bottling lines.
India
FSSAI labeling mandates for packaged food traceability create virgin demand for moisture-resistant kraft labels in emerging cold-chain logistics. Maharashtra and Gujarat pharmaceutical exporters extend specifications into personal care segments. Bangalore and Hyderabad e-commerce hubs drive sheet-label adoption for seasonal home and garden SKU proliferation.
France
Artisan cheese and charcuterie producers in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur specify algae-derived barrier coatings for compostable packaging claims. EU F-Gas Regulation phase-downs widen temperature swing requirements from distribution centers to ambient retail. Lyon-based converters reformulate adhesives for -25°C to ambient performance validation.
Netherlands
Dairy processors in North Brabant and Utrecht drive specification standardization for cold-chain moisture resistance across automated filling lines. EU REACH alkali-resistance mandates accelerate water-based flexographic system adoption. Rotterdam logistics infrastructure anchors roll-label volume throughput for re-export throughout Northern Europe.
Kraft Labels Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pulp-to-label manufacturers commanding supply security advantages over substrate-dependent converters. The upper tier captures food-contact certification premiums through captive fiber sourcing and adhesive chemistry control. Mid-scale specialists compete on sustainable forestry documentation and short-run digital flexibility. Dominant competitive moves include backward integration into pulp supply and strategic partnerships with label aggregators serving micro-brand procurement consolidation.
Within the integrated pulp-to-label tier, Mondi Group exemplifies European supply anchoring through manufacturing footprint concentration, while UPM Raflatac occupies a position emphasizing sustainable forestry certification reach. Among substrate specialists, Avery Dennison Corporation represents adhesive science portfolio leverage for high-performance food-contact grades. Smurfit Westrock and Ahlstrom-Munksjö Oyj sit within the fiber-based packaging materials archetype, bridging containerboard and label substrate competencies.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Mondi Group |
| UPM Raflatac |
| CCL Industries |
| 3M Company |
| Multi-Color Corporation |
| Brady Corporation |
| Smurfit Westrock |
| Ahlstrom-Munksjö Oyj |
| Others |
Supply & Pricing Matrix
Algae-derived barrier coatings displacing polyethylene-laminated substrates are redrawing supply geography toward French and Italian coating houses while compressing legacy pricing premiums previously captured by integrated pulp majors. This substitution dynamic simultaneously fragments incumbent supply relationships and introduces cost variability as boutique producers validate bio-based performance specifications.
Pricing Analysis
Contract-based long-term offtake agreements dominate converter-producer relationships, with annual fixed-price commitments covering unbleached softwood fiber and acrylic emulsion adhesive supply. Price differentiation hinges on sustainable forestry certification tier and dual FDA-EU compliance status, with certified grades commanding substantial premiums over standard food-contact substrates. Cost compression in standard kraft grades is intensifying because Nordic pulp harvest volatility squeezes converter margins on legacy contracts. Artisan cosmetics and craft spirits buyers exhibit lowest price sensitivity, while retail private-label procurement teams drive aggressive renegotiation on volume roll formats.
Supply Chain Analysis
Germany and the Netherlands anchor European kraft label production, with the Rhine-Ruhr corridor concentrating alkali-resistant acrylic emulsion manufacturing and Rotterdam anchoring roll-label volume throughput for Northern European re-export. Raw material supply draws from Nordic softwood pulp mills, German adhesive chemical clusters, and emerging algae-coating specialists in Southern Europe. Single-source vulnerability pervades acrylic emulsion production, where Rhine-Ruhr concentration creates disruption exposure for moisture-resistant grades. Distribution runs through specialized label aggregators bundling substrate sourcing with short-run digital print for UK and Scandinavian micro-brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbent positions. Dual FDA-EU certification requirements create switching costs that lock food-contact accounts into validated supplier relationships.
For Market Incumbents: Secure backward integration into Nordic pulp supply to hedge harvest-cycle volatility and protect margin structures on fixed-price annual contracts. Invest in water-based flexographic training programs to alleviate press-operator scarcity that inflates unit economics. Algae-derived coating specialists represent an emerging substitution threat requiring monitoring or partnership evaluation. For New Entrants and Emerging Players: FSSAI certification fast-track for Indian packaged food traceability mandates opens virgin demand in emerging cold-chain logistics where incumbent relationships remain unformed. Target Maharashtra and Gujarat pharmaceutical exporters extending specifications into personal care segments. Home and garden e-commerce in Bangalore and Hyderabad offers sheet-label white space through aggregator-mediated procurement channels lacking procurement scale for direct converter relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed label aggregators serving UK and Scandinavian micro-brand consolidation. Long-term viability centers on regulatory compliance capabilities rather than commodity substrate conversion. Watch for EU Packaging and Packaging Waste Regulation enforcement intensity as inflection indicator for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Nordic softwood fiber sourcing insulates margins from harvest-cycle volatility affecting German converters. |
| Dual Certification Investment | Parallel FDA food-contact and EU REACH compliance opens premium food and beverage account access. |
| Water-Based Flexographic Training Programs | Skilled press operator development alleviates wage-premium inflation on uncoated stock production. |
| Algae-Derived Coating Partnership | French and Italian bio-based barrier validation enables compostable packaging claims in premium cheese segments. |
| Aggregator Channel Alliance | UK and Scandinavian micro-brand bundling displaces direct procurement relationships for short-run digital volumes. |
Research Methodology
The analysis maps kraft paper substrates, recycled fiber grades, synthetic alternatives, and bio-based coating innovations, each validated through converter operations directors, adhesive R&D chemists, food-brand packaging procurement managers, and label aggregator commercial leads. Primary interview findings triangulate against customs and trade data, EU Packaging and Packaging Waste Regulation implementation filings, FSSAI mandate documentation, and sustainable forestry certification audit records. Bottom-up volume modeling from press-line throughput and top-down demand estimation from end-use consumption patterns cross-validate segment-level outputs.
Consistency checks against external benchmarks confirmed analytical framework robustness across the projection horizon. Segmentation dimensions include material chemistry tier, label format geometry, end-use regulatory intensity, and regional cold-chain infrastructure maturity. CAGRs derive from trend-line extrapolation of historical volume relationships adjusted for regulatory inflection points and substitution technology penetration curves. Forecast inputs incorporate EU F-Gas Regulation phase-down schedules affecting temperature-swing adhesive requirements and Indian cold-chain logistics expansion trajectories.
Underlying assumptions cover sustained EU REACH enforcement intensity, stable Nordic softwood harvest cycles, and gradual algae-coating cost parity achievement, with deviation risk concentrated in pulp price volatility and regulatory timeline acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Sheeted Labels Market
Labels
Integrated Labeling System Market
Labels
Wet Glue Labeling Machines Market
Labels
Screen Print Label Market
Labels
India Print Label Market
Labels
Variable Data Printing Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Freshness Indicator Label Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Shrink and Stretch Sleeve Labels Market
Labels
HAZMAT Labels Market
Labels
Extended Text Labels Market
Labels
GCC Labeling Market
Labels
Print Label Market
Labels
Retro-Reflective Labels Market
Labels
Foil Labels Market