
 Freshness Indicator Label Market | 2026-2036
Freshness Indicator Label Market Size, Share, and Industry Trends Forecast 2026-2036
Freshness Indicator Label Market Insights
Multi-source procurement for freshness indicator substrates is shifting toward vertically integrated film suppliers across North America and Asia. Avery Dennison Corporation leverages its adhesive science portfolio to dominate premium labelstock segments for time-temperature applications. CCL Industries sustains manufacturing scale across European converting facilities, anchoring supply security for regional food packagers. Insignia Technologies specializes in color-changing polymer formulations, competing on proprietary chromatic transition speed.
Freshness indicator labels are pressure-sensitive or self-adhesive substrates incorporating thermochromic, enzymatic, or electronic elements that undergo visible state changes when cumulative temperature exposure exceeds programmed thresholds, primarily enabling cold-chain compliance and spoilage prevention in perishable distribution. Time-temperature indicators occupy the largest installed base due to decades of validation in pharmaceutical logistics, though electronic monitoring segments attract the fastest investment as RFID-enabled freshness tracking penetrates premium produce and seafood channels. Chemical sensors command concentrated margin pools where food manufacturers require irreversible color-change verification for regulatory audit trails.
FDA food safety modernization rules and EPA substrate compliance standards shape product design requirements for US-market labels, while REACH and EU Packaging Directive frameworks restrict certain chromogenic compounds in European imports. Stakeholders must monitor evolving interoperability standards between freshness indicators and blockchain traceability platforms before committing to next-generation hardware architectures.
Market Dynamics
Cold-chain logistics providers are mandating real-time spoilage verification as pharmaceutical and fresh food distributors face escalating liability exposure from temperature excursions. This structural pressure is compressing adoption timelines for smart label technologies that integrate chromogenic polymers with electronic tracking architectures.
Growth Catalysts
- EU Packaging Directive amendments:Brussels-based regulators are tightening substrate traceability requirements for perishable imports, forcing packagers to adopt irreversible time-temperature indicators for audit compliance.
- Enzymatic sensor platforms:Food manufacturers deploying bioreactive freshness labels report measurable reductions in retail spoilage returns, accelerating validation studies for seafood and premium produce categories.
- German pharmaceutical cold-chain:Logistics operators serving vaccine and biologics distribution now require calibrated temperature-monitoring labels on all outbound shipments, creating anchored demand for validated indicator stock.
Market Restraints
- Chromogenic compound supply:REACH restrictions on specific organic dyes have eliminated several Asian chemical suppliers from European qualification pipelines, concentrating qualified feedstock sources in Switzerland and Germany.
- Adhesive substrate volatility:Petroleum-derived filmstock prices fluctuate with polymer feedstock markets, compressing margins for converters lacking long-term resin contracts.
- Electronic label cost structure:RFID-enabled freshness trackers remain priced at multiples of chemical indicators, limiting penetration to high-value pharmaceutical and premium seafood segments.
Strategic Opportunities
- Indian cold-chain infrastructure:FSSAI implementation of mandatory temperature documentation for dairy and frozen food distribution creates first-mover positioning for indicator suppliers establishing local converting partnerships.
- Blockchain-traceability convergence:Integration of chromogenic state-change data with distributed ledger platforms enables immutable spoilage records for insurance and liability adjudication.
- Direct-to-consumer meal kits:Subscription food services are experimenting with consumer-visible freshness indicators as brand differentiation tools, opening retail-packaging channels previously closed to industrial-label formats.
Industry Challenges
- Calibration technician scarcity:Electronic indicator deployment requires field engineers capable of validating temperature thresholds against NIST-traceable standards, with qualified personnel concentrated in established pharmaceutical logistics hubs.
- Legacy warehouse management integration:RFID freshness data streams often conflict with existing ERP architectures, requiring middleware development that extends implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freshness Indicator Label Market |
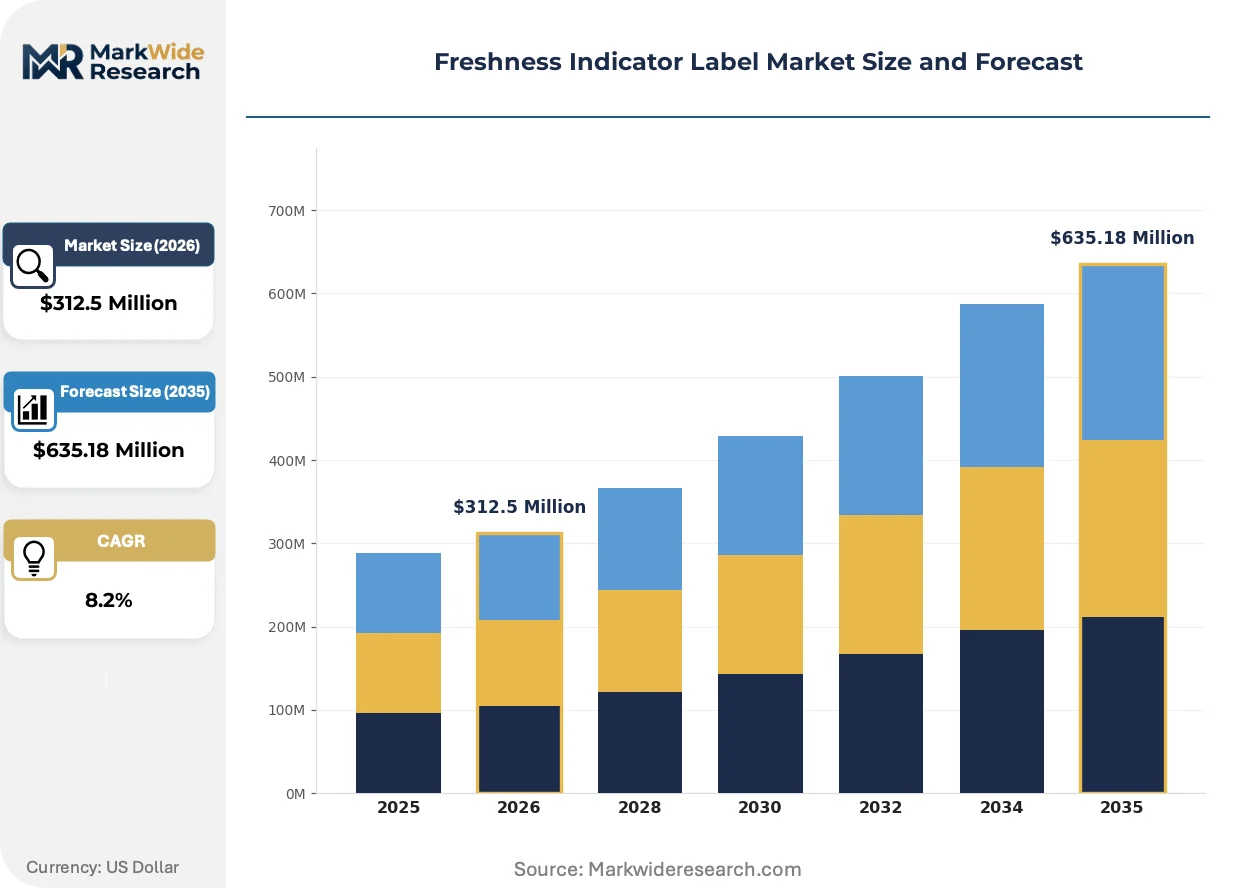
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $635.18 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Sensors, Stickers, Tags Application: Food Preservation, Packaging, Transportation, Retail Technology: Time-Temperature Indicators, Color-Changing Indicators, Electronic Monitoring, Chemical Sensors End User: Food Manufacturers, Logistics Providers, Retailers, Consumers |
| Companies Covered | 3M Company, Avery Dennison Corporation, Zebra Technologies, CCL Industries, DeltaTrak Inc., Insignia Technologies, LCR Hallcrest LLC, Temptime Corporation, NiGK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freshness Indicator Label Market Trends and Innovations
Smart packaging architectures are converging physical state-change verification with digital traceability infrastructure. This fusion is redefining competitive positioning across converter tiers and forcing recalibration of R&D investment priorities.
Printed electronics incorporating nanoscale thermochromic inks are consolidating functional layers previously requiring separate manufacturing steps. Pharmaceutical distributors in Germany and the Netherlands are piloting these integrated substrates for vaccine shipments, reducing label thickness and improving thermal response fidelity. The technology is consolidating mid-tier converter capabilities into specialized film-coating operations with capital-intensive precision deposition equipment.
REACH authorization procedures for novel chromogenic compounds have extended substance approval timelines, forcing formulators to prioritize existing approved dye portfolios over experimental chemistries. European food exporters are responding by dual-sourcing indicator stock from REACH-registered Swiss suppliers and validated Asian converters with European representation. Seafood processors serving EU retail channels face the most acute compliance pressure, with several Nordic packagers accelerating validation of enzymatic alternatives to thermochromic platforms.
Consolidated procurement by multinational food retailers is compressing supplier qualification cycles and demanding standardized data formats across freshness indicator categories. Buyers at major European grocery chains now require API-compatible temperature logs that feed directly into their blockchain traceability platforms. This pattern is most pronounced in Germany, where discounter consolidation has concentrated purchasing power among three retail groups controlling regional fresh produce distribution.
Freshness Indicator Label Market Segmentation
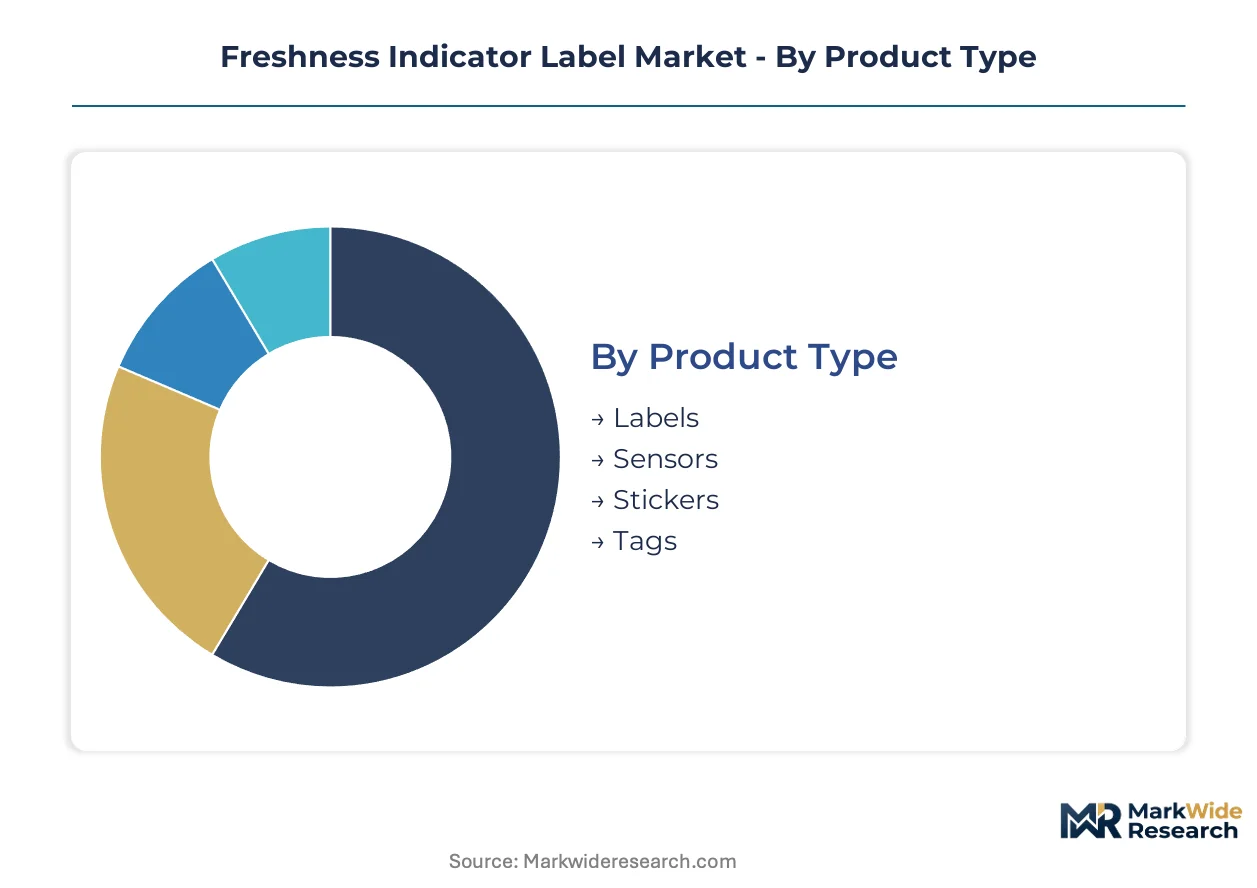
Freshness indicator labels serve divergent compliance and operational requirements across cold-chain stakeholders. Technology selection, application environment, and end-user technical sophistication each reshape procurement specifications and margin structures.
Product Type:
Substrate form factors determine integration complexity with existing packaging lines and the granularity of spoilage data delivered.
- Labels:Pressure-sensitive adhesive substrates dominate pharmaceutical and premium food segments where calibrated temperature thresholds require precise adhesive bonding to primary packaging. German logistics operators mandate these formats for vaccine distribution compliance.
- Sensors:Enzymatic and polymer-based detection elements capture the fastest investment flows as seafood processors seek irreversible spoilage verification for insurance documentation. Nordic packagers are accelerating validation of these platforms for EU retail channel entry.
- Stickers:Consumer-facing formats with visible color-change windows serve direct-to-consumer meal kit differentiation strategies.
- Tags:Detachable indicator formats attach to pallet-level shipments for warehouse management system integration.
Labels lead on scale; sensors lead on momentum.
Application:
Deployment environment dictates durability specifications and regulatory documentation requirements for indicator performance.
- Food Preservation:Static storage applications in refrigerated warehouses demand extended-duration indicators with slow-activation thresholds calibrated for cumulative temperature exposure.
- Packaging:Primary package integration requires thin-film substrates compatible with high-speed converting equipment and food-contact compliance certifications.
- Transportation:Multi-modal shipment tracking commands the steepest expansion trajectory as liability exposure from temperature excursions escalates across pharmaceutical and fresh produce distribution.
- Retail:Point-of-sale visibility applications are gaining share fastest as subscription meal services adopt consumer-readable freshness verification for brand positioning.
Transportation commands premium pricing; retail channels are expanding most quickly.
Technology:
Detection mechanism selection balances capital cost against data granularity and regulatory audit trail requirements.
- Time-Temperature Indicators:Thermochromic polymer platforms with decades of pharmaceutical validation anchor installed base volumes. REACH-registered dye portfolios from Swiss suppliers concentrate qualified feedstock sources for European market access.
- Color-Changing Indicators:Chromogenic formulations undergoing visible state transitions serve cost-sensitive food packaging where irreversible verification satisfies retailer audit protocols.
- Electronic Monitoring:RFID-enabled trackers with real-time data streaming penetrate high-value pharmaceutical and premium seafood segments despite multiples-higher unit economics.
- Chemical Sensors:Enzymatic bioreactive platforms detect specific spoilage metabolites, attracting seafood processor investment for reduced retail return rates.
Time-temperature indicators lead on scale; electronic monitoring leads on momentum.
End User:
Technical sophistication and procurement scale reshape indicator specification requirements and supplier qualification cycles.
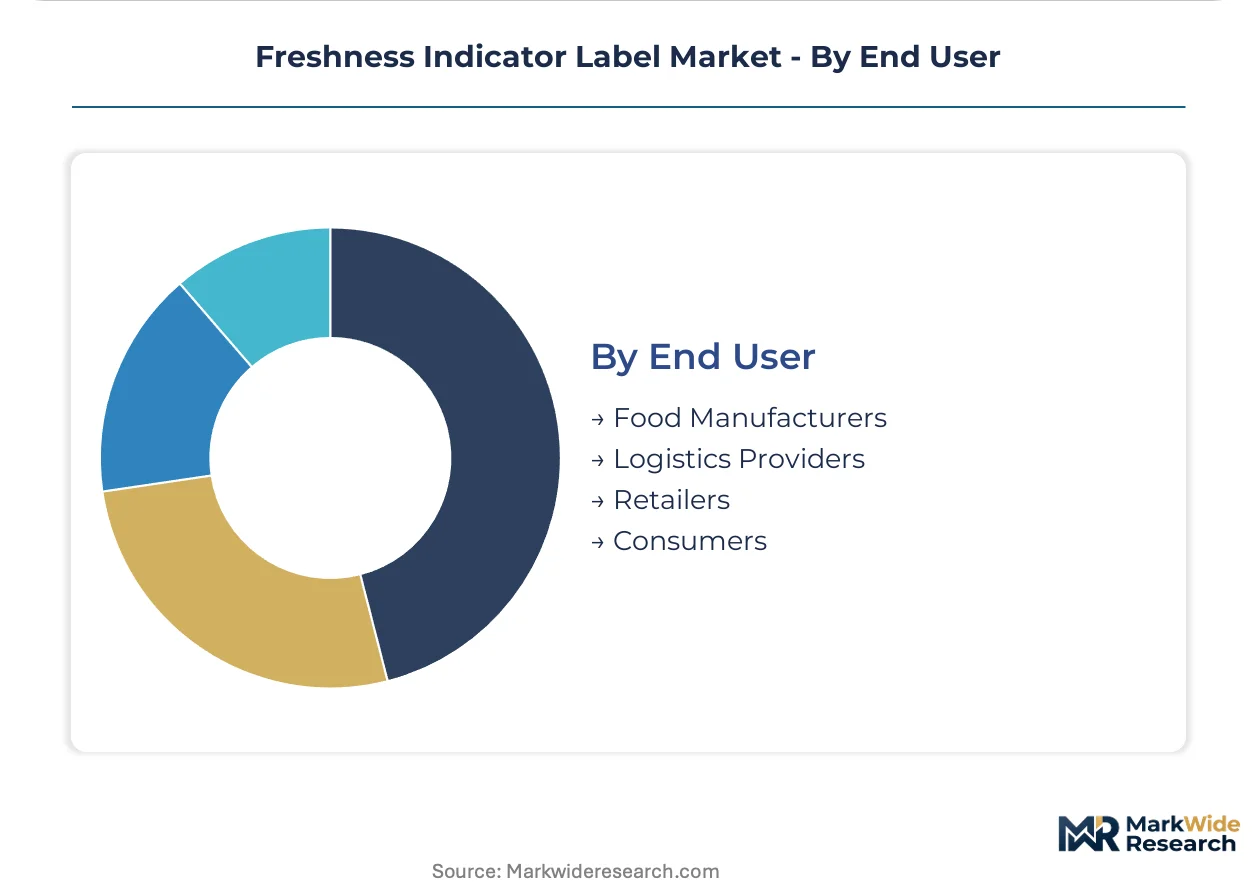
- Food Manufacturers:Packagers with consolidated retail contracts demand API-compatible temperature logs feeding directly into blockchain traceability platforms.
- Logistics Providers:Cold-chain operators in Germany now require calibrated temperature-monitoring labels on all pharmaceutical outbound shipments.
- Retailers:Discounter consolidation in Germany has concentrated purchasing power among three retail groups controlling regional fresh produce distribution.
- Consumers:Subscription meal kit subscribers represent an emerging demand pool for visible freshness verification as a service differentiation signal.
Food manufacturers lead on scale; consumers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cold-chain logistics clusters in Frankfurt and Munich anchor pharmaceutical indicator demand, with REACH-registered dye suppliers in Basel and Ludwigshafen feeding qualified substrate stock into European packaging lines.
Germany
Vaccine distribution mandates from the Paul-Ehrlich-Institut require calibrated temperature-monitoring labels on all pharmaceutical outbound shipments. ECHA REACH restrictions on chromogenic compounds have concentrated qualified feedstock sourcing through Swiss-registered chemical suppliers. The Rhine-Main logistics corridor around Frankfurt houses the densest concentration of cold-chain validation facilities serving EU biologics distribution.
United States
FDA food safety modernization rules drive pharmaceutical and fresh food packagers toward irreversible time-temperature indicators for liability documentation. EPA substrate compliance standards shape adhesive filmstock specifications for domestic label converters. Chicago and Memphis cold-chain hubs are deploying electronic monitoring architectures for high-value produce and seafood shipments.
Switzerland
Swissmedic pharmaceutical traceability requirements position Basel chemical clusters as REACH-registered dye suppliers for EU market access. The country's central bank stability attracts indicator formulators seeking long-term resin contract security. Zurich-area converters specialize in precision-coated thermochromic substrates for vaccine shipment validation.
India
FSSAI mandatory temperature documentation for dairy and frozen food distribution creates first-mover positioning for indicator suppliers establishing local converting partnerships. CDSCO pharmaceutical logistics guidelines are accelerating cold-chain infrastructure investment around Mumbai and Hyderabad. Gujarat chemical parks are emerging as alternative chromogenic compound sources for domestic food packaging lines.
Japan
METI supply chain resilience initiatives promote domestic indicator substrate production for pharmaceutical export security. PMDA temperature excursion reporting requirements for biologics shipments validate time-temperature indicator formats in Osaka-Kobe pharmaceutical logistics clusters. Tokyo-area meal kit subscription services are piloting consumer-visible freshness verification for brand differentiation.
Freshness Indicator Label Market Competitive Landscape
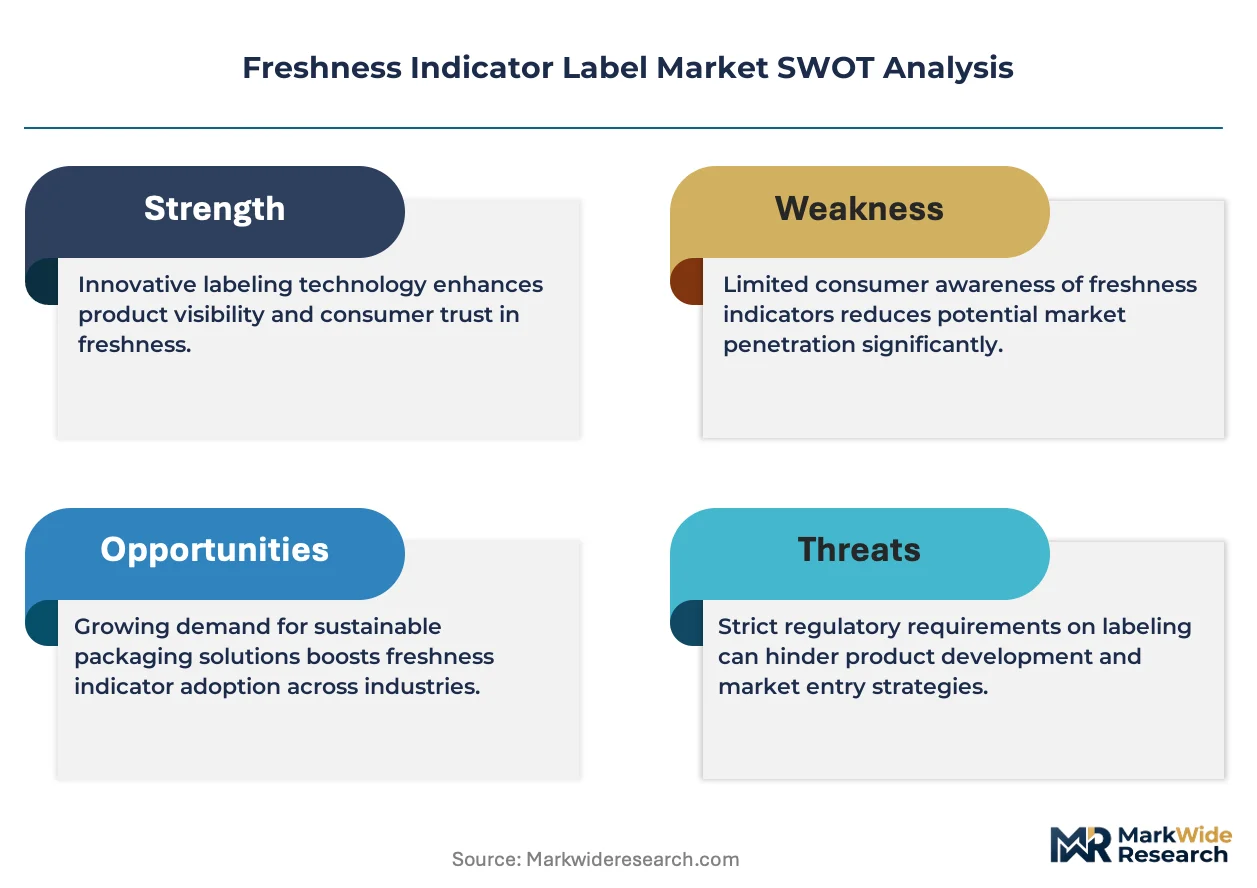
Global majors compete with regional champions across adhesive science and chromogenic formulation capabilities, producing a tiered structure where scale-driven converters face pressure from specialized polymer developers. The market fragments across three strategic archetypes: diversified materials conglomerates with labelstock portfolios, precision coating specialists with REACH-registered dye access, and electronic tracking integrators serving high-value pharmaceutical segments. Competitive moves concentrate on backward integration into film resin supply and technology licensing partnerships for printed electronics deposition.
Among North American materials conglomerates, 3M Company and Avery Dennison Corporation exemplify scale-driven archetypes with adhesive science depth, while CCL Industries represents the European converting specialist model with distributed manufacturing footprint. Insignia Technologies occupies a position within the chromogenic formulation specialist tier, competing on proprietary polymer transition properties. These three anchors illustrate the competitive tension between diversified materials portfolios and focused formulation expertise across freshness indicator segments.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Zebra Technologies |
| CCL Industries |
| DeltaTrak Inc. |
| Insignia Technologies |
| LCR Hallcrest LLC |
| Temptime Corporation |
| NiGK Corporation |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between REACH-registered chromogenic suppliers and unvalidated Asian converters splits both pricing power and procurement geography across the freshness indicator value chain. Pharmaceutical logistics operators in Germany pay substantial premiums for Swiss-registered dye portfolios that satisfy ECHA compliance, while food packagers in India source from domestic Gujarat chemical parks at lower certification tiers.
Pricing Analysis
Input-cost pass-through from petroleum-derived filmstock volatility compresses margins for converters lacking long-term resin contracts. Three-tier pricing structure across premium, standard, and economy levels reflects calibration precision, with NIST-traceable electronic indicators commanding multiples above enzymatic alternatives. Pricing pressure stems from adhesive substrate volatility as polymer feedstock markets fluctuate. Logistics providers show least price sensitivity due to liability exposure, while meal kit subscription services remain most cost-constrained.
Supply Chain Analysis
Workforce availability constraints in precision coating operations concentrate qualified technician pools around Basel and Ludwigshafen chemical clusters. Supply concentrates in Switzerland, Germany, and India, with REACH-registered dye formulators feeding European pharmaceutical channels and Gujarat chemical parks serving domestic Indian food packaging. Chromogenic compound sourcing rests on Swiss-registered suppliers and validated Asian converters with European representation. Single-source vulnerability runs through REACH-authorized dye portfolios where ECHA restrictions eliminated several Asian suppliers. Distribution runs through cold-chain logistics hubs in Frankfurt, Chicago, and Mumbai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory traceability mandates tighten across pharmaceutical and fresh food distribution. Cold-chain liability exposure creates durable demand for validated indicator technologies.
For Market Incumbents: Cement REACH-registered dye portfolio control through backward integration into Swiss chemical suppliers or long-term offtake agreements with Basel formulators. Defend against electronic monitoring displacement by accelerating printed electronics R&D for integrated thermochromic substrates. Capacity addition in Indian converting partnerships captures FSSAI-mandated temperature documentation growth. For New Entrants and Emerging Players: Enter via enzymatic sensor white space in Nordic seafood processing, where irreversible spoilage verification demand outpaces qualified supplier availability. Target Indian dairy cold-chain infrastructure before multinational converters establish local film-coating operations. Go-to-market through FSSAI compliance consulting bundled with indicator supply. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack REACH-registered dye access and face margin compression from petroleum substrate volatility. Long-term viability favors precision coating specialists with pharmaceutical validation credentials and captive resin supply. Watch for CDSCO pharmaceutical logistics guideline acceleration in India as inflection signal for regional demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromogenic Compound Supply | REACH-registered dye access secures European pharmaceutical market entry against ECHA-restricted competitors. |
| Printed Electronics Deposition Capability | Nanoscale thermochromic ink integration consolidates functional layers for vaccine shipment validation in Germany. |
| Blockchain Traceability Platform Partnership | API-compatible temperature logs feed immutable spoilage records for insurance and liability adjudication. |
| Indian Converting Partnership Establishment | FSSAI mandatory temperature documentation creates first-mover positioning in dairy and frozen food distribution. |
| Enzymatic Sensor Platform Validation | Bioreactive freshness labels reduce retail spoilage returns for seafood processors seeking EU channel entry. |
Research Methodology
Bottom-up food manufacturer and logistics provider modeling reconciled against top-down filmstock and adhesive supplier tracking forms the analytical core of this study. Primary interviews with cold-chain operations directors, pharmaceutical packaging engineers, regulatory affairs leads at food manufacturers, and procurement managers at retail grocery chains combined with secondary validation from ECHA REACH substance databases, FDA food safety guidance documents, FSSAI notification records, and customs trade data for chromogenic compound flows.
Input-output matrix framing connects end-use demand segments—pharmaceutical distribution, fresh food logistics, meal kit subscription services, and retail grocery—to upstream substrate supply tiers across thermochromic, enzymatic, and electronic technologies. Segmentation dimensions modeled include product form factor, detection mechanism, application environment, and end-user technical sophistication across the analysis window. CAGRs derived from installed base growth rates calibrated against regulatory mandate implementation timelines and cold-chain infrastructure investment patterns. Forecast inputs incorporate Paul-Ehrlich-Institut vaccine distribution mandates and FSSAI compliance phase-in schedules.
Inputs from ECHA substance registration databases and FDA guidance repositories were available through the study window; gaps in real-time electronic monitoring adoption rates introduce uncertainty bands around high-value segment projections. Forecasts reflect assumptions regarding REACH authorization timelines and CDSCO pharmaceutical logistics guideline evolution. Material deviation in ECHA chromogenic compound restrictions or FSSAI enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global in-Mold Labels Market
Labels
Hang Tags Market
Labels
Sleeve Label Market
Labels
Stretch Sleeve Labels Market
Labels
Wrap Around Labels Market
Labels
Repositionable Labels Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
United States Print Label Market
Labels
Polyester Labels Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Self-Laminating Labels Market
Labels
Primary Packaging Labels Market
Labels
Wash Off Labels Market
Labels
Global Thermal Transfer Label Market
Labels
Glue Applied Automotive Labels Market
Labels
Retro-Reflective Labels Market