
 Ampoule Sticker Labeling Machine Market | 2026-2036
Ampoule Sticker Labeling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Ampoule Sticker Labeling Machine Market Outlook
Equipment leasing and pay-per-label service contracts are reshaping competitive entry in the ampoule sticker labeling machine space. NKP Pharma Pvt Ltd leverages its India-based manufacturing footprint to compete on delivered cost for semi-automatic systems. Marchesini Group S.p.A. anchors its position through integrated packaging lines that bundle labeling with filling and capping. HERMA GmbH differentiates via precision-engineered pressure-sensitive applicators that sustain premium positioning in European pharmaceutical facilities.
An ampoule sticker labeling machine applies self-adhesive labels to small glass ampoules used for sterile injectable pharmaceuticals, typically operating at speeds of 100-400 units per minute with servo-driven dispensing and vision-based verification to ensure label placement within ±0.5 millimeters. Automatic labeling machines dominate current installed base value due to their throughput advantages in high-volume parenteral drug facilities, while digital printing technology represents the fastest-expanding segment as lot-specific variable data replaces pre-printed labels. Pressure-sensitive labeling occupies the largest technology share, though shrink-sleeve applications are gaining share in biologics where tamper-evidence requirements are most stringent.
FDA 21 CFR Part 11 and EU MDR serialization requirements shape equipment specifications by mandating audit trails, electronic signatures, and machine-readable codes on every primary container. ISO 15378 and GAMP 5 guidelines further constrain validation protocols, extending sales cycles but locking in vendor relationships once systems qualify. Stakeholders must monitor evolving national track-and-trace deadlines and decide whether to standardize on modular platforms that accommodate regulatory divergence across manufacturing footprints.
Market Dynamics
Serialization mandates across multiple jurisdictions are forcing pharmaceutical manufacturers to replace legacy labeling equipment, creating a concentrated wave of capital expenditure that favors vendors with validated compliance architectures.
Growth Catalysts
- EU Falsified Medicines Directive:Track-and-trace requirements for parenteral pharmaceuticals mandate machine-readable codes on every ampoule, compelling equipment upgrades across European contract manufacturing facilities.
- Servo-driven dispensing systems:Precision motion control technology enables label placement accuracy within ±0.5 millimeters, satisfying stringent biologics packaging specifications for temperature-sensitive injectables.
- Germany:Precision engineering clusters in Baden-Württemberg and Bavaria supply automated labeling lines to contract manufacturers serving the broader European market, concentrating demand in this manufacturing corridor.
Market Restraints
- Stainless steel and specialty alloys:Input cost volatility for pharmaceutical-grade construction materials compresses margin structures for equipment builders serving price-sensitive emerging markets.
- Validation protocols:ISO 15378 and GAMP 5 compliance requirements extend sales cycles by 12-18 months, locking capital in pre-qualification engineering without revenue recognition.
- Pre-printed label inventory:Existing stockpiles of static labels in mature pharmaceutical facilities create inertia against digital printing adoption despite regulatory mandates for variable data.
Strategic Opportunities
- India:Domestic pharmaceutical production expansion under PLI scheme incentives creates demand for semi-automatic systems that bridge manual operations and full automation.
- Shrink-sleeve technology:Biologics packaging requirements for tamper-evidence and 360-degree branding are opening applications beyond traditional pressure-sensitive labels.
- Equipment leasing models:Pay-per-label service contracts reduce barrier to entry for mid-tier contract manufacturers, converting capital expenditure to operational expenditure.
Industry Challenges
- Validation engineering talent:Scarcity of professionals conversant with FDA 21 CFR Part 11 audit trail requirements and EU MDR electronic signature protocols delays system qualification timelines.
- Legacy line integration:Retrofitting servo-driven labeling heads onto existing filling and capping equipment without disrupting validated pharmaceutical production schedules demands specialized mechanical engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ampoule Sticker Labeling Machine Market |
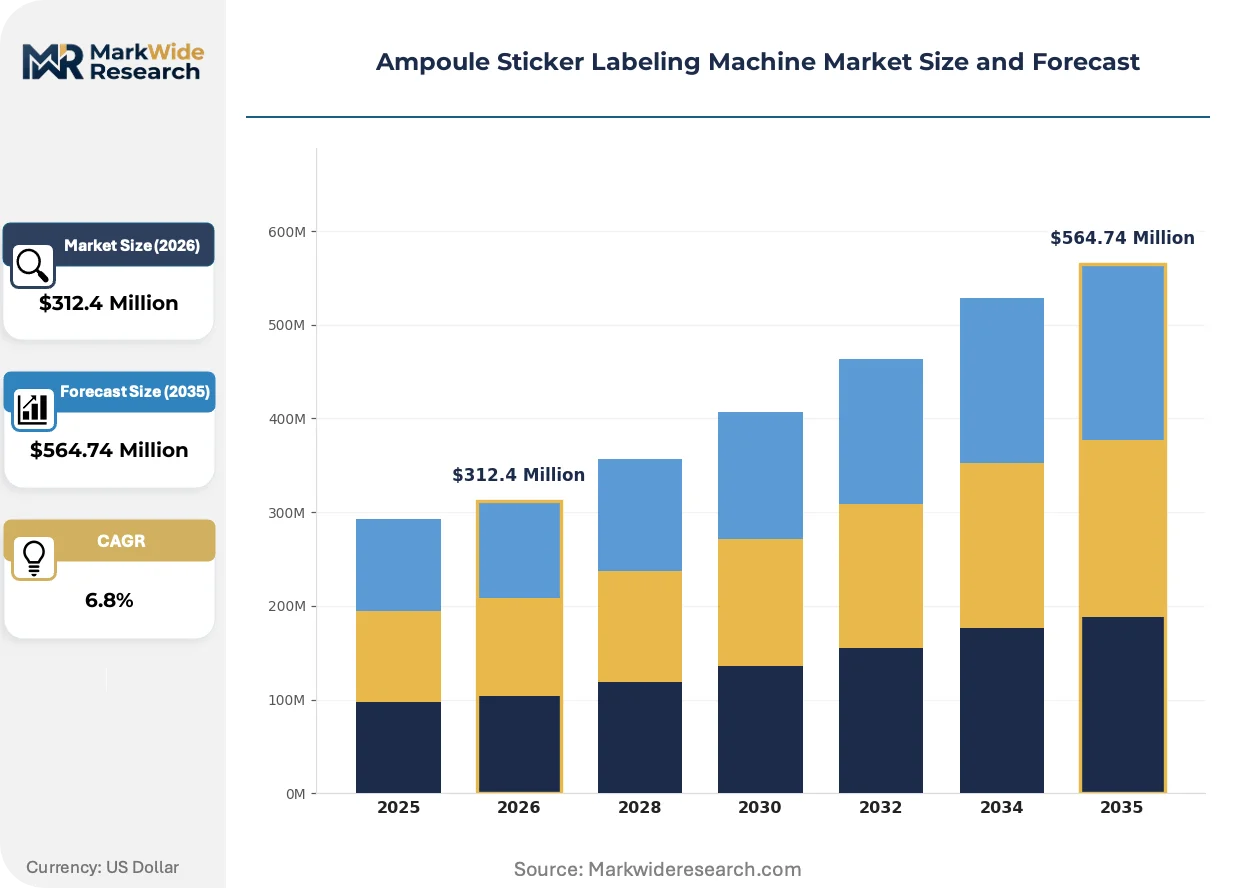
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Labeling Machines, Semi-Automatic Labeling Machines, Manual Labeling Machines, Labeling Applicators End User: Pharmaceutical Companies, Biotechnology Firms, Cosmetics Manufacturers, Food & Beverage Producers Labeling Technology: Pressure-Sensitive Labeling, Shrink-Sleeve Labeling, Wrap-Around Labeling, Digital Printing Application: Vials, Ampoules, Bottles, Tubes |
| Companies Covered | NKP Pharma Pvt Ltd, Viallabeller, Brothers Pharmamach (India) Pvt Ltd, Marchesini Group S.p.A., HERMA GmbH, Multipack Packaging Machinery, Adinath International Inc., Accutek Packaging Equipment Company Inc., Shanghai Skilt Machinery Equipment Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ampoule Sticker Labeling Machine Market Strategic Shifts
Digital printing technology is displacing pre-printed label inventories across pharmaceutical packaging operations, enabling lot-specific serialization and reducing working capital requirements for manufacturers managing multiple SKUs.
Vision-based verification systems are migrating from offline sampling stations to inline 100% inspection configurations. High-volume parenteral drug facilities in Germany and Switzerland are adopting these integrated architectures to eliminate separate quality control bottlenecks. This migration from standalone to embedded verification compresses line footprint requirements and reduces manual handling contamination risks.
FDA 21 CFR Part 11 and EU MDR serialization requirements are mandating audit trails and electronic signatures on every primary container. Equipment specifications now must incorporate tamper-evident data logging and secure user authentication. Automatic labeling machine configurations serving US and European markets are embedding these compliance features as standard rather than optional modules.
Contract manufacturers are consolidating supplier relationships around vendors offering integrated packaging lines rather than standalone labeling equipment. Bundled procurement of filling, capping, and labeling systems reduces validation burden and ensures line-level responsibility. This preference concentration is most visible among European CDMOs serving global pharmaceutical clients with multi-jurisdictional compliance requirements.
Ampoule Sticker Labeling Machine Market Segmentation
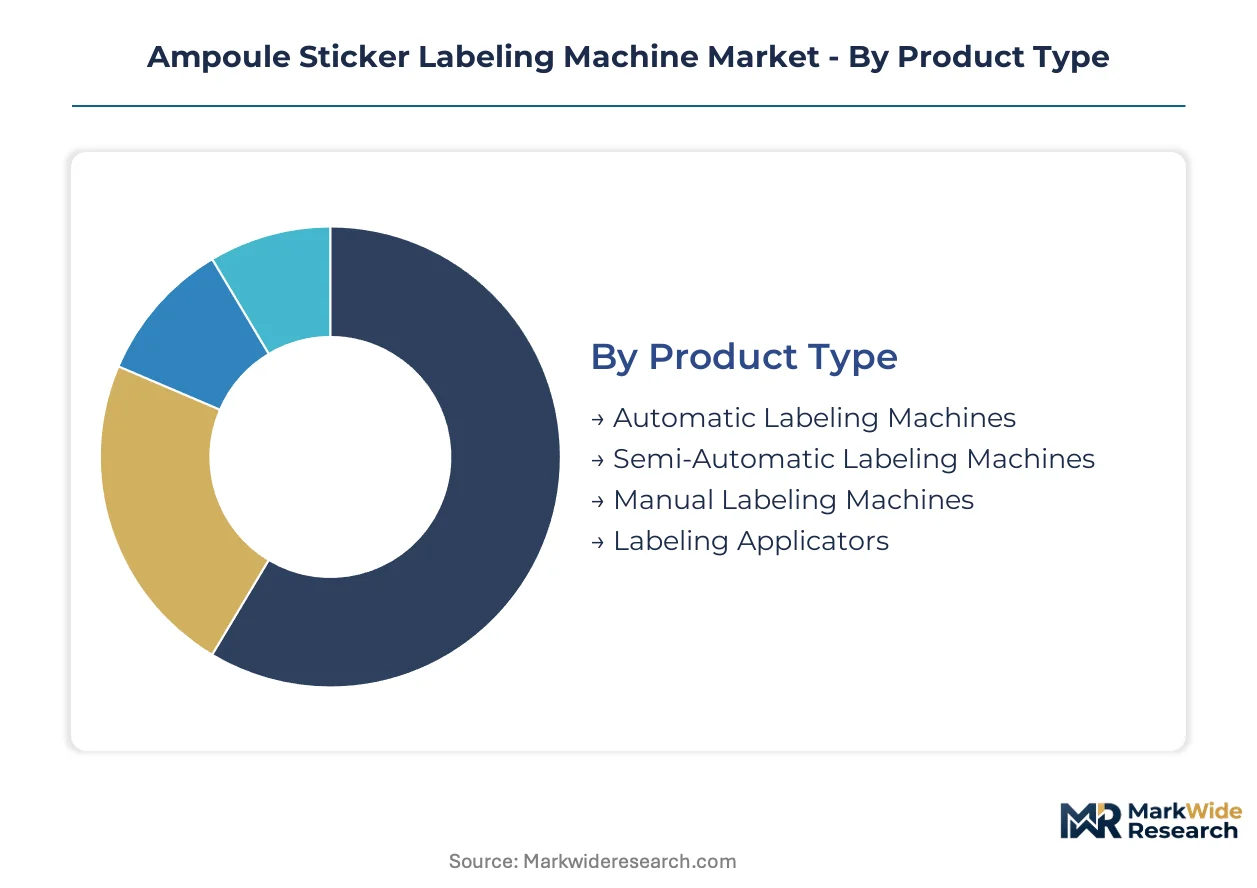
Segmentation in the ampoule sticker labeling machine market reveals distinct procurement patterns across automation tiers and end-use verticals. Equipment specifications diverge sharply between high-volume parenteral drug facilities and smaller batch operations, creating tiered vendor relationships and validation protocols.
Product Type:
Cycle times for labeling equipment span from multi-year capital planning for fully automated lines to quarterly purchasing decisions for manual systems. Servo-driven automatic platforms require 12-18 month qualification timelines, while semi-automatic units turn over on compressed procurement cycles.
- Automatic Labeling Machines:These systems integrate servo-driven dispensing with vision-based verification, operating at 100-400 units per minute with placement accuracy within ±0.5 millimeters. Pharmaceutical facilities in Germany and Switzerland concentrate demand here, driven by EU MDR serialization mandates that eliminate manual verification steps. Automatic labeling machines anchor the volume base while digital printing integration gains share at the steepest rate.
- Semi-Automatic Labeling Machines:Bridging manual operations and full automation, these units suit mid-tier contract manufacturers and emerging market facilities scaling production. India's PLI scheme incentives for domestic pharmaceutical manufacturing are concentrating procurement in this tier, where capital constraints delay fully automated line adoption.
- Manual Labeling Machines:Basic benchtop units serve small-batch compounding pharmacies and research laboratories with minimal throughput requirements.
- Labeling Applicators:Modular dispensing heads retrofit onto existing filling and capping lines, extending equipment life cycles without full line replacement.
Automatic labeling machines anchor the volume base while labeling applicators gain share at the steepest rate among product types.
End User:
Cost tier differentiation separates validation-intensive pharmaceutical procurement from price-sensitive cosmetics purchasing. Biotechnology firms occupy a middle position, demanding precision specifications while accepting shorter equipment life cycles than established drug manufacturers.
- Pharmaceutical Companies:These buyers mandate FDA 21 CFR Part 11 compliance architectures with tamper-evident audit trails and electronic signatures. Serialization requirements across US and European jurisdictions force equipment upgrades on compressed timelines, locking vendor relationships once systems qualify.
- Biotechnology Firms:Temperature-sensitive biologics packaging drives demand for precision-engineered pressure-sensitive applicators with inline vision verification. Facilities in Switzerland and Germany concentrate procurement here, where shrink-sleeve applications for tamper-evidence are expanding fastest.
- Cosmetics Manufacturers:Brand differentiation requirements prioritize 360-degree label coverage and metallic finishes over regulatory compliance features.
- Food & Beverage Producers:Hygiene-grade stainless steel construction and washdown compatibility dominate specifications for condiment and sauce ampoules.
Pharmaceutical companies anchor the volume base while biotechnology firms expand most quickly as biologics pipelines mature.
Labeling Technology:
Application maturity separates established pressure-sensitive systems from emerging digital printing platforms. Margin structures favor precision-engineered European applicators over commodity Asian equipment.
- Pressure-Sensitive Labeling:Self-adhesive labels applied through precision-engineered dispensing heads dominate current installed base value. HERMA GmbH and similar European specialists sustain premium positioning through servo-driven motion control systems serving pharmaceutical facilities with ±0.5 millimeter placement tolerances.
- Digital Printing:Lot-specific variable data printing eliminates pre-printed label inventory working capital requirements. This technology is climbing the fastest as serialization mandates replace static labels with machine-readable unique identifiers across jurisdictions.
- Shrink-Sleeve Labeling:360-degree coverage and tamper-evidence properties suit high-value biologics where container integrity verification is mandatory.
- Wrap-Around Labeling:Cost-efficient paper label application serves volume generic drug producers with limited branding requirements.
Pressure-sensitive labeling anchors the volume base while digital printing climbs the fastest among labeling technologies.
Application:
Container geometry dictates equipment configuration complexity, with cylindrical ampoules requiring specialized handling compared to flat-faced vials. Customer type concentration varies by container format.
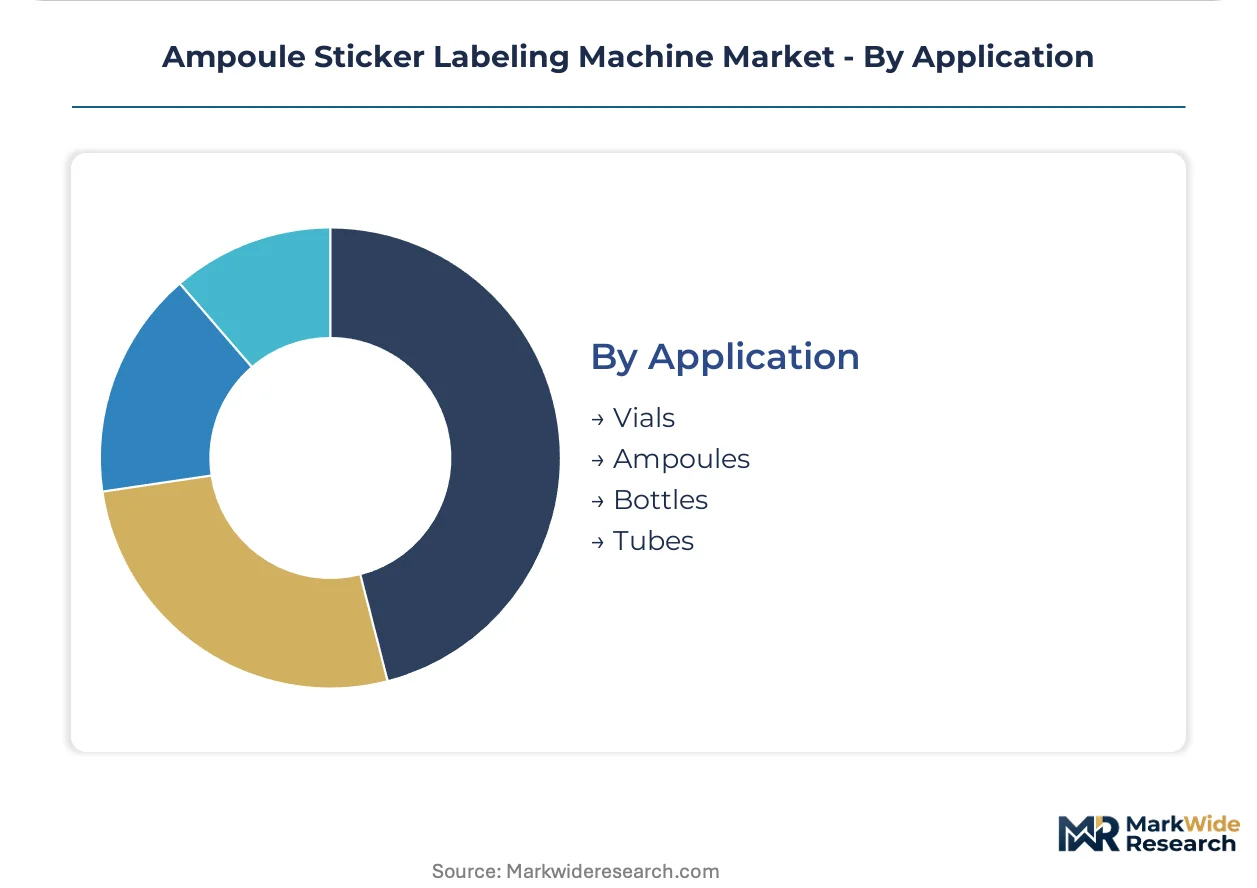
- Ampoules:Small glass containers for sterile injectables demand the most precise label placement and contamination-controlled handling. This application concentrates demand in European contract manufacturing facilities serving global pharmaceutical clients.
- Vials:Larger neck finish dimensions permit faster throughput rates and broader label size flexibility than ampoule formats.
- Bottles:Cosmetic and oral dosage applications drive demand for wrap-around and front-and-back labeling configurations.
- Tubes:Squeeze-container formats for topical pharmaceuticals require specialized mandrel handling systems distinct from rigid glass applications.
Ampoules anchor the volume base while vials gain share at the steepest rate among container applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Falsified Medicines Directive serialization deadlines and India's PLI scheme for domestic pharmaceutical manufacturing are redirecting capital expenditure toward compliant labeling infrastructure across multiple jurisdictions.
Germany
Precision engineering clusters in Baden-Württemberg and Bavaria supply servo-driven automatic labeling lines to contract manufacturers serving European pharmaceutical clients. EMA serialization requirements under EU MDR mandate machine-readable codes on every primary container, compelling equipment upgrades. Stuttgart and Munich metropolitan areas concentrate demand for validated systems with ±0.5 millimeter placement accuracy.
United States
FDA 21 CFR Part 11 compliance architectures with tamper-evident audit trails drive procurement decisions at parenteral drug facilities. The FDA's track-and-trace enforcement for sterile injectables forces replacement of legacy labeling equipment without electronic signature capability. New Jersey and Massachusetts pharmaceutical corridors anchor demand for integrated packaging lines bundling labeling with filling operations.
India
Domestic pharmaceutical production expansion under CDSCO-aligned PLI scheme incentives creates demand for semi-automatic systems bridging manual operations and full automation. Maharashtra and Gujarat manufacturing belts concentrate procurement of cost-optimized equipment serving emerging market price points. Mumbai and Ahmedabad industrial zones host contract manufacturers scaling output for export markets.
Switzerland
Temperature-sensitive biologics packaging specifications from Swissmedic drive demand for precision-engineered pressure-sensitive applicators with inline vision verification. Basel and Zurich pharmaceutical clusters prioritize shrink-sleeve applications for tamper-evidence in high-value injectable therapies. Swiss facilities lead adoption of embedded verification systems eliminating separate quality control bottlenecks.
China
NMPA serialization requirements for pharmaceutical traceability accelerate equipment replacement in sterile injectable manufacturing. Yangtze River Delta pharmaceutical hubs in Shanghai and Jiangsu province concentrate demand for automatic platforms operating at 100-400 units per minute. Domestic equipment fabricators compete on delivered cost while multinational vendors supply premium compliance architectures.
Ampoule Sticker Labeling Machine Market Competitive Environment
On the supply side, the industry is tiered between European precision-engineering specialists, Asian cost-optimized fabricators, and integrated packaging line bundlers. German and Swiss vendors anchor premium positioning through servo-driven motion control systems validated for pharmaceutical compliance. Indian and Chinese manufacturers compete on delivered cost for semi-automatic platforms serving emerging market expansion. Strategic moves concentrate on equipment leasing models converting capital expenditure to operational expenditure, and modular platform development accommodating regulatory divergence across manufacturing footprints.
Among European precision specialists, HERMA GmbH and Marchesini Group S.p.A. exemplify divergent competitive positions. HERMA GmbH occupies a position within pressure-sensitive applicator engineering, while Marchesini Group S.p.A. represents the integrated packaging line archetype bundling labeling with filling and capping operations. NKP Pharma Pvt Ltd anchors the India-based manufacturing tier competing on delivered cost for semi-automatic systems.
| Leading Market Players |
|---|
| NKP Pharma Pvt Ltd |
| Viallabeller |
| Brothers Pharmamach (India) Pvt Ltd |
| Marchesini Group S.p.A. |
| HERMA GmbH |
| Multipack Packaging Machinery |
| Adinath International Inc. |
| Accutek Packaging Equipment Company Inc. |
| Shanghai Skilt Machinery Equipment Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese servo-motor manufacturing is compressing component costs for labeling equipment builders while simultaneously intensifying price competition in Asian markets, forcing European precision specialists to defend premium positioning through validated compliance architectures and extended service bundling.
Pricing Analysis
Certification level creates the primary spread, with FDA 21 CFR Part 11-validated systems commanding substantial premiums over CE-marked equivalents serving emerging markets. Equipment pricing stratifies across three tiers: premium German-engineered platforms with integrated vision verification, mid-tier Asian automatic systems, and economy semi-automatic units for price-constrained Indian contract manufacturers. Cost compression in stainless steel and specialty alloys is intensifying margin pressure at the economy tier, where buyers exhibit acute price sensitivity due to capital constraints under India's PLI scheme incentives.
Supply Chain Analysis
Stainless steel feedstock draws from German and Japanese specialty alloy producers, with servo-drive components sourced predominantly from Chinese and Taiwanese precision motor manufacturers. Control systems and vision modules rest on semiconductor supply chains concentrated in South Korea and Taiwan. Single-source vulnerability in high-resolution optical sensors creates exposure for European equipment builders dependent on Japanese component suppliers. Distribution runs through direct sales forces for validated pharmaceutical systems, while semi-automatic equipment reaches emerging markets via regional distributor networks with local service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ampoule sticker labeling machine market sits in early-cycle expansion as serialization mandates across multiple jurisdictions force replacement of legacy equipment without compliance capabilities, creating a concentrated wave of capital expenditure that favors vendors with pre-validated architectures.
For Market Incumbents: Build switching-cost moats through embedded service contracts and validation documentation libraries that extend replacement timelines for qualified systems. Incumbents should deepen backward integration into servo-drive assembly to defend margin position against Chinese cost-optimized entrants, while simultaneously investing in modular platform development to accommodate regulatory divergence across manufacturing footprints.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's semi-automatic tier, where PLI scheme incentives are accelerating domestic pharmaceutical production expansion. New entrants should target mid-tier contract manufacturers in Maharashtra and Gujarat with leasing-based go-to-market models that convert capital expenditure to operational expenditure, reducing barrier to adoption.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because compliance validation creates durable vendor relationships once systems qualify, with recurring service revenue streams extending equipment life cycle economics. Acquisition targets should display integrated packaging line capabilities or precision pressure-sensitive applicator engineering. The signal to watch is NMPA enforcement acceleration in China, which would trigger equipment replacement waves similar to EU FMD implementation.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Development | Accommodates FDA, EMA, and NMPA regulatory divergence without full system redesign. |
| Equipment Leasing Model | Converts capital expenditure to operational expenditure for Indian contract manufacturers. |
| Backward Integration into Servo-Drives | Reduces dependency on Chinese motor suppliers and defends margin compression. |
| Digital Printing Integration | Eliminates pre-printed label inventory working capital for multi-SKU pharmaceutical facilities. |
| Embedded Vision Verification | Compresses line footprint and reduces contamination risk in Swiss biologics packaging. |
Study Parameters
A spread of perspectives from equipment procurement managers at European CDMOs, validation engineering consultants, and aftermarket service heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with plant engineers at parenteral drug facilities and regulatory affairs specialists conversant with FDA 21 CFR Part 11 protocols. Secondary validation drew from EMA serialization guidance documents, CDSCO PLI scheme notifications, and customs trade data on pharmaceutical machinery imports. Bottom-up equipment shipment analysis and top-down pharmaceutical capital expenditure estimates were triangulated to anchor volume assumptions.
Demand-supply balance dynamics shaped the forecast framework across the analysis window, with segmentation modeled by automation tier, end-use vertical, labeling technology, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and pharmaceutical production capacity expansion pipelines. Industry-specific inputs included EU MDR implementation timelines, NMPA traceability enforcement patterns, and biologics pipeline maturation rates.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity indices or semiconductor availability would shift the trajectory for equipment delivery timelines and margin structures. Forecasts reflect documented assumptions about regulatory enforcement consistency and capital availability for pharmaceutical infrastructure investment. Cross-checking against EPC contractor order backlogs and pharmaceutical facility construction permits is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Barcode Label Printer Market
Labels
In-Mold Labeling (IML) Market
Labels
Global Industrial Labels Market
Labels
Ripeness Indicator Labels Market
Labels
Global Security Labels Market
Labels
Global Cryogenic Label Market
Labels
Kraft Labels Market
Labels
Wrap Around Labels Market
Labels
Print Label Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Pressure Sensitive Labels Market
Labels
Wet Glue Labels Market
Labels
APAC on-Demand Color Labels Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Retro-Reflective Labels Market
Labels
Stand Alone Label Applicator Market