
 Self-Adhesive Labels Market | 2026-2036
Self-Adhesive Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Adhesive Labels Market Intelligence
Expanded production capacity in India is tilting the balance of regional supply chains for label stock materials. Avery Dennison Corporation leverages its extensive R&D in adhesive chemistry and film substrates to maintain a premium market position. CCL Industries competes on the basis of its global manufacturing footprint and deep specialization in high-value segments like pharmaceuticals. UPM focuses on sustainable paper-based label materials, aligning with corporate ESG mandates from consumer brands.
Self-adhesive labels are multi-layered constructs, comprising a facestock, a pressure-sensitive adhesive, and a release liner. The adhesive bonds to surfaces with minimal pressure, eliminating the need for heat, water, or solvents for application. These labels serve critical identification and branding functions across industries. While paper labels continue to dominate volume in food packaging applications, higher-margin film labels are gaining share in cosmetic and pharmaceutical labeling due to their durability and aesthetic flexibility.
Regulatory frameworks directly influence material selection and product design. In the United States, the FDA's regulations for indirect food additives govern adhesives used in food packaging. Concurrently, the European Union's REACH regulation restricts certain chemicals in label components, pushing manufacturers towards safer alternatives. Key decisions for converters and end-users will revolve around balancing the adoption of sustainable, recyclable label materials against established cost structures.
Market Dynamics
The imperative to balance sustainability with performance is the central structural force shaping the self-adhesive label market. This dynamic creates friction between end-user demands for recyclable materials and the established cost and performance benchmarks of conventional label constructions.
Growth Catalysts
- Linerless Technology:This innovation eliminates the release liner, reducing material waste and increasing label count per roll. It is gaining traction in high-volume logistics and food packaging applications where efficiency and sustainability are paramount.
- Pharmaceutical Serialization:Government mandates for drug track-and-trace systems, particularly in the United States and Europe, necessitate unique, durable labels. This drives volume for high-performance film labels with specialized adhesives for pharmaceutical packaging.
- Corporate ESG Mandates:Consumer packaged goods companies are implementing ambitious sustainability goals, increasing demand for labels made with recycled content or certified-compostable materials to align with the EU Green Deal and similar initiatives.
Market Restraints
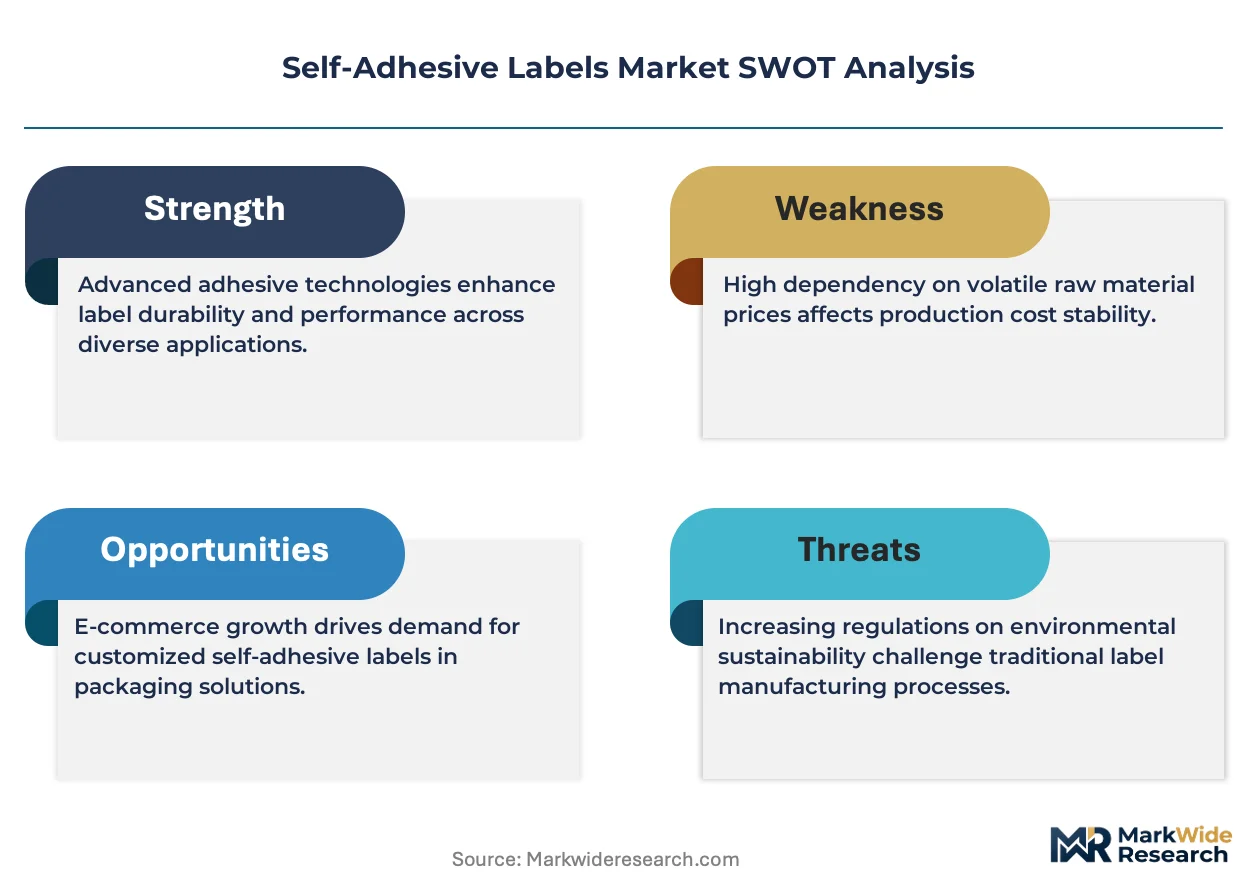
- Raw Material Volatility:Fluctuations in the price and availability of petrochemical feedstocks for film facestocks and acrylic adhesives create margin pressure for converters. Paper pulp pricing instability similarly affects the dominant paper label segment.
- Adhesion on Recycled Substrates:The increasing use of packaging with high post-consumer recycled (PCR) content presents technical challenges. Inconsistent and rougher surfaces can compromise label adhesion, requiring more advanced and costly adhesive formulations.
- Substitution by Direct Printing:In segments like beverage cans and glass bottles, direct-to-container digital printing technologies are emerging as a viable alternative. This method eliminates the need for a label entirely, posing a long-term substitution threat.
Strategic Opportunities
- Intelligent Labeling:Integrating RFID or NFC technology into labels offers significant value in supply chain management and anti-counterfeiting. High-value segments like electronics, pharmaceuticals, and luxury goods represent a key opportunity for smart label adoption.
- Cold-Chain Expansion:The growth of refrigerated and frozen food delivery, alongside stringent temperature requirements for biologics, creates a need for specialized adhesives that perform reliably in low-temperature and high-moisture environments.
- Circular Material Development:Commercializing wash-off adhesives that allow for clean label removal during the recycling process is a major opportunity. This enables higher-quality recovery of PET and glass packaging, meeting brand owner and regulatory demands.
Industry Challenges
- Regulatory Fragmentation:Manufacturers face complexity in ensuring a single product complies with divergent chemical safety regulations, such as the EU's REACH framework and the FDA's rules for indirect food additives in the United States.
- Sustainable Feedstock Sourcing:Securing a consistent, high-quality supply of post-consumer recycled content for facestocks is a significant challenge. The collection and sorting infrastructure for label waste itself remains underdeveloped globally.
- Capital Investment for Converters:Adopting new technologies like linerless labels or thinner film materials often requires significant capital expenditure to upgrade or replace existing printing, die-cutting, and application machinery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Adhesive Labels Market |
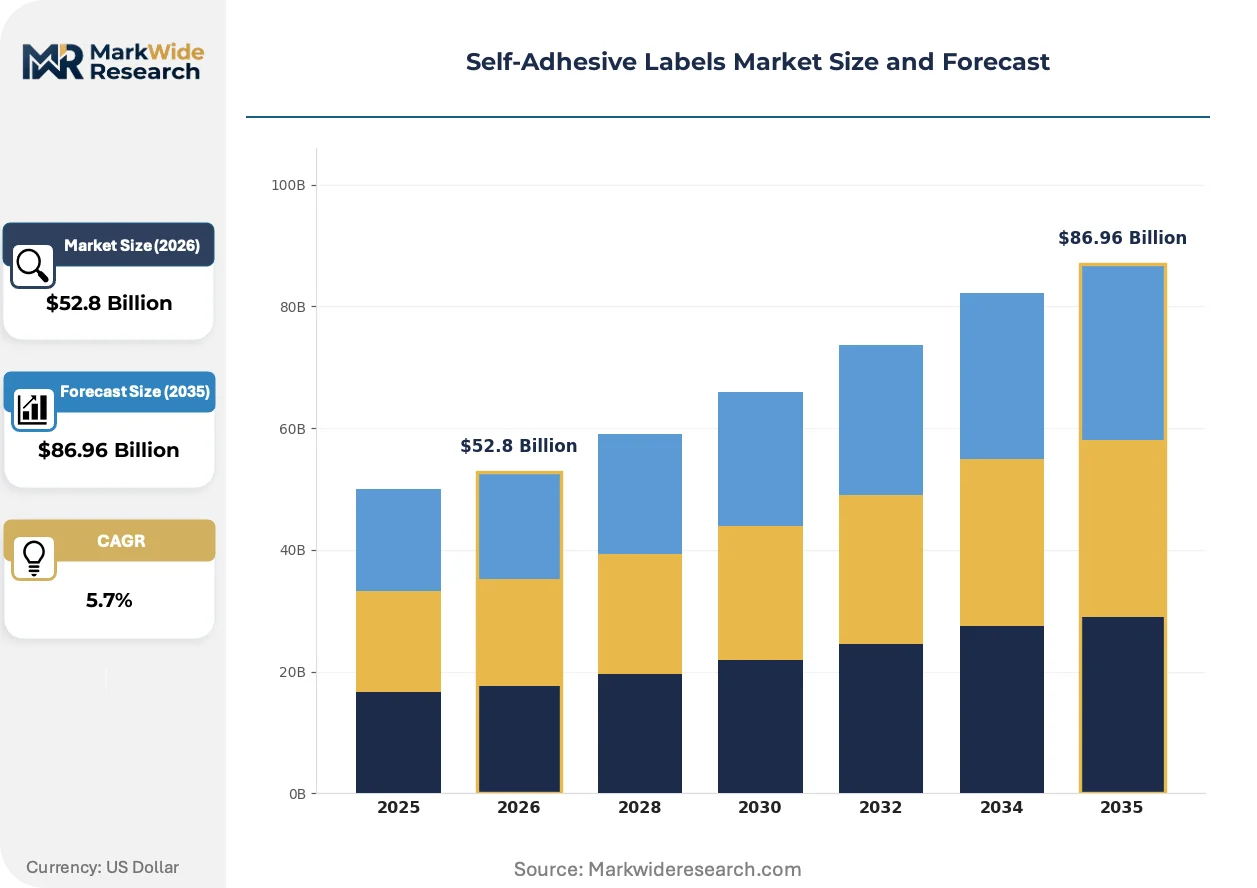
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $86.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Labels, Film Labels, Foil Labels, Fabric Labels, Synthetic Labels Application: Food Packaging, Pharmaceutical Identification, Cosmetic Labeling, Industrial Marking, Electronic Component Tagging End User: Manufacturing Plants, Retail Businesses, Warehousing Facilities, Transportation Companies, Laboratory Settings Adhesive Type: Permanent, Removable, Repositionable, High Tack, Freezer Grade |
| Companies Covered | Mondi, CCL Industries, Avery Dennison Corporation, H optima Group, HERMA, 3M, UPM, Multi-Color Corporation, LINTEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Adhesive Labels Market Strategic Shifts & Innovations
Material science and digital integration are converging to redefine the label's function. Sustainability pressures are accelerating the development of novel adhesives and facestocks, while embedded technologies transform the label into an interactive data carrier for supply chains and consumers.
Linerless label technology provides a facestock with a silicone release coating on its top surface and a special adhesive on the back. High-volume logistics and quick-service food sectors are adopting this technology to increase operational efficiency and meet waste reduction targets. This innovation is collapsing the traditional three-part label construct, simplifying inventory and lowering the total applied cost for end-users.
The European Union’s Packaging and Packaging Waste Regulation (PPWR) establishes stringent design-for-recycling criteria. This forces the value chain to develop label solutions that do not contaminate the primary packaging recycling stream. The beverage and household chemical segments are most affected, accelerating the adoption of wash-off adhesives and facestocks that cleanly separate from PET bottles during reclamation.
Brands are shifting the role of the label from a static information carrier to a dynamic digital gateway. The widespread use of QR codes and NFC chips on labels disrupts the traditional boundary between the physical product and digital brand experiences. This trend is most prominent in the wine, cosmetics, and consumer electronics sectors, where it is used for authentication, user engagement, and providing extended product information.
Self-Adhesive Labels Market Segmentation
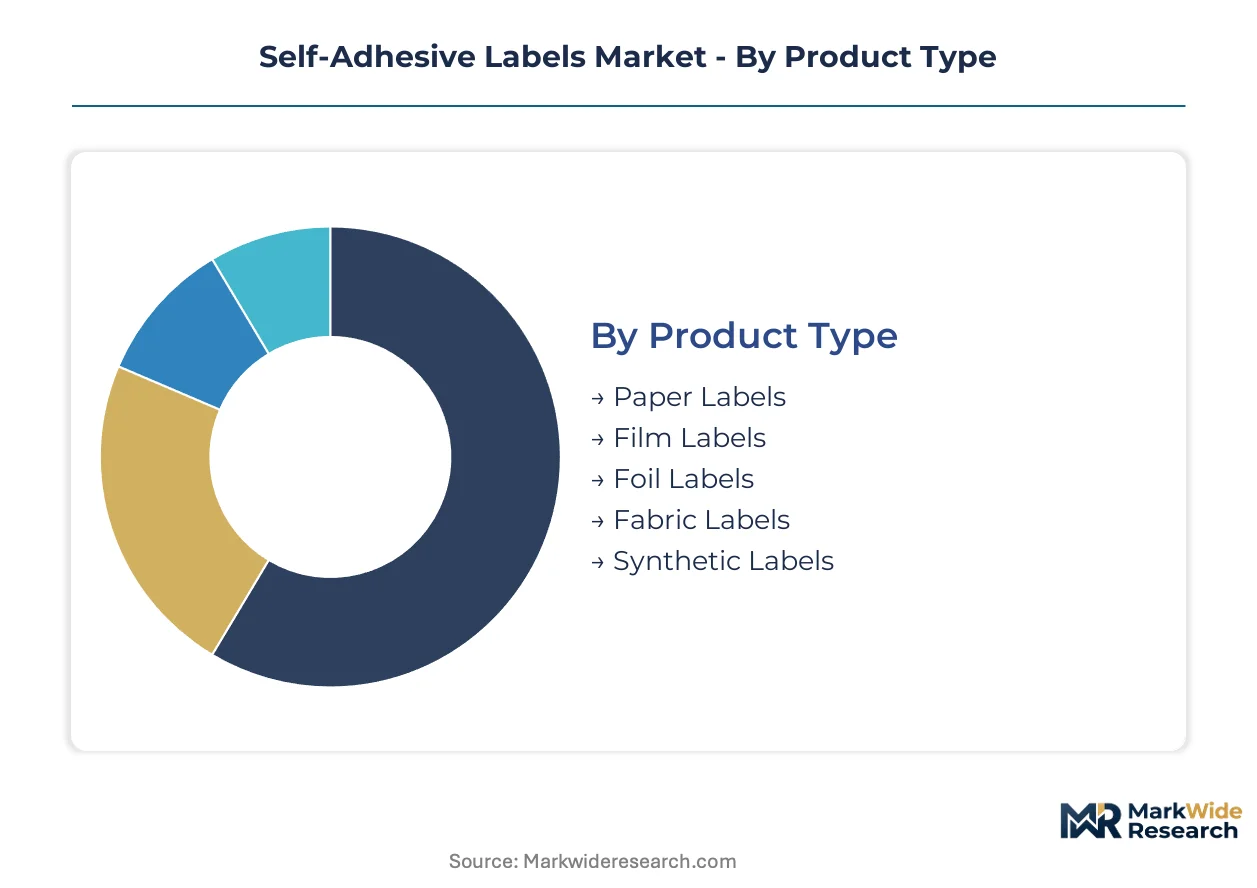
The self-adhesive labels market diversifies across various product compositions, application methods, and end-user requirements. Understanding these distinct segments provides clarity on demand drivers and technological shifts. This granular view reveals where innovation in materials and adhesives is most impactful.
Product Type:
The product type segmentation reflects a maturity spectrum, from established paper-based solutions to high-performance synthetic and film materials.
- Paper Labels:These labels consist of a paper facestock, offering cost-effectiveness and ease of printing. Demand concentrates heavily in food packaging applications, driven by high-volume requirements and established recycling streams.
- Film Labels:Comprising plastic films like PP, PE, or PET, these labels provide superior durability, moisture resistance, and aesthetic flexibility. Cosmetic labeling and pharmaceutical identification drive demand for film labels, requiring robust performance and visual appeal.
- Foil Labels:Constructed from thin aluminum foil, these labels offer a metallic aesthetic and conformability to irregular surfaces. They find use in premium product branding and specialty applications.
- Fabric Labels:Made from textile materials, fabric labels provide a soft touch and are often used for apparel or home textile branding.
- Synthetic Labels:These labels are engineered from advanced polymer blends, offering extreme durability and resistance to chemicals or harsh environments.
Paper Labels retains volume leadership; Film Labels holds the steepest expansion curve.
Application:
Segmentation by application highlights the varied volume requirements and performance needs across different industrial and consumer sectors.
- Food Packaging:These labels provide essential product information, branding, and regulatory compliance for packaged food items. High-volume consumer goods production in China and India drives demand, necessitating efficient application and cost-effective materials.
- Pharmaceutical Identification:Labels for pharmaceuticals require precise serialization, tamper-evidence, and adherence to strict regulatory standards like those from the FDA in the United States and EMA in Europe. Government mandates for drug track-and-trace systems are driving this segment.
- Cosmetic Labeling:These labels focus on aesthetic appeal and brand differentiation, often using film materials and specialized finishes for premium products.
- Industrial Marking:Labels for industrial marking provide durable identification for equipment, components, and inventory in harsh manufacturing environments.
- Electronic Component Tagging:These labels are designed for small-scale, high-precision identification of electronic parts, often requiring heat resistance and anti-static properties.
Food Packaging dominates overall demand, while Pharmaceutical Identification exhibits strong specialized growth.
End User:
The end-user classification delineates distinct customer types with unique operational scales and label performance expectations.
- Manufacturing Plants:These facilities utilize self-adhesive labels for product identification, inventory management, and regulatory compliance on production lines. Advanced manufacturing sectors in Germany and Japan drive demand for robust, automated labeling solutions.
- Retail Businesses:Retailers use labels for pricing, promotion, product information, and inventory control on store shelves and packaging. The shift towards e-commerce fulfillment increases demand for versatile, scannable labels.
- Warehousing Facilities:Labels in warehousing are crucial for tracking goods, managing logistics, and optimizing storage within large-scale distribution centers.
- Transportation Companies:These companies rely on durable labels for shipping, cargo identification, and compliance with international transport regulations.
- Laboratory Settings:Labels for laboratories require resistance to chemicals, extreme temperatures, and precise data capture for samples and equipment.
Manufacturing Plants represents the largest procurement volume, with Retail Businesses showing significant expansion in specialized operational needs.
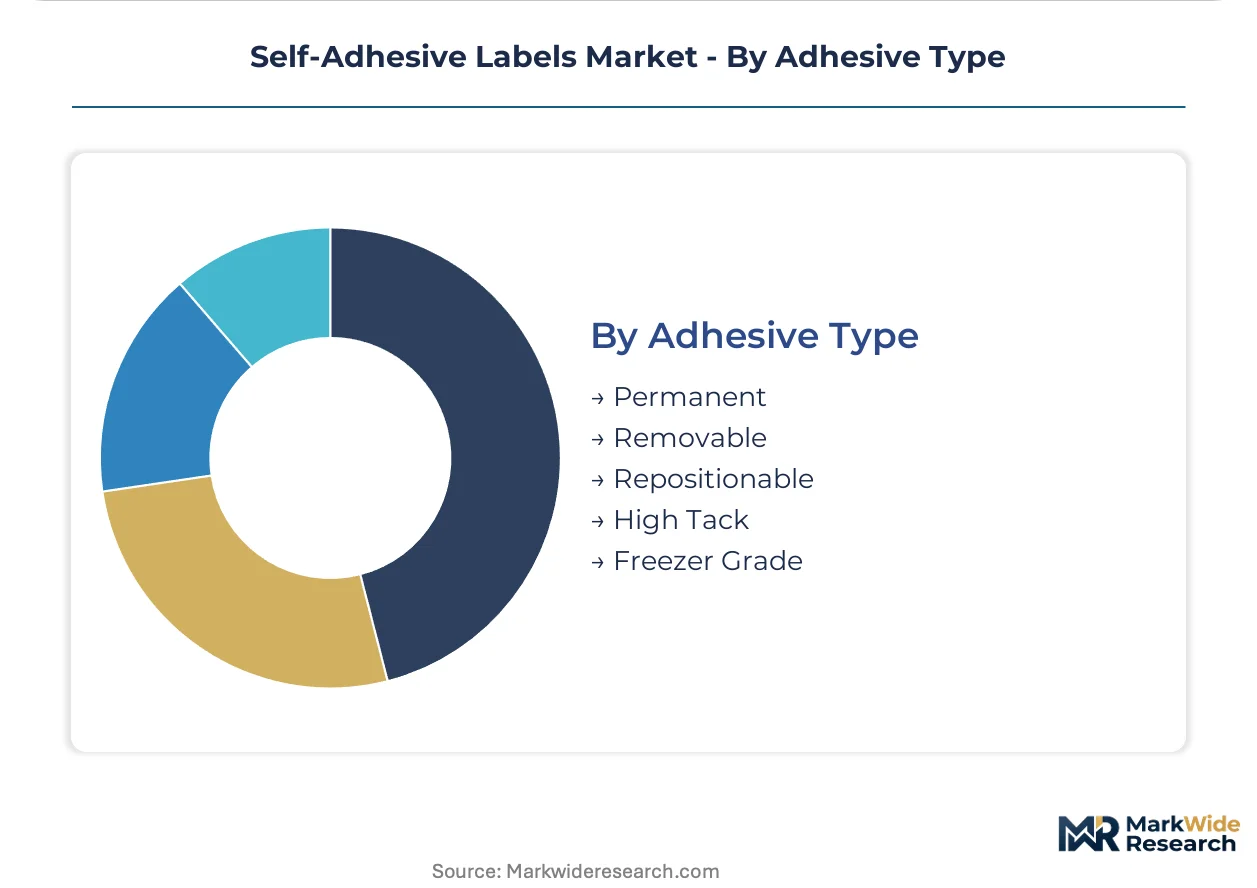
Adhesive Type:
Adhesive type segmentation often correlates with varying performance requirements and, consequently, different margin profiles for manufacturers.
- Permanent:These adhesives form a strong, lasting bond upon application, designed for labels intended to remain affixed indefinitely. Industrial marking and long-term product identification in automotive sectors drive demand.
- Freezer Grade:Engineered to maintain adhesion in sub-zero temperatures and high-humidity environments, these adhesives prevent labels from peeling or detaching. Cold-chain logistics for biologics and frozen food delivery expands this segment.
- Removable:Removable adhesives allow labels to be peeled off cleanly without leaving residue or damaging the surface, suitable for temporary applications.
- Repositionable:These adhesives permit multiple applications and removals, offering flexibility during initial placement or for temporary product modifications.
- High Tack:High tack adhesives provide an aggressive initial bond, often used on rough, textured, or difficult-to-adhere surfaces requiring immediate strong grip.
Permanent forms the foundational volume, while Freezer Grade demonstrates critical performance in niche, high-value applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's regulations for indirect food additives significantly shape material selection across the United States. This regulatory influence extends to adhesive formulations, driving compliance in a major consumer market. Demand for self-adhesive labels remains high across diverse industrial and consumer applications.
United States
Demand for pharmaceutical serialization labels and cold-chain applications drives specialized growth. The FDA's track-and-trace mandates ensure label durability and data integrity for drug packaging. Silicon Valley and Boston's biotech clusters require advanced labeling for medical devices and biologics.
China
Advanced manufacturing and logistics sectors drive substantial demand for efficient self-adhesive labels. China's dual carbon goals promote sustainable label materials and linerless technology adoption. The Yangtze River Delta region, a manufacturing hub, sees high volume in food packaging and industrial marking.
Germany
European Union's REACH regulation restricts certain chemicals in label components, pushing manufacturers towards safer alternatives. Corporate ESG mandates from major consumer brands also influence material choices. The Rhine-Ruhr industrial area concentrates demand for durable industrial labels and sustainable food packaging solutions.
India
Expanded production capacity in India tilts regional supply chains for label stock materials. The PLI scheme for pharmaceuticals encourages domestic drug production, increasing demand for identification labels. Mumbai and Gujarat's pharmaceutical manufacturing clusters are adopting specialized labels for drug track-and-trace systems.
Japan
Precision manufacturing and high-value electronics sectors necessitate specialized and durable self-adhesive labels. JIS standards for industrial products guide material selection for robust performance in harsh environments. The Tokyo metropolitan area, a technology hub, utilizes intelligent labels for supply chain management.
Self-Adhesive Labels Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the self-adhesive labels market. The industry exhibits a tiered structure, where global diversified players compete alongside specialized regional manufacturers and technology-focused niche providers. Strategic archetypes include integrated material science companies, high-volume label converting specialists, and sustainable material innovators. Companies actively pursue both capacity expansion in growth regions and strategic partnerships to secure raw material supply and broaden their product portfolios.
Global diversified players like Avery Dennison Corporation exemplify deep R&D in adhesive chemistry and film substrates, maintaining a premium market position through continuous innovation. CCL Industries represents a leading label converter, leveraging its extensive global manufacturing footprint and deep specialization in high-value segments such as pharmaceuticals and consumer goods. UPM sits within the sustainable material innovator archetype, focusing on paper-based label materials and circular economy solutions to align with corporate ESG mandates from major consumer brands. These players collectively anchor the market's competitive dynamics.
| Leading Market Players |
|---|
| Mondi |
| CCL Industries |
| Avery Dennison Corporation |
| H optima Group |
| HERMA |
| 3M |
| UPM |
| Multi-Color Corporation |
| LINTEC Corporation |
| Others |
Cost & Logistics Intelligence
Commodity volatility in petrochemical feedstocks determines both pricing tier spreads and the geographic shape of the self-adhesive label supply chain. This input price instability creates margin pressure across all segments, particularly for high-volume paper and film label producers. Supply chain resilience for specialized materials often commands a premium, impacting final product costs.
Pricing Analysis
Geographic price spreads for self-adhesive labels vary significantly, with higher costs observed in regions with stringent regulatory requirements like the European Union. The dominant pricing model involves contract-based long-term offtake for large volumes, alongside spot market dynamics for smaller, specialized orders. Price differentiation stems from quality grade (film versus paper), customization level for specific applications, and volume scale. Pricing pressure intensifies from raw material volatility, particularly for petrochemical-derived films and adhesives. Food packaging applications exhibit the highest price sensitivity, while pharmaceutical identification demands prioritize performance over cost.
Supply Chain Analysis
Export control regimes around specialized chemical components, particularly those impacting advanced adhesive formulations, influence the global flow of self-adhesive label materials. Geographic supply concentration for label stock materials centers on China, India, and Germany. Raw material dependencies include petrochemical feedstocks for synthetic films and acrylic adhesives, alongside paper pulp. Raw material volatility presents a significant supply chain risk. Distribution runs through established global networks for major players, complemented by regional specialists serving local markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent self-adhesive label manufacturers must defend against direct-to-container digital printing, a significant substitute threat that eliminates the need for a physical label entirely.
For Market Incumbents: Pre-empt the threat of direct printing by accelerating investment in linerless label technologies and developing advanced wash-off adhesives for circular packaging. Secure long-term supply agreements for sustainable feedstocks to mitigate raw material volatility. Expand production capacity in growth regions like India to optimize regional supply chains. Innovate in adhesive chemistry for challenging recycled substrates, addressing a critical performance gap.
For New Entrants and Emerging Players: Niche cold-chain applications, particularly for biologics and specialized food delivery, represent a penetrable entry point for new self-adhesive label players. Focus on intelligent labeling solutions integrating RFID or NFC technology for high-value segments like electronics. Offer performance-based solutions with strong regulatory compliance for pharmaceutical track-and-trace systems. Target underserved regional markets with localized manufacturing capabilities and specialized material offerings.
For Investors and Strategic Acquirers: The European Union’s Packaging and Packaging Waste Regulation (PPWR) reshapes the acquisition landscape, favoring companies with advanced sustainable material portfolios. Long-term viability rests on innovation in circular materials and embedded digital functionalities. Target technology-focused niche providers specializing in sustainable or smart label solutions. The adoption rate of circular material development mandates across major brands serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Linerless Technology Investment | This reduces material waste and improves operational efficiency for high-volume logistics applications. |
| Circular Material Development | This aligns label solutions with corporate ESG mandates and regulatory design-for-recycling criteria. |
| Cold-Chain Adhesive R&D | This addresses specialized performance needs for refrigerated food and pharmaceutical biologics. |
| RFID/NFC Integration | This transforms labels into interactive data carriers for supply chain management and anti-counterfeiting. |
| Capacity Expansion in India | This leverages regional growth and strengthens supply chain resilience for label stock materials. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation through published reports. Primary interactions included label converters, brand managers from consumer packaged goods companies, material suppliers, and packaging engineers. This direct engagement provided qualitative insights into market dynamics and technological shifts, complemented by bottom-up and top-down triangulation.
Forecast inputs considered across the analysis window include market segmentation by product type, application, end-user, and adhesive type. The compound annual growth rates were derived from historical trends, future demand projections, and the impact of technological innovations. Key industry-specific forecast inputs included pharmaceutical serialization mandates and the projected adoption rates of linerless label technology across various sectors.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth and raw material prices would shift the trajectory of market expansion. Forecasts reflect assumptions regarding regulatory stability and technological progression in sustainable materials. Cross-checking against industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Primary Packaging Labels Market
Labels
Sustainable Labels Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
GCC Labels and Release Liners Market
Labels
Wet Glue Labels Market
Labels
Healthcare and Laboratory Labels Market
Labels
Thermal Labels Market
Labels
Retro-Reflective Labels Market
Labels
Laser Printable Wristbands Market
Labels
Global Sensormatic Labels Market
Labels
Tags Market
Labels
Inventory Tags Market
Labels
Print Label Market
Labels
Screen Print Label Market
Labels
Sleeve Label Market
Labels
Shrink Sleeve Labels Market