
 Glue-Applied Labels Market | 2026-2036
Glue-Applied Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Glue-Applied Labels Market Outlook
Single-source procurement for adhesive formulations is rebalancing toward multi-source resin agreements as converters hedge against petrochemical volatility. Avery Dennison Corporation leverages its polymer science portfolio to sustain premium positions in pressure-sensitive constructions. CCL Industries anchors North American beverage demand through dedicated cold-chain label capacity. Constantia Flexibles competes in European food packaging with aluminum-backed lidding and wet-glue label hybrids.
Glue-applied labels are substrate-backed information carriers bonded to packaging surfaces through wet adhesives, hot melts, or water-activated gums, typically applied via rotary or linear labeling equipment at speeds exceeding 40,000 units per hour for high-volume bottling operations. Paper substrates dominate food and beverage applications due to cost efficiency and established recycling streams, while polyester and polypropylene films extend durability for industrial and cosmetic labels exposed to moisture or solvents. Pressure-sensitive adhesives command the largest volume share across retail and logistics end users, whereas water-activated gummed labels retain structural relevance in corrugated sealing and pharmaceutical booklet applications where tamper evidence matters.
EPA guidelines on volatile organic compound emissions from adhesive solvents shape formulation choices for US-based converters, while REACH restrictions on hazardous substances limit certain resin chemistries in European supply chains. FDA food-contact regulations govern adhesive migration limits for labels applied directly to edible product surfaces. Stakeholders must monitor evolving extended producer responsibility frameworks and adhesive recyclability certifications as sorting infrastructure advances.
Market Dynamics
Converters face simultaneous pressure from the EU Green Deal's recyclability mandates and brand owners demanding shelf differentiation through substrate innovation, forcing capital allocation toward thinner film stocks and water-based adhesive systems.
Growth Catalysts
- Food and beverage packaging expansion:Bottled water and craft beverage producers in Germany, Italy, and Spain are retrofitting lines for wet-glue rotary applicators to achieve premium tactile finishes at speeds above 40,000 units per hour.
- Extended Producer Responsibility frameworks:France's AGEC law and Italy's CONAI fees incentivize mono-material label constructions that streamline PET bottle-to-bottle recycling without adhesive contamination.
- Hot-melt adhesive advances:Metallocene polyolefin formulations from petrochemical suppliers enable lower application temperatures, cutting energy consumption on high-speed labeling lines by 15-20 percent.
Market Restraints
- Petrochemical resin volatility:Ethylene-vinyl acetate and styrene-butadiene block copolymer prices fluctuate with crude oil indices, compressing converter margins on fixed-price annual contracts.
- Substrate supply concentration:Specialty metallized papers for premium beverage labels depend on Austrian and Finnish pulp mills with limited alternative sourcing during energy price spikes.
- Adhesive migration limits:FDA 21 CFR 175.105 compliance testing for direct food-contact labels adds 8-12 weeks to new product qualification timelines.
Strategic Opportunities
- Underpenetrated pharmaceutical booklet labels:Water-activated gummed constructions with tamper-evident perforations retain structural relevance in Eastern European markets where serialization mandates are expanding.
- Recyclable adhesive certification:APR (Association of Plastic Recyclers) recognition for wash-off hot melts opens preferential supplier status with Coca-Cola and PepsiCo sustainability procurement teams.
- Digital printing convergence:Hybrid flexo-inkjet presses from Gallus and Omet enable short-run variable data on traditional wet-glue stocks, capturing craft spirits and seasonal promotional campaigns.
Industry Challenges
- Skilled press operator scarcity:Rotary die-cutting and adhesive viscosity management on 10-color flexo lines require apprenticeship programs that German and Austrian converters struggle to fill.
- Legacy ERP integration:Shop-floor data collection from 1990s-era label applicators lacks OPC-UA connectivity, blocking real-time adhesive consumption tracking for sustainability reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glue-Applied Labels Market |
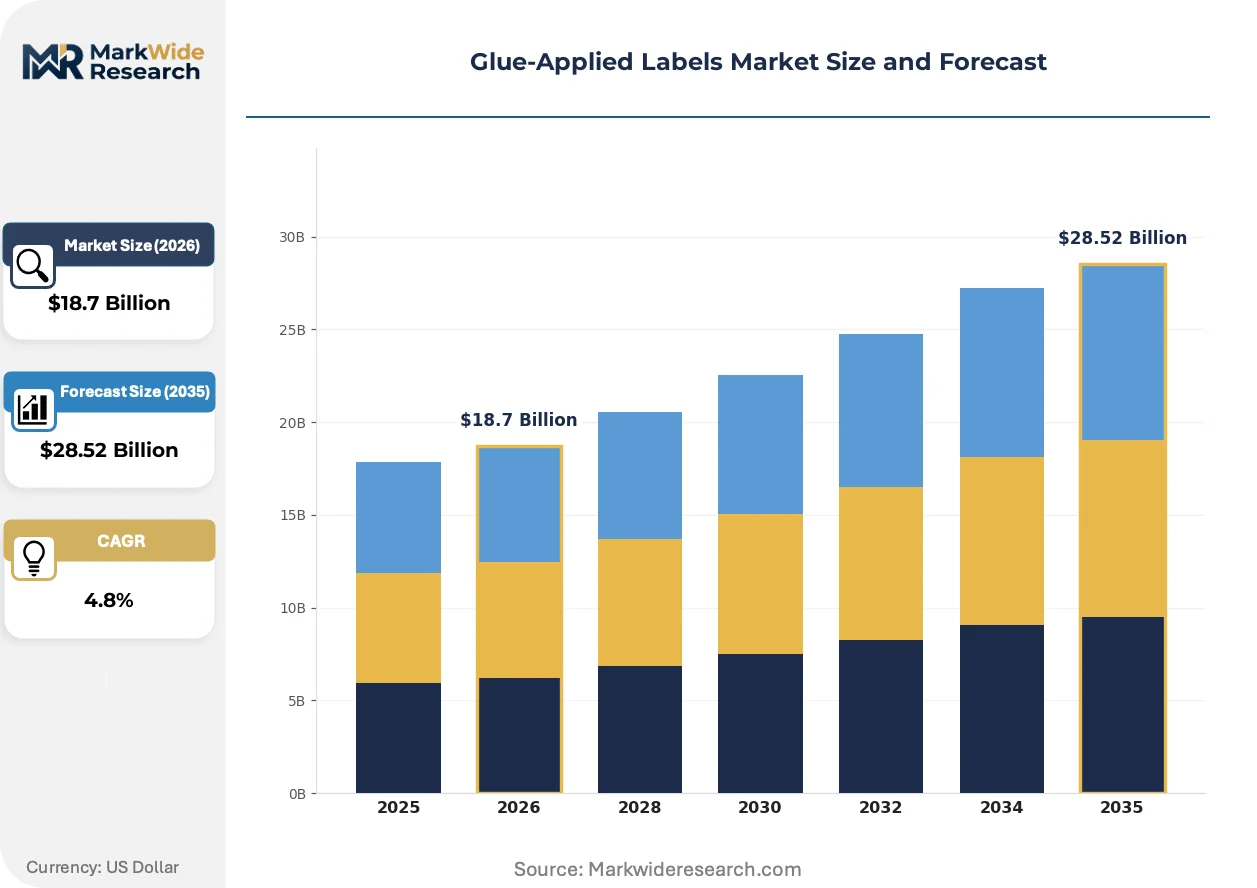
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Pressure Sensitive, Heat Seal, Water Activated, Gummed Material: Paper, Polyester, Polypropylene, Vinyl Application: Food Packaging, Beverage Labels, Cosmetic Labels, Industrial Labels End User: Retail, Food & Beverage, Pharmaceuticals, Logistics |
| Companies Covered | Avery Dennison Corporation, CCL Industries, Multi-Color Corporation, Huhtamaki, Constantia Flexibles, 3M Company, Fort Dearborn Company, WestRock, Skanem AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glue-Applied Labels Market Strategic Shifts
Digital workflow integration and regulatory chemistry restrictions are compressing traditional formulation development cycles while opening substitution pathways for bio-based raw materials.
Water-based acrylic adhesive systems are decentralizing production planning for mid-volume converters. These formulations eliminate solvent recovery infrastructure requirements. Beverage co-packers in Portugal and the Czech Republic are adopting tanker-delivered bulk emulsions to replace drum-handling labor. The shift is decentralizing adhesive sourcing decisions from central procurement to plant-level technical managers.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone solvent content force reformulation of high-tack permanent adhesives. Industrial label producers serving automotive and electronics sectors must validate alternative tackifier resins. German automotive suppliers are accelerating qualification of hydrogenated hydrocarbon tackifiers to maintain CE-marked component traceability labels.
Brand owners now specify adhesive recyclability performance in RFQ technical appendices rather than treating it as a post-qualification checkbox. Major beverage retailers in Scandinavia require documented wash-off behavior in standard caustic recycling baths. This procurement pattern shift elevates converters with in-house PET flake contamination testing capability above commodity competitors in supplier scorecards.
Glue-Applied Labels Market Segmentation
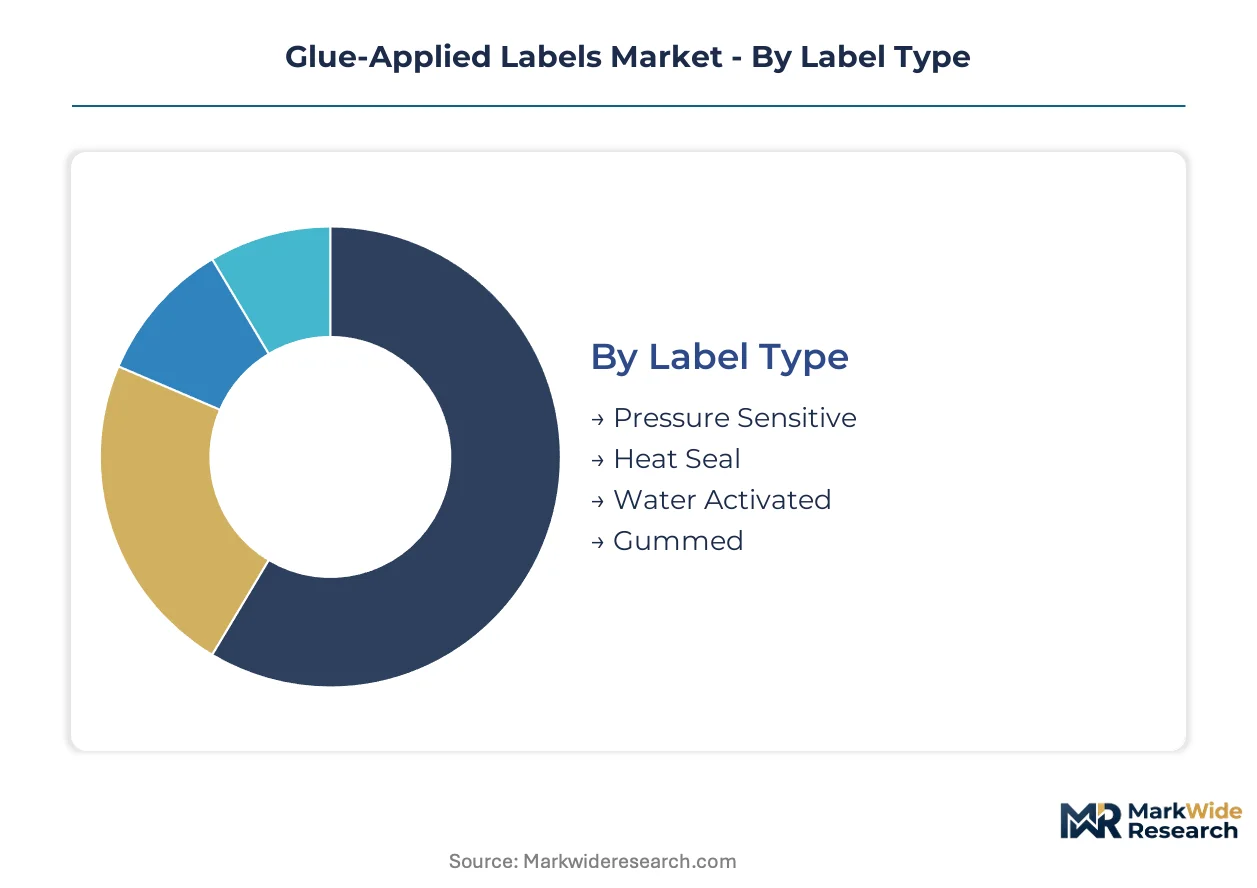
Segmentation in the glue-applied labels market reflects divergent technical requirements across adhesive chemistry, substrate durability, and regulatory exposure. Procurement patterns vary sharply between high-speed beverage bottling and pharmaceutical serialization where tamper evidence governs specification choices.
Label Type:
Adhesive bonding mechanism determines equipment compatibility, line speed capability, and end-of-life recyclability performance in PET stream processing.
- Pressure Sensitive:These self-adhesive constructions carry a release liner and activate under light pressure without heat or moisture. Retail and logistics end users in Germany and Italy specify these for variable-information shipping labels where applicator flexibility across carton sizes matters more than unit economics.
- Heat Seal:Thermal activation creates permanent bonds on coated paperboard and film substrates. Demand concentrates in French dairy and ready-meal packaging where hermetic sealing against moisture intrusion protects shelf-stable formulations through distribution.
- Water Activated:Remoistenable gum adhesives require brief water exposure before application. Corrugated box sealing operations in Spanish logistics hubs favor these for cost efficiency on high-volume B2B shipments where aesthetic finish is secondary.
- Gummed:Traditional starch or dextrin-based adhesives retain relevance in pharmaceutical booklet labels across Eastern European markets. Serialization mandates in Poland and Czechia drive demand for multi-page constructions with perforated tamper evidence.
Mature deployment sits with Pressure Sensitive labels across retail and logistics. Newer deployment is concentrated in Heat Seal formats where mono-material recyclability specifications are tightening.
Material:
Substrate selection trades off cost position against mechanical durability and recycling stream compatibility under EU Green Deal compliance timelines.
- Paper:Uncoated and coated wood-pulp stocks dominate food and beverage applications due to established recycling infrastructure and tactile premium associations. German craft beverage producers specify textured papers for shelf differentiation in export markets.
- Polyester:PET film substrates deliver dimensional stability and chemical resistance for industrial asset tags and cosmetic labels exposed to solvent contact. Automotive suppliers in Stuttgart and Wolfsburg require these for under-hood component traceability.
- Polypropylene:Biaxially oriented PP films offer moisture resistance at lower density than polyester. Italian personal care brands specify clear PP for no-label look applications on transparent bottles.
- Vinyl:PVC-based constructions provide extreme durability for outdoor industrial signage and safety warnings. Limited adoption persists in construction equipment labeling where weathering resistance outweighs recyclability concerns.
Volume leadership belongs to Paper substrates in beverage and food. Steepest expansion trajectory is appearing in Polypropylene as personal care brands chase lightweighting and optical clarity targets.
Application:
End-use environment dictates adhesive migration limits, moisture exposure tolerance, and applicator speed requirements across converter capacity planning.
- Food Packaging:Direct-contact labels face FDA 21 CFR 175.105 and EFSA migration testing protocols. German frozen food processors specify low-migration hot melts for primary packaging where label-to-food contact risk exists.
- Beverage Labels:Wet-glue rotary applicators running above 40,000 units per hour dominate carbonated and bottled water production. Spanish and Portuguese co-packers are retrofitting lines to handle thinner film stocks for weight reduction.
- Cosmetic Labels:Premium tactile finishes and metallic effects drive specification toward metallized papers and specialty coatings. French luxury brands demand cold-chain compatible adhesives for refrigerated serum and cream packaging.
- Industrial Labels:Chemical resistance and UV stability predominate over aesthetic considerations. Automotive and electronics manufacturers in Bavaria specify solvent-resistant acrylic adhesives for component traceability through harsh assembly environments.
Installed capacity concentrates in Beverage Labels across German and Italian bottling corridors. Emerging specification intensity is surfacing in Food Packaging as EPR frameworks tighten adhesive contamination standards.
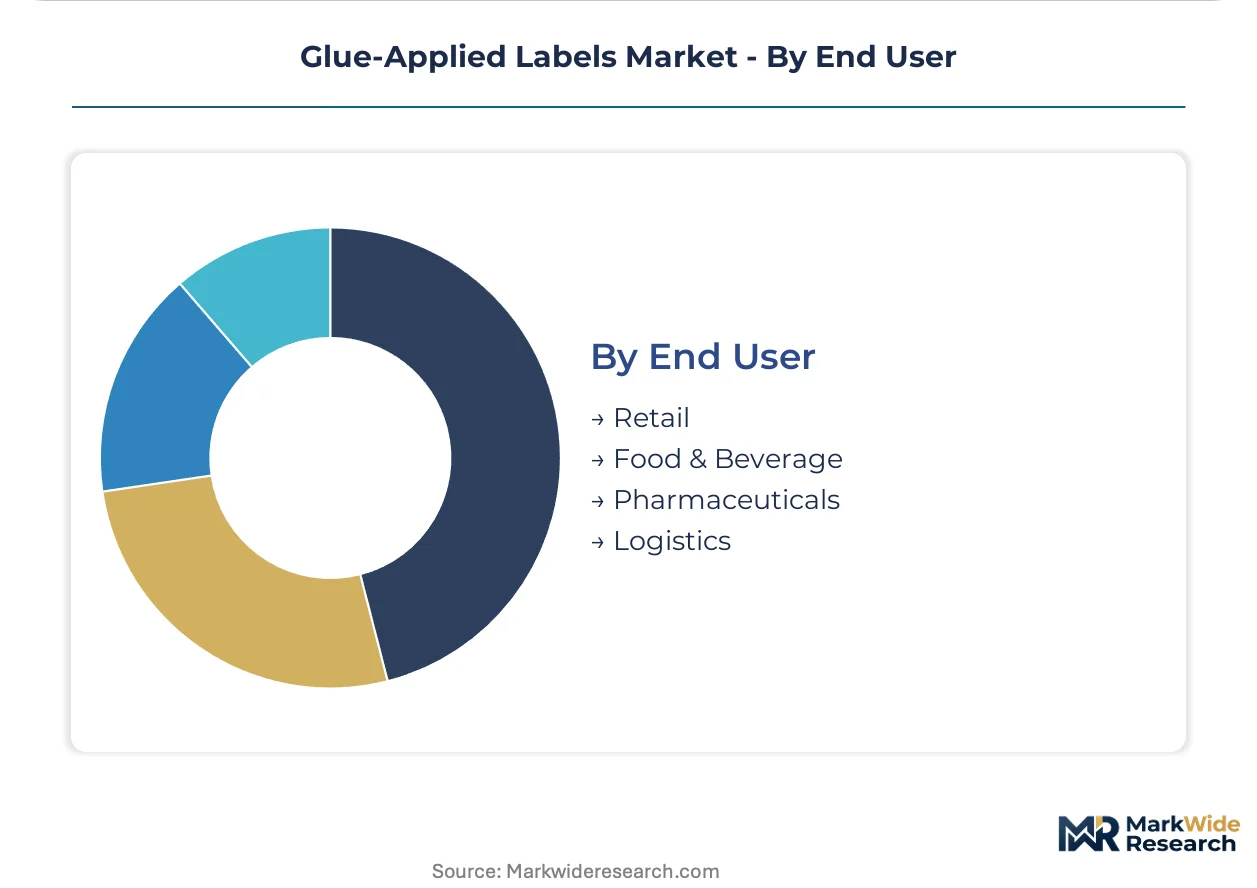
End User:
Customer procurement sophistication ranges from commodity spot purchasing in logistics to collaborative specification development in pharmaceuticals.
- Retail:Private-label brands and supermarket chains prioritize unit cost and supply security over technical differentiation. Scandinavian retailers are embedding wash-off adhesive requirements into supplier scorecards ahead of national EPR implementation.
- Food & Beverage:Brand owners balance shelf impact against recycling stream compatibility. Coca-Cola and PepsiCo sustainability procurement teams award preferential status to converters with APR-certified wash-off adhesive portfolios.
- Pharmaceuticals:Serialization mandates and tamper-evidence regulations drive specification complexity. Eastern European markets are expanding booklet label requirements as track-and-trace systems mature.
- Logistics:E-commerce fulfillment and third-party logistics providers demand thermal-transfer compatible facestocks for variable data printing. Portuguese distribution hubs are adopting water-activated gummed labels for secondary carton sealing to reduce plastic tape consumption.
Procurement maturity is highest in Pharmaceuticals where regulatory compliance gates dominate supplier selection. Fastest volume growth is appearing in Logistics as e-commerce parcel volumes strain existing label application infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical resin supply from the US Gulf Coast and German Rhine-Ruhr corridor anchors converter capacity planning across major glue-applied label markets. Regional specialization reflects diverging regulatory timelines and end-use concentration patterns.
Germany
Precision bottling equipment clusters in Bavaria and Baden-Württemberg serve premium export beverage brands demanding wet-glue rotary application above 40,000 units per hour. The EU Green Deal's recyclability mandates pressure converters toward thinner film stocks and water-based adhesive systems. Stuttgart-based automotive suppliers specify solvent-resistant polyester labels for under-hood component traceability through harsh assembly environments.
United States
EPA guidelines on volatile organic compound emissions from adhesive solvents shape formulation choices for converters serving food and beverage packaging. Cold-chain label capacity concentrates in Midwestern states supporting North American beverage distribution networks. Private-label retail procurement in the Southeast prioritizes unit cost and supply security over technical differentiation.
Italy
CONAI packaging fees incentivize mono-material label constructions that streamline PET bottle-to-bottle recycling without adhesive contamination. Craft beverage producers in Piedmont and Veneto retrofit lines for wet-glue applicators to achieve premium tactile finishes. Personal care brands specify clear polypropylene for no-label look applications on transparent bottles.
France
The AGEC anti-waste law accelerates demand for recyclable adhesive certifications in beverage and dairy packaging. Heat seal label demand concentrates in dairy and ready-meal packaging where hermetic sealing protects shelf-stable formulations. Luxury cosmetic brands in Paris demand cold-chain compatible adhesives for refrigerated serum and cream packaging.
Spain
Portuguese and Spanish co-packers retrofit lines to handle thinner film stocks for weight reduction in bottled water production. Water-activated gummed labels dominate corrugated sealing operations in Barcelona logistics hubs for cost efficiency on high-volume B2B shipments. E-commerce fulfillment growth strains existing label application infrastructure in Madrid distribution centers.
Glue-Applied Labels Market Competitive Environment
Global majors compete with regional champions across adhesive formulation and substrate engineering capabilities. The vendor base organizes into three tiers: integrated material-science conglomerates with polymer portfolios, mid-cap converters with dedicated cold-chain or pharmaceutical capacity, and specialized equipment-integrated service providers. Strategic moves center on multi-source resin agreements to hedge petrochemical volatility and APR certification pursuit for wash-off adhesive preferential supplier status.
Within the integrated material-science tier, Avery Dennison Corporation and 3M Company exemplify polymer portfolio leverage to sustain premium positions in pressure-sensitive constructions. CCL Industries anchors North American beverage demand through dedicated operational infrastructure. Constantia Flexibles occupies a position in European food packaging with aluminum-backed lidding and wet-glue label hybrid capabilities. These three entities represent distinct archetypes: material-science conglomerate, regional scale converter, and flexible packaging hybrid.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries |
| Multi-Color Corporation |
| Huhtamaki |
| Constantia Flexibles |
| 3M Company |
| Fort Dearborn Company |
| WestRock |
| Skanem AS |
| Others |
Value Chain & Pricing Dynamics
Skilled rotary press operators in Bavaria and Baden-Württemberg command wage premiums that compress converter margins, widening spreads between premium certified-grade labels and commodity spot-priced alternatives as labor-cost differentials propagate through tiered service bundles.
Pricing Analysis
Service-bundling separates converters who include adhesive formulation consulting and line-speed optimization from those offering bare substrate supply. Three-tier pricing structure across premium, standard, and economy levels reflects APR certification status and volume commitment scale. Pricing pressure stems from fixed-price annual contracts confronting ethylene-vinyl acetate resin volatility. Private-label retail buyers in Southern Europe exhibit highest price sensitivity, while pharmaceutical serialization mandates insulate booklet label tiers from cost compression.
Supply Chain Analysis
Freight costs from Austrian and Finnish metallized paper mills to German bottling corridors concentrate supply risk during energy price spikes. Raw material flows draw from German petrochemical complexes, US Gulf Coast resin producers, and Chinese biaxially oriented polypropylene film manufacturers. Single-source vulnerability sits with specialty pulp grades for premium beverage applications. Distribution runs through converter-direct relationships with co-packing facilities and beverage brand technical procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around converters with in-house PET flake contamination testing and APR-certified adhesive portfolios as EU Green Deal recyclability mandates force smaller players toward acquisition or exit.
For Market Incumbents: Anchor market position through backward integration into water-based adhesive emulsion production and captive supply of thinner film stocks qualified for high-speed rotary lines. Defend against emerging digital-print hybrid specialists by embedding real-time viscosity monitoring into legacy applicator retrofits. Prioritize multi-source resin agreements hedging styrene-butadiene block copolymer volatility.
For New Entrants and Emerging Players: Beverage co-packers in Portugal and the Czech Republic represent the most penetrable channel partner type for tanker-delivered bulk emulsion services. Target pharmaceutical booklet label demand in Poland and Czechia where serialization mandates expand faster than incumbent capacity. Enter through plant-level technical manager relationships decentralizing sourcing decisions from central procurement.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap converters possessing dedicated cold-chain capacity and hybrid flexo-inkjet press installations given brand owner procurement shifts toward short-run variable data. Long-term viability favors entities with wash-off adhesive certification progress and in-house sustainability reporting infrastructure. Monitor APR recognition announcements as inflection indicators for preferential supplier status with major beverage sustainability procurement teams.
| Strategic Initiative | Industry Significance |
|---|---|
| APR Certification Pursuit | Wash-off adhesive recognition opens preferential supplier status with Coca-Cola and PepsiCo sustainability teams. |
| Backward Integration into Emulsion Production | In-house water-based acrylic capacity eliminates solvent recovery infrastructure and drum-handling labor costs. |
| Hybrid Press Installation | Flexo-inkjet integration from Gallus and Omet captures craft spirits seasonal campaigns with variable data capability. |
| Multi-Source Resin Agreements | Hedging ethylene-vinyl acetate and metallocene polyolefin exposure protects margins on fixed-price contracts. |
| Legacy Applicator Retrofit | OPC-UA connectivity upgrades enable real-time adhesive consumption tracking for EU Green Deal sustainability reporting. |
Study Parameters
Trade association filings from FINAT and TLMI, customs data on adhesive resin imports, and SEC disclosures from listed converters formed the secondary backbone. Primary interviews with rotary press operators, beverage brand technical procurement managers, adhesive formulation chemists, and cold-chain logistics coordinators validated supply-side capacity assumptions. Bottom-up triangulation across substrate consumption volumes and top-down cross-checks against end-use packaging production anchored market sizing.
Historical trendline analysis of wet-glue applicator installation rates and pressure-sensitive label adoption patterns informed projection frameworks across the analysis window. Segmentation modeling incorporated adhesive chemistry type, substrate material durability tier, end-use regulatory exposure level, and geographic equipment cluster density. CAGRs derived from elasticity-adjusted demand curves responding to EU Green Deal compliance timelines and EPR fee structures. Forecast inputs included CONAI packaging fee trajectories and REACH Annex XVII restriction implementation pace.
Caveats apply where petrochemical price volatility, pulp mill energy disruption, or FDA migration testing backlog extensions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Hang Tags Market
Labels
Wet Glue Labeling Machines Market
Labels
Pre-Gummed Labels Market
Labels
Polyester Labels Market
Labels
Foam Labels Market
Labels
Ethical Label Market
Labels
Industrial Label Printers Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Non-Adhesive Tags Market
Labels
Global Pressure Labels Market
Labels
United States Print Label Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Global Waterproof Labels Market
Labels
Eco-Friendly Labels Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Global Laminated Labels Market