
 Thermal Labels Market | 2026-2036
Thermal Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Labels Market Analytics
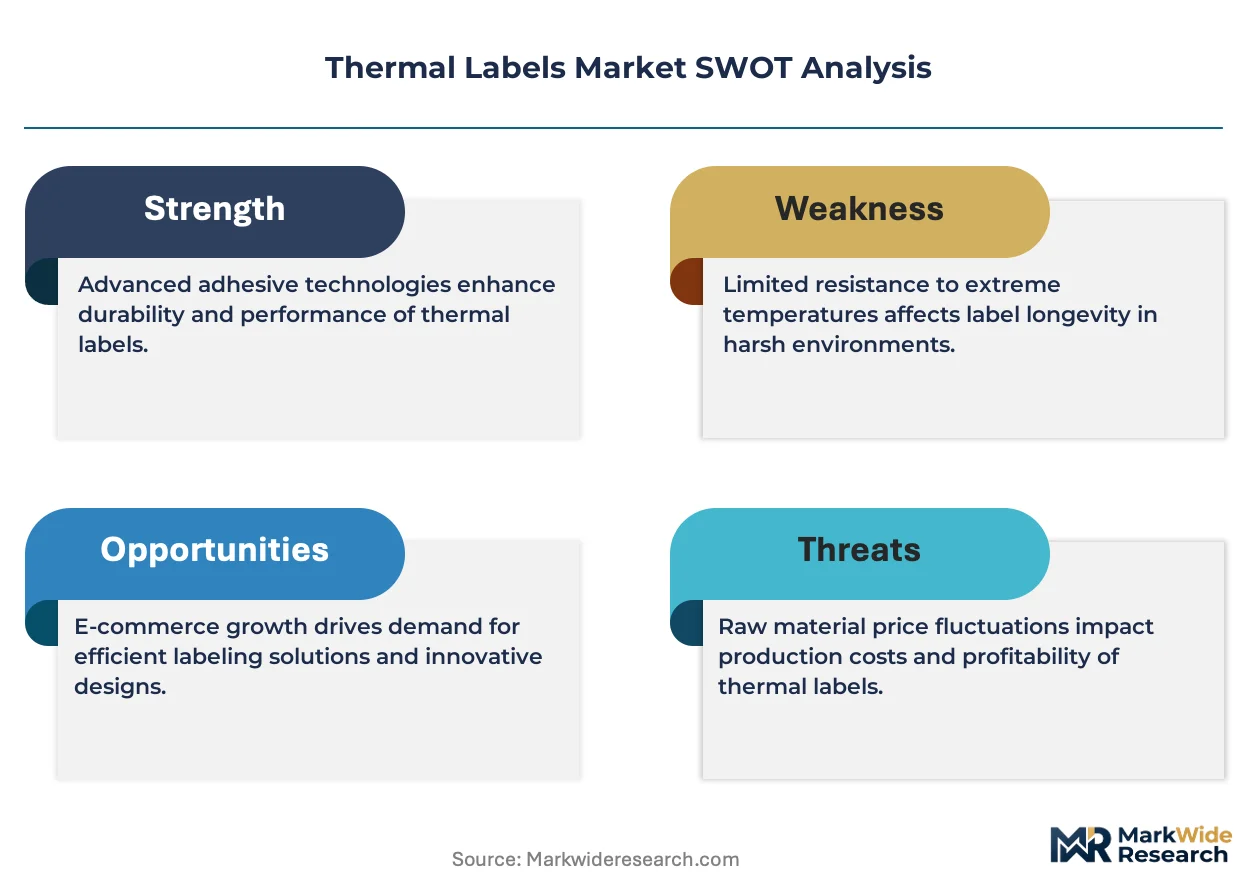
Modular label configurations are shifting how procurement teams evaluate total cost of ownership across thermal printing ecosystems. Avery Dennison Corporation leverages its adhesive science portfolio to dominate premium thermal transfer segments. UPM-Kymmene Corporation anchors European supply through integrated pulp-to-label manufacturing. Zebra Technologies Corporation competes by extending hardware-software bundling that locks in consumable demand.
Thermal labels are pressure-sensitive or tag constructions engineered with heat-sensitive coatings or receptor layers that produce images without liquid inks, typically specified by print speed compatibility, caliper, and adhesive permanence ratings for carton, pallet, or item-level identification. Direct Thermal formulations lead in short-life retail and logistics applications where UV exposure remains controlled, while Thermal Transfer substrates capture margin pools in manufacturing and cold-chain food labeling where archive durability and chemical resistance command premium positioning. Polypropylene and PET material grades are displacing paper in high-moisture environments across food processing and pharmaceutical distribution.
FDA food-contact substance notifications and EU REACH chemical compliance frameworks govern adhesive and coating chemistries in labels destined for consumable goods, while OSHA hazard communication standards mandate durable thermal-printed GHS pictograms on chemical containers in US manufacturing facilities. Stakeholders must monitor how dual regulatory pressures on material safety and data traceability reshape specification requirements and supplier qualification timelines.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing procurement cycles and forcing specification standardization across thermal label ecosystems. Retailers now mandate same-day processing capabilities that reshape adhesive chemistry and substrate durability requirements.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory material traceability protocols are expanding serialized label deployments across German and French distribution networks.
- Cold-chain pharmaceutical logistics:Temperature excursion monitoring requirements in vaccine distribution are driving thermal transfer label adoption for archive-grade documentation.
- Polypropylene substrate migration:Food processors in high-moisture environments are specifying synthetic facestocks that eliminate paper-based failure modes.
Market Restraints
- Pulp cost volatility:Integrated paper-based label manufacturers face margin compression from fluctuating softwood pulp contract pricing.
- Adhesive chemistry constraints:EU REACH substance restrictions limit silicone and acrylic formulation options for direct food-contact applications.
- Digital printing substitution:Inkjet and laser technologies are capturing short-run variable data applications previously served by thermal transfer systems.
Strategic Opportunities
- India pharmaceutical export compliance:CDSCO serialization mandates for active pharmaceutical ingredients create demand for multi-language thermal labels with tamper-evident features.
- RFID-thermal hybrid convergence:Combined visual and electronic identification formats are penetrating apparel and electronics asset-tracking workflows.
- Extended Producer Responsibility frameworks:EU Green Deal packaging directives incentivize recyclable adhesive systems and linerless thermal constructions.
Industry Challenges
- Color formulation chemistry expertise:Shortages of specialists capable of developing heat-stable pigments for color thermal imaging constrain product pipeline velocity.
- Legacy warehouse management system integration:Thermal printer firmware updates frequently conflict with decade-old ERP configurations in third-party logistics facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Labels Market |
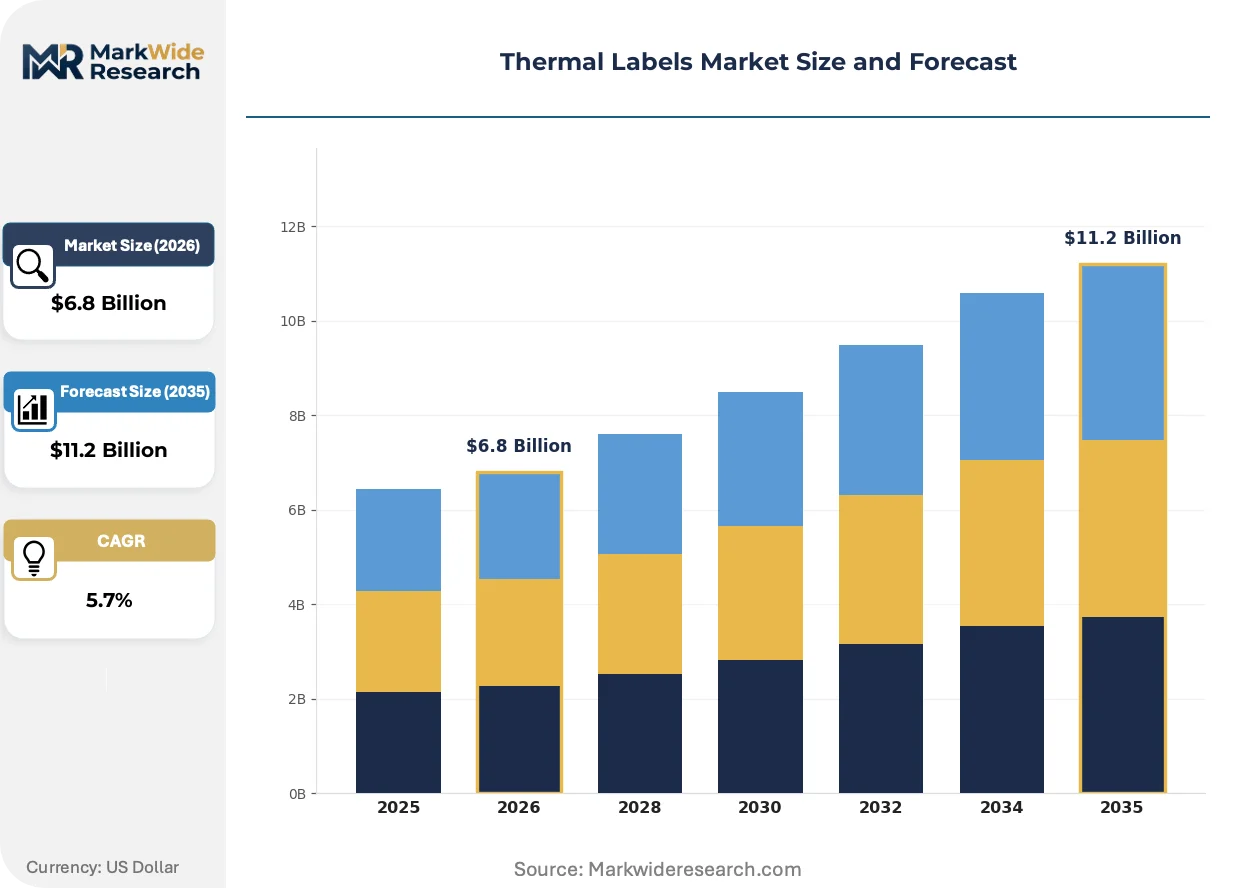
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Thermal, Thermal Transfer, Print & Apply, Labels with Media Application: Retail, Logistics, Manufacturing, Food & Beverage Material: PET, Paper, Polypropylene, Vinyl Technology: Raster Image, Digital Printing, Inkjet, Laser |
| Companies Covered | Avery Dennison Corporation, UPM-Kymmene Corporation, 3M Company, Honeywell International Inc., CCL Industries, Constantia Flexibles, Lintec Corporation, Brady Corporation, Zebra Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Labels Market Evolving Landscape
Automation of label application and inspection workflows is compressing labor content in high-volume packaging operations. Three developments are restructuring competitive requirements.
Print-and-apply systems with integrated vision verification are automating quality assurance in pharmaceutical and food manufacturing lines. Major contract packagers in the Netherlands and Belgium are deploying these units at throughput rates exceeding 200 packages per minute. The technology is automating defect rejection and lot-code validation that previously required manual sampling protocols.
OSHA hazard communication standard updates are mandating enhanced durability specifications for GHS pictogram labels on chemical containers. US manufacturing facilities must now demonstrate legibility after 90-day chemical immersion testing. Chemical distributors are responding by specifying polyester thermal transfer constructions with solvent-resistant topcoats.
Consolidated supplier contracts with multi-year consumable lock-ins are displacing spot purchasing in enterprise retail and logistics operations. Buying organizations in Germany's Ruhr industrial corridor are negotiating total-cost-per-label agreements that bundle hardware, media, and service. This pattern concentrates procurement authority among fewer thermal label vendors with integrated supply capabilities.
Thermal Labels Market Segmentation
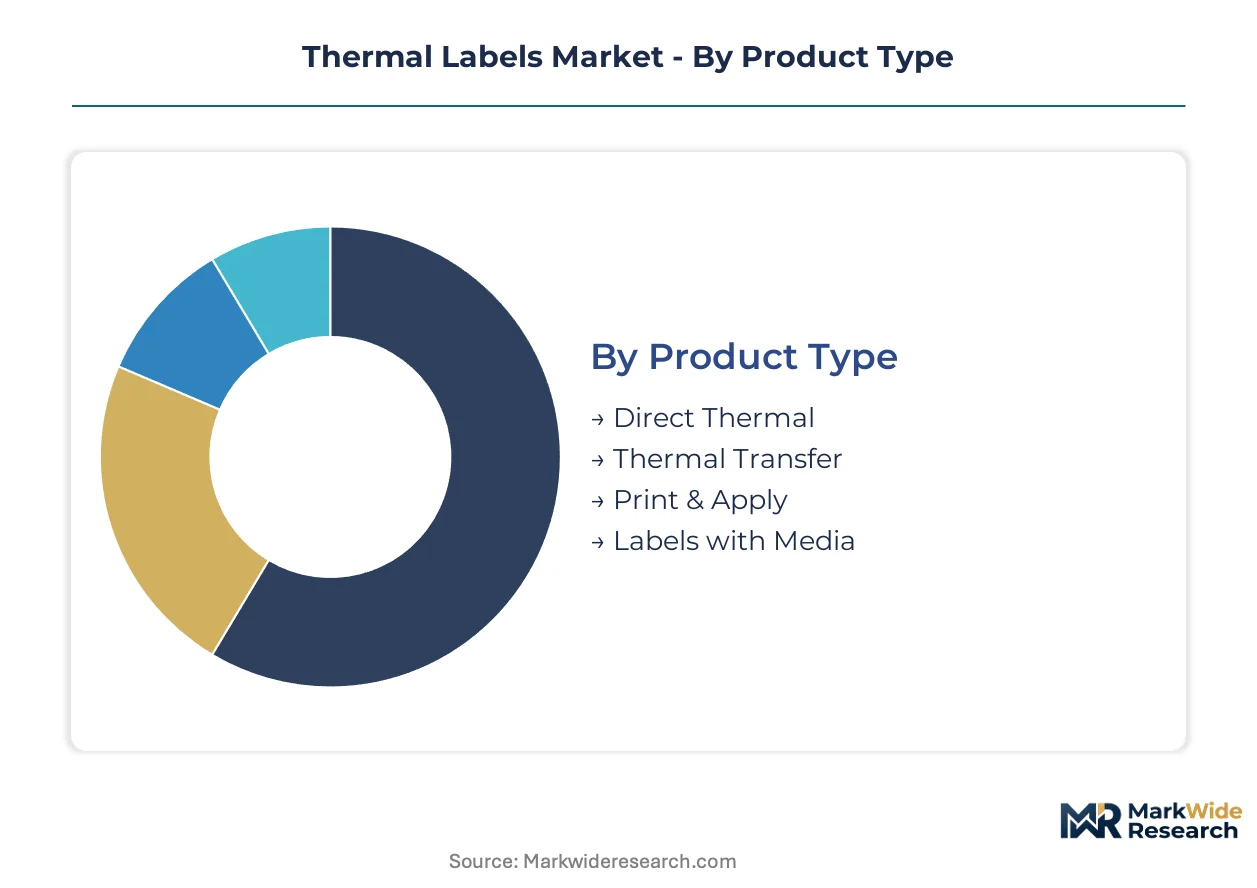
Thermal label procurement decisions cascade through substrate chemistry, print mechanism compatibility, and end-use durability requirements. Specification mismatches trigger failure modes ranging from adhesive degradation in cold-chain environments to image fade in UV-exposed retail displays.
Product Type:
Supply concentration in thermal ribbon and direct thermal coatings manufacturing has consolidated around three integrated chemical formulators controlling coating dispersion technologies.
- Direct Thermal:Heat-sensitive coatings containing leuco dye and developer systems produce images through thermal printhead contact without ribbon consumption. E-commerce fulfillment centers in Germany's Ruhr corridor specify these for short-life carton labels where UV exposure remains minimal and cost-per-impression drives procurement.
- Thermal Transfer:Wax-resin and resin-based ribbons transfer pigment to receptor-coated substrates, delivering archive-grade durability for pharmaceutical serialization and chemical GHS labeling. Cold-chain vaccine distribution networks mandate these constructions for temperature excursion documentation requiring multi-year legibility.
- Print & Apply:Integrated applicator systems combine thermal printing with automated label placement at throughput rates exceeding 200 packages per minute. Major contract packagers in Belgium and the Netherlands deploy these for pharmaceutical lot-code compliance.
- Labels with Media:Pre-printed or partially converted label stocks bundled with complementary ribbons or receipt paper for integrated printer ecosystems. Retailers negotiating total-cost-per-label contracts favor these bundled configurations.
Today's leader: Thermal Transfer. Tomorrow's challenger: Print & Apply.
Application:
Cost tier stratification separates specification-intensive regulated applications from commodity logistics labeling.
- Retail:Price markdowns, shelf-edge labeling, and receipt printing dominate volume consumption. Direct thermal paper constructions with standard permanent adhesives satisfy most requirements, though polypropylene facestocks are penetrating high-humidity grocery environments.
- Logistics:Carton and pallet identification for parcel networks and third-party distribution centers. Same-day processing mandates are compressing procurement cycles and forcing adhesive standardization across carrier networks.
- Manufacturing:Work-in-process tracking, asset identification, and OSHA-mandated hazard communication labels. US chemical facilities must demonstrate GHS pictogram legibility after 90-day solvent immersion, specifying polyester thermal transfer constructions.
- Food & Beverage:Primary packaging labels, case coding, and cold-chain monitoring documentation. EU REACH restrictions on silicone and acrylic adhesives constrain direct food-contact formulations, pushing processors toward compliant synthetic facestock alternatives.
Margin capture concentrates in Manufacturing. Volume expansion runs through Logistics.
Material:
Volume concentration in paper substrates is eroding as moisture-related failure modes drive specification migration.
- PET:Polyester films with solvent-resistant topcoats deliver dimensional stability and chemical resistance for durable goods labeling and chemical container identification. FDA food-contact substance notifications govern coating chemistries for consumable goods applications.
- Paper:Uncoated and topcoated thermal papers remain dominant in cost-sensitive short-life applications. Integrated manufacturers face margin pressure from softwood pulp contract volatility.
- Polypropylene:Synthetic facestocks with enhanced moisture resistance are displacing paper in food processing washdown environments and pharmaceutical distribution cold rooms.
- Vinyl:Flexible PVC constructions conform to curved surfaces for drum labeling and outdoor asset tracking where weatherability exceeds polyester cost justification.
Installed base dominance: Paper. Specification upgrade trajectory: Polypropylene.
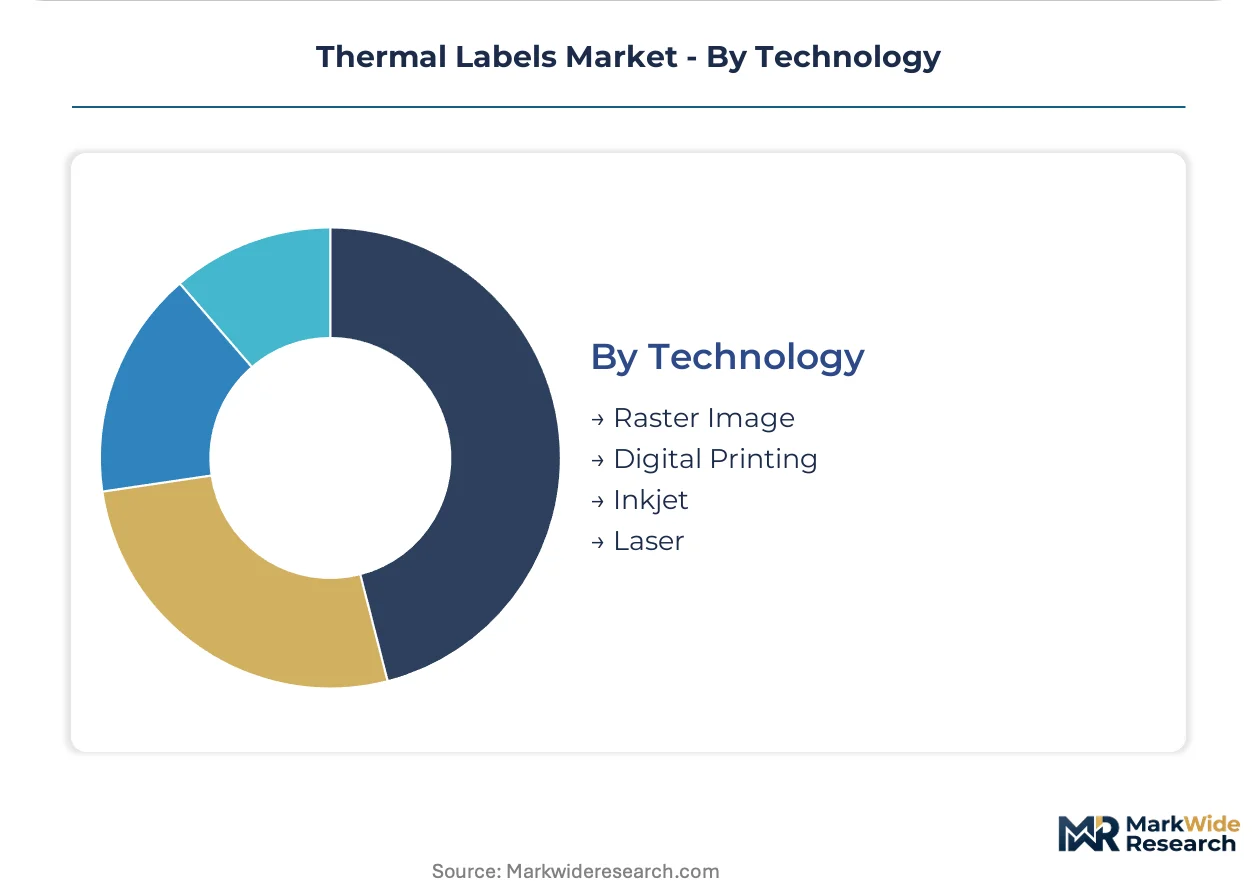
Technology:
Customer type segmentation separates integrated hardware-software ecosystems from consumable-agnostic printing platforms.
- Raster Image:Bitmap-based thermal printhead control dominates industrial printer architectures, with firmware compatibility determining media specification lock-in.
- Digital Printing:Variable data integration without plate changes enables short-run customization for promotional and regional packaging variants.
- Inkjet:Piezoelectric and thermal inkjet systems are capturing variable data applications previously served by thermal transfer, particularly in primary packaging decoration.
- Laser:Toner-based systems compete for document and label production in office environments where thermal printer hardware procurement is avoided.
Established infrastructure: Raster Image. Displacement threat: Inkjet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal label manufacturing originated in the United States during the 1960s with the commercialization of heat-sensitive coatings for retail and logistics applications. German chemical and paper engineering expertise subsequently scaled European production through integrated pulp-to-label supply chains. Today, demand concentrates in industrial logistics corridors across Germany, the United States, China, India, and Japan.
United States
OSHA hazard communication mandates drive durable label specifications for chemical container identification in manufacturing facilities. FDA food-contact substance notifications govern adhesive chemistries for consumable goods applications. The Midwest industrial corridor spanning Ohio and Illinois concentrates contract packaging operations requiring high-throughput thermal transfer systems.
Germany
The EU Packaging and Packaging Waste Regulation compels serialized material traceability across distribution networks in the Ruhr industrial region. REACH chemical compliance frameworks restrict silicone and acrylic formulation options for direct food-contact labels. Bavaria's automotive supply chain anchors demand for work-in-process tracking labels with archive-grade durability.
China
E-commerce fulfillment velocity requirements from domestic platform operators compress procurement cycles for carton and pallet identification labels. NMPA pharmaceutical serialization mandates for export compliance drive thermal transfer adoption in cold-chain documentation. The Yangtze River Delta manufacturing belt hosts contract packagers migrating from paper to polypropylene facestocks for moisture resistance.
India
CDSCO serialization requirements for active pharmaceutical ingredients create demand for multi-language thermal labels with tamper-evident features. FSSAI food safety regulations constrain adhesive chemistry selections for primary packaging applications. Maharashtra's pharmaceutical export corridor in Mumbai-Pune concentrates label specification expertise for regulated international markets.
Japan
METI industrial standardization programs promote RFID-thermal hybrid formats for electronics asset-tracking workflows. PMDA pharmaceutical distribution regulations mandate temperature excursion documentation for biologics logistics. The Kansai manufacturing region around Osaka maintains specification leadership in synthetic facestock development for high-humidity environments.
Thermal Labels Market Competitive Landscape
Premium-margin players sit above commodity-margin players across adhesive science and coating formulation capabilities. The market exhibits tiered concentration with integrated chemical-materials conglomerates controlling upstream coating technologies and mid-scale converters dominating regional distribution. Three archetypes prevail: pulp-to-label integrated manufacturers, hardware-software ecosystem bundlers, and specialty adhesive formulators. Competitive moves center on multi-year consumable lock-in contracts and backward integration into coating dispersion technologies.
Within the integrated materials tier, Avery Dennison Corporation and UPM-Kymmene Corporation exemplify divergent geographic anchoring strategies. Zebra Technologies Corporation occupies a position among hardware-software ecosystem providers that bundle printer deployment with captive consumable demand. These three entities represent the dominant competitive archetypes without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| UPM-Kymmene Corporation |
| 3M Company |
| Honeywell International Inc. |
| CCL Industries |
| Constantia Flexibles |
| Lintec Corporation |
| Brady Corporation |
| Zebra Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters in Germany's Ruhr corridor and Ohio's industrial belt anchor pricing discipline through multi-year consumable lock-ins with enterprise logistics buyers, while their limited balance-sheet capacity constrains aggressive price competition against integrated chemical conglomerates with captive coating dispersion technologies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates archive-grade thermal transfer constructions with FDA food-contact certifications from commodity direct thermal paper and uncoated logistics grades. Price differentiation rests on adhesive chemistry complexity and substrate durability ratings. Cost compression in economy-tier paper labels is intensifying because softwood pulp contract volatility squeezes integrated manufacturers without backward integration into pulp assets. Third-party logistics operators exhibit highest price sensitivity, while pharmaceutical contract packers prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Belgium, the Netherlands, and Illinois operate as hub-and-spoke nodes for just-in-time label replenishment to pharmaceutical and food manufacturing lines. Manufacturing concentrates in Germany, the United States, and Finland, with coating dispersion technologies controlled by integrated pulp-to-label conglomerates. Raw material dependencies include softwood pulp, leuco dye developer systems, and silicone release liners. Single-source vulnerability in thermal ribbon wax-resin formulations creates exposure to chemical feedstock disruptions. Distribution runs through converter networks with localized slitting and finishing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where cold-chain pharmaceutical logistics and EU Packaging and Packaging Waste Regulation traceability mandates are shifting procurement toward premium thermal transfer specifications with archive-grade durability.
For Market Incumbents: Anchor defensive positioning through backward integration into coating dispersion technologies to capture margin pools currently flowing to chemical formulators. Consolidate converter networks in Germany's industrial corridor to tighten channel control against emerging hardware-software bundlers. Prioritize certification investment for FDA food-contact and EU REACH-compliant adhesive systems.
For New Entrants and Emerging Players: Specialty adhesive formulators with heat-stable pigment expertise represent the most penetrable white-space target, given specialist shortages constraining color thermal imaging pipelines. Target India's CDSCO-mandated pharmaceutical serialization market through partnerships with Mumbai-Pune export corridor contract packagers. Pursue RFID-thermal hybrid convergence as a differentiated go-to-market angle in Japanese electronics asset-tracking workflows.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional converters lacking integrated coating capabilities but holding sticky relationships with German automotive and logistics buyers. Long-term viability favors entities with exposure to regulated pharmaceutical and food labeling segments over commodity e-commerce fulfillment. Watch NMPA and CDSCO serialization mandate enforcement velocity as the signal indicating inflection toward premium specification demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Dispersion | Captures margin pools currently flowing to chemical formulators in Germany and Finland. |
| Multi-Year Consumable Lock-In Contracts | Bundles hardware, media, and service to displace spot purchasing among Ruhr corridor retailers. |
| FDA Food-Contact Certification Investment | Unlocks premium positioning in cold-chain pharmaceutical and food processing applications. |
| RFID-Thermal Hybrid Product Development | Penetrates Japanese electronics and apparel asset-tracking workflows per METI standardization. |
| Regional Converter Network Consolidation | Tightens channel control against Zebra Technologies' hardware-software ecosystem bundling. |
Research Methodology
Direct dialogue with procurement directors at German automotive OEMs, pharmaceutical contract packaging executives in Belgium, thermal printer firmware engineers, and adhesive chemistry R&D leads grounded qualitative findings. Secondary validation drew from EU REACH substance restriction filings, FDA food-contact substance notifications, OSHA hazard communication standard updates, and customs trade data for thermal paper and synthetic facestock imports. Bottom-up and top-down triangulation reconciled converter shipment data with end-use demand estimates across retail, logistics, manufacturing, and pharmaceutical verticals.
Bottom-up modeling segmented volume and value across the analysis window by product type, application, material grade, and print technology compatibility. Top-down cross-checks incorporated e-commerce fulfillment center expansion pipelines, pharmaceutical serialization mandate implementation timelines, and cold-chain infrastructure investment patterns. CAGRs were derived from regression analysis of historical label consumption against industrial production indices and regulatory compliance deadlines. Forecast inputs included pulp futures pricing volatility and REACH chemical restriction expansion scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal packaging directive implementation, digital printing substitution rates, and adhesive chemistry specialist availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Waterproof Labels Market
Labels
United States Print Label Market
Labels
Linerless Labels Market
Labels
Water Dissolvable Labels Market
Labels
Sustainable Labels Market
Labels
Retro-Reflective Labels Market
Labels
Global Laminated Labels Market
Labels
Europe Self Adhesives Label Market
Labels
Pressure Sensitive Labels Market
Labels
Integrated Labeling System Market
Labels
Primary Packaging Labels Market
Labels
Inventory Tags Market
Labels
Sheeted Labels Market
Labels
Global in-Mold Labels Market
Labels
India Print Label Market
Labels
Ampoule Sticker Labeling Machine Market