
 Water Dissolvable Labels Market | 2026-2036
Water Dissolvable Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Water Dissolvable Labels Market Analytics
Polyvinyl alcohol film is decoupling water dissolvable labels from conventional paper adhesives by eliminating residue contamination in automated wash systems. Avery Dennison Corporation leverages its global pressure-sensitive materials network to supply pharmaceutical-grade dissolvable substrates across North American and European plants. UPM Raflatac anchors its position through integrated pulp sourcing and proprietary barrier coatings that control dissolution rates in variable water temperatures. SmartSolve Industries specializes in custom-engineered label constructions for industrial laundries and food processing equipment where complete wash-away is mandatory.
Water dissolvable labels are pressure-sensitive or adhesive-coated identifiers engineered from polyvinyl alcohol, modified pulp, or biodegradable polymer substrates that disintegrate completely upon contact with water without leaving adhesive residue, typically dissolving within thirty seconds to five minutes depending on temperature and agitation levels. These labels serve critical functions in pharmaceutical serialization, food container return programs, and reusable industrial tote tracking where label removal must not contaminate the product or processing stream. The material type dimension shows polyvinyl alcohol constructions commanding the dominant share due to their tunable dissolution profiles and compatibility with thermal transfer printing, while biodegradable plastics represent the fastest-expanding category as brand owners pursue alternatives to petroleum-derived films. Application-level demand concentrates in pharmaceutical products, where FDA and EMA track-and-trace mandates require labels that survive distribution but disappear during container washing for reuse.
The FDA enforces pharmaceutical labeling integrity through 21 CFR Part 211 while the EPA guides sustainable packaging claims under its Safer Choice program, together pushing manufacturers toward verified dissolvable constructions that meet both performance and environmental assertions. EMA's Falsified Medicines Directive and the EU Green Deal's packaging waste reduction targets are converging to accelerate regulatory preference for labels that eliminate secondary removal steps and adhesive waste streams. Stakeholders must monitor evolving dissolution test standards from ISO and regional pharmacopeias to ensure product qualification ahead of procurement specification changes.
Market Dynamics
Pharmaceutical serialization mandates and reusable packaging economics are forcing label suppliers to engineer substrates that survive supply chain rigors yet vanish completely during automated wash cycles, decoupling performance from permanent adhesion.
Growth Catalysts
- EMA Falsified Medicines Directive:European pharmaceutical packagers must deploy track-and-trace labels on returnable glass vials, creating mandatory demand for dissolvable constructions that clear washing tunnels without residue.
- Polyvinyl alcohol film tunability:Thermal transfer compatibility and dissolution rate control allow contract manufacturers to standardize on single substrate families across variable water temperature regimes.
- East Asian export hub concentration:Contract packagers in China and South Korea serve multinational consumer brands with sustainability scorecards, concentrating procurement volume for certified dissolvable label suppliers.
Market Restraints
- Petrochemical feedstock volatility:Polyvinyl alcohol production depends on acetic acid and ethylene derivatives, exposing converters to input cost swings that compress margin on fixed-price pharmaceutical contracts.
- Specialized resin supply concentration:Dissolvable-grade PVA resin production clusters among a limited set of chemical manufacturers in Japan and Germany, creating single-source vulnerability for mid-tier label converters.
- Dissolution rate standardization gaps:Absence of harmonized ISO test protocols forces suppliers to maintain multiple qualification batches for regional pharmacopeia requirements, inflating inventory carrying costs.
Strategic Opportunities
- Industrial laundry equipment tracking:Textile rental services and food processing plants require complete wash-away identification for regulatory compliance, opening volume demand outside pharmaceutical channels.
- EU Green Deal packaging waste targets:Mandatory reduction in single-use packaging creates regulatory tailwind for returnable container programs requiring dissolvable labels as enabling infrastructure.
- SmartSolve barrier coating convergence:Integration of moisture-triggered dissolution with RFID inlay compatibility enables closed-loop asset tracking without secondary label removal labor.
Industry Challenges
- Formulation chemistry expertise scarcity:Compounding PVA with plasticizers and surfactants for specific dissolution windows requires polymer science specialization that outpaces current technical training pipeline output.
- Pharmacopeia certification timelines:USP and EP extractables testing protocols demand 18-24 month validation cycles, delaying revenue recognition on new pharmaceutical customer qualifications.
- Legacy adhesive system integration:Converters must retrofit coating lines designed for permanent acrylics to handle water-soluble hot melts without cross-contamination or downtime penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Dissolvable Labels Market |
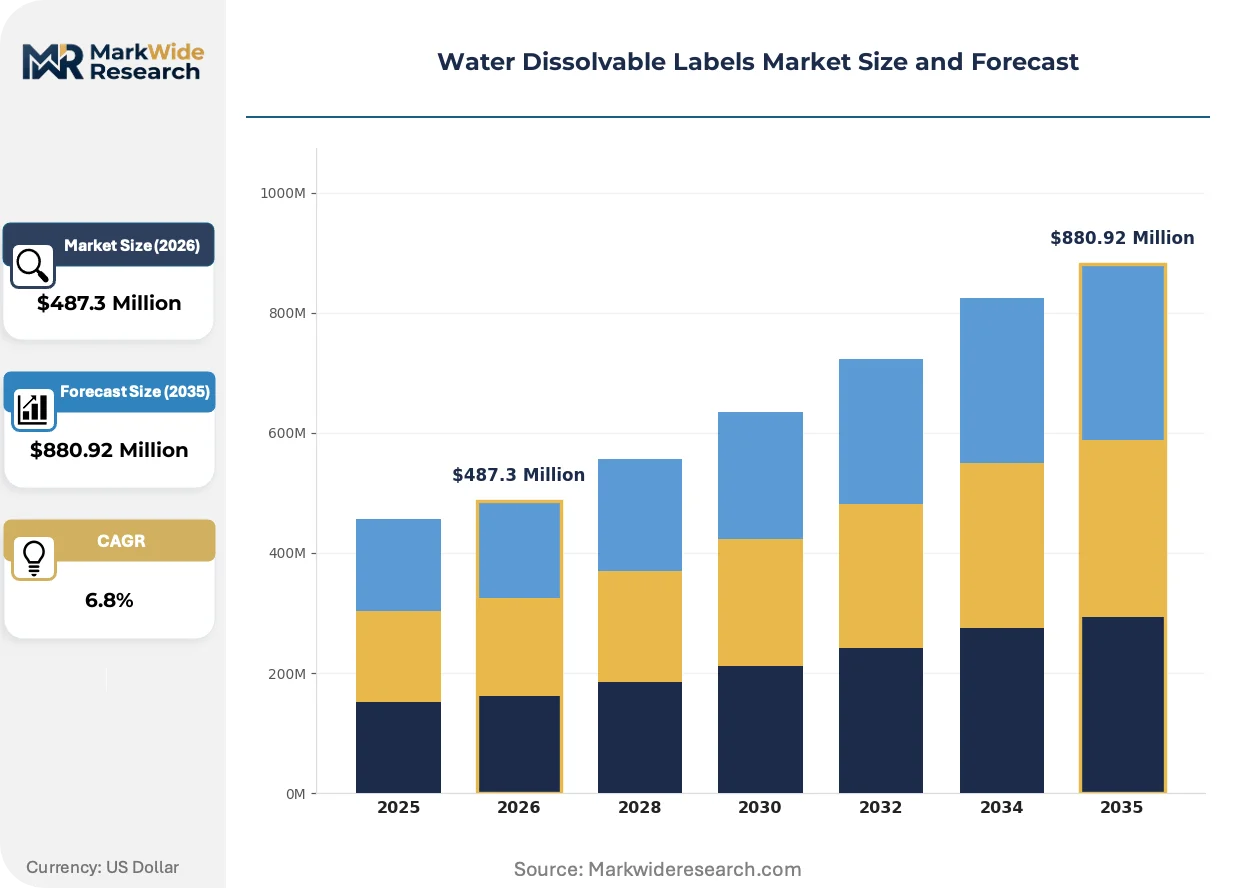
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Pulp, Polyvinyl Alcohol, Paper, Biodegradable Plastics Application: Food Packaging, Pharmaceutical Products, Cleaning Supplies, Cosmetics End User: Retail, Manufacturing, Healthcare, Foodservice Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Avery Dennison Corporation, UPM Raflatac, 3M Company, CCL Industries, Stranco, Brady Worldwide Inc., Lintec Corporation, Multi-Color Corporation, SmartSolve Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Dissolvable Labels Market Evolving Landscape
Material science advances and regulatory harmonization efforts are compressing the gap between laboratory dissolution performance and industrial wash system reliability, reshaping how converters specify substrate constructions.
Modified cellulose pulp substrates are integrating nanocellulose reinforcement layers to achieve wet strength during shipping while maintaining rapid disintegration in ambient-temperature rinses. Food container return programs in Nordic markets are piloting these constructions to eliminate the temperature dependency that complicates polyvinyl alcohol logistics. The structural consequence is integration of pulp-based alternatives into premium pricing tiers previously reserved for synthetic films.
REACH restrictions on persistent organic pollutants are compelling adhesive formulators to eliminate fluorinated surfactants from dissolvable hot melt recipes. Industrial laundries operating under tightened effluent standards in Germany and the Netherlands now reject labels containing perfluorinated compounds, forcing suppliers to validate bio-based wetting agents. Small-format pharmaceutical vial labels face the steepest reformulation burden given their stringent residue limits.
Consolidated procurement by multinational consumer brands is compressing supplier qualification cycles from multi-year frameworks to annual sustainability scorecard reviews. Contract packagers in China's Yangtze River Delta region are consolidating label purchases through preferred supplier programs that bundle dissolvable constructions with permanent adhesive volumes. This concentration is most visible in personal care refill pod programs where brand owners mandate single-source accountability for all primary and secondary packaging components.
Water Dissolvable Labels Market Segmentation
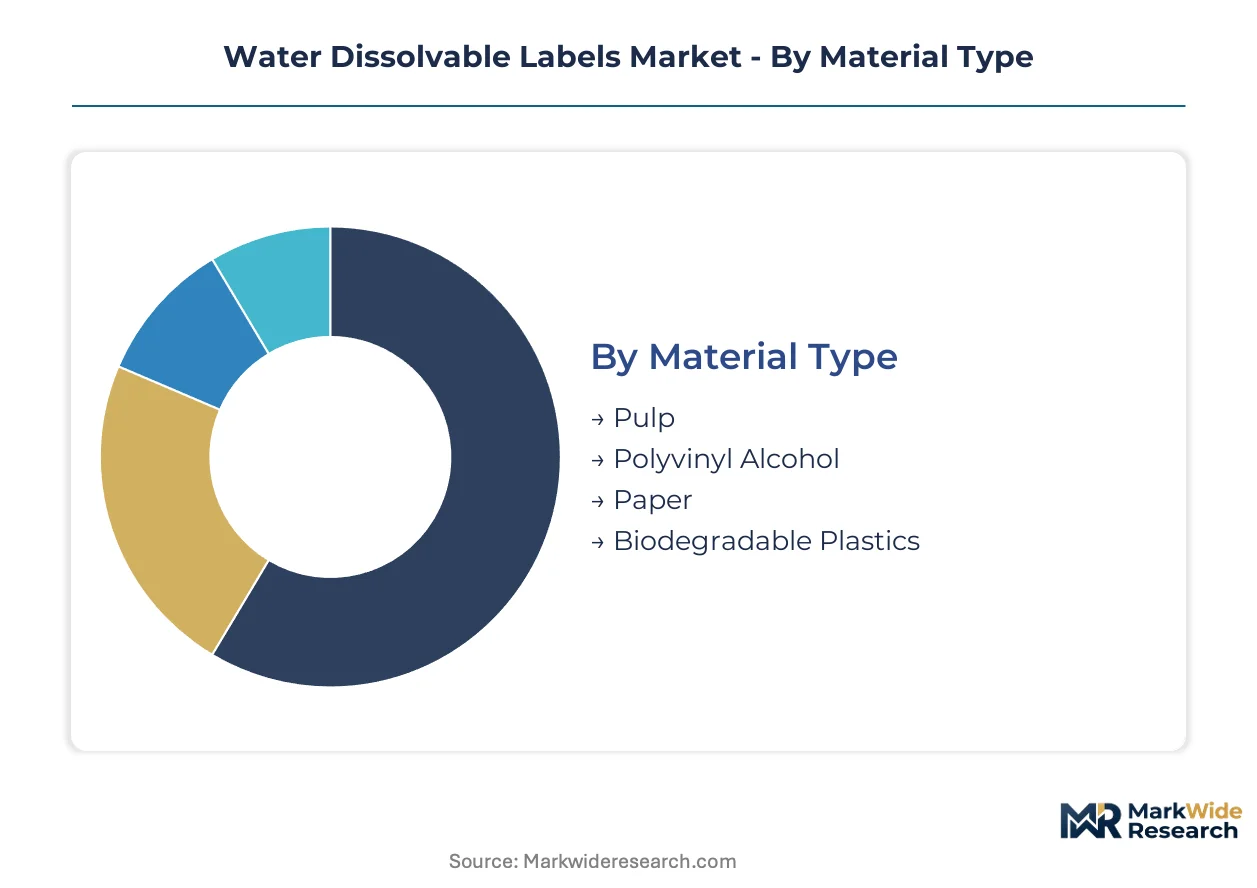
Substrate selection and application requirements are driving divergent specification paths across water dissolvable labels. Pharmaceutical serialization mandates and reusable packaging economics are forcing converters to align material portfolios with dissolution performance tiers rather than one-size-fits-all constructions.
Material Type:
Converters face upgrade pressure as legacy paper adhesives fail new residue limits in automated wash systems, triggering replacement cycles toward engineered films.
- Polyvinyl Alcohol:Thermal transfer printable films with tunable dissolution windows from thirty seconds to five minutes. Demand concentrates in German pharmaceutical plants serving EU Green Deal compliance deadlines for returnable glass vial programs.
- Pulp:Modified cellulose substrates reinforced with nanocellulose layers for ambient-temperature disintegration. Nordic food container return programs are piloting these constructions to eliminate hot-water logistics dependencies.
- Paper:Conventional dissolvable constructions with starch-based adhesives. Limited to cost-sensitive applications where residue tolerance permits slower dissolution kinetics.
- Biodegradable Plastics:Polylactic acid and polyhydroxyalkanoate alternatives to petroleum-derived films. Brand owners pursuing fossil-free packaging scorecards are driving qualification trials in South Korean contract manufacturing hubs.
Volume placements concentrate in Polyvinyl Alcohol; the faster expansion belongs to Biodegradable Plastics.
Application:
Regulatory mandates are fragmenting demand across end-use sectors with incompatible performance specifications and certification timelines.
- Pharmaceutical Products:FDA 21 CFR Part 211 and EMA Falsified Medicines Directive require track-and-trace labels surviving distribution but vanishing during container washing. USP and EP extractables testing protocols demand eighteen to twenty-four month validation cycles for new constructions.
- Food Packaging:Returnable container programs in Germany and the Netherlands require complete wash-away under tightened effluent standards rejecting perfluorinated compounds.
- Cleaning Supplies:Refill pod programs mandate dissolvable labels for primary and secondary packaging accountability. Personal care brands are consolidating procurement through preferred supplier programs in China's Yangtze River Delta.
- Cosmetics:Premium packaging with sustainability scorecard requirements. Smaller volume than pharmaceutical or food channels but higher margin tolerance for certified dissolvable constructions.
Revenue concentration sits with Pharmaceutical Products; Cosmetics is climbing fastest on premium positioning.
End User:
Customer procurement sophistication varies sharply, with institutional buyers demanding integrated compliance documentation versus fragmented retail purchasing.
- Manufacturing:Contract packagers serving multinational brands with bundled sustainability mandates. East Asian export hubs in China and South Korea concentrate volume through annual scorecard reviews.
- Healthcare:Hospital pharmacy operations and clinical trial logistics requiring serialized container tracking with complete wash-away.
- Foodservice:Industrial laundries and food processing plants under regulatory compliance pressure for complete label removal.
- Retail:Fragmented demand from small-format pharmacies and specialty food retailers with limited technical specification capabilities.
Procurement scale favors Manufacturing; Foodservice is expanding most quickly on regulatory tailwinds.
Distribution Channel:
Channel selection reflects customer technical support needs and order consolidation patterns across converter networks.
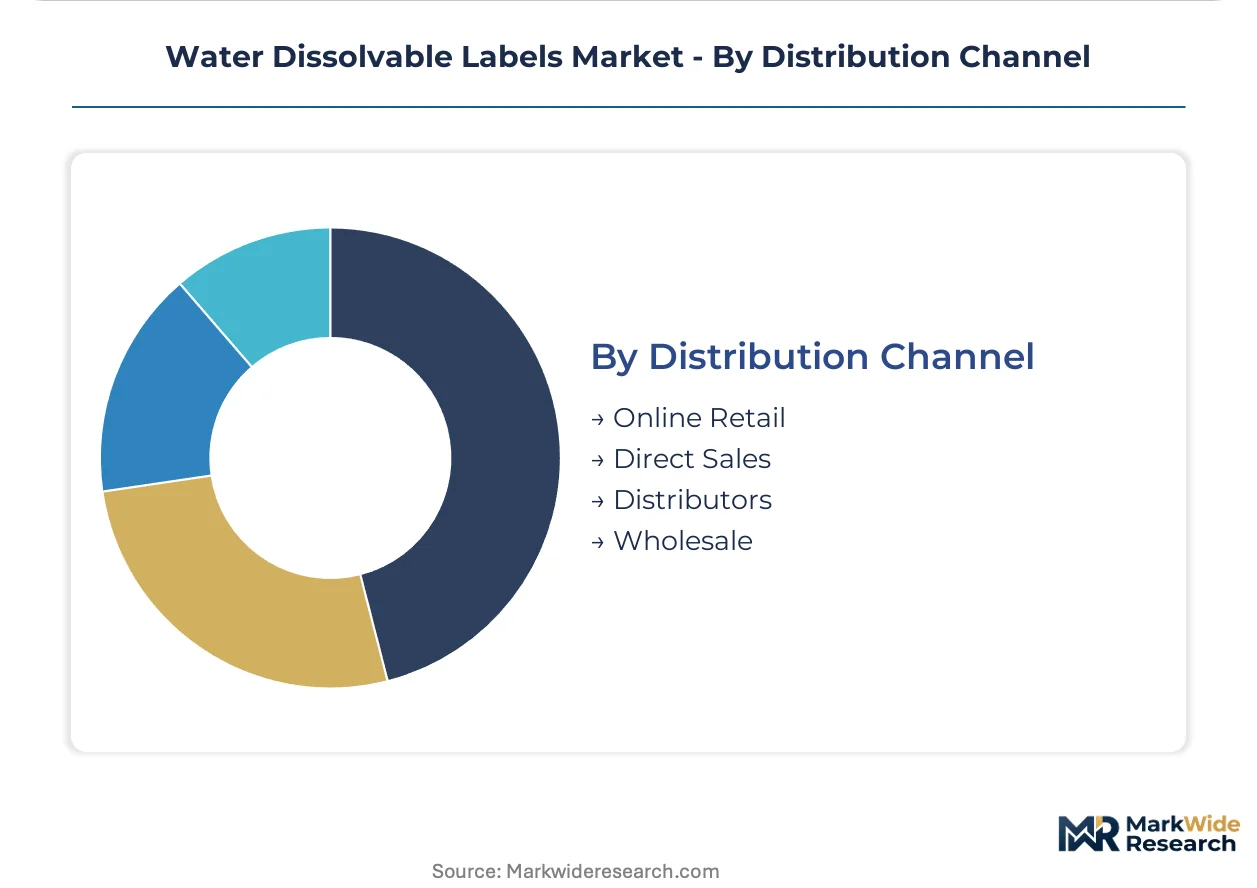
- Distributors:Technical specialists maintaining qualification documentation for pharmaceutical and food safety certifications. Serve mid-tier converters lacking direct resin supplier relationships.
- Direct Sales:Strategic accounts with volume commitments and custom formulation requirements. Enables collaborative dissolution rate engineering for specific wash tunnel parameters.
- Online Retail:Standardized product lines for small-volume buyers and pilot program sampling. Limited to constructions not requiring application engineering support.
- Wholesale:Commodity-grade dissolvable labels for cost-sensitive industrial applications with relaxed residue specifications.
Transaction value concentrates through Direct Sales; Online Retail is gaining share fastest on sampling efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract packagers in China's Yangtze River Delta and South Korea's Seoul Capital Area concentrate procurement volume for multinational consumer brands with strict sustainability mandates. German pharmaceutical manufacturers anchor European demand as EU Green Deal packaging deadlines approach.
China
Personal care refill pod programs and food container return schemes drive label demand among contract manufacturers serving Western brand owners. The country's national packaging regulator enforces tightened effluent standards under dual carbon goals. Shanghai and Suzhou industrial clusters host preferred supplier programs bundling dissolvable constructions with permanent adhesive volumes.
Germany
Pharmaceutical serialization mandates for returnable glass vials create mandatory procurement of polyvinyl alcohol labels. EMA's Falsified Medicines Directive and REACH restrictions on fluorinated surfactants reshape formulation requirements. The Rhine-Ruhr and Bavarian chemical corridors concentrate dissolvable-grade resin production among specialized manufacturers.
United States
FDA 21 CFR Part 211 enforcement and EPA Safer Choice program guidance push pharmaceutical packagers toward verified dissolvable constructions. Industrial laundry equipment tracking opens volume demand outside pharmaceutical channels. The New Jersey pharmaceutical corridor and Midwest industrial belt anchor domestic converter networks.
South Korea
Multinational electronics and personal care brands mandate sustainability scorecards for contract packagers. The national pharmaceutical regulator aligns with international track-and-trace standards for export-oriented manufacturing. The Seoul Capital Area and Busan-Ulsan industrial zones concentrate procurement through annual supplier consolidation reviews.
Japan
PMDA serialization requirements and METI packaging waste reduction targets converge on dissolvable label specifications. Specialized PVA resin production clusters among limited chemical manufacturers serving regional converters. The Kanto and Kansai industrial belts maintain technical leadership in dissolution rate engineering for variable temperature regimes.
Water Dissolvable Labels Market Competitive Landscape
Portfolio diversification dominates the current landscape as established adhesive specialists expand into pharmaceutical-grade dissolvable substrates. The vendor base spans multinational materials conglomerates with integrated pulp networks, mid-tier converters with regional coating capabilities, and niche specialists in custom-engineered dissolution systems. Three archetypes define competitive positioning: integrated substrate-coating operations, technology licensors controlling proprietary barrier formulations, and regional converters serving single-industry verticals. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing captive resin supply or co-development agreements with wash equipment manufacturers.
Among North American materials specialists, Avery Dennison Corporation and SmartSolve Industries exemplify divergent strategic archetypes. Avery Dennison occupies a position representing global pressure-sensitive materials networks supplying pharmaceutical-grade substrates across multiple continents. SmartSolve Industries anchors the specialist tier, occupying a position tied to custom-engineered label constructions for industrial laundries and food processing equipment. European integrated pulp operations, represented by UPM Raflatac, sit within the substrate-control archetype through proprietary barrier coating technologies. These three named entities collectively illustrate how competitive advantage derives from either geographic reach, application specialization, or upstream material control rather than undifferentiated scale.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| UPM Raflatac |
| 3M Company |
| CCL Industries |
| Stranco |
| Brady Worldwide Inc. |
| Lintec Corporation |
| Multi-Color Corporation |
| SmartSolve Industries |
| Others |
Value Network & Pricing Analysis
EU Green Deal packaging deadlines for returnable glass vials are compressing procurement timelines and forcing converters to pre-qualify multiple resin suppliers simultaneously, which fragments volume commitments and prevents the scale discounts that would otherwise soften input cost volatility.
Pricing Analysis
Volume-mid-economy pricing differentiation separates pharmaceutical-grade polyvinyl alcohol labels with USP and EP extractables certification from standard industrial grades and commodity paper-based alternatives. Price differentiation hinges on certification tier and dissolution rate precision, with FDA-validated constructions commanding substantial premiums over uncertified equivalents. Cost compression in the industrial laundry segment is intensifying because REACH restrictions on fluorinated surfactants force adhesive reformulation. Small-format contract packagers exhibit the highest price sensitivity, while multinational pharmaceutical manufacturers prioritize qualification reliability over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from EMA-compliant pharmaceutical packagers mandate that converters qualify resin suppliers in both Japan and Germany, preventing single-source dependence despite the limited global base of dissolvable-grade PVA manufacturers. The supply chain draws from acetic acid and ethylene derivative feedstocks, with coating operations concentrated in the Rhine-Ruhr corridor, China's Yangtze River Delta, and the New Jersey pharmaceutical belt. Single-source vulnerability persists for nanocellulose-reinforced pulp substrates piloted in Nordic food container programs. Distribution runs through technical specialist distributors serving mid-tier converters lacking direct chemical supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated substrate-coating operations as REACH compliance costs and eighteen-month pharmacopeia validation cycles eliminate capital-constrained regional converters.
For Market Incumbents: Hedge against resin cost volatility through captive supply agreements or backward integration into dissolvable-grade PVA production in Germany or Japan. Deepen barrier coating R&D to maintain differentiation as nanocellulose pulp alternatives erode synthetic film premiums in food packaging applications. For New Entrants and Emerging Players: Launch via online retail channels targeting small-volume pilot programs for industrial laundry equipment tracking, the least penetrated application with relaxed certification requirements. Concentrate formulation development on ambient-temperature dissolution profiles to bypass the hot-water logistics dependencies that complicate polyvinyl alcohol distribution in Nordic markets. For Investors and Strategic Acquirers: The window for entry favors mid-tier converters with existing coating line infrastructure and established pharmaceutical customer relationships but lacking capital for REACH-compliant adhesive reformulation. Watch for EMA packaging waste regulation harmonization as the inflection signal that would accelerate mandatory procurement and validate premium pricing for certified constructions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVA Resin Production | Captive supply secures margin protection against acetic acid feedstock volatility from German chemical corridors. |
| REACH-Compliant Adhesive Reformulation | Elimination of fluorinated surfactants opens access to Dutch and German industrial laundry markets under tightened effluent standards. |
| Nanocellulose Pulp Substrate Development | Ambient-temperature disintegration profiles bypass hot-water logistics dependencies in Nordic food container return programs. |
| RFID Inlay Compatibility Integration | Moisture-triggered dissolution convergence enables closed-loop asset tracking without secondary label removal labor in textile rental services. |
| Preferred Supplier Program Consolidation | Annual scorecard bundling with permanent adhesive volumes locks in volume commitments from Yangtze River Delta contract packagers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with label converters, pharmaceutical packaging engineers, industrial laundry operations managers, and adhesive formulation chemists. EMA guidance documents, FDA 21 CFR Part 211 enforcement records, EPA Safer Choice program listings, and ISO dissolution test protocols provided regulatory validation. Bottom-up demand modeling from end-use application volumes was cross-checked against top-down chemical resin production data.
Data-stream reconciliation across material type, application, end user, and distribution channel dimensions ensured segmentation integrity throughout the projection horizon. CAGRs were derived from trend extrapolation of pharmaceutical serialization mandate compliance deadlines and EU Green Deal packaging waste reduction targets. Dissolution rate standardization gaps and pharmacopeia certification timelines were modeled as demand-side constraints on new supplier qualification rates.
Feedstock price volatility, regulatory harmonization delays, and dissolution test protocol divergence are the dominant revision risks to the demand outlook. Deviation in EMA packaging waste regulation enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Shrink Sleeve Labels Market
Labels
Wrap Around Labels Market
Labels
Sheeted Labels Market
Labels
Die Cut Labels Market
Labels
Pin Feed Labels Market
Labels
Europe Self Adhesives Label Market
Labels
Barcode Label Market
Labels
Global Laminated Labels Market
Labels
Glue-Applied Labels Market
Labels
Freezer Label Market
Labels
Global QR Code Labels Market
Labels
Healthcare and Laboratory Labels Market
Labels
Global Security Labels Market
Labels
Global Automotive Labels Market
Labels
Retro-Reflective Labels Market
Labels
Repositionable Labels Market