
 Self-Laminating Tags Market | 2026-2036
Self-Laminating Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Laminating Tags Market Analytics
REACH chemical restrictions is consolidating the cost-of-entry calculus for European suppliers, forcing reformulation investments that favor incumbents with dedicated compliance teams. Brady leverages its laboratory-testing infrastructure to sustain premium positioning across hazardous-environment applications. Avery Dennison anchors North American supply through backward integration into adhesive resin production, insulating margins from petrochemical volatility. 3M competes on optical-grade film technology, extending its patent portfolio into tamper-evident laminate architectures.
Self-laminating tags consist of a printable substrate bonded to a transparent protective film that seals upon pressure application, typically manufactured through coextrusion of polyester or polypropylene layers with acrylic or rubber-based adhesives. These assemblies serve primarily to preserve legibility of barcodes, serial numbers, and safety warnings under chemical exposure, abrasion, and UV degradation in industrial and commercial settings. Plastic and vinyl materials dominate volume production due to their balance of tear resistance and thermal stability, though polyethylene formulations are gaining share in cold-chain logistics where flexibility at sub-zero temperatures proves critical. Identification and inventory management use cases absorb the majority of output, with event access applications representing a faster-growing niche as venues replace disposable wristbands with reusable laminated credentials.
EPA guidelines on volatile organic compound emissions influence adhesive selection for US-manufactured tags, while ECHA's SVHC candidate list drives substitution of phthalate plasticizers in European supply chains. OSHA hazard-communication standards mandate specific label durability thresholds that directly determine laminate thickness and adhesive bond-strength specifications. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments optimized for one geography may not transfer efficiently to markets with divergent chemical-restriction timelines.
Market Dynamics
REACH chemical restrictions are consolidating the cost-of-entry calculus for European suppliers, forcing reformulation investments that favor incumbents with dedicated compliance teams and reshaping competitive positioning across the entire adhesive substrate supply base.
Growth Catalysts
- Asset-tracking mandates:Healthcare facilities in Germany are accelerating procurement of durable identification substrates that withstand sterilization cycles and chemical exposure, exceeding baseline EU traceability standards.
- UV-curable adhesive transition:The shift from solvent-based to UV-curable formulations under REACH compliance is reshaping material specifications and creating preference for suppliers with in-house resin synthesis capabilities.
- Cold-chain logistics expansion:Polyethylene formulations are gaining share where flexibility at sub-zero temperatures proves critical for pharmaceutical and food distribution networks.
Market Restraints
- Petrochemical input volatility:Acrylic and rubber-based adhesive resins expose margins to crude oil derivative pricing swings that compress working capital for non-integrated manufacturers.
- European supply concentration:Germany's industrial corridor dominates high-specification production, creating geographic vulnerability for buyers requiring hazardous-environment certification.
- Phthalate substitution friction:ECHA's SVHC candidate list drives costly reformulation timelines for plasticizer-dependent vinyl substrates, delaying new product qualification.
Strategic Opportunities
- Event credential replacement:Venues are displacing disposable wristbands with reusable laminated credentials, opening a faster-growing niche with higher margin profiles than industrial volume contracts.
- Optical-grade film convergence:Tamper-evident laminate architectures combining polyester coextrusion with holographic security features are unifying identification and anti-counterfeiting functions.
- OSHA durability thresholds:Hazard-communication standards mandating specific label longevity are creating specification lock-in for suppliers meeting minimum bond-strength and thickness requirements.
Industry Challenges
- Regulatory divergence complexity:Compliance investments optimized for EPA VOC guidelines do not transfer efficiently to markets operating under ECHA restriction timelines, fragmenting R&D allocation.
- Coextrusion equipment lead times:Capital-intensive polyester and polypropylene layer bonding systems require 18-24 month procurement cycles, constraining capacity response to demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Laminating Tags Market |
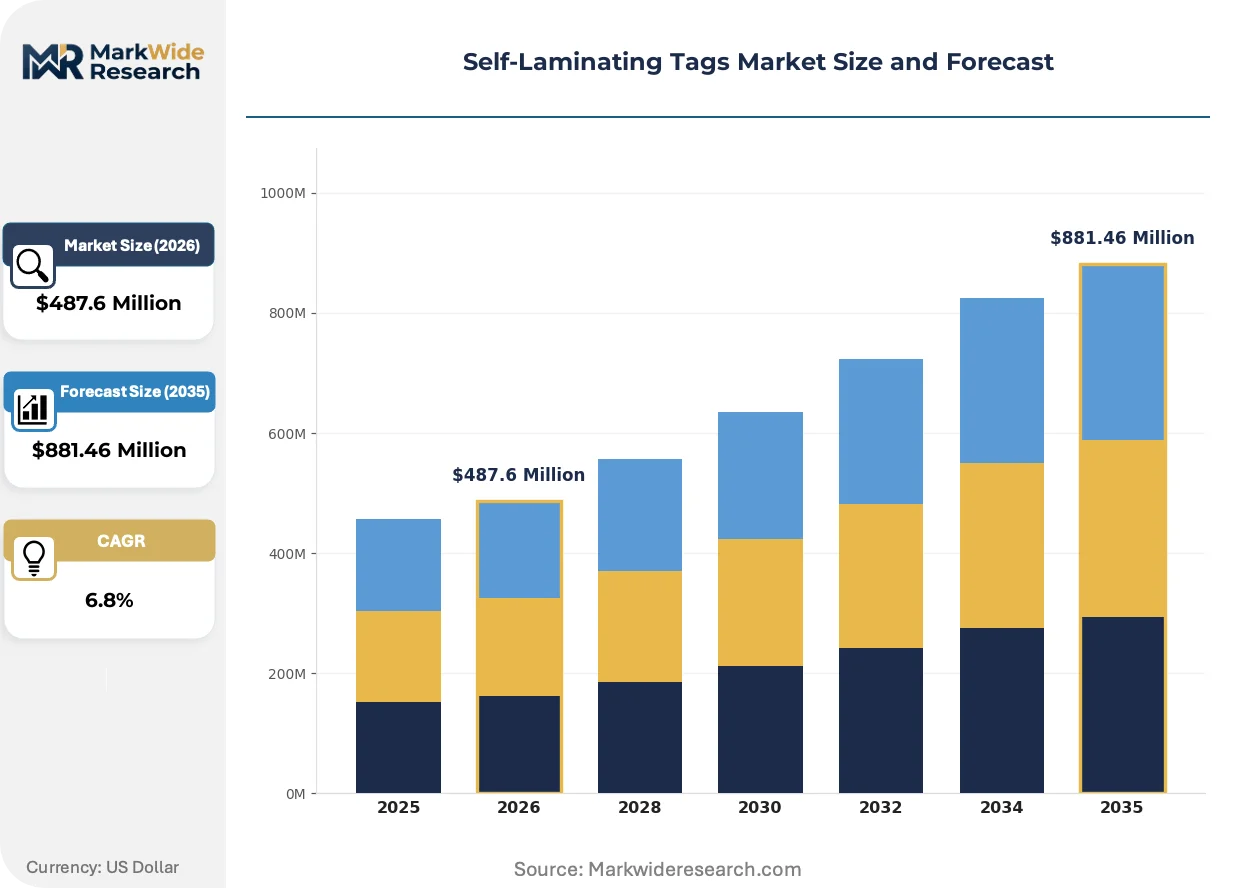
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Stickers, Cards, Badges Use Case: Identification, Inventory Management, Event Access, Personalization Material: Plastic, Vinyl, Paper, Polyethylene Application: Retail, Education, Logistics, Manufacturing |
| Companies Covered | Avery Dennison, Brady, 3M, Stranco, Universal Tag, LEM Products, Badger Tag & Label Corporation, Zebra Technologies, Panduit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Laminating Tags Market Evolving Landscape
Active reshaping in this market centers on adhesive chemistry reformulation, regulatory compliance architecture, and buyer procurement consolidation. Three distinct movements are compressing traditional supplier margins while opening premium positioning for compliant incumbents.
Digital printing integration with self-laminating substrates is unifying variable-data serialization with on-demand protective film application. Pharmaceutical manufacturers and medical device producers are adopting this hybrid workflow to eliminate pre-printed inventory obsolescence. The technology is compressing minimum order quantities and enabling lot-specific compliance marking without plate-changeover delays.
REACH authorization requirements for diisocyanates in polyurethane adhesives are forcing reformulation toward epoxy-acrylic hybrid chemistries. Industrial label converters in the European Union face 12-18 month requalification cycles for bonded polyester assemblies. Cold-chain logistics operators are most affected, as sub-zero flexibility specifications limit viable adhesive substitutions.
Consolidated procurement by healthcare systems is displacing fragmented distributor purchasing with direct manufacturer contracts tied to multi-year compliance guarantees. Integrated delivery networks in the United States are negotiating laminate durability warranties extending across entire facility footprints. This concentration is most visible in Germany's hospital consortiums, where standardization mandates favor single-source identification substrate suppliers.
Self-Laminating Tags Market Segmentation
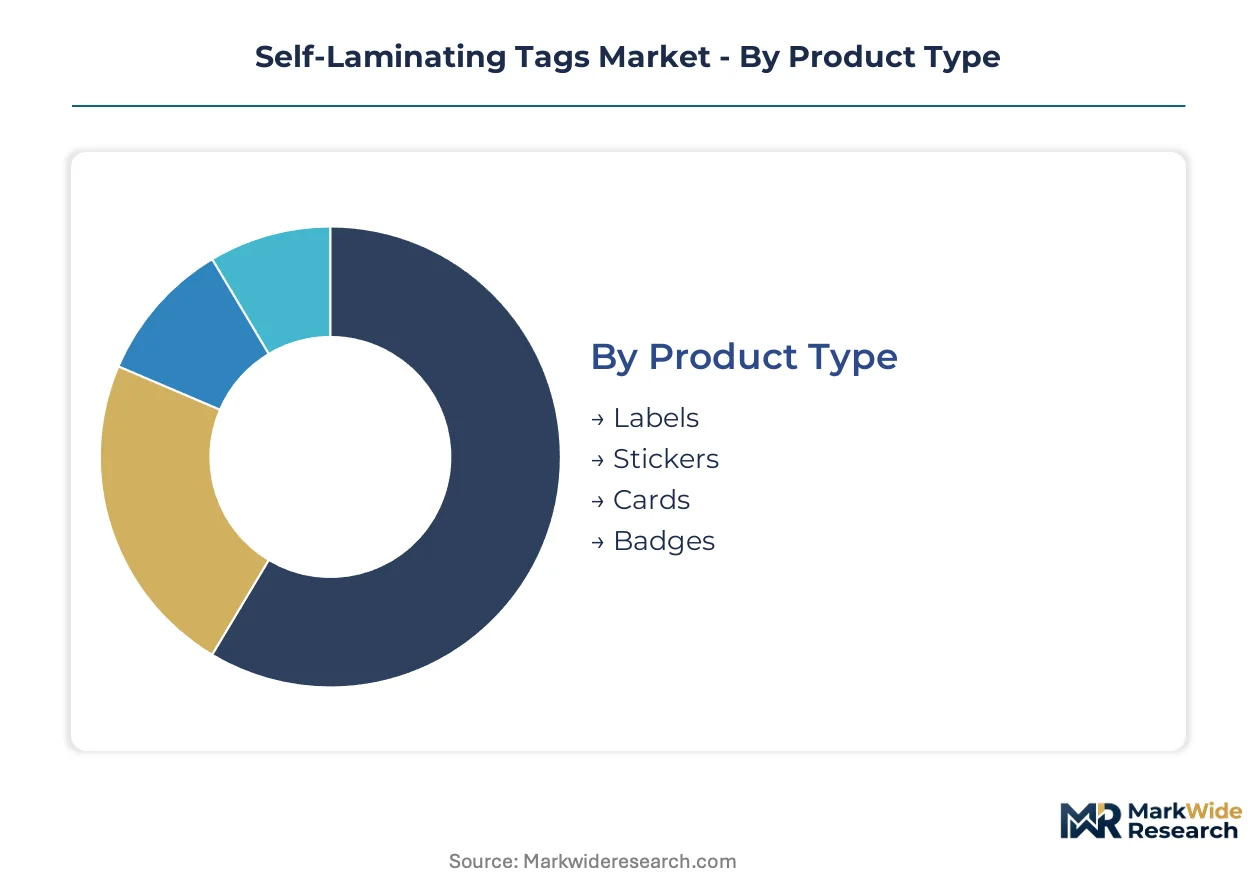
Segmentation in self-laminating tags reveals how capital deployment, regulatory exposure, and end-use durability requirements fragment supplier specialization. Buyers optimize procurement across material chemistry, application environment, and credential reusability rather than treating tags as interchangeable commodities.
Product Type:
Capital intensity concentrates in coextrusion lines for multi-layer polyester assemblies, while simpler die-cut formats require minimal fixed-asset commitment.
- Labels:Continuous-roll formats with pressure-activated laminating films dominate industrial asset-tracking. German manufacturing clusters specify solvent-resistant acrylic adhesives that withstand chemical washdown protocols.
- Stickers:Individual-cut units with pre-scored release liners serve short-run personalization workflows. Print-on-demand adoption in US healthcare systems is displacing pre-printed inventory models.
- Cards:Rigid PVC or composite substrates with thermal-transfer receptive coatings absorb the bulk of installed capacity; badges are expanding most quickly.
- Badges:Reusable credential formats with slot-punched laminating pouches serve event venues and corporate visitor management.
Labels absorb the bulk of installed capacity; badges are expanding most quickly.
Use Case:
Margin structure diverges sharply between compliance-mandated durability specifications and discretionary aesthetic customization.
- Identification:Personnel and asset verification tags with barcode or RFID integration require ISO-grade print permanence. OSHA hazard-communication thresholds directly determine laminate thickness specifications in US industrial facilities.
- Inventory Management:Cycle-count labels with sequential serialization face abrasion exposure in warehouse environments. Cold-chain operators specify polyethylene flexibility at sub-zero temperatures.
- Event Access:Single-day or multi-day credentials with holographic security features command premium positioning over disposable wristbands.
- Personalization:On-demand photo ID and custom graphics production serves education and corporate markets with shorter run lengths.
Identification commands the largest revenue pool; event access climbs the fastest.
Material:
Raw material chemistry determines regulatory compliance pathways and thermal performance boundaries.
- Plastic:Polyester and polypropylene coextrusions balance tear resistance with thermal stability for industrial labeling. REACH diisocyanate restrictions are forcing reformulation toward epoxy-acrylic hybrids.
- Vinyl:Flexible PVC formulations with phthalate plasticizers face ECHA SVHC substitution pressure. Reformulation timelines delay new product qualification by 12-18 months.
- Paper:Synthetic paper with in-mold labeling compatibility serves cost-sensitive retail applications.
- Polyethylene:Low-density formulations maintain pliability in pharmaceutical cold-chain distribution.
Plastic commands the dominant volume position; polyethylene gains share fastest.
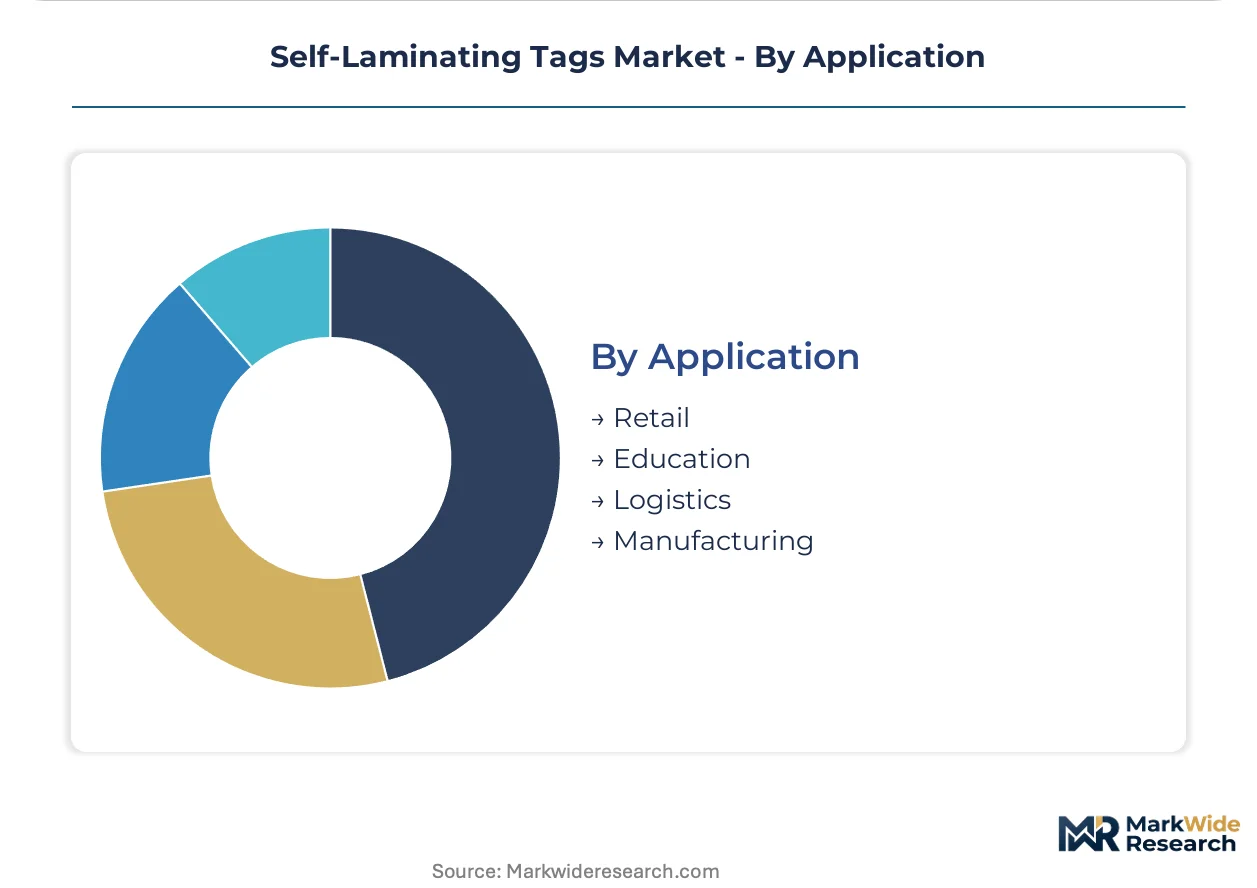
Application:
End-use environment dictates adhesive specification, print technology compatibility, and replacement frequency.
- Retail:Price-point and promotional labels face moderate abrasion with indoor exposure. Digital printing integration enables store-level customization without plate inventory.
- Education:Student ID and library asset tags prioritize cost efficiency over extended durability. Procurement concentrates in district-level consolidated contracts.
- Logistics:Shipping labels and tote identification withstand mechanical sorting and environmental exposure. UV-curable adhesives are displacing solvent-based formulations under EPA VOC guidelines.
- Manufacturing:Work-in-process tracking and safety-warning labels face chemical and thermal stress. Germany's factory-floor traceability requirements exceed baseline EU standards.
Manufacturing absorbs the bulk of specification-grade capacity; logistics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones are concentrating coextrusion capacity for export-grade laminating substrates, drawing resin suppliers and adhesive formulators into clustered industrial parks with preferential tax treatment.
United States
Healthcare system procurement consolidation drives direct manufacturer contracts for durable identification substrates. EPA VOC guidelines under the Clean Air Act are accelerating UV-curable adhesive adoption across Midwestern label converters. Chicago's industrial corridor hosts specialized fabricators serving OSHA-mandated hazard-communication labeling for manufacturing facilities.
Germany
Factory-floor traceability requirements exceed baseline EU standards, mandating sterilization-resistant tags for medical device production. REACH diisocyanate restrictions are forcing 12-18 month reformulation cycles for polyurethane adhesive suppliers. Bavaria's medical technology cluster anchors high-specification laminate demand from Siemens Healthineers and regional hospital consortiums.
China
Pharmaceutical cold-chain expansion is absorbing polyethylene-flexible laminates for sub-zero distribution networks. GB standards for food-contact materials are tightening plasticizer migration limits in vinyl formulations. Shenzhen's electronics manufacturing hub generates volume demand for barcode-preserving labels in high-humidity assembly environments.
Japan
Automotive just-in-time tracking systems require thermal-transfer receptive laminates with extended outdoor durability. METI carbon-neutrality roadmaps are pressuring solvent-based adhesive phaseouts by 2030. Nagoya's automotive supplier belt concentrates specification-grade tag procurement from Toyota and tier-one component manufacturers.
India
Pharmaceutical serialization mandates under the Drugs and Cosmetics Act are expanding tamper-evident laminate demand for export packaging. BIS certification requirements for adhesive-backed identification products are lengthening import qualification timelines. Gujarat's pharmaceutical manufacturing zone anchors domestic laminate converter capacity serving Sun Pharma and regional exporters.
Self-Laminating Tags Market Competitive Landscape
German producers anchor the premium-compliance tier; North American specialists hold volume-scale positions in healthcare and industrial verticals. The supplier base exhibits moderate concentration, with three to five integrated manufacturers commanding specification-grade segments while regional converters fragment the commoditized die-cut category. Strategic archetypes separate into resin-integrated formulators, digital-printing workflow enablers, and event-credential niche specialists. Capacity expansion and REACH-driven reformulation partnerships constitute the dominant competitive moves reshaping supplier relationships.
Within the integrated-formulator tier, Avery Dennison and 3M exemplify divergent specialization paths. Avery Dennison occupies a position emphasizing adhesive resin backward integration and North American supply security. 3M represents optical-grade film technology extension into security-feature laminates. Brady sits within the hazardous-environment certification specialist archetype, leveraging laboratory-testing infrastructure for premium positioning in industrial safety applications.
| Leading Market Players |
|---|
| Avery Dennison |
| Brady |
| 3M |
| Stranco |
| Universal Tag |
| LEM Products |
| Badger Tag & Label Corporation |
| Zebra Technologies |
| Panduit |
| Others |
Value Network & Pricing Analysis
Petrochemical resin indices cascade through self-laminating tag supply chains into three-tier pricing structures across premium, standard, and economy levels. Acrylic and polyester feedstock volatility compresses margins for non-integrated converters while rewarding suppliers with captive adhesive production.
Pricing Analysis
Lead-time premiums of 40-60% apply to spot orders requiring sub-30-day turnaround, while contract volumes command 15-25% discounts against list pricing. Certification-grade laminates for OSHA hazard-communication applications sustain the highest price realization, with standard industrial labels facing the steepest buyer price sensitivity among procurement managers at consolidated healthcare systems. Cost compression in economy-tier die-cut formats is intensifying because Asian import competition erodes domestic spot-market pricing.
Supply Chain Analysis
REACH and OSHA qualification gating restricts supply base participation to converters with documented requalification protocols, effectively segmenting the market between certified and uncertified producers. Coextrusion capacity concentrates in Germany, China, and the United States, with raw material dependencies on Saudi and Korean petrochemical feedstocks and Japanese optical-grade polyester films. Single-source vulnerability in specialized UV-curable adhesive resin supply creates concentration risk for European converters. Distribution runs through industrial distribution networks and direct manufacturer contracts to healthcare systems and automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The self-laminating tags market functions as a cost-of-compliance arena where REACH authorization requirements for diisocyanates erect barrier-to-entry moats favoring incumbents with dedicated regulatory affairs infrastructure.
For Market Incumbents: Cement laboratory-testing infrastructure investments to sustain premium positioning in hazardous-environment certification segments. Deepen backward integration into UV-curable adhesive resin production to insulate margins from petrochemical volatility threatening non-integrated competitors. Defend against digital-printing workflow disruptors by bundling on-demand serialization capabilities with laminate durability warranties.
For New Entrants and Emerging Players: EPA VOC guidelines in the United States open a window for solvent-free adhesive specialists to capture share among Midwestern label converters facing compliance-driven supplier switching. Target event-credential replacement demand as the most penetrable white-space segment, displacing disposable wristbands with reusable laminated badges at sports venues and corporate campuses. Pursue direct-to-venue sales models bypassing traditional industrial distribution markups.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converters with established ECHA pre-registration dossiers and stranded coextrusion assets in Germany's industrial corridor. Long-term viability hinges on regulatory compliance architecture rather than commodity scale. Watch cold-chain logistics certification adoption as the inflection signal indicating polyethylene-flexible laminate demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Resin | Captive UV-curable production insulates margins from petrochemical volatility affecting European converters. |
| Digital Printing Workflow Partnership | On-demand serialization bundling captures pharmaceutical lot-marking demand from pre-printed inventory models. |
| REACH Reformulation Certification | Diisocyanate authorization compliance locks out non-registered competitors from EU medical device supply chains. |
| Event Credential Direct Sales Channel | Venue bypass models capture 25-35 point margin improvement over industrial distributor networks. |
| Cold-Chain Logistics Specification Development | Sub-zero flexibility testing protocols create polyethylene laminate preference among pharmaceutical distributors. |
Research Methodology
Document review covered customs trade data, SEC 10-K filings, and ECHA registration dossiers, complemented by interviews with adhesive R&D directors, industrial label procurement managers, and healthcare system GPO contract specialists. Primary fieldwork with coextrusion equipment operators and regulatory affairs consultants validated secondary findings on REACH reformulation timelines. Bottom-up capacity modeling triangulated against top-down end-use demand estimates across manufacturing, logistics, and healthcare verticals.
Segmented volume and value estimates emerged from material-grade, application-environment, and geographic-regulatory clustering across the projection horizon. The analytical framework modeled polyester, vinyl, and polyethylene substrate demand separately, with adhesive chemistry transitions tracked against EPA VOC and ECHA SVHC restriction timelines. CAGRs derived from installed capacity expansion rates, substitution elasticity between solvent and UV-curable formulations, and healthcare procurement consolidation patterns.
The model assumes gradual UV-curable adhesive adoption; alternative pathways involving rapid solvent-phaseout mandates would accelerate incumbent margin compression. Forecasts reflect assumptions on coextrusion equipment lead times, regulatory divergence persistence, and petrochemical input cost trajectories. A model refresh is warranted upon material change in REACH authorization timelines or OSHA hazard-communication durability threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
India Print Label Market
Labels
Global Laminated Labels Market
Labels
Wrap Around Labels Market
Labels
BOPP Labels Market
Labels
Future-Proof Pharma Labels Market
Labels
Shipping Label Market
Labels
Domed Labels Market
Labels
Print Label Market
Labels
Laser Markable Labels Market
Labels
Global Label Adhesive Market
Labels
Canning Labels Market
Labels
Inspection and Inventory Labels Market
Labels
Freezer Label Market
Labels
Self-Laminating Labels Market
Labels
Barcode Label Printer Market
Labels
Sustainable Labels Market