
 Linerless Labels Market | 2026-2036
Linerless Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Linerless Labels Market Intelligence
Silicone-coated release liner is shifting toward direct thermal and thermal transfer substrates that eliminate liner waste entirely. Avery Dennison Corporation leverages its adhesive chemistry portfolio to anchor high-volume supply agreements with European grocery retailers. UPM Raflatac specializes in sustainable paper-based linerless constructions that compete on carbon footprint metrics against conventional label formats. 3M Company controls proprietary hot-melt adhesive platforms that sustain performance across variable temperature logistics environments.
Linerless labels are pressure-sensitive adhesive constructions manufactured without a release liner backing, typically incorporating a silicone release coating on the face stock itself or utilizing specialized adhesives that release from adjacent label layers in roll format; they require minimum caliper tolerances of 50-80 microns to prevent adhesive bleed-through during high-speed dispensing. Direct thermal and thermal transfer product types dominate current volume due to their compatibility with existing printer infrastructure across logistics tracking and food packaging applications. Inkjet-compatible linerless substrates represent the fastest-growing segment as pharmaceutical packaging operations demand variable data printing with reduced material handling.
FDA food contact substance regulations govern adhesive migration limits in U.S. food packaging applications, while ECHA REACH compliance constrains silicone chemistry formulations across European manufacturing. The EU Packaging and Packaging Waste Regulation creates binding recyclability targets that favor liner elimination across Fast Moving Consumer Goods supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks and adhesive innovation cycles to determine capital allocation between linerless substrate platforms and legacy label formats.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is mandating recyclability improvements that favor adhesive technologies eliminating liner substrates, forcing converters to reconfigure coating lines and supply agreements around silicone-free constructions.
Growth Catalysts
- REACH compliance constraints:ECHA restrictions on silicone chemistry formulations are accelerating migration toward linerless alternatives in European manufacturing.
- Food packaging waste reduction:German and French retail supply chains are adopting linerless formats to eliminate release liner disposal costs and meet sustainability scorecard requirements.
- Variable temperature logistics:Hot-melt adhesive platforms that sustain performance across cold chain and ambient distribution are expanding addressable applications.
Market Restraints
- Silicone price volatility:Fluctuations in silicone feedstock costs create margin compression for manufacturers transitioning between conventional and linerless coating chemistries.
- Equipment retrofit requirements:Minimum caliper tolerances of 50-80 microns demand precision dispensing machinery that many mid-scale converters lack.
- Direct thermal substitution limits:Image fade susceptibility in direct thermal linerless formats restricts adoption in archival pharmaceutical labeling applications.
Strategic Opportunities
- Pharmaceutical serialization mandates:Inkjet-compatible linerless substrates for variable data printing represent underpenetrated demand in track-and-trace compliance packaging.
- Extended producer responsibility frameworks:Emerging EPR schemes in France and Italy create preferential procurement status for liner-eliminating formats.
- Adhesive-face stock convergence:Integration of silicone release coatings directly onto face stock materials is collapsing traditional multi-layer supply chains.
Industry Challenges
- High-speed dispensing calibration:Preventing adhesive bleed-through during roll-to-roll processing requires specialized technician expertise that converters struggle to source.
- FDA food contact migration testing:Extended certification timelines for adhesive formulations in U.S. food packaging applications delay product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linerless Labels Market |
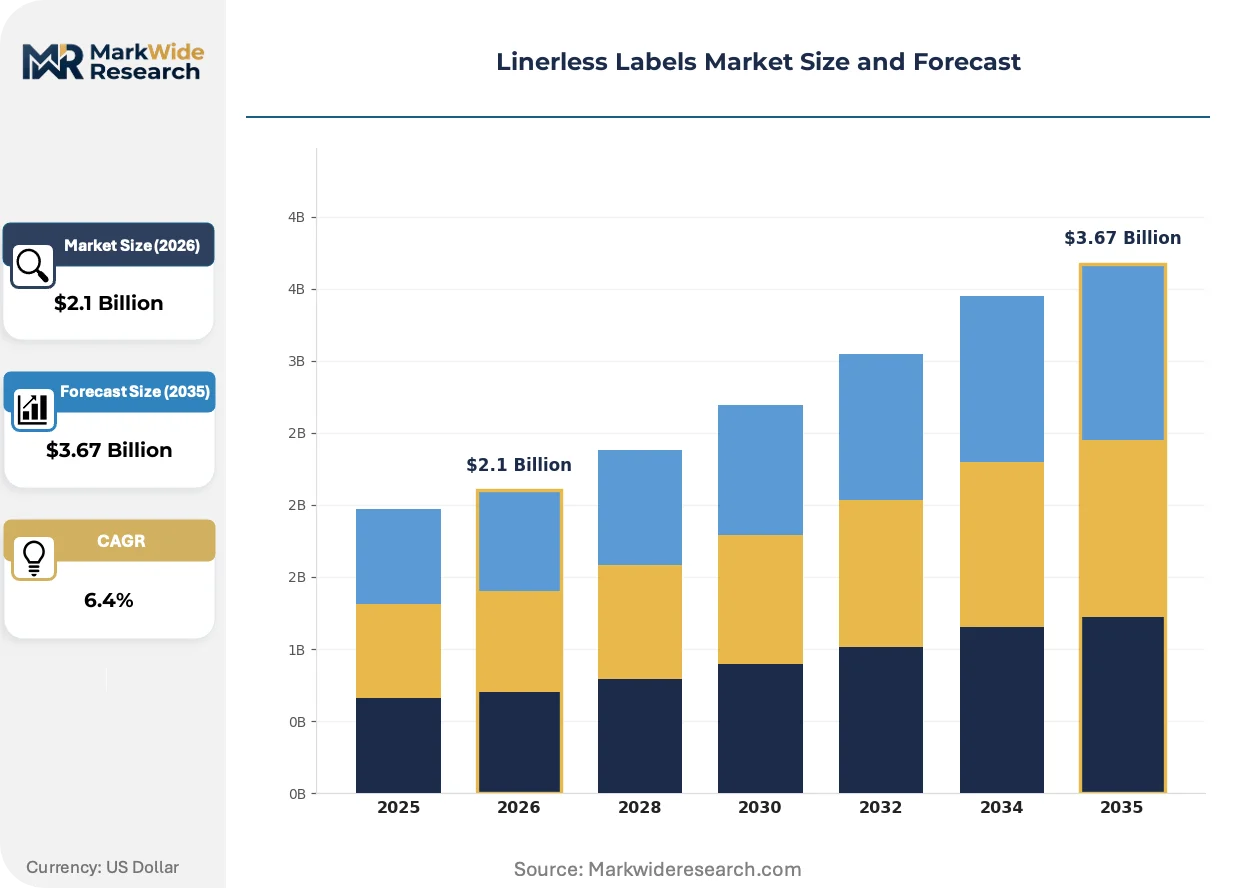
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Thermal, Thermal Transfer, Inkjet, Laser, Flexographic Application: Food Packaging, Pharmaceutical Packaging, Logistics Tracking, Personal Care, Electronics Inventory End User Industry: Fast Moving Consumer Goods, Healthcare Providers, Transportation & Warehousing, Consumer Electronics, Cosmetics Manufacturing Distribution Channel: Online Retailers, Authorized Distributors, Direct Sales, Wholesale Suppliers, Third-party Marketplaces |
| Companies Covered | Avery Dennison Corporation, UPM Raflatac, 3M Company, CCL Industries Ltd., R.R. Donnelley & Sons Company, Hub Labels, Skanem AS, Coveris, Reflex Labels Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linerless Labels Market Strategic Shifts & Innovations
Silicone-coated release liner elimination is reshaping substrate engineering priorities, with adhesive chemistry and face stock construction converging into single-material solutions that reduce handling complexity and waste streams.
Direct thermal and thermal transfer substrates are consolidating market position in logistics tracking and food packaging applications. Major European grocery retailers are specifying these formats in supply agreements to meet waste reduction targets. The technology is consolidating printer infrastructure requirements, compressing demand for legacy label formats that require separate liner disposal.
REACH compliance is constraining silicone chemistry formulations across European manufacturing, favoring alternative release mechanisms in linerless constructions. Industrial consequence includes accelerated R&D investment in hot-melt and UV-curable adhesive platforms. Pharmaceutical packaging operations in Germany and France are responding fastest, driven by dual pressure from ECHA restrictions and EU Packaging and Packaging Waste Regulation recyclability targets.
Buyer concentration in Western European retail supply chains is compressing supplier qualification cycles. Sustainability scorecards now govern supplier selection, displacing price-only procurement models. Food packaging operations across Germany, France, and Italy exhibit the most visible shift, with private-label manufacturers facing mandatory linerless adoption thresholds to retain shelf-space agreements.
Linerless Labels Market Segmentation
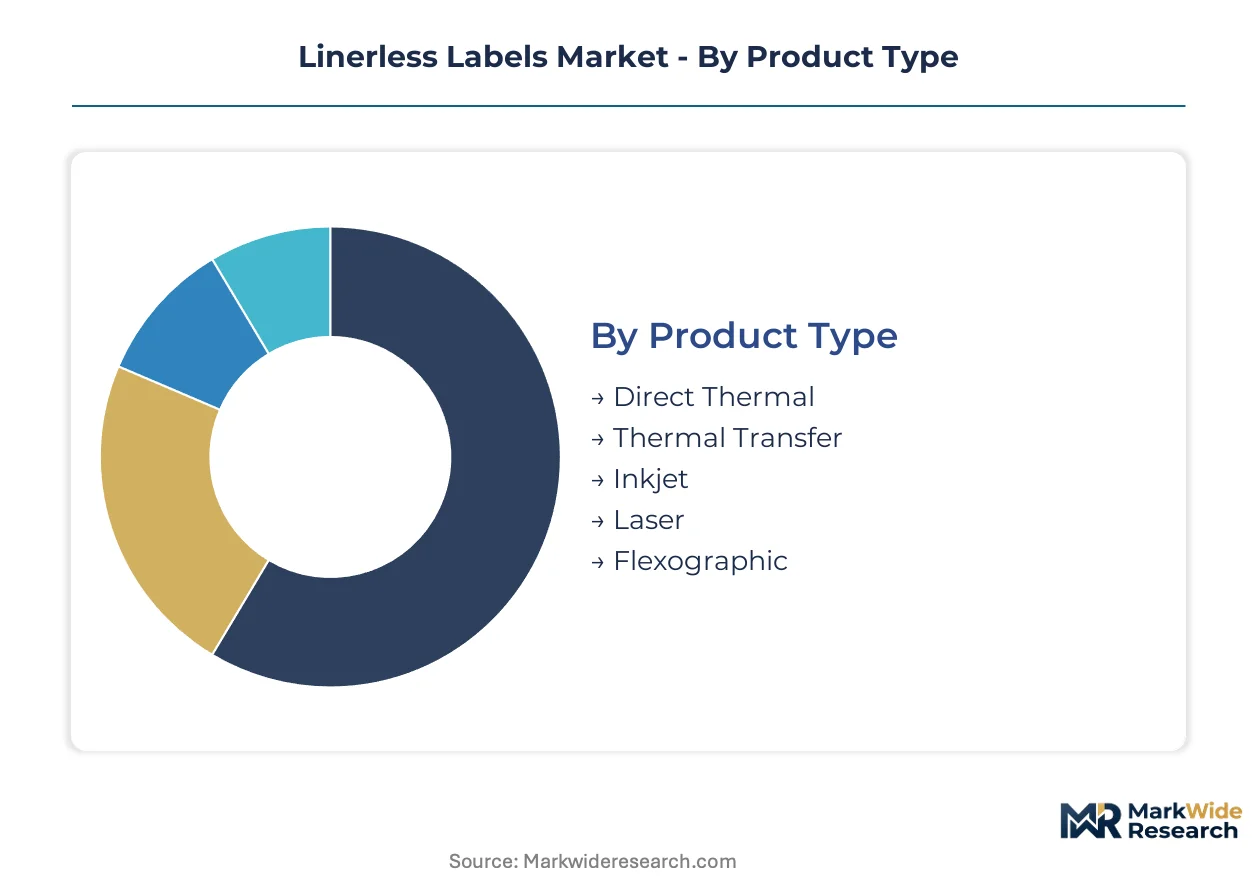
Linerless label manufacturers configure production assets around print technology compatibility and adhesive performance specifications. Each segment carries distinct equipment requirements, regulatory burdens, and margin profiles that shape converter investment priorities.
Product Type:
Supply concentration clusters around thermal imaging technologies where printer infrastructure lock-in creates switching costs for end-users.
- Direct Thermal:Heat-sensitive coatings activate without ribbon, reducing consumable complexity in logistics tracking and short-life food packaging. German and French retail supply chains specify this format to meet EU Packaging and Packaging Waste Regulation waste reduction targets.
- Thermal Transfer:Wax-resin or resin ribbons transfer ink onto synthetic or paper face stocks, delivering archival durability for pharmaceutical serialization mandates. Healthcare providers in Germany favor this technology for cold chain compliance labeling.
- Inkjet:Porous coatings accept water-based or UV-curable inks for variable data printing at pharmaceutical packaging lines.
- Laser:Toner-receptive substrates withstand high-temperature fusing processes in electronics inventory applications.
- Flexographic:Pre-printed linerless constructions serve high-volume food packaging contracts with static graphics requirements.
Today's leader: Direct Thermal. Tomorrow's challenger: Inkjet.
Application:
Application demand fragments across regulatory intensity tiers, with food and pharmaceutical packaging commanding premium qualification cycles.
- Food Packaging:FDA food contact substance regulations and EFSA compliance govern adhesive migration limits in direct contact applications. Private-label manufacturers across Germany and France face mandatory linerless adoption thresholds to retain retail shelf-space agreements under sustainability scorecard governance.
- Pharmaceutical Packaging:Track-and-trace serialization mandates in Germany and France drive inkjet-compatible substrate demand for variable data printing. ECHA REACH compliance constraints on silicone chemistry accelerate migration toward linerless alternatives in European manufacturing.
- Logistics Tracking:High-speed dispensing environments favor direct thermal formats with minimum caliper tolerances of 50-80 microns to prevent adhesive bleed-through.
- Personal Care:Moisture-resistant adhesives withstand humidity exposure in bathroom and vanity product labeling.
- Electronics Inventory:Static-dissipative coatings prevent damage to sensitive components during warehouse handling.
Food Packaging commands current volume. Pharmaceutical Packaging climbs the fastest as serialization mandates expand.
End User Industry:
Customer concentration in Fast Moving Consumer Goods creates procurement leverage that compresses supplier margins.
- Fast Moving Consumer Goods:Sustainability scorecards now govern supplier selection, displacing price-only procurement models. Retail supply chains across Germany, France, and Italy exhibit the most visible shift toward linerless adoption.
- Healthcare Providers:Cold chain logistics requirements favor hot-melt adhesive platforms that sustain performance across variable temperature distribution environments.
- Transportation & Warehousing:High-throughput distribution centers specify direct thermal formats compatible with existing printer infrastructure.
- Consumer Electronics:ESD-sensitive applications require specialized face stock constructions.
- Cosmetics Manufacturing:Aesthetic presentation standards drive demand for premium finish substrates.
Fast Moving Consumer Goods anchors demand today. Healthcare Providers represent the steepest expansion trajectory.
Distribution Channel:
Channel structure reflects converter scale and technical service requirements, with direct relationships dominating complex specification accounts.
- Authorized Distributors:Technical inventory and local service support mid-scale converters lacking in-house adhesive expertise. European coating line reconfiguration demand concentrates orders through distributors with silicone-free construction portfolios.
- Direct Sales:High-volume grocery retailers and pharmaceutical packaging operations negotiate supply agreements directly with adhesive chemistry specialists for customized release coating formulations.
- Online Retailers:Standardized product configurations serve small-format printer users and maintenance-repair-operations procurement.
- Wholesale Suppliers:Bulk substrate volumes feed converter secondary processing operations.
- Third-party Marketplaces:Spot purchasing for emergency replenishment and specification testing samples.
Authorized Distributors dominate transaction volume. Direct Sales gains share fastest as sustainability scorecards consolidate supplier bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retail supply chains anchor the linerless labels demand trajectory, with sustainability scorecards now mandating liner elimination across Fast Moving Consumer Goods packaging operations throughout the country.
Germany
Private-label manufacturers in Bavaria and North Rhine-Westphalia face mandatory linerless adoption thresholds to retain supermarket shelf-space agreements under retailer sustainability governance. ECHA REACH compliance constraints on silicone chemistry formulations are accelerating migration toward linerless alternatives in coating operations. The Frankfurt-Rhine-Main logistics corridor is reconfiguring distribution center labeling infrastructure around direct thermal formats compatible with high-speed dispensing requirements.
France
Paris-based grocery retailers are specifying linerless label formats in supply contracts to meet EU Packaging and Packaging Waste Regulation waste reduction targets. ANSM pharmaceutical packaging standards are driving inkjet-compatible substrate demand for serialization compliance in track-and-trace applications. The Lyon-Grenoble industrial cluster is concentrating adhesive chemistry R&D investment as EPR frameworks create preferential procurement status for liner-eliminating formats.
Italy
Lombardy-based food packaging converters are retrofitting coating lines to handle silicone-free constructions as extended producer responsibility schemes consolidate supplier selection criteria. EFSA compliance requirements govern adhesive migration limits in direct contact food applications. The Emilia-Romagna packaging belt is witnessing accelerated qualification cycles as sustainability scorecards displace price-only procurement models among mid-scale manufacturers.
United Kingdom
London-headquartered retail chains are importing linerless specification standards from continental European supply agreements, pressuring domestic converters to reconfigure production assets. UK REACH alignment with ECHA restrictions is constraining silicone chemistry formulations across coating operations. The Midlands manufacturing corridor is experiencing equipment retrofit demand as precision dispensing machinery requirements exclude legacy converter capabilities.
United States
FDA food contact substance regulations are extending certification timelines for adhesive formulations in food packaging applications, delaying commercialization for European exporters. California's extended producer responsibility frameworks are creating template legislation for other states considering liner-elimination mandates. The Chicago-Milwaukee logistics hub is piloting direct thermal linerless formats in high-throughput distribution centers to reduce release liner disposal costs.
Linerless Labels Market Key Industry Players
Strategic partnerships dominate the current landscape as adhesive chemistry specialists align with coating equipment manufacturers to accelerate converter transition timelines. The vendor base fragments across three tiers: multinational materials conglomerates with integrated adhesive-face stock portfolios, regional coating specialists serving single-country supply chains, and equipment-integrated solution providers bundling substrate and dispensing technology. Two strategic archetypes are consolidating share: chemistry-forward players leveraging proprietary hot-melt and UV-curable platforms, and sustainability-focused specialists competing on carbon footprint metrics. Portfolio diversification and geographic expansion represent the dominant competitive moves as participants build silicone-free construction capabilities across multiple regulatory jurisdictions.
Among North American materials conglomerates, Avery Dennison Corporation and 3M Company exemplify the chemistry-forward archetype through their adhesive technology heritage and integrated supply chain positioning. UPM Raflatac represents the sustainability-specialist vector within the European tier, anchoring paper-based linerless construction development. These three entities occupy positions that reflect the market's bifurcation between scale-driven adhesive chemistry control and carbon-footprint-differentiated substrate engineering.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| UPM Raflatac |
| 3M Company |
| CCL Industries Ltd. |
| R.R. Donnelley & Sons Company |
| Hub Labels |
| Skanem AS |
| Coveris |
| Reflex Labels Ltd. |
| Others |
Cost & Logistics Intelligence
Specialized adhesive chemists concentrated in Germany's Rhine-Ruhr industrial basin command wage premiums that compress pricing spreads between premium and standard linerless label tiers. Labor-cost differentials between German coating operations and Eastern European converter facilities create arbitrage opportunities that reshape procurement geography across EU supply chains.
Pricing Analysis
Silicone feedstock volatility passes through to finished substrate pricing on quarterly contract resets, compressing margins for converters lacking long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels differentiates by adhesive performance certification and volume commitment scale. Pricing pressure stems from REACH compliance-driven formulation changes that elevate R&D amortization costs. Mid-scale food packaging converters exhibit highest price sensitivity due to sustainability scorecard procurement mandates, while pharmaceutical serialization specialists accept premium tiers for FDA-compliant adhesive platforms.
Supply Chain Analysis
EU Packaging and Packaging Waste Regulation domestic-content preferences are redirecting sourcing toward German, French, and Italian coating operations with verified silicone-free construction capabilities. Supply chains draw from Finnish pulp feedstocks, German specialty chemical intermediates, and Austrian precision dispensing equipment. Single-source vulnerability concentrates in hot-melt adhesive polymer supply from Benelux petrochemical complexes. Distribution runs through authorized technical distributors serving converter retrofit demand, with direct sales channels gaining share among high-volume grocery retailers consolidating supplier bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
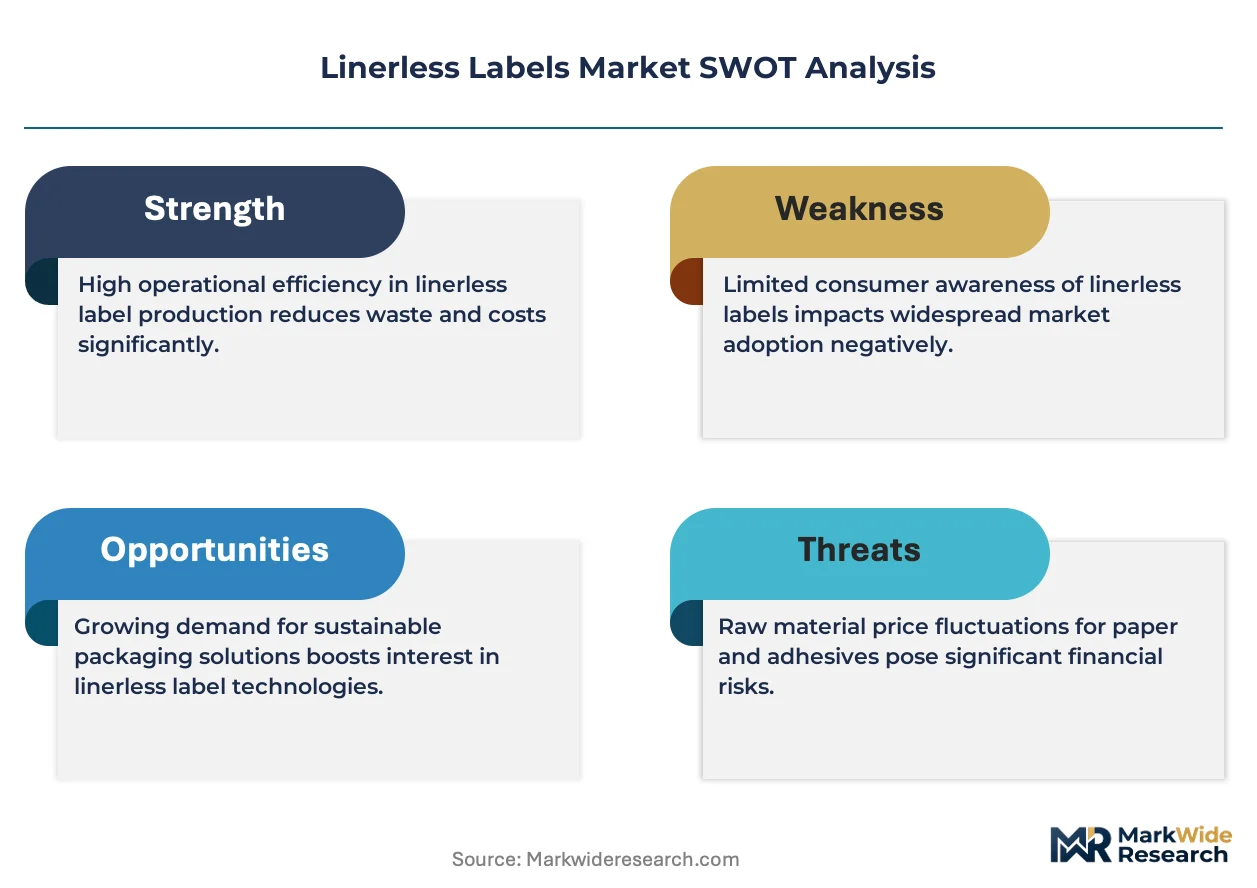
The linerless labels market functions as a geographic-arbitrage play where ECHA REACH compliance costs in Germany and France exceed Eastern European regulatory burdens, creating margin expansion opportunities for converters with multi-jurisdictional production footprints.
For Market Incumbents: Hedge silicone chemistry exposure by accelerating captive production of UV-curable adhesive platforms in lower-cost Polish and Czech manufacturing zones. Consolidate coating equipment partnerships to lock in precision dispensing machinery allocation ahead of mid-scale converter retrofit demand surges. Defensive priority centers on backward integration into release coating formulation to preserve margin structure against commodity substrate traders. For New Entrants and Emerging Players: E-commerce-enabled technical distributor channels offer lowest-friction market entry for inkjet-compatible substrate portfolios targeting underpenetrated pharmaceutical packaging operations in Italy and Spain. White-space concentration sits in variable-data serialization applications where ANSM and BfArM track-and-trace mandates are expanding fastest. Go-to-market leverage rests on sustainability certification bundling that satisfies retailer scorecard requirements without incumbent legacy coating line overhead. For Investors and Strategic Acquirers: Adhesive chemistry specialists with proprietary hot-melt platforms are the most active acquirer category in this space, consolidating regional coating specialists to secure silicone-free construction IP. Five-to-ten-year viability hinges on extended producer responsibility framework proliferation across EU member states. Acquisition target archetype: mid-scale Italian or French converters with validated EFSA-compliant food contact adhesive portfolios and established retail supply chain relationships. Watch for BfArM serialization deadline accelerations as inflection signal for inkjet substrate demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Chemistry | Captive hot-melt formulation control insulates margins from silicone feedstock volatility. |
| Coating Line Retrofit Partnerships | Equipment-integrated solution bundling locks in converter switching costs across German supply chains. |
| Inkjet-Compatible Substrate Development | Variable-data printing demand from ANSM pharmaceutical mandates opens premium pricing tiers. |
| Extended Producer Responsibility Certification | Verified liner-elimination credentials satisfy French and Italian retailer sustainability scorecards. |
| Multi-Jurisdictional Production Footprint | Polish and Czech manufacturing assets arbitrage REACH compliance cost differentials against German operations. |
Research Approach
Multiple input streams — converter production data, adhesive chemistry patent filings, and retailer procurement contract terms — were reconciled through structured primary interviews with coating line engineers, sustainability procurement leads at German grocery retailers, ECHA regulatory affairs specialists, and pharmaceutical packaging operations managers. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation timelines, ECHA REACH restriction dossiers, and SEC filings of listed materials conglomerates. Bottom-up volume estimates from converter capacity utilization were triangulated against top-down demand projections from end-use industry consumption patterns.
Historical volume trajectories were cross-referenced against expert panel assessments of silicone substitution rates and equipment retrofit timelines across the analysis window. Segmentation modeling incorporated print technology compatibility, adhesive performance specifications, application regulatory intensity, and end-user industry procurement concentration. CAGRs were derived from slope-consistency checks against macroeconomic indicators and industry-specific demand drivers including pharmaceutical serialization mandate schedules and extended producer responsibility framework adoption curves.
The model assumes a particular technology adoption path; alternative pathways for UV-curable adhesive platforms would alter the outlook if hot-melt formulations achieve unexpected REACH compliance extensions. Forecasts reflect assumptions regarding EPR framework harmonization and retailer sustainability scorecard enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Fiber Optic Labels Market
Labels
Shipping Label Market
Labels
Heat Shrink Sleeve Market
Labels
HAZMAT Labels Market
Labels
GHS Labels Market
Labels
Label Applicator Market
Labels
Future-Proof Pharma Labels Market
Labels
Self-Laminating Tags Market
Labels
Sheeted Labels Market
Labels
Foil Labels Market
Labels
Booklet Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Braille Labels Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Freezer Label Market
Labels
Canning Labels Market