
 Hang Tags Market | 2026-2036
Hang Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Hang Tags Market Outlook
FSC chain-of-custody certification is collapsing as a gatekeeping standard for premium hang tag supply, squeezing uncertified converters out of European and North American retail procurement. Avery Dennison leverages its integrated RFID inlay capabilities to dominate intelligent tagging programs for mass fashion retailers. CCL Industries sustains margin density through specialty substrate formulations and security feature integration. Eisho Co., Ltd. anchors Asian supply through vertically controlled paperboard finishing operations in China's Pearl River Delta.
Hang tags are information-bearing labels physically attached to merchandise, typically constructed from paper stocks between 200-400 gsm, coated or uncoated, with die-cut holes reinforced by metal eyelets or cotton twill string attachments, serving to communicate brand identity, pricing, care instructions, and anti-theft functionality at the point of sale. The material split shows paper and cardboard commanding volume in fast fashion replenishment cycles, while plastic substrates retain footholds in durable goods and outdoor apparel where moisture resistance governs specification. Eco-friendly tags represent the fastest-growing product type as brand sustainability commitments harden into procurement mandates, with QR code integrated designs capturing investment as digital traceability becomes a non-negotiable retail requirement.
The EU Packaging and Packaging Waste Regulation and FDA indirect food contact standards shape substrate selection and adhesive chemistry for tags entering regulated supply chains, while ISO 14001 environmental management certification increasingly filters vendor qualification lists. California's extended producer responsibility frameworks and India's BIS packaging standards are propagating compliance complexity across multi-destination production programs. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualification gaps.
Market Dynamics
RFID inlay integration is compressing traditional hang tag economics, forcing converters to absorb semiconductor sourcing complexity while apparel brands demand item-level traceability at no unit-cost premium.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates fiber-based substrate substitution for plastic-laminated tags entering European retail channels, redirecting converter R&D toward recyclable barrier coatings.
- Tiruppur-Surat textile corridor expansion:India's apparel export concentration is pulling dedicated hang tag finishing capacity into Tamil Nadu and Gujarat, reducing lead times for fast-fashion replenishment programs.
- QR-embedded traceability:Digital product passports are becoming mandatory for EU market access, requiring tag real estate to accommodate scannable data matrices alongside physical branding elements.
Market Restraints
- Pulp price volatility:Coated paperboard feedstock costs swing with Nordic softwood supply disruptions, squeezing converter margins on fixed-price annual contracts with mass retailers.
- RFID chip allocation bottlenecks:Semiconductor foundry capacity constraints in Taiwan concentrate inlay supply risk, delaying intelligent tag program rollouts for mid-tier fashion brands lacking volume commitments.
- Moisture resistance trade-offs:Fiber-based substrates certified under FSC chain-of-custody standards fail durability tests for outdoor apparel applications, preserving plastic tag footholds in technical sportswear.
Strategic Opportunities
- Underpenetrated Latin American luxury retail:São Paulo and Mexico City boutique expansion lacks localized RFID-integrated tag supply, creating first-mover advantage for converters establishing regional finishing partnerships.
- Blockchain-QR convergence:Immutable provenance verification layered onto physical tags enables premium pricing for transparency-marketed apparel in German and French markets.
- Direct-to-consumer channel bypass:E-commerce-native brands are sourcing tags separately from garment manufacturing, opening procurement relationships outside traditional full-package supplier networks.
Industry Challenges
- RFID antenna design talent scarcity:Electromagnetic engineering expertise for optimized inlay performance concentrates at Avery Dennison and a handful of specialized job shops, inflating recruitment costs for independent converters.
- FSC certification timeline compression:Chain-of-custody audits now require 8-14 months for new supplier qualification, stranding uncertified converters during seasonal procurement windows for European department store private labels.
- Legacy ERP integration friction:Tag converters adopting digital print workflows face data format incompatibilities with apparel brand PLM systems, delaying automated artwork approval pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hang Tags Market |
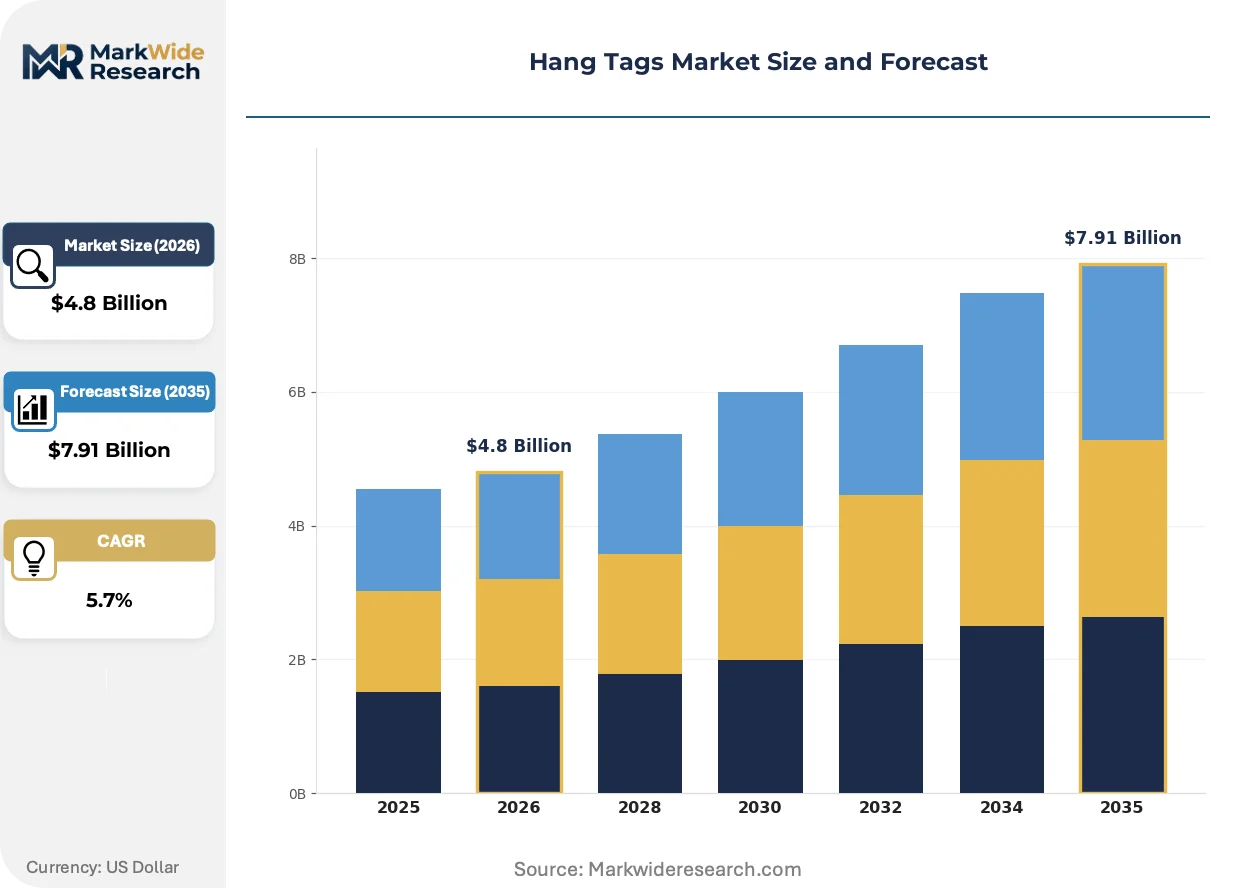
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Tags, Eco-friendly Tags, Writable Tags, Security Tags Material: Paper, Plastic, Fabric, Cardboard Design: Custom Designs, Standard Designs, Folded Designs, QR Code Integrated Sector: Fashion, Food & Beverage, Electronics, Home Décor |
| Companies Covered | Eisho Co., Ltd., Hallmark, Avery Dennison, Petoskey Plastics, Labels Inter-Global Inc, CCL Industries, Soli's Labels, Technicode, Inc., Taylor Labeling Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hang Tags Market Strategic Shifts
Physical-digital convergence is redefining hang tag function from static branding to interactive data infrastructure, compressing the boundary between merchandise presentation and supply chain visibility.
RFID inlay technology is miniaturizing through ultra-high-frequency chip designs that embed within 300-gsm paperboard without bulging or read-range degradation. Mass fashion retailers in Germany and the United Kingdom are adopting these slimmer profiles for 2025 replenishment cycles. The form-factor reduction is miniaturizing cost premiums for item-level tagging, collapsing the economic barrier that previously restricted RFID deployment to luxury tiers.
REACH substance restrictions are eliminating specific adhesive chemistries and metallic pigments from tags entering European Union markets, forcing reformulation of eyelet attachments and heat-activated coatings. Converter qualification costs have risen substantially for specialty finishing operations. Outdoor apparel brands sourcing through Milan-based buying offices are accelerating pre-compliance testing to avoid customs detention at Rotterdam and Hamburg.
Brand sustainability officers are mandating recycled fiber content minimums that outpace certified pulp availability, creating procurement competition for B-Corp and Cradle-to-Cradle verified material streams. Fast-fashion volume buyers in India and Bangladesh are accepting visible fiber irregularities as authenticity markers for recycled content claims. The specification tightening is most visible in Scandinavian retail markets, where consumer-facing transparency apps scan tag QR codes to display fiber origin documentation.
Hang Tags Market Segmentation
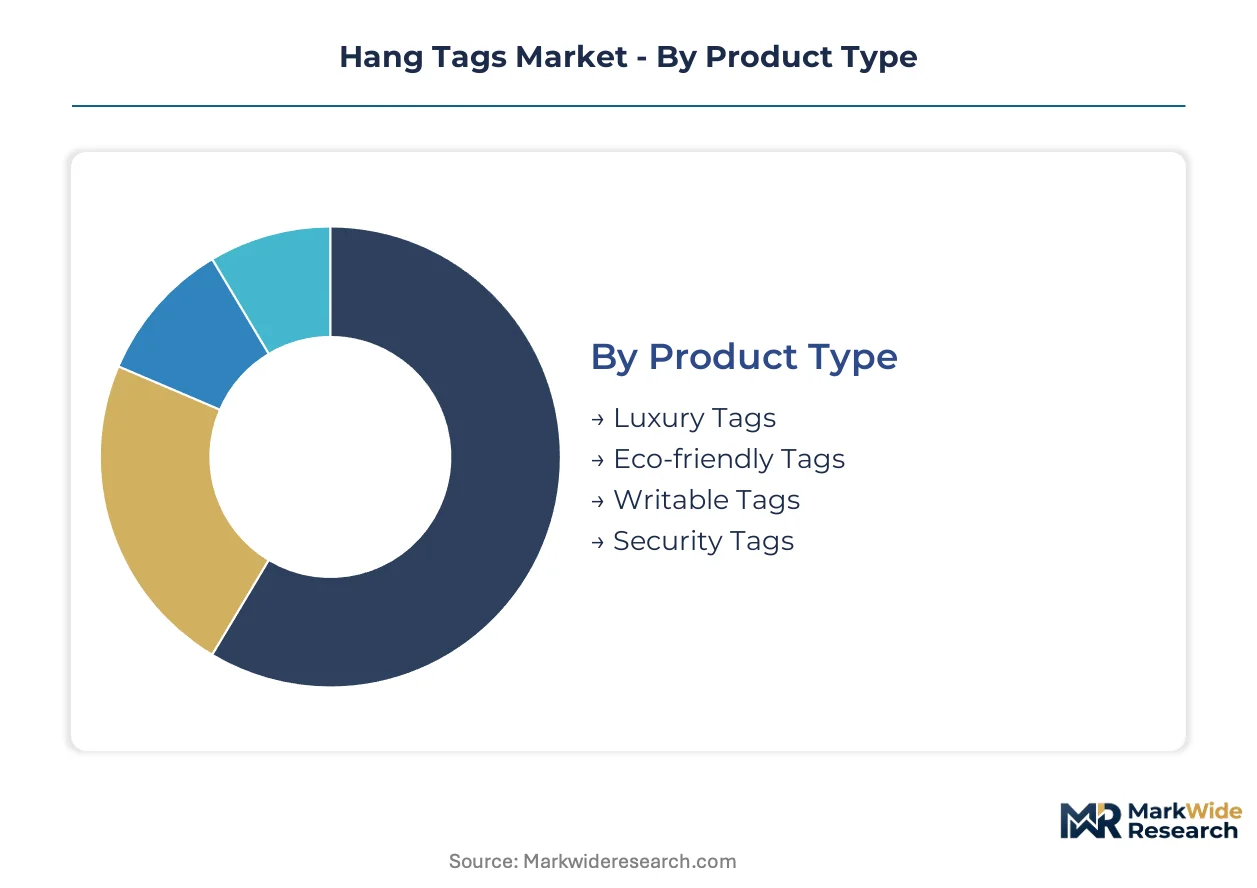
Hang tag procurement splits sharply between replenishment-driven volume programs and brand-led specialty orders. Channel configuration determines margin structure, converter qualification requirements, and lead time tolerance across each segment cluster.
Product Type:
Luxury tags flow through Milan and Paris buying offices with 12-16 week lead times, while eco-friendly variants penetrate fast-fashion replenishment through Tiruppur and Surat direct sourcing.
- Luxury Tags:Heavy-gauge paperboard between 350-450 gsm with metallic foil stamping, embossed logos, and cotton twill attachments. Paris and Milan flagship retail programs specify these for brand elevation at point of sale, with FSC chain-of-custody certification now mandatory for European department store placement.
- Eco-friendly Tags:Recycled fiber content exceeding 50% with visible pulp irregularities accepted as authenticity markers. Scandinavian retailers and German sustainability-focused brands are pulling these through dedicated supply chains, with QR-linked provenance documentation becoming standard specification.
- Writable Tags:Uncoated kraft surfaces compatible with thermal transfer and handwriting for price markdown flexibility.
- Security Tags:RFID inlay integration with EAS functionality for loss prevention in high-shrink retail environments.
Luxury tags dominate installed base value concentration. Eco-friendly tags are where expansion concentrates most steeply.
Material:
Cost tier stratification separates premium fiber-based specifications from commodity plastic alternatives, with moisture resistance requirements preserving plastic footholds in technical applications.
- Paper:Coated and uncoated stocks between 200-300 gsm serving fast-fashion replenishment cycles in India and Bangladesh. REACH-compliant adhesive systems and barrier coatings are redirecting converter R&D spend as EU Packaging and Packaging Waste Regulation enforcement tightens.
- Plastic:Polypropylene and PVC substrates with welded eyelet construction for outdoor apparel and durable goods. Technical sportswear brands sourcing through Milan buying offices specify these for wash-cycle durability, though fiber-based alternatives are gaining share in non-technical applications.
- Fabric:Woven cotton and synthetic textile tags for premium denim and heritage positioning.
- Cardboard:Uncoated recycled board for economy-tier retail and promotional tagging.
Paper commands unit volume leadership. Plastic retains margin density in performance-specification niches.
Design:
Application-driven specification separates interactive digital-physical hybrids from static branding executions, with traceability mandates accelerating QR integration.
- Custom Designs:Die-cut shapes, specialty finishing, and brand-exclusive color matching for flagship retail programs. German and UK mass fashion retailers are adopting these for 2025 replenishment cycles with compressed turnaround requirements.
- QR Code Integrated:Data matrix placement alongside physical branding elements for digital product passport compliance. EU market access requirements are making these mandatory for apparel categories, with blockchain-verified provenance layering emerging as a premium specification in French and German markets.
- Standard Designs:Rectangular formats with minimal finishing for economy-tier volume procurement.
- Folded Designs:Multi-panel constructions accommodating extended care instruction and regulatory labeling.
Custom designs anchor brand differentiation investment. QR-integrated formats are climbing the fastest as regulatory compliance hardens.
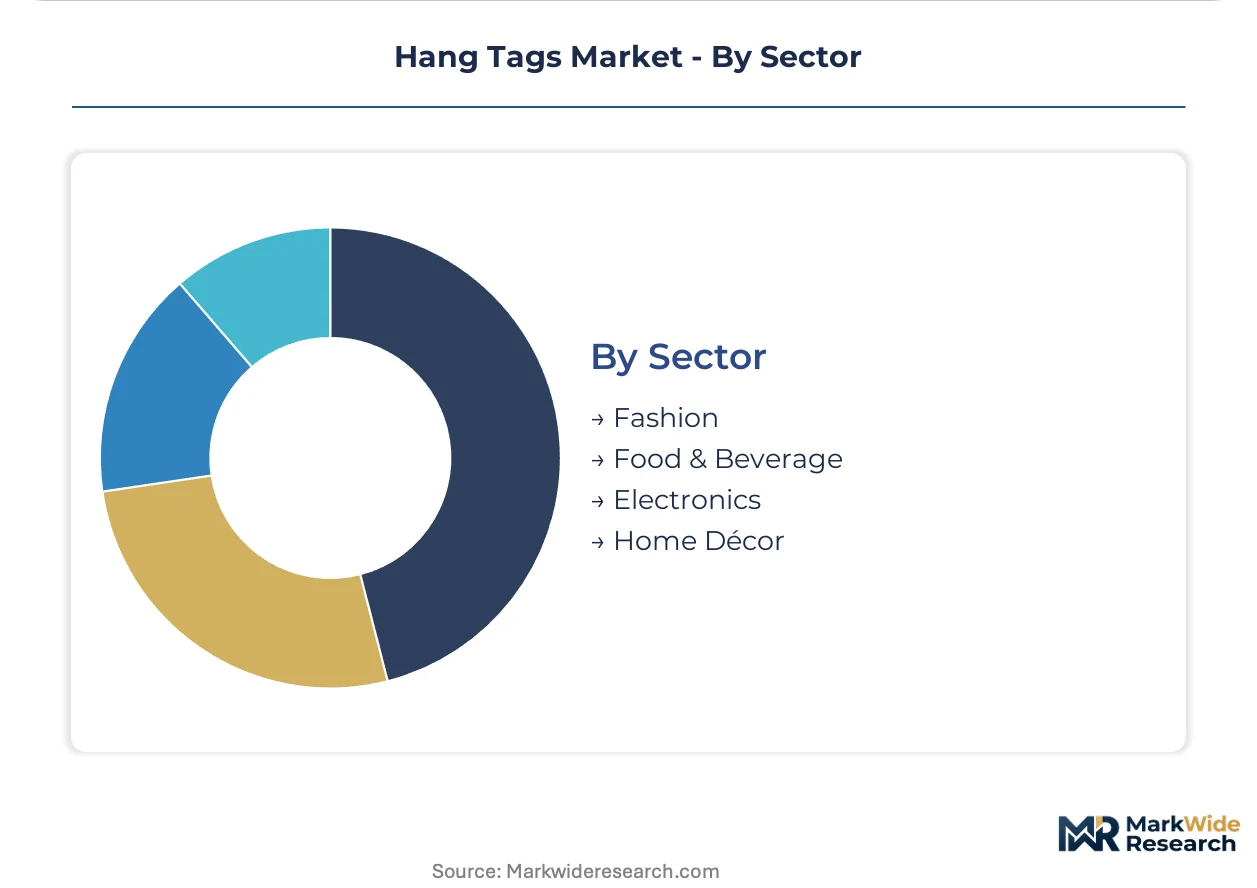
Sector:
Customer type concentration drives specification divergence, with fashion commanding technology integration while food and beverage emphasizes regulatory compliance.
- Fashion:Dominant demand concentration spanning luxury, mass, and fast-fashion tiers with RFID and QR integration now baseline for tier-one suppliers. Tiruppur and Surat export corridors are pulling dedicated finishing capacity into Tamil Nadu and Gujarat to compress replenishment lead times.
- Electronics:Anti-static substrates and tamper-evident attachments for high-value device packaging.
- Food & Beverage:FDA indirect food contact compliance and FSSAI alignment for tags adjacent to packaged goods, with barrier coating specifications stricter than apparel applications.
- Home Décor:Extended durability specifications for furniture and textile accessories with slower inventory turns.
Fashion dominates procurement volume and technology adoption. Food and beverage is gaining compliance-driven specification complexity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation is redirecting substrate selection across major apparel export corridors, while India's textile clusters and China's manufacturing zones absorb displaced finishing capacity from European converters facing compliance cost inflation.
United States
California's extended producer responsibility frameworks are filtering vendor qualification lists for tags entering West Coast retail channels. FDA indirect food contact standards govern substrate selection for hang tags adjacent to packaged goods in food and beverage applications. Los Angeles and New York Metro buying offices are consolidating procurement around converters with ISO 14001 certification and domestic finishing capacity.
Germany
Mass fashion retailers in Berlin and Hamburg are adopting RFID-integrated tags for 2025 replenishment cycles with compressed turnaround requirements. REACH substance restrictions are eliminating specific adhesive chemistries and metallic pigments from European market access. The country's national packaging regulator is enforcing fiber-based substitution mandates that redirect converter R&D toward recyclable barrier coatings.
China
Pearl River Delta finishing operations anchor Asian supply through vertically controlled paperboard operations serving export-oriented apparel brands. The country's national standards administration is aligning domestic packaging regulations with EU market access requirements for textile exports. Zhejiang and Jiangsu province converters are expanding capacity to capture orders displaced from European suppliers by FSC certification timeline compression.
India
Tiruppur and Surat textile corridors are pulling dedicated hang tag finishing capacity into Tamil Nadu and Gujarat to compress lead times for fast-fashion replenishment programs. BIS packaging standards are propagating compliance complexity across multi-destination production programs. Mumbai and Delhi-NCR buying offices are consolidating procurement around converters with integrated digital print workflows and QR code embedding capabilities.
France
Paris flagship retail programs specify heavy-gauge luxury tags with FSC chain-of-custody certification now mandatory for department store placement. The country's national data protection regulator is shaping QR code data architecture for consumer-facing transparency applications. Lyon and Marseille logistics hubs are consolidating distribution for fiber-based tag shipments entering Southern European retail channels.
Hang Tags Market Competitive Environment
Listed leaders compete with private specialists across integrated technology capabilities, with public companies leveraging capital market access for RFID inlay integration while family-owned converters defend position through specialty substrate relationships. The vendor base stratifies into three tiers: multinational conglomerates with semiconductor sourcing partnerships, mid-cap specialists with regional finishing networks, and local job shops serving replenishment-driven volume programs. Dominant competitive moves include strategic partnerships for digital print workflow integration and capacity expansion in India's textile export corridors.
Within the multinational conglomerate tier, Avery Dennison and CCL Industries exemplify scale-driven positioning through integrated RFID capabilities and specialty substrate formulations respectively. Among Asia-Pacific-based fabricators, Eisho Co., Ltd. occupies a position reflecting vertically controlled finishing operations in China's Pearl River Delta. These three companies represent the archetype spectrum from technology-integrated global supply to regionally anchored production control.
| Leading Market Players |
|---|
| Eisho Co., Ltd. |
| Hallmark |
| Avery Dennison |
| Petoskey Plastics |
| Labels Inter-Global Inc |
| CCL Industries |
| Soli's Labels |
| Technicode, Inc. |
| Taylor Labeling Solutions |
| Others |
Value Chain & Pricing Dynamics
FSC chain-of-custody certification gates both supplier qualification and price differentiation simultaneously, squeezing uncertified converters out of premium procurement while commanding margin premiums for compliant fiber-based substrates serving European department store private labels.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FSC-verified fiber-based substrates commanding price premiums over uncertified alternatives while RFID-integrated tags stratify across performance tiers based on inlay complexity and read-range specifications. Three-tier pricing structure across premium, standard, and economy levels reflects brand tier alignment, with luxury apparel buyers least price-sensitive and fast-fashion volume programs in India and Bangladesh most susceptible to cost compression. Pricing pressure stems from pulp feedstock volatility and fixed-price annual contracts with mass retailers, squeezing converter margins on coated paperboard specifications.
Supply Chain Analysis
Semiconductor foundry capacity in Taiwan concentrates RFID inlay supply risk, with chip allocation bottlenecks delaying intelligent tag program rollouts for mid-tier fashion brands lacking volume commitments. Raw material dependencies center on Nordic softwood pulp for premium paperboard, cotton twill for luxury attachments, and UHF chips from Taiwan foundries. Tariff exposure runs through EU Packaging and Packaging Waste Regulation enforcement, which redirects substrate selection toward fiber-based alternatives. Distribution runs through Milan and Paris buying offices for luxury tiers, Tiruppur and Surat direct sourcing for fast-fashion replenishment, and Los Angeles and New York Metro consolidation for North American retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital product passport services and blockchain-verified provenance platforms represent a recurring-revenue layer expanding faster than physical tag hardware, converting one-time substrate sales into ongoing data infrastructure subscriptions.
For Market Incumbents: Compound defensive positioning through backward integration into RFID antenna design capabilities and captive pulp supply arrangements, countering semiconductor sourcing complexity and Nordic softwood price volatility that threaten margin stability on fixed-price retail contracts.
For New Entrants and Emerging Players: Differentiate on blockchain-QR convergence for transparency-marketed apparel in German and French markets, targeting underpenetrated Latin American luxury retail in São Paulo and Mexico City where localized RFID-integrated tag supply remains scarce.
For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation reshapes the acquisition landscape toward converters with recyclable barrier coating R&D and FSC certification already in place, with long-term viability favoring asset-light digital print workflow platforms over legacy finishing capacity; watch for FSC audit timeline compression as an inflection signal for stranded inventory risk among uncertified suppliers.
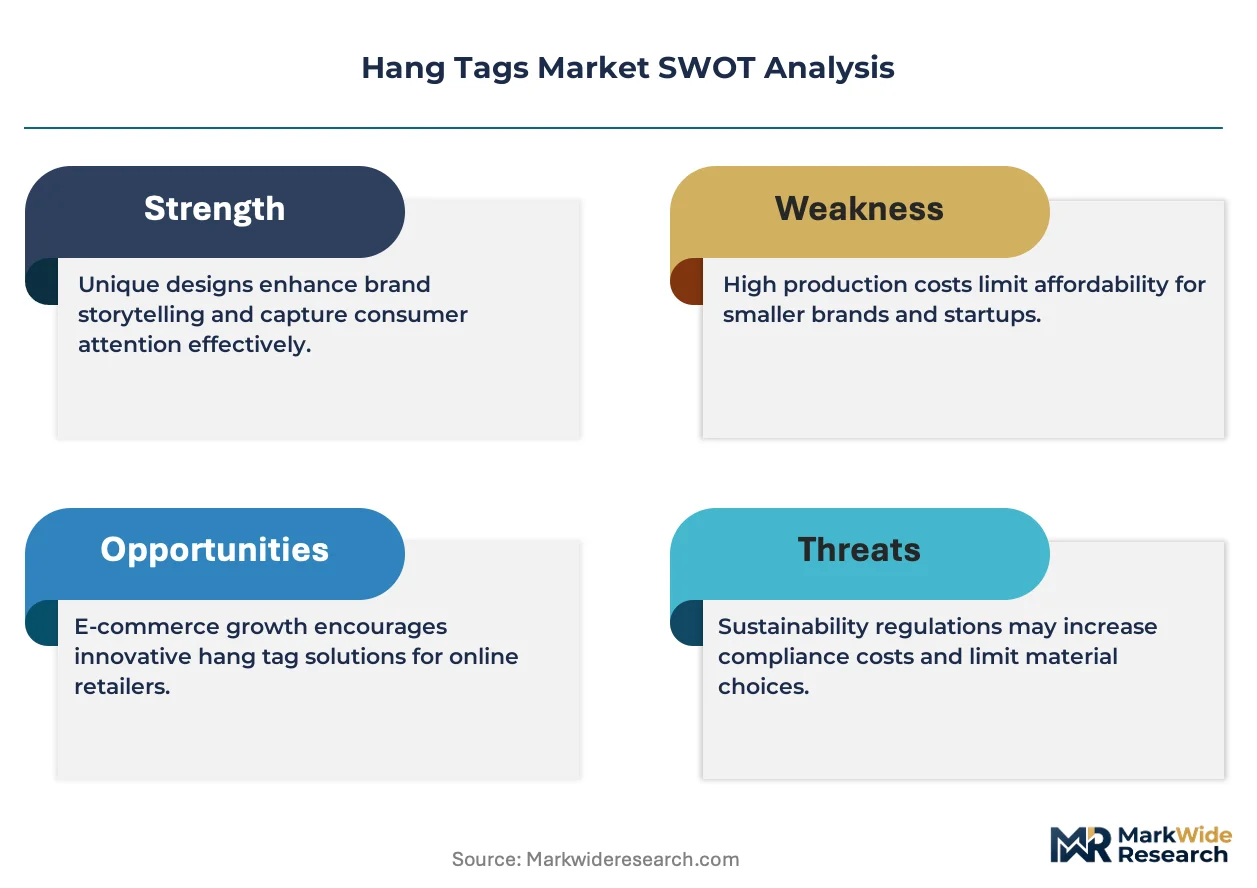
| Strategic Initiative | Industry Significance |
|---|---|
| RFID Inlay Integration Partnership | Secures semiconductor allocation from Taiwan foundries for mass fashion retailer programs. |
| Fiber-Based Barrier Coating R&D | Aligns substrate portfolios with EU Packaging and Packaging Waste Regulation mandates. |
| India Textile Corridor Capacity Expansion | Captures fast-fashion replenishment demand concentrating in Tiruppur and Surat clusters. |
| Blockchain-QR Provenance Platform Launch | Enables premium pricing for transparency-marketed apparel in German and French markets. |
| Direct-to-Consumer Channel Development | Bypasses traditional full-package supplier networks for e-commerce-native brand procurement. |
Study Parameters
Initial hypotheses were tested against primary input from brand sustainability officers, apparel procurement directors, converter operations managers, and RFID technology specialists, and refined through secondary validation against EU regulatory filings, FSC chain-of-custody databases, customs trade records, and semiconductor foundry capacity disclosures. Bottom-up volume modeling across substrate types and top-down value triangulation against retail procurement spend were cross-checked for consistency.
Variance decomposition across the projection horizon isolates volume drivers from price mix effects, with segmentation modeling across product type, material specification, design complexity, and end-use sector informing CAGR derivation. Industry-specific inputs include pulp futures pricing trajectories, RFID inlay cost curves, and regulatory compliance timeline assumptions for EU Packaging and Packaging Waste Regulation implementation.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or stable semiconductor supply would require recalibration. Practitioners should keep alternative scenarios live as Nordic softwood harvest conditions and Taiwan foundry allocation priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Water Dissolvable Labels Market
Labels
Variable Data Printing Labels Market
Labels
HAZMAT Labels Market
Labels
Sustainable Labels Market
Labels
Cut and Stack Labels Market
Labels
Pressure Sensitive Labels Market
Labels
Future-Proof Pharma Labels Market
Labels
Glue-Applied Labels Market
Labels
Primary Packaging Labels Market
Labels
Warning Labels and Stickers Market
Labels
Wet Glue Labeling Machines Market
Labels
Hot Melt Glue Labeler Market
Labels
Domed Labels Market
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
BOPP Labels Market
Labels
Multi-Part Labels Market