
 United States Airframe MRO Market | 2026-2036
United States Airframe MRO Market Size, Share, and Industry Trends Forecast 2026-2036
United States Airframe MRO Market Insights
Cargo airline maintenance demand is broadening as freighter fleet utilization climbs and e-commerce logistics networks expand their domestic coverage. AAR Corp leverages its integrated supply chain to capture military and commercial contracts across multiple airframe platforms. Delta TechOps sustains one of the largest captive MRO operations in North America, servicing both internal fleet requirements and third-party customers. HAECO Americas specializes in narrow-body and wide-body overhaul work from its Southeast facilities, anchoring regional capacity.
United States Airframe MRO encompasses structural inspection, repair, and modification of fuselage, wing, and empennage assemblies to maintain FAA-certified airworthiness standards, typically involving non-destructive testing, corrosion treatment, and fatigue-critical component replacement. Scheduled Maintenance commands the largest share of service-type revenue as aging commercial fleets require more frequent C-check and D-check intervals. Commercial Aircraft generates the highest absolute spending within aircraft-type segmentation, though Military Aircraft overhaul work carries superior margin profiles due to specialized tooling and security-cleared labor requirements. Advanced Materials adoption within the technological approach dimension is expanding fastest as carbon-fiber-reinforced polymer repairs displace traditional aluminum patching on newer airframes.
FAA airworthiness directives and OSHA workplace safety standards shape labor deployment and facility certification requirements across the sector, while EPA hazardous waste regulations govern chemical stripping and coating removal processes. The Department of Defense MIL-STD compliance framework adds a separate certification layer for military airframe work, creating barriers that favor incumbent providers with established security clearances. Stakeholders must monitor how additive manufacturing qualification pathways evolve under FAA guidance, as 3D Printing adoption for structural repair parts could redistribute value between OEMs and independent MRO shops.
Market Dynamics
The United States Airframe MRO sector is undergoing structural recalibration as carbon-fiber-reinforced polymer repairs displace legacy aluminum patching, forcing facility retooling and workforce reskilling across Southeast maintenance clusters.
Growth Catalysts
- FAA Airworthiness Directives:Aging commercial fleets face mandatory structural inspection intervals that expand shop demand for C-check and D-check services.
- E-commerce logistics networks:Freighter fleet utilization climbs as domestic cargo coverage expands, driving overhaul volume for converted narrow-body aircraft.
- Defense procurement:Military airframe work requires security-cleared labor and specialized tooling, creating protected revenue pools for qualified providers.
Market Restraints
- Specialized labor scarcity:Composite repair certification programs produce insufficient technicians relative to fleet material transition timelines.
- EPA hazardous waste compliance:Chemical stripping and coating removal processes face escalating disposal cost structures and facility permitting delays.
- OEM technical data control:Airframers restrict access to structural repair manuals, limiting independent shop capability expansion.
Strategic Opportunities
- Additive manufacturing qualification:FAA pathway development for 3D-printed structural parts could redistribute value from OEMs to independent MRO shops.
- Military-civilian dual-use facilities:Southeast infrastructure clusters can leverage existing security clearances to capture adjacent defense contracts.
- Non-destructive testing automation:Ultrasonic and thermographic inspection convergence reduces cycle times and labor dependency.
Industry Challenges
- Skill pipeline gaps:Airframe and powerplant mechanics with composite expertise remain scarce relative to fleet transition velocity.
- Capital equipment intensity:Autoclave and automated fiber placement systems require multi-million-dollar facility investments.
- MIL-STD certification timelines:Department of Defense compliance frameworks extend onboarding periods for new military contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Airframe MRO Market |
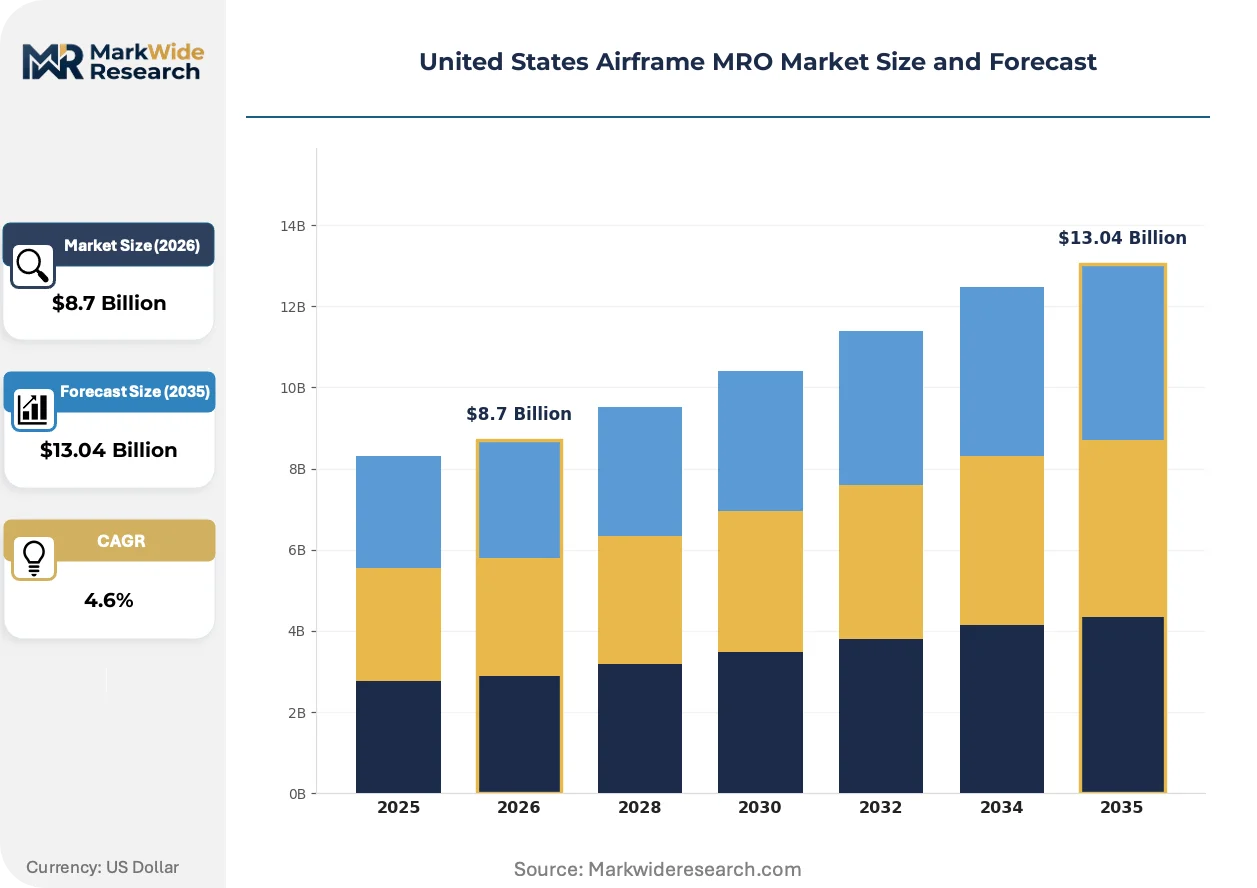
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Scheduled Maintenance, Unscheduled Repairs, Modification Services, Other Services Aircraft Type: Commercial Aircraft, Military Aircraft, Executive Jets, Cargo Aircraft End User: Airlines, Armed Forces, Charter Companies, Maintenance Providers Technological Approach: Traditional Techniques, Advanced Materials, Automation, 3D Printing |
| Companies Covered | AAR Corp, Delta TechOps, Lufthansa Technik, ST Engineering Aerospace, HAECO Americas, GE Aviation, Honeywell Aerospace, Pratt & Whitney, Collins Aerospace, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Airframe MRO Market Trends and Innovations
Advanced material repair methodologies and automated inspection systems are compressing turnaround times while elevating technical qualification barriers across the United States maintenance base.
Automated fiber placement is electrifying structural repair workflows for carbon-fiber fuselage sections. Major cargo operators retrofitting converted freighters now specify robotic layup for major damage events. This electrifying capability is compressing skilled labor dependency and narrowing the performance gap between OEM facilities and independent shops.
OSHA workplace safety standards are tightening respiratory protection and confined-space protocols for chemical stripping operations. Facility operators must deploy engineering controls and documented exposure monitoring. Southeast maintenance clusters face the steepest compliance costs given their concentration of legacy coating removal bays.
Airline procurement departments now unbundle heavy maintenance from bundled flight-hour agreements, seeking direct shop relationships for structural work. Low-cost carriers lead this disintermediation, negotiating fixed-price contracts for scheduled inspections. Texas and Florida-based MROs report the highest contract win rates under this model.
United States Airframe MRO Market Segmentation
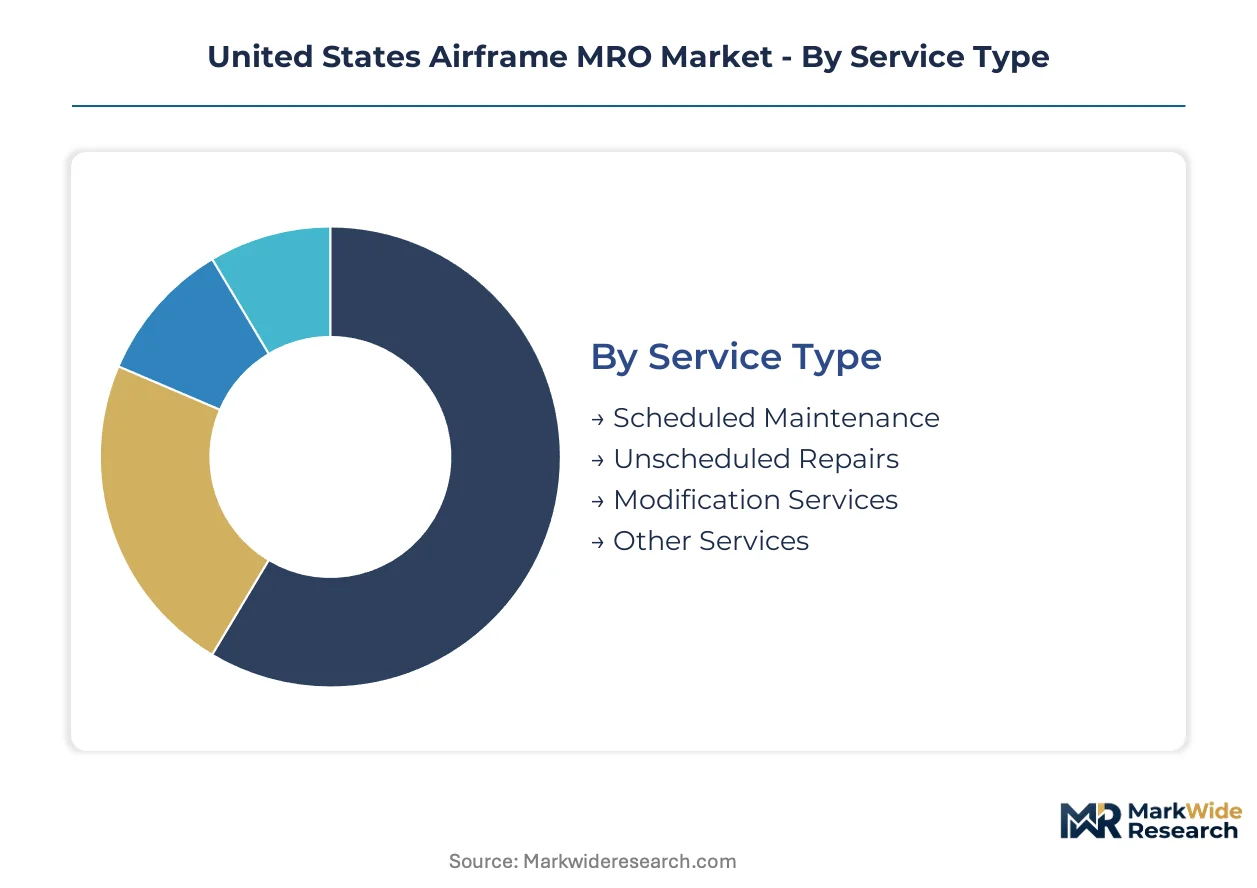
Airframe MRO segmentation reveals distinct capital requirements and margin profiles across service lines. Fleet composition and regulatory exposure determine where providers allocate technical resources and facility investment.
Service Type:
Scheduled Maintenance demands the heaviest upfront capital commitment through dedicated hangar bays and specialized tooling infrastructure.
- Scheduled Maintenance:Encompasses C-check and D-check intervals for fuselage, wing, and empennage inspection per FAA airworthiness directives. Southeast clusters near Atlanta and Miami absorb the majority of domestic heavy maintenance volume as legacy fleets age into mandatory structural intervals.
- Unscheduled Repairs:Addresses damage events from hard landings, hail strikes, and ground incidents requiring immediate airworthiness restoration. Demand concentrates at hub airports where operational disruption costs justify premium turnaround pricing.
- Modification Services:Includes passenger-to-freighter conversions and avionics upgrades.
- Other Services:Covers paint, interior refurbishment, and minor component replacement.
Scheduled Maintenance absorbs the bulk of installed capacity; Modification Services is expanding most quickly.
Aircraft Type:
Commercial Aircraft generate the highest absolute throughput, though margin profiles vary sharply by platform age and material composition.
- Commercial Aircraft:Narrow-body and wide-body fleets drive volume through high-cycle utilization patterns. Texas and Florida MROs report the strongest contract win rates as low-cost carriers unbundle heavy maintenance from flight-hour agreements.
- Military Aircraft:Requires security-cleared labor pools and MIL-STD compliance certification. The Department of Defense procurement framework creates protected revenue streams for incumbent providers with established facility clearances.
- Executive Jets:Demands specialized interiors expertise and rapid turnaround protocols.
- Cargo Aircraft:Freighter conversions and utilization-driven overhaul cycles anchor demand.
Commercial Aircraft commands the largest facility footprint; Cargo Aircraft is climbing the fastest on e-commerce logistics expansion.
End User:
Airlines represent the most price-sensitive customer segment, driving procurement disintermediation away from bundled service agreements.
- Airlines:Legacy and low-cost carriers now negotiate direct shop relationships for structural work. Fixed-price contracts for scheduled inspections dominate procurement patterns in the Southeast maintenance corridor.
- Armed Forces:Military end-users prioritize technical compliance and security protocols over unit cost. Multi-year sustainment contracts favor providers with existing Department of Defense security infrastructure.
- Charter Companies:Require flexible scheduling and rapid dispatch reliability.
- Maintenance Providers:Third-party MROs subcontract specialized capabilities.
Airlines represent the largest addressable spend pool; Maintenance Providers are gaining share fastest through OEM-independent capability expansion.
Technological Approach:
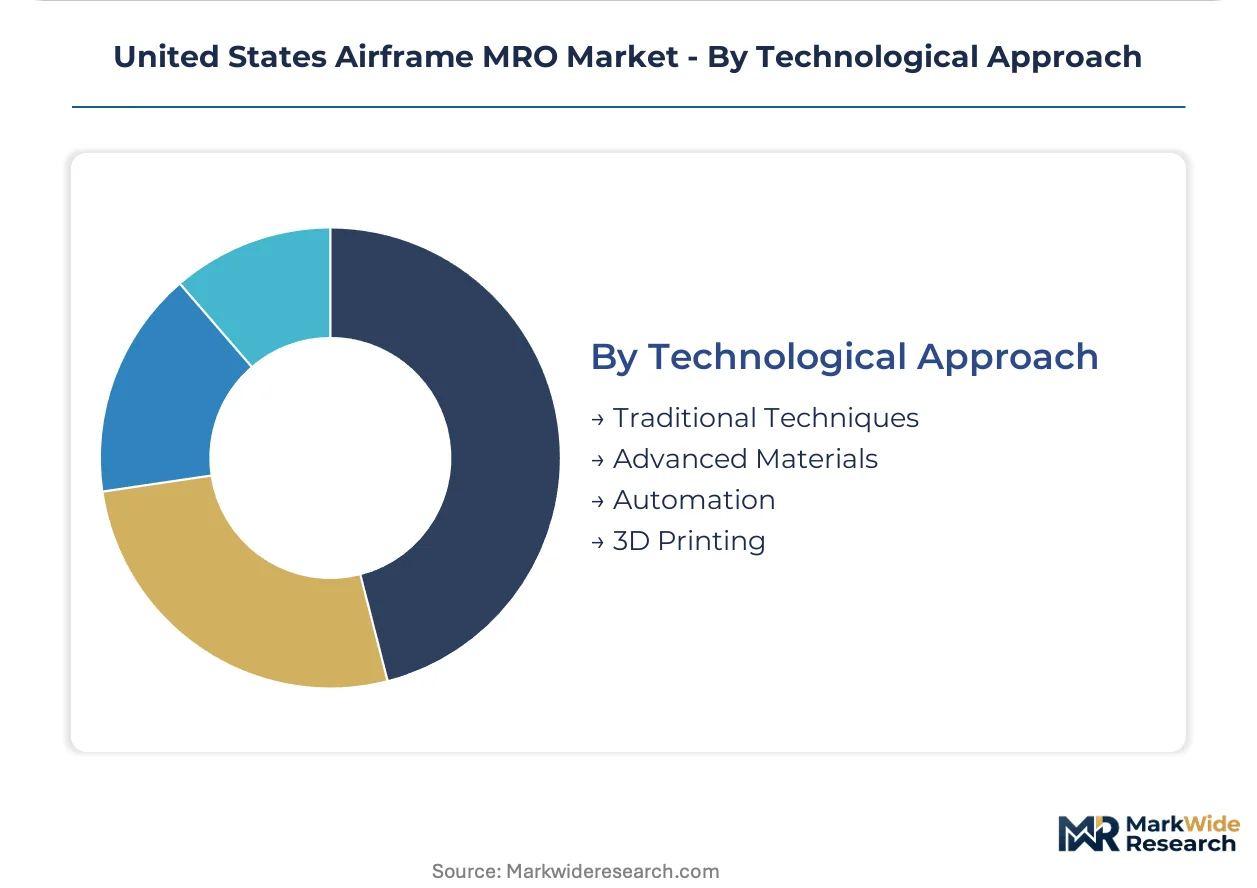
Advanced Materials and Automation require the steepest capital reinvestment as facilities retool for carbon-fiber repair workflows.
- Traditional Techniques:Aluminum patching and riveted repair methods dominate legacy fleet maintenance. Southeast clusters retain substantial installed base of metal-working equipment for aging narrow-body aircraft.
- Advanced Materials:Carbon-fiber-reinforced polymer repairs displace aluminum patching on newer airframes. Autoclave and automated fiber placement systems demand multi-million-dollar facility upgrades.
- Automation:Robotic inspection and layup systems compress cycle times.
- 3D Printing:Additive manufacturing for structural repair parts awaits FAA qualification pathways.
Traditional Techniques retains the widest installed base; Advanced Materials is gaining share fastest on fleet material transition timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign-Trade Zone 26 in Miami anchors aerospace logistics concentration, while the Southeast maintenance corridor concentrates under FAA Part 145 certificate density. State-level workforce development grants in Georgia and Florida accelerate technician pipeline investments.
Southeast (Florida/Georgia)
Miami International Airport's FTZ 26 status enables duty-deferred parts importation for heavy maintenance operations. FAA Part 145 repair station certificates cluster heavily in Broward and Dade counties, with Georgia's Quick Start program subsidizing composite technician training at Savannah Technical College. HAECO Americas operates wide-body overhaul capacity from Lake City, Florida, while Delta TechOps maintains its Atlanta hub as North America's largest captive MRO facility.
Southwest (Texas)
San Antonio's Kelly Field FTZ attracts military airframe contractors seeking MIL-STD compliance infrastructure. Texas Workforce Commission aviation grants fund A&P mechanic apprenticeships at St. Philip's College. AAR Corp leverages its dual-use facility at San Antonio International Airport for both commercial C-checks and military depot-level maintenance, with the region reporting the highest contract win rates for unbundled heavy maintenance procurement.
Midwest (Illinois/Michigan/Ohio)
Chicago Rockford International Airport's cargo hub expansion drives freighter conversion demand for e-commerce logistics networks. Illinois Department of Commerce EDGE tax credits support MRO facility modernization. Rockford's emerging maintenance cluster specializes in narrow-body passenger-to-freighter modifications, with Boeing's adjacent final assembly line creating supplier ecosystem density for structural repair parts.
Pacific Northwest (Washington)
Boeing's Everett and Renton production facilities generate adjacent MRO demand for legacy fleet support and modification engineering. Washington State's aerospace training programs at Everett Community College feed technician pipelines. The region concentrates on wide-body engineering services and fatigue-critical component replacement rather than line maintenance, with specialized shops supporting Alaska Airlines' Seattle hub operations.
United States Airframe MRO Market Competitive Landscape
Top-tier vendors anchor integrated supply chain positions, while mid-tier independents specialize in platform-specific capabilities. The market structure exhibits moderate consolidation around defense-cleared providers and airline-captive operations. Three strategic archetypes dominate: military-certified depot operators, commercial airline captive MROs, and independent third-party heavy maintenance specialists. Competitive moves center on dual-use facility certification and composite capability acquisition.
Within the defense-cleared tier, AAR Corp and Delta TechOps represent contrasting archetypes of military-commercial integration. AAR Corp occupies a position as a pure-play independent with established Department of Defense security infrastructure. Delta TechOps exemplifies the airline-captive model that has successfully commercialized internal capacity. HAECO Americas sits within the Asia-Pacific headquartered specialist tier, leveraging Hong Kong-based engineering resources for its Southeast US facilities.
| Leading Market Players |
|---|
| AAR Corp |
| Delta TechOps |
| Lufthansa Technik |
| ST Engineering Aerospace |
| HAECO Americas |
| GE Aviation |
| Honeywell Aerospace |
| Pratt & Whitney |
| Collins Aerospace |
| Others |
Pricing and Supply Chain Analysis
Captive airline MRO operations anchor both supply positioning and pricing power across the United States airframe maintenance sector. Delta TechOps and similar airline-owned facilities leverage internal fleet commitments to secure volume discounts on composite materials and specialized tooling, while independent shops compete on turnaround speed rather than unit cost.
Pricing Analysis
Short-lead-time contracts command substantial premiums over scheduled maintenance slots booked months in advance. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FAA Part 145 repair stations capturing higher rates than non-certified competitors. Pricing pressure stems from low-cost carriers unbundling heavy maintenance from flight-hour agreements and negotiating fixed-price contracts directly. Airlines represent the most price-sensitive buyer segment, while Armed Forces procurement prioritizes technical compliance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle proprietary composite prepreg and specialized fasteners for military-certified facilities. Raw material sourcing draws from Japan, Germany, and domestic suppliers for carbon-fiber reinforcements, aerospace-grade adhesives, and corrosion-resistant alloys. Single-source vulnerability concentrates in autoclave equipment manufacturing, where European and Japanese producers dominate installed base expansion. Distribution runs through authorized distributor networks for FAA-regulated materials, with Southeast maintenance clusters maintaining regional inventory buffers to compress turnaround times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
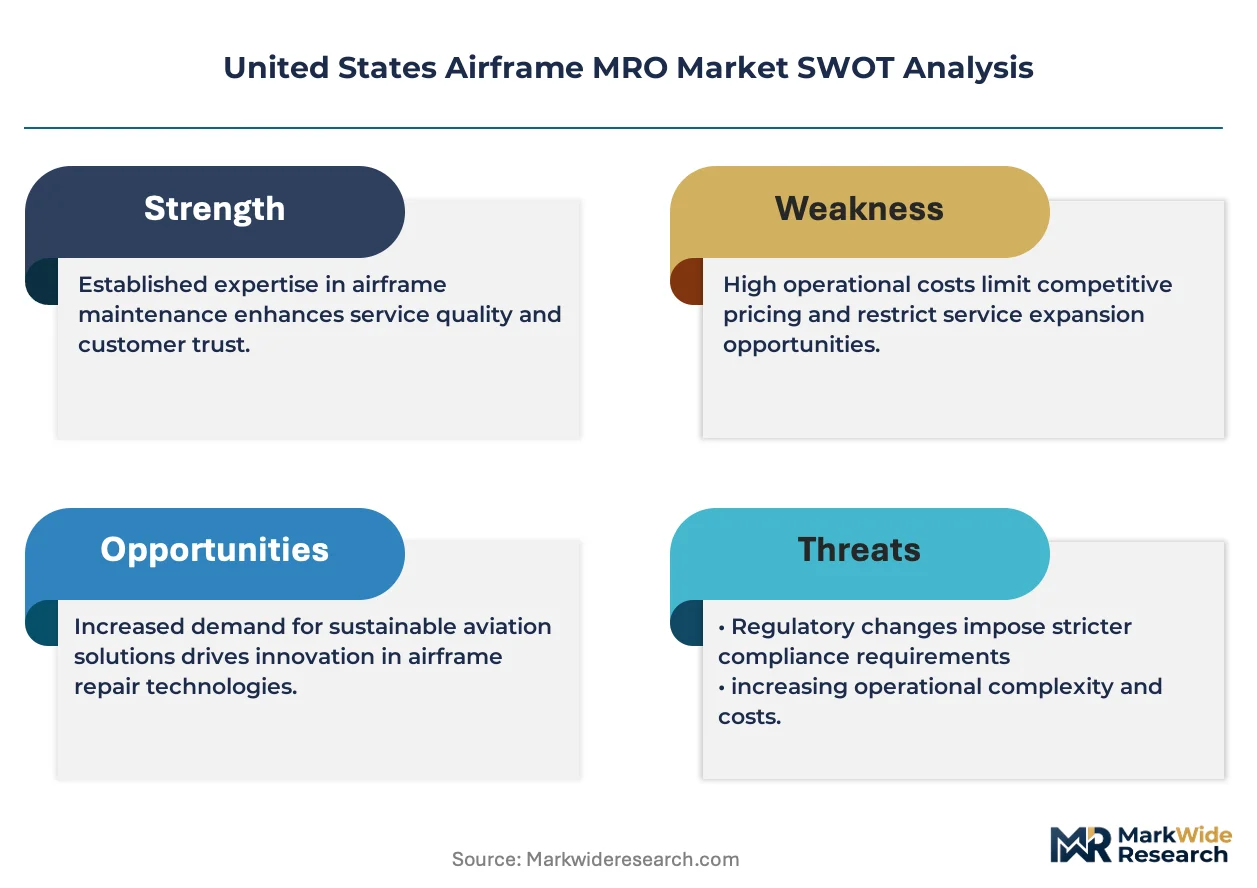
This market consolidates around defense-cleared providers and composite-capable facilities, with EPA compliance costs and capital equipment intensity forcing sub-scale independents toward exit or acquisition.
For Market Incumbents: Cement dual-use facility certification to capture adjacent defense contracts while commercializing excess capacity. Acquire specialized composite repair shops in the Southeast corridor to anchor regional talent pools. Military procurement security requirements and multi-million-dollar autoclave investments create defensive moats against price-competitive entrants. For New Entrants and Emerging Players: Digital-channel routes through airline procurement platforms offer lower customer acquisition costs than traditional sales networks. Target unscheduled repair services at hub airports where operational disruption costs justify premium pricing. Focus on narrow-body freighter conversions for e-commerce logistics operators seeking rapid turnaround partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in defense contractor roll-ups and airline-captive MRO commercialization. Long-term viability favors providers with established FAA Part 145 certificates and security-cleared labor infrastructure. Monitor FAA additive manufacturing qualification pathways as inflection indicator for 3D-printed structural parts redistributing value from OEMs to independent shops.| Strategic Initiative | Industry Significance |
|---|---|
| Military-Civilian Dual-Use Certification | Captures protected Department of Defense revenue streams while utilizing commercial excess capacity. |
| Composite Capability Acquisition | Addresses technician scarcity through targeted shop purchases in Southeast maintenance clusters. |
| Automated Fiber Placement Investment | Compresses skilled labor dependency for carbon-fiber fuselage repairs on converted freighters. |
| Additive Manufacturing Qualification | Positions for FAA pathway development redistributing structural part value from OEMs. |
| Non-Destructive Testing Automation | Reduces cycle times and labor dependency through ultrasonic and thermographic inspection convergence. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this United States airframe MRO analysis. Primary interviews with FAA Part 145 repair station operators, airline procurement directors, defense contract officers, composite technician training program administrators, and EPA compliance consultants validated demand assumptions. Secondary sources included FAA airworthiness directive databases, Department of Defense procurement records, OSHA workplace safety filings, and Bureau of Transportation Statistics fleet utilization data. Bottom-up facility capacity modeling and top-down defense budget allocation analysis were triangulated against commercial airline maintenance spend patterns.
Data-stream reconciliation across the projection horizon integrated scheduled maintenance interval projections, fleet age demographics, and material transition timelines for carbon-fiber airframes. Segmentation dimensions modeled encompassed service type, aircraft platform, end-user category, and technological approach, with regional variation captured through state-level workforce development grant analysis and Foreign-Trade Zone utilization patterns. CAGRs were derived from compound growth modeling of baseline market value against projected fleet expansion and regulatory-mandated inspection frequency increases. Industry-specific inputs included FAA airworthiness directive issuance rates and e-commerce logistics network expansion trajectories.
The model holds under steady FAA regulatory enforcement and continued defense procurement commitment; deviation in additive manufacturing qualification timelines or composite technician pipeline expansion would shift capacity utilization assumptions. Forecasts reflect documented base conditions around fleet age profiles and material transition velocity. Periodic stress-testing of base assumptions is recommended given sensitivity to EPA hazardous waste compliance cost escalation and OEM technical data access restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market
Aircraft Maintenance and MRO Solutions
Middle-East Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Aviation Engine MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market